
 Image-Guided Biopsy Market | 2026-2036
Image-Guided Biopsy Market Size, Share, and Industry Trends Forecast 2026-2036
Image-Guided Biopsy Market Analysis
Multi-source procurement for imaging core components is realigning vendor relationships across the image-guided biopsy supply chain. GE HealthCare leverages its installed base of ultrasound and CT platforms to bundle guidance software with hardware refreshes. Siemens Healthineers anchors its position through MRI-compatible biopsy workflows that integrate with its magnet systems. Hologic specializes in breast imaging-guided biopsy systems, competing on workflow automation and specimen quality.
Image-guided biopsy encompasses tissue sampling procedures directed by real-time or pre-procedural imaging, typically employing stereotactic coordinates, electromagnetic tracking, or robotic needle alignment with sub-millimeter precision to target lesions inaccessible through palpation alone. The technique serves primarily to obtain diagnostic histopathology while minimizing collateral tissue trauma and procedure time. Ultrasound-guided systems dominate procedural volume due to portability, absence of ionizing radiation, and lower capital requirements, while MRI-guided platforms command premium positioning in prostate and breast applications where soft-tissue contrast determines target delineation. Needles and biopsy devices represent the most fragmented product category, with margin pools shifting toward disposable single-use designs that reduce cross-contamination risk and sterilization overhead.
The FDA regulates image-guided biopsy devices through the 510(k) premarket notification pathway, with increasing scrutiny of software-as-a-medical-device algorithms that automate lesion detection or needle trajectory planning. CE marking under the EU MDR imposes stricter clinical evidence requirements for class IIa and IIb devices, extending timelines for European market access. Stakeholders must monitor evolving reimbursement codes for image-guided procedures across Medicare and commercial payers, as coverage determinations increasingly tie payment to demonstrated reduction in repeat biopsy rates and diagnostic accuracy metrics.
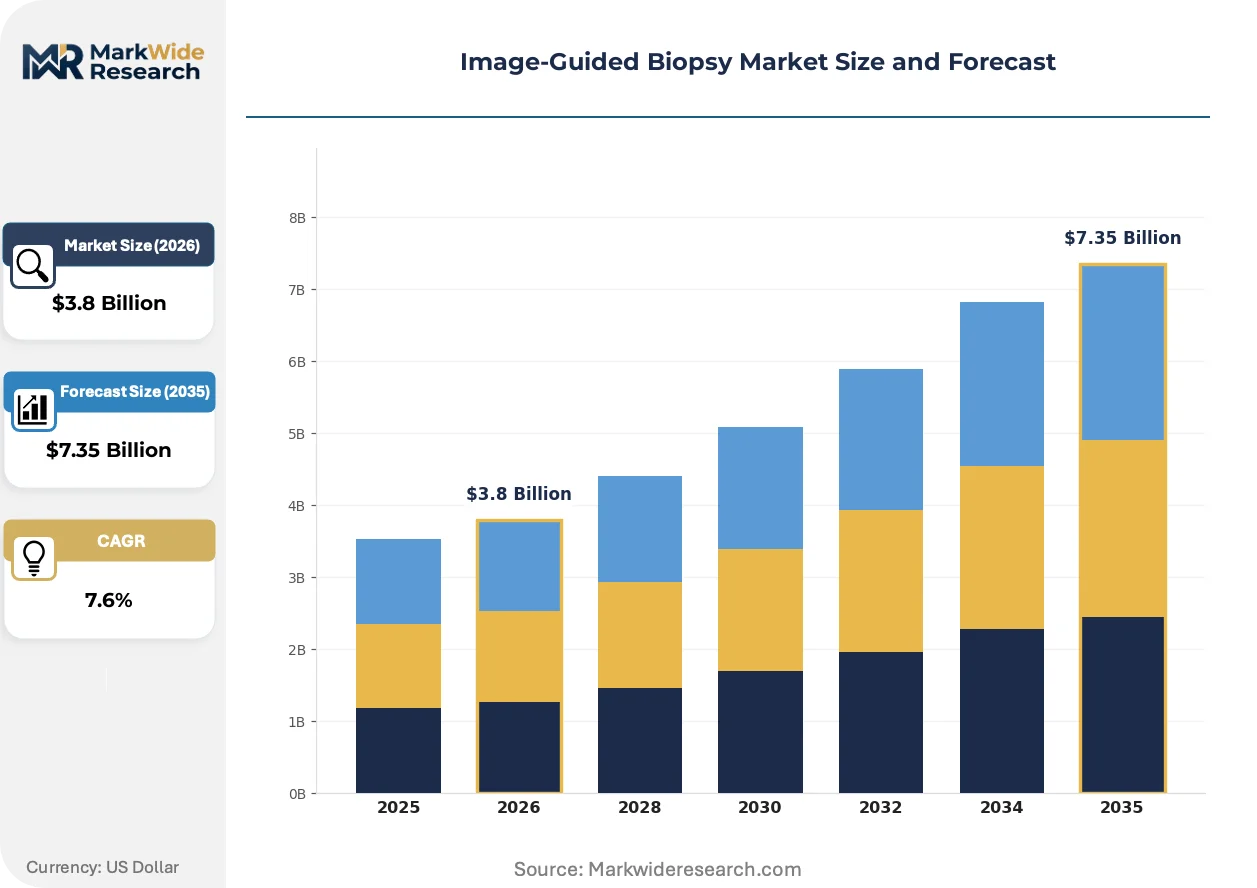
Market Dynamics
AI-integrated needle guidance software is compressing the learning curve for interventional radiologists while simultaneously fragmenting the vendor landscape as imaging OEMs race to bundle proprietary algorithms with hardware refreshes.
Growth Catalysts
- Hospital-based oncology expansion:Integrated health networks in the United States are consolidating interventional services into centralized cancer centers, creating dedicated capital budgets for minimally invasive tissue sampling platforms.
- FDA 510(k) pathway acceleration:The premarket notification framework for software-enabled devices shortens commercialization timelines for AI-integrated guidance platforms compared to traditional PMA routes.
- Disposable single-use migration:Infection control protocols are displacing reusable needle systems, expanding recurring revenue pools for manufacturers of sterile biopsy devices.
Market Restraints
- MRI-compatible hardware cost structure:Specialized non-ferromagnetic components and shielded electromagnetic tracking systems carry 3-4x capital intensity versus ultrasound-guided alternatives.
- EU MDR clinical evidence requirements:Class IIa and IIb device reclassification under the Medical Device Regulation extends European market access timelines by 18-24 months for novel guidance platforms.
- CT fluoroscopy substitution threat:Low-dose cone-beam CT systems are capturing procedural volume in lung and bone biopsies where real-time 3D reconstruction matches MRI soft-tissue contrast at lower operational cost.
Strategic Opportunities
- Ambulatory surgery center penetration:CMS site-of-service payment differentials are pulling outpatient biopsy volume away from hospital outpatient departments into freestanding ASCs with lower overhead structures.
- Robotic needle alignment convergence:Integration of haptic feedback systems with electromagnetic tracking is enabling sub-millimeter precision in prostate applications previously restricted to template-based brachytherapy platforms.
- India PLI scheme localization:Production-linked incentives for medical electronics manufacturing are attracting component suppliers to establish sterile needle assembly operations serving South Asian and Middle Eastern markets.
Industry Challenges
- Interventional radiology workforce constraints:Fellowship-trained operators capable of MRI-guided prostate and breast procedures remain concentrated in academic medical centers, limiting platform utilization in community settings.
- Legacy PACS integration complexity:Biopsy guidance software must interface with heterogeneous imaging archives across health systems that have deferred vendor-neutral archive upgrades, forcing costly custom HL7 interface development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Image-Guided Biopsy Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Ultrasound, CT, MRI, PET Product Type: Needles, Guidance Systems, Biopsy Devices, Imaging Agents End User: Hospitals, Diagnostic Labs, Specialty Clinics, Research Institutions Application: Oncology, Neurology, Orthopedics, Cardiovascular |
| Companies Covered | GE HealthCare, Philips Healthcare, Siemens Healthineers, KOELIS, Becton, Dickinson and Company, Hologic, Inc., Argon Medical Devices, Cook Medical, Boston Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Image-Guided Biopsy Market Emerging Trajectories
Real-time imaging fusion and disposable device architectures are simultaneously elevating procedural precision and reconfiguring supplier economics across the biopsy guidance value chain.
Electromagnetic tracking arrays for needle navigation are modularizing from integrated console designs into detachable components compatible with third-party ultrasound probes. Community hospitals and ambulatory centers are adopting these plug-in systems to extend existing equipment lifecycles rather than committing to full platform replacements. This modularity is compressing replacement cycles for guidance hardware while expanding addressable markets for aftermarket sensor and software providers.
CE marking under the EU MDR is imposing stricter post-market surveillance obligations on class IIb software-as-a-medical-device algorithms that automate lesion detection or trajectory planning. Manufacturers must now maintain active implantable device-level vigilance systems for AI guidance tools, driving consolidation of regulatory affairs functions among mid-cap vendors. European notified bodies are prioritizing review capacity for MRI-compatible biopsy devices, creating queue advantages for prostate and breast applications over lung interventions.
Hospital procurement committees are unbundling after-sales service contracts from capital equipment purchases, shifting toward third-party preventive maintenance and remote technical support subscriptions. This disintermediation pressures OEM service margins while creating openings for independent service organizations with multi-vendor imaging engineering capabilities. The United States exhibits the most pronounced unbundling as integrated delivery networks centralize clinical engineering functions across geographically dispersed facilities.
Image-Guided Biopsy Market Segmentation
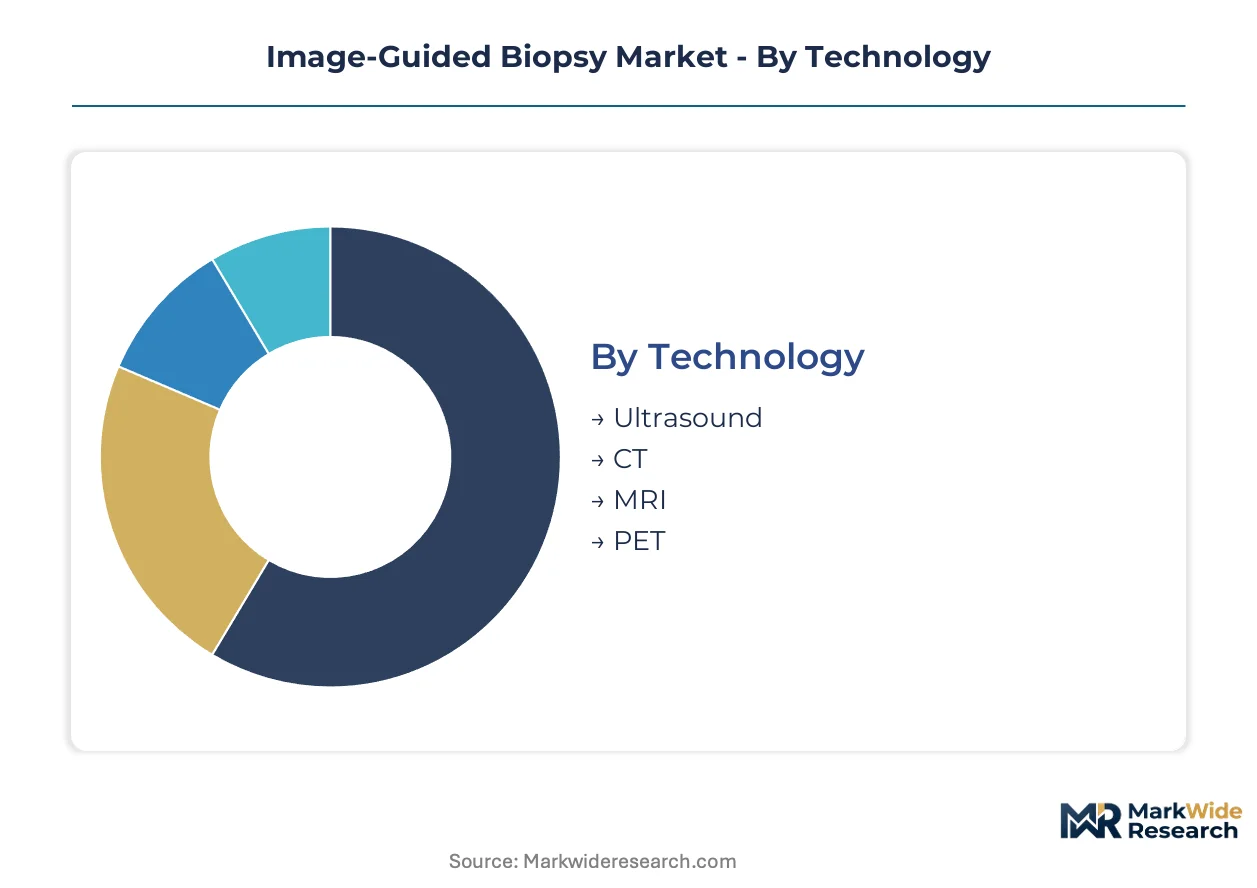
Technology modality, product architecture, and site-of-service economics create distinct investment profiles across the image-guided biopsy value chain. Procurement committees evaluate each segment against procedure volume, reimbursement codes, and equipment lifecycle costs.
Technology:
Capital intensity and radiation exposure define the customization-to-standardization spectrum across imaging platforms.
- Ultrasound:Portable transducers with electromagnetic needle tracking deliver real-time guidance without ionizing radiation. Community hospitals in the United States deploy these systems for thyroid and breast procedures where soft-tissue contrast requirements remain moderate.
- CT:Cone-beam reconstruction enables 3D trajectory planning for lung and bone lesions. Academic medical centers in Germany integrate these platforms with interventional radiology suites serving high-volume thoracic oncology programs.
- MRI:Non-ferromagnetic components and shielded tracking arrays command premium positioning in prostate and breast applications.
- PET:Metabolic lesion targeting for recurrent cancer staging in specialized tertiary centers.
Most installed capacity flows through ultrasound platforms. Expansion is steepest in MRI-compatible configurations.
Product Type:
Margin pools concentrate in disposable architectures versus capital equipment with extended depreciation schedules.
- Needles:Single-use core biopsy and fine-needle aspiration devices with coaxial introducer systems. Ambulatory surgery centers in Texas and Florida prioritize sterile disposable designs to eliminate reprocessing overhead.
- Guidance Systems:Electromagnetic tracking arrays and robotic needle alignment consoles. Siemens Healthineers bundles these with MRI magnet installations in university hospitals across France and Switzerland.
- Biopsy Devices:Vacuum-assisted and spring-loaded mechanisms for tissue acquisition.
- Imaging Agents:Contrast media and radiotracers for lesion enhancement.
Revenue concentration sits with needles and guidance systems. Imaging agents are climbing fastest on PET-CT procedural expansion.
End User:
Reimbursement differentials and capital access separate institutional tiers across care delivery settings.
- Hospitals:Integrated oncology departments with dedicated interventional radiology suites. Hospital systems in California and New York consolidate biopsy services into centralized cancer centers with dedicated MRI-guided platforms.
- Diagnostic Labs:High-throughput pathology workflows with on-site imaging capabilities. Reference laboratories in India leverage PLI scheme incentives to establish sterile needle assembly operations for regional distribution.
- Specialty Clinics:Urology and breast imaging centers with focused procedure menus.
- Research Institutions:Clinical trial infrastructure for novel guidance algorithm validation.
Procedure volume concentrates in hospital outpatient departments. Diagnostic labs are expanding capacity most aggressively on reference testing consolidation.
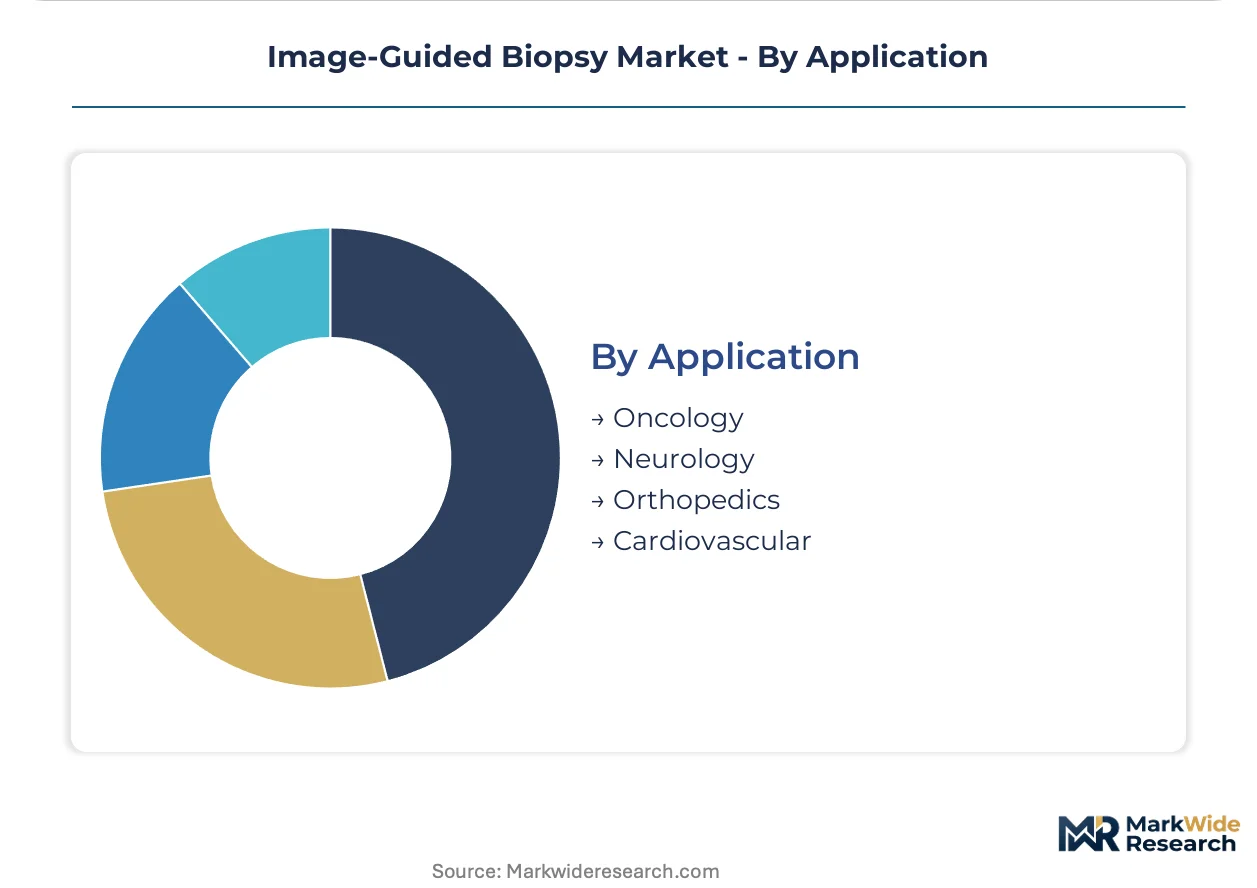
Application:
Target anatomy and lesion characteristics determine imaging modality selection and device specification.
- Oncology:Tissue sampling for histopathological diagnosis and molecular profiling across solid tumors. Comprehensive cancer networks in the United Kingdom deploy multi-modality guidance platforms to support precision medicine programs.
- Neurology:Stereotactic brain biopsy for intracranial mass characterization. Academic centers in Japan integrate these procedures with intraoperative MRI suites for real-time trajectory verification.
- Orthopedics:Bone and soft-tissue lesion sampling for musculoskeletal oncology.
- Cardiovascular:Myocardial biopsy and endomyocardial sampling for transplant rejection monitoring.
Oncology commands the dominant share of installed guidance systems. Neurology applications are scaling fastest on intraoperative imaging adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated cancer networks in the United States concentrate demand for MRI-compatible biopsy platforms. Hospital procurement committees across Germany and Japan prioritize electromagnetic tracking systems for interventional suites. India's PLI scheme for medical electronics is attracting sterile needle assembly operations serving South Asian distribution.
United States
Hospital-based oncology departments in California and New York are consolidating interventional services into centralized cancer centers with dedicated capital budgets. The FDA's 510(k) clearance pathway accelerates commercialization timelines for AI-integrated guidance platforms versus traditional PMA routes. Academic medical centers in Boston and Houston deploy multi-modality guidance systems to support precision medicine programs.
Germany
University hospitals across Bavaria and Baden-Württemberg integrate MRI-compatible biopsy workflows with Siemens Healthineers magnet installations. CE marking under the EU MDR imposes stricter clinical evidence requirements for class IIb software-as-a-medical-device algorithms. The Eindhoven-to-Munich medical technology corridor hosts specialized non-ferromagnetic component suppliers serving prostate biopsy platform manufacturers.
Japan
Academic centers in Tokyo and Osaka deploy intraoperative MRI suites for real-time trajectory verification in stereotactic brain biopsy procedures. The PMDA regulates software-enabled devices through premarket consultation frameworks that align with international harmonization efforts. The Kansai region's medical device cluster concentrates electromagnetic tracking array production for Asia-Pacific distribution.
India
Reference laboratories in Maharashtra and Gujarat leverage PLI scheme incentives to establish sterile needle assembly operations for regional distribution. CDSCO oversight of class C and D medical devices requires local clinical trials for novel guidance platforms entering the domestic market. The Hyderabad-Bengaluru medical technology corridor attracts component suppliers serving Middle Eastern and African export markets.
United Kingdom
Comprehensive cancer networks in London and Manchester deploy multi-modality guidance platforms to support molecular profiling workflows for solid tumor diagnosis. MHRA post-Brexit regulations maintain alignment with EU MDR standards while streamlining UK-specific market access pathways. The Oxford-Cambridge life sciences cluster hosts clinical trial infrastructure for novel guidance algorithm validation.
Image-Guided Biopsy Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue AI-integrated software overlays and modular tracking components. The vendor base concentrates around imaging original equipment manufacturers bundling guidance systems with hardware refreshes, mid-cap specialists in disposable needle architectures, and independent software vendors licensing lesion detection algorithms. Competitive positioning depends on installed base leverage, regulatory clearance velocity, and service contract retention. Dominant moves include strategic partnerships between imaging OEMs and AI developers, plus vertical integration into sterile single-use device manufacturing.
Among imaging equipment manufacturers, GE HealthCare, Siemens Healthineers, and Philips Healthcare occupy positions defined by magnet and transducer installed bases. These entities exemplify the platform-bundling archetype, anchoring guidance software to hardware refresh cycles. Hologic and KOELIS represent specialization-focused competitors, with the former exemplifying breast imaging workflow automation and the latter prostate biopsy electromagnetic tracking. Becton, Dickinson and Company and Boston Scientific Corporation sit within the disposable device tier, their positions shaped by sterile manufacturing scale and distribution reach into ambulatory surgery centers.
| Leading Market Players |
|---|
| GE HealthCare |
| Philips Healthcare |
| Siemens Healthineers |
| KOELIS |
| Becton, Dickinson and Company |
| Hologic, Inc. |
| Argon Medical Devices |
| Cook Medical |
| Boston Scientific Corporation |
| Others |
Supply Flow & Price Mechanics
Fellowship-trained interventional radiologists concentrated in academic medical centers across the United States and Germany command premium compensation that widens pricing spreads between MRI-compatible platforms and portable ultrasound alternatives. Labor-cost differentials between these specialized operators and community-hospital generalists translate directly into three-tier equipment pricing across guidance system categories.
Pricing Analysis
Input-cost pass-through from non-ferromagnetic component sourcing and shielded electromagnetic tracking arrays sustains premium positioning for MRI-guided platforms. Price differentiation rests on FDA 510(k) clearance tier and after-sales service bundling, with academic medical centers exhibiting lowest price sensitivity and ambulatory surgery centers highest. Cost compression in disposable needle categories intensifies as sterile single-use designs displace reusable systems, squeezing mid-tier manufacturers without captive sterilization infrastructure.
Supply Chain Analysis
Regional distribution centers in the Netherlands and Singapore coordinate hub-and-spoke delivery of electromagnetic tracking arrays to interventional radiology suites across Europe and Asia-Pacific. Manufacturing concentrates in Germany, Japan, and the United States for precision-machined biopsy needles and guidance consoles. Raw material dependencies include rare-earth magnets for tracking sensors, medical-grade stainless steel for needle cores, and specialized polymers for sterile packaging. Single-source vulnerability in MRI-compatible component supply creates exposure to EU MDR regulatory delays. Distribution runs through manufacturer-direct sales for capital equipment and third-party medical distributors for disposable consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between the FDA's accelerated 510(k) pathway and the EU MDR's extended review timelines creates procurement timing advantages for health systems with dual-continent sourcing strategies. Cost differentials in sterile needle manufacturing between India and Western Europe amplify margin capture for suppliers with South Asian assembly operations.
For Market Incumbents: Hedge against CT fluoroscopy substitution in lung applications by deepening software integration with installed ultrasound bases. Prioritize backward integration into sterile single-use needle manufacturing to defend margin position against commoditization pressure from Indian PLI scheme entrants. Lock hospital system procurement committees into multi-year service contracts before third-party independent service organizations capture preventive maintenance revenue. For New Entrants and Emerging Players: AI-integrated lesion detection algorithms offer the most penetrable wedge into hospital outpatient departments lacking fellowship-trained interventional radiologists. Target ambulatory surgery centers in Texas and Florida with modular electromagnetic tracking attachments compatible with existing ultrasound probes. Pursue hospital-at-home and remote pathology partnerships as alternative go-to-market channels bypassing capital-intensive magnet installation requirements. For Investors and Strategic Acquirers: Imaging OEMs with magnet installed bases are the most active acquirer in this space, seeking software capabilities to bundle with hardware refresh cycles. Acquisition target archetypes include mid-cap electromagnetic tracking specialists and sterile needle manufacturers with FDA 510(k) clearances. Watch CDSCO domestic clinical trial requirements for class C and D devices as the signal indicating India market access inflection.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission for AI Guidance Software | Accelerates commercialization timelines versus PMA routes for algorithm-integrated platforms. |
| CE Marking Pathway Under EU MDR | Extends European market access timelines but creates queue advantages for prostate and breast applications. |
| Hospital System Partnership for MRI Suite Integration | Siemens Healthineers leverages magnet installations to anchor biopsy workflow software in university hospitals. |
| Software Companion Development for PACS Integration | Reduces custom HL7 interface costs that currently burden heterogeneous imaging archive environments. |
| Reimbursement Strategy for ASC Site-of-Service | Captures CMS payment differentials pulling outpatient biopsy volume from hospital departments. |
Methodological Framework
Coverage spans the United States, Germany, Japan, India, and the United Kingdom, with primary inputs from each market. Interviews with interventional radiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers combined with secondary validation from FDA 510(k) filings, EMA submissions, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up procedure volume estimates triangulated against top-down capital equipment shipment data.
Granularity-level modeling disaggregated the market across technology modality, product architecture, end-user setting, and application area. Segment-specific CAGRs derived from equipment replacement cycle analysis, procedure volume elasticity to reimbursement changes, and disposable penetration rates. Forecast inputs included fellowship-trained workforce growth projections, PLI scheme capacity buildout timelines, and EU MDR notified body review capacity allocation.
The model holds under stable regulatory clearance timelines and reimbursement code maintenance; deviation in FDA AI scrutiny intensity or CMS site-of-service payment reform would shift trajectory. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Spain Digital X-Ray Market
Medical Imaging
Global Mammography Systems Market
Medical Imaging
Magnetoencephalography (MEG) Market
Medical Imaging
Diagnostic Imaging Services Market
Medical Imaging
Brain PET-MRI Systems Market
Medical Imaging
Contrast Media/Contrast Agents Market
Medical Imaging
Global Digital Subtraction Angiography Market
Medical Imaging
Global Elastography Imaging Market
Medical Imaging
Brazil Digital X-Ray Market
Medical Imaging
Dental Diagnostic Imaging Equipment Market
Medical Imaging
Global Medical Imaging Reagents Market
Medical Imaging
Next Generation Ultrasound Systems Market
Medical Imaging
South Korea Diagnostic Imaging Equipment Market
Medical Imaging
Robotic X-Ray Scanner Market
Medical Imaging
United States Diagnostic Imaging Market
Medical Imaging
Germany Nuclear Imaging Market