
 Global Brachytherapy Treatment Planning Systems Market | 2026-2036
Global Brachytherapy Treatment Planning Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Brachytherapy Treatment Planning Systems Market Foresight
The EU Medical Device Regulation is hardening the cost-of-entry calculus for brachytherapy software vendors seeking CE marking in European markets. Varian Medical Systems leverages its installed base of linear accelerators to cross-sell integrated planning workflows across major cancer centers. Elekta AB anchors its competitive stance through dedicated R&D investment in adaptive brachytherapy algorithms. RaySearch Laboratories differentiates via specialized oncology software that extends beyond planning into treatment delivery analytics.
Brachytherapy treatment planning systems are software platforms that compute radioactive source positioning, dwell times, and dose distribution maps for internal radiation therapy, typically achieving spatial resolution below one millimeter for tumor margin definition. These systems serve the primary commercial purpose of enabling clinicians to optimize therapeutic radiation exposure while sparing adjacent healthy tissue. High dose rate systems dominate current revenue pools due to shorter procedure times and outpatient compatibility, while cloud-based deployment models represent the fastest-expanding segment as hospital IT departments prioritize remote access and multi-site collaboration. Electronic brachytherapy systems occupy a narrower but higher-margin niche in intraoperative settings where shielded vaults prove impractical.
The FDA maintains 510(k) premarket notification requirements for brachytherapy planning software, while the EU MDR imposes stricter clinical evidence standards for Class IIb and III devices. ISO 13485 quality management certification shapes supplier qualification processes for hospitals and group purchasing organizations. Japan's PMDA adds another layer of localization testing for foreign vendors entering Asian markets. Stakeholders must monitor evolving cybersecurity guidance from national health regulators, as networked planning systems face escalating scrutiny over patient data protection and ransomware resilience.
Market Dynamics
The EU Medical Device Regulation's 2021 enforcement is compressing vendor timelines for CE marking, forcing software developers to front-load clinical evidence generation and quality management system investments before commercial release in European oncology networks.
Growth Catalysts
- Cloud-based deployment architecture:Hospital IT departments in Germany and France prioritize remote access capabilities for multi-site collaboration, accelerating procurement cycles for SaaS-based planning platforms.
- FDA 510(k) clearance pathway:Streamlined premarket notification for software-only devices enables faster US market entry compared to hardware-dependent radiation therapy systems.
- Outpatient procedure migration:High dose rate brachytherapy's compatibility with ambulatory surgical centers expands addressable patient volumes beyond traditional inpatient oncology wards.
Market Restraints
- MDR clinical evidence requirements:Class IIb and III software devices face expanded post-market surveillance obligations, extending time-to-revenue for European launches by 18-24 months.
- Shielded vault infrastructure dependency:Conventional high dose rate systems require capital-intensive bunker construction, limiting adoption in smaller community hospitals and emerging market facilities.
- Electronic brachytherapy substitution:Intraoperative radiation systems using miniaturized X-ray sources eliminate radioactive isotope handling, capturing margin-rich cases in breast and skin cancer segments.
Strategic Opportunities
- Adaptive planning algorithms:Real-time dwell time optimization based on intraoperative imaging is electrifying clinical workflows in tertiary prostate cancer programs.
- Japan PMDA localization pathway:Foreign vendors establishing Tokyo-based regulatory affairs capabilities gain preferential access to Asia-Pacific's second-largest oncology device market.
- Cybersecurity certification premiums:ISO 27001-aligned planning platforms command pricing advantages in US hospital systems facing HIPAA enforcement escalation and ransomware insurance requirements.
Industry Challenges
- Medical physicist workforce scarcity:Specialized training requirements for brachytherapy dose calculation and quality assurance create bottlenecks for system utilization expansion.
- Legacy EMR integration complexity:Proprietary data formats from incumbent planning systems resist interoperability with modern hospital information architectures, prolonging implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Brachytherapy Treatment Planning Systems Market |
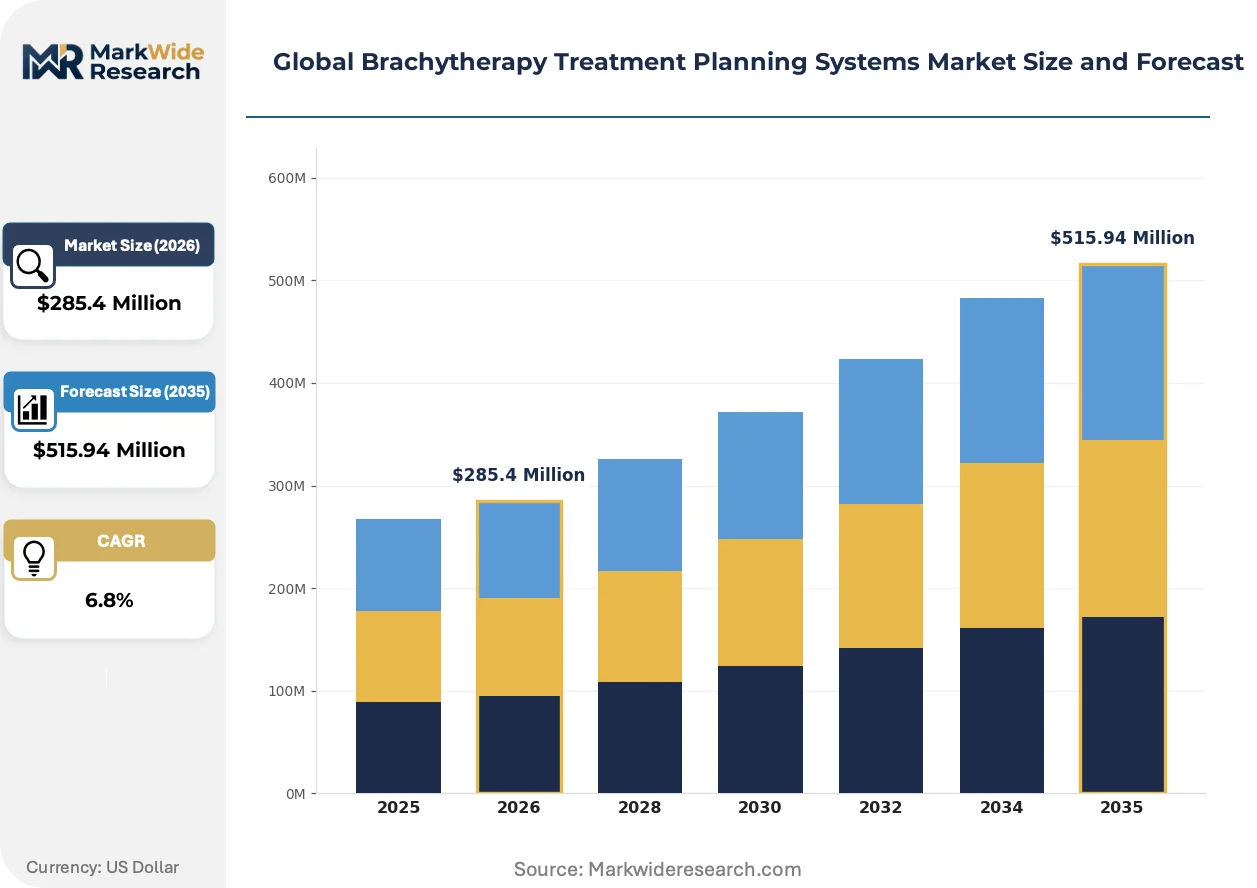
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $515.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low Dose Rate Systems, High Dose Rate Systems, Pulsed Dose Rate Systems, Electronic Brachytherapy Systems Application: Gynecological Cancer, Prostate Cancer, Breast Cancer, Esophageal Cancer, Lung Cancer End User: Oncology Centers, Radiotherapy Clinics, Hospitals, Ambulatory Surgery Centers Deployment Model: On-Premise, Cloud-Based, Hybrid Solutions, Hosted Services |
| Companies Covered | Varian Medical Systems, Elekta AB, MIM Software, RaySearch Laboratories, Prowess Inc., Theragenics Corporation, ALCEN, Eckert & Ziegler BEBIG, CIVCO Medical Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Brachytherapy Treatment Planning Systems Market Shifts & Advancements
Artificial intelligence is penetrating dose optimization workflows, compressing planning time from hours to minutes while introducing new validation protocols for algorithmic decision support in clinical settings.
Deep learning-based auto-segmentation is electrifying anatomical contouring workflows, enabling radiation oncologists at high-volume US academic centers to process prostate and gynecological cases with reduced manual intervention. The technology is compressing departmental throughput constraints and allowing same-day treatment scheduling that was previously operationally impossible.
EU MDR's software-as-a-medical-device classification is forcing vendors to restructure technical documentation and post-market surveillance systems. Manufacturers serving German and French university hospitals are consolidating quality management functions to satisfy notified body expectations for continuous clinical evidence generation.
Subscription pricing for cloud-native planning platforms is displacing perpetual license models in North American health systems. Group purchasing organizations negotiate enterprise agreements spanning multiple hospital sites, with IT directors prioritizing vendors offering centralized security patching and automated backup recovery over on-premise deployment flexibility.
Global Brachytherapy Treatment Planning Systems Market Segmentation
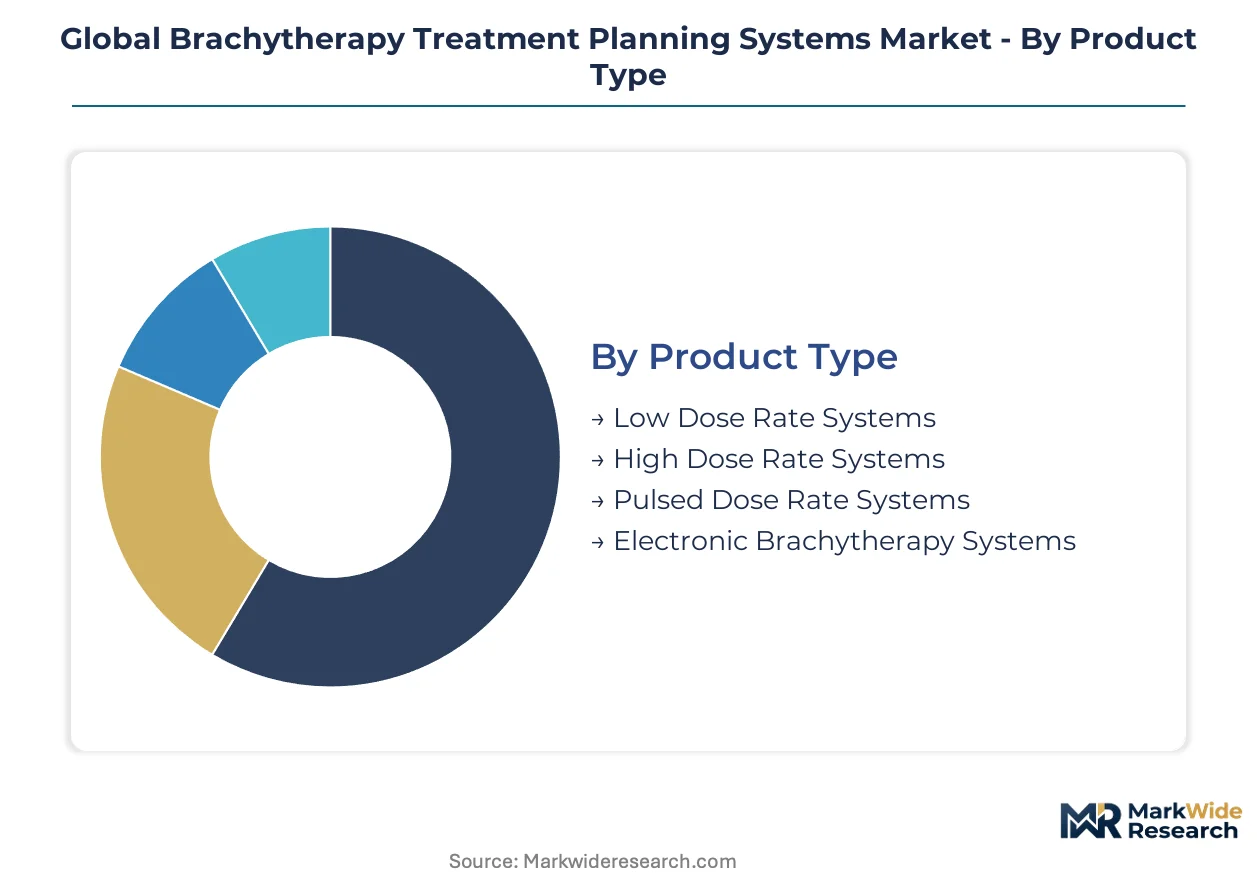
Brachytherapy treatment planning systems fragment across four structural dimensions that determine procurement workflows, regulatory pathways, and clinical utility. Product architecture dictates shielding infrastructure requirements. Deployment models reshape hospital IT governance. Application specialization concentrates expertise and reimbursement patterns. End-user settings determine throughput economics and physicist staffing ratios.
Product Type:
Integration depth varies sharply across dose delivery architectures, with standalone systems demanding dedicated vault construction while embedded platforms leverage existing linear accelerator infrastructure.
- High Dose Rate Systems:Iridium-192 or Cobalt-60 sources deliver radiation in minutes through remote afterloading, enabling outpatient procedures. Demand concentrates in German university hospitals and US National Cancer Institute-designated centers where same-day discharge protocols maximize bed turnover.
- Electronic Brachytherapy Systems:Miniaturized X-ray sources eliminate radioactive isotope handling and shielded bunker requirements, permitting intraoperative deployment in conventional surgical suites. Breast cancer programs at ambulatory surgery centers in France and the United States drive procurement for intraoperative radiation therapy compatibility.
- Low Dose Rate Systems:Permanent seed implants using Iodine-125 or Palladium-103 dominate prostate cancer volume in community hospital settings where physicist staffing constraints favor simpler workflows.
- Pulsed Dose Rate Systems:Hybrid delivery combining LDR biology with HDR logistics sees niche adoption in select European gynecological oncology networks seeking tissue repair intervals.
High Dose Rate Systems lead volumes today; Electronic Brachytherapy Systems is gaining share fastest.
Application:
Margin structures diverge across anatomical sites based on reimbursement complexity, procedure volume, and competitive modality substitution risk.
- Prostate Cancer:Transperineal needle placement with real-time ultrasound guidance demands submillimeter spatial resolution for urethral and rectal sparing. US urology-oncology joint ventures and Dutch proton-brachytherapy hybrid centers concentrate demand for integrated planning workflows.
- Gynecological Cancer:Intracavitary and interstitial applicator configurations for cervical and endometrial malignancies require specialized tandem-and-ovoid or needle template libraries. Tertiary referral networks in France, Germany, and the United Kingdom anchor procurement for complex recurrent disease cases.
- Breast Cancer:Intraoperative radiation therapy and accelerated partial breast irradiation protocols favor electronic brachytherapy for shielding-free deployment in conventional operating theaters.
- Esophageal Cancer:Intraluminal brachytherapy for palliative obstruction relief sees limited but steady utilization in Japanese and South Korean esophageal cancer centers.
- Lung Cancer:Endobronchial brachytherapy for central airway obstruction occupies a narrow niche with constrained growth due to stereotactic body radiation therapy competition.
Prostate Cancer commands the largest installed base; Gynecological Cancer applications are climbing the fastest as MDR-compliant systems penetrate European screening programs.
End User:
Customer scale determines purchasing authority structure, with integrated delivery networks consolidating vendor selection while independent clinics prioritize modular upgrade paths.
- Oncology Centers:Comprehensive cancer centers with dedicated brachytherapy suites require enterprise-grade planning platforms with multi-modality integration and clinical trial data management capabilities.
- Hospitals:General acute care facilities with radiation oncology departments balance capital constraints against case volume sufficiency for physicist staffing justification.
- Radiotherapy Clinics:Freestanding radiation therapy centers focus on throughput optimization and payer mix diversification through high dose rate gynecological service lines.
- Ambulatory Surgery Centers:Outpatient surgical facilities prioritize electronic brachytherapy systems for breast intraoperative radiation therapy where shielded vault construction proves economically prohibitive.
Hospitals retain the dominant procurement volume; Ambulatory Surgery Centers are expanding most quickly as site-of-care migration accelerates.
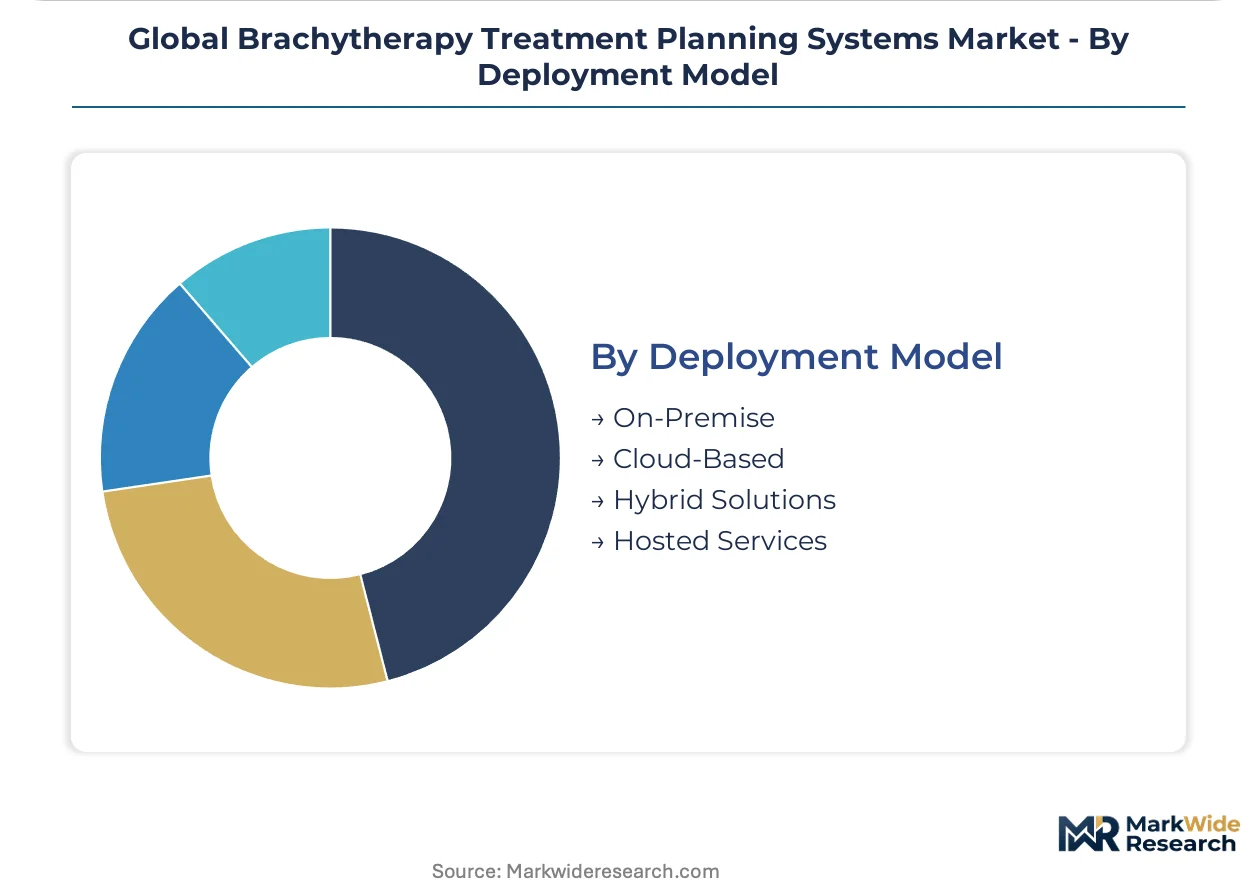
Deployment Model:
IT architecture selection reflects hospital system cybersecurity maturity and multi-site governance complexity.
- Cloud-Based:SaaS delivery enables centralized security patching, automated backup recovery, and remote physicist access for peer review across distributed hospital networks. German and French multi-site oncology consortia prioritize ISO 27001-aligned platforms.
- On-Premise:Local server installation maintains data sovereignty and minimizes external network dependency for institutions with legacy infrastructure investments or stringent institutional review board requirements.
- Hybrid Solutions:Split architectures with local dose calculation engines and cloud-based analytics balance computational latency against collaboration functionality.
- Hosted Services:Vendor-managed private cloud deployments offer intermediate control for mid-sized health systems lacking internal IT security expertise.
On-Premise retains majority installed base; Cloud-Based deployment is expanding most quickly as HIPAA enforcement and ransomware insurance requirements reshape IT governance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brachytherapy treatment planning systems trace their commercial origins to post-war radiation oncology programs in the United States and Sweden, where cobalt-based source technologies first achieved clinical scale before spreading through European university networks and Japanese cancer centers.
United States
MD Anderson Cancer Center and Memorial Sloan Kettering anchor demand for adaptive planning algorithms in prostate and gynecological service lines. FDA 510(k) clearance pathways enable faster software-only market entry compared to hardware-dependent systems. The National Cancer Institute's designated comprehensive cancer centers concentrate procurement authority for enterprise-grade platforms.
Germany
University hospitals in Munich and Heidelberg drive adoption of cloud-based deployment models for multi-site physicist collaboration. EU MDR enforcement compresses vendor timelines for CE marking, forcing front-loaded clinical evidence investments. The country's medical device notified bodies shape quality management expectations for software-as-a-medical-device classification.
France
Gustave Roussy and Institut Curie anchor demand for high dose rate systems in cervical and endometrial cancer protocols. ANSM oversight of Class IIb and III software devices imposes expanded post-market surveillance obligations. Paris and Lyon oncology networks prioritize ISO 27001-aligned cybersecurity certifications for hospital IT governance.
Japan
Tokyo and Osaka cancer centers concentrate procurement for esophageal and lung brachytherapy applications. PMDA localization requirements favor vendors establishing domestic regulatory affairs capabilities. METI funding for precision medicine initiatives accelerates adoption of real-time dwell time optimization technologies.
United Kingdom
The Royal Marsden and Christie NHS Foundation Trust anchor demand for integrated planning workflows in academic radiotherapy networks. MHRA post-Brexit regulatory divergence creates parallel compliance pathways for software validation. London and Manchester oncology consortia negotiate enterprise SaaS agreements spanning multiple hospital sites.
Global Brachytherapy Treatment Planning Systems Market Competitive Landscape
The competitive structure tilts toward diversified radiation therapy equipment manufacturers with installed base leverage. Consolidation around linear accelerator vendors shapes cross-selling dynamics for integrated planning workflows. Three archetypes dominate: diversified therapy platform vendors, specialized oncology software developers, and regional equipment fabricators. M&A activity concentrates on adaptive algorithm capabilities, while strategic partnerships address legacy EMR interoperability gaps.
Among diversified therapy platform vendors, Varian Medical Systems and Elekta AB exemplify archetypes leveraging hardware installed bases for software attach rates. RaySearch Laboratories occupies a position within the specialized oncology software tier, anchoring competitive dynamics around treatment delivery analytics beyond core planning functions. These three entities represent the dominant competitive anchors shaping procurement negotiations in tertiary hospital settings.
| Leading Market Players |
|---|
| Varian Medical Systems |
| Elekta AB |
| MIM Software |
| RaySearch Laboratories |
| Prowess Inc. |
| Theragenics Corporation |
| ALCEN |
| Eckert & Ziegler BEBIG |
| CIVCO Medical Solutions |
| Others |
Supply & Pricing Matrix
Cloud-native deployment architectures are compressing both software delivery costs and vendor consolidation economics, as SaaS infrastructure eliminates on-premise server provisioning while concentrating procurement authority within multi-site hospital networks. This dual compression simultaneously reduces marginal deployment costs for vendors and intensifies price competition for enterprise contracts.
Pricing Analysis
Bundled hardware-software packages from linear accelerator manufacturers command premium positioning against unbundled planning-only licenses. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485 certification status and adaptive algorithm capabilities. Pricing pressure stems from group purchasing organization consolidation in US hospital systems. Ambulatory surgery centers exhibit highest price sensitivity due to capital constraints, while NCI-designated comprehensive cancer centers prioritize functionality over cost.
Supply Chain Analysis
ISO 13485 and FDA 510(k) qualification requirements gate supplier access to hospital procurement channels, filtering component vendors through quality management audits. Software development concentrates in Sweden, the United States, and Germany, with Iridium-192 source production anchored in Canada and South Africa. Supply chain risk centers on single-source dependency for high-activity isotope supply. Distribution runs through authorized medical device distributors with radiation safety licensing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU MDR enforcement timelines and FDA cybersecurity guidance collectively accelerate replacement demand for non-compliant legacy systems.
For Market Incumbents: Cement installed base retention by embedding adaptive planning algorithms into existing linear accelerator workflows before electronic brachytherapy vendors capture intraoperative market share. Deepen backward integration into cloud infrastructure to reduce SaaS delivery costs and defend margin position against specialized software entrants. Prioritize ISO 27001 certification investments to meet HIPAA enforcement escalation in US hospital systems. For New Entrants and Emerging Players: Capture ambulatory surgery center demand for electronic brachytherapy systems where shielded vault requirements exclude conventional HDR vendors. Target Japanese cancer centers through Tokyo-based PMDA regulatory affairs capabilities, as foreign vendor localization creates preferential market access. Pursue hospital IT department relationships emphasizing centralized security patching over clinical workflow features. For Investors and Strategic Acquirers: Roll-up economics work for specialized oncology software developers because MDR compliance costs are forcing smaller vendors toward strategic exit. Long-term viability hinges on adaptive algorithm IP portfolios and cloud-native architecture. Acquisition target archetype: mid-cap planning software vendors with CE-marked platforms and unresolved EMR interoperability gaps. Watch FDA cybersecurity guidance enforcement as inflection signal for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Class IIb software classification compresses vendor timelines for European market entry. |
| Hospital System Partnership | Group purchasing organization agreements consolidate procurement authority across multi-site oncology networks. |
| Software Companion Development | AI-based auto-segmentation modules reduce planning time and enable same-day treatment scheduling. |
| Reimbursement Strategy | CPT code alignment for HDR outpatient procedures expands addressable patient volumes beyond inpatient wards. |
| FDA Submission | 510(k) clearance for cloud-based platforms enables faster US market entry compared to hardware-dependent systems. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region's major oncology networks. The analysis combines structured interviews with radiation oncologists, medical physicists, hospital purchasing committee members, and GPO contracts managers with secondary validation from FDA 510(k) filings, EU MDR notified body documentation, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up demand modeling triangulates against top-down market sizing.
Granularity-level modeling extends to product type, deployment architecture, application site, and end-user setting dimensions across the analysis window. CAGRs derive from segment-level volume projections calibrated to installed base replacement cycles and regulatory compliance deadlines. Forecast inputs incorporate medical physicist workforce growth constraints and cloud adoption curves in German and French multi-site consortia.
Regulatory timeline delays, cybersecurity incident frequency, and isotope supply disruptions are the dominant revision risks. Deviation in EU MDR notified body capacity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Additional Defibrillator Accessories (AED) Market
Medical Devices
Pulse Electromagnetic Field (PEMF) Therapy Devices Market
Medical Devices
Global Stroke Assistive Devices Market
Medical Devices
Acoustic Puncture Assist Devices Market
Medical Devices
Global on-Body Injectors Market
Medical Devices
Global Cochlear Implant Market
Medical Devices
Gastric Electrical Stimulators Market
Medical Devices
Global Blood Warmer Devices Market
Medical Devices
Remote Magnetic Catheter Systems Market
Medical Devices
Global Intraoral Cameras Market
Medical Devices
Capnography Devices Market
Medical Devices
Prefilled Syringe Small Molecule Market
Medical Devices
Struts Implants Market
Medical Devices
France Ophthalmic Devices Market
Medical Devices
South Korea ECG Market
Medical Devices
Canada Aesthetic Devices Market