
 Global Surgical Imaging Arms Market | 2026-2036
Global Surgical Imaging Arms Market Size, Share, and Industry Trends Forecast 2026-2036
Global Surgical Imaging Arms Market Intelligence
Modular system bundling is recalibrating capital procurement decisions across hospital networks. Siemens Healthineers leverages integrated software-hardware packages to anchor long-term service contracts in European accounts. GE Healthcare competes through backward integration into detector manufacturing, sustaining margin control across its mobile imaging portfolio. Koninklijke Philips differentiates via open-architecture platforms that accommodate third-party surgical navigation systems.
Surgical imaging arms are electromechanical positioning systems with articulated joints enabling fluoroscopic, digital radiographic, or tomographic image acquisition during operative procedures; typical specifications include isocentric rotation ranges exceeding 180 degrees and payload capacities above 20 kilograms for C-arm configurations. Ceiling-mounted systems lead capital expenditure in greenfield hospital construction, while mobile units capture replacement demand in budget-constrained ambulatory surgical centers. Cone beam CT represents the fastest-growing technology segment as orthopedic and neurosurgical protocols integrate intraoperative three-dimensional verification into standard workflow.
The FDA's 510(k) clearance framework and the EU Medical Device Regulation (MDR) impose divergent clinical evidence requirements, fragmenting product registration timelines and shaping regional launch sequencing. Japan's PMDA enforces JIS electromagnetic compatibility standards that constrain design commonality with North American platforms. Stakeholders must monitor regulatory convergence negotiations between the FDA and European notified bodies to anticipate unified quality management system expectations.
Market Dynamics
Ceiling-mounted surgical imaging systems are displacing mobile C-arms in greenfield hospital construction as hybrid operating suites become standard infrastructure for complex procedures.
Growth Catalysts
- Cone Beam CT Integration:Orthopedic and neurosurgical protocols now mandate intraoperative three-dimensional verification, pulling fluoroscopic systems toward volumetric imaging capabilities.
- Germany's Hospital Modernization:University hospitals in Berlin, Munich, and Heidelberg are retrofitting surgical suites with integrated imaging arms to support minimally invasive spine and trauma procedures.
- FDA 510(k) Pathway Evolution:Tightened documentation requirements for intraoperative CT submissions are accelerating quality system investments among device manufacturers seeking US market access.
Market Restraints
- Detector Supply Concentration:Flat-panel detector manufacturing concentrates in Japan and South Korea, creating input cost volatility for mobile imaging system producers.
- EU MDR Clinical Evidence Burden:The Medical Device Regulation's expanded clinical evaluation requirements extend product registration timelines by 12-18 months for European launches.
- Service Contract Lock-In:Integrated software-hardware bundling by incumbent vendors raises switching costs for hospital networks seeking competitive alternatives.
Strategic Opportunities
- Ambulatory Surgical Center Penetration:Freestanding ASCs in Texas, Florida, and California represent underdeployed demand for refurbished and entry-level mobile C-arm systems.
- Open-Architecture Convergence:Third-party surgical navigation integration is expanding into platforms that previously operated as closed ecosystems, enabling modular procurement.
- Japan PMDA Electromagnetic Harmonization:Negotiations between Japanese regulators and FDA toward mutual recognition of EMC testing could collapse dual certification costs for multi-region launches.
Industry Challenges
- Biomedical Engineer Shortage:Servicing articulated arm systems with isocentric precision requires specialized training that outpaces current vocational pipeline output in most markets.
- Legacy PACS Integration:Picture archiving and communication systems from the 2010s lack native interoperability with modern DICOM-RT interfaces, forcing costly middleware deployments.
Report Scope
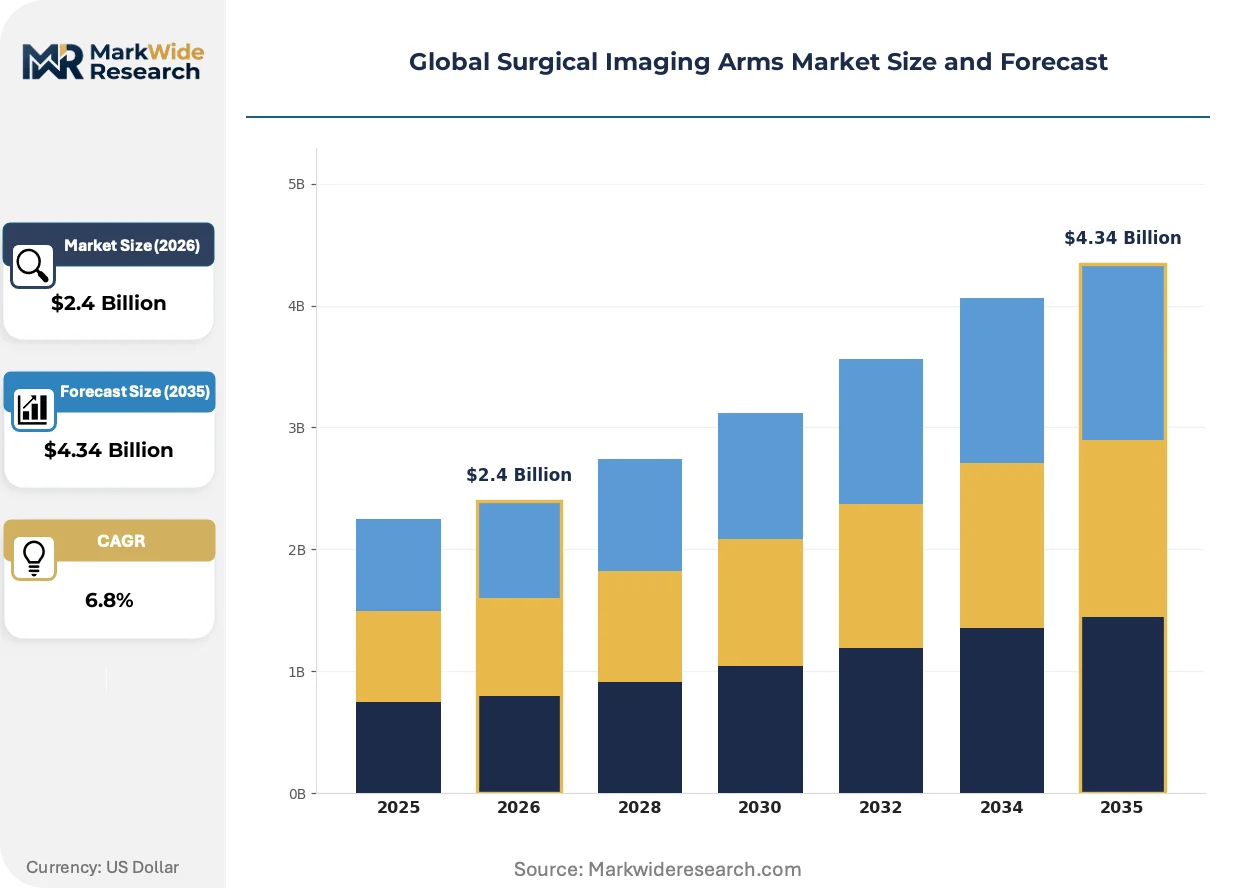
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Surgical Imaging Arms Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ceiling-Mounted, Mobile, Hybrid, Table-Mounted Technology: Fluoroscopy, Digital Radiography, 3D Imaging, Cone Beam CT, Intraoperative CT Application: Neurosurgery, Orthopedic Surgery, Cardiovascular Procedures, Urology, Interventional Radiology End User: Hospitals, Ambulatory Surgical Centers, Diagnostic Imaging Centers, Specialty Clinics |
| Companies Covered | GE Healthcare, Siemens Healthineers, Koninklijke Philips, Ziehm Imaging GmbH, Shimadzu Corporation, Canon Medical Systems Corporation, Hologic Inc., ATON GmbH, Whale Imaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Surgical Imaging Arms Market Strategic Shifts & Innovations
Articulated positioning systems are converging with intraoperative navigation, compressing the boundary between imaging acquisition and surgical guidance into unified workflow platforms.
Flat-panel detector technology is expanding into surgical C-arms from diagnostic radiology origins, replacing image intensifiers with solid-state arrays that deliver superior dose efficiency and spatial resolution. Academic medical centers in the United States and Germany are adopting these systems for complex spine and trauma procedures. The technology is expanding into mid-tier community hospitals as refurbishment programs and detector leasing models collapse capital barriers.
The EU Medical Device Regulation's post-market surveillance requirements are forcing manufacturers to deploy real-time performance monitoring across installed bases. Notified bodies in Germany and the Netherlands now demand systematic clinical follow-up data for Class IIb imaging devices. Japanese manufacturers with legacy European approvals face compressed timelines to transition MDD certificates to MDR compliance before 2027 expiration deadlines.
After-sales service unbundling is fragmenting traditional vendor-captive relationships as third-party independent service organizations capture maintenance contracts for out-of-warranty systems. Hospital procurement departments in the United Kingdom and Australia are mandating separate pricing disclosure for hardware, software, and service components. This transparency is accelerating competitive pressure on incumbent service pricing while creating entry points for specialized imaging service firms.
Global Surgical Imaging Arms Market Segmentation
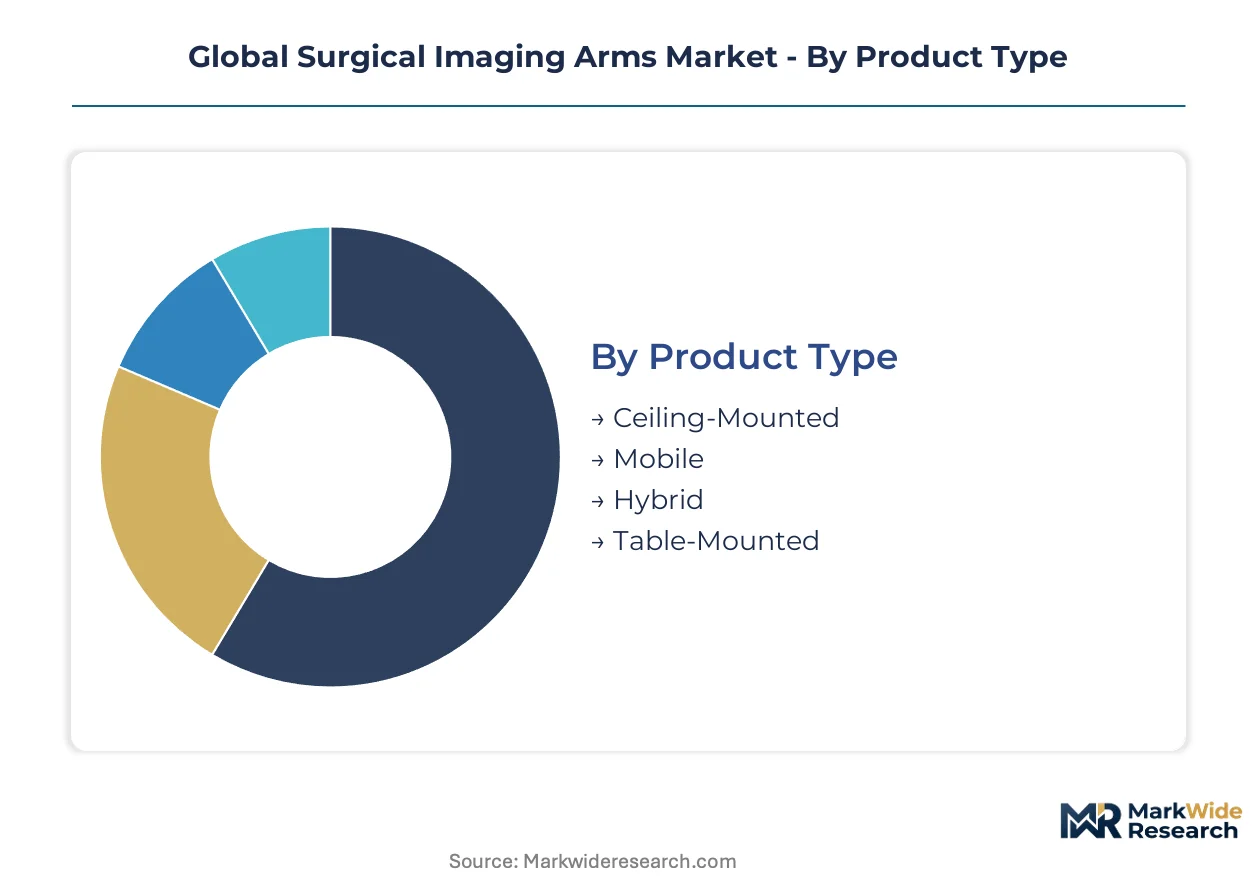
Surgical imaging arms segment across four dimensions that shape procurement workflows, regulatory pathways, and service contract structures. Product type determines installation infrastructure and capital commitment. Technology tier dictates clinical evidence requirements and reimbursement positioning. Application and end-user categories channel demand toward distinct performance specifications and price points.
Product Type:
Regulatory burden varies sharply: ceiling-mounted and hybrid systems trigger Class IIb designations under EU MDR with mandatory clinical evaluation, while mobile units often clear via streamlined 510(k) pathways in the United States.
- Ceiling-Mounted:Permanent installation with isocentric rotation exceeding 180 degrees and payload capacity above 20 kilograms. University hospitals in Germany—Berlin, Munich, Heidelberg—anchor demand as hybrid operating suites become standard infrastructure for complex spine and trauma procedures.
- Mobile:Articulated C-arms on motorized bases enabling intraoperative repositioning without structural modification. Ambulatory surgical centers in Texas, Florida, and California drive replacement demand where budget constraints preclude fixed installations.
- Hybrid:Dual-configuration systems supporting both fixed-room and portable deployment through detachable mounting interfaces. These command premium positioning in greenfield hospital construction.
- Table-Mounted:Compact articulating arms integrated directly with surgical tables for specialized urology and interventional radiology workflows.
Leading the category by volume: Mobile systems. Growing fastest: Hybrid configurations.
Technology:
Cost tier stratification separates premium volumetric systems from standard fluoroscopic platforms, with reimbursement differentials widening the investment gap between academic medical centers and community hospitals.
- Cone Beam CT:Volumetric imaging with sub-millimeter isotropic resolution enabling intraoperative three-dimensional verification. Orthopedic and neurosurgical protocols now mandate this capability, pulling fluoroscopic systems toward tomographic functionality.
- Intraoperative CT:Full gantry CT integrated into surgical suites for real-time anatomical confirmation. The FDA's tightened 510(k) documentation requirements for these submissions accelerate quality system investments among manufacturers seeking US market access.
- Fluoroscopy:Continuous X-ray imaging with digital subtraction angiography capabilities for cardiovascular and interventional procedures.
- Digital Radiography:Static high-resolution capture replacing film-based systems in budget-constrained settings.
- 3D Imaging:Reconstructed tomographic views from rotational fluoroscopy data without dedicated CT hardware.
Dominating procurement value: Intraoperative CT. Expanding most quickly: Cone Beam CT.
Application:
Customer type concentration varies by surgical discipline—neurosurgery and orthopedics cluster in academic medical centers, while cardiovascular and urology procedures distribute across community hospitals and freestanding ASCs.
- Neurosurgery:Demands sub-millimeter spatial resolution and electromagnetic compatibility with surgical navigation systems. German university hospitals retrofit suites specifically for minimally invasive cranial and spinal procedures.
- Orthopedic Surgery:Trauma, spine, and joint reconstruction procedures requiring intraoperative three-dimensional verification of implant positioning. Flat-panel detector technology penetrates fastest here as refurbishment programs collapse capital barriers.
- Cardiovascular Procedures:Digital subtraction angiography and rotational imaging for structural heart interventions.
- Urology:Endourological and percutaneous procedures utilizing table-mounted compact configurations.
- Interventional Radiology:Minimally invasive diagnostic and therapeutic procedures demanding rapid imaging acquisition.
Commanding highest average selling prices: Neurosurgery. Gaining share fastest: Orthopedic Surgery.
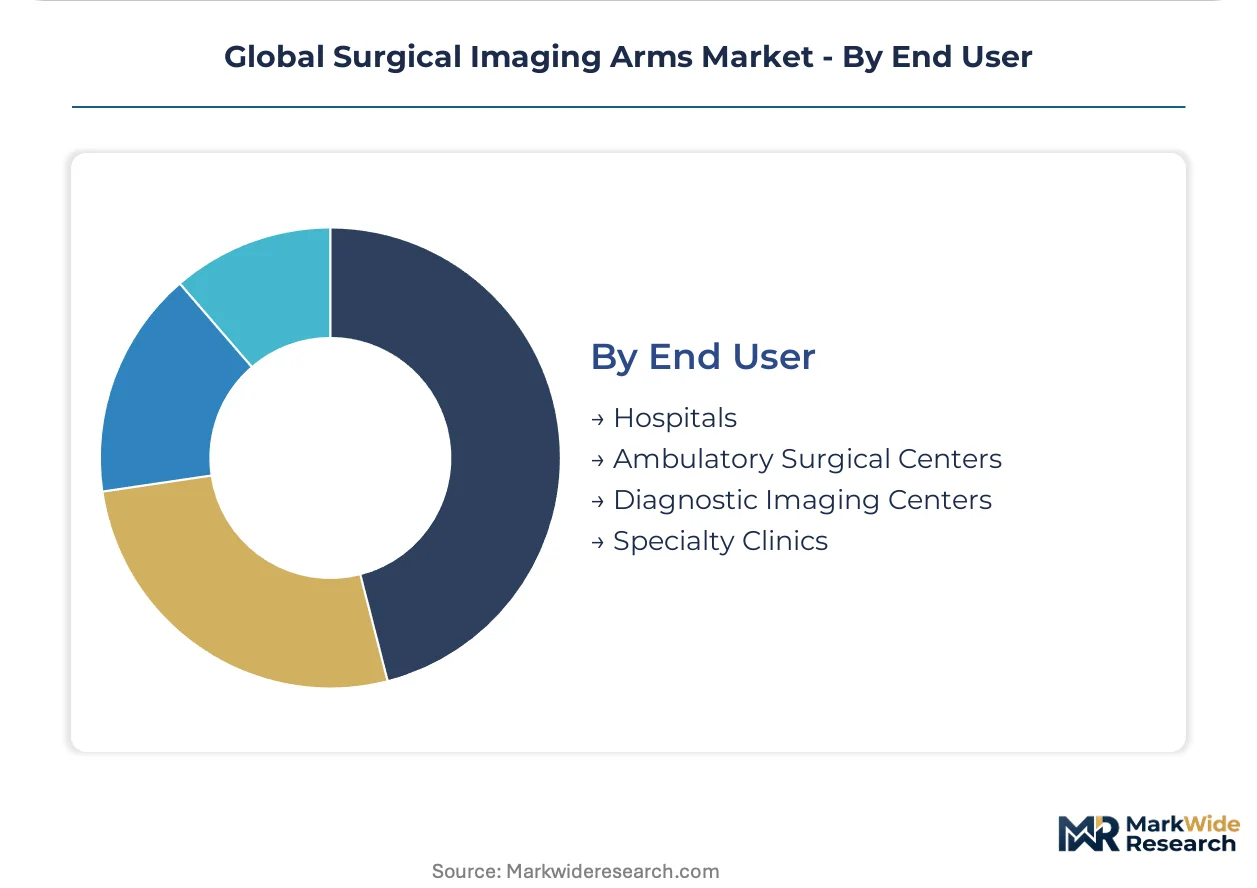
End User:
Supply concentration in detector manufacturing—Japan and South Korea—creates input cost volatility that propagates differently across customer tiers, with hospitals absorbing premiums through bundled service contracts while ASCs seek refurbished alternatives.
- Hospitals:Integrated hybrid operating suites with ceiling-mounted systems and captive long-term service agreements. Procurement departments in the United Kingdom and Australia now mandate separate pricing disclosure for hardware, software, and service components.
- Ambulatory Surgical Centers:Freestanding facilities in Texas, Florida, and California represent underdeployed demand for refurbished and entry-level mobile C-arm systems.
- Diagnostic Imaging Centers:Specialized facilities requiring high-throughput configurations with rapid patient turnaround.
- Specialty Clinics:Concentrated orthopedic, pain management, and vein care practices utilizing compact mobile units.
Generating largest absolute revenue: Hospitals. Expanding addressable market fastest: Ambulatory Surgical Centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Detector manufacturing concentrates in Japan and South Korea, while consumption clusters in Germany and the United States where hospital modernization accelerates. This production-consumption divide shapes trade flows and regional pricing dynamics across the forecast window.
United States
Freestanding ambulatory surgical centers in Texas, Florida, and California drive replacement demand for mobile C-arm systems where budget constraints preclude fixed installations. The FDA's tightened 510(k) documentation requirements for intraoperative CT submissions accelerate quality system investments among manufacturers seeking US market access. Academic medical centers in Boston and Stanford retrofit surgical suites with integrated imaging arms for complex spine procedures.
Germany
University hospitals in Berlin, Munich, and Heidelberg anchor European demand as hybrid operating suites become standard infrastructure for minimally invasive spine and trauma procedures. The EU Medical Device Regulation's expanded clinical evaluation requirements extend product registration timelines by 12-18 months for European launches. The Baden-Württemberg medical technology cluster concentrates engineering talent for articulated arm system development.
Japan
Flat-panel detector manufacturing concentrates domestically, creating input cost advantages for indigenous mobile imaging system producers. The PMDA enforces JIS electromagnetic compatibility standards that constrain design commonality with North American platforms. Tokyo and Osaka medical centers drive adoption of cone beam CT for orthopedic and neurosurgical protocols requiring intraoperative three-dimensional verification.
United Kingdom
Hospital procurement departments mandate separate pricing disclosure for hardware, software, and service components, accelerating competitive pressure on incumbent service pricing. NHS England's capital expenditure frameworks prioritize ceiling-mounted systems in greenfield hospital construction. The Oxford-Cambridge-London golden triangle concentrates academic research driving intraoperative navigation integration.
Australia
Public hospital networks in New South Wales and Victoria unbundle after-sales service contracts, creating entry points for specialized imaging service firms. The TGA's alignment with EU MDR clinical evidence requirements fragments product registration timelines for European manufacturers. Melbourne and Sydney academic medical centers lead adoption of open-architecture platforms accommodating third-party surgical navigation systems.
Global Surgical Imaging Arms Market Key Industry Players
The competitive structure tilts toward diversified medical technology conglomerates with captive detector supply chains and long-term service contract anchoring. Siemens Healthineers, GE Healthcare, and Koninklijke Philips occupy positions that leverage integrated software-hardware bundling to raise hospital switching costs. Strategic archetypes include: full-stack imaging platform providers, specialized mobile C-arm fabricators, and third-party independent service organizations capturing maintenance contracts for out-of-warranty systems. Dominant competitive moves center on backward integration into detector manufacturing and open-architecture platform development enabling modular procurement.
Among diversified conglomerates, Siemens Healthineers AG and GE Healthcare exemplify the full-stack archetype through integrated software-hardware packages that anchor long-term service relationships. Ziehm Imaging GmbH represents the specialized mobile C-arm fabricator tier, occupying a position focused on articulated positioning systems for intraoperative fluoroscopy. Koninklijke Philips N.V. anchors the open-architecture convergence vector, exemplifying platform strategies that accommodate third-party surgical navigation integration. These three entities collectively illustrate the strategic positioning spectrum—from bundled ecosystem control to modular interoperability—that defines competitive differentiation in capital procurement decisions.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Koninklijke Philips |
| Ziehm Imaging GmbH |
| Shimadzu Corporation |
| Canon Medical Systems Corporation |
| Hologic Inc. |
| ATON GmbH |
| Whale Imaging |
| Others |
Cost & Logistics Intelligence
Flat-panel detector manufacturing costs in Japan and South Korea cascade through three pricing tiers as hospital procurement departments unbundle hardware, software, and service components. This input concentration amplifies margin pressure on mobile C-arm producers serving budget-constrained ambulatory surgical centers.
Pricing Analysis
Margin tightening in entry-level mobile systems reflects detector leasing models and refurbishment programs collapsing capital barriers for ambulatory surgical centers. Three-tier pricing structure across premium, standard, and economy levels separates ceiling-mounted hybrid suites from mobile C-arms and refurbished units. Price differentiation hinges on after-sales service bundling and FDA 510(k) clearance tier. Ambulatory surgical centers in Texas, Florida, and California exhibit highest price sensitivity; German university hospitals demonstrate lowest.
Supply Chain Analysis
Japan's PMDA electromagnetic compatibility standards and domestic-content preferences reshape sourcing patterns for articulated arm assemblies. Flat-panel detector fabrication concentrates in Japan and South Korea; precision machining of isocentric rotation components draws from Germany and Switzerland. Single-source vulnerability in amorphous silicon sensor supply creates exposure to semiconductor foundry allocation shifts. Distribution runs through hospital procurement committees and group purchasing organizations with multi-year contract cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Detector fabrication capacity constraints in East Asia prop pricing power for manufacturers with captive supply arrangements. This supply bottleneck sustains margin premiums for integrated producers across the analysis window.
For Market Incumbents: Anchor long-term service relationships through software-hardware bundling that raises hospital switching costs. Deepen backward integration into detector manufacturing to sustain margin control against third-party independent service organizations capturing out-of-warranty maintenance contracts. Prioritize MDR certificate transition ahead of 2027 expiration deadlines.
For New Entrants and Emerging Players: Capture ambulatory surgical center demand for refurbished and entry-level mobile C-arm systems in Texas, Florida, and California where budget constraints preclude fixed installations. Target open-architecture platform development enabling third-party surgical navigation integration. Pursue detector leasing models as primary go-to-market mechanism.
For Investors and Strategic Acquirers: FDA-EU regulatory convergence negotiations toward unified quality management system expectations are the leading indicator that multi-region launch economics will shift favorably. Five-to-ten year viability favors diversified conglomerates with captive detector supply chains and installed base service density. Monitor PMDA electromagnetic harmonization progress with FDA as inflection signal for Japanese market entry cost collapse.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Tightened documentation requirements accelerate quality system investments among manufacturers seeking US market access. |
| CE Marking Pathway | MDR expanded clinical evaluation requirements extend registration timelines for European launches. |
| Hospital System Partnership | Procurement departments in United Kingdom and Australia mandate separate pricing disclosure for hardware, software, and service components. |
| Software Companion Development | Integrated platforms compress boundary between imaging acquisition and surgical guidance into unified workflow. |
| Reimbursement Strategy | Cone beam CT integration into orthopedic and neurosurgical protocols mandates intraoperative three-dimensional verification. |
Research Approach
FDA 510(k) clearance databases, EU MDR notified body documentation, and hospital procurement records formed the secondary backbone of this analysis. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and aftermarket service heads combined with secondary validation. Bottom-up and top-down triangulation anchored volume and value estimates.
Bottom-up modeling segmented demand across product type, technology tier, application, and end-user categories; top-down cross-checks validated aggregate market scale. CAGRs derived from weighted regression across technology adoption curves, replacement cycles, and capital expenditure patterns. Forecast inputs incorporated regulatory pathway timelines, detector supply constraints, and hybrid operating suite construction pipelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to PMDA-FDA harmonization progress, detector foundry allocation shifts, and EU MDR certificate transition deadlines. Forecasts reflect assumptions around regulatory stability, supply continuity, and capital expenditure trajectories in hospital modernization programs. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Germany Digital X-Ray Market
Medical Imaging
X-Ray Flat Panel Detectors Market
Medical Imaging
Automated Contouring Radiotherapy Software Market
Medical Imaging
Meningitis Imaging Market
Medical Imaging
Dual and Multi-Energy Computed Tomography (CT) Market
Medical Imaging
Mexico Computed Tomography Market
Medical Imaging
Global Confocal Microscope Market
Medical Imaging
Veterinary Imaging Systems Market
Medical Imaging
Mexico Diagnostic Imaging Equipment Market
Medical Imaging
Japan Diagnostic Imaging Equipment Market
Medical Imaging
Global Spinal Imaging Treatment Market
Medical Imaging
Digital X Ray Market
Medical Imaging
Europe Open System MRI Market
Medical Imaging
Spain Digital Radiology Market
Medical Imaging
Brain PET-MRI Systems Market
Medical Imaging
United States Computed Tomography Market