
 Global Magnetic Resonance Imaging System Market | 2026-2036
Global Magnetic Resonance Imaging System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Magnetic Resonance Imaging System Market Foresight
The EU Medical Device Regulation (MDR) is hardening compliance requirements for electromagnetic compatibility and clinical evidence, forcing manufacturers to redesign quality management systems. Siemens Healthineers anchors its position through captive superconducting wire production and direct service networks across Western Europe. GE HealthCare competes by leveraging AI-integrated reconstruction software that reduces scan times in busy hospital workflows. Koninklijke Philips N.V. differentiates through modular system architectures that allow field upgrades from 1.5T to 3T without full room reconstruction.
Magnetic resonance imaging systems employ strong static magnetic fields, typically 0.2 to 7 Tesla, generated by superconducting, permanent, or resistive magnets to align hydrogen nuclei in tissue; radiofrequency pulses disturb this alignment, and received echo signals reconstruct cross-sectional anatomical images for non-invasive diagnostic evaluation. Closed MRI systems dominate installed base value due to superior signal-to-noise ratios at 1.5T and 3T field strengths, while portable MRI represents the fastest-expanding product category as point-of-care neurology screening migrates beyond traditional radiology suites. Superconducting magnets command the technology segment's margin pool because of helium cryogen dependency and specialized refurbishment cycles that lock customers into long-term service contracts.
The FDA's 510(k) pathway and the EU MDR's notified body surveillance reshape product development timelines, while ISO 13485 quality system certification remains mandatory for supply access across both jurisdictions. China's NMPA now requires domestic clinical trials for imported Class III imaging devices, extending registration timelines for multinational manufacturers. Stakeholders must monitor helium supply chain restructuring as alternative cryogen-free magnet designs approach commercial viability and threaten incumbent service revenue models.
Market Dynamics
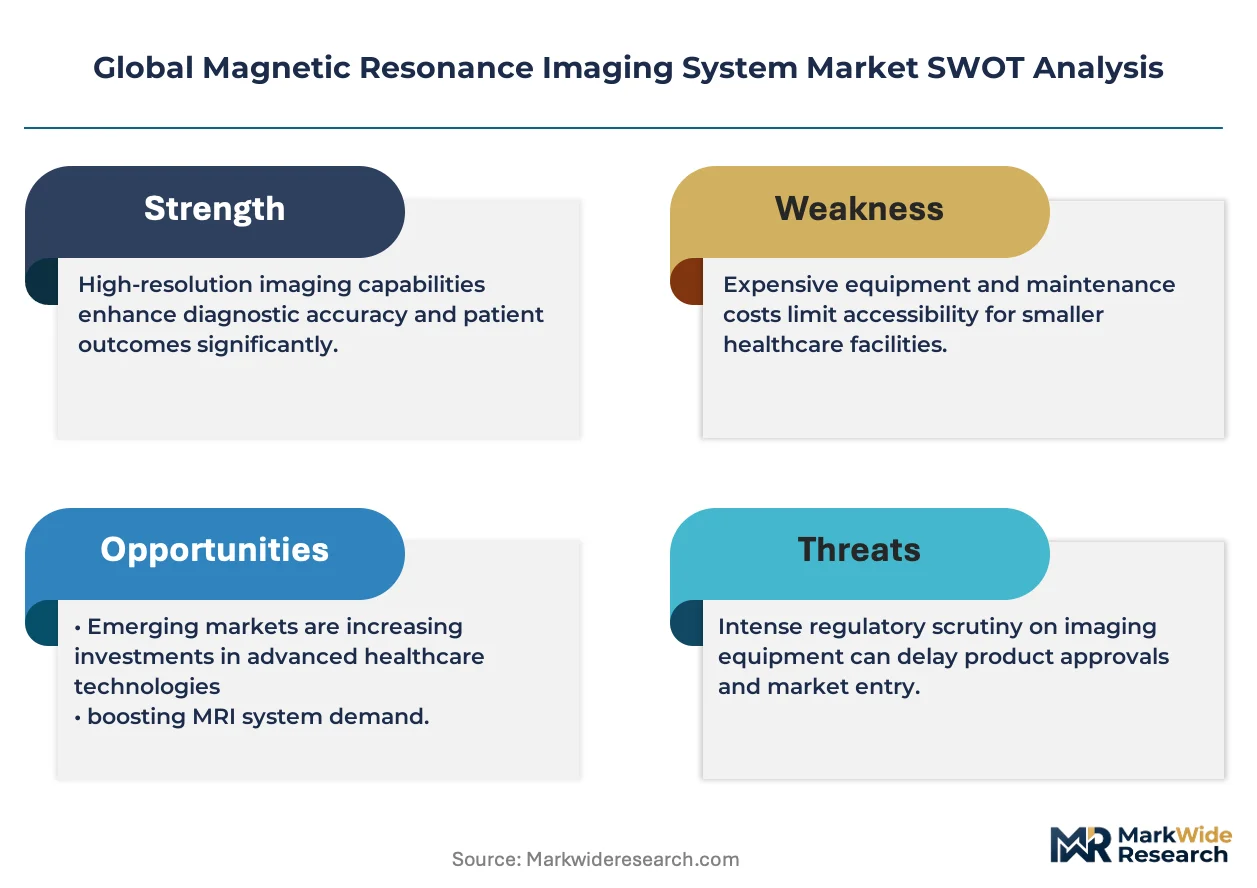
Helium supply chain restructuring and the FDA's 510(k) modernization initiative are compressing product development timelines while forcing manufacturers to redesign service revenue models around cryogen-free magnet architectures.
Growth Catalysts
- Oncology expansion:Academic medical centers in Germany are scaling MRI-guided radiotherapy programs, creating installed base demand for high-field systems with integrated planning software.
- AI-integrated reconstruction:Deep learning algorithms are reducing scan times in high-throughput hospital workflows, improving asset utilization rates for capital-intensive equipment.
- EU MDR compliance:Hardened electromagnetic compatibility requirements are filtering out marginal suppliers and consolidating procurement toward full-service manufacturers with captive quality management systems.
Market Restraints
- Helium price volatility:Superconducting magnet dependency on liquid helium creates input cost exposure as geopolitical supply disruptions constrain Qatar and Russia export volumes.
- China NMPA localization:Mandatory domestic clinical trials for imported Class III devices extend registration timelines and duplicate development expenditure for multinational manufacturers.
- Portable MRI performance ceiling:Low-field permanent magnet designs face signal-to-noise ratio limitations that restrict diagnostic confidence in complex neurological applications.
Strategic Opportunities
- India private chains:Diagnostic imaging center consolidation is accelerating as public hospital procurement cycles lengthen, creating volume concentration for equipment financiers.
- Cryogen-free magnet convergence:High-temperature superconductor and permanent magnet hybrid designs threaten incumbent service contract lock-in by eliminating helium logistics dependency.
- Point-of-care neurology:Emergency department stroke triage protocols are expanding addressable demand beyond traditional radiology suite footprints into intensive care settings.
Industry Challenges
- Superconducting wire talent scarcity:Specialized cryogenic engineering and magnet winding expertise concentrates at a handful of academic programs and incumbent manufacturers.
- ISO 13485 certification timelines:Quality system surveillance audits and technical documentation updates consume 18-24 month product launch windows across FDA and EU MDR jurisdictions.
- Legacy system integration:Hospital information system connectivity requirements and DICOM conformance testing multiply deployment complexity for mixed-vendor imaging environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Magnetic Resonance Imaging System Market |
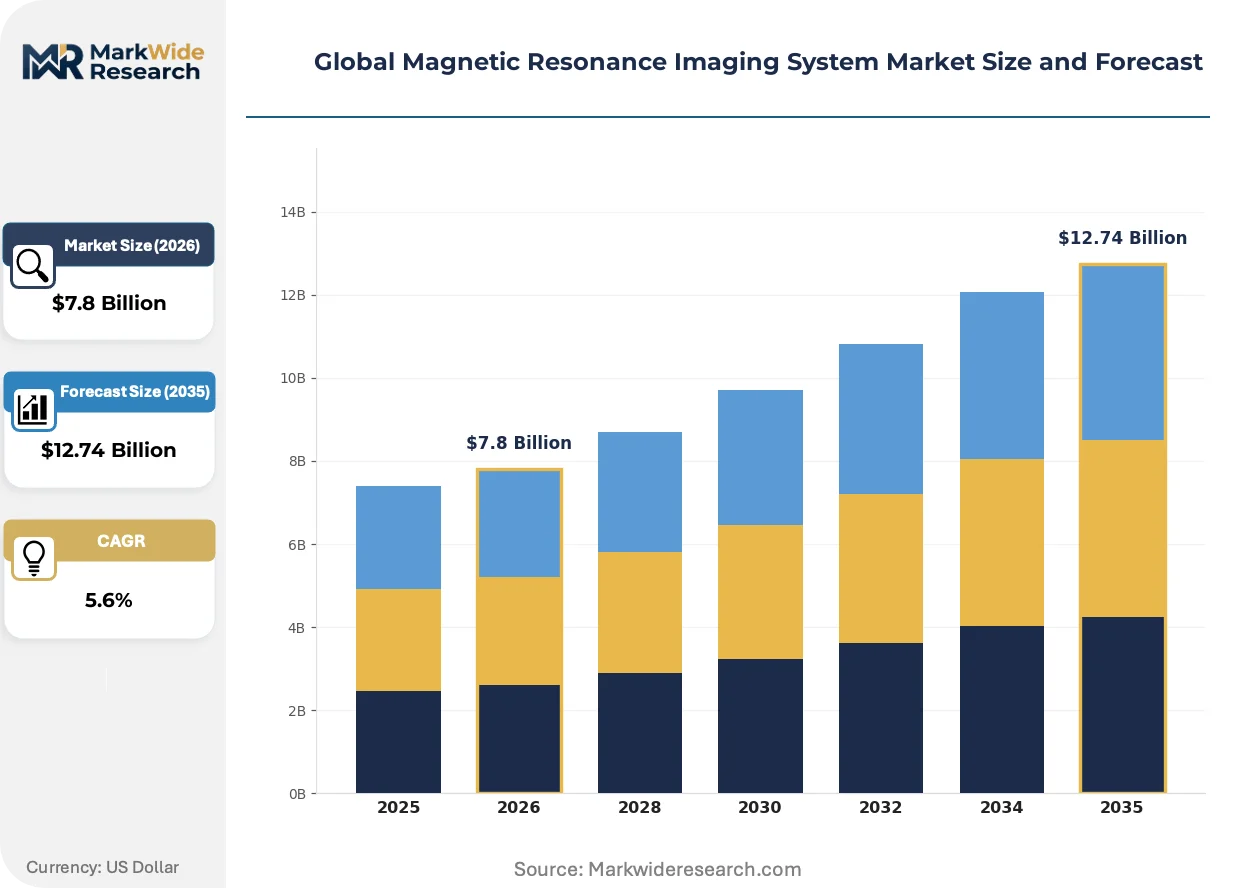
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.74 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open MRI, Closed MRI, Ultra-high Field MRI, Low-field MRI, Portable MRI Application Area: Neurology, Cardiology, Oncology, Orthopedics, Musculoskeletal End User: Hospitals, Diagnostic Imaging Centers, Ambulatory Surgical Centers, Research Institutes Technology: Superconducting Magnets, Permanent Magnets, Resistive Magnets, Hybrid Magnets |
| Companies Covered | Siemens Healthineers, GE HealthCare, Koninklijke Philips N.V., Canon Medical Systems Corporation, FUJIFILM Corporation, Esaote S.p.A, Shanghai United Imaging Healthcare, Bruker Corporation, Hitachi Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Magnetic Resonance Imaging System Market Shifts & Advancements
Reconstruction software, regulatory surveillance, and procurement concentration are simultaneously compressing scan economics, extending compliance timelines, and reshaping buyer-vendor power dynamics across the installed base.
Deep learning-based image reconstruction is automating noise reduction and acquisition acceleration in 3T neurological protocols. Tertiary care hospitals in the United States and Western Europe are deploying these algorithms to double daily patient throughput without magnet replacement. The technology is automating radiologist workflow prioritization by generating diagnostic-quality images from abbreviated scan sequences.
The EU MDR's notified body surveillance and clinical evidence requirements are hardening market access barriers for electromagnetic compatibility certification. Manufacturers must now submit post-market surveillance data and risk management updates that duplicate FDA 510(k) documentation burdens. High-field closed systems face the steepest compliance cost escalation as legacy predicates lose validity under tightened equivalence standards.
Diagnostic chains in India are consolidating procurement decisions at the holding-company level, displacing individual center autonomy in vendor selection. Equipment leasing and managed service contracts are replacing outright purchase for mid-field systems in tier-two cities. This concentration is most visible in Maharashtra and Karnataka, where private equity-backed platforms standardize on single-manufacturer fleets to reduce training and spare parts complexity.
Global Magnetic Resonance Imaging System Market Segmentation
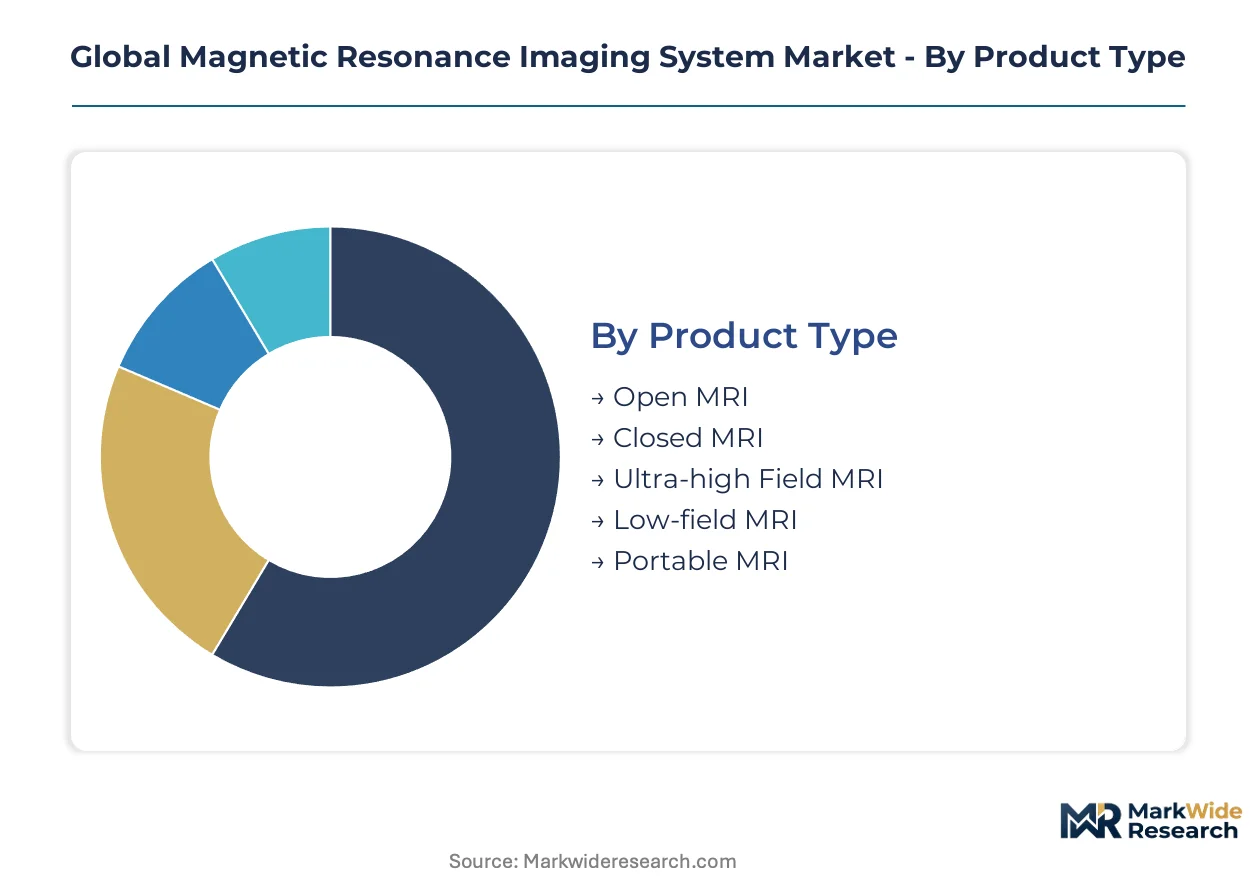
Magnetic resonance imaging systems fragment across technical architectures, clinical applications, and procurement channels that each impose distinct performance requirements and commercial constraints. Understanding these segment boundaries clarifies where capital deployment concentrates and where technology substitution threatens incumbent positions.
Product Type:
Field strength and magnet geometry define the fundamental trade-off between image fidelity and operational flexibility across installation environments.
- Closed MRI:Cylindrical bore designs with 1.5T and 3T superconducting magnets generate superior signal-to-noise ratios for neurological and oncological diagnostics. Academic medical centers in Germany anchor demand for these systems as MRI-guided radiotherapy programs expand.
- Portable MRI:Low-field permanent magnet configurations weighing under 500 kilograms enable point-of-care deployment in intensive care units and emergency departments. Neurology screening protocols in the United States are migrating beyond traditional radiology suites into distributed clinical settings.
- Open MRI:Vertical or horizontal gap architectures accommodate claustrophobic patients and larger body habitus with reduced field strength trade-offs.
- Ultra-high Field MRI:7 Tesla systems deliver sub-millimeter resolution for research applications requiring spectroscopic tissue characterization.
- Low-field MRI:Sub-0.5T designs serve cost-constrained markets where diagnostic confidence requirements permit reduced spatial resolution.
Closed MRI leads on scale; Portable MRI leads on momentum.
Application Area:
Clinical specialization dictates coil configurations, sequence protocols, and software licensing structures that segment the installed base.
- Neurology:Brain and spinal cord imaging demands high-field systems with specialized phased-array coils and diffusion-weighted sequence capabilities. Stroke triage protocols in the United States are expanding addressable demand beyond traditional radiology footprints.
- Oncology:Tumor staging and treatment monitoring require multi-parametric imaging with integrated positron emission tomography compatibility. German academic medical centers are scaling MRI-guided radiotherapy programs that fuse real-time anatomical imaging with radiation delivery.
- Cardiology:Cardiac MRI employs cine sequences and late gadolinium enhancement for functional and viability assessment.
- Orthopedics:Musculoskeletal protocols prioritize dedicated extremity coils and high-resolution cartilage imaging.
- Musculoskeletal:Sports medicine applications concentrate in ambulatory settings requiring rapid throughput and patient throughput optimization.
Neurology commands the largest installed base; Oncology is climbing the fastest as radiotherapy integration accelerates.
End User:
Procurement authority and capital availability diverge sharply between consolidated hospital systems and fragmented independent operators.
- Hospitals:Tertiary care institutions with captive radiology departments deploy high-field systems for comprehensive diagnostic services. India's public hospital procurement cycles are lengthening, displacing volume toward private diagnostic chains.
- Diagnostic Imaging Centers:Independent operators and chain affiliates prioritize asset utilization rates and lease financing structures. Maharashtra and Karnataka in India are witnessing consolidation as private equity-backed platforms standardize on single-manufacturer fleets.
- Ambulatory Surgical Centers:Limited-service facilities require compact systems for pre-operative planning and post-operative monitoring.
- Research Institutes:Academic and government laboratories drive ultra-high field adoption for spectroscopic and functional neuroimaging protocols.
Hospitals retain the deepest installed base; Diagnostic Imaging Centers are gaining share fastest as procurement concentrates at holding-company level.
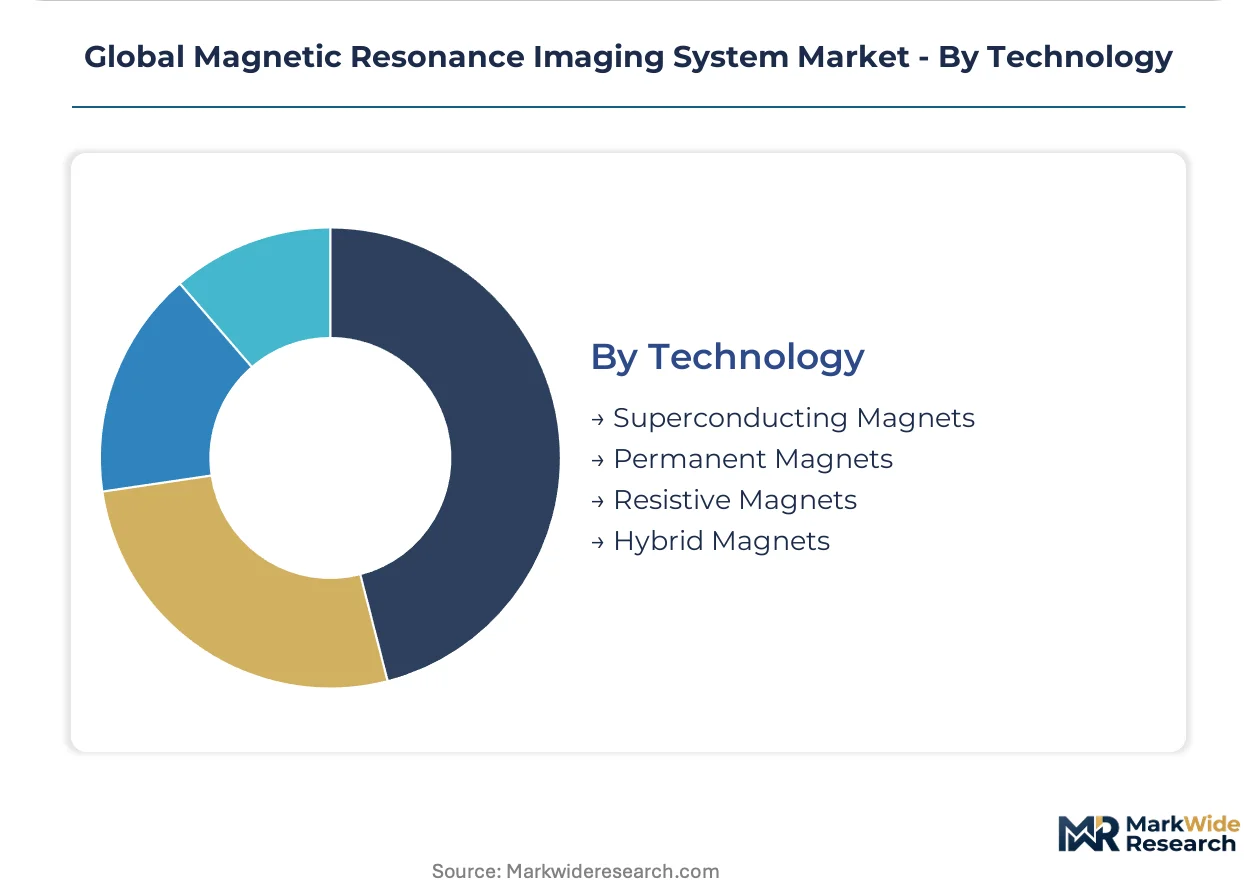
Technology:
Magnet construction determines cryogenic requirements, field stability, and long-term service revenue potential.
- Superconducting Magnets:Niobium-titanium wire coils operating at 4 Kelvin with liquid helium cooling deliver the highest field strengths and homogeneity. Helium supply chain disruptions from Qatar and Russia are compressing margin structures and accelerating cryogen-free development.
- Permanent Magnets:Rare-earth alloy configurations eliminate cryogenic dependency but constrain field strength to sub-0.5T ranges. Portable MRI manufacturers are exploiting this architecture to penetrate point-of-care settings previously inaccessible to superconducting designs.
- Resistive Magnets:Copper or aluminum conductor coils offer lower capital cost with higher operational power consumption and field instability.
- Hybrid Magnets:High-temperature superconductor and permanent magnet combinations promise intermediate field strengths without helium logistics.
Superconducting Magnets dominate current revenue; Hybrid Magnets are expanding most quickly as helium price volatility forces architectural innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The magnetic resonance imaging industry traces its commercial origins to Germany and the United States, where superconducting magnet technology first achieved clinical scale in the 1980s. These founding markets continue to anchor high-field system deployment while manufacturing and demand patterns diffuse across Asia-Pacific and emerging economies.
United States
Stroke triage protocols in emergency departments are expanding point-of-care neurology screening beyond traditional radiology suites. The FDA's 510(k) modernization initiative tightens predicate-device requirements, compressing clearance timelines for AI-integrated reconstruction software. Tertiary care hospitals in Boston and the San Francisco Bay Area deploy deep learning algorithms to double daily patient throughput.
Germany
Academic medical centers in Munich and Heidelberg scale MRI-guided radiotherapy programs, creating installed base demand for 3T systems with integrated planning software. The EU Medical Device Regulation hardens electromagnetic compatibility requirements, filtering procurement toward full-service manufacturers with captive quality management systems. Bavaria's medical technology cluster anchors superconducting wire production and direct service networks.
China
Domestic clinical trials for imported Class III imaging devices extend registration timelines under NMPA requirements, duplicating development expenditure for multinational manufacturers. Shanghai and Beijing concentrate demand for high-field systems in tertiary hospitals. The Yangtze River Delta hosts domestic manufacturers advancing cryogen-free magnet architectures to reduce helium dependency.
India
Private diagnostic imaging center chains in Maharashtra and Karnataka consolidate procurement decisions at holding-company level, displacing individual center autonomy. Equipment leasing and managed service contracts replace outright purchase for mid-field systems in tier-two cities. Public hospital procurement cycles lengthen, accelerating volume concentration toward private equity-backed platforms.
Japan
Research institutes in Tokyo and Osaka drive ultra-high field adoption for spectroscopic and functional neuroimaging protocols. METI standards govern electromagnetic compatibility certification for clinical deployment. The Kansai region maintains specialized cryogenic engineering expertise concentrated at academic programs and incumbent manufacturers.
Global Magnetic Resonance Imaging System Market Competitive Landscape
Premium-margin players sit above commodity-margin players across service contract lock-in and captive magnet technology dimensions. The vendor base concentrates around full-system manufacturers with backward integration into superconducting wire production and direct field service networks. Three archetypes dominate: integrated technology conglomerates with captive cryogen supply chains, modular architecture specialists enabling field upgrades without room reconstruction, and portable MRI innovators exploiting permanent magnet designs for point-of-care penetration. Competitive moves center on cryogen-free magnet development to disrupt incumbent service revenue models and AI-integrated reconstruction software to improve hospital workflow throughput.
Among integrated technology conglomerates, Siemens Healthineers anchors the premium tier through captive superconducting wire production and direct service networks across Western Europe. GE HealthCare occupies a position emphasizing AI-integrated reconstruction software that reduces scan times in high-throughput hospital workflows. Koninklijke Philips N.V. exemplifies modular system architecture specialization, enabling field upgrades from 1.5T to 3T without full room reconstruction. These three represent distinct competitive vectors—vertical supply chain control, software-driven workflow optimization, and hardware flexibility—rather than convergent strategic positioning.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE HealthCare |
| Koninklijke Philips N.V. |
| Canon Medical Systems Corporation |
| FUJIFILM Corporation |
| Esaote S.p.A |
| Shanghai United Imaging Healthcare |
| Bruker Corporation |
| Hitachi Healthcare |
| Others |
Supply & Pricing Matrix
Diagnostic imaging center chains in Maharashtra and Karnataka concentrate procurement authority at holding-company level, forcing equipment vendors toward long-term managed service contracts with embedded maintenance pricing rather than transactional unit sales.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates system procurement, separating 3T superconducting installations with AI reconstruction bundles from mid-field 1.5T configurations and portable low-field units. Price differentiation hinges on helium cryogen dependency and ISO 13485 certification tier. Cost compression in the standard tier intensifies as Chinese domestic manufacturers advance cryogen-free alternatives. Private diagnostic chains in India exhibit highest price sensitivity; German academic medical centers show lowest sensitivity due to radiotherapy integration requirements.
Supply Chain Analysis
China's NMPA domestic clinical trial mandates and India's phased manufacturing program are reshaping component sourcing decisions for multinational manufacturers. Superconducting niobium-titanium wire production concentrates in Germany, Japan, and the United States; rare-earth permanent magnet processing rests on Chinese separation facilities. Helium supply vulnerability from Qatar and Russia export disruptions creates single-source exposure for cryogenic cooling systems. Distribution runs through direct manufacturer service networks with captive spare parts inventories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on eliminating helium logistics costs through high-temperature superconductor development and capturing premium pricing for AI-integrated reconstruction software in high-throughput hospital workflows.
For Market Incumbents: Deploy captive superconducting wire production to lock in magnet manufacturing cost advantages against cryogen-free entrants. Accelerate FDA 510(k) submissions for AI reconstruction algorithms before predicate-device requirements tighten further. Consolidate service contract lock-in by embedding predictive maintenance software that monitors helium boil-off rates and magnet quench risk. For New Entrants and Emerging Players: Enter via portable MRI permanent magnet designs targeting emergency department stroke triage protocols in the United States, where point-of-care deployment bypasses incumbent radiology suite footprints. Pursue white-space penetration in India's tier-two cities through equipment leasing partnerships with private equity-backed diagnostic chains. Position go-to-market around zero-helium operational cost claims against superconducting incumbents. For Investors and Strategic Acquirers: Medical technology conglomerates with existing imaging portfolios are the most active acquirer in this space, seeking cryogen-free magnet IP and AI reconstruction software assets. Long-term viability favors manufacturers with backward integration into superconducting materials or software-defined imaging platforms. Watch helium price futures and NMPA registration timeline announcements as inflection indicators for technology substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Cryogen-Free Magnet Development | Eliminates helium supply chain dependency that constrains Siemens Healthineers and GE HealthCare service margins. |
| AI Reconstruction Software Launch | Reduces scan times in Boston and San Francisco Bay Area tertiary hospitals, improving asset utilization rates. |
| EU MDR Certification Pathway | Filters electromagnetic compatibility compliance toward full-service manufacturers with captive quality systems. |
| Hospital System Partnership | Locks in 3T system installed base for MRI-guided radiotherapy programs at German academic medical centers. |
| Managed Service Contract Expansion | Captures recurring revenue from Maharashtra and Karnataka diagnostic chains displacing outright purchase models. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital purchasing committees, biomedical engineers, GPO contracts managers, and MRI system service technicians with secondary validation against FDA 510(k) filings, EU MDR notified body databases, NMPA registration records, and hospital procurement databases. Bottom-up installed base modeling and top-down revenue triangulation cross-checked segment-level outputs.
Segment-weighting across the modeling period applied field strength tier, magnet technology type, clinical application specialization, and end-user procurement channel as core dimensions. CAGRs derived from logistic diffusion curves fitted to replacement cycle data and technology substitution parameters. Forecast inputs incorporated helium price volatility scenarios and NMPA domestic trial timeline assumptions.
Inputs from regulatory filing databases and hospital procurement systems were available through the study window; gaps in real-time service contract pricing transparency introduce uncertainty bands around aftermarket revenue projections. Forecasts reflect documented assumptions regarding cryogen-free magnet commercialization timelines and AI software adoption curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Neurophotonics Market
Medical Imaging
Canada Computed Tomography Market
Medical Imaging
Intraoperative Imaging Market
Medical Imaging
Image Guided Radiotherapy Market
Medical Imaging
Retinal Imaging Devices Market
Medical Imaging
US and Europe Digital Pathology Market
Medical Imaging
France Digital X-Ray Devices Market
Medical Imaging
Non-Invasive & Minimally Invasive Medical Imaging and Visualization Systems Market
Medical Imaging
Italy Digital Radiology Market
Medical Imaging
Japan Magnetic Resonance Imaging Market
Medical Imaging
Malaysia Digital Radiography Market
Medical Imaging
Global Surgical Imaging Arms Market
Medical Imaging
Saudi Arabia Diagnostic Imaging Market
Medical Imaging
Digital Radiology Market
Medical Imaging
North America Digital Pathology Market
Medical Imaging
Cone Beam Computed Tomography (CBCT) System Market