
 Global Veterinary Orthopedics Market | 2026-2036
Global Veterinary Orthopedics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Veterinary Orthopedics Market Foresight
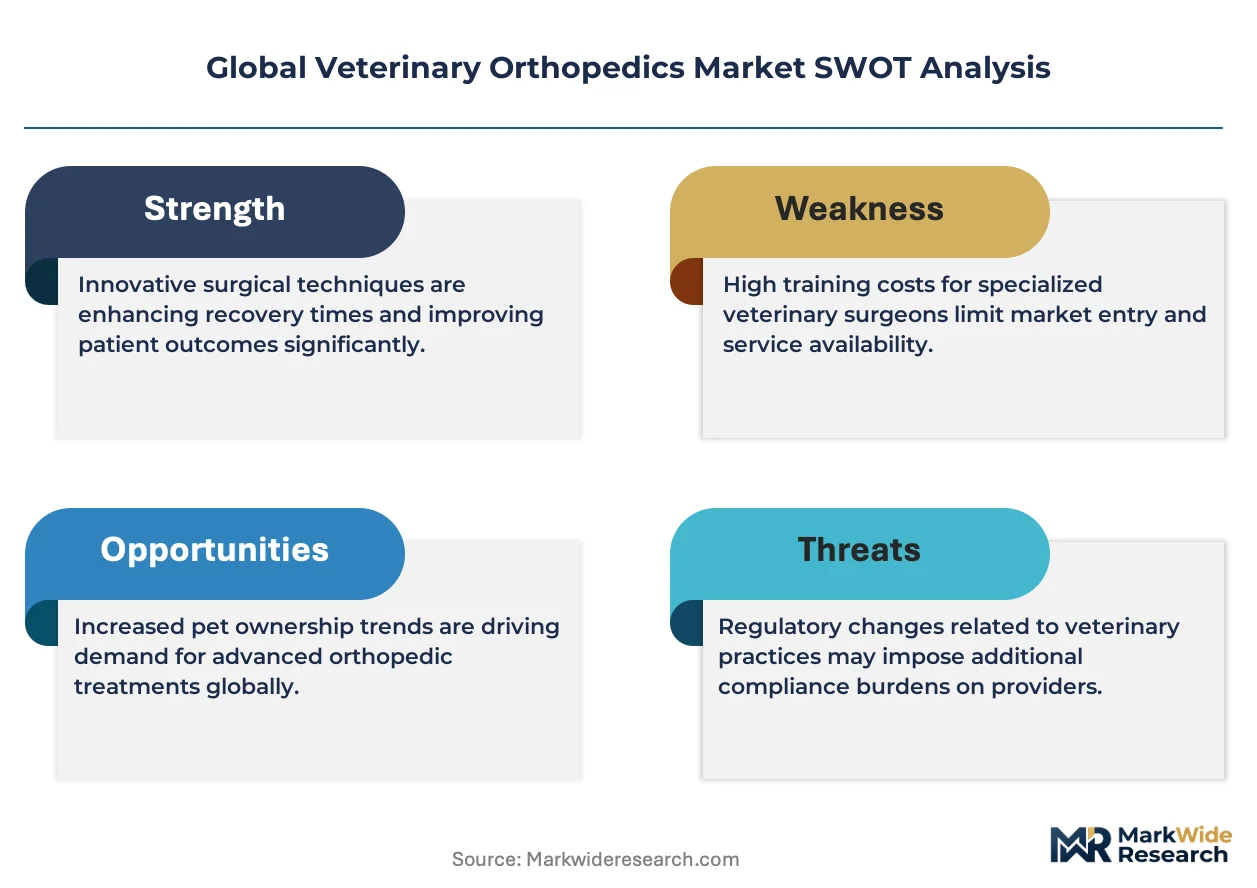
Titanium is hardening its position against stainless steel in plate and screw systems, reshaping cost structures across veterinary implant portfolios. B. Braun SE leverages its human-health manufacturing scale to transfer metallurgical standards into veterinary lines. Movora anchors its competitive position through Nordic design protocols that emphasize anatomical fit precision. DePuy Synthes extends its orthopaedic heritage into veterinary applications through specialized distributor networks.
Veterinary orthopedics encompasses surgical devices and implants engineered to treat musculoskeletal trauma, degenerative conditions, and congenital deformities in non-human animals, with titanium alloy compositions typically meeting ASTM F136 standards for biocompatibility and fatigue resistance. The field serves primarily companion animal trauma centers and equine sports medicine practices requiring load-bearing reconstruction capabilities. Plates and screws occupy the largest revenue pool given their ubiquity in fracture repair protocols, while external fixators represent the fastest-expanding category as minimally invasive techniques gain traction among referral surgeons. Joint stabilization applications command premium pricing due to the complexity of ligament reconstruction and postoperative rehabilitation requirements.
The FDA Center for Veterinary Medicine regulates implantable devices in the United States, while the EU Medical Device Regulation through notified bodies governs CE-marked veterinary products in Europe, and ISO 10993 biocompatibility standards shape material qualification protocols across manufacturing jurisdictions. These frameworks elevate R&D costs for new entrants but protect incumbent specialists with established quality management systems. Stakeholders must monitor how regulatory convergence between human and veterinary device pathways affects product development timelines and market access strategies.
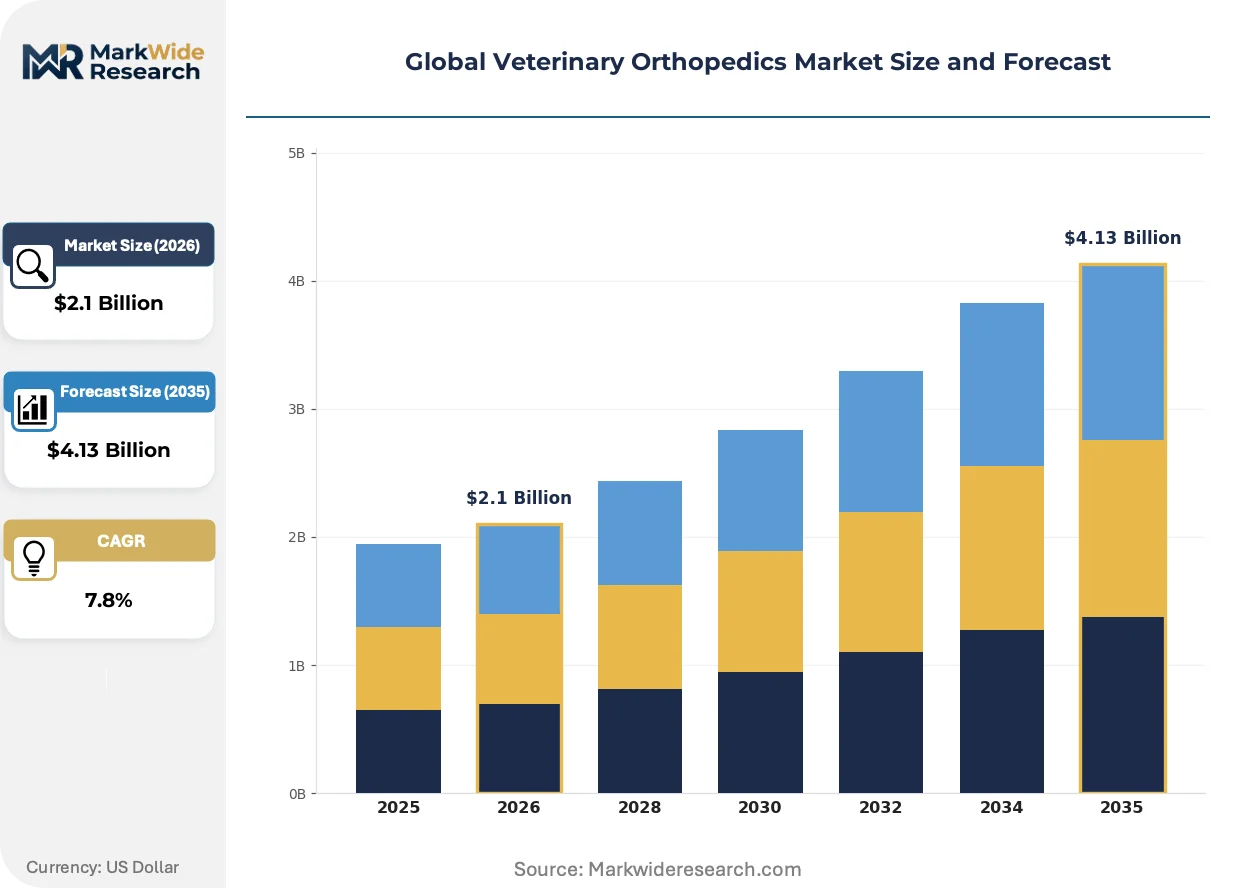
Market Dynamics
Titanium alloy adoption is compressing legacy stainless steel margins across plate and screw portfolios, while FDA Center for Veterinary Medicine compliance thresholds filter new entrants from established quality system holders.
Growth Catalysts
- Specialty Referral Hospital Expansion:Companion animal trauma centers in the United States are scaling surgical volumes as pet owners pursue advanced fracture repair and joint stabilization interventions.
- ISO 10993 Biocompatibility Standardization:Harmonized material qualification protocols reduce re-certification burdens for manufacturers operating across multiple jurisdictions.
- Minimally Invasive Technique Migration:External fixator demand is accelerating as veterinary surgeons adopt percutaneous fracture management protocols requiring reduced soft tissue disruption.
Market Restraints
- Titanium Feedstock Cost Volatility:ASTM F136-compliant titanium alloy pricing fluctuates with aerospace sector demand cycles, squeezing implant margin structures.
- European Notified Body Bottleneck:EU Medical Device Regulation certification queues extend product launch timelines for CE-marked veterinary devices.
- Orthopedic Surgeon Training Pipeline Constraints:ACVS residency program output limits supply of referral-level surgeons capable of complex ligament reconstruction procedures.
Strategic Opportunities
- Brazilian Equine Sports Medicine Penetration:Underdeveloped veterinary orthopedic infrastructure in South America's largest market offers first-mover positioning for trauma implant portfolios.
- 3D-Printed Patient-Specific Implant Convergence:Additive manufacturing and computed tomography segmentation are enabling anatomically matched plate geometries for brachycephalic breeds.
- Telemedicine-Enabled Postoperative Monitoring:Remote rehabilitation tracking creates subscription revenue attachment to hardware sales in United States companion animal practices.
Industry Challenges
- Veterinary-Specific Biomechanical Data Scarcity:Species-specific bone mineral density and loading pattern research lags human orthopedics, complicating implant fatigue validation.
- Legacy Practice Management System Integration:Surgical planning software deployment faces friction from entrenched radiology PACS architectures in established referral hospitals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Veterinary Orthopedics Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.13 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bone Plates, Screws, Pins, External Fixators, Orthopedic Implants, Cerclage Wires Animal Type: Canine, Feline, Equine, Bovine, Avian, Exotic Pets Application: Fracture Repair, Joint Stabilization, Arthrodesis, Ligament Repair, Osteotomy, Spinal Surgery End User: Veterinary Clinics, Research Institutions, Veterinary Hospitals, Specialty Orthopedic Centers |
| Companies Covered | B. Braun SE, Movora, Integra LifeSciences, DePuy Synthes, Arthrex, Inc., BioMedtrix, LLC, Veterinary Orthopedic Implants, KYON, Orthomed (UK) Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Veterinary Orthopedics Market Shifts & Advancements
Additive manufacturing is penetrating veterinary implant production, consolidating distributed machining capacity into centralized printing facilities while enabling geometric complexity impossible through conventional subtractive methods.
Locking plate technology is consolidating market preference across fracture repair protocols. These constructs eliminate screw-plate friction dependence, enabling stable fixation in osteoporotic bone common in geriatric companion animals. United States referral hospitals are standardizing locking screw inventory, compressing demand for conventional dynamic compression plates.
The EU Medical Device Regulation is tightening clinical evidence requirements for implantable veterinary devices. Manufacturers must now demonstrate species-specific safety profiles beyond historical predicate reliance. European notified bodies are prioritizing large animal orthopedic submissions, delaying small companion animal product clearances.
Pet insurance penetration is altering payment dynamics at United States specialty hospitals. Policyholders facing predictable out-of-pocket maximums are selecting premium implant tiers previously rejected by cash-paying clients. This behavioral shift is visible in coastal metropolitan markets where employer-sponsored veterinary benefits have achieved critical mass.
Global Veterinary Orthopedics Market Segmentation
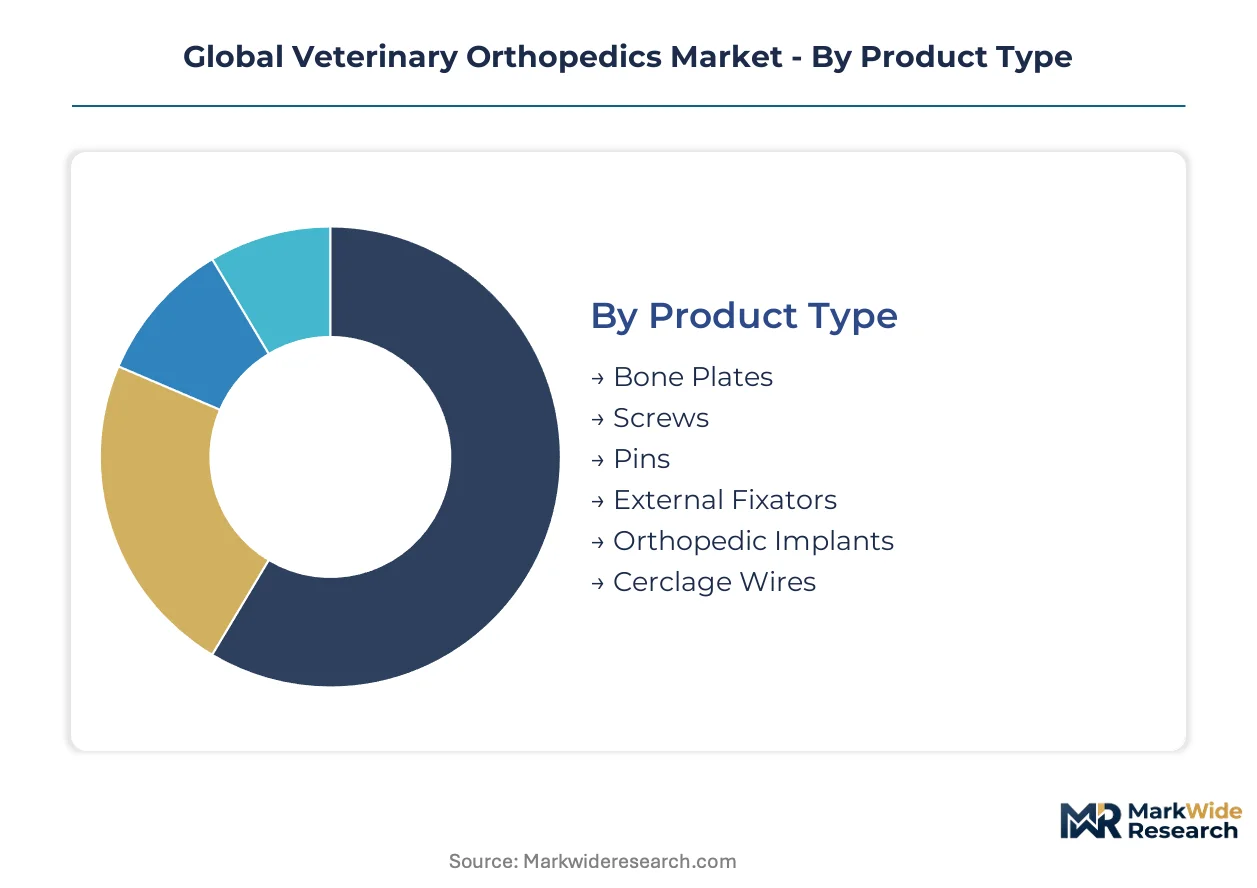
Veterinary orthopedic procurement patterns diverge sharply across product categories and animal types, with titanium alloy specifications and species-specific anatomical requirements driving portfolio design decisions. Manufacturers must align implant geometries with distinct biomechanical loading patterns across companion and production animals.
Product Type:
Upgrade cycles from stainless steel to titanium alloys are compressing replacement timelines across veterinary implant portfolios as referral hospitals standardize on ASTM F136-compliant metallurgy.
- Plates:Locking plate constructs eliminate friction-dependent fixation, enabling stable anchorage in osteoporotic bone common in geriatric companion animals. United States specialty hospitals are consolidating inventory around titanium locking systems, displacing conventional dynamic compression plates from procurement lists.
- Screws:Self-tapping and locking screw variants dominate orthopedic fixation protocols, with thread pitch and core diameter optimized for species-specific cortical thickness. Demand concentrates in referral-level trauma centers performing complex fracture repairs on large-breed canines.
- Pins:Intramedullary fixation devices serve provisional stabilization roles in cost-sensitive practice settings.
- External Fixators:Minimally invasive fracture management applications are accelerating percutaneous fixation adoption.
- Orthopedic Implants:Joint replacement and intervertebral disc prostheses command premium positioning in specialty centers.
- Cerclage Wires:Tension band applications persist in equine long-bone fracture protocols.
Plates sit at the top of the volume ranking, with external fixators climbing the fastest as minimally invasive techniques displace open reduction methods.
Animal Type:
Procedure economics vary dramatically across species, with equine sports medicine and companion animal trauma reconstruction anchoring divergent pricing structures and implant performance specifications.
- Canine:Large-breed trauma cases generate the highest implant consumption per procedure, with cranial cruciate ligament repair and femoral head ostectomy driving joint stabilization volumes. United States pet insurance penetration is shifting owner willingness toward premium titanium locking systems previously rejected by cash-paying clients.
- Equine:Load-bearing long-bone reconstruction demands fatigue-resistant implant geometries capable of withstanding 500-kg athletic loading cycles. Brazilian sports medicine practices represent underpenetrated territory for trauma implant portfolios given limited domestic manufacturing capacity.
- Feline:Miniaturized plate and screw systems address high metabolic bone turnover and smaller skeletal dimensions.
- Bovine:Production animal applications concentrate in university veterinary hospitals and large dairy operation contracts.
- Avian:Exotic veterinary specialists require ultra-fine fixation hardware for hollow-bone anatomy.
- Exotic Pets:Reptile and small mammal orthopedic interventions occupy niche specialist practices with limited standardization.
Canine applications generate the highest absolute implant volumes, while equine procedures sustain the steepest expansion trajectory in emerging markets.
Application:
Complexity gradients across surgical categories determine reimbursement capture and implant tier selection, with joint reconstruction commanding multiples of fracture repair economics.
- Fracture Repair:Plate-osteosynthesis and external fixation protocols constitute the foundational revenue pool, with locking construct standardization reducing revision surgery incidence. United States referral hospitals are consolidating supplier relationships around comprehensive trauma system portfolios.
- Joint Stabilization:Cranial cruciate ligament reconstruction and hip dysplasia management require advanced implant geometries and extended rehabilitation protocols. Coastal metropolitan markets with employer-sponsored veterinary benefits are driving premium tier selection among insured pet owners.
- Arthrodesis:Joint fusion applications address end-stage degenerative conditions in working and sporting animals.
- Ligament Repair:Synthetic graft and anchor systems serve specialized tendon reconstruction cases.
- Osteotomy:Corrective bone resection procedures demand precise angular correction planning.
- Spinal Surgery:Vertebral stabilization and disc disease interventions occupy the highest complexity tier with limited surgeon supply.
Fracture repair anchors volume leadership, with joint stabilization gaining share fastest as pet owners pursue mobility-preserving interventions.
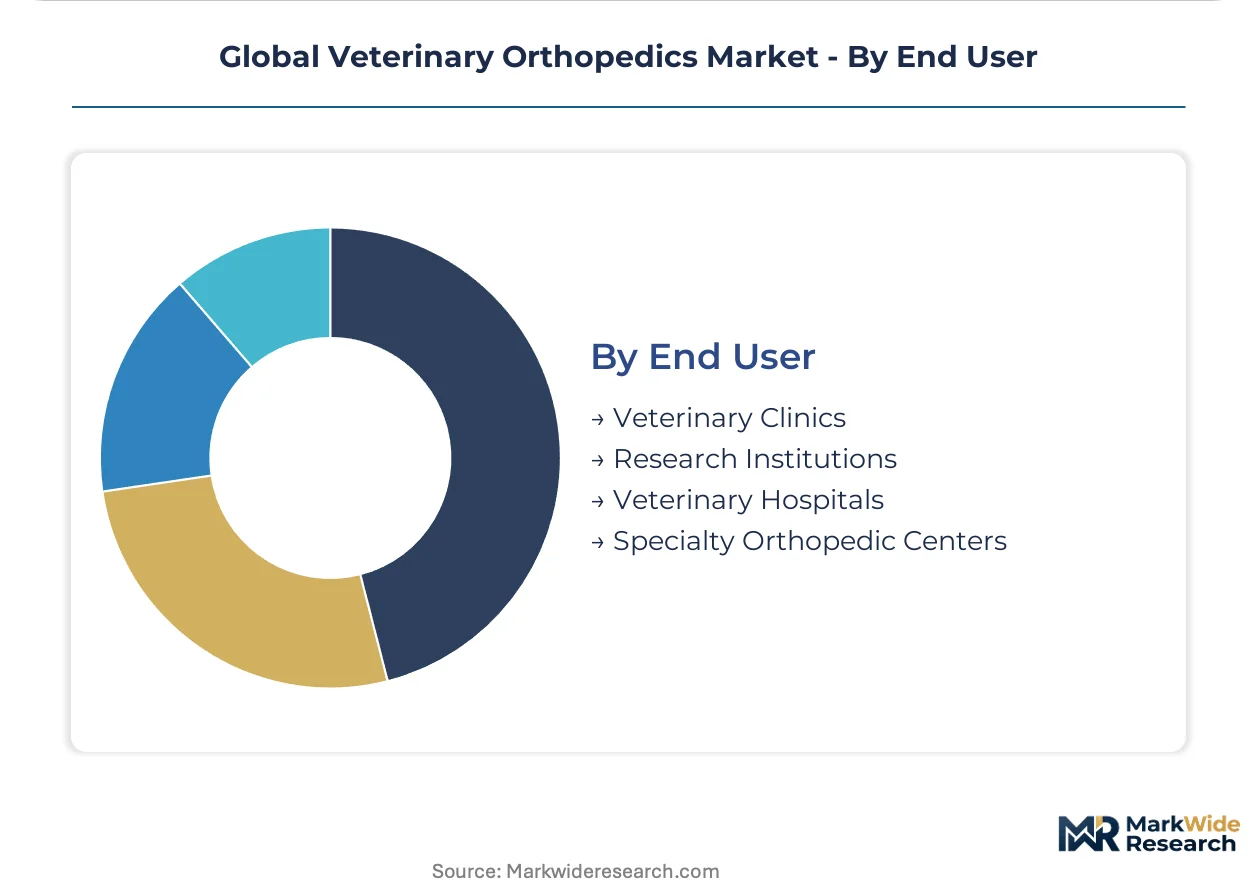
End User:
Procurement authority and technical sophistication vary sharply across practice types, with specialty centers driving specification upgrades that diffuse slowly into general practice settings.
- Veterinary Hospitals:Multi-specialty referral institutions consolidate high-complexity trauma and joint reconstruction volumes, establishing vendor standards that shape regional procurement patterns. These facilities maintain dedicated orthopedic surgical suites with fluoroscopy and arthroscopy capabilities.
- Specialty Orthopedic Centers:Focused musculoskeletal practices concentrate surgical expertise and implant inventory breadth unavailable in general settings. United States metropolitan clusters host the densest concentration of these facilities.
- Veterinary Clinics:Primary care settings handle screening and postoperative rehabilitation, with limited in-house surgical capacity.
- Research Institutions:University veterinary schools drive biomechanical validation studies and residency training pipelines.
Veterinary hospitals command the highest implant throughput, with specialty orthopedic centers expanding their procedural share fastest as owners seek advanced surgical options.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States veterinary orthopedic infrastructure anchors the sector's procedural volume and premium economics. Specialty referral hospitals in metropolitan corridors concentrate surgical expertise and implant procurement authority. Regulatory frameworks across multiple jurisdictions shape market access conditions for device manufacturers.
United States
Pet insurance penetration is shifting owner willingness toward premium titanium locking systems in coastal metropolitan markets. FDA Center for Veterinary Medicine oversight of implantable devices elevates compliance thresholds for market entry. Greater Boston and Pacific Northwest clusters host dense concentrations of ACVS residency programs and multi-specialty referral institutions.
Germany
Equine sports medicine practices drive demand for fatigue-resistant trauma implants capable of withstanding high-load athletic cycles. EU Medical Device Regulation through notified bodies governs CE-marked veterinary product certification. Bavaria and Baden-Württemberg industrial regions concentrate precision manufacturing capabilities serving both human and veterinary orthopedic lines.
United Kingdom
Specialty orthopedic centers in London and Southeast England are consolidating complex joint stabilization procedures previously distributed across general practices. The Veterinary Medicines Directorate aligns with broader EU regulatory convergence post-Brexit transition. Midlands veterinary schools anchor biomechanical research pipelines and surgeon training output.
Brazil
Underdeveloped veterinary orthopedic infrastructure in South America's largest market offers expansion territory for trauma implant portfolios. ANVISA regulates medical device registration with increasing harmonization toward international standards. São Paulo and Rio de Janeiro metropolitan areas concentrate emerging specialty hospital development and equine sports medicine investment.
Australia
Companion animal trauma centers in Sydney and Melbourne are scaling surgical volumes as pet owner expenditure on advanced interventions rises. TGA oversight of veterinary medical devices maintains alignment with international quality management expectations. New South Wales and Victoria host the densest concentrations of university veterinary hospitals driving residency training and clinical validation studies.
Global Veterinary Orthopedics Market Competitive Landscape
Global majors compete with regional champions across metallurgical standards and anatomical design protocols. The market exhibits tiered consolidation with human-health orthopaedic heritage transferring into veterinary lines through specialized distribution structures. Three archetypes dominate: diversified medical technology conglomerates leveraging manufacturing scale, Nordic design specialists emphasizing anatomical precision, and focused veterinary implant houses with species-specific portfolios. Competitive dynamics center on titanium alloy certification and locking plate technology licensing.
Among diversified medical technology conglomerates, B. Braun SE and DePuy Synthes occupy positions reflecting human-health manufacturing scale transferred into veterinary lines. Movora exemplifies the Nordic design specialist archetype with protocols emphasizing anatomical fit precision. Integra LifeSciences sits within the regenerative medicine tier, representing convergence between soft tissue and orthopedic reconstruction capabilities.
| Leading Market Players |
|---|
| B. Braun SE |
| Movora |
| Integra LifeSciences |
| DePuy Synthes |
| Arthrex, Inc. |
| BioMedtrix, LLC |
| Veterinary Orthopedic Implants |
| KYON |
| Orthomed (UK) Ltd. |
| Others |
Supply & Pricing Matrix
ASTM F136 certification divergence between titanium alloy and legacy stainless steel implant tiers manifests in procurement bifurcation across United States referral hospitals and cost-sensitive general practices. Tier separation concentrates supply chain leverage with FDA-registered manufacturers holding validated quality systems, while price-sensitive clinics source non-certified alternatives through distributor gray channels.
Pricing Analysis
Input-cost pass-through from aerospace-linked titanium alloy feedstock volatility compresses margin structures for plate and screw portfolios. Three-tier pricing structure across premium, standard, and economy levels reflects ASTM F136 certification status, locking screw technology licensing, and after-sales technical support bundling. Pricing pressure stems from Brazilian and Australian markets where domestic manufacturing scarcity forces import dependency. General veterinary clinics exhibit highest price sensitivity, while United States specialty orthopedic centers prioritize fatigue-resistance specifications over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with German precision machining clusters and United States titanium alloy forging facilities serving veterinary implant production. Raw material dependencies encompass ASTM F136-compliant titanium billet, surgical-grade stainless steel rod, and cobalt-chrome casting feedstock. Supply chain risk centers on European notified body certification queues extending CE-marking timelines for new product introductions. Distribution runs through specialized veterinary distributor networks maintaining surgeon relationships and inventory consignment programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories in veterinary orthopedics rest on titanium alloy cost-down curves and insured pet owner willingness to select premium locking constructs. Manufacturers capturing certification economies and surgeon training allegiances will outpace commodity competitors.
For Market Incumbents: To counter Brazilian and Australian new entrant challenges, deepen ASTM F136 metallurgical certification moats and establish captive surgeon training partnerships with ACVS residency programs. Locking plate technology licensing and exclusive distributor consignment arrangements defend procurement relationships at United States referral hospitals. For New Entrants and Emerging Players: Capture white-space in Brazilian equine sports medicine and Australian companion animal trauma centers where incumbent distribution coverage remains thin. Minimally invasive external fixator portfolios targeting percutaneous fracture protocols offer the most penetrable entry vector. Go-to-market execution should anchor on direct surgeon education bypassing established distributor markups. For Investors and Strategic Acquirers: Consolidation pressure builds where FDA quality system validation and European notified body relationships create insurmountable entry barriers for capital-constrained specialists. Five-to-ten year viability favors targets with species-specific anatomical design libraries and established GPO contracts at United States multi-specialty veterinary hospitals. The signal to watch is pet insurance penetration thresholds crossing employer-sponsored benefit critical mass in coastal metropolitan markets.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Quality System Registration | Unlocks United States referral hospital procurement and validates ASTM F136 metallurgical protocols. |
| Locking Plate Technology Licensing | Enables stable fixation in osteoporotic bone and displaces conventional dynamic compression inventory. |
| ACVS Residency Training Partnership | Captures surgeon preference formation and embeds proprietary instrumentation early in career trajectories. |
| Brazilian Distribution Joint Venture | Addresses ANVISA registration complexity and local logistics for equine sports medicine penetration. |
| Telemedicine Rehabilitation Platform | Creates subscription revenue attachment to hardware sales through postoperative monitoring services. |
Research Methodology
Direct dialogue with veterinary orthopedic surgeons, ACVS residency program directors, GPO contracts managers, and implant distributor principals anchored qualitative grounding. Secondary validation drew from FDA 510(k) filings, EU Medical Device Regulation notified body guidance documents, ISO 10993 biocompatibility standards, and hospital procurement database extracts. Bottom-up implant volume modeling and top-down veterinary expenditure triangulation cross-verified segment-level outputs.
Segmentation outputs reflect product type, animal species, application complexity, and end-user facility tier across the analysis window. CAGRs were derived from procedure volume elasticity to pet insurance penetration and referral hospital capital expenditure cycles. Species-specific bone mineral density research gaps and titanium alloy feedstock pricing volatility informed sensitivity bands.
Regulatory convergence between human and veterinary device pathways, notified body certification queue extensions, and ACVS surgeon training pipeline constraints are the dominant revision risks. Forecasts reflect documented assumptions on specialty hospital expansion rates and insured owner willingness-to-pay thresholds. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Europe Kyphoplasty Market
Orthopedic Devices
South Africa Spinal Surgery Devices Market
Orthopedic Devices
Keyhole Orthopaedic Surgery Market
Orthopedic Devices
Orthopedic Wire Pin Driver Market
Orthopedic Devices
Patient Lifts Market
Orthopedic Devices
Orthopedic Extremity Market
Orthopedic Devices
Hip Reconstruction Devices Market
Orthopedic Devices
Hip Orthosis Market
Orthopedic Devices
Distal Compression Plates Market
Orthopedic Devices
Prosthetics and Orthotics Market
Orthopedic Devices
Spine Devices Market
Orthopedic Devices
Global Elbow Replacement Market
Orthopedic Devices
US Tendon Repair Market
Orthopedic Devices
Polyethylene Orthopaedic Insert Market
Orthopedic Devices
Europe Orthopedic Navigation Systems Market
Orthopedic Devices
India Orthopedic Braces and Supports Market