
 Germany Magnetic Resonance Imaging Market | 2026-2036
Germany Magnetic Resonance Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Magnetic Resonance Imaging Market Foresight
CE marking under the EU Medical Device Regulation is collapsing the supplier base for non-compliant MRI manufacturers seeking access to German procurement channels. Siemens Healthcare GmbH anchors its position through captive magnet manufacturing and direct hospital integration across Bavaria and Baden-Württemberg. GE Healthcare competes on hybrid MRI architectures that blend superconducting and cryogen-free technologies for mid-tier diagnostic centers.
Magnetic Resonance Imaging deploys superconducting coils cooled by liquid helium to generate magnetic fields between 1.5 and 7 Tesla, producing high-resolution tomographic images of soft tissue without ionizing radiation; its primary purpose is non-invasive diagnostic visualization for neurological, oncological, and musculoskeletal pathologies. Closed Bore MRI dominates hospital installations where maximum field strength drives clinical throughput, while Portable MRI segments expand fastest into ambulatory surgery centers seeking point-of-care deployment without fixed infrastructure. Superconducting technology leads value capture due to helium dependency and maintenance contracts, though Cryogen-Free MRI gains share where supply chain resilience matters.
BfArM oversight combined with EU MDR conformity requirements and DIN EN 60601-1 electrical safety standards shapes product certification timelines and reimbursement eligibility for installed systems. KBA-equivalent transport regulations for mobile MRI units add compliance layers for portable segment vendors. Stakeholders must weigh helium sourcing strategies against emerging cryogen-free platforms as supply security and sustainability criteria reshape procurement specifications.
Market Dynamics
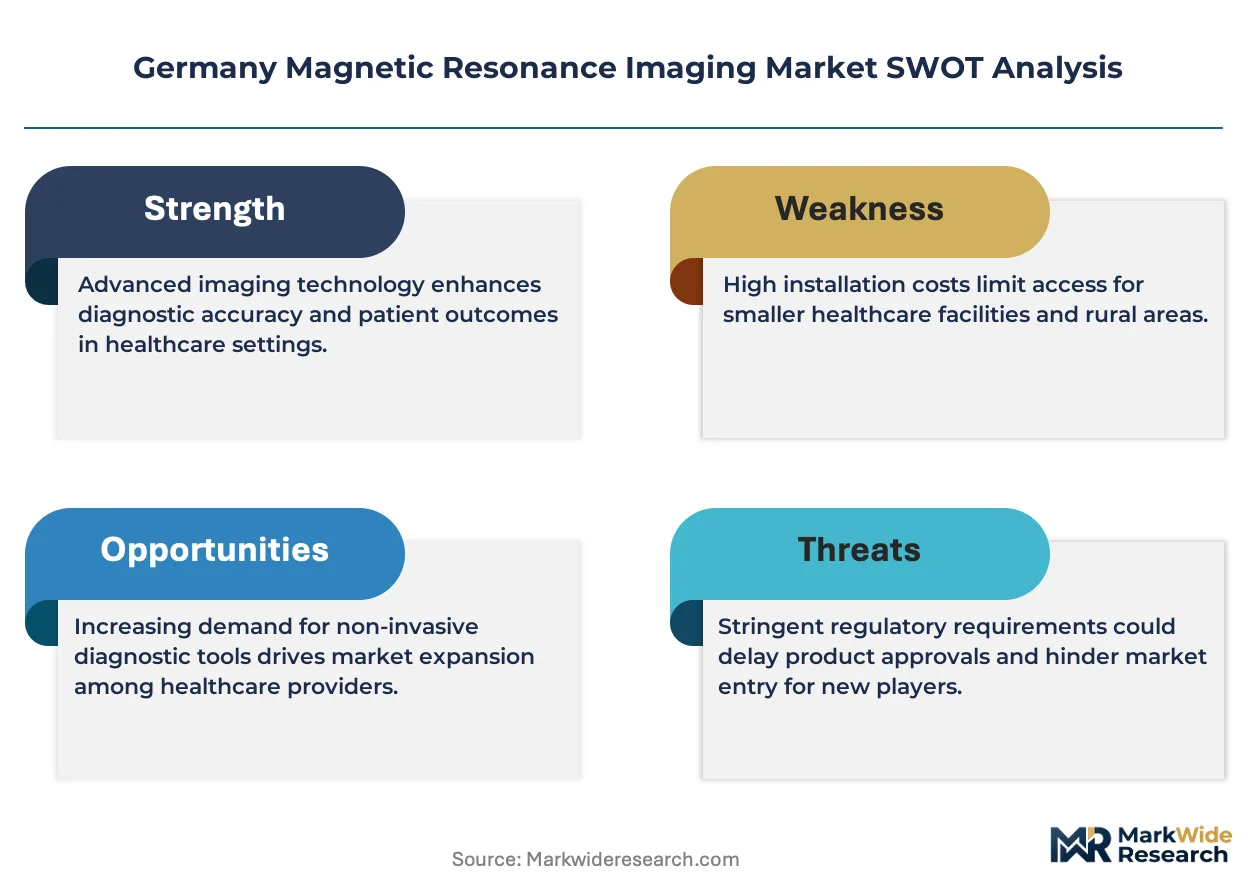
Helium supply chain volatility is compressing procurement timelines across German hospital networks, forcing accelerated evaluation of cryogen-free alternatives and captive sourcing strategies for superconducting magnet maintenance.
Growth Catalysts
- EU MDR conformity deadlines:Replacement cycles for legacy MRI systems are accelerating as BfArM enforcement tightens reimbursement eligibility for non-compliant installations.
- Bavaria university hospital clusters:Concentrated research funding and patient referral networks sustain demand for high-field 7 Tesla platforms in neurological diagnostics.
- Hybrid MRI architectures:Superconducting and cryogen-free technology convergence enables mid-tier diagnostic centers to access advanced imaging without fixed infrastructure investments.
Market Restraints
- Liquid helium cost volatility:Global supply concentration in Qatar and Algeria exposes German operators to price shocks and rationing during geopolitical disruptions.
- BfArM certification timelines:Extended technical documentation reviews under EU MDR Article 10 delay new system launches by 12-18 months versus pre-2017 Medical Device Directive pathways.
- Closed bore technical limitations:Patient claustrophobia and body habitus constraints restrict throughput in bariatric and pediatric populations, limiting addressable volume in community hospitals.
Strategic Opportunities
- Ambulatory surgery centers:Portable MRI segments penetrate point-of-care settings in North Rhine-Westphalia where fixed infrastructure investments face capital allocation constraints.
- CSRD sustainability reporting:Mandatory environmental disclosure requirements create procurement preference for helium-recycling systems and lower-carbon magnet technologies.
- AI-assisted reconstruction convergence:Deep learning algorithms reduce scan acquisition times, enabling throughput expansion without proportional hardware scaling in saturated urban markets.
Industry Challenges
- Clinical engineering talent scarcity:Specialized cryogen handling and superconducting coil maintenance skills concentrate in Siemens Healthineers' captive service networks, constraining third-party servicing options.
- Legacy PACS integration complexity:DICOM interoperability gaps between new MRI platforms and existing hospital information systems extend deployment timelines and inflate IT consultancy costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Magnetic Resonance Imaging Market |
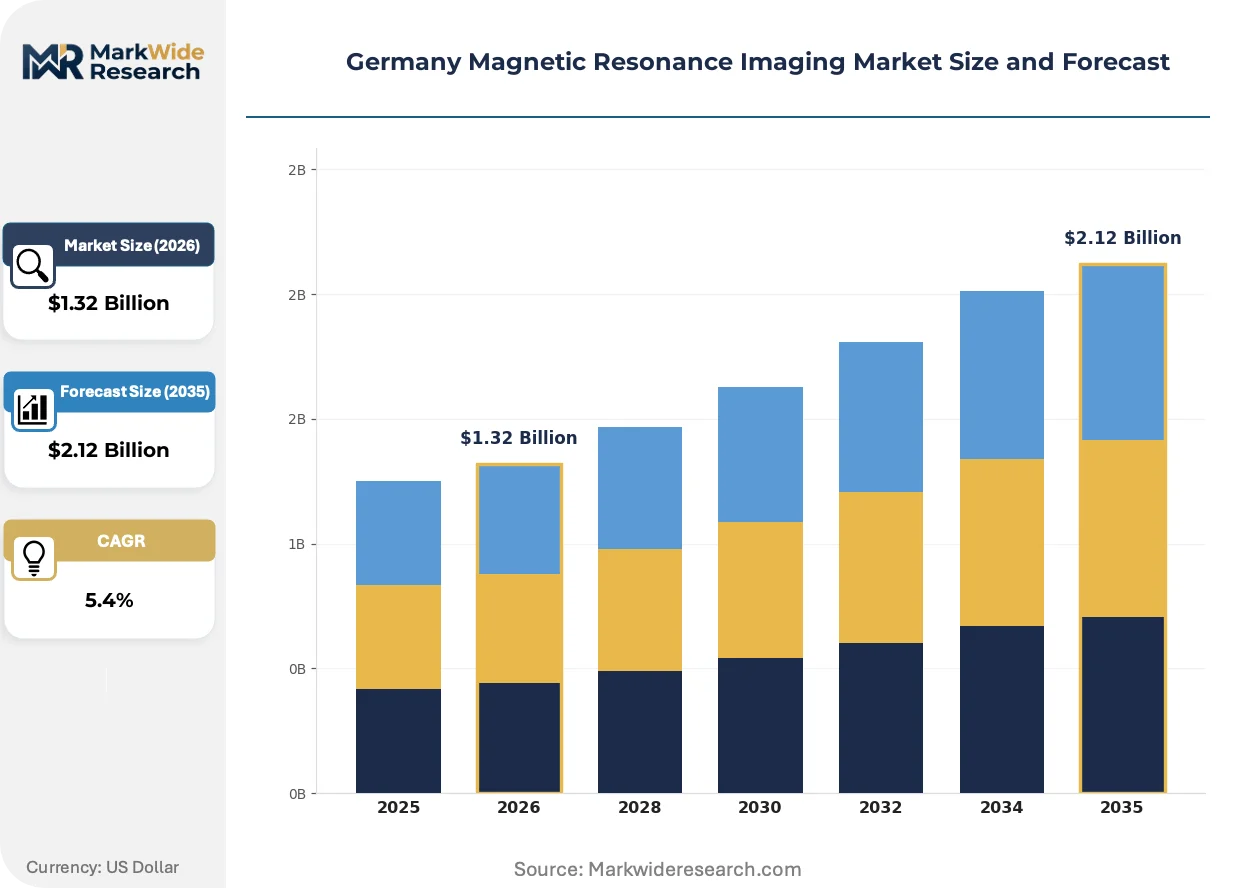
| Market Size in 2026 | $1.32 Billion |
| Market Size in 2035 | $2.12 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Closed Bore MRI, Open Bore MRI, Upright MRI, Portable MRI, High-Field MRI Technology: Superconducting, Permanent Magnet, Resistive Magnet, Hybrid MRI, Cryogen-Free MRI Application: Neurology, Cardiology, Musculoskeletal, Oncology, Obstetrics, Urology End User: Hospitals, Diagnostic Centers, Ambulatory Surgery Centers, Research Institutes |
| Companies Covered | Canon Medical Systems Corporation, Esaote SpA, Siemens Healthcare GmbH, Neoscan Solutions, Fonar Corporation, GE Healthcare, Fujifilm Holdings Corporation, SternMed GmbH, Koninklijke Philips NV, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Magnetic Resonance Imaging Market Shifts & Advancements
Artificial intelligence reconstruction algorithms and helium-independent magnet designs are restructuring competitive positioning across German procurement channels, compressing the traditional superconducting equipment lifecycle.
Cryogen-free permanent magnet technology is displacing conventional liquid helium-cooled systems in outpatient diagnostic chains. Regional radiology networks in Baden-Württemberg are piloting these platforms for musculoskeletal imaging, attracted by eliminated helium logistics and reduced site preparation costs. The structural consequence is a bifurcation in vendor pricing power between premium high-field segments and commoditized extremity imaging.
EU MDR Article 10 technical documentation requirements are extending certification timelines for novel MRI sequences and software upgrades. BfArM notified body capacity constraints are creating queuing bottlenecks, particularly for artificial intelligence-enabled diagnostic modules. Siemens Healthineers and GE Healthcare are responding by pre-submission engagement strategies and modular approval pathways that decouple hardware from algorithmic enhancements.
Outcome-based equipment leasing is penetrating municipal hospital procurement in Saxony and Thuringia where capital budgets face regional government austerity constraints. Per-scan pricing models displace traditional capital purchase structures, transferring utilization risk to manufacturers and compressing margin structures for mid-tier equipment tiers. This shift is most visible in East German states where hospital privatization has concentrated purchasing authority in regional procurement consortia.
Germany Magnetic Resonance Imaging Market Segmentation
German MRI procurement patterns diverge sharply between centralized hospital networks and decentralized outpatient chains, with each channel demanding distinct technical specifications and compliance profiles. Understanding these segment boundaries clarifies where BfArM enforcement and helium supply constraints reshape vendor priorities.
Product Type:
Domestic demand concentrates in Bavaria and North Rhine-Westphalia for fixed installations, while portable systems gain traction in ambulatory networks across Baden-Württemberg.
- Closed Bore MRI:Superconducting coils cooled by liquid helium generate fields between 1.5 and 7 Tesla for maximum soft-tissue resolution. University hospital clusters in Munich and Cologne prioritize these systems for neurological throughput despite patient claustrophobia constraints.
- Portable MRI:Cryogen-free permanent magnet designs enable point-of-care deployment without fixed infrastructure. Ambulatory surgery centers in North Rhine-Westphalia adopt these platforms to bypass capital allocation bottlenecks in municipal procurement.
- Open Bore MRI:Vertical field architectures accommodate bariatric and pediatric populations excluded from closed-bore protocols.
- Upright MRI:Weight-bearing imaging configurations target musculoskeletal specialists in sports medicine networks.
- High-Field MRI:7 Tesla platforms serve research consortia requiring sub-millimeter resolution for functional neuroimaging protocols.
Closed Bore MRI holds the largest share; momentum sits with Portable MRI as point-of-care networks expand.
Technology:
Cost stratification separates premium superconducting platforms from emerging helium-independent alternatives reshaping mid-tier procurement.
- Superconducting:Niobium-titanium coils operating at 4 Kelvin deliver the highest field strengths and signal-to-noise ratios. Bavarian university hospitals maintain captive helium sourcing contracts to sustain these installations despite supply volatility.
- Cryogen-Free MRI:Permanent magnet arrays eliminate liquid helium dependency entirely. Regional radiology networks in Baden-Württemberg pilot these systems for extremity imaging, attracted by reduced site preparation and eliminated cryogen logistics.
- Permanent Magnet:Lower-field configurations serve cost-constrained diagnostic chains with simplified maintenance profiles.
- Resistive Magnet:Copper coil designs occupy niche applications where field stability requirements are modest.
- Hybrid MRI:Convergent architectures blend superconducting performance with cryogen-free operational flexibility for mid-tier centers.
Superconducting technology dominates revenue capture; Cryogen-Free MRI is climbing the fastest as supply security criteria enter procurement specifications.
Application:
Volume concentration in neurological and oncological diagnostics reflects Germany's aging demographic and specialized referral network structure.
- Neurology:High-field protocols for multiple sclerosis, epilepsy, and stroke imaging command premium reimbursement rates. Concentrated demand at Charité Berlin and Heidelberg University Hospital drives 7 Tesla adoption.
- Oncology:Multiparametric sequences enable tumor characterization and treatment response monitoring. Comprehensive cancer centers in Essen and Dresden prioritize MRI for radiation therapy planning integration.
- Musculoskeletal:Sports medicine networks and orthopedic chains drive outpatient demand for extremity-dedicated platforms.
- Cardiology:Stress perfusion and late gadolinium enhancement protocols compete with CT angiography for coronary assessment.
- Obstetrics:Fetal anatomical surveys and placental imaging applications face reimbursement constraints limiting penetration.
- Urology:Multiparametric prostate MRI gains adoption for active surveillance protocols in regional urology networks.
Neurology holds the largest share; momentum sits with Oncology as precision therapy planning tightens imaging integration requirements.
End User:
Customer type determines capital structure preferences, with municipal hospitals favoring ownership and private chains exploring operational lease models.
- Hospitals:Maximum case complexity and referral authority sustain demand for 3 Tesla and 7 Tesla platforms. Bavarian and North Rhine-Westphalian university hospitals anchor procurement volume through centralized capital budgets.
- Diagnostic Centers:High throughput requirements favor 1.5 Tesla workhorse systems with rapid sequence protocols. Private radiology chains in Hesse and Lower Saxony compete on appointment availability and report turnaround.
- Ambulatory Surgery Centers:Point-of-care deployment needs drive portable MRI evaluation where fixed infrastructure investments face regulatory delays.
- Research Institutes:Methodology development and clinical trial imaging demand specialized sequences and extended magnet time allocation.
Hospitals hold the largest share; momentum sits with Ambulatory Surgery Centers as decentralized care models gain policy support.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German federal hospital investment programs and BfArM reimbursement alignment are redistributing MRI procurement toward university hospital clusters and decentralized ambulatory networks.
Bavaria
University hospital clusters in Munich and Erlangen drive demand for 7 Tesla research-grade platforms. BfArM technical documentation requirements under EU MDR Article 10 compress procurement timelines for high-field installations. Siemens Healthineers anchors captive magnet manufacturing in Forchheim, supplying superconducting coils directly to regional procurement consortia.
North Rhine-Westphalia
Comprehensive cancer centers in Essen and Cologne prioritize multiparametric MRI for radiation therapy planning integration. DIN EN 60601-1 electrical safety standards shape site preparation specifications for new installations. Private radiology chains in Düsseldorf compete on throughput metrics, favoring 1.5 Tesla workhorse systems with rapid sequence protocols.
Baden-Württemberg
Regional radiology networks pilot cryogen-free permanent magnet systems for extremity imaging applications. KBA-equivalent transport regulations for mobile MRI units add compliance layers for portable segment vendors. Stuttgart-based hospital groups evaluate hybrid architectures blending superconducting performance with cryogen-free operational flexibility.
Lower Saxony
Municipal hospital procurement in Hanover and Braunschweig faces capital budget constraints under regional government austerity measures. Outcome-based equipment leasing models displace traditional capital purchase structures, transferring utilization risk to manufacturers. Diagnostic centers in Wolfsburg compete on appointment availability, driving demand for AI-assisted reconstruction to compress scan times.
Berlin-Brandenburg
Charité Berlin anchors neurological imaging volume through specialized multiple sclerosis and epilepsy protocols. CSRD sustainability reporting requirements create procurement preference for helium-recycling systems and lower-carbon magnet technologies. Research institutes in Potsdam demand extended magnet time allocation for methodology development and clinical trial imaging.
Germany Magnetic Resonance Imaging Market Competitive Landscape
Player mix skews toward diversified medical technology conglomerates with captive magnet manufacturing capabilities. Siemens Healthcare GmbH anchors Bavarian supply chains through in-house production of superconducting coils. Three strategic archetypes dominate: integrated conglomerates with full magnet production, hybrid-technology specialists bridging superconducting and cryogen-free platforms, and portable-system innovators targeting ambulatory deployment. Competitive moves concentrate on modular approval pathways that decouple hardware from algorithmic enhancements, plus helium sourcing strategies that secure supply chain resilience against geopolitical disruption.
Among Germany-based integrated manufacturers, Siemens Healthcare GmbH occupies the archetype of captive vertical control, while SternMed GmbH represents mid-tier equipment specialists. GE Healthcare and Koninklijke Philips NV exemplify diversified conglomerates competing on hybrid architectures. Canon Medical Systems Corporation, Fujifilm Holdings Corporation, and Esaote SpA sit within the imaging-systems tier, each representing geographic origin archetypes—Japanese precision engineering, diversified Japanese holding structures, and Italian specialized diagnostics respectively. Fonar Corporation and Neoscan Solutions anchor the portable-innovation vector, with Fonar representing legacy open-bore specialization and Neoscan exemplifying compact-platform engineering.
| Leading Market Players |
|---|
| Canon Medical Systems Corporation |
| Esaote SpA |
| Siemens Healthcare GmbH |
| Neoscan Solutions |
| Fonar Corporation |
| GE Healthcare |
| Fujifilm Holdings Corporation |
| SternMed GmbH |
| Koninklijke Philips NV |
| Others |
Supply & Pricing Matrix
EU MDR Article 10 technical documentation requirements gate both supplier qualification timelines and price differentiation across German MRI procurement channels, compressing margins for non-compliant entrants while amplifying premium capture for pre-certified systems.
Pricing Analysis
Certification level (CE marking under EU MDR) creates the primary spread between premium superconducting platforms and commoditized extremity systems. Three-tier pricing structure across premium, standard, and economy levels stratifies by field strength, helium dependency, and after-sales service bundling. Cost compression in mid-tier diagnostic centers is intensifying because municipal hospital procurement consortia favor operational lease models over capital purchase. Private radiology chains exhibit highest price sensitivity due to throughput-dependent margin structures, while university hospital clusters prioritize performance specifications over acquisition cost.
Supply Chain Analysis
Strategic helium stockpiling dominates inventory strategy for superconducting magnet operators, contrasting with just-in-time component flows for cryogen-free permanent magnet assemblies. Niobium-titanium coil fabrication concentrates in Germany and Japan, while liquid helium extraction feeds from Qatar and Algeria. Raw material dependencies encompass rare earth elements for permanent magnets, liquid helium for cryogenic cooling, and specialized copper for gradient coils. Single-source vulnerability in helium logistics exposes German operators to geopolitical rationing. Distribution runs through regional procurement consortia that aggregate hospital demand across Bavaria and North Rhine-Westphalia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue streams—particularly helium supply contracts and AI-enabled reconstruction modules—expand faster than hardware sales, repositioning vendor economics toward recurring-revenue models.
For Market Incumbents: Fortify captive magnet manufacturing capabilities through backward integration into niobium-titanium coil production, insulating against rare earth supply disruptions. Deepen hospital system partnerships in Bavaria and North Rhine-Westphalia to lock out hybrid-technology competitors. Prioritize modular CE marking pathways that decouple hardware certification from algorithmic upgrades, compressing BfArM queue times.
For New Entrants and Emerging Players: Aftermarket service gaps in cryogen handling and superconducting coil maintenance—where Siemens Healthineers concentrates specialized clinical engineering talent—present white-space entry points. Portable MRI deployment in ambulatory surgery centers across Baden-Württemberg offers the most penetrable segment, bypassing fixed infrastructure capital constraints. Pursue outcome-based leasing partnerships with municipal hospital procurement consortia in Saxony and Thuringia.
For Investors and Strategic Acquirers: EU MDR enforcement deadlines reshaping the acquisition landscape favor targets with pre-certified technical documentation and established BfArM relationships. Five-to-ten year viability centers on helium-independent technology portfolios and AI reconstruction capabilities. Target mid-tier equipment specialists with cryogen-free platforms and regional radiology network contracts. Watch BfArM notified body capacity utilization as the inflection signal—queuing bottlenecks accelerate consolidation pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 10 compliance gates reimbursement eligibility across German hospital networks. |
| Helium Supply Agreement | Captive sourcing contracts with Qatar and Algeria insulate superconducting installations from price volatility. |
| Hospital System Partnership | Direct integration with Charité Berlin and Munich university clusters secures high-field platform demand. |
| Software Companion Development | AI-assisted reconstruction modules reduce scan times without proportional hardware scaling in saturated markets. |
| Reimbursement Strategy | BfArM alignment on multiparametric sequences enables premium capture in oncology and neurology applications. |
Research Methodology
Desk research of BfArM certification databases, EU MDR technical documentation filings, and hospital procurement records preceded structured interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and radiology department heads. Secondary validation drew from DIN standards publications, helium trade flow data, and regional government hospital investment disclosures. Bottom-up installation counts across Bavaria, North Rhine-Westphalia, and Baden-Württemberg triangulated against top-down market value estimates.
Variance decomposition across product type, technology architecture, clinical application, and end-user facility tier informed the analytical framework throughout the forecast period. CAGRs derived from segmented volume projections weighted by average selling price trajectories. Industry-specific inputs encompassed BfArM notified body capacity constraints, helium spot price volatility indices, and university hospital research funding allocations.
Forecasts assume regulatory continuity in EU MDR enforcement and BfArM reimbursement frameworks; material policy shifts would require re-modeling. Supply disruption in Qatari helium exports or extended BfArM certification queues constitute primary revision triggers. Revision becomes warranted when cryogen-free platform adoption crosses threshold penetration in regional radiology networks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Argentina Computed Tomography Market
Medical Imaging
North America Fluoroscopy Market
Medical Imaging
Asia-Pacific Digital Pathology Market
Medical Imaging
Hand-Held X-Rays Market
Medical Imaging
Intraoperative Imaging Market
Medical Imaging
Automated Contouring Radiotherapy Software Market
Medical Imaging
Mobile Radiography Systems Market
Medical Imaging
Mammography Detectors Market
Medical Imaging
Asia Pacific Nuclear Imaging Market
Medical Imaging
Europe Digital X-Ray Market
Medical Imaging
Magnetic Resonance Imaging Market
Medical Imaging
China Nuclear Imaging Market
Medical Imaging
Global Surgical Imaging Arms Market
Medical Imaging
Angiography Imaging Systems Market
Medical Imaging
Argentina Magnetic Resonance Imaging (MRI) Market
Medical Imaging
South Africa Nuclear Imaging Market