
 Facial Erythema Treatment Market | 2026-2036
Facial Erythema Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Facial Erythema Treatment Market Analysis
Specialty pharmacy distribution is fragmenting as direct-to-clinic channels and telemedicine platforms gain share. Galderma S.A. leverages its integrated dermatology portfolio to sustain physician loyalty across prescription and aesthetic segments. Bausch Health Companies Inc. anchors its position through concentrated R&D in topical immunomodulators. Pfizer Inc. competes via global manufacturing scale that supports cost-efficient supply to institutional buyers.
Facial erythema treatment encompasses pharmacological and device-based interventions targeting visible redness from rosacea, contact dermatitis, and vascular dysfunction, typically involving topical vasoconstrictors, anti-inflammatory agents, or selective laser wavelengths calibrated to hemoglobin absorption peaks. The primary commercial purpose centers on symptom suppression and aesthetic normalization for patients seeking both medical clearance and cosmetic improvement. Topical creams occupy the largest revenue pool due to established reimbursement pathways and physician familiarity, while laser treatments represent the fastest-expanding segment as fractional and pulsed-dye technologies achieve broader clinic adoption. Oral medications retain stable demand for severe and refractory cases where monotherapy proves insufficient.
The FDA governs drug approval and device clearance pathways, while HIPAA mandates data handling standards for telemedicine consultations that increasingly drive treatment initiation. State-level scope-of-practice regulations determine whether nurse practitioners and physician assistants can independently prescribe topical therapies, creating uneven access across jurisdictions. Stakeholders must monitor evolving payer policies on prior authorization for biologic and laser interventions, as coverage decisions will shape clinic investment and patient affordability.
Market Dynamics
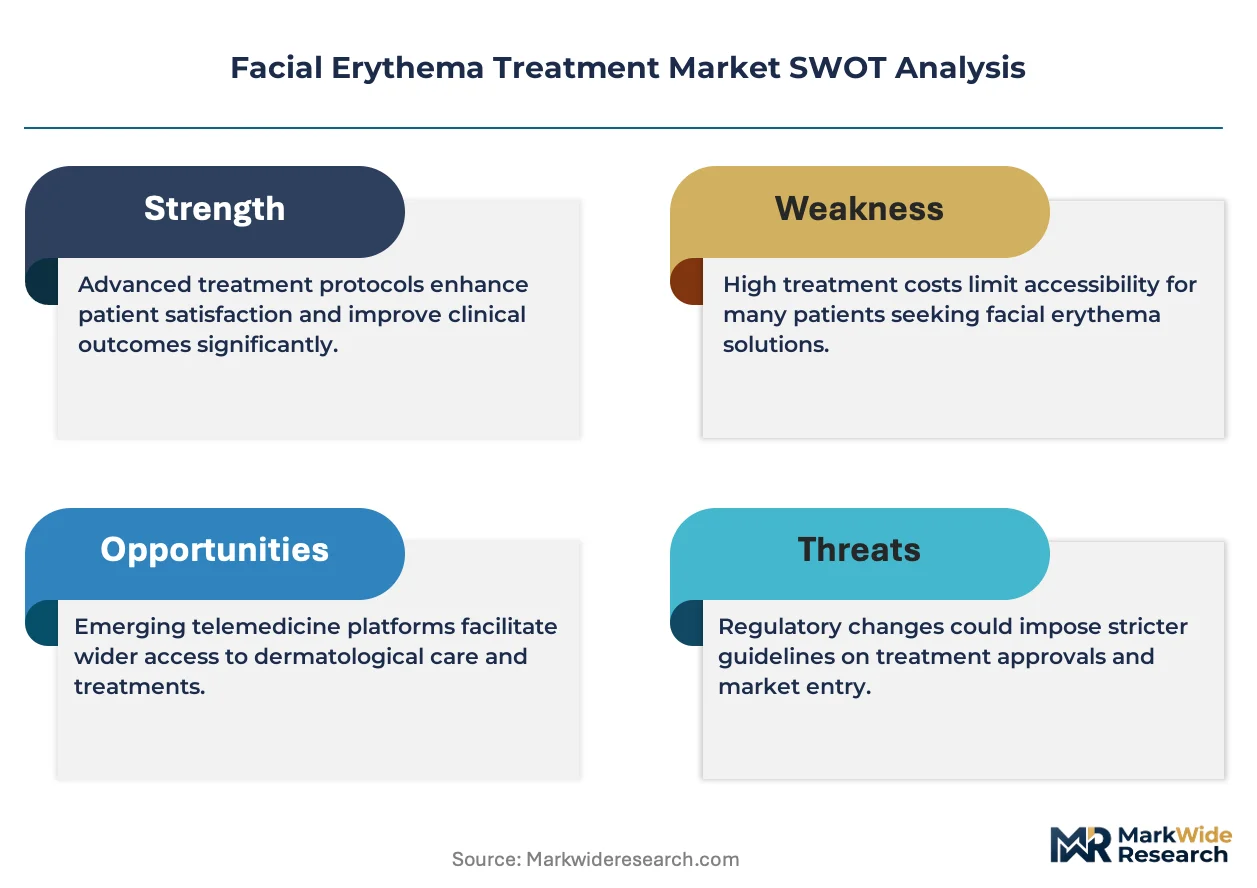
The FDA's escalating scrutiny of topical corticosteroid safety labels is forcing reformulation cycles across the facial erythema treatment pipeline, compressing development timelines while elevating investment in non-steroidal anti-inflammatory alternatives.
Growth Catalysts
- Telemedicine platform expansion:HIPAA-compliant virtual consultations now initiate treatment protocols in dermatology, accelerating patient access beyond traditional clinic geography.
- Topical immunomodulator innovation:Calcineurin inhibitors and JAK inhibitors are broadening the therapeutic arsenal for steroid-intolerant rosacea patients.
- Aesthetic medicine convergence:Medical spas and dermatology practices in the United States are integrating vascular laser services with pharmaceutical management, creating bundled care models.
Market Restraints
- Active pharmaceutical ingredient concentration:Dependence on specialized vasoconstrictor compounds from limited European suppliers creates supply vulnerability.
- Laser device capex thresholds:Pulsed-dye and fractional laser platforms require $150,000-$400,000 capital deployment per unit, restricting clinic adoption.
- Reimbursement fragmentation:Prior authorization requirements for biologic and device-based interventions vary by payer, creating unpredictable patient out-of-pocket exposure.
Strategic Opportunities
- Direct-to-clinic distribution channels:Specialty pharmacy intermediaries are losing share to manufacturer-direct fulfillment models that preserve margin and capture patient data.
- Combination therapy protocols:Sequential topical-laser regimens are demonstrating superior erythema reduction, opening protocol-driven prescribing opportunities.
- Rural and secondary market penetration:Nurse practitioner scope-of-practice expansions in select US states enable independent prescription authority where dermatologist density remains low.
Industry Challenges
- Laser technician certification pipelines:Safe operation of vascular-selective wavelengths demands specialized training that outpaces workforce development in expanding clinic networks.
- Legacy electronic health record integration:Telemedicine platforms face friction connecting with established practice management systems, complicating prescription workflow automation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Facial Erythema Treatment Market |
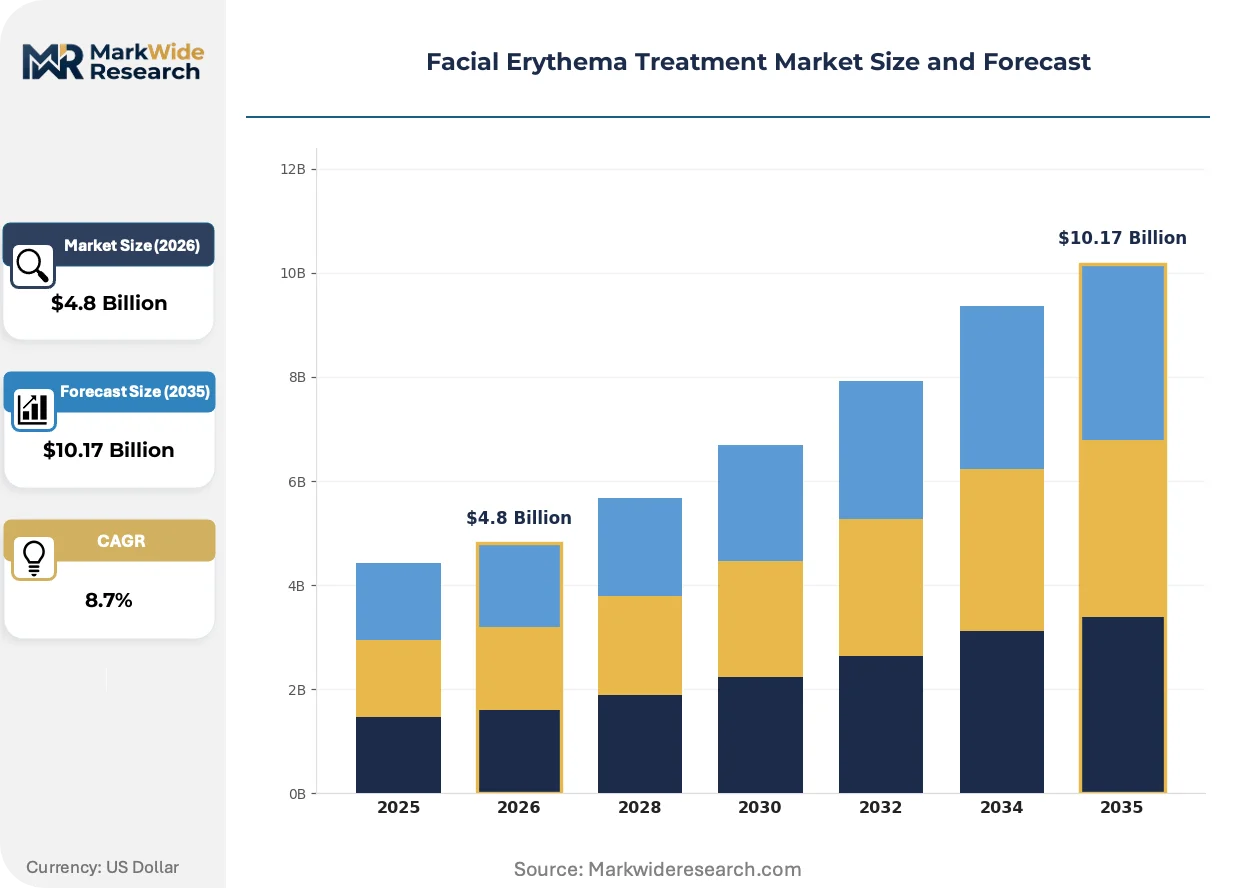
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Creams, Oral Medications, Laser Treatments, Light Therapy End User: Dermatology Clinics, Hospitals, Homecare Settings, Aesthetic Centers Treatment Stage: Initial, Maintenance, Severe, Acute Patient Demographics: Adults, Adolescents, Elderly, Males |
| Companies Covered | Galderma S.A., Bausch Health Companies Inc., Pfizer Inc., Astellas Pharma Inc., Novartis International AG, Sanofi S.A., LEO Pharma A/S, Merck & Co. Inc., AbbVie Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Facial Erythema Treatment Market Emerging Trajectories
Device-based interventions are compressing the traditional pharmaceutical-first treatment paradigm, while regulatory pressure on steroid safety accelerates alternative mechanism exploration. These forces are reshaping competitive positioning across the value chain.
Brimonidine-free vasoconstrictor formulations are collapsing the historical trade-off between rapid erythema suppression and rebound flushing risk. Dermatology clinics in high-competition metropolitan markets are adopting these alternatives within twelve months of formulary availability. The technology is collapsing confidence in legacy alpha-agonist monotherapy, forcing portfolio diversification among established topical manufacturers.
EMA's Medical Device Regulation (MDR) recertification requirements are extending laser device approval timelines by eighteen to thirty-six months for European market entry. Manufacturers are consolidating technical documentation and clinical evidence packages to satisfy notified body scrutiny. The vascular laser segment is absorbing these compliance costs through premium pricing in Germany, France, and the United Kingdom while delaying launches in smaller EU markets.
Subscription-based skincare protocols are displacing episodic prescription fulfillment for maintenance-phase rosacea management. Direct-to-consumer platforms capture patient adherence data that feeds back into personalized regimen adjustment, bypassing traditional pharmacy intermediaries. This behavioral shift concentrates in the United States where cash-pay aesthetic services already normalize recurring payment models for dermatological care.
Facial Erythema Treatment Market Segmentation
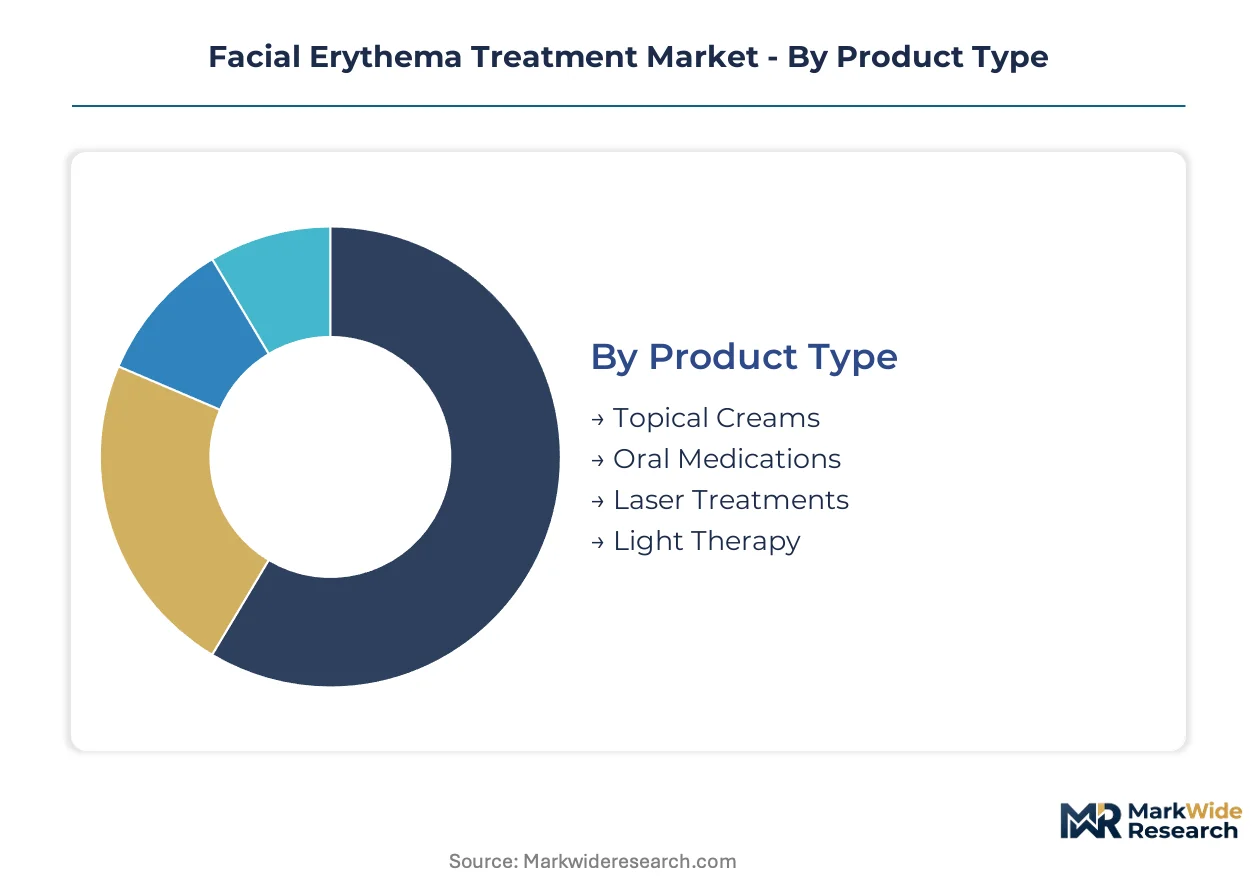
Treatment modality selection in facial erythema hinges on reimbursement pathways, physician certification requirements, and patient aesthetic expectations. Segmentation reveals where capital investment concentrates versus where volume prescription scales.
Product Type:
After-sales service intensity varies sharply across product categories, with laser platforms demanding continuous calibration support and topical formulations requiring minimal post-dispensing engagement.
- Topical Creams:Alpha-agonist and calcineurin inhibitor formulations dominate prescription volume through established pharmacy channels. United States dermatology practices favor these for first-line rosacea management due to favorable prior authorization profiles and patient self-administration convenience.
- Laser Treatments:Pulsed-dye and fractional platforms target hemoglobin absorption peaks for vascular lesion resolution. Aesthetic centers in metropolitan United States markets absorb the capital intensity, driven by cash-pay bundling with cosmetic services and superior erythema clearance rates for refractory cases.
- Oral Medications:Tetracycline-class antibiotics and isotretinoin derivatives address systemic inflammation in severe presentations. Demand concentrates where topical monotherapy fails.
- Light Therapy:LED-based narrowband devices offer home-use alternatives with lower efficacy ceilings. Adoption tracks direct-to-consumer marketing spend and telemedicine platform integration.
By volume, Topical Creams leads. By growth pace, Laser Treatments is ahead.
End User:
Procurement authority and reimbursement capture determine site-of-care economics, with institutional buyers extracting volume discounts unavailable to fragmented retail channels.
- Dermatology Clinics:Physician-directed diagnosis and prescription authority anchor the specialty channel. These sites combine pharmaceutical dispensing with procedural services, capturing margin across both modalities in United States urban and suburban markets.
- Aesthetic Centers:Medical spas and cosmetic surgery practices emphasize device-based interventions over pharmaceutical management. Patient self-pay orientation bypasses insurance friction, enabling premium pricing for bundled vascular laser protocols.
- Hospitals:Academic medical centers manage complex, multi-comorbid presentations requiring interdisciplinary coordination. Volume scales with referral network density.
- Homecare Settings:Telemedicine-originated prescriptions and direct-to-consumer device shipments bypass traditional clinical infrastructure. Growth tracks HIPAA-compliant platform expansion and subscription model normalization.
By patient throughput, Dermatology Clinics leads. By margin expansion, Aesthetic Centers is climbing fastest.
Treatment Stage:
Clinical protocol positioning dictates compound selection and visit frequency, with maintenance-phase regimens driving recurring revenue against acute interventions' episodic character.
- Initial:Diagnostic workup and first-line therapy selection establish patient-provider relationships. United States practices emphasize rapid visual improvement to secure adherence.
- Maintenance:Long-term suppression protocols prevent flare recurrence. Subscription-based skincare platforms capture this phase through automated refill and regimen adjustment.
- Severe:Refractory cases demand combination oral-device approaches. Concentrated in academic and high-volume specialty practices.
- Acute:Flare management requires rapid-access intervention capacity. Urgent care and telemedicine platforms compete for this episodic demand.
By revenue stability, Maintenance leads. By acuity-driven pricing, Severe commands premium expansion.
Patient Demographics:
Aesthetic concern intensity and treatment-seeking behavior vary across age and gender cohorts, shaping marketing allocation and product positioning.
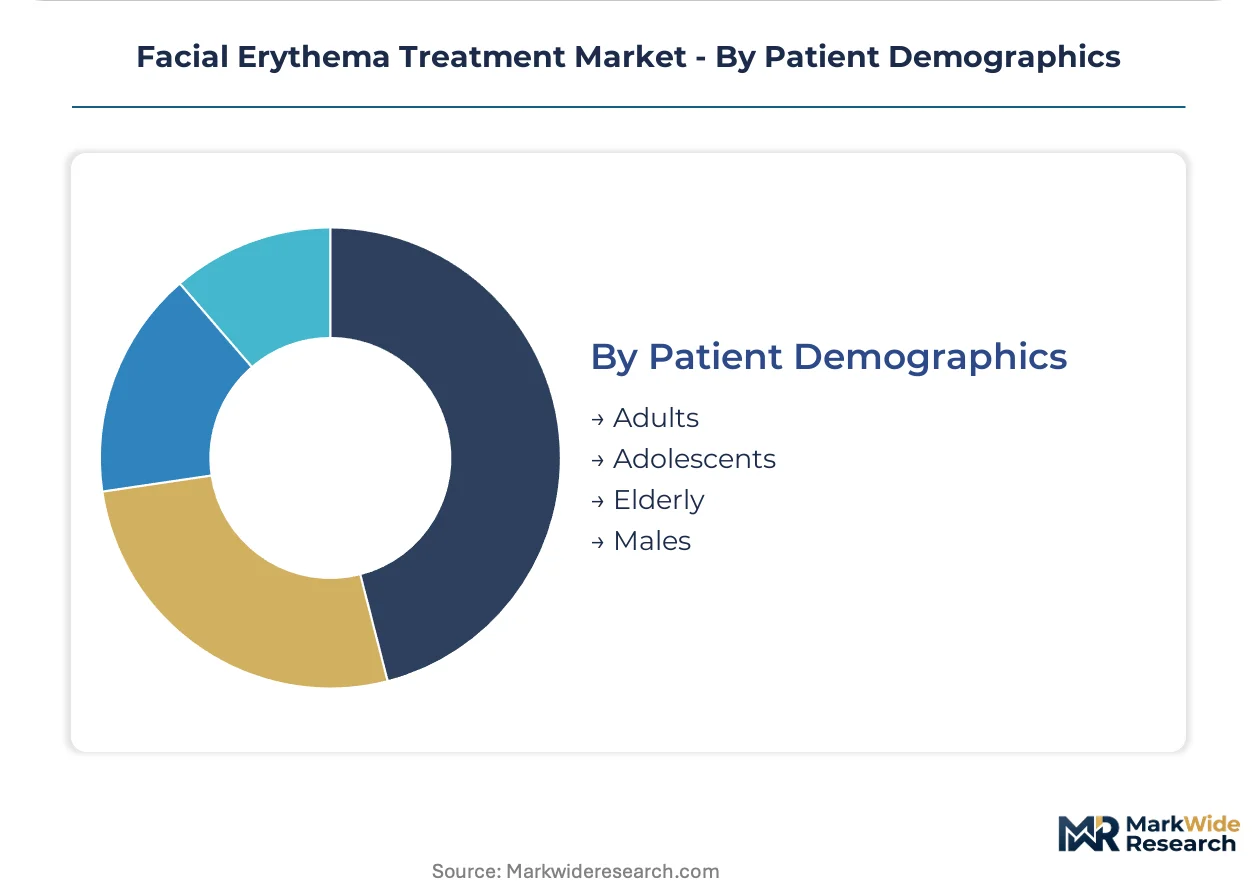
- Adults:Rosacea prevalence peaks in the 30-60 age bracket, correlating with discretionary income for elective aesthetic services. United States demand concentrates among employed professionals with employer-sponsored coverage.
- Elderly:Photodamage and vascular fragility compound erythema presentation. Medicare reimbursement patterns and polypharmacy risk constrain therapeutic options.
- Adolescents:Acne-rosacea overlap drives pediatric dermatology consultation. Parental consent requirements and off-label prescribing caution limit market development.
- Males:Underdiagnosed relative to females due to lower healthcare-seeking rates. Emerging targeted awareness campaigns seek to unlock latent demand.
By absolute volume, Adults leads. By diagnosis-rate improvement potential, Males shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States aesthetic clinics extract 40-60% pricing premiums over German dermatology practices for equivalent vascular laser protocols. Japanese patients face reimbursement delays that compress device adoption timelines relative to North American cash-pay markets. This asymmetry shapes where manufacturers prioritize regulatory submissions and direct sales force deployment.
United States
Employer-sponsored coverage expansion and medical spa consolidation drive procedural volume in metropolitan corridors. FDA's tightening topical steroid labeling requirements accelerate non-steroidal formulation submissions. Miami and Los Angeles anchor aesthetic center density, with bundled laser-pharmaceutical protocols capturing premium self-pay segments.
Germany
EMA Medical Device Regulation recertification extends laser platform approval timelines, compressing manufacturer margins. Statutory health insurance reimbursement codes for rosacea biologics remain restrictive relative to topical categories. Berlin and Munich concentrate academic dermatology research, with university hospitals piloting combination oral-device protocols for refractory cases.
Japan
PMDA's cautious stance on novel vasoconstrictor mechanisms delays launch windows versus US and EU markets. Aging demographics expand elderly erythema presentations from photodamage and vascular fragility. Osaka and Tokyo metropolitan areas concentrate aesthetic clinic chains, though cash-pay orientation limits volume scaling.
United Kingdom
NICE technology appraisals create binary reimbursement outcomes that concentrate prescribing in approved categories. Post-Brexit divergence from EMA centralized procedures adds regulatory complexity for topical innovators. London's Harley Street medical district sustains premium private dermatology, while NHS trusts in Manchester and Birmingham ration biologic access through specialist referral gates.
Australia
TGA's priority review pathway for dermatology devices accelerates pulsed-dye laser market entry relative to regional peers. Medicare rebate freezes on cosmetic indications push patients toward private payment for erythema management. Sydney and Melbourne anchor aesthetic medicine adoption, with telemedicine platforms penetrating Queensland and Western Australia secondary markets.
Facial Erythema Treatment Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower margin capture. The facial erythema treatment market consolidates around dermatology-focused pharmaceutical conglomerates and aesthetic device manufacturers with bundled service capabilities. Three archetypes dominate: integrated dermatology portfolios spanning prescription and aesthetic segments, concentrated topical immunomodulator R&D shops, and global manufacturing scale players serving institutional buyers. Competitive dynamics center on M&A activity absorbing mid-cap laser device firms and strategic partnerships between telemedicine platforms and direct-to-clinic distributors.
Among Swiss-headquartered dermatology specialists, Galderma S.A. occupies a position exemplifying integrated portfolio strategy across therapeutic and cosmetic segments. Bausch Health Companies Inc. represents the concentrated R&D archetype with its topical immunomodulator focus. Pfizer Inc. anchors the manufacturing scale tier, leveraging global supply infrastructure to serve hospital and clinic procurement channels. These three entities illustrate how geographic origin and corporate structure map to distinct competitive positioning within the value chain.
| Leading Market Players |
|---|
| Galderma S.A. |
| Bausch Health Companies Inc. |
| Pfizer Inc. |
| Astellas Pharma Inc. |
| Novartis International AG |
| Sanofi S.A. |
| LEO Pharma A/S |
| Merck & Co. Inc. |
| AbbVie Inc. |
| Others |
Supply Flow & Price Mechanics
Basel's cluster of topical formulation specialists supplies alpha-agonist APIs and calcineurin inhibitors that feed global dermatology markets, concentrating upstream pricing power among Swiss and German chemical manufacturers while downstream clinics face margin compression from laser device capex requirements.
Pricing Analysis
Configured-to-order pricing for compounded topical formulations commands spreads of 40-60% above standard pharmacy-dispensed generics. Three-tier pricing structure across premium, standard, and economy levels separates branded vasoconstrictor creams from authorized generics and mass-market alternatives. Price differentiation rests on FDA approval tier and after-sales clinical support bundling. Pricing pressure stems from Medicare rebate freezes and cash-pay aesthetic center competition. Hospital procurement committees exhibit highest price sensitivity; aesthetic centers with bundled service models show lowest.
Supply Chain Analysis
Export-control regimes on specialized laser optics and semiconductor components for vascular wavelength generation limit flows from German and Japanese precision manufacturers to non-allied markets. Active pharmaceutical ingredient production concentrates in Switzerland, Germany, and India for topical immunomodulators. Raw material dependencies include specialized vasoconstrictor compounds, medical-grade silicones for device housings, and rare-earth elements for laser crystal arrays. Single-source vulnerability runs through European notified-body certification bottlenecks for MDR compliance. Distribution runs through specialty pharmacy intermediaries losing share to direct-to-clinic manufacturer fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Laser technician certification pipelines and EMA MDR technical documentation expertise constitute binding constraints that gate market expansion, with qualified personnel and regulatory specialists commanding premium retention packages across European and North American markets.
For Market Incumbents: Build switching-cost moats through integrated electronic health record-telemedicine platform partnerships that embed prescription workflow automation. Deepen backward integration into API manufacturing to offset European supplier concentration. Expand nurse practitioner training partnerships in Texas and Florida where scope-of-practice expansions enable independent prescription authority. Counter threat from direct-to-consumer subscription platforms by capturing patient adherence data through proprietary refill systems.
For New Entrants and Emerging Players: Pursue white-space opportunity in male-targeted rosacea awareness campaigns and diagnostic protocols, where underdiagnosis rates exceed 40% relative to female populations. Target rural United States markets in the Mountain West and Great Plains where dermatologist density falls below 3 per 100,000 population. Penetrate through telemedicine platform partnerships that bypass traditional clinic infrastructure requirements and accelerate patient access beyond metropolitan corridors.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors aesthetic device manufacturers with bundled service capabilities and recurring revenue attachment rates. Five-to-ten year viability hinges on FDA clearance backlogs and EMA MDR recertification timelines that compress competitive pressure from Asian entrants. Acquisition target archetype: mid-cap laser device firms with proprietary wavelength patents and established European notified-body relationships. Signal to watch: prior authorization approval rates for biologic-device combination protocols as inflection indicator for reimbursement-driven demand expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Telemedicine Platform Integration | HIPAA-compliant virtual consultations accelerate patient access beyond traditional clinic geography constraints. |
| Direct-to-Clinic Distribution Buildout | Manufacturer-direct fulfillment preserves margin and captures patient adherence data lost to pharmacy intermediaries. |
| Laser Technician Certification Pipeline | Specialized training programs address workforce development gaps that outpace expanding clinic network demands. |
| Non-Steroidal Formulation R&D | Calcineurin inhibitor and JAK inhibitor innovation responds to FDA tightening of topical corticosteroid safety labels. |
| Combination Therapy Protocol Development | Sequential topical-laser regimens demonstrate superior erythema reduction and open protocol-driven prescribing opportunities. |
Methodological Framework
Operator-level perspectives from dermatology practice administrators, laser device service engineers, specialty pharmacy procurement directors, and telemedicine platform compliance officers anchored the qualitative base. These primary inputs combined with secondary validation from FDA 510(k) filings, EMA MDR technical documentation, ClinicalTrials.gov rosacea intervention records, and hospital GPO contract databases. Bottom-up prescription volume modeling and top-down aesthetic procedure expenditure estimates provided triangulation across analysis approaches.
Scenario-bracketing framed demand projections across conservative, baseline, and accelerated telemedicine adoption pathways over the projection horizon. Segmentation dimensions modeled include treatment modality, end-user site of care, disease severity stage, and patient demographic cohort. CAGRs derived from procedure volume trajectories and average selling price evolution by product tier. Industry-specific forecast inputs incorporated prior authorization approval rate assumptions and laser device replacement cycle timing.
Sensitivities concentrate around FDA labeling regulation shifts, EMA MDR recertification timeline extensions, and nurse practitioner scope-of-practice legislative changes. Forecasts reflect assumptions on reimbursement stability and cash-pay aesthetic service demand normalization. Material shifts in Medicare coverage determination for biologic-device combination protocols or major European notified-body capacity constraints would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
Exfoliators and Scrubs Market
Skincare
Bangladesh Skin Care Products Market
Skincare
Acne Treatment Market
Skincare
Hand Eczema (HE) Treatment Market
Skincare
Facial Mist Market
Skincare
Sun-Care Wipes Market
Skincare
Retinol Skincare Product Market
Skincare
Biological Skin Substitutes Market
Skincare
Africa Cosmeceutical Market
Skincare
Sensitive Skin Care Products Market
Skincare
Allantoin Extract for Skincare Products Market
Skincare
CBD Skincare Products Market
Skincare
Global Hand Lotion and Hand Cream Market
Skincare
Encapsulated Retinol Market
Skincare
DNA-Based Skin Care Products Market
Skincare
Peel Off Face Mask Market