
 Germ Cell Tumors Market | 2026-2036
Germ Cell Tumors Market Size, Share, and Industry Trends Forecast 2026-2036
Germ Cell Tumors Market Foresight
The capital-intensity divergence between large-cap biopharma and emerging immuno-oncology specialists is unwinding as platform technologies commoditize. Bristol-Myers Squibb leverages its checkpoint inhibitor infrastructure to anchor combination trials in refractory germ cell settings. Pfizer sustains manufacturing scale advantages across platinum-based chemotherapy supply chains. Merck & Co. dominates PD-1 expansion into rare oncology indications through investigator-initiated study networks.
Germ cell tumors comprise neoplasms arising from primordial germ cells, characterized by histological subtypes including seminomatous and non-seminomatous differentiation, with serum tumor markers AFP and beta-hCG serving as diagnostic and monitoring parameters. These malignancies primarily demand multimodal treatment approaches spanning surgical resection, systemic chemotherapy, and radiation intervention. Chemotherapy drugs retain the largest revenue pool due to entrenched platinum-based protocols, while immunotherapy agents represent the fastest-expanding segment as checkpoint inhibitors penetrate salvage therapy. Diagnostic kits command premium pricing in specialized cancer centers where biomarker stratification guides treatment selection.
FDA orphan drug designation and EMA PRIME eligibility criteria shape clinical development priorities and market access timelines for germ cell innovators. ISO 14155 and ICH-GCP standards govern trial conduct across North American and European investigative sites, elevating compliance costs for mid-stage sponsors. Stakeholders must monitor regulatory precedent for accelerated approval in platinum-refractory populations where unmet need remains acute.
Market Dynamics
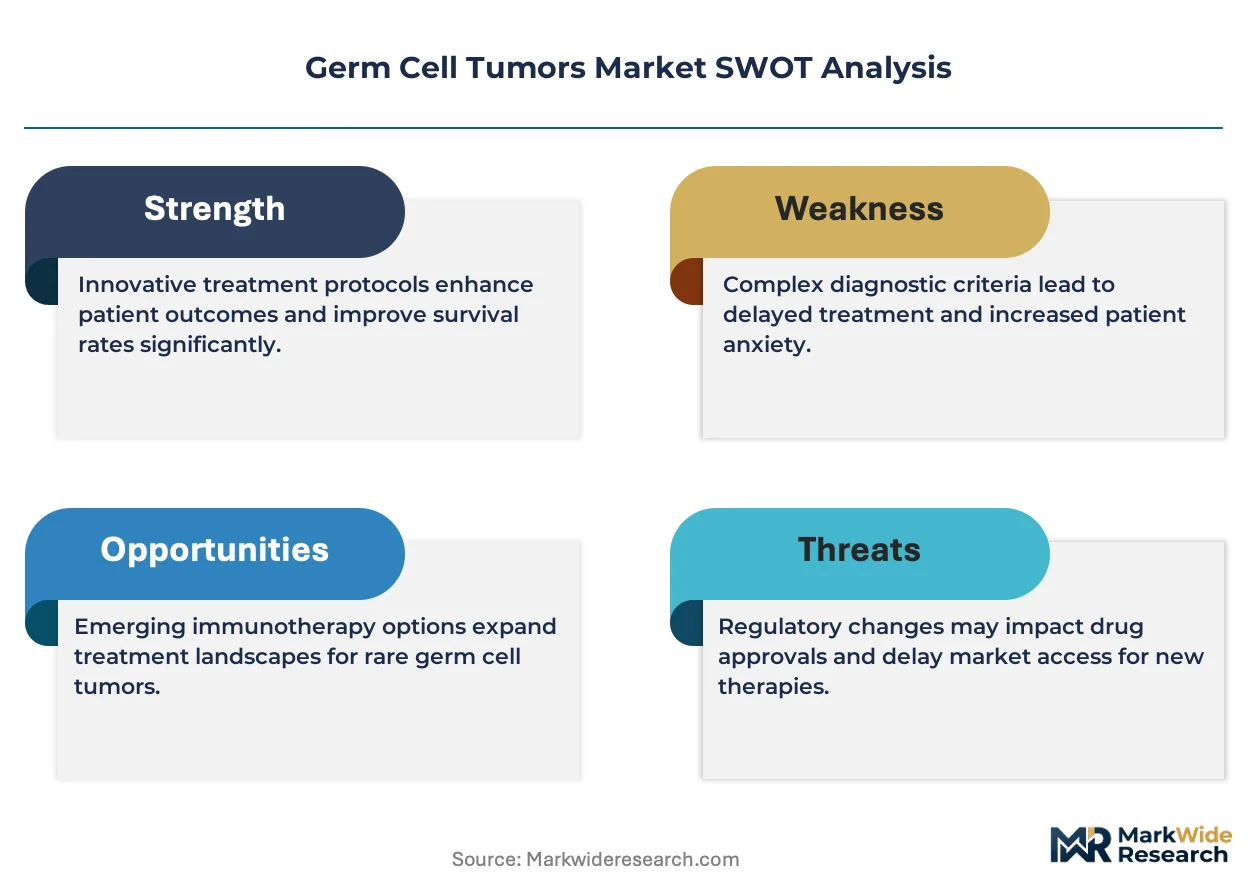
Checkpoint inhibitor platform commoditization is redrawing competitive boundaries between large-cap biopharma and emerging immuno-oncology specialists in germ cell tumor therapeutics.
Growth Catalysts
- EMA PRIME eligibility:Accelerated assessment pathways compress development timelines for platinum-refractory indications, attracting venture funding into rare oncology pipelines.
- Serum biomarker stratification:AFP and beta-hCG monitoring protocols enable precision dosing in oncology clinics, improving salvage therapy selection and patient retention.
- Specialized cancer center clustering:Concentrated expertise in the United States, Germany, and Japan drives protocol standardization and investigator-initiated trial volume.
Market Restraints
- Platinum supply concentration:Manufacturing scale advantages concentrate among established chemotherapy producers, creating barriers for new entrants in platinum-based protocol supply.
- ICH-GCP compliance costs:Mid-stage sponsors face elevated trial conduct expenses across North American and European investigative sites, compressing R&D budgets.
- Radiation therapy substitution:Multimodal treatment approaches in early-stage seminoma reduce chemotherapy dependency in select patient populations.
Strategic Opportunities
- Japan's orphan drug framework:PMDA accelerated review pathways for rare malignancies create regulatory arbitrage for first-movers in PD-1 expansion.
- Diagnostic kit premiumization:Biomarker-guided treatment selection commands pricing power in tertiary referral centers with integrated pathology services.
- AI-enabled imaging convergence:Machine learning classification of histological subtypes is streamlining pathology workflows in high-volume cancer centers.
Industry Challenges
- Investigator network scarcity:Qualified principal investigators with germ cell tumor trial experience concentrate at academic medical centers, limiting site activation speed.
- ISO 14155 certification timelines:Medical device diagnostic kit manufacturers face extended validation periods for European market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germ Cell Tumors Market |
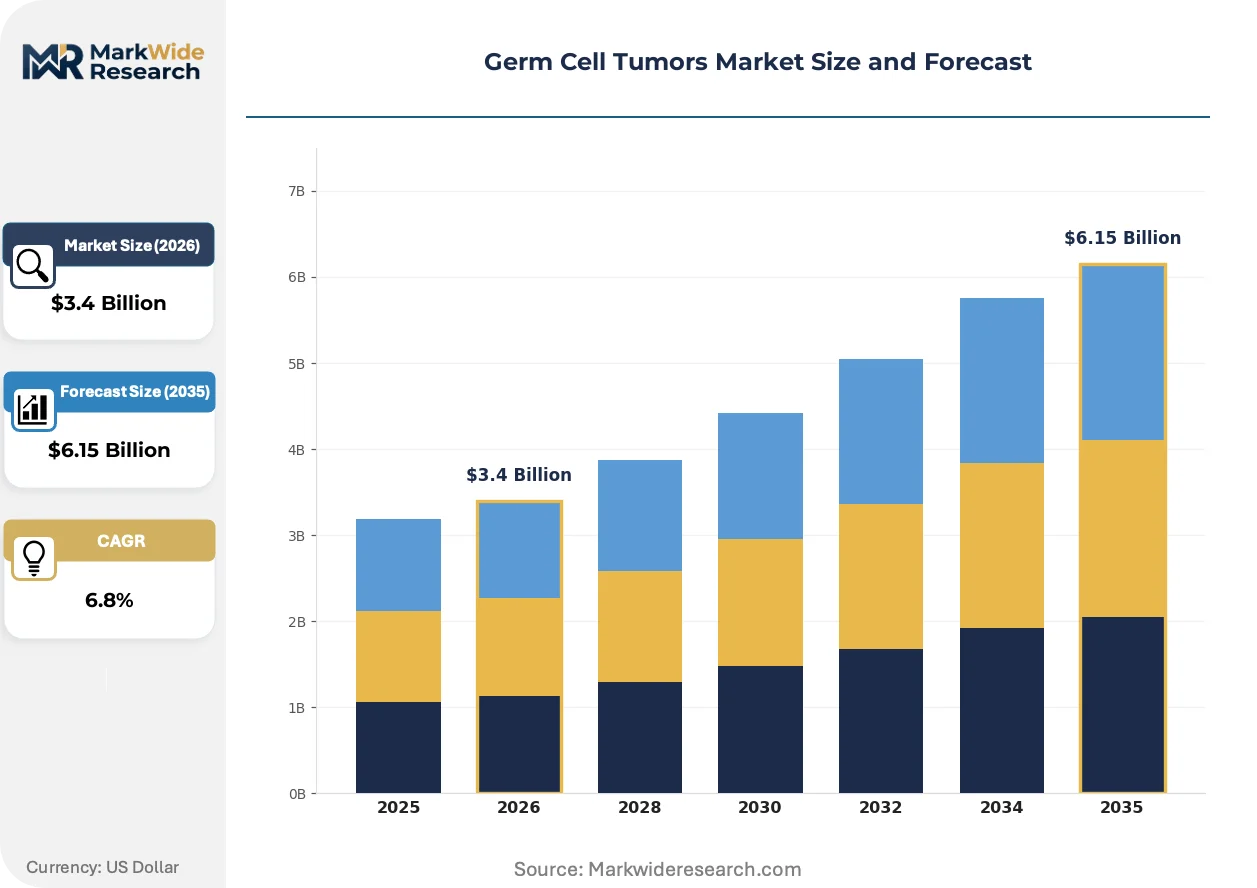
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $6.15 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy Drugs, Surgical Instruments, Radiation Equipment, Diagnostic Kits, Immunotherapy Agents Therapy Area: Testicular Tumors, Ovarian Germ Cell Tumors, Extragonadal Tumors, Pediatric Germ Cell Neoplasms, Mediastinal Tumors End User: Oncology Clinics, Specialized Cancer Centers, Academic Hospitals, Ambulatory Surgical Centers, Research Laboratories Treatment Modality: Surgical Resection, Radiotherapy, Chemotherapy, Targeted Therapy, Stem Cell Transplantation |
| Companies Covered | Bristol-Myers Squibb Company, Pfizer Inc., F. Hoffmann-La Roche AG, Novartis AG, Merck & Co., Inc., AstraZeneca PLC, Bayer AG, Johnson & Johnson, Eli Lilly and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germ Cell Tumors Market Shifts & Advancements
Platform technology diffusion is eroding traditional moats between biopharma scale players and specialized immuno-oncology developers, forcing new collaboration architectures.
Liquid biopsy monitoring for circulating tumor DNA is supplanting serial imaging in post-chemotherapy surveillance protocols. Oncology clinics in tertiary referral networks are adopting this technology to reduce radiation exposure and compress follow-up intervals. The shift is enabling earlier detection of recurrence while compressing demand for traditional radiology services.
FDA orphan drug designation criteria are tightening evidentiary standards for accelerated approval in platinum-refractory settings. Sponsors must now demonstrate durable response rates rather than single-arm activity signals, extending Phase II duration. Germ cell innovators are responding by embedding biomarker enrichment strategies into trial design.
Consolidated purchasing by integrated delivery networks is displacing individual hospital pharmacy procurement for high-cost immunotherapy agents. Specialty distributors with cold-chain capabilities are capturing volume previously handled by wholesale intermediaries. This concentration is most pronounced in the United States where hospital system mergers have accelerated formulary standardization.
Germ Cell Tumors Market Segmentation
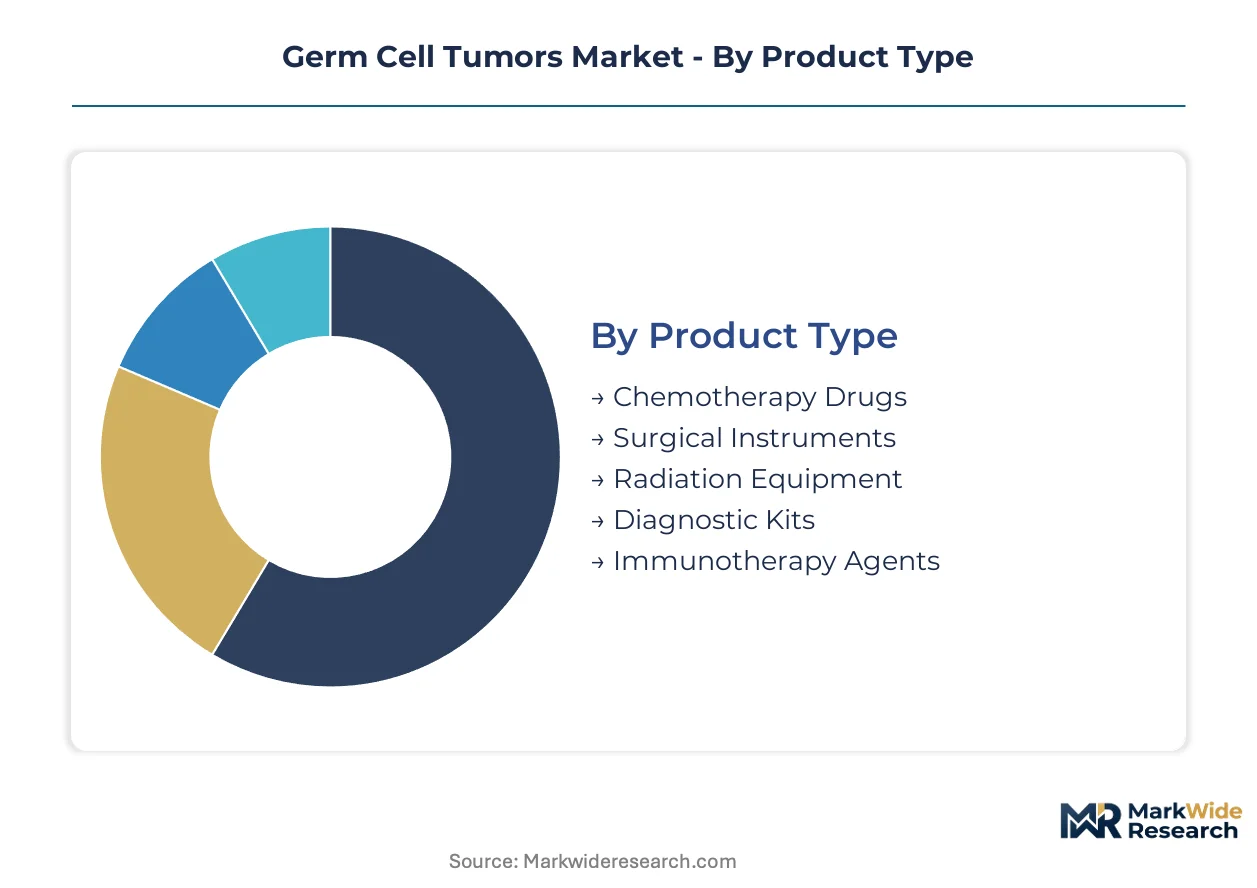
Segmentation in the germ cell tumors market reveals how therapeutic modality, institutional setting, and disease site interact to shape procurement patterns and technology adoption. Understanding these divisions enables stakeholders to identify where platinum-based protocols retain dominance versus where checkpoint inhibitors and precision diagnostics are gaining traction.
Product Type:
Domestic manufacturing concentration varies sharply across product categories, with chemotherapy drugs and surgical instruments showing strong regional supply bases while immunotherapy agents flow through global distribution networks.
- Chemotherapy Drugs:Platinum-based regimens retain entrenched protocol status across first-line and salvage therapy settings. Demand concentrates in oncology clinics across the United States and Germany where established infusion infrastructure supports high-volume administration.
- Immunotherapy Agents:Checkpoint inhibitors targeting PD-1/PD-L1 pathways represent the fastest-expanding revenue pool as salvage therapy protocols evolve. Japan's PMDA accelerated review pathways and the FDA's orphan drug designation framework are compressing commercial timelines for first-movers.
- Diagnostic Kits:AFP and beta-hCG biomarker assays command premium pricing in specialized cancer centers with integrated pathology services.
- Surgical Instruments:Resection tools for retroperitoneal lymph node dissection follow hospital capital equipment procurement cycles.
- Radiation Equipment:Linear accelerator capacity expansion is slowing as multimodal protocols shift toward chemotherapy and immunotherapy prioritization.
Chemotherapy drugs command the established base. The steepest expansion runs through immunotherapy agents.
Therapy Area:
Volume distribution across therapy areas reflects epidemiological incidence patterns and age-stratified presentation, with testicular tumors driving adult case volume and pediatric neoplasms requiring specialized institutional capabilities.
- Testicular Tumors:Seminomatous and non-seminomatous subtypes comprise the largest addressable population, with serum marker monitoring enabling precision surveillance. Academic hospitals in the United States and Germany anchor clinical trial activity for platinum-refractory protocols.
- Ovarian Germ Cell Tumors:Rare malignancies in young women demand fertility-preserving surgical approaches and modified chemotherapy dosing. Specialized cancer centers in Japan and the United States concentrate expertise and patient referral networks.
- Pediatric Germ Cell Neoplasms:Sacrococcygeal and intracranial presentations require multidisciplinary coordination between pediatric oncology and surgical subspecialties.
- Extragonadal Tumors:Pineal and retroperitoneal sites present diagnostic complexity and delayed detection challenges.
- Mediastinal Tumors:Anterior mediastinal masses require differentiation from lymphoma and thymic neoplasms through immunohistochemical profiling.
Testicular tumors anchor volume concentration. Pediatric germ cell neoplasms show the most pronounced institutional capability differentiation.
End User:
Procurement authority and budget scale diverge markedly across settings, with integrated delivery networks consolidating purchasing for high-cost agents while academic sites retain investigator-initiated trial autonomy.
- Specialized Cancer Centers:Tertiary referral networks in the United States, Germany, and Japan concentrate protocol innovation and biomarker-guided treatment selection. These sites command premium pricing for diagnostic kits and experimental therapy access.
- Oncology Clinics:Community-based infusion centers handle stable chemotherapy administration but lack salvage therapy complexity. Consolidated purchasing through specialty distributors is displacing wholesale intermediaries for immunotherapy agents.
- Academic Hospitals:Principal investigator networks with germ cell tumor trial experience concentrate at these sites, limiting site activation speed for mid-stage sponsors.
- Ambulatory Surgical Centers:Early-stage seminoma orchiectomy procedures are migrating to lower-acuity settings where feasible.
- Research Laboratories:Liquid biopsy and circulating tumor DNA platforms are supplanting serial imaging in post-chemotherapy surveillance protocol development.
Specialized cancer centers concentrate pricing power. Oncology clinics are gaining share fastest through network expansion.
Treatment Modality:
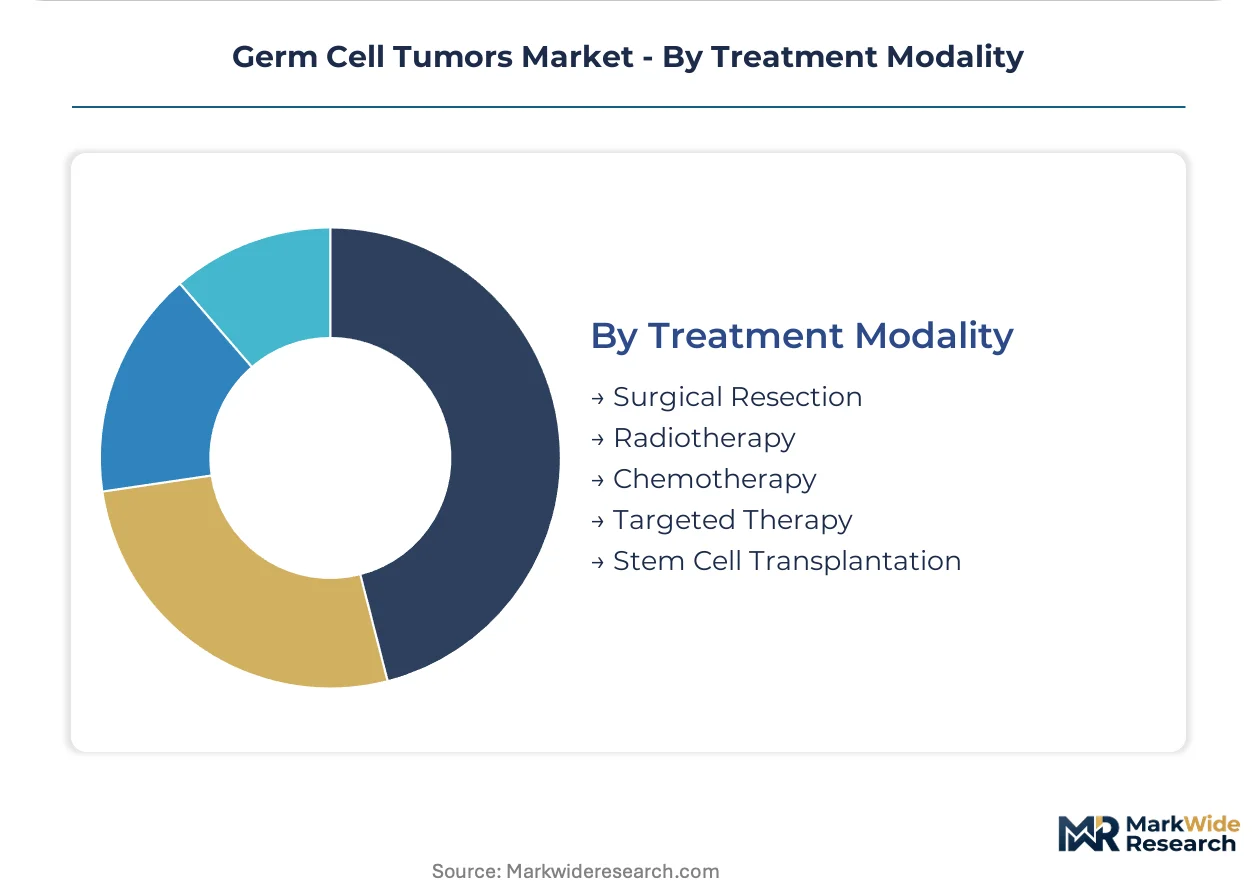
Cost tier stratification separates capital-intensive radiation infrastructure from pharmaceutical-driven systemic therapy, with targeted agents occupying the highest margin position.
- Chemotherapy:Platinum-based protocols retain first-line standard of care across seminomatous and non-seminomatous disease. Manufacturing scale advantages concentrate among established producers, creating supply barriers for new entrants.
- Targeted Therapy:Signal pathway inhibitors and antibody-drug conjugates represent the highest-margin treatment tier with concentrated development pipelines. FDA orphan drug designation criteria tightening evidentiary standards is extending Phase II duration for sponsors.
- Surgical Resection:Retroperitoneal lymph node dissection expertise concentrates at high-volume academic centers.
- Radiotherapy:Early-stage seminoma treatment is seeing substitution toward surveillance protocols, compressing volume growth.
- Stem Cell Transplantation:High-dose chemotherapy with autologous rescue remains restricted to select platinum-refractory cases at specialized centers.
Chemotherapy anchors the established revenue base. Targeted therapy shows the steepest margin expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in germ cell tumor therapeutics tilts toward the United States and Germany, where specialized cancer centers command premium reimbursement for biomarker-guided protocols, while manufacturing scale advantages concentrate chemotherapy supply chains in established pharmaceutical clusters.
United States
FDA accelerated approval pathways for orphan oncology indications compress commercial timelines for platinum-refractory germ cell therapies. The Orphan Drug Act provisions grant market exclusivity incentives that attract venture funding into rare malignancy pipelines. Memorial Sloan Kettering Cancer Center and MD Anderson anchor investigator-initiated trial networks in New York City and Houston.
Germany
EMA PRIME eligibility criteria enable accelerated assessment for innovative germ cell tumor therapeutics entering European markets. The country's statutory health insurance system maintains favorable reimbursement for biomarker-stratified treatment selection in tertiary oncology centers. Heidelberg and Munich concentrate clinical trial infrastructure through university hospital networks.
Japan
PMDA accelerated review pathways for rare malignancies create regulatory arbitrage opportunities for checkpoint inhibitor developers targeting germ cell salvage therapy. The country's aging demographic profile sustains demand for precision oncology diagnostics in urban cancer centers. Tokyo and Osaka host the highest concentration of specialized gonadal tumor treatment facilities.
United Kingdom
NICE technology appraisals govern market access for high-cost immunotherapy agents in testicular and ovarian germ cell malignancies. The Cancer Drugs Fund provides provisional reimbursement for promising therapies pending full evidence generation. London's Royal Marsden Hospital anchors national referral networks for complex retroperitoneal lymph node dissection cases.
Switzerland
Swissmedic maintains streamlined authorization procedures for oncology therapeutics with existing FDA or EMA approvals, reducing time-to-market for germ cell innovators. The country's compulsory health insurance framework supports premium pricing for targeted therapy agents. Basel and Zurich concentrate pharmaceutical R&D infrastructure through established biopharma headquarters.
Germ Cell Tumors Market Competitive Landscape
Concentration sits with large-cap biopharma holding checkpoint inhibitor infrastructure and platinum-based chemotherapy manufacturing scale. The competitive terrain divides between established oncology portfolios with global distribution networks and emerging immuno-oncology specialists pursuing salvage therapy indications. Three archetypes dominate: scale-driven incumbents with integrated manufacturing, platform-technology developers licensing combination protocols, and diagnostic kit specialists capturing biomarker stratification value. Competitive moves center on investigator-initiated trial network expansion and specialty distributor partnerships for cold-chain immunotherapy logistics.
Within the scale-driven tier, Bristol-Myers Squibb Company and Pfizer Inc. occupy positions anchoring combination therapy development, while Merck & Co., Inc. represents the platform-leverage archetype through PD-1 pathway expansion into rare oncology indications. These entities exemplify how manufacturing infrastructure and clinical trial footprint determine competitive positioning in platinum-refractory germ cell settings.
| Leading Market Players |
|---|
| Bristol-Myers Squibb Company |
| Pfizer Inc. |
| F. Hoffmann-La Roche AG |
| Novartis AG |
| Merck & Co., Inc. |
| AstraZeneca PLC |
| Bayer AG |
| Johnson & Johnson |
| Eli Lilly and Company |
| Others |
Supply & Pricing Matrix
FDA orphan drug designation criteria and EMA PRIME eligibility standards simultaneously gate supply qualification for germ cell tumor innovators and enable premium pricing tiers for biomarker-stratified protocols. These regulatory frameworks compress development timelines for first-movers while erecting compliance cost barriers that protect pricing power in platinum-refractory indications.
Pricing Analysis
The customization-premium spread separates standard platinum-based chemotherapy protocols from precision-guided immunotherapy combinations in tertiary cancer centers. Pricing stratifies across premium, standard, and economy tiers based on biomarker enrichment complexity and cold-chain logistics requirements. Cost compression in community oncology clinics is intensifying because consolidated purchasing by integrated delivery networks concentrates formulary decision-making. Academic medical centers show least price sensitivity due to investigator-initiated trial autonomy and research funding offsets.
Supply Chain Analysis
Strategic stockpiling of platinum salts and checkpoint inhibitor biologics dominates inventory strategy over just-in-time approaches given manufacturing lead times and cold-chain fragility. Active pharmaceutical ingredient production concentrates in India, China, and Switzerland for small-molecule chemotherapy, while biologics manufacturing clusters in the United States, Germany, and Ireland. Supply chain risk hinges on single-source vulnerability for platinum group metal refining. Distribution runs through specialty distributors with validated cold-chain capabilities rather than wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germ cell tumor therapeutics represent early-cycle expansion as checkpoint inhibitors penetrate salvage therapy protocols previously dominated by chemotherapy alone. PD-1 pathway expansion into platinum-refractory settings accelerates adoption velocity across specialized cancer centers.
For Market Incumbents: Consolidate investigator-initiated trial networks at academic medical centers to defend against emerging immuno-oncology specialists encroaching on salvage therapy indications. Deepen backward integration into platinum-based API supply to offset manufacturing scale advantages held by established chemotherapy producers. Prioritize biomarker companion diagnostic co-development to lock in protocol standardization. For New Entrants and Emerging Players: Service-layer gaps in liquid biopsy monitoring and circulating tumor DNA surveillance present entry vectors where incumbents under-serve community oncology clinics. Target ambulatory surgical centers in the United States for orchiectomy procedure migration as the most penetrable setting. Deploy AI-enabled pathology classification tools as a differentiated go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across diagnostic kit manufacturing as platform technologies commoditize, compressing returns for hardware-heavy business models. Platform-technology developers with PD-1 licensing flexibility and combination trial infrastructure represent optimal acquisition archetypes. Watch FDA orphan drug designation evidentiary standards tightening as the signal for portfolio rebalancing toward durable response rate demonstrators.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Checkpoint inhibitor salvage therapy protocols in platinum-refractory settings reshape competitive positioning at Memorial Sloan Kettering and MD Anderson. |
| Regulatory Approval Pathway | EMA PRIME eligibility compresses European market access timelines for biomarker-enriched germ cell indications. |
| Manufacturing Scale-Up | Platinum-based chemotherapy supply chain concentration in established producers creates barriers for mid-stage sponsors. |
| Pipeline Diversification | Antibody-drug conjugate expansion into ovarian germ cell tumors addresses fertility-preserving protocol demand in Japan. |
| Strategic Partnership | Specialty distributor alliances for cold-chain logistics capture volume from wholesale intermediaries in United States integrated delivery networks. |
Research Methodology
Cross-validation between primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers anchors the qualitative findings against secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient flow modeling and top-down revenue triangulation reconcile volume and value estimates across the analysis window.
Sensitivity analysis frames the quantitative framework, with segmentation dimensions spanning treatment line, histological subtype, administration route, and regional regulatory cluster. CAGRs derive from epidemiological incidence projections, protocol penetration curves, and pricing elasticity assumptions. Forecast inputs incorporate biomarker-guided therapy adoption rates and platinum-refractory population sizing.
Forecasts assume regulatory continuity in FDA accelerated approval pathways and EMA PRIME eligibility; material policy shifts would require re-modeling. Revision becomes warranted when checkpoint inhibitor durable response rate thresholds cross evidentiary standards for full approval conversion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Vesicoureteral Reflux Market
Specialty Medicine
Acute Myeloid Leukemia Therapeutics Market
Specialty Medicine
Liver Metastases Treatment Market
Specialty Medicine
Toxoplasmosis Treatment Market
Specialty Medicine
Hypothyroidism Market
Specialty Medicine
Global Occupational Medicines Market
Specialty Medicine
Barotrauma Market
Specialty Medicine
Global Anal Fistula Treatment Market
Specialty Medicine
Whipple's Disease Market
Specialty Medicine
Global Primary Immunodeficiency Therapeutics Market
Specialty Medicine
Benign and Malignant Soft Tissue Tumors Treatment Market
Specialty Medicine
Severe Combined Immunodeficiency Market
Specialty Medicine
Epilepsy Treatment Market
Specialty Medicine
Stuttering Therapeutics Market
Specialty Medicine
Hemangioma Market
Specialty Medicine
Advanced Basal Cell Carcinoma Market