
 Contrast Media/Contrast Agents Market | 2026-2036
Contrast Media/Contrast Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Contrast Media/Contrast Agents Market Intelligence
The capital investment gap between developing next-generation macrocyclic gadolinium agents and producing high-volume iodinated generics is unwinding traditional competitive structures. GE HealthCare leverages its installed base of imaging equipment to drive agent sales. Bayer AG sustains a strong position through its extensive portfolio in both CT and MRI contrast media. Bracco Imaging S.p.A. specializes in a diversified range of diagnostic imaging solutions, including ultrasound.
Contrast media are chemical substances administered to patients to improve the visibility of internal body structures during medical imaging. These agents function by selectively attenuating X-rays for computed tomography or altering proton relaxation times for magnetic resonance imaging. Iodinated agents represent the largest product segment, tied to the high volume of CT and X-ray procedures. In contrast, gadolinium-based agents, while smaller in volume, are critical for specific diagnostic questions in magnetic resonance imaging.
Regulatory oversight from bodies like the U.S. FDA, the European Medicines Agency (EMA), and China's NMPA is stringent. These agencies mandate extensive clinical trials for new agent approvals and enforce strict labeling regarding potential risks, such as gadolinium deposition. Forward-looking strategy for manufacturers depends on navigating these safety regulations while addressing demands for cost-effective solutions from large hospital networks.
Market Dynamics
The central structural force shaping the contrast media market is the unwinding of traditional competitive structures, driven by the capital investment gap between developing safer, next-generation macrocyclic agents and producing high-volume, commoditized iodinated generics for routine procedures.
Growth Catalysts
- Advanced Microbubbles:The development of new microbubble and nanobubble technologies for contrast-enhanced ultrasound (CEUS) is expanding its diagnostic utility in areas like cardiology and oncology, creating new demand streams.
- China's Healthcare Expansion:Rapid expansion of hospital infrastructure and increasing public health insurance coverage in China, coupled with its aging demographic, are major volume drivers for CT and MRI procedures.
- Non-Ionic Agent Adoption:A decisive shift towards safer, low-osmolality non-ionic iodinated agents is reducing the incidence of adverse patient reactions, supporting higher procedural volumes in diagnostic imaging centers.
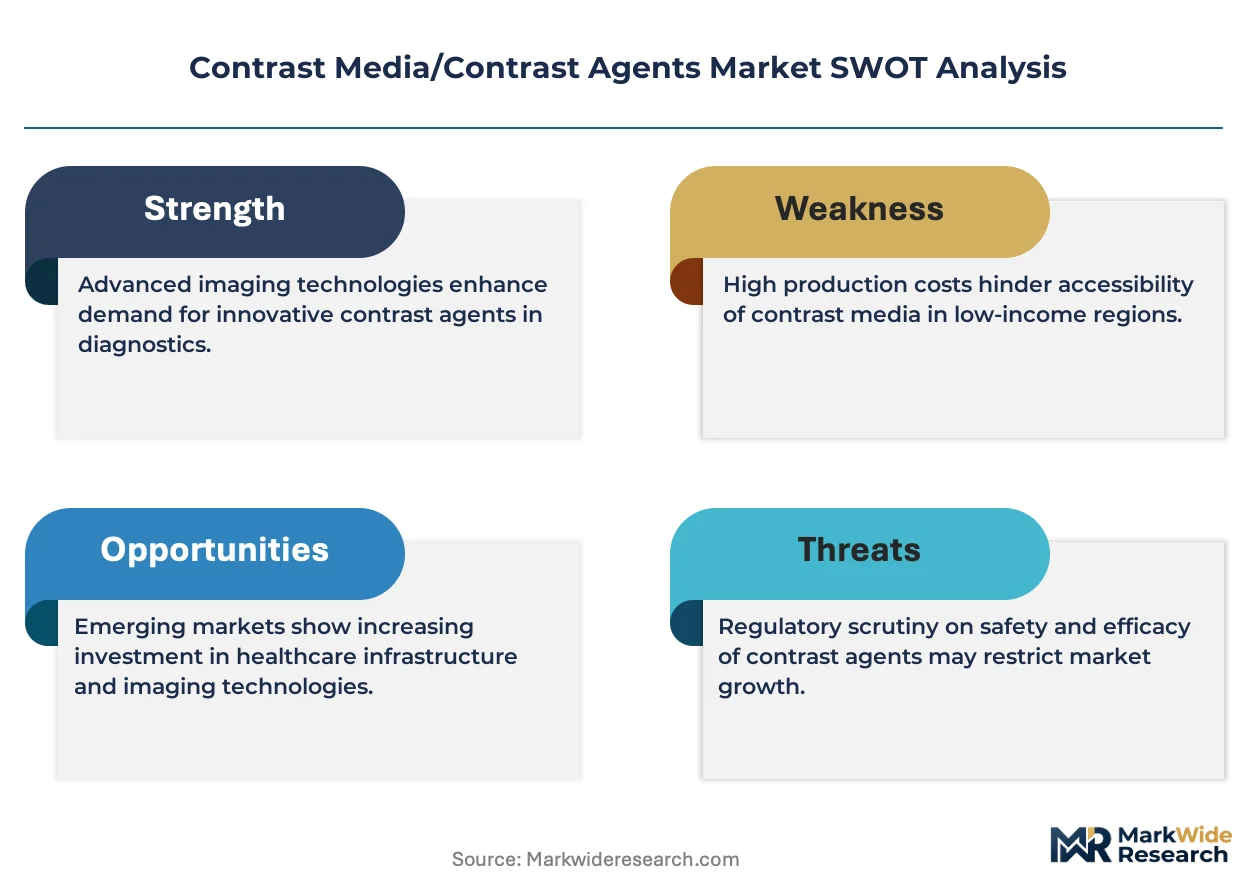
Market Restraints
- Stringent Regulatory Hurdles:Extensive and costly clinical trials mandated by the U.S. FDA, EMA, and China's NMPA for new agent approvals act as a significant barrier to market entry and slow innovation.
- Gadolinium Safety Concerns:Persistent concerns and regulatory scrutiny regarding gadolinium deposition in the brain and body from certain gadolinium-based contrast agents (GBCAs) restrain their use and invite substitution.
- Raw Material Concentration:The global supply of iodine, a critical raw material for the largest agent segment, is geographically concentrated, exposing manufacturers to significant price volatility and supply chain disruption risks.
Strategic Opportunities
- Theranostic Agent Development:Combining diagnostic contrast agents with therapeutic capabilities to create theranostic agents for targeted drug delivery and treatment monitoring represents a significant value-add opportunity in oncology.
- AI-Powered Dosing Solutions:Developing artificial intelligence algorithms that optimize contrast dose on a per-patient basis can improve diagnostic accuracy and safety, creating a new software-as-a-service revenue stream.
- Emerging Market Penetration:Expanding distribution and clinical education in underpenetrated regions like Latin America and Southeast Asia, where diagnostic imaging infrastructure is improving, offers substantial volume growth potential.
Industry Challenges
- Supply Chain Resilience:Manufacturers face the challenge of securing a stable, long-term supply of iodine and other key starting materials amidst geopolitical instability and increasing competition for limited resources.
- Interoperability with Imaging Systems:Ensuring new contrast agents and their associated injection systems are fully compatible and integrated with a diverse and aging installed base of imaging equipment from multiple vendors is a key operational hurdle.
- Post-Market Surveillance Demands:Managing and complying with increasingly rigorous post-market safety reporting and risk management plan requirements across different global regulatory jurisdictions is a complex and resource-intensive task.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contrast Media/Contrast Agents Market |
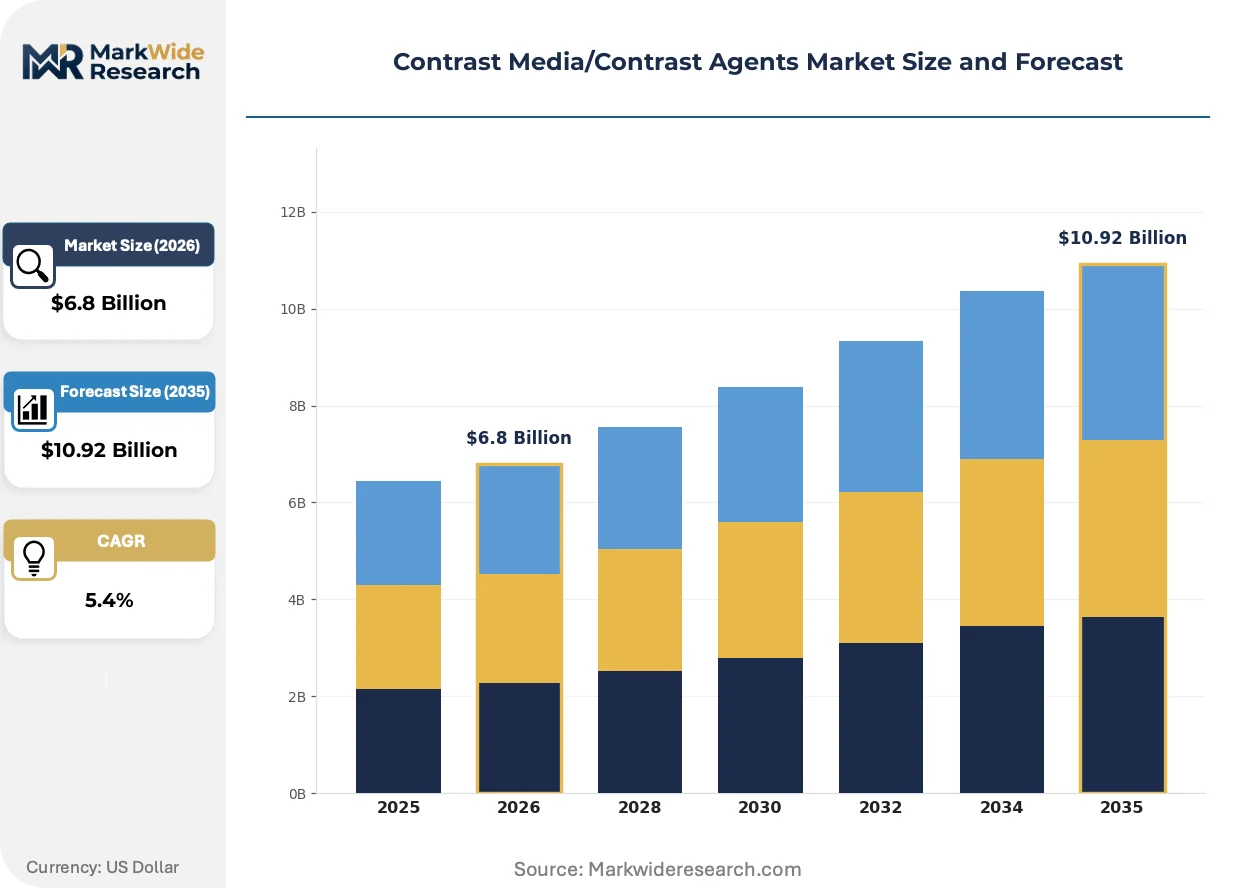
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Iodinated Agents, Gadolinium-Based Agents, Barium Sulfate, Microbubble Agents, Iron Oxide Nanoparticles Application: Computed Tomography, Magnetic Resonance Imaging, Ultrasound Imaging, X-ray, Fluoroscopy End User: Diagnostic Imaging Centers, Specialty Clinics, Outpatient Facilities, Research Institutions Technology: Non-Ionic, Ionic, Paramagnetic, Gas-Filled, Nanoparticle-Based |
| Companies Covered | Guerbet, Beijing Beilu Pharmaceutical Co., Ltd., Bayer AG, Daiichi Sankyo Company, Ltd., Fujifilm Holdings Corporation, GE HealthCare, Lantheus Medical Imaging, J.B. Chemicals & Pharmaceuticals Ltd., Bracco Imaging S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contrast Media/Contrast Agents Market Strategic Shifts & Innovations
A fundamental rebalancing is underway, as manufacturers navigate the dual pressures of funding R&D for clinically superior, safer agents while competing on price for commoditized products demanded by large healthcare purchasers. This dynamic influences technology development, regulatory strategy, and procurement models.
Macrocyclic gadolinium-based contrast agents (GBCAs) provide a more stable chemical structure that securely binds the gadolinium ion, reducing the risk of its release into the body. Specialized diagnostic centers, particularly in neurology and pediatrics, are leading the adoption of these premium agents. This trend is bifurcating the MRI contrast market into a high-stability segment for sensitive applications and a legacy segment where older agents are still used.
The European Medicines Agency's (EMA) stringent guidance on gadolinium-based agents represents a major regulatory inflection point. This policy has effectively mandated the phase-out of certain linear GBCAs in the EU due to concerns about gadolinium retention. The MRI contrast agent category is most affected, forcing a market-wide transition toward more stable macrocyclic or newer linear agents with demonstrated safety profiles.
Consolidated purchasing by large hospital networks and group purchasing organizations (GPOs) is altering procurement patterns. These powerful buyers are moving away from single-product transactions in favor of multi-year, multi-product contracts that bundle high-volume iodinated agents with specialty MRI or ultrasound agents. This shift, most prominent in the United States, favors large-portfolio suppliers and squeezes smaller, specialized manufacturers.
Contrast Media/Contrast Agents Market Segmentation
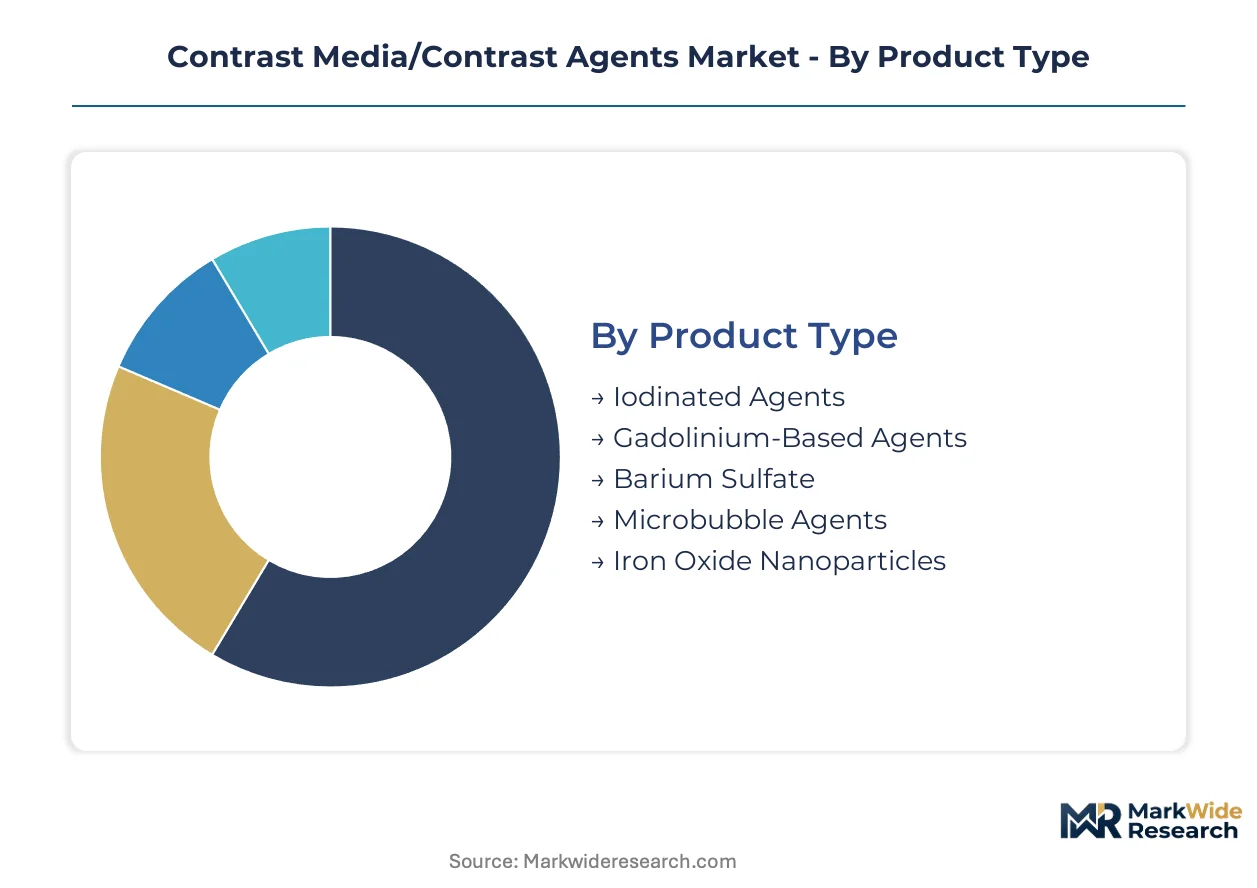
Segmentation within the contrast media market allows for a granular understanding of product utility and demand drivers across diverse clinical settings. This breakdown highlights the specific chemical properties, application areas, and end-user requirements that shape competitive dynamics and innovation pathways.
Product Type:
Regulatory bodies such as the U.S. FDA, European Medicines Agency (EMA), and China's NMPA significantly influence product type segmentation through safety mandates and approval processes.
- Iodinated Agents:These agents function by selectively attenuating X-rays, making them indispensable for computed tomography (CT) and X-ray procedures. Demand remains robust in China, driven by expanding healthcare infrastructure and a high volume of routine diagnostic imaging.
- Gadolinium-Based Agents:These agents alter proton relaxation times, providing critical contrast enhancement for magnetic resonance imaging (MRI). Regulatory scrutiny regarding gadolinium deposition, particularly from the EMA, has intensified the shift towards more stable macrocyclic formulations for sensitive neurological and pediatric applications.
- Barium Sulfate:This orally administered agent provides contrast for gastrointestinal imaging, primarily in fluoroscopy and X-ray studies. Its utility is confined to specific diagnostic questions of the digestive tract.
- Microbubble Agents:These gas-filled agents enhance ultrasound imaging, expanding diagnostic utility in areas like cardiology and oncology.
- Iron Oxide Nanoparticles:These agents are used in magnetic resonance imaging for specific diagnostic applications, including liver lesion detection.
Iodinated Agents handle the majority of throughput; Microbubble Agents are the fastest mover on share.
Application:
The volume and specific diagnostic requirements of imaging procedures dictate the demand across various application segments.
- Computed Tomography:This application utilizes iodinated contrast media to produce detailed cross-sectional images of internal organs and structures. High procedural volumes in diagnostic imaging centers drive consistent demand for cost-effective agents.
- Magnetic Resonance Imaging:This modality relies on gadolinium-based agents to provide superior soft tissue contrast for neurological, musculoskeletal, and oncological diagnostics. Specialized diagnostic questions often necessitate premium, high-stability agents.
- Ultrasound Imaging:Contrast-enhanced ultrasound (CEUS) utilizes microbubble agents to improve visualization of blood flow and tissue perfusion. This application is gaining traction in cardiology and liver imaging.
- X-ray:Conventional X-ray imaging, particularly with iodinated agents, remains fundamental for initial diagnostics and bone structure visualization. This is a high-volume application across diverse healthcare settings.
- Fluoroscopy:This application uses real-time X-ray imaging, often with barium sulfate or iodinated agents, for dynamic studies of organ function and interventional procedures.
High-volume modalities like Computed Tomography and X-ray drive broad demand, while specialized procedures in Magnetic Resonance Imaging command premium agents.
End User:
The operational model and patient throughput of end-user facilities shape their procurement needs and agent preferences.
- Diagnostic Imaging Centers:These specialized facilities focus on high-volume imaging procedures, prioritizing efficient workflow and cost-effective contrast agent solutions. Consolidated purchasing by large networks influences their procurement patterns.
- Specialty Clinics:Clinics focused on specific medical areas, such as cardiology or oncology, require tailored contrast agents for advanced diagnostics. These facilities often seek agents optimized for specific disease states.
- Outpatient Facilities:These facilities provide routine diagnostic imaging services, valuing convenience and patient comfort alongside agent efficacy. They contribute to the broad demand for standard contrast media.
- Research Institutions:These entities are involved in the development and clinical evaluation of novel contrast agents and imaging techniques. They utilize a diverse range of agents for preclinical and clinical trials.
Large Diagnostic Imaging Centers prioritize efficiency and cost, while Specialty Clinics and Research Institutions seek advanced, targeted solutions.
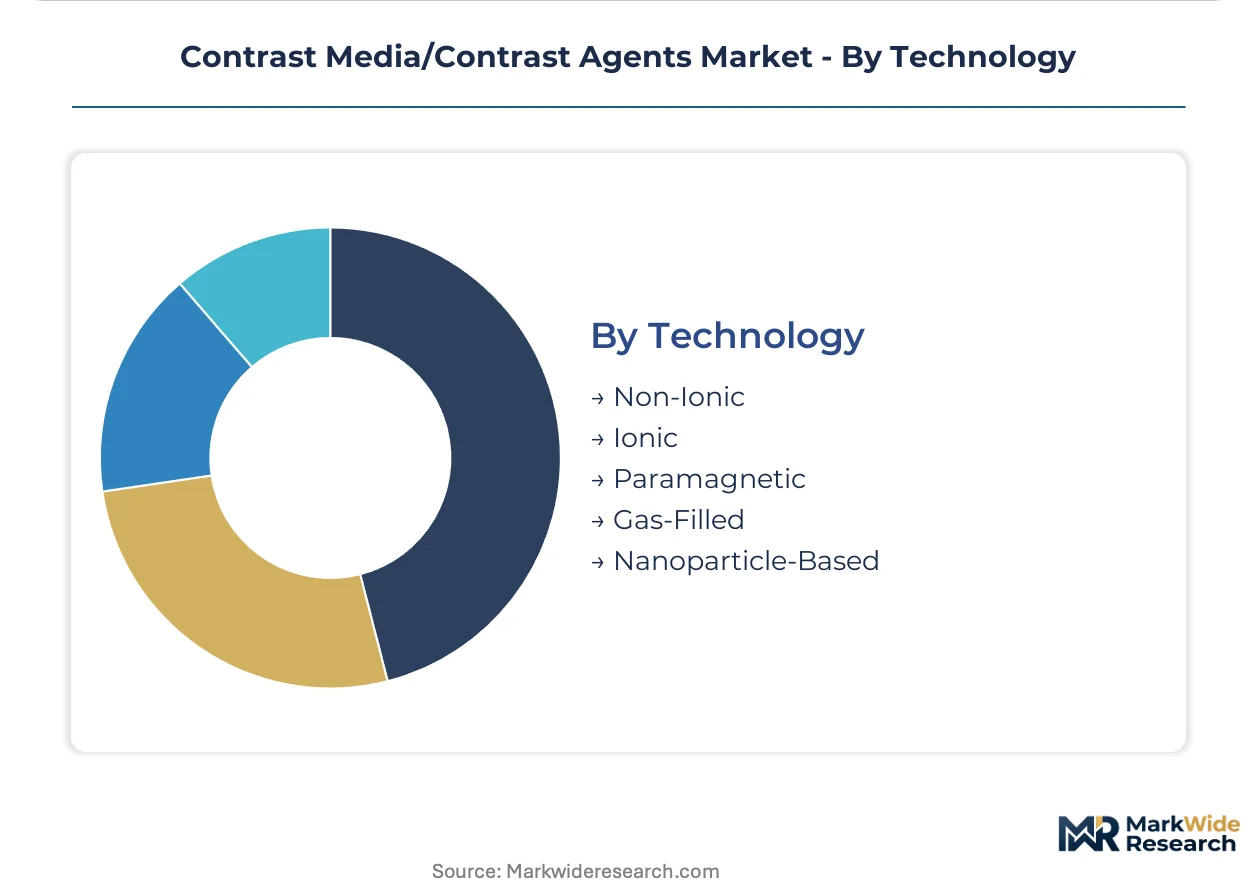
Technology:
The safety profile and technological maturity of contrast agents influence their market acceptance and regulatory status.
- Non-Ionic:These iodinated agents feature low osmolality, significantly reducing the incidence of adverse patient reactions compared to older formulations. The decisive shift towards non-ionic agents supports higher procedural volumes in diagnostic imaging centers.
- Ionic:These older generation iodinated agents have higher osmolality and are associated with a greater risk of adverse reactions. Their use is declining due to safety concerns and regulatory pressures.
- Paramagnetic:This technology underpins gadolinium-based contrast agents, which alter the magnetic properties of water protons to enhance MRI images. Macrocyclic agents within this category provide superior stability.
- Gas-Filled:This technology forms the basis of microbubble agents, which are engineered to resonate with ultrasound waves. These agents are expanding the diagnostic utility of ultrasound in various medical fields.
- Nanoparticle-Based:This advanced technology involves contrast agents designed at the nanoscale for targeted delivery and improved imaging characteristics. It offers potential for theranostic applications in oncology.
The shift towards Non-Ionic and Nanoparticle-Based technologies reflects a focus on safety and advanced functionality.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns for contrast media vary significantly across global geographies, reflecting diverse healthcare infrastructure and regulatory priorities. China's market is driven by high-volume iodinated agents for routine CT scans, whereas European nations prioritize safer macrocyclic gadolinium agents due to stringent regulatory oversight.
China
Expanding hospital infrastructure and increasing public health insurance coverage drive substantial demand for iodinated agents in China. The country's NMPA mandates extensive clinical trials for new agent approvals, shaping market access. Major pharmaceutical manufacturing hubs in Shanghai and Beijing are central to local production and distribution efforts.
United States
High procedural volumes in diagnostic imaging centers sustain consistent demand for both iodinated and gadolinium-based agents. The U.S. FDA enforces strict labeling requirements regarding potential risks, influencing product development. Biotech and medical imaging research clusters in Boston and the San Francisco Bay Area foster innovation in contrast media technologies.
Germany
Robust adoption of advanced macrocyclic gadolinium agents characterizes the German market, supported by a sophisticated healthcare system. European Medicines Agency (EMA) guidance on gadolinium retention has significantly impacted product availability and usage. Bavaria and North Rhine-Westphalia are key regions for medical technology and pharmaceutical companies.
Japan
Japan's aging demographic and emphasis on high-quality diagnostic imaging contribute to demand for advanced contrast agents. The PMDA oversees rigorous pharmaceutical and medical device approvals, ensuring patient safety. Medical research and advanced imaging equipment development are concentrated in major hubs like Tokyo and Osaka.
France
Demand for safer, low-osmolality non-ionic iodinated agents is growing across French diagnostic facilities. The Agence nationale de sécurité du médicament et des produits de santé (ANSM) regulates medical products, influencing market dynamics. Paris and Lyon are important centers for medical technology innovation and clinical research activities.
Contrast Media/Contrast Agents Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the contrast media market. This market structure favors large, diversified pharmaceutical companies and imaging equipment manufacturers. Key archetypes include global diversified healthcare conglomerates, pure-play contrast media specialists, and regional generic producers. Strategic partnerships and portfolio diversification are common competitive moves.
Global diversified healthcare conglomerates like GE HealthCare exemplify the strategy of leveraging an installed base of imaging equipment to drive agent sales. Bayer AG, a major pharmaceutical firm, sustains its strong position through an extensive portfolio spanning both CT and MRI contrast media. Bracco Imaging S.p.A. represents a specialist approach, focusing on a diversified range of diagnostic imaging solutions, including advanced ultrasound agents.
| Leading Market Players |
|---|
| Guerbet |
| Beijing Beilu Pharmaceutical Co., Ltd. |
| Bayer AG |
| Daiichi Sankyo Company, Ltd. |
| Fujifilm Holdings Corporation |
| GE HealthCare |
| Lantheus Medical Imaging |
| J.B. Chemicals & Pharmaceuticals Ltd. |
| Bracco Imaging S.p.A. |
| Others |
Cost & Logistics Intelligence
The decisive shift towards safer non-ionic iodinated agents and macrocyclic gadolinium agents is reshaping production costs and supply chain resilience. This substitution dynamic influences pricing power across different product segments and raw material sourcing.
Pricing Analysis
After-sales services for integrated injection systems drive lifetime value for imaging equipment manufacturers, influencing bundled contract pricing. The dominant pricing structure for contrast media is contract-based long-term offtake for high-volume iodinated agents. Price differentiation stems from product stability and regulatory approvals, such as those from the U.S. FDA and EMA. Pricing softness reflects consolidated purchasing power from large hospital networks, making diagnostic imaging centers highly price-sensitive, while specialty clinics prioritize performance.
Supply Chain Analysis
Just-in-time inventory strategies are common for high-volume, commoditized iodinated agents, while strategic stockpiling occurs for niche, high-value gadolinium-based contrast agents. Geographic supply concentration for iodine, a critical raw material, centers on Chile and Japan. Supply chain risk arises from commodity price volatility and geopolitical instability affecting raw material extraction. Distribution runs through pharmaceutical distributors and direct sales to large hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The contrast media market is witnessing a significant buyer-power shift, driven by the consolidated purchasing patterns of large hospital networks and Group Purchasing Organizations. This consolidation forces manufacturers to adapt their sales and product bundling strategies.
For Market Incumbents:Compound existing installed base advantages by bundling advanced macrocyclic gadolinium agents with high-volume iodinated generics. Invest in R&D for theranostic agents to counter the threat of substitute imaging modalities and enhance diagnostic utility. Secure long-term supply agreements for critical raw materials like iodine to mitigate geopolitical supply chain risks. Expand clinical education programs in emerging markets to reinforce brand loyalty.
For New Entrants and Emerging Players:Specialized AI-powered dosing solutions represent a service-layer gap where incumbents under-serve, offering a pathway for new entrants. Target underpenetrated regions like Latin America and Southeast Asia with cost-effective, high-quality non-ionic iodinated agents. Focus on developing advanced microbubble technologies for contrast-enhanced ultrasound, a segment with lower regulatory barriers compared to MRI agents. A go-to-market angle involves direct partnerships with smaller diagnostic centers.
For Investors and Strategic Acquirers:Capital is best deployed toward specialist contrast media manufacturers with strong R&D pipelines in theranostic or microbubble agents. These companies offer long-term viability by addressing unmet diagnostic needs and navigating stringent regulatory environments. Look for firms with robust intellectual property portfolios and established regulatory approvals from bodies like the U.S. FDA or EMA. A signal to watch is successful Phase III clinical trial completions for novel, safer agents.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates market entry for novel contrast agents with improved safety profiles. |
| Manufacturing Scale-Up | Secures cost advantages for high-volume iodinated agents in key markets like China. |
| Strategic Partnership | Expands distribution networks and co-develops advanced imaging solutions with equipment vendors. |
| Regulatory Approval Pathway | Ensures compliance and market access for new agents in stringent regions like the EU. |
| Pipeline Diversification | Mitigates risk by developing agents across MRI, CT, and ultrasound modalities. |
Research Approach
A standing panel of medical imaging specialists, hospital procurement managers, regulatory affairs leads, and pharmaceutical R&D directors provided ongoing calibration for primary research. This involved combining in-depth interviews with secondary validation from U.S. FDA filings, EMA submissions, and NMPA guidelines. The approach utilized both bottom-up and top-down triangulation, further informed by industry association reports.
Consistency checks validated volume and value outputs against external benchmarks and historical market trends across the analysis window. The analytical framework modeled segmentation dimensions including product type, application, end-user, and technology, alongside regional regulatory dynamics. Compound annual growth rates were derived from a multi-factor analysis, integrating procedural volume projections and agent adoption rates.
Underlying assumptions cover stable geopolitical conditions and consistent regulatory enforcement, with deviation risk concentrated in raw material supply disruptions. Forecasts reflect current market dynamics and anticipated technological advancements. Revision becomes warranted when major regulatory shifts or unforeseen clinical trial outcomes cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Global Magnetic Resonance Imaging System Market
Medical Imaging
Medical Imaging Displays Market
Medical Imaging
Global Automated Breast Ultrasound System (ABUS) Market
Medical Imaging
Asia Pacific Magnetic Resonance Imaging (MRI) Market
Medical Imaging
South Africa Mammography Market
Medical Imaging
Pre-Clinical Imaging System Market
Medical Imaging
China Mammography Market
Medical Imaging
Perfusion Radiology Market
Medical Imaging
Stationary Anode CT X-Ray Tube Market
Medical Imaging
Magnetic Resonance Imaging (MRI) Coils Market
Medical Imaging
Global 3D Laparoscopy Imaging Market
Medical Imaging
Asia-Pacific Intraoperative Imaging Market
Medical Imaging
China Nuclear Imaging Market
Medical Imaging
Europe Medical Imaging Market
Medical Imaging
X-Ray Flat Panel Detectors Market
Medical Imaging
South America Fluoroscopy Market