
 Diagnostic Imaging Market | 2026-2036
Diagnostic Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Diagnostic Imaging Market Intelligence
The traditional hospital-centric procurement model is collapsing as purchasing power shifts towards distributed diagnostic centers and ambulatory surgical centers. This trend benefits vendors with flexible, lower-footprint systems. Siemens Healthineers leverages its extensive portfolio to serve both large hospital networks and smaller clinics. GE Healthcare competes on service and software integration across its imaging modalities. Philips Healthcare differentiates through its focus on integrated solutions for specific clinical pathways like cardiology.
Diagnostic imaging encompasses technologies that create visual representations of the body's internal structures for clinical analysis. These systems, such as Magnetic Resonance Imaging (MRI) operating at field strengths of 1.5T to 3.0T, provide detailed anatomical and functional information to clinicians. Within the product landscape, Computed Tomography and Magnetic Resonance Imaging represent the largest value segments. The oncology application segment demands higher-performance imaging to improve early detection and treatment monitoring.
Regulatory frameworks from bodies like the US FDA, the European Union under its MDR, and China's NMPA impose stringent requirements on device safety and efficacy. These regulations dictate market access pathways and mandate rigorous quality management systems for all manufacturers. A key strategic decision for vendors will be balancing investment in next-generation hardware against the development of recurring revenue from software and AI-driven analytics platforms.
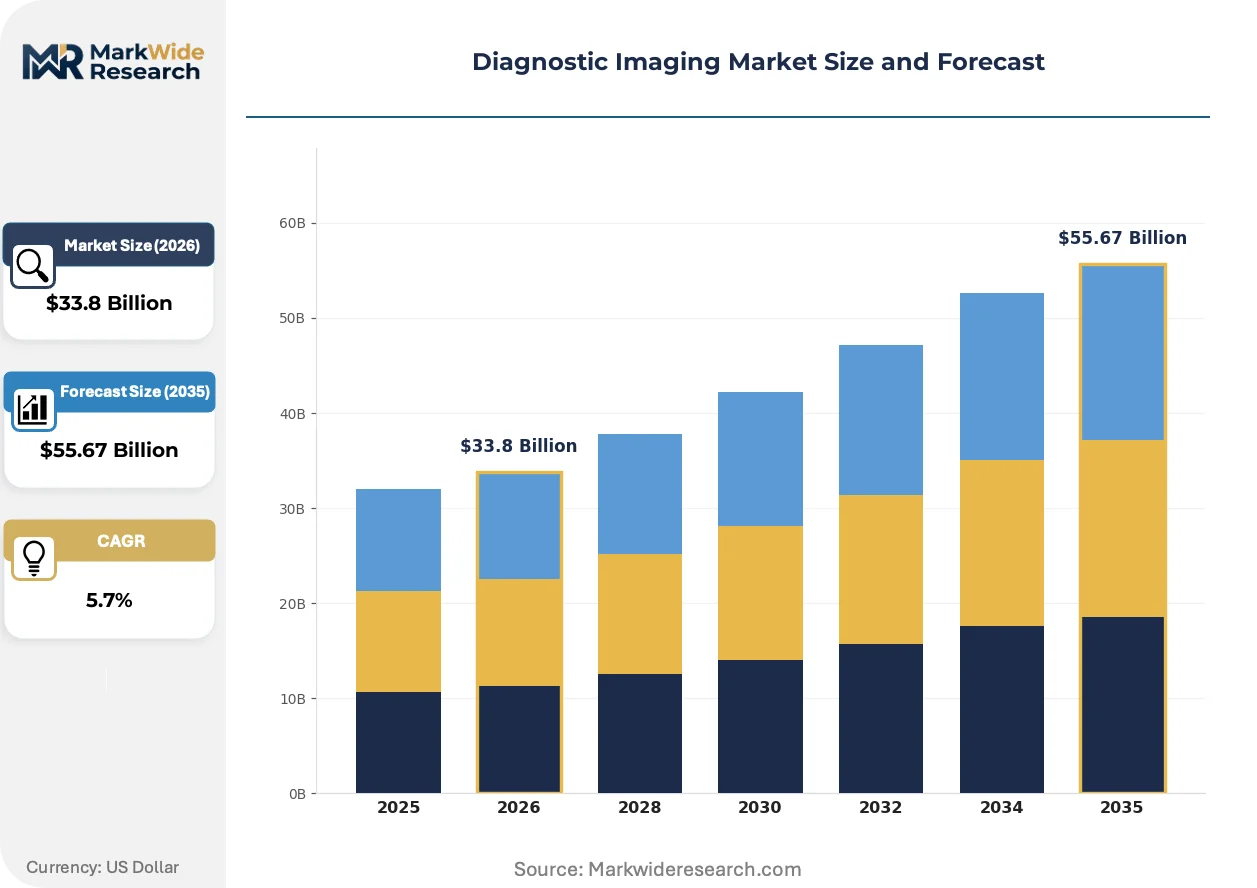
Market Dynamics
The central tension between capital investment in next-generation hardware and the development of recurring-revenue software platforms is defining the market's competitive positioning. This dynamic is forcing vendors to balance long-cycle product innovation with agile, data-driven service offerings.
Growth Catalysts
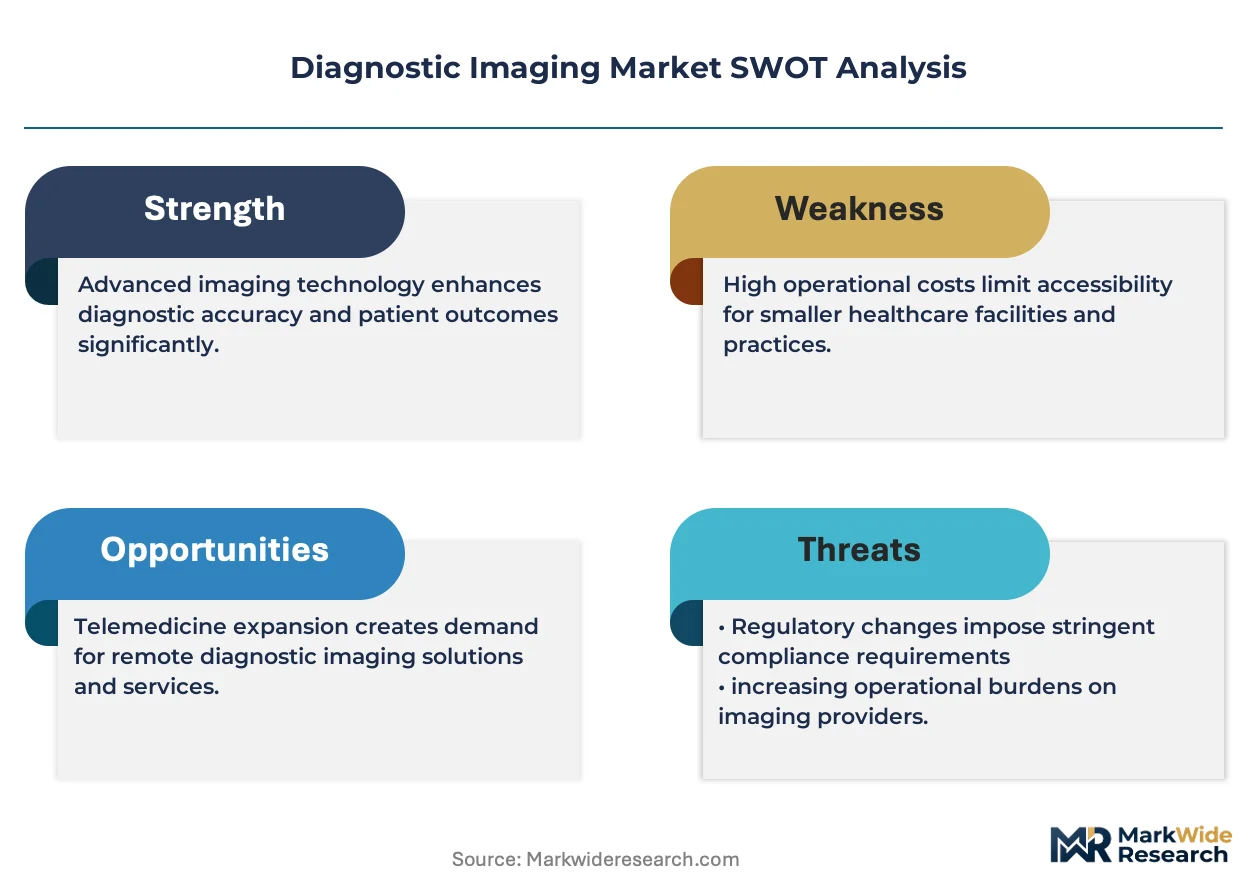
- AI Regulatory Frameworks:Guidance from bodies like the US FDA on Software as a Medical Device (SaMD) provides a clear pathway for the validation and commercialization of AI algorithms, stimulating innovation in automated image analysis.
- Demographic Shifts:Aging populations in developed economies, including Japan and Germany, are increasing the prevalence of chronic diseases like cancer and cardiovascular conditions, which require routine diagnostic imaging for management.
- Hybrid Modalities:The clinical adoption of hybrid imaging systems, such as PET/MRI and PET/CT, offers superior diagnostic accuracy in oncology and neurology, creating demand for these high-value systems in specialized centers.
Market Restraints
- High System Costs:The significant capital outlay required for high-field MRI and advanced CT systems, coupled with substantial installation and maintenance expenses, restricts procurement by smaller hospitals and clinics with limited budgets.
- Regulatory Hurdles:The European Union's stringent Medical Device Regulation (MDR) imposes extensive clinical evidence and documentation requirements, increasing the time and cost for manufacturers to achieve and maintain CE marking.
- Supply Chain Logistics:The production of certain imaging agents, particularly radioisotopes for PET scans, depends on a limited number of cyclotrons and has a short shelf-life, creating supply vulnerabilities and logistical challenges.
Strategic Opportunities
- Infrastructure Investment:Large-scale healthcare infrastructure projects in Gulf Cooperation Council countries, including Saudi Arabia and the UAE, create greenfield opportunities for vendors to equip new hospitals and diagnostic centers with advanced imaging technology.
- Emerging Clinical Applications:The expansion of quantitative imaging biomarkers for neurodegenerative diseases, such as Alzheimer's, provides an opportunity to develop specialized software and protocols beyond the core oncology segment.
- Workflow Automation Software:Integrating AI-powered analytics directly into Picture Archiving and Communication Systems (PACS) and radiology information systems (RIS) offers a significant opportunity for creating efficiency gains and reducing radiologist burnout.
Industry Challenges
- Specialized Talent Shortage:A persistent lack of qualified radiologists, medical physicists, and data scientists trained to operate advanced imaging modalities and interpret AI-assisted results creates an operational bottleneck for healthcare providers.
- Data Integration Complexity:Ensuring seamless interoperability between new imaging platforms and existing legacy hospital IT infrastructure, including electronic health records (EHRs), remains a significant technical and financial hurdle.
- Capital Budget Cycles:The high capital expenditure for imaging equipment means purchases are often subject to long and unpredictable hospital budget cycles, which can delay technology adoption and create demand volatility for vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diagnostic Imaging Market |
| Market Size in 2026 | $33.8 Billion |
| Market Size in 2035 | $55.67 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Computed Tomography, Magnetic Resonance Imaging, Ultrasound Imaging, X-Ray Imaging Application: Neurology, Cardiology, Orthopedics, Oncology End User: Hospitals, Diagnostic Centers, Research Institutes, Ambulatory Surgical Centers Technology: 3D Imaging, Digital Radiography, Nuclear Imaging, Molecular Imaging |
| Companies Covered | GE Healthcare, Siemens Healthineers, Philips Healthcare, FUJIFILM Corporation, Canon Medical Systems, Hologic, Inc., Mindray, Samsung Electronics Co., Ltd., Carestream Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diagnostic Imaging Market Strategic Shifts & Innovations
Software-centric business models are reshaping the value proposition in diagnostic imaging. The industry's focus is pivoting from hardware specifications alone to the clinical and operational outcomes enabled by integrated data analytics and workflow automation.
Point-of-care ultrasound (POCUS) technology delivers real-time diagnostic imaging in a compact, handheld form factor. Adoption is accelerating within emergency medicine and primary care settings for rapid, on-site patient evaluation. This development is fragmenting the traditional, centralized radiology department model by distributing imaging capabilities directly to clinicians at the bedside.
China's National Medical Products Administration (NMPA) is utilizing fast-track approval channels for innovative medical devices, specifically targeting AI-powered diagnostic software. This regulatory incentive has shortened market-entry timelines for vendors with validated algorithms. The oncology and neurology software segments are responding most rapidly, prioritizing NMPA submissions to gain access to the vast domestic market.
A clear shift towards enterprise-wide procurement strategies is replacing departmental, transactional purchasing for imaging equipment. This change elevates the importance of system interoperability and total cost of ownership over single-modality performance specifications. The trend is most visible in large integrated delivery networks across the United States, where IT and finance executives now lead purchasing decisions.
Diagnostic Imaging Market Segmentation
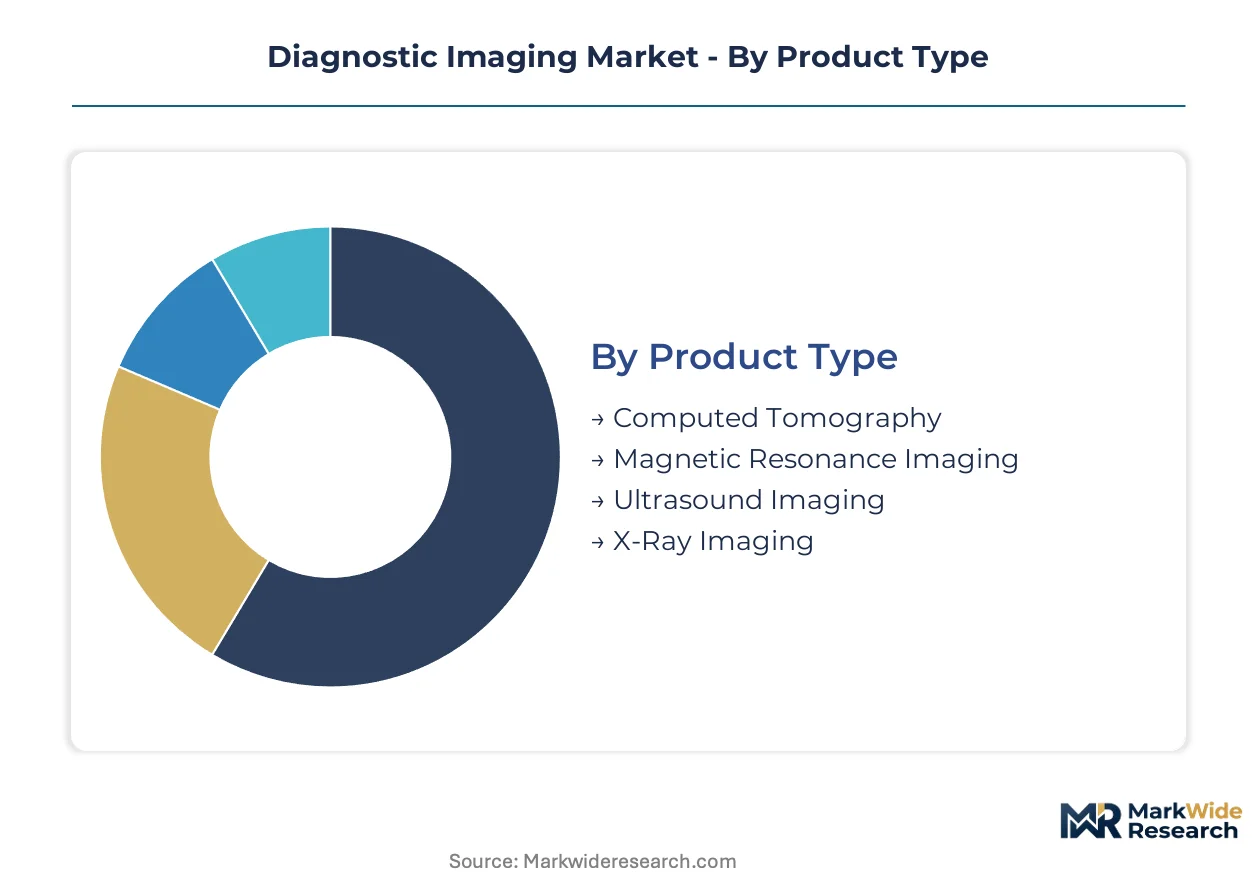
Understanding the Diagnostic Imaging Market through its constituent segments reveals the nuanced shifts in technology adoption and procurement models. Market segmentation provides critical insights into where investment flows, which applications drive demand, and how end-user preferences are evolving across different healthcare settings.
Product Type:
The product type segmentation highlights areas where newer, more advanced modalities face substitution pressure from established, lower-cost alternatives, or where they complement existing systems for enhanced diagnostic accuracy.
- Computed Tomography:These systems utilize X-rays and computer processing to create cross-sectional images of the body. Demand concentrates in large hospital networks in countries like China, driven by high-volume emergency and trauma diagnostics.
- Magnetic Resonance Imaging:MRI employs strong magnetic fields and radio waves to generate detailed images of organs and soft tissues. Adoption is expanding in specialized neurology and oncology centers in Germany, focusing on precise disease staging.
- Ultrasound Imaging:This technology uses high-frequency sound waves to visualize internal body structures in real-time. Clinicians in primary care settings and emergency departments in the United States increasingly use handheld devices.
- X-Ray Imaging:X-ray systems produce images by passing electromagnetic radiation through the body. This fundamental imaging modality maintains a strong presence in general diagnostics and orthopedic applications globally.
X-Ray Imaging anchors the volume base while Magnetic Resonance Imaging gains share at the steepest rate.
Application:
Segmentation by application reveals how specific clinical needs dictate the performance characteristics and software integration requirements for diagnostic imaging systems. Each application demands tailored solutions for optimal patient outcomes.
- Oncology:This segment requires high-performance imaging for early cancer detection, staging, and treatment monitoring. Demand for advanced hybrid modalities like PET/CT is particularly strong in cancer treatment centers across the United States.
- Neurology:Imaging in neurology focuses on brain and spinal cord disorders, necessitating high-resolution and functional imaging capabilities. Research institutes in Japan are increasingly adopting advanced MRI for neurodegenerative disease biomarkers.
- Cardiology:Cardiac imaging assesses heart structure and function for diagnosing cardiovascular diseases. Echocardiography and cardiac MRI are essential tools in specialized heart clinics.
- Orthopedics:This application primarily uses X-ray and MRI for diagnosing musculoskeletal injuries and conditions. Sports medicine clinics in Australia rely on these modalities for accurate diagnosis.
Oncology applications exhibit the steepest expansion trajectory, driven by increasing disease prevalence.
End User:
The end-user segmentation highlights shifting procurement patterns and varying infrastructure needs across different healthcare providers. Each customer type has distinct purchasing power and operational requirements.
- Hospitals:These traditional healthcare facilities represent a significant portion of imaging equipment procurement, often requiring a full suite of modalities. Large public hospitals in the United Kingdom prioritize enterprise-wide procurement strategies for efficiency.
- Diagnostic Centers:Independent diagnostic centers are gaining purchasing power, favoring flexible, lower-footprint systems and advanced AI-powered analytics. These centers in India focus on high patient throughput for common imaging procedures.
- Research Institutes:These organizations primarily utilize advanced imaging for clinical trials and scientific discovery. University medical centers in Canada invest in cutting-edge molecular imaging technologies.
- Ambulatory Surgical Centers:ASCs require imaging solutions for pre-operative assessments and intra-operative guidance. These centers in the United States adopt compact and efficient imaging systems.
Diagnostic Centers represent the fastest growing customer segment, reflecting a shift in healthcare delivery models.
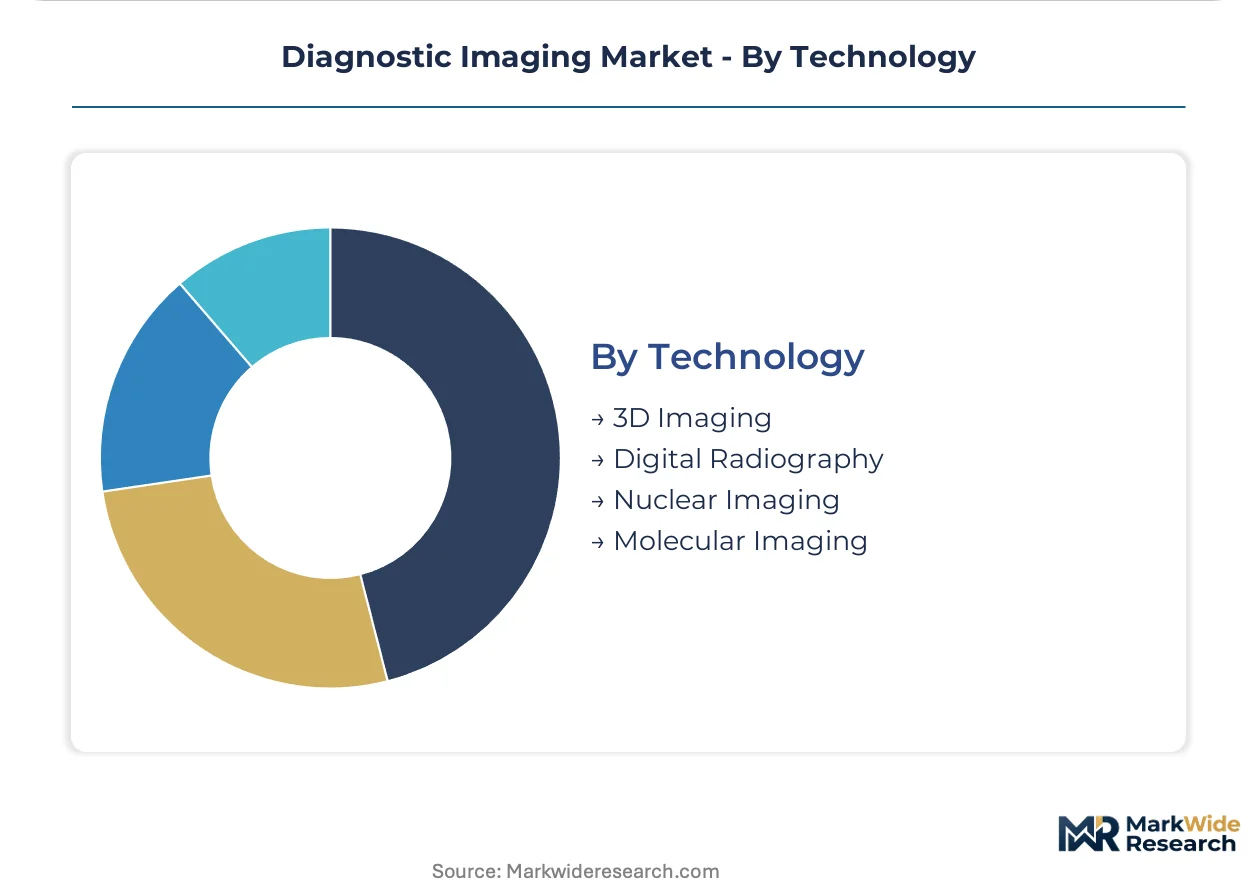
Technology:
The technology segment delineates the market based on the underlying imaging principles and their stage of development. Innovation cycles drive the introduction of new capabilities and improved diagnostic accuracy.
- Digital Radiography:This technology converts X-ray images into digital data, enabling faster acquisition and enhanced image manipulation. Hospitals in Brazil are upgrading from analog to digital systems for improved workflow.
- Molecular Imaging:This advanced technique visualizes biological processes at the cellular and molecular level, often using radiotracers. Specialized clinics in France utilize PET scans for early disease detection and therapy response monitoring.
- 3D Imaging:This technology creates three-dimensional representations from multiple 2D images. Surgeons in South Korea employ 3D imaging for complex surgical planning and navigation.
- Nuclear Imaging:Nuclear medicine techniques use small amounts of radioactive material to diagnose and treat diseases. These procedures are common in oncology and cardiology departments.
Molecular Imaging is climbing fastest in terms of adoption, driven by its precision in disease characterization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The export of high-field MRI systems from Germany to specialized neurology centers in Japan underscores the global nature of diagnostic imaging technology flows. Demand for advanced imaging is concentrating in countries making substantial healthcare infrastructure investments, reflecting varying clinical needs and regulatory environments. These regional dynamics shape procurement patterns and technology adoption across diverse healthcare systems.
United States
Demand for advanced diagnostic imaging systems in the United States stems from the prevalence of chronic diseases and the expansion of oncology applications. The US FDA's guidance on Software as a Medical Device (SaMD) provides clear pathways for AI-powered diagnostic algorithms. Large integrated delivery networks across major metropolitan areas like New York and Los Angeles drive enterprise-wide procurement strategies.
China
China's market for diagnostic imaging is characterized by significant demand for Computed Tomography systems within its extensive hospital networks. The National Medical Products Administration (NMPA) utilizes fast-track approval channels for innovative medical devices, particularly AI-powered diagnostic software. Major medical technology hubs in the Yangtze River Delta region are prioritizing domestic manufacturing and R&D for imaging equipment.
Germany
Germany exhibits strong demand for Magnetic Resonance Imaging in specialized neurology and oncology centers, driven by an aging population. The European Union's Medical Device Regulation (MDR) imposes stringent requirements on device safety and efficacy, influencing market access. Bavaria's medical technology cluster, centered around Erlangen and Munich, fosters innovation in high-resolution imaging systems.
Japan
Aging populations in Japan are increasing the need for routine diagnostic imaging for chronic disease management, particularly cardiovascular and neurodegenerative conditions. The Ministry of Economy, Trade and Industry (METI) supports the development of advanced medical equipment through various initiatives. Research institutes in Tokyo and Kyoto are leading the adoption of advanced MRI for neurodegenerative disease biomarkers.
Saudi Arabia
Saudi Arabia's market is expanding due to large-scale healthcare infrastructure projects, creating greenfield opportunities for advanced imaging technology. The Ministry of Health (MOH) is implementing ambitious healthcare transformation plans, including digital health initiatives. Major medical cities like King Fahad Medical City in Riyadh are equipping new facilities with state-of-the-art diagnostic imaging suites.
Diagnostic Imaging Market Key Industry Players
Listed leaders compete with private specialists across hardware innovation and software integration within the diagnostic imaging market. This market exhibits a tiered structure, with established multinational corporations dominating high-end modalities. Strategic archetypes include integrated solution providers, specialized technology innovators, and regional value-focused players. Dominant competitive moves involve portfolio diversification into AI-driven analytics and strategic partnerships for workflow automation.
Integrated solution providers such as GE Healthcare, Siemens Healthineers, and Philips Healthcare exemplify this market's focus on comprehensive offerings. These multinational corporations anchor the premium segment, leveraging extensive R&D capabilities and global distribution networks. Their strategies emphasize service and software integration, alongside hardware advancements, to serve diverse healthcare settings.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Philips Healthcare |
| FUJIFILM Corporation |
| Canon Medical Systems |
| Hologic, Inc. |
| Mindray |
| Samsung Electronics Co., Ltd. |
| Carestream Health |
| Others |
Cost & Logistics Intelligence
Long-term service-level agreements (SLAs) for diagnostic imaging systems often lock in both hardware procurement and software subscription pricing, ensuring predictable revenue streams for vendors. These agreements provide healthcare providers with cost visibility and guaranteed uptime for critical equipment.
Pricing Analysis
The technology-generation pricing gap differentiates established 1.5T MRI systems from cutting-edge 3.0T or hybrid modalities, reflecting varying R&D investments and clinical capabilities. Pricing stratifies across premium, standard, and economy tiers, driven by software integration depth and after-sales service contracts. Pricing softness stems from increasing purchasing power among distributed diagnostic centers, which prioritize cost-effectiveness. Large university medical centers and specialized research institutes exhibit lower price sensitivity for advanced molecular imaging systems, valuing precision and research capabilities.
Supply Chain Analysis
Limited cyclotron availability for radioisotope production in Europe and North America creates a critical chokepoint for PET imaging agents, impacting supply stability. Manufacturing of advanced diagnostic imaging systems concentrates in Germany, China, and the United States, drawing from specialized magnets and high-performance detector components. Single-source vulnerability for these complex sub-components represents a significant structural risk. Distribution runs through direct sales forces and established regional service networks, supporting installation and ongoing maintenance for healthcare providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The diagnostic imaging market is experiencing a cyclical recovery, driven by renewed healthcare infrastructure investments across key geographies. This upswing presents strategic opportunities for market participants to re-evaluate their competitive positions.
For Market Incumbents:Secure long-term service contracts with large integrated delivery networks by bundling AI-driven analytics and workflow automation software, mitigating the threat from specialized software innovators. Deepen vertical integration of critical component supply chains to reduce exposure to geopolitical risks and ensure product availability. Invest heavily in R&D for next-generation hardware that integrates seamlessly with existing hospital IT infrastructure, maintaining a technological edge.
For New Entrants and Emerging Players:Anchor in workflow automation software for radiology departments, targeting the efficiency gains demanded by diagnostic centers in India. Develop compact, AI-enabled point-of-care ultrasound (POCUS) devices, offering a cost-effective solution for primary care settings in the United States. Leverage SaaS subscription models for image analysis algorithms, lowering capital expenditure barriers for smaller clinics and accelerating market entry.
For Investors and Strategic Acquirers:Capital is best deployed toward software-centric AI developers specializing in image analysis and workflow optimization, reflecting the long-term shift towards data-driven diagnostics. Prioritize acquisition targets with strong intellectual property in hybrid imaging modalities or advanced detector technology. A critical signal to watch is the increasing pace of US FDA and NMPA fast-track approvals for AI-powered diagnostic software, indicating accelerating market validation and commercial viability.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Algorithm Development | Enhances diagnostic accuracy and operational efficiency across various clinical applications for healthcare providers. |
| Hybrid Modality Investment | Addresses the growing demand for superior diagnostic precision in oncology and neurology segments. |
| SaaS Model Expansion | Generates predictable recurring revenue streams and lowers capital expenditure for end-users. |
| Regulatory Pathway Navigation | Accelerates market access for innovative medical devices, particularly AI-powered diagnostic software, in key regions. |
| Workflow Integration Solutions | Reduces radiologist burnout and improves patient throughput by streamlining imaging processes within hospitals. |
Research Approach
Desk research of academic journals, industry reports, and regulatory filings preceded structured interviews with radiologists, hospital procurement managers, medical physicists, and R&D directors. This approach combined primary insights from industry stakeholders with secondary validation from US FDA filings, EU MDR documentation, and NMPA approval databases. Bottom-up data aggregation and top-down market sizing ensured comprehensive triangulation of findings for the diagnostic imaging sector.
Variance decomposition isolated the impact of individual market drivers on overall growth, informing the forecast framework across the analysis window. The analytical framework modeled segmentation dimensions including product type, application, end-user, technology, and geographic region. Compound Annual Growth Rates were derived from historical growth trends and projected healthcare expenditure growth. Chronic disease prevalence, particularly in oncology and neurology, served as a key forecast input.
Material uncertainties — including geopolitical instability and major technological breakthroughs — sit outside the modeled envelope, influencing long-term market trajectories. Forecasts reflect assumptions regarding regulatory stability and healthcare investment patterns. Practitioners should keep alternative scenarios live as supply chain disruptions and shifts in regulatory enforcement evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
France Magnetic Resonance Imaging Market
Medical Imaging
Global Artificial Intelligence in MRI Market
Medical Imaging
Republic of Ireland (ROI) and Northern Ireland MRI and CT Scan Radiology Services Market
Medical Imaging
Digital Radiography Detectors Market
Medical Imaging
Mexico Mammography Market
Medical Imaging
Hand-Held X-Rays Market
Medical Imaging
Diagnostic Imaging Markers Market
Medical Imaging
Fluoroscopy C-Arms Market
Medical Imaging
New Born Eye Imaging Systems Market
Medical Imaging
South Africa Magnetic Resonance Imaging Market
Medical Imaging
Global Surgical Imaging Arms Market
Medical Imaging
Global Single-Photon Emission Computed Tomography (SPECT) Market
Medical Imaging
Global Mammography Systems Market
Medical Imaging
South Korea Computed Tomography Market
Medical Imaging
Artificial Intelligence in Medical Imaging Market
Medical Imaging
Next Generation Ultrasound Systems Market