
 Brazil Digital X-Ray Market | 2026-2036
Brazil Digital X-Ray Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Digital X-Ray Market Outlook
Flat-panel detector technology is rewriting radiology infrastructure economics across Brazilian healthcare networks. Siemens Healthineers leverages its established service footprint to sustain long-term contracts with large hospital consortia in the Southeast. GE Healthcare anchors its position through localized technical support and financing arrangements tailored to public procurement cycles. Fujifilm Holdings Corporation differentiates by competing aggressively in the portable digital X-ray segment, where emergency care and mobile screening applications are expanding fastest.
Brazil digital X-ray systems employ solid-state detectors—amorphous selenium or cesium iodide scintillator arrays—to convert X-ray photons directly into digital signals, eliminating chemical processing and enabling immediate image transmission to PACS networks for diagnostic review. Direct radiography systems now dominate new installations in tertiary hospitals due to superior dose efficiency and throughput, while portable X-ray systems represent the fastest-expanding product category as outpatient clinics and emergency departments prioritize point-of-care imaging capability. The dental imaging application segment maintains distinct procurement dynamics, with smaller practice sizes driving demand for compact, lower-capital units compared to the high-throughput systems required in orthopedic and cardiovascular departments.
ANVISA governs medical device registration and post-market surveillance, requiring substantial equivalence demonstrations or local clinical data for digital radiography systems seeking commercialization in Brazil. The Brazilian Ministry of Health's diagnostic imaging qualification programs shape demand through centralized purchasing for the Unified Health System, while INMETRO certification requirements for electromagnetic compatibility and radiation safety filter which international manufacturers can participate in public tenders. Stakeholders must monitor how ANVISA's alignment with international harmonization initiatives affects registration timelines and whether federal budget allocations for equipment modernization sustain current procurement momentum through political transitions.
Market Dynamics
Flat-panel detector technology is compressing equipment replacement cycles across Brazilian public hospital networks, forcing procurement departments to accelerate capital planning timelines.
Growth Catalysts
- ANVISA harmonization initiatives:Streamlined registration pathways for imported digital imaging systems reduce approval bottlenecks for multinational manufacturers.
- Southeast diagnostic imaging chains:Consolidation among São Paulo and Minas Gerais radiology networks drives bulk procurement of high-throughput DR systems.
- Mobile screening applications:Emergency departments and outpatient clinics expand portable X-ray deployment for point-of-care triage.
Market Restraints
- Import dependency:Flat-panel detectors and solid-state sensor arrays concentrate supply among East Asian component manufacturers.
- INMETRO certification friction:Electromagnetic compatibility and radiation safety testing requirements delay market entry for smaller international suppliers.
- Capital intensity:Public sector procurement cycles tied to federal budget allocations create demand volatility across election periods.
Strategic Opportunities
- North and Northeast underpenetration:Lower installed base density in Amazonas and Ceará states offers first-mover positioning for mobile screening units.
- Tele-radiology convergence:Integration of cloud-based PACS networks with portable digital X-ray systems enables remote diagnostic workflows.
- SUS equipment modernization mandates:Ministry of Health diagnostic imaging qualification programs channel federal resources toward digital replacement of analog infrastructure.
Industry Challenges
- Biomedical engineering talent scarcity:Specialized technicians for solid-state detector calibration and PACS integration remain concentrated in São Paulo and Rio de Janeiro metropolitan corridors.
- Legacy analog integration:Hybrid workflows combining new digital systems with existing film-based archives create operational friction in mid-sized municipal hospitals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Digital X-Ray Market |
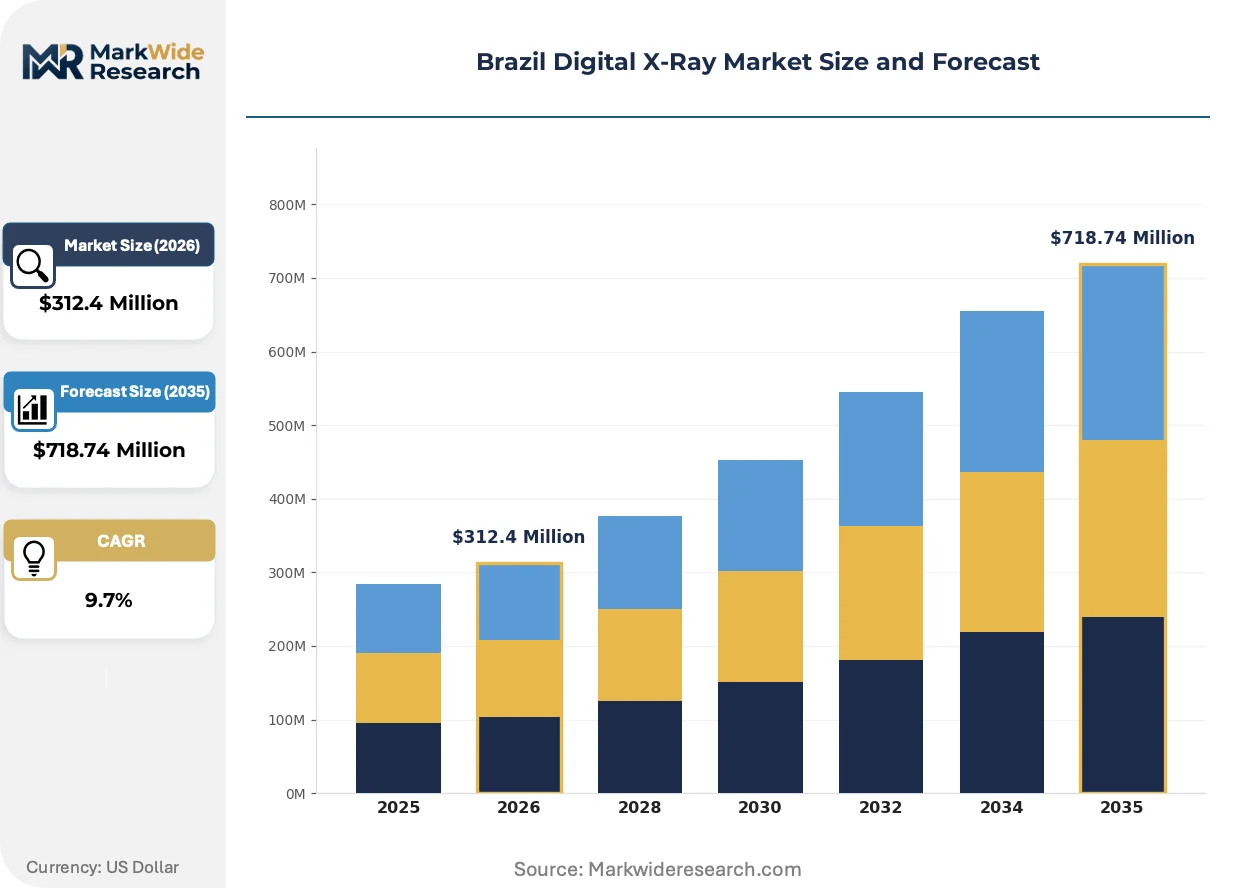
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $718.74 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Computed Radiography, Direct Radiography, Hybrid Systems, Portable X-Ray Systems End User: Hospitals, Diagnostic Imaging Centers, Outpatient Clinics, Research Institutions Technology: X-Ray Imaging, Fluoroscopy, 3D Imaging, Mobile Imaging Application: Orthopedics, Dental Imaging, Cardiovascular, Emergency Care |
| Companies Covered | Canon Medical Systems Corporation, Siemens Healthineers, GE Healthcare, Agfa HealthCare, Carestream Health, Fujifilm Holdings Corporation, Shimadzu Corporation, Konica Minolta Healthcare, Koninklijke Philips NV, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Digital X-Ray Market Strategic Shifts
Detector architecture evolution and regulatory pathway compression are restructuring how Brazilian healthcare networks acquire and deploy radiography infrastructure. Three forces merit particular attention.
Wireless cassette-based flat-panel technology is hybridizing conventional radiography workflows across Brazilian emergency departments. These battery-powered detectors eliminate tethered connections to generator consoles, permitting bedside imaging in intensive care units. Hospital networks in São Paulo are hybridizing their equipment fleets faster than originally planned, compressing traditional seven-year replacement cycles toward five-year horizons.
ANVISA's alignment with International Medical Device Regulators Forum standards is reducing documentation burdens for established manufacturers. The regulator now accepts substantial equivalence demonstrations based on foreign regulatory approvals, cutting registration timelines for Class III imaging equipment. Smaller European and Asian manufacturers are responding by prioritizing Brazil as their first Latin American market entry.
Diagnostic imaging center chains are unbundling equipment procurement from service contracts, creating standalone maintenance markets. Independent service organizations now compete with original manufacturers for multi-vendor fleet management contracts. This disintermediation is most visible in Minas Gerais, where consolidated radiology groups operate mixed-vendor installations exceeding fifty units per network.
Brazil Digital X-Ray Market Segmentation
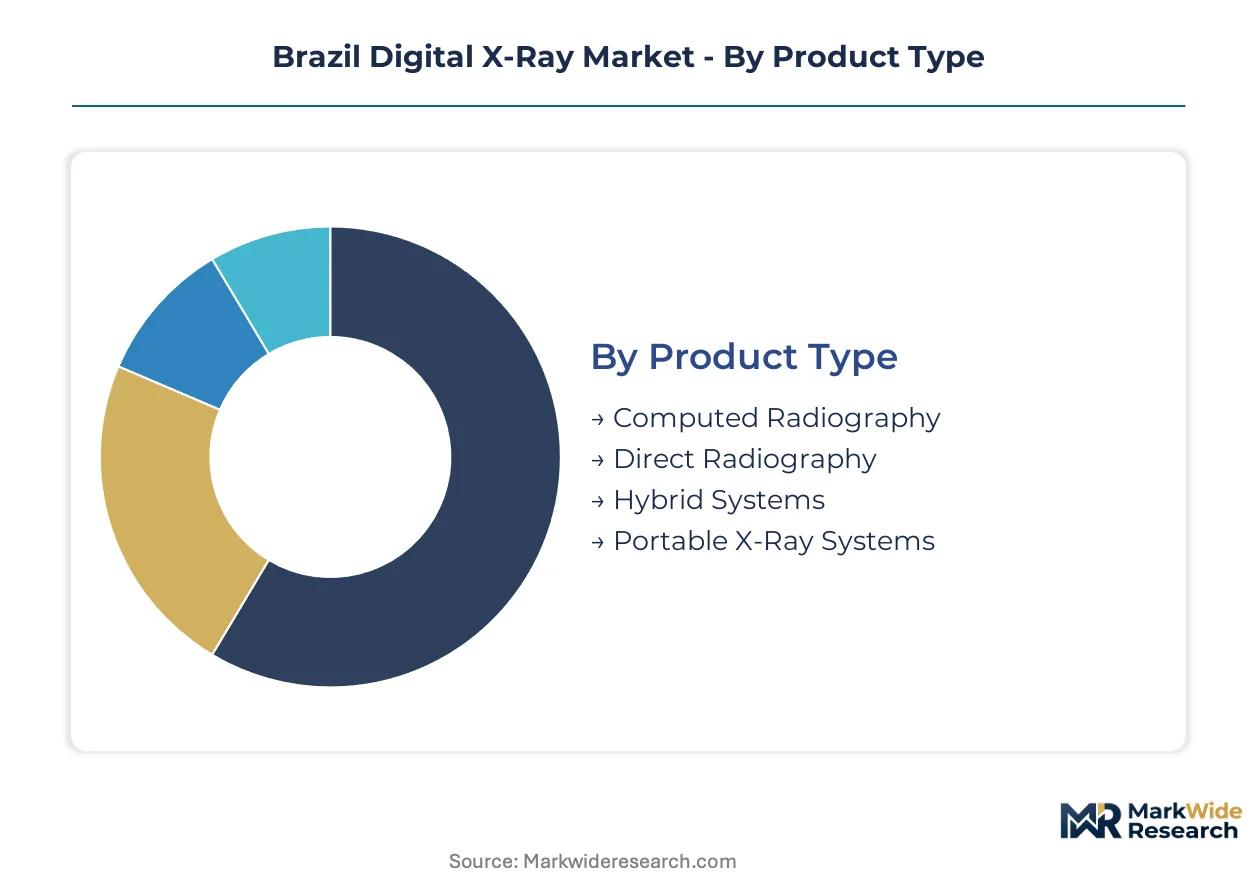
Equipment replacement cycles and procurement patterns vary sharply across digital radiography segments in Brazil. Understanding these structural differences clarifies where capital deployment concentrates and which technologies face compressed upgrade timelines.
Product Type:
Replacement velocity diverges dramatically—portable systems turn over fastest as battery and wireless technology evolves, while fixed-room installations persist longer due to infrastructure lock-in.
- Computed Radiography:Cassette-based systems using photostimulable phosphor plates to capture latent images for laser scanning and digitization. Municipal hospitals in Minas Gerais retain CR infrastructure as bridge technology during phased analog-to-digital transitions, constrained by generator compatibility and room retrofit costs.
- Direct Radiography:Solid-state flat-panel detectors converting X-ray photons immediately into digital signals without intermediate processing. Tertiary hospitals in São Paulo prioritize DR for high-throughput departments where dose reduction and PACS integration justify premium capital outlays.
- Hybrid Systems:Configurations supporting both CR cassettes and DR panels on shared generator infrastructure.
- Portable X-Ray Systems:Battery-powered mobile units with wireless detector communication for bedside and emergency deployment.
Direct Radiography dominates installed base. Portable X-Ray Systems is where expansion concentrates.
End User:
Procurement sophistication and financing access create tiered demand patterns across Brazilian healthcare institutions.
- Hospitals:Large-scale integrated networks with centralized purchasing through SUS qualification programs. Public hospital consortia in São Paulo and Rio de Janeiro drive volume procurement of high-capacity systems, though federal budget cycles introduce demand volatility.
- Diagnostic Imaging Centers:Private radiology chains consolidating in the Southeast region. These operators pursue multi-vendor fleet standardization to negotiate service contract unbundling and reduce per-study operational costs.
- Outpatient Clinics:Smaller-capital settings emphasizing point-of-care efficiency over throughput.
- Research Institutions:Specialized academic medical centers with protocol-driven imaging requirements.
Hospitals anchor volume procurement. Diagnostic Imaging Centers is gaining share fastest.
Technology:
Capability boundaries blur as detector platforms support multiple imaging modalities through software configuration.
- X-Ray Imaging:Conventional static radiography for skeletal and thoracic assessment.
- Fluoroscopy:Real-time moving image acquisition for interventional guidance and contrast studies.
- 3D Imaging:Tomosynthesis and cone-beam computed tomography for volumetric reconstruction.
- Mobile Imaging:Wireless detector platforms enabling untethered operation across care environments.
X-Ray Imaging dominates installed base. Mobile Imaging is climbing the fastest.
Application:
Clinical workflow requirements and reimbursement structures shape distinct equipment specifications across specialties.
- Orthopedics:Weight-bearing and trauma imaging demanding high-resolution bone detail.
- Dental Imaging:Compact intraoral and panoramic systems for private practice settings.
- Cardiovascular:Angiography and catheterization laboratory integration requiring rapid frame rates.
- Emergency Care:Triage-optimized protocols prioritizing speed over diagnostic depth.
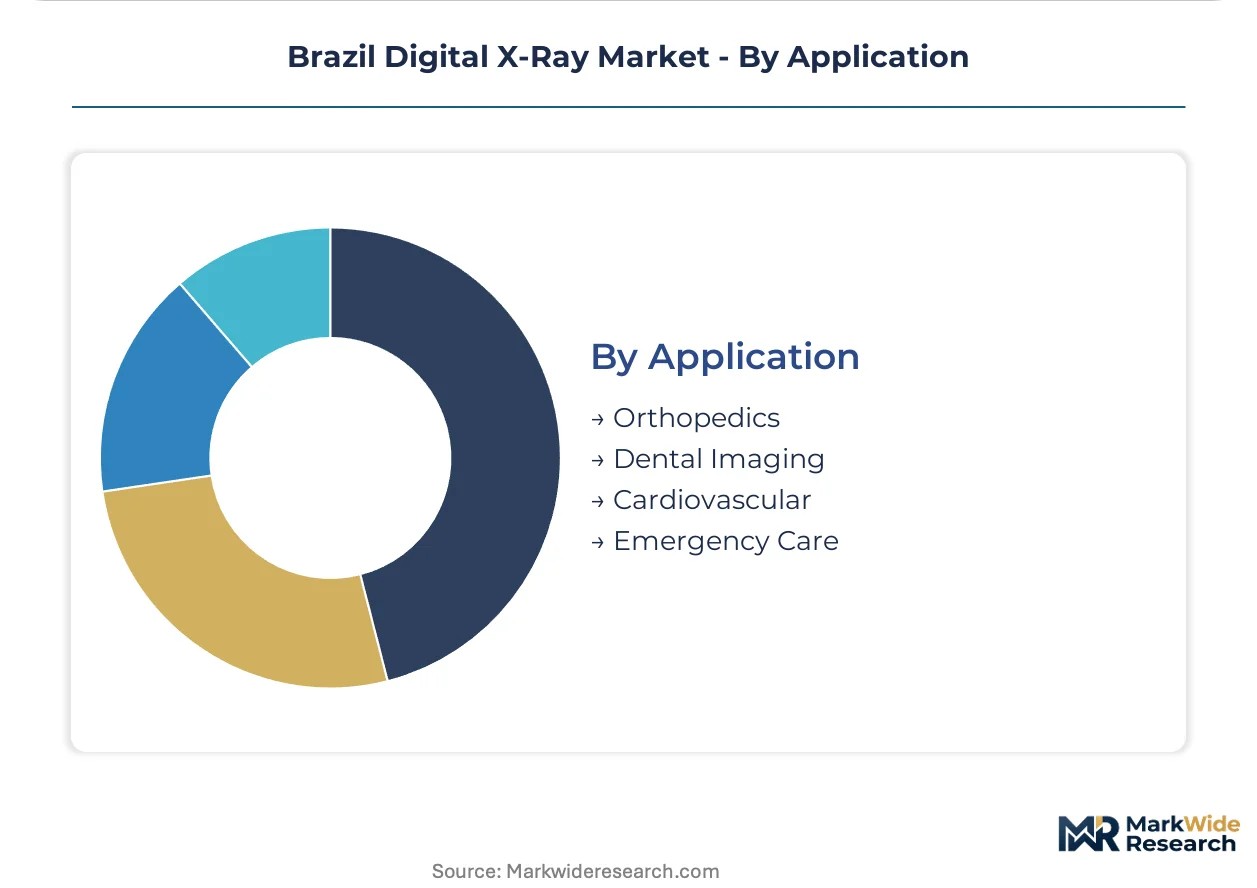
Orthopedics dominates installed base. Emergency Care is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic imaging procurement concentrates in Brazil's Southeast corridor, where hospital consortia and private radiology chains command capital budgets exceeding northern states by multiples. Federal SUS qualification programs channel equipment modernization funds toward municipal networks with documented analog infrastructure.
São Paulo
Hospital consortia in São Paulo deploy multi-vendor fleets exceeding fifty units per network, driving bulk procurement of high-throughput DR systems. ANVISA's streamlined registration pathways accelerate approval timelines for imported imaging equipment. The metropolitan corridor anchors technical service capacity, with specialized biomedical engineers concentrated for detector calibration and PACS integration.
Minas Gerais
Municipal hospitals in Minas Gerais retain computed radiography as bridge technology during phased analog-to-digital transitions. SUS diagnostic imaging qualification programs direct federal resources toward equipment replacement in underserved municipal networks. Consolidated radiology groups in Belo Horizonte operate mixed-vendor installations, unbundling service contracts from equipment procurement.
Rio de Janeiro
Public hospital networks in Rio de Janeiro face compressed replacement cycles as wireless cassette technology hybridizes emergency department workflows. INMETRO certification requirements for electromagnetic compatibility filter supplier participation in state-level tenders. Tertiary facilities in the metropolitan area prioritize portable X-ray deployment for intensive care unit bedside imaging.
Rio Grande do Sul
Outpatient clinic chains in Rio Grande do Sul expand point-of-care imaging capacity through portable digital X-ray acquisition. State health secretariats align procurement with federal SUS modernization mandates. Porto Alegre's diagnostic imaging market exhibits lower installed base density than São Paulo, creating positioning opportunities for mobile screening units.
Bahia
Public health networks in Bahia confront capital intensity barriers as federal budget allocations fluctuate across election cycles. ANVISA's harmonization with international standards reduces documentation burdens for established manufacturers seeking northeast market entry. Salvador's hospital infrastructure lags Southeast replacement velocity, extending equipment lifecycles beyond typical seven-year horizons.
Brazil Digital X-Ray Market Competitive Environment
Channel-controlling players compete with product-specialist players across Brazil's procurement landscape. The vendor base stratifies into multinational imaging conglomerates with established service footprints, mid-tier European and Asian manufacturers leveraging regulatory pathway compression, and independent service organizations capturing disintermediated maintenance contracts. Three archetypes dominate: full-system integrators bundling hardware with long-term service agreements; portable-specialist manufacturers targeting emergency and mobile screening segments; and component-agnostic service providers managing multi-vendor fleets. Competitive intensity centers on M&A activity consolidating diagnostic imaging center chains and strategic partnerships between international suppliers and local distributors navigating INMETRO certification complexity.
Among the multinational imaging conglomerates, Siemens Healthineers, GE Healthcare, and Fujifilm Holdings Corporation occupy distinct positioning vectors. Siemens Healthineers exemplifies the full-system integrator archetype through sustained long-term contracts with large hospital consortia. GE Healthcare anchors market presence via localized technical support infrastructure aligned to public procurement cycles. Fujifilm Holdings Corporation represents the portable-specialist trajectory, competing aggressively in segments where emergency care and mobile screening applications expand fastest.
| Leading Market Players |
|---|
| Canon Medical Systems Corporation |
| Siemens Healthineers |
| GE Healthcare |
| Agfa HealthCare |
| Carestream Health |
| Fujifilm Holdings Corporation |
| Shimadzu Corporation |
| Konica Minolta Healthcare |
| Koninklijke Philips NV |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in flat-panel detector fabrication across East Asian component hubs is compressing supplier margins while inflating equipment procurement costs for Brazilian hospital networks. This utilization squeeze simultaneously tightens capital planning timelines for public sector buyers and accelerates vendor consolidation toward manufacturers with captive supply arrangements.
Pricing Analysis
Cost-plus contracts with semiconductor indexation dominate procurement agreements between Brazilian hospital consortia and multinational imaging suppliers. Three-tier pricing structure across premium DR systems, standard CR configurations, and economy portable units separates Siemens Healthineers' integrated service bundles from Fujifilm's unbundled hardware plays. Cost compression in the portable segment is intensifying because battery and wireless detector commoditization erodes hardware margins. Diagnostic imaging center chains exhibit highest price sensitivity due to unbundled service contract negotiations, while SUS-qualified public hospitals absorb premium pricing for long-term technical support commitments.
Supply Chain Analysis
Upstream feedstock concentration in amorphous selenium deposition and cesium iodide scintillator crystal growth centers on Japan, South Korea, and Taiwan. Flat-panel detector assembly draws from specialized TFT substrate fabrication in Taiwan, sensor packaging in South Korea, and final module integration in Japan or China. Single-source vulnerability in amorphous selenium evaporation equipment creates procurement risk for DR system manufacturers serving ANVISA-registered markets. Distribution runs through authorized Brazilian distributors holding INMETRO certification credentials, with São Paulo-based logistics hubs managing customs clearance and technical training deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's digital X-ray market functions as a service-attach opportunity where multi-vendor fleet management contracts expand faster than underlying hardware replacement cycles. Independent service organizations now capture maintenance revenue disintermediated from original equipment manufacturers, particularly in consolidated radiology networks exceeding fifty units.
For Market Incumbents: Harden service contract retention through embedded PACS integration and predictive detector calibration protocols. Siemens Healthineers and GE Healthcare should deepen backward integration into solid-state sensor refurbishment capabilities to defend against independent service organization encroachment. Biomedical engineering talent scarcity in São Paulo and Rio de Janeiro corridors threatens response-time commitments, making captive technician training programs essential for contract renewal rates. For New Entrants and Emerging Players: Pursue Amazonas and Ceará state health secretariats with mobile screening unit leasing models that circumvent upfront capital intensity barriers. The North and Northeast regions exhibit lowest installed base density and minimal incumbent service footprint. European and Asian manufacturers should leverage ANVISA's IMDRF harmonization to fast-track registration, then partner with established Brazilian distributors for INMETRO certification navigation. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among independent service organizations managing multi-vendor fleets for consolidated diagnostic imaging center chains. Long-term viability across the analysis window hinges on tele-radiology convergence capabilities and cloud-based PACS integration depth. Acquisition targets should demonstrate established relationships with Minas Gerais radiology groups or SUS procurement committees. The signal to monitor is federal budget allocation continuity through political transition periods.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | SUS qualification programs channel federal resources toward ANVISA-registered equipment vendors with localized technical support. |
| Software Companion Development | Cloud-based PACS integration enables remote diagnostic workflows and recurring subscription revenue streams. |
| Reimbursement Strategy | Alignment with Ministry of Health diagnostic imaging qualification programs accelerates procurement committee approval timelines. |
| CE Marking Pathway | ANVISA's IMDRF harmonization accepts substantial equivalence demonstrations based on European regulatory approvals. |
| Backward Integration into Detector Refurbishment | In-house solid-state sensor recalibration capabilities reduce service contract costs and improve margin retention. |
Study Parameters
A standing panel of biomedical engineering directors, hospital purchasing committee members, GPO contracts managers, and diagnostic imaging center operations heads provided ongoing calibration throughout the study. Primary interviews with these stakeholders combined with secondary validation against ANVISA registration databases, SUS procurement disclosure records, and INMETRO certification filings. Bottom-up equipment shipment tracking across São Paulo, Minas Gerais, and Rio de Janeiro metropolitan corridors triangulated against top-down federal budget allocation analysis.
Scenario-bracketing framed demand projections across the modeling period, with sensitivity testing around public sector procurement cycle volatility and import dependency disruptions. Segmentation dimensions modeled include product type, end-user institution tier, technology platform, and regional installed base density. CAGRs derived from equipment replacement velocity analysis and capital expenditure intention surveys. Forecast inputs incorporated ANVISA registration timeline compression effects and flat-panel detector supply concentration dynamics.
Sensitivities concentrate around federal budget reallocation risk, East Asian component supply disruptions, and biomedical engineering talent migration patterns. Forecasts reflect documented assumptions regarding SUS modernization mandate continuity and ANVISA regulatory harmonization trajectory. Cross-checking against Ministry of Health diagnostic imaging qualification program disbursement records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Europe Intraoperative Imaging Market
Medical Imaging
Wireless Intraoral Camera Market
Medical Imaging
Radiology Services Market
Medical Imaging
US Contrast Media Market
Medical Imaging
Perfusion Radiology Market
Medical Imaging
United Arab Emirates Diagnostic Imaging Equipment Market
Medical Imaging
Global Orthopedic Imaging Equipment Market
Medical Imaging
Veterinary Imaging Systems Market
Medical Imaging
Global Vendor-Neutral Archive (VNA) and PACS Market
Medical Imaging
Germany Digital Pathology Market
Medical Imaging
Spain Digital Radiology Market
Medical Imaging
Global Single-Photon Emission Computed Tomography (SPECT) Market
Medical Imaging
Global MRI Scanner Market
Medical Imaging
Positron Emission Tomography Devices (PET) Market
Medical Imaging
Germany Nuclear Imaging Market
Medical Imaging
United States Computed Tomography Market