
 Spain Nuclear Imaging Market | 2026-2036
Spain Nuclear Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Nuclear Imaging Market Analytics
Radiopharmacist workforce expansion is rotating toward hybrid imaging competencies as Spanish hospitals integrate PET-CT and SPECT-CT protocols. Siemens Healthineers AG anchors its position through installed base density across Madrid's tertiary centers. GE Healthcare differentiates via cyclotron-to-clinic radiopharmaceutical networks that shorten tracer delivery windows. Bracco Group competes on iodine-based contrast and nuclear agent portfolios tailored to cardiology workflows.
Spain nuclear imaging encompasses diagnostic systems and radiopharmaceuticals that detect gamma ray or positron emissions from administered tracers, typically operating at spatial resolutions below 5 millimeters for lesion localization and metabolic activity quantification. Its primary purpose is non-invasive visualization of perfusion, metabolism, and receptor binding to guide treatment selection in cancer, cardiac, and neurological care. Positron Emission Tomography systems command premium placement due to FDG tracer reimbursement alignment with oncology staging protocols. SPECT technology occupies stable demand in cardiology stress testing where technetium sestamibi protocols remain cost-efficient. Radiopharmaceuticals represent the margin-concentrated segment where half-life logistics and production licensing create supply moats.
Spain's Nuclear Safety Council enforces radiological protection standards that govern tracer handling, waste disposal, and personnel exposure limits across nuclear medicine departments. The Spanish Agency for Medicines and Health Products regulates radiopharmaceutical marketing authorizations and good manufacturing practice compliance for domestic cyclotron facilities. Stakeholders must monitor how EU MDR conformity requirements and EMA guidance on novel radioligand therapies reshape capital allocation between scanner upgrades and tracer pipeline investments.
Market Dynamics
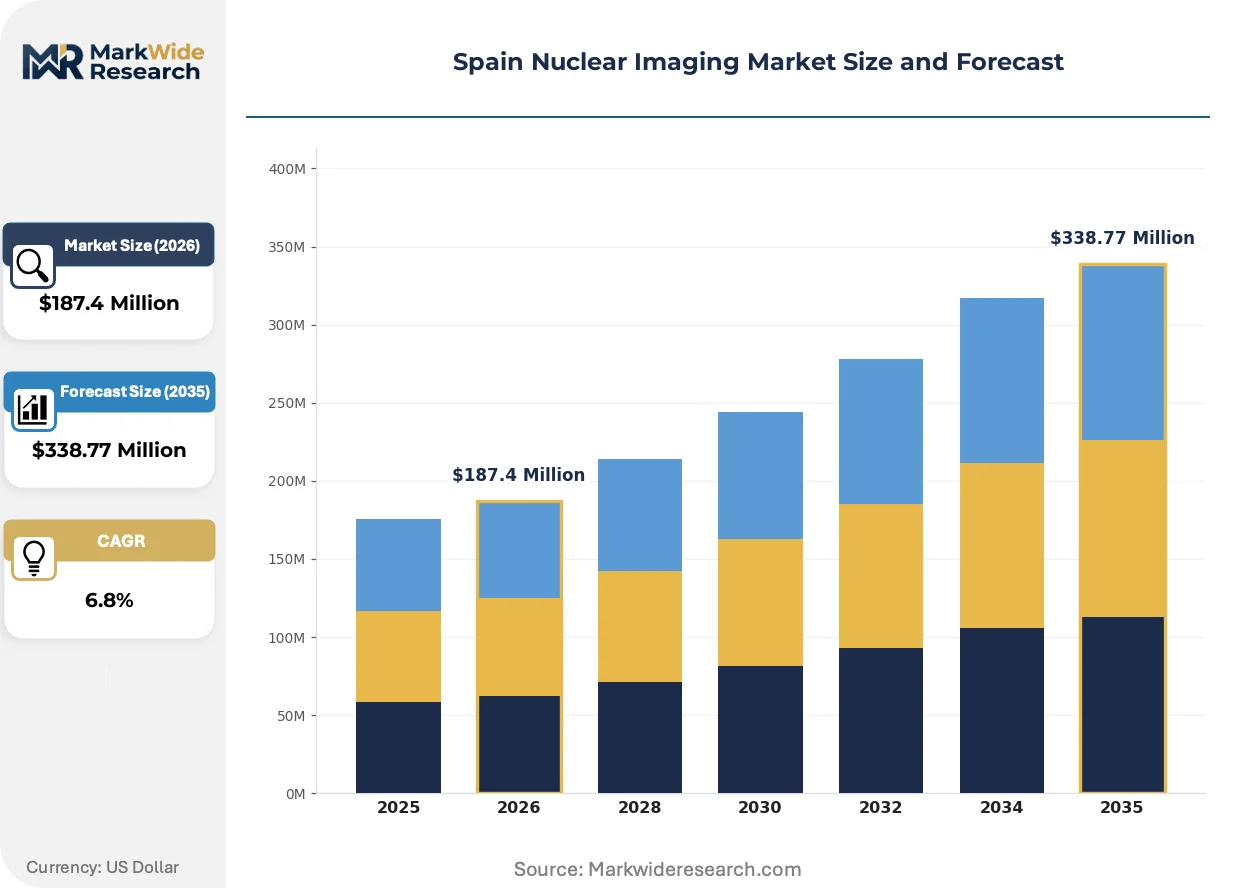
Spain's nuclear imaging sector is compressing around hybrid modality adoption, as hospitals consolidate standalone SPECT and PET scanners into fused PET-CT and SPECT-CT systems to maximize throughput per square meter of shielded suite space.
Growth Catalysts
- Oncology protocol expansion:Madrid's tertiary centers are embedding FDG-PET into lung and lymphoma staging pathways, creating pull-through demand for cyclotron-produced tracers.
- EU MDR alignment:The Medical Devices Regulation is accelerating scanner replacement cycles as Class IIa and IIb devices face renewed conformity assessment pressure.
- Cardiology workflow integration:Technetium sestamibi stress testing protocols remain embedded in Barcelona's hospital networks, sustaining SPECT-CT utilization rates.
Market Restraints
- Short-half-life logistics:Fluorodeoxyglucose's 110-minute decay window forces radiopharmaceutical production within 200 kilometers of injection sites, limiting rural scanner deployment.
- Cyclotron capital intensity:Each on-site or regional cyclotron demands EUR 4-8 million upfront plus specialized bunker construction, concentrating supply in Madrid and Barcelona corridors.
- Personnel exposure ceilings:Spain's Nuclear Safety Council enforces annual dose limits that cap departmental throughput without additional radiopharmacist hiring.
Strategic Opportunities
- Andalusian network gaps:Seville and Málaga absorb patients from Extremadura and Murcia, creating whitespace for satellite cyclotron facilities or mobile PET-CT units.
- Theranostic convergence:Lutetium-177 PSMA therapies for prostate cancer are driving paired diagnostic imaging demand, expanding radioligand development pipelines.
- Tele-nuclear medicine:Remote image interpretation protocols are extending specialist coverage to Galicia and Castile-León without full-time on-site physicists.
Industry Challenges
- Radiopharmacist scarcity:Spain's university programs produce fewer than 40 nuclear pharmacy specialists annually, creating recruitment bottlenecks for expanding departments.
- Shielded suite retrofit costs:Converting conventional CT rooms to PET-CT compliance requires lead-lined walls and HVAC reconfiguration, stretching hospital capital budgets.
- Waste disposal compliance:The Nuclear Safety Council's spent tracer and contaminated material handling rules impose recurring operational overhead that smaller centers struggle to absorb.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Nuclear Imaging Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Photon Emission Computed Tomography, Positron Emission Tomography, Radiopharmaceuticals, Imaging Agents End User: Hospitals, Diagnostic Centers, Research Institutions, Outpatient Facilities Application: Cardiology, Oncology, Neurology, Orthopedics Technology: SPECT, PET, CT Hybrid Systems, Fluorescence Imaging |
| Companies Covered | Siemens Healthineers AG, GE Healthcare, Canon Medical Systems Corporation, Koninklijke Philips NV, Fujifilm Holdings Corporation, Curium, Bayer AG, Bracco Group, Oncovision, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Nuclear Imaging Market Evolving Landscape
Digital PET detector technology and AI-assisted reconstruction algorithms are compressing scan times while improving lesion detectability, forcing equipment refresh cycles faster than traditional depreciation schedules anticipated.
Digital silicon photomultiplier arrays are displacing conventional photomultiplier tube detectors in new scanner installations. Hospital procurement committees in Madrid's La Paz and Gregorio Marañón complexes have specified solid-state detectors for all 2024-2026 capital purchases. The technology is displacing legacy Anger camera architectures by enabling time-of-flight resolution below 300 picoseconds, directly impacting competitive positioning among installed base vendors.
Spain's transposition of the EU MDR is requiring renewed technical documentation for all active implantable and diagnostic imaging devices. The Spanish Agency for Medicines and Health Products has extended transition timelines for certain Class IIb devices, but PET and SPECT systems face full conformity assessment pressure. Nuclear medicine departments are responding by consolidating vendor relationships to simplify post-market surveillance obligations.
Radiopharmaceutical sourcing patterns are shifting from hospital-based cyclotrons toward centralized production hubs with validated cold-chain distribution. Madrid's Hospital Clínico San Carlos now receives FDG from a regional commercial cyclotron rather than on-site production, reducing capital intensity. This restructuring is most visible in Catalonia, where Barcelona's network of private cyclotron facilities supplies multiple autonomous community hospitals under long-term tracer supply agreements.
Spain Nuclear Imaging Market Segmentation
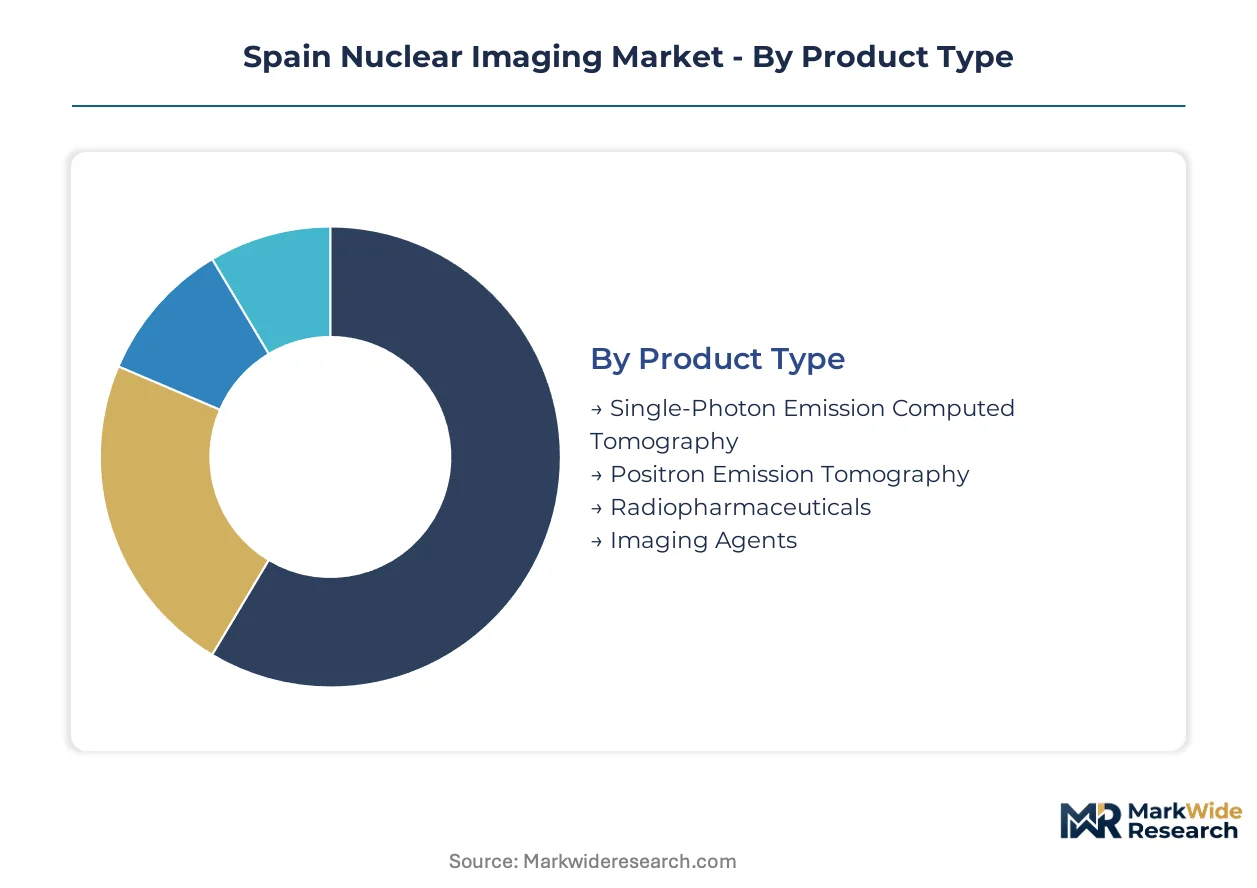
Nuclear imaging segmentation in Spain reflects distinct regulatory pathways, capital intensity tiers, and clinical workflow integrations that shape procurement decisions across autonomous communities. Each dimension carries specific compliance obligations from the Nuclear Safety Council and the Spanish Agency for Medicines and Health Products.
Product Type:
Spain's Nuclear Safety Council imposes differentiated licensing requirements across device categories, with PET systems facing stricter bunker construction standards than SPECT installations due to positron emission shielding demands.
- Single-Photon Emission Computed Tomography:Gamma camera systems detect technetium-99m emissions through sodium iodide crystal arrays. Madrid's Hospital Universitario La Paz maintains one of Spain's highest SPECT throughput rates for cardiac perfusion protocols, constrained by radiopharmacist staffing ceilings.
- Positron Emission Tomography:Ring-detector arrays capture coincident 511 keV photon pairs from positron-electron annihilation events. Barcelona's Hospital Clínic has prioritized digital PET-CT replacements, driven by EMA-aligned oncology staging guidelines that reward metabolic quantification precision.
- Radiopharmaceuticals:Cyclotron-produced tracers including fluorodeoxyglucose and gallium-68 analogs require AEMPS manufacturing authorizations.
- Imaging Agents:Iodine-131 and technetium-labeled compounds dominate thyroid and bone scan protocols across Andalusian diagnostic networks.
Positron Emission Tomography handles the majority of throughput in Madrid and Barcelona corridors; Radiopharmaceuticals are expanding most quickly on share as centralized production hubs displace hospital-based cyclotrons.
End User:
Capital allocation patterns diverge sharply between integrated health systems and standalone operators, with public hospital networks absorbing the bulk of PET-CT installations through regional ministry tenders.
- Hospitals:Tertiary centers with on-site nuclear medicine departments manage complete tracer-to-interpretation workflows. Gregorio Marañón Hospital in Madrid operates Spain's largest hybrid imaging suite, processing over 8,000 PET-CT studies annually with dedicated radiopharmacist teams.
- Diagnostic Centers:Private imaging chains concentrate SPECT capacity for stress testing and bone scintigraphy. Quirónsalud's Catalonia network leverages centralized technetium sourcing to maintain cost parity with public competitors.
- Research Institutions:Academic medical centers pursue novel radioligand development under AEMPS clinical trial frameworks.
- Outpatient Facilities:Limited nuclear imaging presence due to shielding requirements and waste handling compliance costs.
Hospitals command the dominant installed base; Diagnostic Centers are climbing the fastest as public-private partnerships expand regional access.
Application:
Reimbursement alignment with SNS (Sistema Nacional de Salud) tariff schedules determines procedure volume distribution, with oncology and cardiology securing the most favorable coding positions.
- Oncology:FDG-PET staging for lung, lymphoma, and colorectal malignancies dominates tracer consumption. Valencia's Instituto Valenciano de Oncología has embedded metabolic imaging into neoadjuvant chemotherapy response assessment protocols.
- Cardiology:Technetium sestamibi stress-rest perfusion imaging remains the standard for ischemia detection. Basque Country hospitals maintain SPECT-CT utilization rates above national averages due to integrated cardiac catheterization pathways.
- Neurology:Amyloid-PET for Alzheimer's diagnosis faces restricted SNS reimbursement, limiting deployment to research cohorts.
- Orthopedics:Bone scintigraphy for occult fracture and prosthetic infection evaluation occupies stable demand in trauma centers.
Oncology generates the majority of PET-CT procedure volume; Cardiology sustains SPECT utilization through established stress testing workflows.
Technology:
Detector architecture choices carry long-term implications for time-of-flight resolution and silicon photomultiplier upgrade paths, influencing procurement committee specifications across Spain's major health clusters.
- SPECT:Anger camera technology with parallel-hole collimators continues serving technetium-based protocols. Galicia's hospital network has deferred SPECT replacement cycles pending EU MDR conformity clarity.
- PET:Ring-based coincidence detection with lutetium-based scintillators enables sub-5mm lesion localization. Digital silicon photomultiplier arrays are displacing conventional photomultiplier tubes in Madrid's 2024-2026 capital purchase waves.
- CT Hybrid Systems:PET-CT and SPECT-CT fusion platforms maximize shielded suite productivity per square meter. Hospital Clínico San Carlos converted standalone PET capacity to hybrid configuration, eliminating separate CT scheduling bottlenecks.
- Fluorescence Imaging:Intraoperative nuclear guidance systems remain niche, confined to sentinel lymph node mapping in select oncology centers.
CT Hybrid Systems absorb the majority of new capital expenditure; Digital PET detector architectures are gaining share fastest as time-of-flight specifications tighten competitive requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain's Nuclear Safety Council anchors regulatory oversight across autonomous communities, with tracer production licensing and dose exposure limits shaping regional deployment patterns for PET-CT and SPECT-CT systems.
Madrid
Oncology staging protocols at Gregorio Marañón Hospital and La Paz University Hospital drive FDG-PET consumption volumes. The regional health ministry channels capital through centralized tenders that favor hybrid imaging suite consolidation. Madrid's tertiary corridor concentrates Spain's highest cyclotron density, with Hospital Clínico San Carlos transitioning to commercial tracer sourcing.
Catalonia
Barcelona's Hospital Clínic embeds digital PET-CT replacements within EMA-aligned metabolic quantification guidelines. The Catalan health service reimburses cardiac SPECT-CT stress testing at rates sustaining private diagnostic chain participation. Quirónsalud's network leverages centralized technetium logistics to maintain cost parity with public competitors across Girona and Tarragona.
Andalusia
Seville and Málaga absorb nuclear imaging demand from Extremadura and Murcia, creating whitespace for satellite cyclotron facilities. The regional ministry's infrastructure plan identifies mobile PET-CT units as priority investments for coastal provinces. Hospital Universitario Virgen del Rocío processes referral volumes exceeding local production capacity, forcing tracer shipments from Madrid corridors.
Basque Country
Integrated cardiac catheterization pathways at Donostia University Hospital sustain SPECT-CT utilization rates above Spanish averages. The regional health system embeds technetium sestamibi protocols within ischemia detection workflows. Bilbao's hospital network coordinates with Navarre facilities to share radiopharmacist staffing across shielded suites.
Valencia
Instituto Valenciano de Oncología has embedded metabolic imaging into neoadjuvant chemotherapy response assessment protocols. The regional health ministry's imaging tariff schedule favors FDG-PET for lung and lymphoma staging. Alicante's Hospital General processes overflow oncology referrals from Murcia, straining tracer logistics across the coastal corridor.
Spain Nuclear Imaging Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Spain's nuclear imaging sector. Siemens Healthineers AG and GE Healthcare dominate scanner installations through Madrid and Barcelona tertiary center relationships, while Bracco Group and Curium occupy radiopharmaceutical supply positions. The competitive terrain splits between equipment vendors pursuing hybrid modality refresh cycles and tracer producers securing cyclotron-to-clinic distribution contracts. Consolidation pressures intensify as EU MDR conformity requirements favor simplified vendor relationships.
Among Germany-based integrated healthcare conglomerates, Siemens Healthineers AG exemplifies the equipment-dominant archetype through installed base density across Spanish tertiary centers. GE Healthcare, a US-based multinational, represents the cyclotron-network competitive vector with regional tracer production capabilities. Bracco Group, an Italy-based specialty pharmaceutical company, anchors the contrast agent and nuclear imaging agent portfolio tier tailored to cardiology workflows. These three entities collectively illustrate how geographic origin and corporate structure map onto distinct strategic positions within Spain's regulated nuclear medicine environment.
| Leading Market Players |
|---|
| Siemens Healthineers AG |
| GE Healthcare |
| Canon Medical Systems Corporation |
| Koninklijke Philips NV |
| Fujifilm Holdings Corporation |
| Curium |
| Bayer AG |
| Bracco Group |
| Oncovision |
| Others |
Value Network & Pricing Analysis
Cyclotron utilization rates above 70 percent in Madrid and Barcelona corridors generate decisive scale economies that compress unit tracer production costs while erecting price floors for rural scanner deployment. Spain's Nuclear Safety Council licensing density concentrates radiopharmaceutical supply within 200-kilometer distribution radii, binding pricing power to bunker-proximate tertiary centers and excluding peripheral autonomous communities from competitive sourcing.
Pricing Analysis
Madrid-Barcelona corridor pricing for FDG-PET studies runs 15-25 percent below Seville-Málaga rates due to cyclotron density and cold-chain logistics efficiency. Three-tier pricing structure across premium digital PET-CT, standard hybrid SPECT-CT, and economy standalone gamma camera levels stratifies procurement committees by shielded suite investment capacity. Cost compression in economy-tier SPECT services is intensifying because diagnostic chains compete on technetium sourcing scale. Public hospital networks exhibit lowest price sensitivity due to SNS reimbursement alignment; private outpatient centers face acute margin pressure from tracer logistics premiums.
Supply Chain Analysis
Strategic stockpiling of technetium-99m generators dominates inventory strategy given molybdenum-99 decay constraints, while FDG production adheres to just-in-time protocols with 110-minute half-life windows. Cyclotron manufacturing concentrates in Spain, Belgium, and France for EU-served markets; Spain's domestic production draws from molybdenum-99 imports via the Netherlands and Poland. Single-source vulnerability permeates the generator supply chain following reactor consolidation in the Netherlands and Belgium. Distribution runs through regional commercial cyclotron hubs to hospital nuclear medicine departments under long-term supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's nuclear imaging sector approaches a platform-economics inflection as digital PET-CT interoperability standards and AI-assisted reconstruction algorithms consolidate vendor ecosystems around integrated hardware-software-service bundles.
For Market Incumbents: Fortify installed base lock-in through radiopharmacist training academy investments that deepen human capital dependencies among Madrid and Barcelona tertiary centers. Prioritize cyclotron-to-clinic distribution contract extensions before EU MDR conformity assessments accelerate vendor consolidation. Siemens Healthineers and GE Healthcare face emerging substitution pressure from Canon Medical's solid-state detector pricing aggression in 2024-2026 capital purchase cycles. For New Entrants and Emerging Players: Lead with mobile PET-CT unit deployment targeting Andalusian coastal provinces where Hospital Universitario Virgen del Rocío tracer deficits force patient referrals to Madrid corridors. The whitespace concentrates in Seville-Málaga satellite cyclotron facilities or fleet-based diagnostic services. A radiopharmaceutical logistics partnership with existing private cyclotron networks offers the most penetrable go-to-market angle without EUR 4-8 million bunker capital requirements. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among regional commercial cyclotron operators with validated cold-chain distribution networks and long-term hospital supply agreements. Five-to-ten year viability hinges on theranostic pipeline positioning as lutetium-177 PSMA therapies expand diagnostic pairing demand. Acquisition targets should display AEMPS manufacturing authorizations and established radiopharmacist teams. The signal to watch is EU MDR transition timeline extensions that temporarily freeze hospital procurement committees and compress equipment vendor valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Regional Cyclotron Consolidation | Centralized FDG production at Hospital Clínico San Carlos reduces capital intensity for satellite hospitals. |
| Digital Detector Upgrade Cycles | Solid-state silicon photomultiplier arrays at La Paz and Gregorio Marañón displace legacy Anger camera architectures. |
| Radiopharmacist Workforce Expansion | Hybrid imaging competencies address Nuclear Safety Council dose exposure ceilings that cap departmental throughput. |
| Mobile PET-CT Fleet Deployment | Andalusian network gaps in Seville-Málaga absorb Extremadura referrals without fixed bunker construction. |
| Theranostic Pipeline Investment | Lutetium-177 PSMA therapies at Valencia's Instituto Valenciano de Oncología drive paired diagnostic imaging demand. |
Research Methodology
Cross-validation between AEMPS regulatory filings and Spanish Agency for Medicines and Health Products manufacturing authorization databases anchors the qualitative findings on cyclotron facility capacity and tracer production licensing. Primary interviews with nuclear medicine department heads, radiopharmacist specialists, hospital procurement committee members, and biomedical engineering directors combined with secondary validation against EU MDR technical documentation and SNS reimbursement tariff schedules. Bottom-up scanner installation counts and top-down autonomous community health ministry capital expenditure allocations were triangulated to establish market sizing boundaries.
Sensitivity analysis across digital PET detector adoption curves, EU MDR transition timeline scenarios, and theranostic radioligand approval pathways informs the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, end user category, clinical application, and detector technology architecture alongside regional cyclotron proximity tiers. CAGRs were derived from installed base replacement cycles, tracer consumption per procedure trends, and reimbursement rate trajectories. Cyclotron capital expenditure patterns and radiopharmacist graduation rates from Spanish university programs served as industry-specific forecast inputs.
Underlying assumptions cover EU MDR conformity assessment pacing, molybdenum-99 generator supply stability, and SNS oncology staging protocol expansion, with deviation risk concentrated in reactor shutdown schedules affecting technetium-99m availability. Forecasts reflect these documented conditions without certainty guarantees. Revision becomes warranted when AEMPS manufacturing authorization thresholds or Nuclear Safety Council dose exposure limits cross regulatory inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
US Gadolinium-Based Contrast Media Market
Medical Imaging
Global Medical Imaging Phantoms Market
Medical Imaging
India Nuclear Imaging Market
Medical Imaging
Global Contrast-Enhanced Ultrasound Market
Medical Imaging
South Africa Magnetic Resonance Imaging Market
Medical Imaging
North America Nuclear Medicine Market
Medical Imaging
Germany Computed Tomography Market
Medical Imaging
Remanufactured Medical Imaging Devices Market
Medical Imaging
United States Computed Tomography Market
Medical Imaging
Italy Nuclear Imaging Market
Medical Imaging
France Digital X-Ray Devices Market
Medical Imaging
Coronary Heart Disease Diagnostic Imaging Market
Medical Imaging
China Computed Tomography Market
Medical Imaging
Brazil Mammography Market
Medical Imaging
PSMA-PET Imaging Market
Medical Imaging
Small Animal Imaging (in-Vivo) Market