
 Digital X Ray Market | 2026-2036
Digital X Ray Market Size, Share, and Industry Trends Forecast 2026-2036
Digital X Ray Market Intelligence
The traditional hospital-centric purchasing model is decoupling from the broader market's growth, as outpatient clinics and specialized diagnostic centers become major procurement hubs. This shift favors vendors with flexible, lower-cost systems. Siemens Healthineers leverages its extensive portfolio to serve both large hospitals and smaller clinics. Meanwhile, Carestream Health specializes in dental and orthopedic applications, securing a strong position in niche segments. GE Healthcare competes through its broad imaging and software ecosystem integration.
Digital X-ray systems capture medical images using solid-state detectors, such as amorphous silicon flat panels, converting X-ray photons directly or indirectly into digital signals. This technology provides immediate image acquisition and advanced post-processing capabilities for enhanced diagnostic accuracy. Direct Radiography technology continues to displace older Computed Radiography due to superior image quality and workflow efficiency. Within applications, orthopedics and dentistry represent mature, high-volume segments, while veterinary use is a smaller but expanding area.
Market access is governed by stringent regulatory approvals for medical devices. Manufacturers must secure clearance from bodies like the US FDA, adhere to CE marking requirements under Europe's Medical Devices Regulation (MDR), and meet NMPA standards in China. These regulations enforce strict safety, quality, and performance criteria. Consequently, navigating the varied international approval pathways remains a critical competency for system vendors and component suppliers.
Market Dynamics
The market’s primary structural force is the regulatory mandate for lower radiation exposure, compelling a technological upgrade cycle. This pressure, exemplified by WHO guidelines, accelerates the replacement of older systems with more efficient digital radiography technologies across global healthcare systems.
Growth Catalysts
- Healthcare Modernization Programs:Public and private investments in upgrading healthcare infrastructure, particularly in Brazil and India, are expanding the installed base of digital systems in hospitals and new diagnostic centers.
- Dose Reduction Mandates:Global health initiatives and national regulations increasingly emphasize patient and operator safety, promoting the adoption of digital systems that offer lower radiation doses compared to analog and computed radiography.
- Expanding Clinical Applications:The use of digital X-ray is growing beyond traditional orthopedics into high-volume segments like dentistry and emerging areas such as veterinary medicine, creating new avenues for market expansion.
Market Restraints
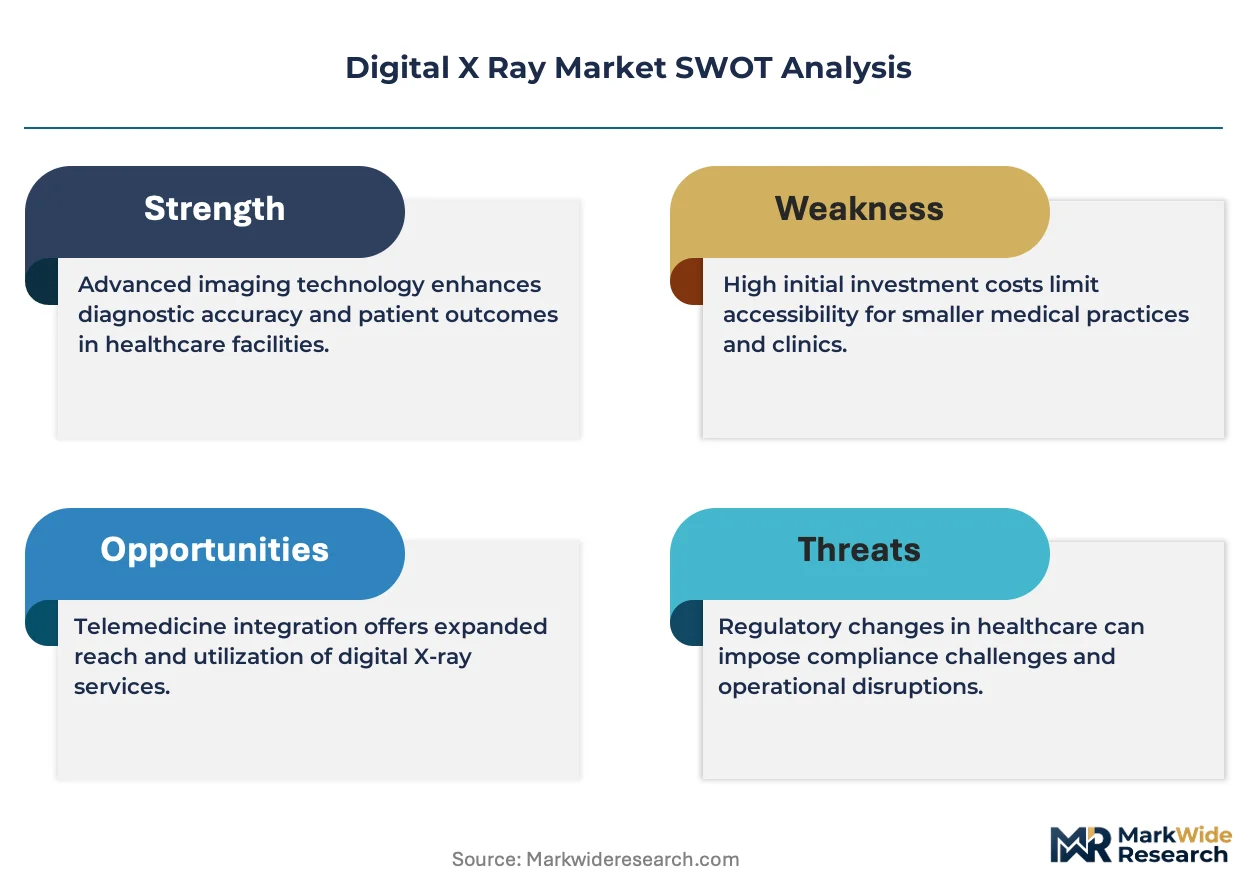
- High Capital Investment:The significant upfront cost associated with acquiring high-resolution digital radiography systems, particularly those with advanced flat-panel detectors, remains a substantial barrier for smaller clinics and hospitals in developing economies.
- Stringent Regulatory Pathways:Navigating the complex and lengthy approval processes of bodies like the US FDA, China's NMPA, and Brazil's ANVISA creates market entry delays and increases compliance costs for manufacturers.
- Data Infrastructure Requirements:The transition to digital imaging necessitates robust IT infrastructure, including Picture Archiving and Communication Systems (PACS) and secure networks, which represents an additional layer of cost and complexity.
Strategic Opportunities
- AI-Powered Diagnostics:Integrating artificial intelligence algorithms for automated image analysis and computer-aided detection presents a significant opportunity to enhance diagnostic accuracy, improve workflow efficiency, and reduce radiologist workload.
- Portable and Mobile Systems:There is a clear opportunity in developing and marketing lightweight, portable DR systems for use in emergency rooms, intensive care units, and remote or underserved geographic locations.
- Emerging Economies:Underpenetrated markets in Southeast Asia and Africa represent long-term growth frontiers as their healthcare spending and infrastructure development increase, creating demand for cost-effective digital imaging solutions.
Industry Challenges
- Systems Interoperability:A primary operational challenge is ensuring seamless integration of new digital X-ray equipment with existing, often disparate, hospital information systems (HIS) and radiology information systems (RIS) from various vendors.
- Cybersecurity Vulnerabilities:Networked digital imaging systems are susceptible to cyberattacks, creating a critical need for vendors and healthcare providers to implement strong security measures to protect sensitive patient data.
- Skilled Personnel Shortage:A lack of technicians and radiologists trained to operate advanced digital systems and utilize post-processing software effectively can limit the full realization of the technology's diagnostic benefits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital X Ray Market |
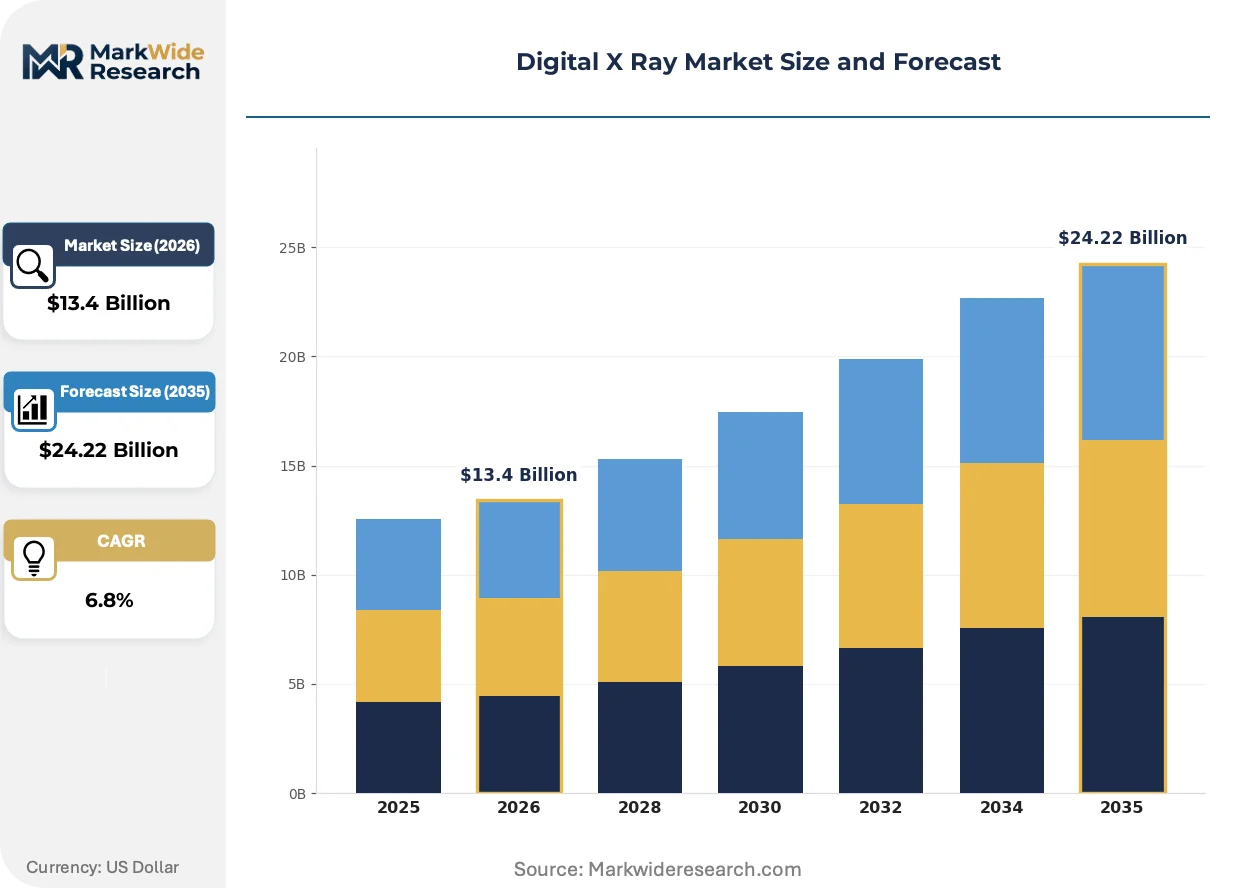
| Market Size in 2026 | $13.4 Billion |
| Market Size in 2035 | $24.22 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Systems, Fixed Systems, Mobile Systems, Fluoroscopy Systems End User: Hospitals, Clinics, Diagnostic Centers, Research Facilities Technology: Computed Radiography, Direct Radiography, Wireless Detector, CCD Application: Orthopedics, Dentistry, Veterinary, General Surgery |
| Companies Covered | Siemens Healthineers, GE Healthcare, Philips Healthcare, Fujifilm Holdings Corporation, Canon Medical Systems Corporation, Carestream Health, Shimadzu Corporation, Agfa-Gevaert Group, Konica Minolta, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital X Ray Market Strategic Shifts & Innovations
Intelligent automation and system mobility are the core themes driving product evolution. The convergence of AI-driven analytics with more portable hardware is redefining where and how diagnostic imaging is performed, shifting capabilities away from centralized departments toward the point of care.
Portable, battery-powered Direct Radiography (DR) systems utilize lightweight, durable detectors to function outside of traditional radiology suites. Outpatient clinics, mobile screening units, and sports medicine practices are adopting these systems for their flexibility and rapid image acquisition. This technology is decentralizing diagnostic imaging, bringing essential services directly to patients in diverse settings and reducing reliance on fixed hospital infrastructure.
Europe's Medical Devices Regulation (MDR) is reshaping the compliance landscape for all imaging equipment sold within the EU. The regulation mandates more rigorous clinical evidence, lifecycle documentation, and post-market surveillance than the previous directive. This affects all manufacturers, who must now invest heavily in recertifying existing products and designing new systems with these stringent requirements in mind from the outset.
Value-based healthcare models are altering equipment acquisition patterns in developed markets. This shift away from simple fee-for-service transactions disrupts the traditional capital sales cycle, creating an opening for vendors offering managed service agreements or subscription-based access to technology. This trend is most visible in large hospital networks in the United States, where total cost of ownership and clinical outcomes are key procurement drivers.
Digital X Ray Market Segmentation
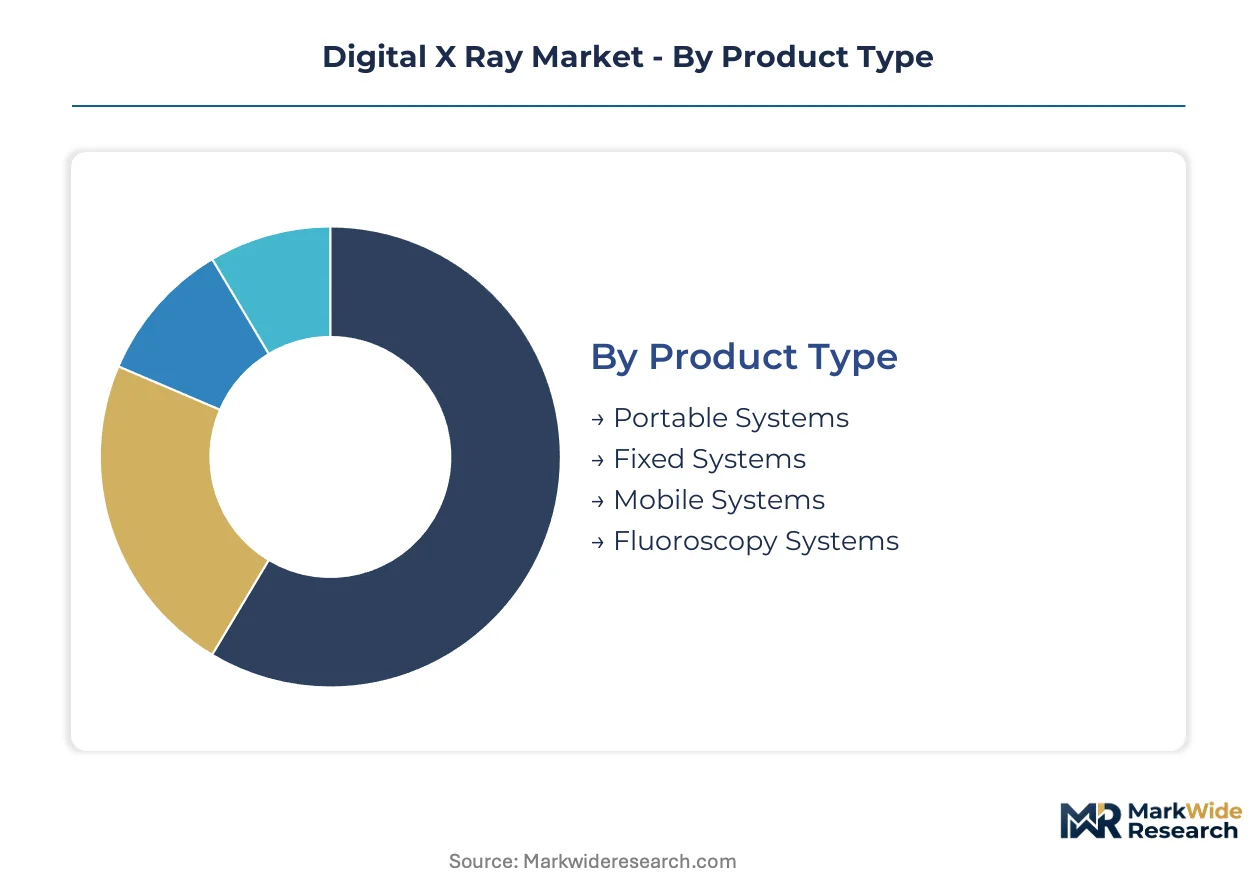
The Digital X Ray Market segments across various dimensions, providing a granular view of purchasing patterns and technological preferences. Understanding these segments helps manufacturers tailor offerings to specific clinical needs and operational environments. Each segment reflects distinct requirements for imaging capabilities, system mobility, and integration with existing healthcare infrastructure.
Product Type:
Buyers in this category differentiate based on system mobility and deployment flexibility within a clinical setting.
- Portable Systems:These lightweight, often battery-powered units are designed for use outside traditional radiology departments. Demand concentrates in emergency rooms and intensive care units, driven by the need for imaging critically ill or immobile patients at the point of care.
- Fixed Systems:Permanently installed units offer high-throughput imaging and superior image quality within dedicated radiology suites. Hospitals and large diagnostic centers in developed economies primarily drive this segment, prioritizing diagnostic accuracy and workflow efficiency.
- Mobile Systems:These wheeled units are movable within a facility, providing diagnostic capabilities across multiple departments. Outpatient clinics and smaller hospitals often procure mobile systems for their versatility and ability to serve various patient needs.
- Fluoroscopy Systems:These systems provide real-time X-ray imaging for dynamic studies like angiography or guided procedures. Specialized surgical centers and interventional radiology departments utilize fluoroscopy for complex diagnostic and therapeutic interventions.
Volume sits with Fixed Systems; growth tilts toward Portable Systems.
End User:
Customer type determines purchasing priorities, influencing system specifications and budget allocations.
- Hospitals:These institutions represent the largest end-user segment, requiring a broad range of digital X-ray systems for diverse clinical applications. Procurement decisions in hospitals are often influenced by the need for high patient throughput and seamless integration with hospital information systems.
- Diagnostic Centers:Specialized diagnostic centers focus on rapid image acquisition and efficient patient processing, often preferring systems with advanced post-processing features. These centers prioritize quick turnaround times for patient results, especially in urban areas of India and Brazil.
- Clinics:Smaller outpatient clinics and general practitioner offices require compact, user-friendly digital X-ray solutions for basic diagnostic needs. Cost-effectiveness and ease of operation are primary considerations for clinics adopting digital imaging.
- Research Facilities:Academic institutions and pharmaceutical companies utilize digital X-ray for preclinical studies and specialized research applications. Precision imaging and customizable parameters are crucial for research-oriented procurement.
Hospitals remain the dominant end-user, while Diagnostic Centers exhibit the steepest expansion trajectory.
Technology:
Technological maturity and image quality drive selection within the digital X-ray market.
- Computed Radiography:CR systems use phosphor plates to capture X-ray images, which are then scanned to produce digital files. This technology offers a cost-effective transition from analog film, particularly for facilities in emerging economies with budget constraints.
- Direct Radiography:DR technology directly converts X-ray photons into digital signals using flat-panel detectors, providing immediate image display and superior clarity. Demand for DR systems is high in developed markets, driven by mandates for lower radiation dosages and enhanced diagnostic capabilities.
- Wireless Detector:These detectors offer unparalleled flexibility, eliminating cables and allowing for easier positioning and patient comfort. Portable and mobile systems frequently integrate wireless detectors, supporting imaging in various clinical settings.
- CCD:Charge-Coupled Device detectors capture X-ray images indirectly, converting X-rays to light before digital conversion. CCD technology provides a balance of image quality and cost for specific dental and orthopedic applications.
Direct Radiography technology captures the largest share, with Wireless Detector technology gaining share fastest.
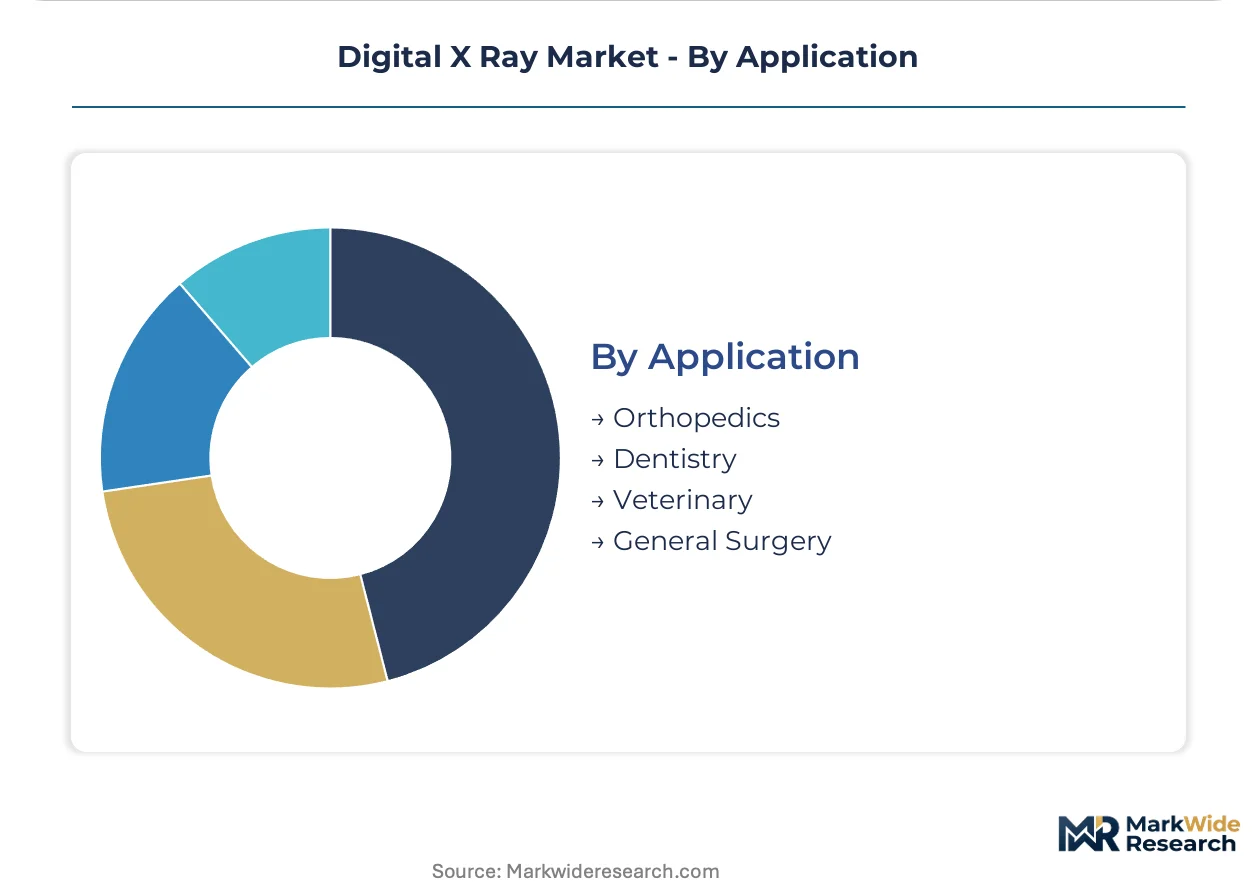
Application:
Clinical utility and patient volume shape demand across different medical specialties.
- Orthopedics:This segment represents a mature, high-volume application for digital X-ray, used for diagnosing fractures, joint diseases, and musculoskeletal conditions. Siemens Healthineers and GE Healthcare offer specialized imaging solutions for orthopedic practices.
- Dentistry:Dental applications utilize digital X-ray for intraoral and panoramic imaging, offering reduced radiation exposure and immediate image review. Carestream Health holds a strong position in this segment, providing dedicated dental imaging systems.
- Veterinary:Digital X-ray systems are increasingly adopted in veterinary clinics for diagnosing animal injuries and diseases. This expanding area benefits from portable systems that can accommodate various animal sizes and settings.
- General Surgery:Digital X-ray supports general surgical procedures through intraoperative imaging and post-surgical assessment. The need for rapid, high-resolution images drives adoption in operating rooms.
Traditional demand centers on Orthopedics, with Dentistry showing significant expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Healthcare modernization programs, particularly in India and Brazil, are driving significant investment in digital X-ray systems. These initiatives expand the installed base of diagnostic centers and hospitals. Such concentrated efforts resemble special economic zones for healthcare technology adoption.
United States
The United States market demands advanced digital imaging solutions for high patient throughput. US FDA regulations ensure strict safety and performance criteria for all medical devices. Major medical technology clusters like Boston drive innovation in diagnostic equipment.
Germany
Germany prioritizes high-quality healthcare infrastructure and advanced medical technology research. CE marking requirements under the Medical Devices Regulation (MDR) govern market access across Europe. Bavaria and other MedTech valleys foster significant development in imaging systems.
India
India's healthcare modernization programs fuel demand for digital X-ray systems in new diagnostic centers. The CDSCO regulates medical devices, while PLI schemes incentivize domestic manufacturing. Bengaluru and Hyderabad are emerging as key hubs for medical technology innovation.
Brazil
Brazil's public and private investments expand the installed base of digital systems, particularly seeking cost-effective solutions. ANVISA ensures regulatory compliance for medical equipment sold within the country. São Paulo represents a major center for medical equipment manufacturing and distribution.
Japan
Japan's aging population drives demand for advanced, preventative diagnostic imaging technologies. The PMDA oversees medical device approvals, ensuring product quality and safety. Tokyo and Kyoto host significant R&D activities for cutting-edge medical device development.
Digital X Ray Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, reflecting varied market entry strategies. The market structure features large diversified imaging giants alongside specialized niche players. Companies pursue portfolio diversification and ecosystem integration to maintain competitive positioning.
Among the established global players, Siemens Healthineers exemplifies a diversified imaging giant leveraging an extensive portfolio. Carestream Health, conversely, represents a specialist focusing on niche dental and orthopedic applications. GE Healthcare occupies a position as a broad imaging and software ecosystem integrator.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| Philips Healthcare |
| Fujifilm Holdings Corporation |
| Canon Medical Systems Corporation |
| Carestream Health |
| Shimadzu Corporation |
| Agfa-Gevaert Group |
| Konica Minolta |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap manufacturers often influence supply behavior, shaping pricing discipline across the Digital X Ray Market. Their focus on specialized components and regional distribution networks impacts equipment availability and cost structures.
Pricing Analysis
Premium pricing for short lead times often applies to advanced Direct Radiography systems, particularly those with specialized flat-panel detectors. The dominant pricing structure involves contract-based long-term agreements for large hospital systems, with transactional sales for smaller clinics. Price differentiation stems from certification levels, such as US FDA clearance, and the scope of after-sales service. Pricing pressure stems from the high capital investment required by end-users in developing economies. Diagnostic centers in India and Brazil are highly price-sensitive, while large hospitals in developed markets prioritize advanced features.
Supply Chain Analysis
Reverse logistics, including the refurbishment and remanufacturing of X-ray tubes and detectors, is gaining importance due to sustainability mandates and cost pressures. Geographic supply concentration for critical components like amorphous silicon flat panels centers on East Asia and Europe. The supply chain draws from specialized input providers for X-ray tubes and detector arrays. Regulatory restrictions, particularly CE marking requirements under Europe's MDR, represent a structural risk for manufacturers. Distribution runs primarily through direct sales forces and established medical equipment distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Digital X Ray Market operates as a supply-constrained story, primarily due to the specialized manufacturing capacity for advanced flat-panel detectors, which props up equipment pricing.
For Market Incumbents:Deepen strategic partnerships with large hospital networks to secure long-term procurement contracts, mitigating the threat from lower-cost emerging entrants. Invest in advanced AI-powered diagnostics to enhance product differentiation and maintain a competitive edge against technological obsolescence. Expand manufacturing capacity for critical components in key regions like Germany to reduce single-source vulnerability. Control distribution channels in emerging economies to capture market share.
For New Entrants and Emerging Players:A price-point gap exists between premium diagnostic centers and budget-conscious smaller clinics, offering an entry opportunity for cost-effective mobile systems. Target underpenetrated markets in Southeast Asia with portable DR solutions for basic diagnostic needs. Focus on user-friendly interfaces and robust after-sales support as a go-to-market angle. Develop systems optimized for veterinary applications, a smaller but expanding segment.
For Investors and Strategic Acquirers:Distressed-cycle entries favor regional specialists in Europe, particularly those with strong CE marking compliance, seeking to acquire firms with robust intellectual property. The long-term viability of the digital X-ray market remains strong over the next decade, driven by healthcare modernization. Acquisition targets should include companies with strong software integration capabilities or specialized detector technology. Practitioners should monitor changes in global regulatory harmonization for early signals of market shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in AI-Powered Diagnostics | Enhances diagnostic accuracy and workflow efficiency, reducing radiologist workload in hospitals. |
| Develop Portable DR Systems | Decentralizes diagnostic imaging, bringing services to emergency rooms and remote locations. | Secure Long-Term Hospital Contracts | Provides stable revenue streams and market access for established medical device vendors. |
| Expand Manufacturing in Key Regions | Mitigates supply chain risks and ensures component availability for global production. |
| Navigate Stringent Regulatory Pathways | Ensures market access and compliance with US FDA and Europe's MDR requirements. |
Research Approach
Document review covered regulatory filings from the US FDA, Europe's MDR, and China's NMPA, complemented by interviews with hospital purchasing managers, radiologists, medical device engineers, and regulatory affairs specialists. This approach combined primary insights with secondary validation across diverse data points. Bottom-up analysis of installed base data and top-down market sizing were triangulated for accuracy.
Market size and growth projections emerged from a comprehensive analytical framework, segmenting by product type, end user, technology, application, and regional regulatory cluster. Compound Annual Growth Rates were derived from historical data and projected forward based on identified growth catalysts and restraints. Key forecast inputs included healthcare spending trends and regulatory compliance costs across the analysis window.
Inputs from public financial reports and industry association data were available through the study window; gaps in real-time hospital procurement data introduce uncertainty bands around short-term volume forecasts. Forecasts reflect assumptions regarding technological advancements and healthcare policy stability. Practitioners should monitor changes in national healthcare spending for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Global Contrast-Enhanced Ultrasound Market
Medical Imaging
Enterprise Medical Image Viewers Market
Medical Imaging
Teleultrasound System Market
Medical Imaging
Image Guided Therapy Market
Medical Imaging
Perfusion Radiology Market
Medical Imaging
Mexico Digital Radiology Market
Medical Imaging
Magnetic Resonance Imaging (MRI) Equipment Market
Medical Imaging
Global Mobile Medical Imaging Services Market
Medical Imaging
Teleradiology Market
Medical Imaging
United Kingdom Mammography Market
Medical Imaging
Germany Nuclear Imaging Market
Medical Imaging
Malaysia Digital Radiography Market
Medical Imaging
Orthopedic Imaging Market
Medical Imaging
Asia-Pacific Intraoperative Imaging Market
Medical Imaging
Radiation Dose Management Market
Medical Imaging
Global Cardiac Imaging Software Market