
 Transradial Access Devices Market | 2026-2036
Transradial Access Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Transradial Access Devices Market Analysis
Silicone-coated introducers is decoupling legacy polyurethane economics in transradial access, trimming per-procedure material costs while improving thrombogenicity profiles. Merit Medical Systems leverages vertical integration across sheath manufacturing to sustain margin control in the United States. Terumo Corporation anchors Japanese production of hydrophilic-coated catheters, competing aggressively in European tenders. Boston Scientific Corporation specializes in integrated introducer-sheath systems, dominating cath lab bundled-procurement channels.
Transradial access devices constitute minimally invasive vascular entry instruments—typically 4-7 French sheaths, tapered introducers, and hydrophilic-coated catheters—engineered for wrist artery cannulation to deliver diagnostic and interventional tools to coronary, peripheral, and neurovascular beds. Catheters command the largest product-type revenue pool due to recurring procedural consumption, while advanced imaging technology within digital solutions represents the fastest-expanding segment as real-time ultrasound guidance reduces access failure rates. Application demand tilts heavily toward cardiology, though vascular surgery adoption is accelerating as radial approaches migrate to peripheral endovascular procedures.
FDA biocompatibility standards and ISO 10993 testing protocols govern material safety and lubricious coating durability, directly shaping R&D allocation and product clearance timelines for manufacturers. The EU MDR recertification burden is compressing supplier counts in Europe, advantaging firms with established notified-body relationships and clinical data repositories. Stakeholders must monitor reimbursement parity between radial and femoral approaches across national health systems, as payment differentials will determine whether transradial penetration advances beyond early-adopter institutions into standard-of-care territory.
Market Dynamics
Medicare reimbursement incentives for same-day discharge post-angioplasty are compressing hospital length-of-stay economics and forcing cath lab administrators to reevaluate access site protocols. This payment pressure is accelerating radial-first adoption across United States hospital systems.
Growth Catalysts
- Same-day discharge reimbursement:Medicare bundled payment models reward reduced hospital stays, making transradial approaches financially attractive for coronary interventions.
- Hydrophilic coating advances:Lubricious polymer technologies reduce vessel trauma and access failure rates, improving procedural throughput in busy interventional suites.
- Cardiology department expansion:Hospital systems are building dedicated transradial programs with specialized nursing protocols and wrist-specific recovery protocols.
Market Restraints
- Silicone raw material concentration:Medical-grade silicone supply chains concentrate among a limited set of chemical suppliers, creating input cost volatility for coated device manufacturers.
- Learning curve barriers:Operator proficiency in radial artery cannulation requires substantial case volume, slowing adoption at low-volume community hospitals.
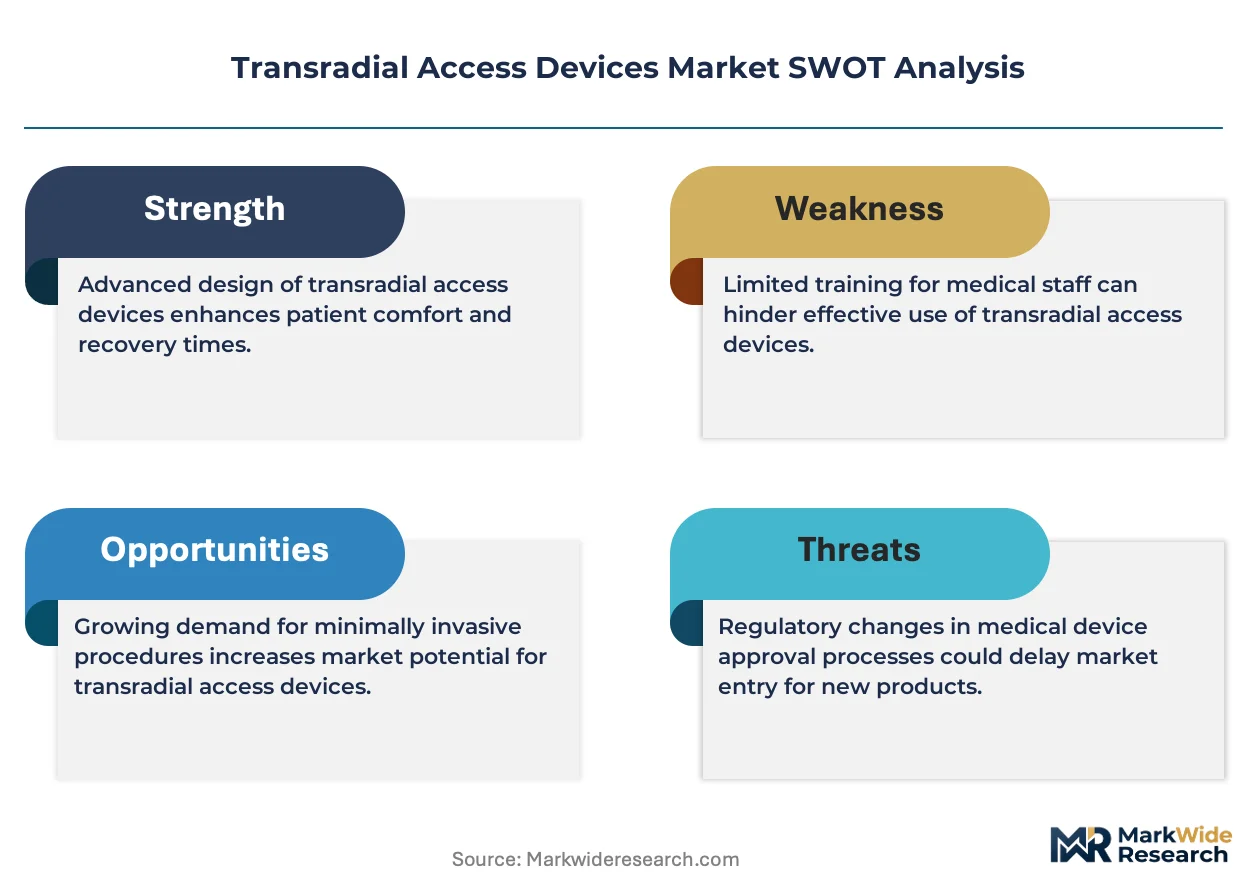
- FDA biocompatibility testing timelines:Extended ISO 10993 validation protocols delay product clearances and compress commercialization windows for novel coating formulations.
Strategic Opportunities
- Peripheral vascular migration:Radial access for lower-extremity endovascular procedures remains underdeveloped, offering procedural expansion beyond coronary applications.
- Real-time ultrasound guidance:Integration of portable imaging systems with access kits reduces failure rates and opens ambulatory surgery center channels.
- EU MDR recertification consolidation:Smaller competitors face notified-body capacity constraints, creating acquisition opportunities for firms with established clinical data repositories.
Industry Challenges
- Specialized nursing workforce gaps:Transradial programs require dedicated recovery protocols and hemostasis management skills that standard cath lab staff often lack.
- Legacy femoral infrastructure:Existing cath lab layouts and compression device inventories create capital reallocation friction for hospitals transitioning to radial-first workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transradial Access Devices Market |
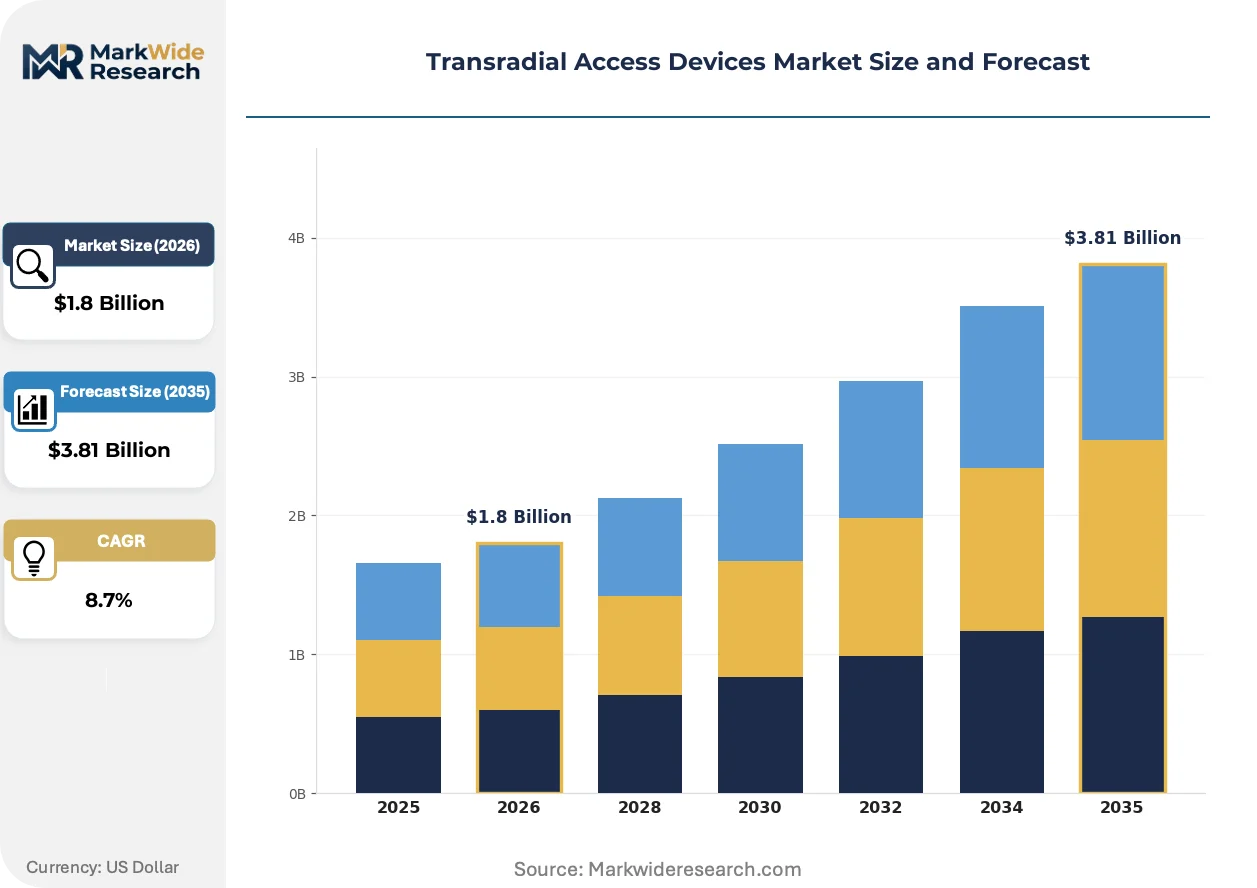
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Catheters, Sheaths, Introducers, Accessories Application: Cardiology, Radiology, Vascular Surgery, Interventional Procedures End User: Hospitals, Clinics, Ambulatory Surgical Centers, Research Institutes Technology: Single-Use Devices, Reusable Devices, Advanced Imaging, Digital Solutions |
| Companies Covered | Becton Dickinson and Company, Merit Medical Systems, Terumo Corporation, AngioDynamics, Edwards Lifesciences Corporation, Medtronic, Teleflex Incorporated, Nipro Medical Corporation, Boston Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transradial Access Devices Market Emerging Trajectories
Digital imaging convergence with vascular access hardware is compressing procedure times and reducing complication rates. Three interconnected developments are reshaping how devices are designed, procured, and deployed.
Ultrasound-guided access technology is integrating real-time vessel visualization directly into sheath introducer systems. Interventional cardiologists at high-volume United States centers are adopting these hybrid platforms rapidly. The technology is integrating previously separate imaging and access workflows into single-procedure efficiency gains.
EU MDR recertification requirements are elevating clinical data burdens for hydrophilic coating durability claims. Manufacturers must now submit extended biocompatibility surveillance data to maintain CE marking. European notified bodies are prioritizing reviews for firms with pre-existing ISO 10993 master files, compressing competitive timelines.
Hospital procurement teams are unbundling device bundles and negotiating sheath-introducer-catheter combinations separately. Cath lab administrators at integrated delivery networks now source components through direct manufacturer contracts rather than distributor tiers. This pattern is most visible in United States health systems with centralized supply chain governance.
Transradial Access Devices Market Segmentation
Transradial access device procurement patterns diverge sharply across clinical settings and technology tiers. Understanding these fault lines reveals where margin pools concentrate and which specifications drive purchasing decisions.
Product Type:
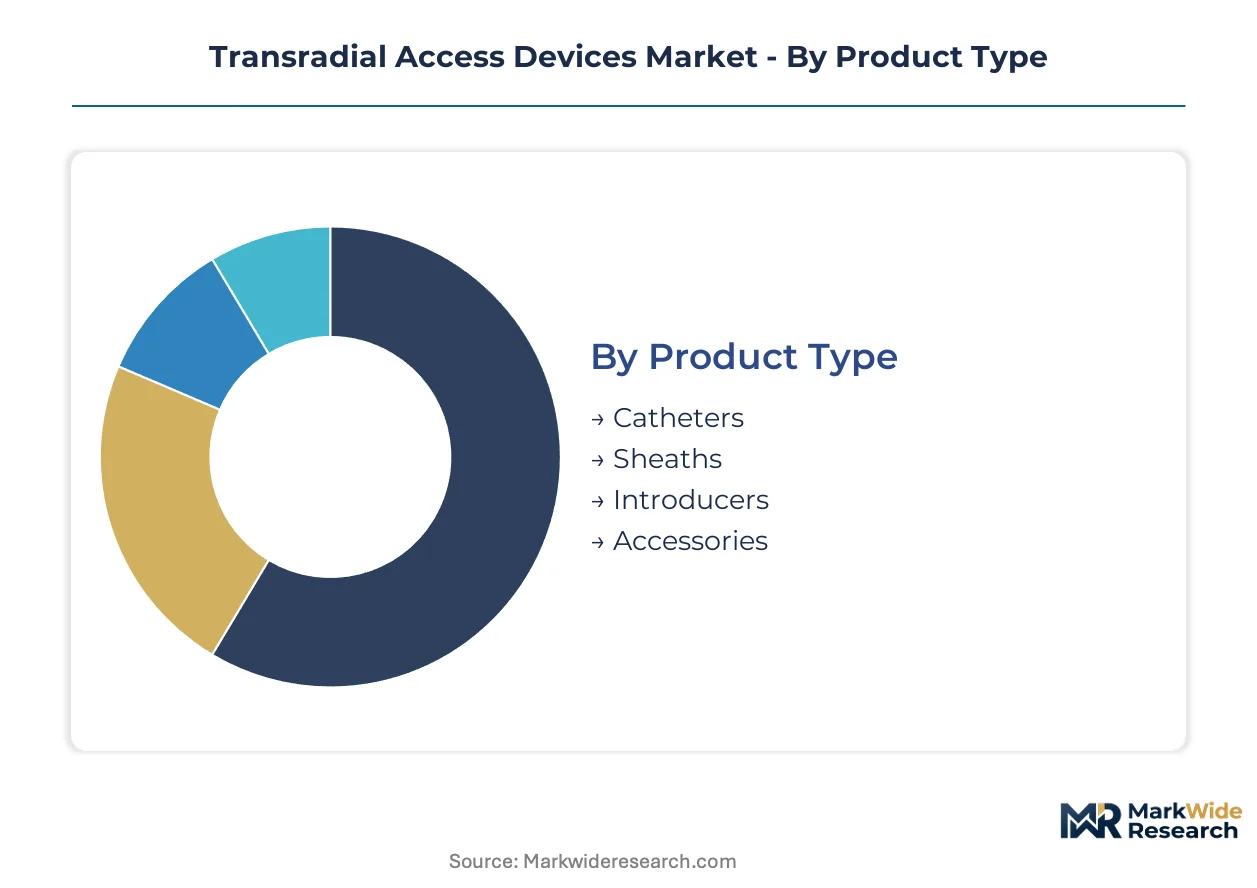
Catheter manufacturing absorbs disproportionate silicone and hydrophilic coating capacity, locking suppliers into long-term polymer supply agreements.
- Catheters:Hydrophilic-coated delivery instruments in 4-7 French configurations dominate procedural consumption. Demand concentrates in high-volume United States cardiac catheterization laboratories where same-day discharge protocols mandate reliable radial artery navigation.
- Sheaths:Tapered radial entry devices with integrated hemostasis valves anchor procedural workflows. Japanese and German manufacturers control specialty thin-wall extrusion capacity, constraining supply expansion for competing vendors.
- Introducers:Silicone-coated entry tools reduce vessel trauma during initial cannulation.
- Accessories:Compression bands and closure devices complete procedural kits.
Catheters absorb the bulk of installed capacity; advanced imaging integration is expanding most quickly.
Application:
Procedure reimbursement differentials determine which clinical specialties can justify dedicated radial program investments.
- Cardiology:Coronary angiography and percutaneous coronary intervention constitute the procedural foundation. United States Medicare bundled payments for same-day discharge create direct financial incentives for radial-first protocols in hospital-owned cath labs.
- Interventional Procedures:Structural heart interventions and complex PCI require specialized catheter configurations. European centers in Germany and the Netherlands lead adoption curves for transradial transcatheter aortic valve replacement.
- Radiology:Diagnostic neuroangiography and peripheral runoff studies utilize radial access for patient comfort.
- Vascular Surgery:Lower-extremity endovascular procedures represent an emerging application with unstandardized protocols.
Cardiology commands the dominant revenue share; interventional procedures are climbing the fastest as structural heart volumes expand.
End User:
Capital intensity and regulatory compliance burdens stratify the customer base into distinct procurement segments.
- Hospitals:Integrated delivery networks with centralized supply chain governance negotiate direct manufacturer contracts for sheath-introducer-catheter bundles. These institutions maintain dedicated transradial nursing protocols and wrist-specific recovery infrastructure.
- Ambulatory Surgical Centers:Freestanding interventional facilities prioritize disposable kit simplicity and rapid turnover. Real-time ultrasound guidance integration reduces access failure rates, supporting migration of select procedures outside hospital walls.
- Clinics:Office-based labs face reimbursement constraints that limit radial program development.
- Research Institutes:Academic medical centers drive protocol innovation and training curriculum development.
Hospitals retain the dominant installed base; ambulatory surgical centers are gaining share fastest as site-of-service payment differentials widen.
Technology:
Regulatory clearance timelines and clinical evidence requirements separate mature disposable categories from emerging digital platforms.
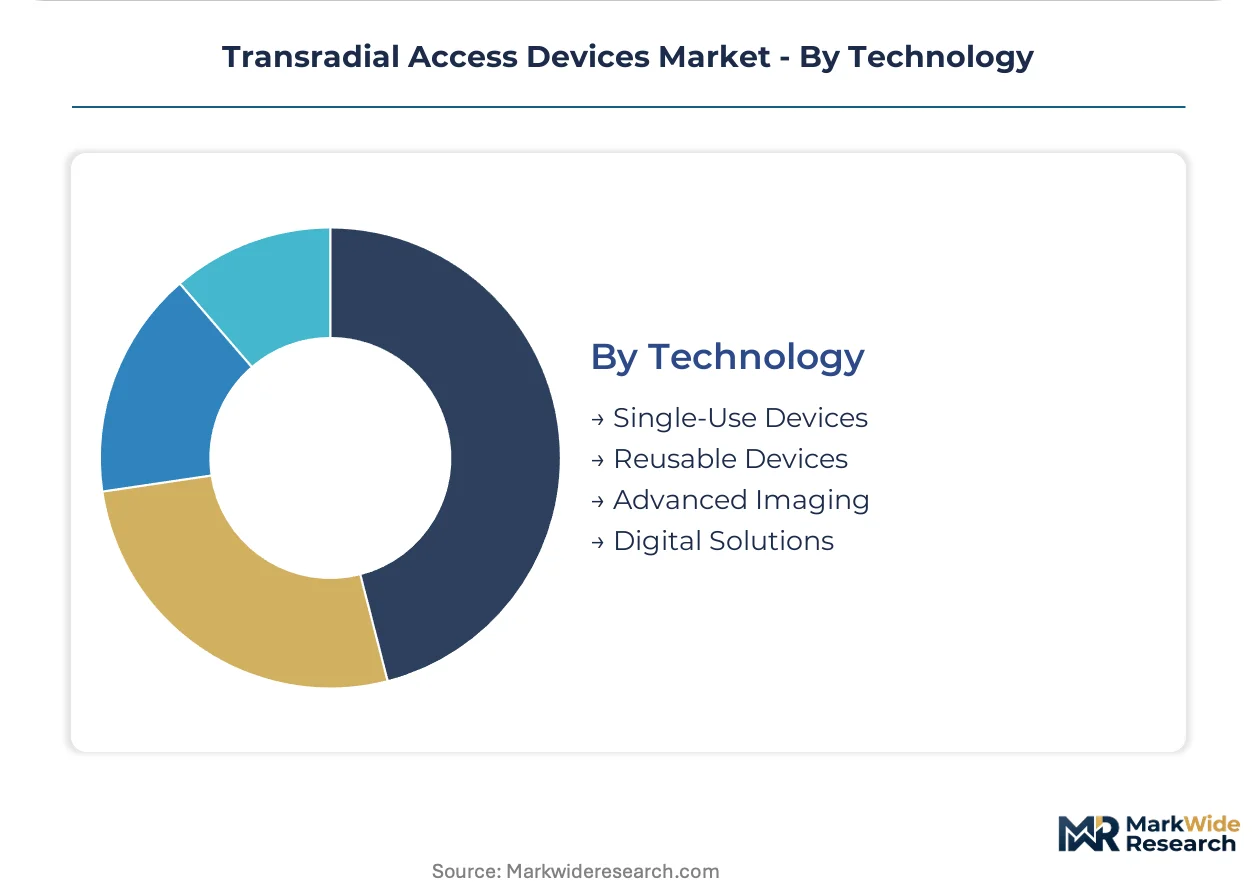
- Single-Use Devices:Sterile-packaged sheaths, catheters, and introducers dominate commercial volumes. FDA biocompatibility testing under ISO 10993 protocols governs coating durability claims and material safety validation.
- Advanced Imaging:Portable ultrasound systems integrated with access kits reduce first-attempt failure rates. United States high-volume centers are adopting these hybrid platforms rapidly as separate imaging and access workflows merge.
- Reusable Devices:Limited to capital equipment like imaging consoles and pressure monitoring systems.
- Digital Solutions:Procedure documentation and inventory management software support operational efficiency.
Single-use devices command the prevailing revenue pool; advanced imaging represents the steepest expansion trajectory as real-time guidance becomes standard of care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospital systems concentrate the most acute demand for transradial access devices, driven by Medicare reimbursement structures that reward same-day discharge protocols. This payment environment has compressed length-of-stay economics and accelerated radial-first adoption curves across integrated delivery networks.
United States
Medicare bundled payment models for coronary angioplasty create direct financial incentives for radial approaches over femoral access. FDA biocompatibility standards under ISO 10993 govern silicone-coated and hydrophilic material clearances, extending validation timelines for novel coating formulations. High-volume cardiac catheterization laboratories in the Cleveland Clinic and Mayo Clinic systems anchor specialized transradial nursing protocols and wrist-specific recovery infrastructure.
Germany
Structural heart intervention volumes drive catheter consumption at centers performing transradial transcatheter aortic valve replacement. EU MDR recertification requirements under the Medical Device Regulation elevate clinical data burdens for hydrophilic coating durability claims. The Rhine-Ruhr metropolitan region hosts concentrated cath lab networks negotiating direct manufacturer contracts for sheath-introducer bundles.
Japan
Terumo Corporation anchors domestic production of hydrophilic-coated catheters, supplying regional demand for coronary and peripheral procedures. PMDA regulatory frameworks align with international ISO standards while maintaining distinct documentation requirements for coating biocompatibility. The Kansai region around Osaka maintains specialized thin-wall extrusion capacity for tapered radial entry devices.
Netherlands
European tender processes for interventional cardiology supplies concentrate procurement decisions at national health system levels. EMA coordination with notified bodies streamlines CE marking pathways for firms with established clinical data repositories. The Randstad conurbation houses university medical centers leading protocol innovation for radial access in complex PCI cases.
China
Domestic hospital system expansion of interventional cardiology departments drives volume demand for cost-optimized access kits. NMPA regulatory pathways for imported devices require local clinical trials, compressing commercialization windows for foreign manufacturers. The Yangtze River Delta medical device manufacturing cluster supports contract production of silicone-coated introducers for regional distribution.
Transradial Access Devices Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated device companies controlling bundled-procurement channels while component suppliers serve distributor tiers. The vendor base concentrates around three strategic archetypes: vertically integrated sheath manufacturers, hydrophilic coating technology specialists, and cath lab workflow integrators. M&A activity targets notified-body relationships and clinical data repositories under EU MDR pressure. Geographic expansion into ambulatory surgery center channels represents the second dominant competitive vector.
Among United States-based integrated device companies, Merit Medical Systems and Boston Scientific Corporation exemplify the cath lab workflow integrator archetype, occupying positions where bundled-procurement negotiations favor direct manufacturer contracts over distributor intermediaries. Terumo Corporation anchors the hydrophilic coating technology specialist tier, with its Japanese manufacturing base supporting competitive positioning in European tender processes. These three entities represent distinct strategic postures: backward integration into sheath extrusion, integrated introducer-sheath system specialization, and coating chemistry expertise respectively.
| Leading Market Players |
|---|
| Becton Dickinson and Company |
| Merit Medical Systems |
| Terumo Corporation |
| AngioDynamics |
| Edwards Lifesciences Corporation |
| Medtronic |
| Teleflex Incorporated |
| Nipro Medical Corporation |
| Boston Scientific Corporation |
| Others |
Supply Flow & Price Mechanics
ISO 10993 certification tiers bifurcate transradial access device procurement, with FDA-cleared hydrophilic coating formulations commanding substantial premiums over standard silicone-coated alternatives while thin-wall extrusion capacity constraints in Japan and Germany lock supply into long-term polymer allocation agreements that prop pricing power for incumbent manufacturers.
Pricing Analysis
High-volume catheter consumption runs on thin margins while integrated sheath-introducer systems retain pricing power. Three-tier pricing structure across premium hydrophilic-coated, standard silicone-coated, and economy bare-polymer levels separates academic medical centers from community hospitals from cost-optimized ambulatory surgery centers. Pricing pressure stems from Medicare bundled payment compression forcing cath lab administrators toward unbundled component sourcing. Ambulatory surgery centers exhibit highest price sensitivity; integrated delivery networks with direct manufacturer contracts show lowest.
Supply Chain Analysis
Specialized thin-wall extrusion technician shortages in Osaka and Munich constrain radial sheath production expansion. Medical-grade silicone feedstock draws from concentrated chemical suppliers in Germany and Japan, while hydrophilic coating polymer synthesis rests on proprietary Japanese and United States chemical platforms. Single-source vulnerability pervades specialty thin-wall extrusion equipment. Distribution runs through GPO contracts and direct manufacturer agreements with integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thin-wall extrusion capacity scarcity props pricing across sheath manufacturing tiers, with qualified technician pipelines constituting the binding constraint preventing supply response to demand acceleration.
For Market Incumbents: Extend coating chemistry R&D investment to differentiate hydrophilic durability claims ahead of EU MDR recertification deadlines, while consolidating notified-body relationships to compress competitor clearance timelines. Threat of emerging Asian contract manufacturers with NMPA pathway experience demands preemptive capacity addition in United States and European production footprints. For New Entrants and Emerging Players: Ambulatory surgery center channels offer the most penetrable entry vector given procurement simplicity requirements and ultrasound-guidance integration demand. Target peripheral vascular radial migration protocols as procedural expansion white space. Go-to-market through disposable kit bundling with portable imaging OEMs bypasses entrenched GPO contract structures. For Investors and Strategic Acquirers: Re-rating potential sits with hydrophilic coating technology specialists given EU MDR clinical data repository scarcity and European tender process consolidation. Long-term viability frames around 5-10 year procedural volume trajectories as radial-first protocols standardize. Signal to watch: Medicare reimbursement parity expansion beyond coronary into peripheral vascular applications.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Clinical Data Repository Buildout | Accelerates CE marking timelines for hydrophilic coating durability claims against notified-body capacity constraints. |
| Peripheral Vascular Protocol Development | Opens procedural expansion beyond coronary applications into lower-extremity endovascular radial access. |
| Real-Time Ultrasound Integration Partnership | Merges imaging and access workflows for ambulatory surgery center channel penetration. |
| Thin-Wall Extrusion Capacity Expansion | Addresses qualified technician scarcity constraining Japanese and German sheath manufacturing output. |
| Direct Manufacturer Contract Negotiation | Bypasses distributor tiers for integrated delivery network procurement consolidation in United States health systems. |
Methodological Framework
Multi-period observation of Medicare reimbursement policy shifts, FDA 510(k) clearance timelines, and EU MDR notified-body queue lengths anchored the trend analysis, supplemented by interviews with interventional cardiologists, cath lab administrators, biomedical engineers, and GPO contracts managers. Secondary validation drew from FDA 510(k) databases, CMS Medicare claims data, European tender documentation, and ISO 10993 master file registries. Bottom-up procedural volume modeling triangulated against top-down manufacturer revenue estimates.
Segment-weighting applied product-type splits across catheter, sheath, introducer, and accessory categories, with technology tier differentiation between single-use disposables and advanced imaging platforms, and end-user stratification across hospitals, ambulatory surgical centers, clinics, and research institutes. CAGRs derived from logistic growth curve fitting to procedural adoption S-curves, with inputs including operator training pipeline capacity, same-day discharge protocol expansion rates, and hydrophilic coating formulation innovation cycles.
Caveats apply where FDA biocompatibility testing timeline extensions, medical-grade silicone supply disruptions, or Medicare reimbursement category redefinitions could materially shift the outlook. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Implantable Defibrillators Market
Medical Devices
Global Nasal Cannula Market
Medical Devices
Platelet Concentration Systems Market
Medical Devices
US Medical Display Monitors Market
Medical Devices
Global Pediatric Medical Devices Market
Medical Devices
Global Gynecology Robotic Surgery Market
Medical Devices
Global Non-Surgical Skin Tightening Devices Market
Medical Devices
Artificial Eye Lenses Market
Medical Devices
Magnetic Ablation Catheter Market
Medical Devices
Digital Impression System Market
Medical Devices
MIS Sacroiliac Joint Fusion Market
Medical Devices
Bone Growth Stimulators Market
Medical Devices
Concentrator O2 Devices Market
Medical Devices
Medical Pendant Market
Medical Devices
Home Dialysis Systems Market
Medical Devices
Diode Laser Aesthetic Medical Device Market