
 Medical Puncture Navigation Robot Market | 2026-2036
Medical Puncture Navigation Robot Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Puncture Navigation Robot Market Insights
China is rewriting competitive dynamics in surgical robotics through state-backed manufacturing zones and dedicated med-tech industrial parks. Medtronic leverages its spine and navigation heritage to extend hardware-software integration across interventional suites. Stryker sustains orthopedic-to-surgical cross-selling through its installed base of navigation platforms. Intuitive Surgical anchors the field with da Vinci-trained surgeon networks that lower adoption friction for emerging puncture systems.
A medical puncture navigation robot integrates electromechanical actuators, real-time imaging feedback, and closed-loop control algorithms to guide needles or catheters to anatomical targets with sub-millimeter accuracy, primarily serving minimally invasive diagnostic and therapeutic procedures. Robotic Assistance technology leads installed value due to capital intensity and recurring instrument revenue, while Artificial Intelligence integration represents the fastest-expanding capability layer as vendors train models on procedural imaging archives. Control Software captures disproportionate margin pools relative to hardware given subscription pricing and regulatory lock-in effects.
FDA 510(k) and de novo pathways shape US market entry timelines for autonomous needle steering functions, while the EU MDR and CE marking framework impose clinical evidence requirements that favor established players with post-market surveillance infrastructure. China's NMPA has accelerated review tracks for domestically manufactured surgical robots under innovation-device programs. Stakeholders must weigh regulatory jurisdiction sequencing against reimbursement parity timelines when allocating clinical trial capital.
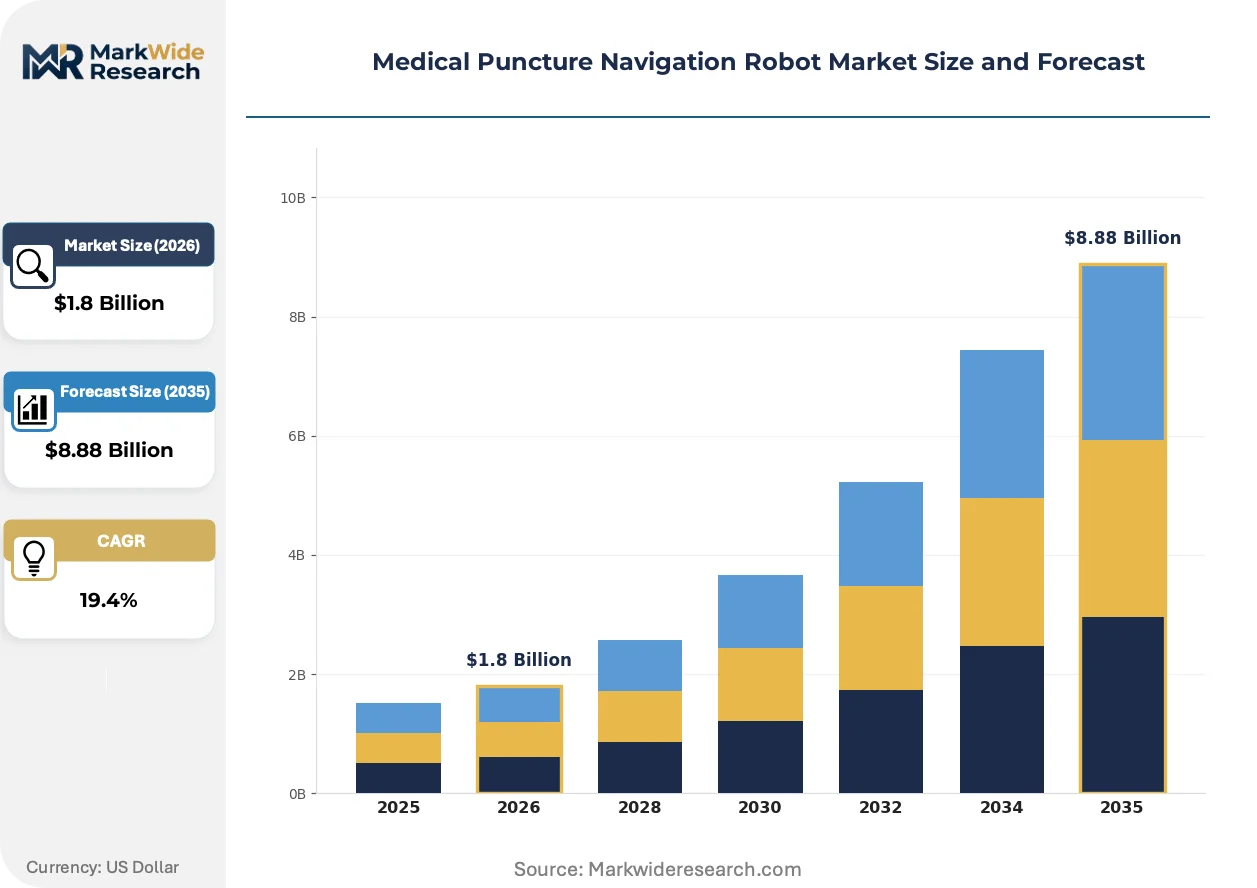
Market Dynamics
FDA 510(k) clearance compression for autonomous needle steering functions is accelerating developer time-to-market while EU MDR clinical evidence requirements favor established players with post-market surveillance infrastructure, creating divergent competitive entry conditions across regulatory jurisdictions.
Growth Catalysts
- Minimally Invasive Surgery Mandates:Hospital reimbursement policies in Germany and Japan now prioritize outpatient biopsy procedures, driving capital allocation toward robotic puncture systems that reduce length-of-stay metrics.
- Real-Time Imaging Convergence:Integration of intraoperative CT and MRI feedback loops with electromechanical actuators enables sub-millimeter targeting accuracy previously unattainable with freehand techniques.
- Surgeon Training Network Effects:da Vinci-certified physician pools in the United States lower adoption friction for emerging puncture platforms through transferable console navigation skills.
Market Restraints
- Capital Equipment Intensity:Robotic biopsy systems require seven-figure upfront investment plus recurring instrument revenue commitments that strain mid-tier hospital capital budgets.
- Supply Concentration Risk:Precision motion control components and high-torque surgical motors concentrate among German and Japanese component suppliers, exposing assemblers to lead-time volatility.
- Regulatory Friction:EU MDR post-market surveillance obligations impose documentation burdens that extend certification timelines for novel autonomous navigation features beyond historical CE-marking windows.
Strategic Opportunities
- Underpenetrated Ambulatory Settings:Freestanding surgical centers in Texas and Florida lack robotic biopsy capacity despite high prostate and lung screening volumes, creating greenfield installation potential.
- NMPA Innovation Tracks:China's accelerated review pathways for domestically manufactured surgical robots compress regulatory timelines versus standard NMPA procedures, rewarding localized production commitments.
- AI-Assisted Trajectory Planning:Machine learning models trained on institutional imaging archives enable predictive needle deflection compensation, differentiating next-generation platforms from hardware-only competitors.
Industry Challenges
- Interventional Radiologist Scarcity:Fellowship-trained physicians capable of supervising robotic biopsy procedures remain concentrated at academic medical centers, limiting deployment to community hospitals.
- Legacy PACS Integration Complexity:Robotic navigation systems require DICOM interoperability with existing radiology infrastructure, forcing costly middleware development or rip-and-replace scenarios.
- Reimbursement Parity Delays:CMS and private payors maintain separate coding for manual versus robotic-assisted biopsies, creating margin pressure until Category III codes achieve Category I status.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Puncture Navigation Robot Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.88 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Navigation Systems, Electromechanical Sensors, Imaging Equipment, Control Software End User: Hospitals, Surgical Centers, Diagnostic Labs, Research Institutions Technology: 3D Imaging, Robotic Assistance, Artificial Intelligence, Machine Learning Application: Biopsy Procedures, Catheter Insertions, Medical Imaging, Surgical Interventions |
| Companies Covered | Medtronic, Stryker, Intuitive Surgical, Perfint Healthcare, iSYS Medizintechnik, NDR Medical Technology, MicroPort MedBot, Quantum Surgical, Robocath, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Puncture Navigation Robot Market Trends and Innovations
Digital twin technology is virtualizing preoperative planning workflows while regulatory bodies on three continents simultaneously tighten software-as-medical-device classifications, reshaping how vendors architect control systems and validate algorithmic outputs.
Electromagnetic tracking systems with dynamic reference arrays are virtualizing patient registration protocols, eliminating the need for rigid stereotactic frames during cranial and spinal puncture procedures. University hospitals in Switzerland and South Korea are piloting frameless navigation for deep-brain biopsy applications. The technology is virtualizing capital allocation away from fixed-frame infrastructure toward software-subscription revenue models.
EU MDR Article 10 software classification requirements now capture AI-enabled trajectory planning modules as standalone medical devices, forcing vendors to maintain parallel technical documentation for hardware and algorithmic components. This regulatory expansion particularly affects control software vendors who previously operated under lower-evidence pathways. German notified bodies are responding with specialized review tracks for machine-learning-enabled surgical robots.
Hospital procurement committees now unbundle capital acquisition from multi-year service contracts, compressing vendor pricing power and shifting margin capture toward disposable instrument revenue. This behavioral shift is most visible in the United States, where IDN consolidation has centralized robotic platform decisions to system-level value analysis committees. Independent community hospitals increasingly lease rather than purchase puncture navigation systems to preserve balance-sheet flexibility.
Medical Puncture Navigation Robot Market Segmentation
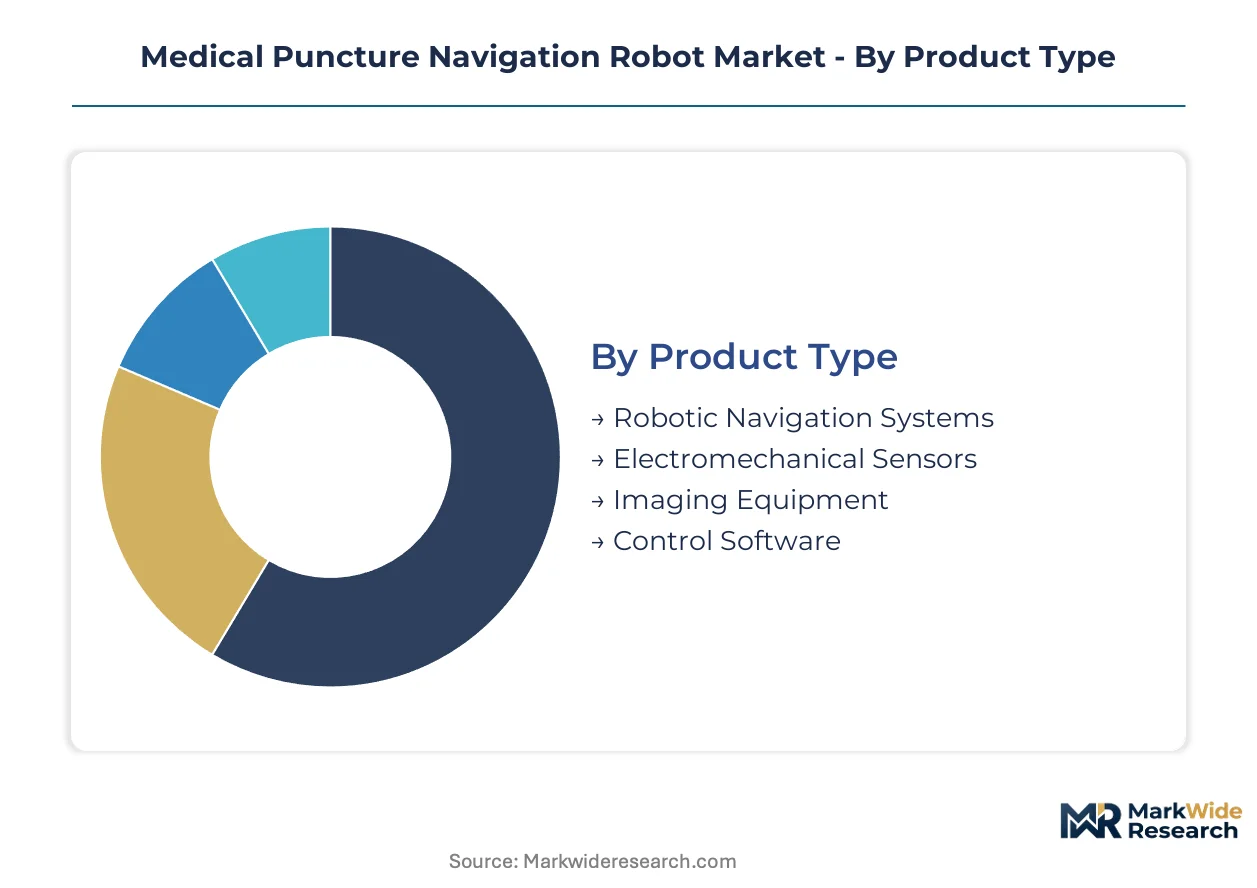
Segmentation in the medical puncture navigation robot market reveals distinct value pools across hardware, software, and service layers. Procurement patterns diverge sharply between capital-intensive hospital systems and lean ambulatory operators, while technology integration depth separates premium platforms from commodity alternatives.
Product Type:
The use-case spectrum spans intraoperative hardware deployment through cloud-based algorithmic services, with margin capture concentrating in recurring revenue streams rather than one-time equipment sales.
- Robotic Navigation Systems:Capital equipment integrating electromechanical actuators with real-time imaging feedback loops. Demand concentrates at academic medical centers in Germany and Japan where fellowship-trained interventional radiologists supervise complex cranial and spinal procedures.
- Control Software:Subscription-licensed platforms enabling trajectory planning, needle deflection compensation, and DICOM interoperability with legacy PACS infrastructure. Surgical centers in Texas and Florida prioritize this segment to extend hardware utility without full system replacement.
- Electromechanical Sensors:High-precision motion feedback components manufactured by concentrated German and Japanese suppliers.
- Imaging Equipment:Intraoperative CT and MRI integration modules for sub-millimeter targeting accuracy.
Established volume favors Robotic Navigation Systems; emerging adoption favors Control Software.
End User:
Customer archetypes range from balance-sheet-constrained community hospitals to IDN-affiliated surgical centers with centralized procurement authority.
- Hospitals:Primary deployment sites for integrated robotic biopsy systems, particularly university hospitals anchoring clinical validation programs. German institutions lead validation throughput for next-generation autonomous navigation features.
- Surgical Centers:Freestanding facilities in high-screening-volume regions pursuing minimally invasive outpatient procedures. Centers in Florida and Texas represent greenfield installation potential given reimbursement prioritization of reduced length-of-stay metrics.
- Diagnostic Labs:Specialized operators requiring puncture navigation for image-guided tissue acquisition.
- Research Institutions:Early-stage technology evaluators piloting frameless electromagnetic tracking for deep-brain applications.
Capital intensity restricts Hospitals to multi-year lease structures; Surgical Centers drive fastest expansion through subscription-based access models.
Technology:
Capability layers stack from foundational imaging through predictive algorithmic control, with regulatory classification complexity rising at each tier.
- Robotic Assistance:Electromechanical guidance systems generating recurring instrument revenue through proprietary consumable lock-in. FDA 510(k) clearance compression accelerates developer time-to-market for autonomous needle steering functions.
- Artificial Intelligence:Machine learning models trained on institutional imaging archives enabling predictive needle deflection compensation. EU MDR Article 10 now captures AI-enabled trajectory planning as standalone medical devices, forcing parallel technical documentation.
- 3D Imaging:Intraoperative visualization backbone for real-time anatomical targeting.
- Machine Learning:Algorithmic refinement layer for procedural optimization and outcome prediction.
Hardware margins dominate current revenue; AI integration climbs the fastest toward disproportionate margin pools.
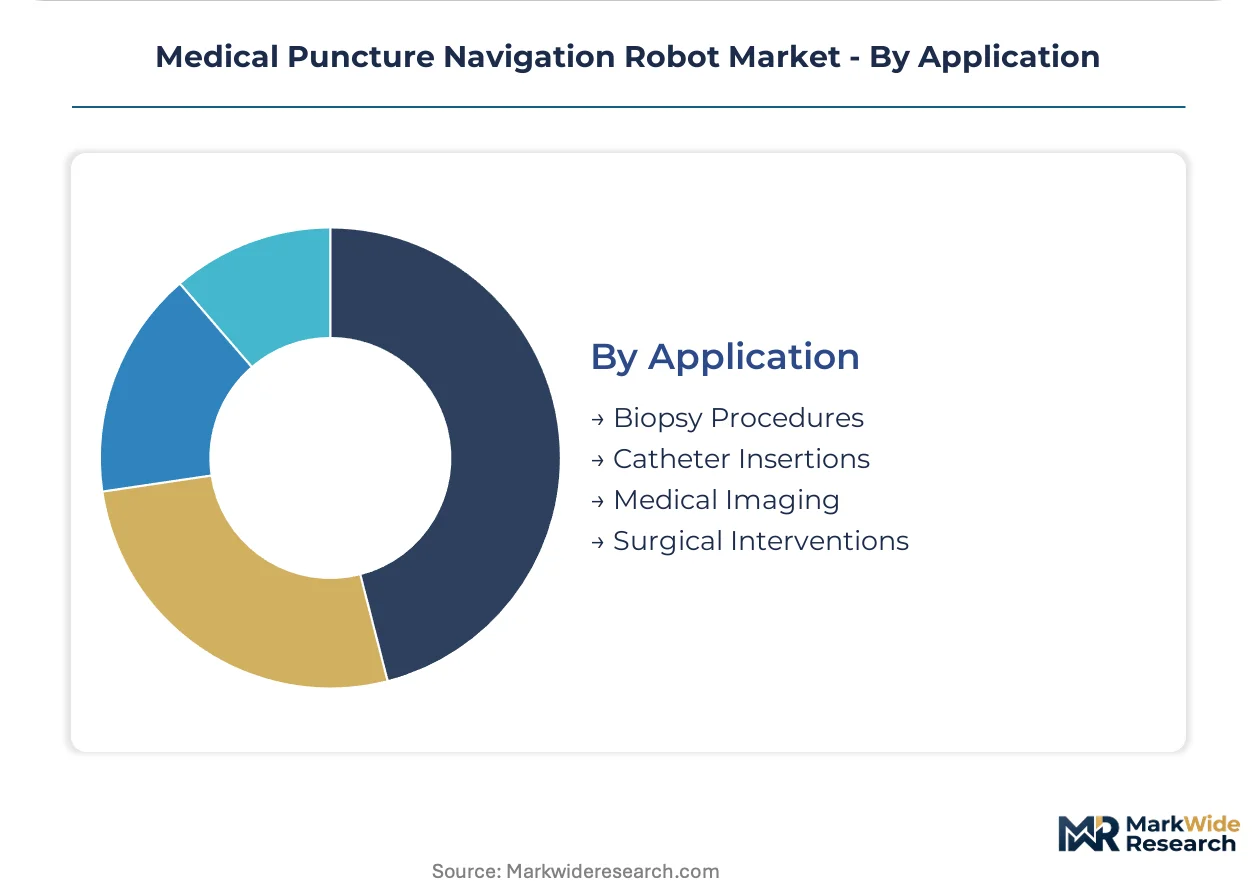
Application:
Procedural breadth extends from diagnostic tissue acquisition through therapeutic catheter delivery, with reimbursement coding status determining commercial viability.
- Biopsy Procedures:Core diagnostic application for robotic puncture navigation, spanning prostate, lung, and cranial targets. CMS maintains separate coding for manual versus robotic-assisted biopsies, creating margin pressure until Category III codes achieve Category I status.
- Surgical Interventions:Therapeutic deployment including ablation and localized drug delivery. Swiss and South Korean university hospitals pilot frameless navigation for deep-brain procedures, virtualizing capital allocation toward software-subscription models.
- Catheter Insertions:Vascular and non-vascular access procedures requiring sub-millimeter trajectory precision.
- Medical Imaging:Image-guided navigation support for radiology workflow integration.
Reimbursement parity delays constrain Biopsy Procedures; Surgical Interventions gain share fastest through outcome-based contracting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA clearance pathways anchor the United States as the dominant geography, with EU MDR timelines and China's NMPA innovation tracks creating divergent entry conditions for developers of autonomous needle steering systems.
United States
Hospital procurement committees at IDN-affiliated systems in Texas and Florida prioritize outpatient biopsy procedures that reduce length-of-stay metrics. FDA 510(k) compression for autonomous navigation features accelerates developer time-to-market versus historical de novo windows. The Greater Boston cluster anchors clinical validation programs for next-generation puncture robots through partnerships with academic medical centers.
Germany
University hospitals in Bavaria and North Rhine-Westphalia anchor clinical validation throughput for frameless electromagnetic tracking systems. EU MDR Article 10 software classification requirements impose parallel technical documentation burdens for AI-enabled trajectory planning modules. The Baden-Württemberg industrial corridor concentrates precision motion control component suppliers serving electromechanical actuator manufacturers.
China
State-backed manufacturing zones in the Yangtze River Delta and Pearl River Delta rewrite competitive dynamics through dedicated med-tech industrial parks. NMPA accelerated review tracks for domestically manufactured surgical robots compress regulatory timelines versus standard procedures. Beijing-Tianjin-Hebei anchors pilot programs for AI-assisted trajectory planning trained on institutional imaging archives.
Japan
METI reimbursement policies now prioritize minimally invasive outpatient procedures, driving capital allocation toward robotic puncture systems at surgical centers in Osaka and Nagoya. PMDA regulatory frameworks align with MDR evidence requirements, favoring established players with post-market surveillance infrastructure. The Kanto region concentrates fellowship-trained interventional radiologists capable of supervising complex cranial and spinal procedures.
Switzerland
Swissmedic oversight of software-as-medical-device classifications tightens validation requirements for algorithmic control systems. University hospitals in Zurich and Geneva pilot frameless navigation for deep-brain biopsy applications, virtualizing capital allocation toward software-subscription revenue models. The Basel industrial cluster supports precision sensor manufacturing for sub-millimeter targeting accuracy.
Medical Puncture Navigation Robot Market Competitive Landscape
Integrated platform vendors and component specialists split the market into capability-driven tiers. Consolidation pressure concentrates among hardware-software integrators with navigation heritage, while modular software vendors capture disproportionate margin pools through subscription pricing. Three archetypes dominate: capital equipment incumbents extending installed bases, AI-native challengers training models on procedural archives, and precision component suppliers anchoring electromechanical supply chains. Competitive moves center on strategic partnerships for imaging interoperability and backward integration into motion control manufacturing.
Within the integrated platform tier, Medtronic and Stryker occupy positions shaped by spine and orthopedic navigation heritage that extends across interventional suites. Intuitive Surgical exemplifies the console-navigation archetype through da Vinci-trained surgeon networks that lower adoption friction for emerging puncture systems. Among Asia-Pacific challengers, MicroPort MedBot represents the state-backed manufacturing archetype leveraging NMPA innovation tracks to compress regulatory timelines.
| Leading Market Players |
|---|
| Medtronic |
| Stryker |
| Intuitive Surgical |
| Perfint Healthcare |
| iSYS Medizintechnik |
| NDR Medical Technology |
| MicroPort MedBot |
| Quantum Surgical |
| Robocath |
| Others |
Pricing and Supply Chain Analysis
The Baden-Württemberg industrial corridor concentrates precision motion control component suppliers whose capacity utilization directly shapes downstream pricing power for electromechanical actuator manufacturers serving robotic biopsy system assemblers.
Pricing Analysis
US-Germany price spreads of 15-25% reflect divergent regulatory compliance costs and service bundling intensity. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared autonomous navigation platforms from CE-marked manual systems and unlicensed research configurations. Cost compression in mid-tier hospital segments is intensifying because IDN procurement committees unbundle capital acquisition from multi-year service contracts. Community hospitals exhibit highest price sensitivity due to balance-sheet constraints, while academic medical centers prioritize outcome metrics over acquisition cost.
Supply Chain Analysis
High-torque surgical motors and precision encoders draw from concentrated manufacturing bases in Germany, Japan, and Switzerland. Raw material dependencies span rare-earth magnets for motor assemblies, medical-grade aluminum alloys for structural frames, and specialized optical glass for imaging calibration. Single-source vulnerability concentrates in electromagnetic tracking sensor arrays produced by two Swiss component specialists. Distribution runs through authorized distributor networks serving hospital procurement committees and surgical center leasing consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from AI-native software vendors whose trajectory planning modules threaten to commoditize hardware-only platforms through cloud-based deployment models.
For Market Incumbents: Pre-empt software-as-medical-device classification by accelerating parallel technical documentation for AI-enabled control modules under EU MDR Article 10. Anchor backward integration into precision motion control manufacturing to reduce exposure to German and Japanese supplier lead-time volatility. Defend against modular software challengers by embedding proprietary instrument lock-in through disposable needle guidance consumables.
For New Entrants and Emerging Players: Freestanding surgical centers in Florida and Texas represent the most penetrable deployment channel given reimbursement prioritization of reduced length-of-stay metrics and absence of incumbent installed base. Target ambulatory settings through subscription-based access models that preserve customer balance-sheet flexibility. Accelerate NMPA innovation-track submissions for domestically manufactured systems to compress regulatory timelines versus standard procedures.
For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because hardware-software integration depth determines sustainable margin capture in an environment where pure software vendors face escalating regulatory documentation burdens. Target acquisition candidates with FDA-cleared autonomous navigation features and established hospital system partnerships. Monitor CMS Category III-to-Category I coding transitions as the critical inflection signal for reimbursement parity and margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission for Autonomous Needle Steering | Accelerates market entry timelines versus de novo pathways for robotic biopsy platforms. |
| CE Marking Pathway Under EU MDR Article 10 | Captures software-as-medical-device revenue streams through parallel hardware-algorithm documentation. |
| Hospital System Partnership for Clinical Validation | Generates procedural imaging archives essential for training predictive needle deflection models. |
| Software Companion Development for Legacy PACS | Resolves DICOM interoperability barriers that constrain deployment to community hospital settings. |
| Reimbursement Strategy for Category III Codes | Positions robotic-assisted biopsies for eventual Category I status and margin parity with manual procedures. |
Research Methodology
Cross-validation between primary interviews with interventional radiologists, hospital procurement managers, biomedical engineers, and GPO contracts managers anchors the qualitative findings against secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, NMPA innovation-device registrations, and EU MDR notified body guidance documents. Bottom-up installation base modeling triangulates against top-down capital equipment spending surveys across hospital systems and ambulatory surgical centers.
Calibration against historical adoption curves for robotic surgery platforms informs penetration assumptions across the analysis window. Segmentation dimensions span product type, end-user archetype, technology capability layer, and application procedure, with regional regulatory cluster as an additional modeling dimension. CAGRs derive from installed base growth trajectories and recurring instrument revenue per procedure, incorporating AI integration adoption curves and reimbursement coding evolution as industry-specific forecast inputs.
Practitioners should monitor NMPA accelerated review track outcomes, EU MDR software classification enforcement patterns, and CMS coding committee deliberations for early signals of regulatory or reimbursement inflection. Cross-checking against hospital capital expenditure surveys and surgical center leasing database trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Gracey Curette Market
Medical Devices
Global Sternal Closure Systems Market
Medical Devices
Augmented Bone Graft Market
Medical Devices
Global Pacemakers Market
Medical Devices
New Zealand Diabetes Devices Market
Medical Devices
Global Wearable Pregnancy Devices Market
Medical Devices
Neurofeedback Systems Market
Medical Devices
Medical Device Regulatory Affairs Market
Medical Devices
Neuro Ablation Devices Market
Medical Devices
Artificial Cartilage Implant Market
Medical Devices
Europe Sperm Separation Devices Market
Medical Devices
Sputum Ejection Machine Market
Medical Devices
Germany Minimally Invasive Surgery Devices Market
Medical Devices
Rechargeable Medical Battery Market
Medical Devices
Intervertebral Implants Market
Medical Devices
Global Medical Tricorder Device Market