
 Implantable Defibrillators Market | 2026-2036
Implantable Defibrillators Market Size, Share, and Industry Trends Forecast 2026-2036
Implantable Defibrillators Market Analysis
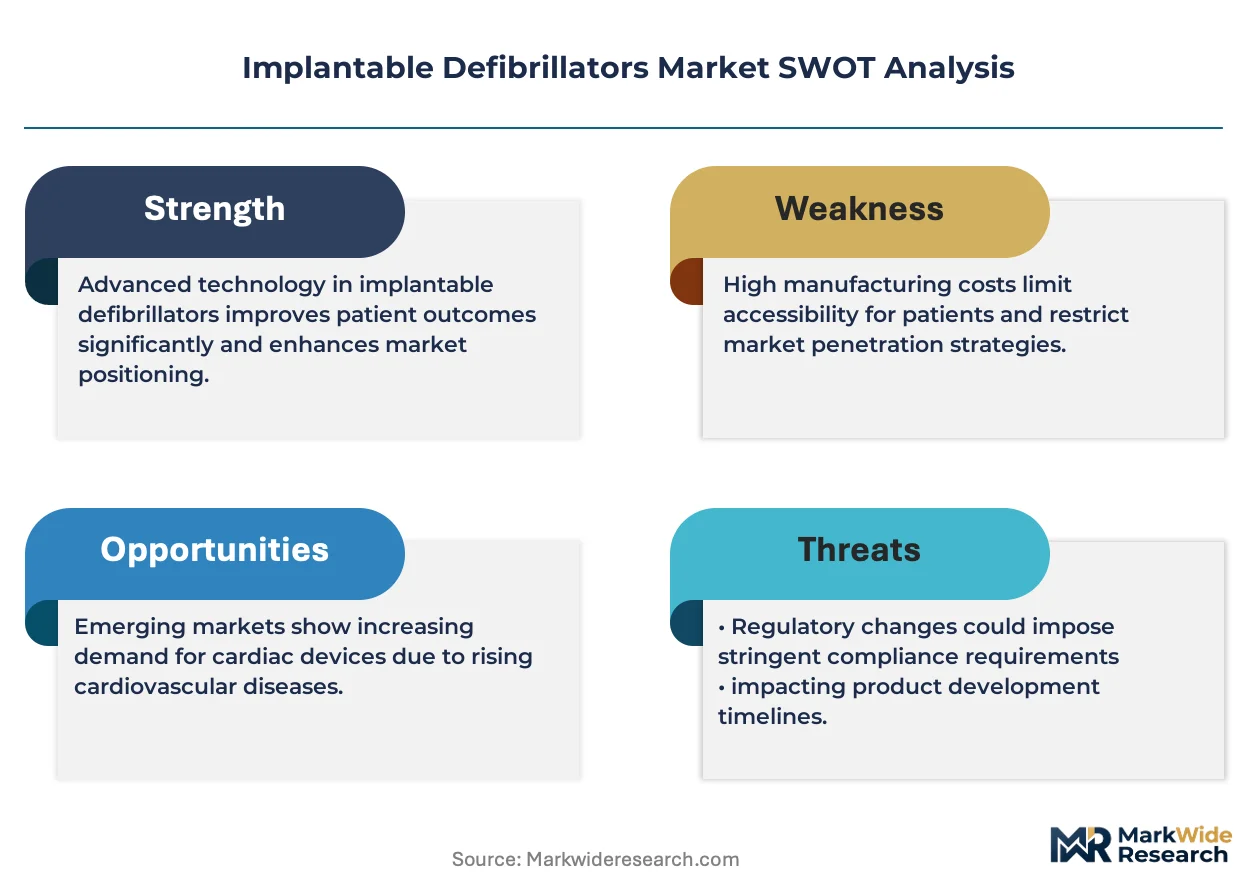
The capital-intensity divergence between subcutaneous specialists and full-portfolio manufacturers is collapsing as reimbursement parity erodes premium positioning. Medtronic leverages vertical integration across leads, generators, and remote monitoring to sustain margin capture in dual-chamber systems. Abbott competes through catheter-lab synergies that anchor its electrophysiology-to-implant workflow control.
An implantable defibrillator is a battery-powered pulse generator connected to leads that sense cardiac rhythm and deliver shocks to terminate ventricular fibrillation or tachycardia, typically housed in a titanium casing with lithium silver vanadium oxide cells and programmable detection zones. The device type dimension shows biventricular systems carrying the deepest margin pools due to heart failure comorbidity bundling, while subcutaneous technology leads growth by eliminating transvenous lead complications. End-user concentration in hospitals reflects capital equipment requirements for implant suites, though ambulatory surgery centers are capturing select elective cases as procedural complexity standardizes.
FDA premarket notification and PMA pathways govern US market access, while the EU MDR and EMA notified body frameworks impose strengthened clinical evidence requirements for active implantable medical devices. The FDA's evolving cybersecurity guidance and EMA's post-market surveillance integration are forcing manufacturers to embed software lifecycle documentation into design controls. Stakeholders must monitor reimbursement recalibration for wireless remote monitoring as a billable service separate from device implantation.
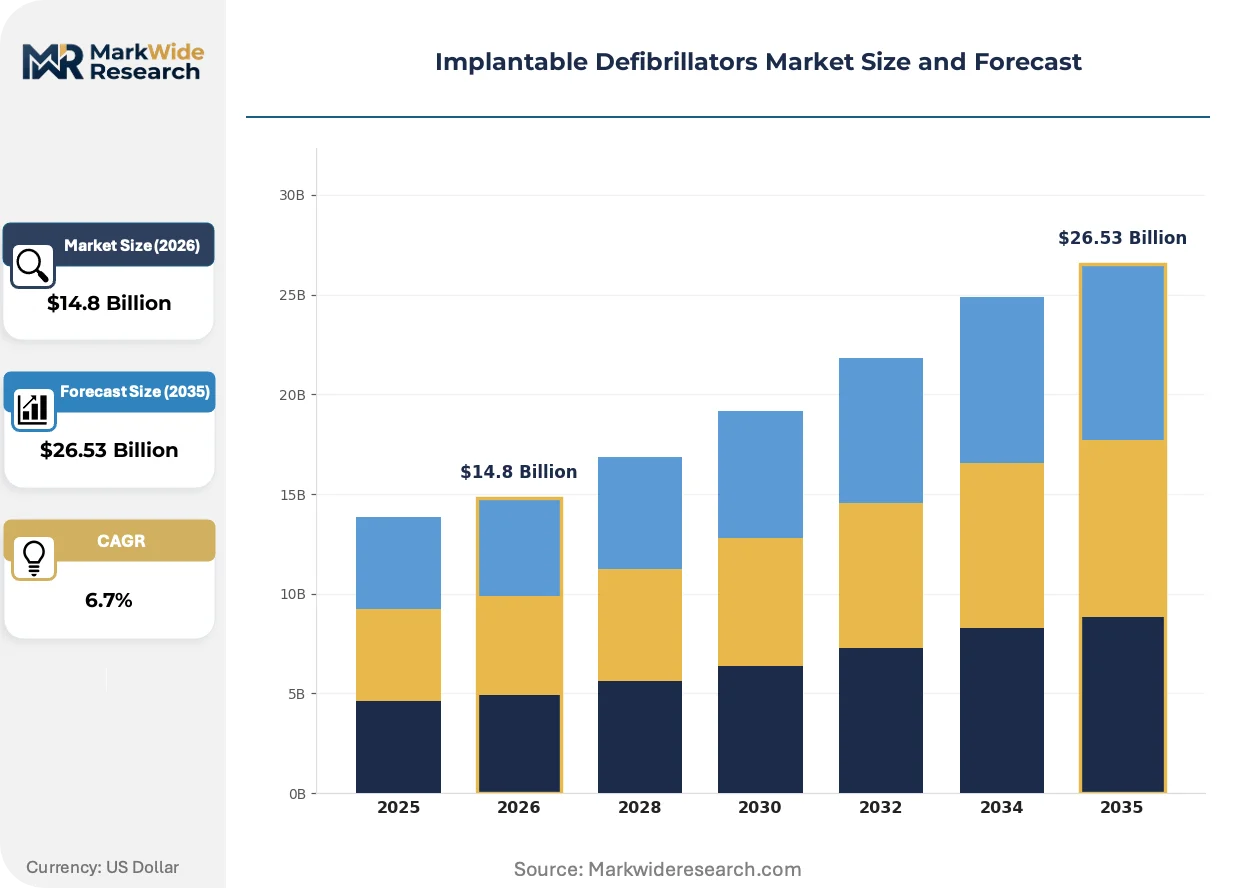
Market Dynamics
Reimbursement parity between transvenous and subcutaneous systems is collapsing the premium pricing that once sustained specialist manufacturers, forcing portfolio diversification across lead technologies and remote monitoring services.
Growth Catalysts
- EU MDR Conformity Pathways:Strengthened clinical evidence requirements for active implantable medical devices are accelerating consolidation toward manufacturers with established post-market surveillance infrastructure.
- Heart Failure Comorbidity Bundling:Cardiology clinics in the United States are expanding biventricular device adoption as first-line intervention sites for patients with reduced ejection fraction.
- Subcutaneous Lead Elimination:Transvenous lead complication avoidance is driving procedural volume migration toward systems that bypass vascular access entirely.
Market Restraints
- Lithium Silver Vanadium Oxide Supply Concentration:Battery cell chemistry dependence on limited specialty chemical suppliers creates input cost volatility for generator manufacturers.
- FDA PMA Timeline Friction:Premarket approval pathways for novel detection algorithms extend commercialization timelines by 18-36 months compared to predicate device clearances.
- Catheter Ablation Substitution:Electrophysiology lab investments in pulmonary vein isolation are capturing arrhythmia patients who would otherwise progress to device implantation.
Strategic Opportunities
- Japan's Aging Demographics:Reimbursement clarity from METI and PMDA for wireless remote monitoring as a billable service separate from implantation creates margin expansion potential.
- Ambulatory Surgery Center Channel:Procedural complexity standardization is enabling elective case capture outside hospital implant suites.
- FDA Cybersecurity Guidance Integration:Software lifecycle documentation requirements favor manufacturers with embedded design control capabilities.
Industry Challenges
- Electrophysiology-to-Implant Workflow Control:Catheter-lab synergies require cross-functional training investments that strain smaller device manufacturers.
- EMA Post-Market Surveillance Integration:Active implantable medical device traceability mandates demand supply chain reconfiguration for European market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Implantable Defibrillators Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Single-Chamber, Dual-Chamber, Biventricular, Subcutaneous End User: Hospitals, Cardiology Clinics, Ambulatory Surgery Centers, Emergency Medical Services Technology: Transvenous, Wireless, Bioprosthetic, Programmable Application: Arrhythmia Treatment, Sudden Cardiac Arrest, Heart Failure, Preventive Care |
| Companies Covered | Medtronic, Abbott, Boston Scientific Corporation, Biotronik SE & Co. KG, Koninklijke Philips N.V., LivaNova Plc, MicroPort Scientific Corporation, Nihon Kohden Corporation, Fukuda Denshi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Implantable Defibrillators Market Emerging Trajectories
Device architecture is converging around leadless and extravascular sensing modalities that eliminate the mechanical failure modes defining legacy system liability. Software-defined detection zones and machine-augmented rhythm classification are compressing the clinical validation burden.
Subcutaneous pulse generators with extravascular sensing coils are displacing transvenous lead-dependent systems in primary prevention populations. Electrophysiology practices in Germany and the United States are adopting these platforms for patients with vascular access limitations or prior lead complications. The technology is displacing premium pricing tiers as reimbursement parity eliminates the cost justification for lead-based complexity.
EU MDR clinical evidence requirements for active implantable medical devices are forcing manufacturers to embed post-market surveillance into design controls. The regulation mandates systematic literature reviews and PMCF study protocols that extend regulatory affairs timelines. Class III device categories face the steepest compliance burden as notified body capacity constrains conformity assessment throughput.
Hospital procurement committees are unbundling device implantation from remote monitoring service contracts. Cardiology clinics in Japan and the United States are negotiating separate reimbursement streams for wireless transmission of arrhythmia episodes and device integrity alerts. This bifurcation is most visible in Medicare Advantage and German statutory insurance frameworks where episode-based payment models create incentives for continuous care monetization.
Implantable Defibrillators Market Segmentation
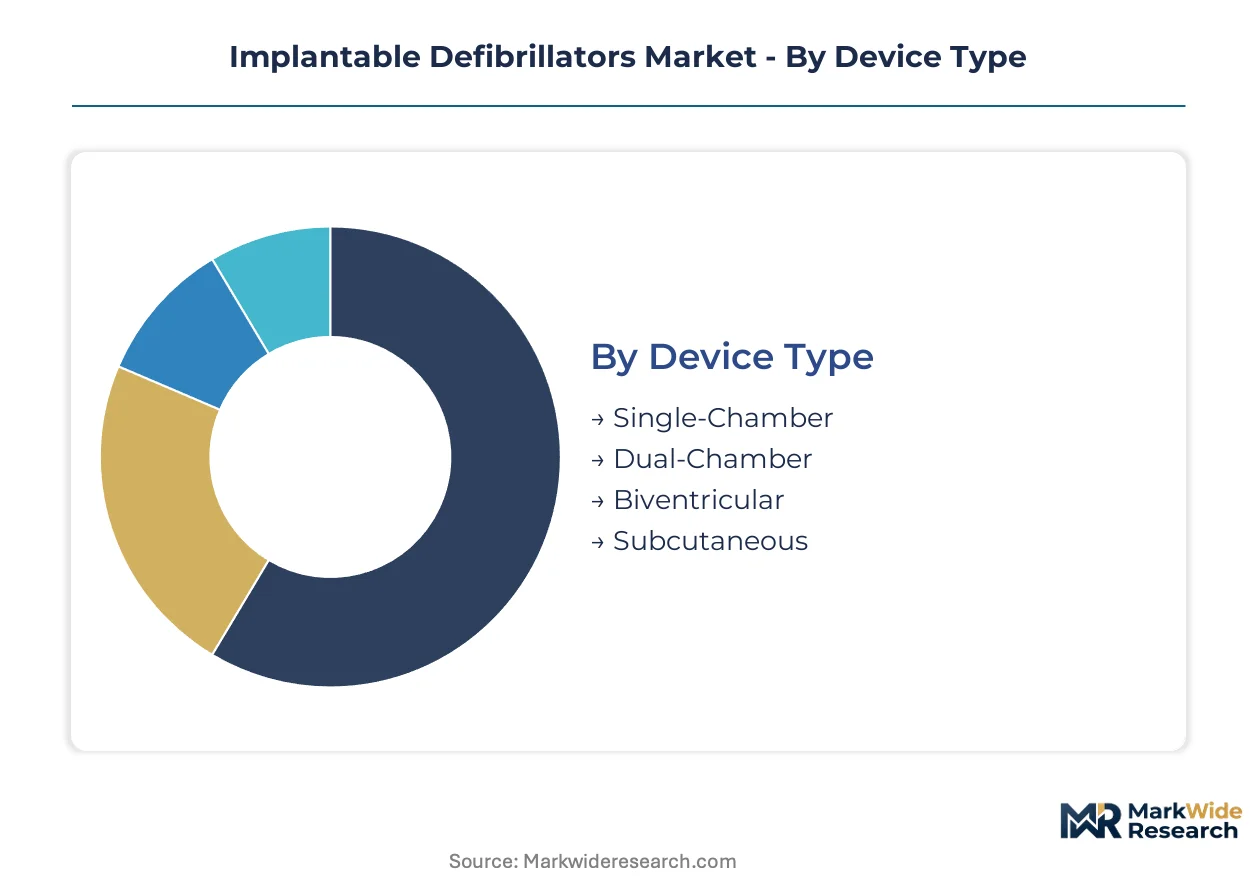
Segmentation in implantable defibrillators reveals how catheter ablation substitution and leadless technology are fragmenting traditional demand pools across device architectures and care settings.
Device Type:
Transvenous lead systems face the most acute substitution pressure from catheter-based pulmonary vein isolation, forcing manufacturers to defend implant volume through leadless alternatives.
- Single-Chamber:These systems deploy one lead in the right ventricle with simplified programming for primary prevention patients. Demand concentrates in Germany's statutory insurance framework where cost-conscious hospital procurement favors streamlined generator configurations for elderly populations with limited comorbidity burden.
- Dual-Chamber:Atrial and ventricular sensing capabilities enable discrimination between supraventricular and ventricular arrhythmias. Adoption clusters in United States cardiology clinics where Medicare reimbursement for dual-chamber implantation sustains procedural economics despite higher device acquisition costs.
- Biventricular:Cardiac resynchronization therapy generators with left ventricular lead placement for heart failure comorbidity management.
- Subcutaneous:Extravascular sensing coils eliminate transvenous lead complications entirely.
Single-chamber systems anchor the volume base while subcutaneous technology gains share at the steepest rate.
End User:
Capital equipment requirements create sharp cost tier differentiation between implant suite configurations and point-of-care accessibility.
- Hospitals:Comprehensive electrophysiology labs with fluoroscopy, mapping systems, and surgical backup for lead extraction. These facilities capture complex redo procedures and generator replacements in Japan's urban centers where PMDA reimbursement clarity supports high-volume implant programs.
- Cardiology Clinics:Outpatient-based implant suites with portable C-arm imaging and telemetry monitoring capabilities. Volume is expanding fastest in United States metropolitan markets where physician-owned practices negotiate direct contracts with commercial payers for device-plus-procedure bundles.
- Ambulatory Surgery Centers:Elective primary prevention implants with standardized procedural protocols.
- Emergency Medical Services:Pre-hospital automated external defibrillator deployment and transport coordination.
Hospitals retain the highest-acuity case mix while cardiology clinics are climbing the fastest in procedural volume share.
Technology:
Maturity gradients separate legacy lead-dependent architectures from emerging wireless modalities that bypass mechanical failure modes.
- Transvenous:Endocardial lead placement via subclavian or cephalic vein access with passive or active fixation mechanisms. Demand persists in United States academic medical centers where fellowship training programs maintain proficiency in lead extraction techniques for system upgrades.
- Wireless:Leadless pulse generators delivered via femoral catheter to right ventricular septum. Germany's university hospitals are piloting these systems for patients with prior lead complications or vascular access limitations.
- Bioprosthetic:Tissue-engineered lead coatings and biological fixation surfaces.
- Programmable:Software-defined detection zones and therapy algorithms with non-invasive adjustability.
Transvenous technology holds the installed base while wireless platforms are expanding most quickly in addressable patient populations.
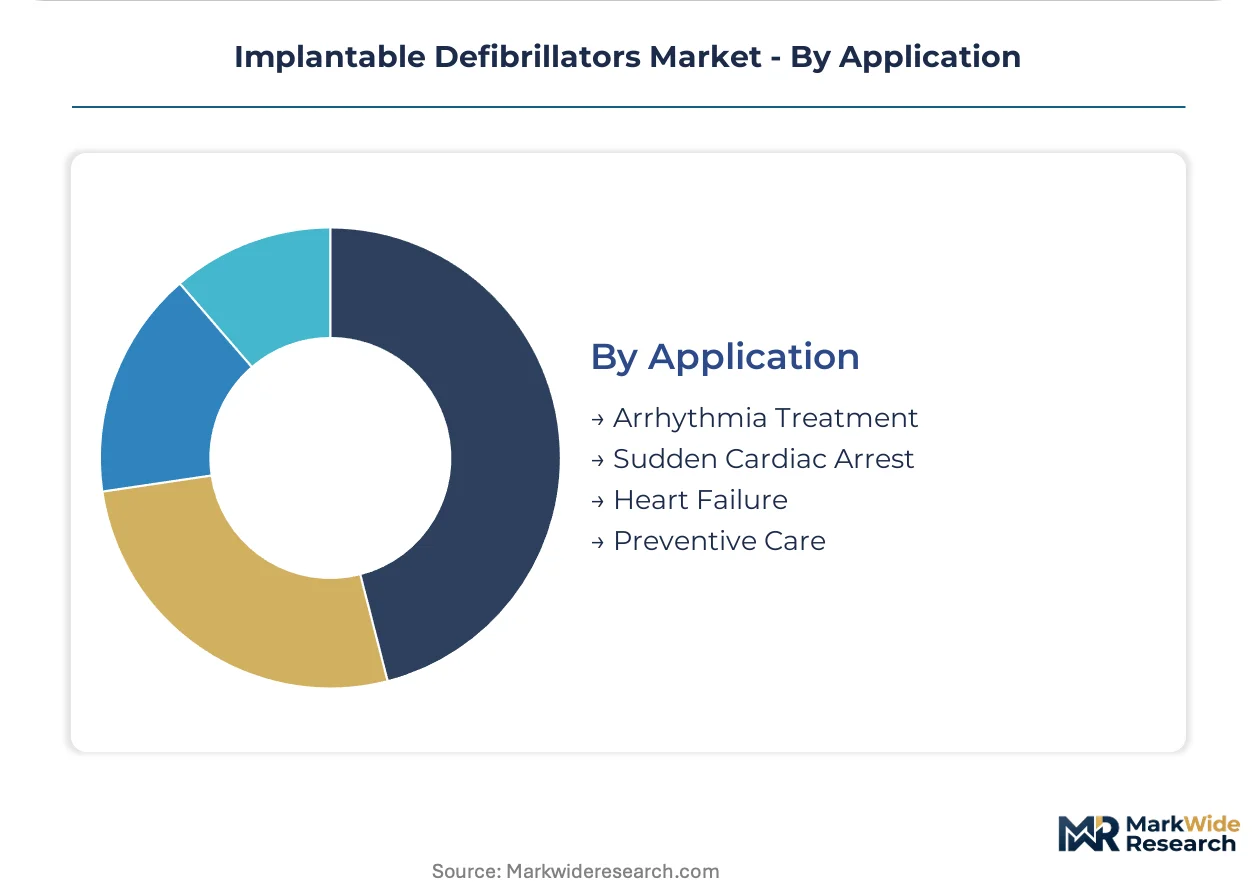
Application:
Clinical indication severity determines reimbursement tiering and device complexity selection across prevention-to-intervention spectrum.
- Arrhythmia Treatment:Secondary prevention for documented ventricular tachycardia or fibrillation episodes. United States electrophysiology practices prioritize these implants given established Medicare coverage for documented life-threatening events.
- Sudden Cardiac Arrest:Post-resuscitation implantation for survivors of cardiac arrest without reversible cause. Japan's emergency medical networks coordinate rapid referral to implant-capable centers under METI-directed regional care protocols.
- Heart Failure:Primary prevention with cardiac resynchronization therapy for reduced ejection fraction.
- Preventive Care:Risk-stratified primary prevention in genetic cardiomyopathy or channelopathy.
Arrhythmia treatment anchors current procedural volume while preventive care applications are gaining share fastest as genetic screening expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement elasticity varies sharply across geographies. German statutory insurance imposes rigid cost ceilings that compress margins, while United States Medicare Advantage plans tolerate premium device pricing when bundled with remote monitoring services.
United States
Medicare Advantage penetration drives procedural volume concentration in metropolitan cardiology clinics. FDA PMA pathways for novel detection algorithms extend approval timelines, favoring incumbents with established predicate device portfolios. Boston and Cleveland anchor high-volume electrophysiology programs where academic medical centers train fellowship pipelines.
Germany
Statutory health insurance cost ceilings constrain biventricular system adoption rates relative to clinical guidelines. EU MDR conformity assessment through notified bodies in Tübingen and Berlin extends regulatory affairs timelines for Class III active implantables. Bavarian university hospitals pilot subcutaneous systems for vascular access-limited patient cohorts.
Japan
METI reimbursement clarity for wireless remote monitoring as a billable service separate from implantation creates margin expansion potential. PMDA streamlined approval pathways for predicate-equivalent generators accelerate market entry for established manufacturers. Tokyo and Osaka metropolitan clusters concentrate implant volume in physician-owned cardiology practices.
China
NMPA priority review pathways for innovative medical devices accelerate market access for leadless pulse generator technologies. Provincial centralized procurement programs compress pricing tiers for transvenous systems in tier-one hospitals. Shanghai and Beijing academic medical centers dominate complex redo procedures and lead extraction capabilities.
Switzerland
Swissmedic parallel review pathways with EMA reduce regulatory duplication for manufacturers with EU MDR certificates. Premium reimbursement tiers for cardiac resynchronization therapy sustain procedural economics despite small population scale. Basel and Zurich hospital networks concentrate biventricular implant volume for cross-border patient flows.
Implantable Defibrillators Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with full-portfolio manufacturers dominating generator and lead integration while subcutaneous specialists capture vascular-access-limited segments. The vendor base consolidates around three strategic tiers: vertically integrated multinationals with remote monitoring platforms, mid-cap regional specialists with catheter-lab synergies, and emerging Asian manufacturers with cost-optimized generator production. Competitive moves center on portfolio diversification across lead technologies and backward integration into battery cell supply.
Among diversified multinationals, Medtronic anchors the integrated systems tier with captive lead and generator manufacturing, while Abbott exemplifies the catheter-lab workflow control archetype through electrophysiology-to-implant service bundling. Boston Scientific Corporation occupies a position bridging premium device innovation with scaled European market access.
| Leading Market Players |
|---|
| Medtronic |
| Abbott |
| Boston Scientific Corporation |
| Biotronik SE & Co. KG |
| Koninklijke Philips N.V. |
| LivaNova Plc |
| MicroPort Scientific Corporation |
| Nihon Kohden Corporation |
| Fukuda Denshi |
| Others |
Supply Flow & Price Mechanics
FDA premarket approval pathways and EU MDR conformity requirements gate both supply qualification and price differentiation simultaneously, as manufacturers must absorb extended regulatory affairs timelines and post-market surveillance infrastructure costs before capturing margin in premium device tiers.
Pricing Analysis
Remote monitoring service contracts drive lifetime value beyond the initial implantation event, with wireless transmission of arrhythmia episodes and device integrity alerts now reimbursable as separate billable services in Medicare Advantage and German statutory insurance frameworks. Price differentiation rests on detection algorithm sophistication and lead technology complexity, with biventricular systems commanding premium positioning through heart failure comorbidity bundling while subcutaneous platforms face compression as reimbursement parity eliminates transvenous lead cost justification. Cost compression in single-chamber configurations is intensifying because provincial centralized procurement programs in China and statutory insurance cost ceilings in Germany constrain hospital procurement flexibility. Cardiology clinics in physician-owned United States metropolitan markets demonstrate lowest price sensitivity due to direct commercial payer contract negotiation, while tier-one hospital procurement committees in China exhibit highest sensitivity under volume-based purchasing mandates.
Supply Chain Analysis
Lithium silver vanadium oxide cell chemistry concentration among limited specialty chemical suppliers in Japan and the United States creates input cost volatility that propagates through generator manufacturing economics. Raw material dependencies center on titanium casing forgings, platinum-iridium electrode tips, and medical-grade silicone lead insulation sourced from established aerospace and chemical processing supply bases. Single-source vulnerability in battery cell chemistry exposes manufacturers to commodity price swings when mining output from Chilean vanadium deposits fluctuates. Distribution runs through hospital procurement committees and GPO contracts in the United States, direct statutory insurance framework negotiations in Germany, and PMDA-aligned distributor networks in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subcutaneous lead elimination and wireless remote monitoring unbundling are disrupting established reimbursement and competitive architectures, creating acceleration windows for manufacturers with embedded software lifecycle capabilities and post-market surveillance infrastructure.
For Market Incumbents: Secure backward integration into lithium silver vanadium oxide cell supply to buffer input cost volatility from Japanese and United States specialty chemical suppliers. Lock catheter-lab workflow control through electrophysiology-to-implant service bundling that anchors procedural volume against subcutaneous substitution. Defend biventricular margin pools by deepening cardiac resynchronization therapy training investments in United States cardiology clinics where Medicare reimbursement clarity sustains procedural economics.
For New Entrants and Emerging Players: Anchor in ambulatory surgery center channels for elective primary prevention implants where procedural complexity standardization enables case capture outside hospital implant suites. Target vascular-access-limited patient populations in Germany's Bavarian university hospital pilot programs where subcutaneous system adoption is expanding fastest. Pursue predicate-equivalent generator pathways through PMDA streamlined approval mechanisms in Japan's Tokyo and Osaka metropolitan clusters.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across wireless leadless platform development as EU MDR clinical evidence requirements extend regulatory affairs timelines and demand embedded post-market surveillance infrastructure. Long-term viability favors manufacturers with captive lead and generator integration or catheter-lab synergies that anchor electrophysiology-to-implant workflow control. Acquisition target archetypes include mid-cap regional specialists with established notified body relationships and emerging Asian manufacturers with cost-optimized generator production. Monitor wireless remote monitoring reimbursement clarity from METI and PMDA as the signal indicating margin expansion potential decoupled from device implantation economics.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Cybersecurity Guidance Integration | Software lifecycle documentation requirements favor manufacturers with embedded design control capabilities. |
| EU MDR Conformity Pathway Investment | Post-market surveillance infrastructure mandates accelerate consolidation toward established notified body relationships. |
| Wireless Remote Monitoring Reimbursement Strategy | Medicare Advantage and German statutory insurance unbundling creates separate billable service revenue streams. |
| Subcutaneous System Hospital Partnership | Bavarian and United States academic medical center pilots anchor vascular-access-limited patient access. |
| Lithium Silver Vanadium Oxide Supply Agreement | Long-term offtake contracts with Japanese and United States specialty chemical suppliers buffer input cost volatility. |
Methodological Framework
Desk research of FDA PMA filings, EU MDR notified body certificates, CMS Medicare reimbursement databases, and hospital procurement records preceded structured interviews with electrophysiology lab directors, biomedical engineers, hospital purchasing committee members, and GPO contracts managers. Primary fieldwork captured procedural volume patterns, device selection criteria, and reimbursement negotiation dynamics across United States metropolitan markets, German statutory insurance frameworks, and Japanese physician-owned cardiology practices. Secondary validation drew from PMDA approval summaries, METI reimbursement bulletins, and academic medical center fellowship training program disclosures. Bottom-up implant volume estimates triangulated against top-down market sizing from generator manufacturer revenue disclosures and lithium silver vanadium oxide cell supplier shipment data.
Variance decomposition across device type, end user, technology, and application dimensions structured the analytical framework over the projection horizon. CAGRs derived from fitted growth curves applied to procedural volume trajectories in cardiology clinics and ambulatory surgery centers, adjusted for catheter ablation substitution effects and leadless technology penetration rates. Industry-specific forecast inputs included EU MDR conformity assessment timeline assumptions, wireless remote monitoring reimbursement clarity indices, and subcutaneous system adoption curves in vascular-access-limited populations.
Material uncertainties — regulatory timeline extensions, lithium silver vanadium oxide supply disruptions, and catheter ablation technology substitution acceleration — sit outside the modeled envelope. Forecasts reflect assumptions about reimbursement parity stability and notified body capacity constraints. Practitioners should keep alternative scenarios live as EU MDR post-market surveillance integration requirements and FDA cybersecurity guidance enforcement timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Surgical Display Market
Medical Devices
Minimally Invasive Neurosurgery Devices Market
Medical Devices
United Kingdom Drug Delivery Devices Market
Medical Devices
Soft Tissue Market
Medical Devices
Skin Rejuvenation Devices Market
Medical Devices
Global Insulin Pumps Market
Medical Devices
Radial Access Catheter Market
Medical Devices
Dry Eye Treatment Devices Market
Medical Devices
Reusable Laparoscopic Instrument Market
Medical Devices
Rigid Laparoscope Market
Medical Devices
Automated Insulin Delivery Device Market
Medical Devices
Bone Densitometer Devices Market
Medical Devices
Global Orthopedic Surgical Robots Market
Medical Devices
Brazil Cardiac Pacemakers Market
Medical Devices
Spine Positioning Devices Market
Medical Devices
Peripheral Interventions Market