
 Global Non-Surgical Skin Tightening Devices Market | 2026-2036
Global Non-Surgical Skin Tightening Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Non-Surgical Skin Tightening Devices Market Foresight
Radiofrequency energy delivery is broadening treatment protocols across non-surgical aesthetic practices. BTL Industries leverages integrated muscle stimulation platforms to differentiate its portfolio across European and North American clinics. Alma Lasers anchors its position through fractional laser technology leadership, while Venus Concept competes via multipolar radiofrequency systems optimized for body contouring workflows.
Non-surgical skin tightening devices employ electromagnetic energy—typically radiofrequency at 1–6 MHz, ultrasound at 1–3 MHz, or infrared at 700–2000 nm—to induce dermal collagen neogenesis without incision. These systems target fibroblast activation and elastin remodeling for facial rejuvenation and body contouring applications in outpatient settings. Radiofrequency devices command the largest installed base due to versatility across skin types, though ultrasound platforms represent the fastest-growing category as practitioners seek deeper tissue penetration for body contouring outcomes. Dermatology clinics retain the highest procedure volume, while medical spas capture expanding margin pools through membership-based treatment packages.
FDA 510(k) premarket notification requirements govern device safety and efficacy claims in the United States, while the EU Medical Device Regulation mandates clinical evidence standards and post-market surveillance across European member states. South Korea's MFDS enforces stringent electromagnetic compatibility testing that shapes product design cycles for Asia-Pacific distribution. Stakeholders must monitor evolving reimbursement classifications for aesthetic procedures as payor policies increasingly influence patient out-of-pocket decisions and clinic capital allocation priorities.
Market Dynamics
Radiofrequency and ultrasound platforms are fragmenting procedure authority from hospital-based plastic surgeons toward outpatient dermatology clinics and medical spas, compressing capital recovery timelines while expanding addressable patient populations.
Growth Catalysts
- EU Medical Device Regulation:Clinical evidence standards for Class IIa devices are elevating barrier-to-entry for low-quality competitors, protecting premium-tier manufacturers with established post-market surveillance infrastructure.
- Medical spa expansion:Membership-based aesthetic clinics in Seoul, Los Angeles, and Dubai are deploying multipolar radiofrequency systems to capture recurring revenue from facial rejuvenation protocols.
- Collagen neogenesis science:Published histological studies demonstrating measurable elastin remodeling at 3-month follow-up are converting skeptical dermatologists toward non-invasive alternatives.
Market Restraints
- Capital intensity:Ultrasound platforms with integrated cooling systems require $80,000–$150,000 upfront investment, constraining independent practice adoption.
- Input concentration:Piezoelectric transducer manufacturing concentrates in Japanese and German precision component suppliers, exposing device OEMs to single-source supply risk.
- Technical ceiling:Radiofrequency penetration depth plateaus at 4–6 mm regardless of power modulation, limiting efficacy for patients with substantial subcutaneous adiposity.
Strategic Opportunities
- Brazil aesthetic market:ANVISA regulatory pathways for Class II medical devices remain less stringent than FDA or EU MDR, enabling faster market entry for radiofrequency platforms.
- Home-use convergence:Lower-power radiofrequency devices with smartphone-guided treatment protocols are creating direct-to-consumer channels previously inaccessible to clinical-grade manufacturers.
- Combination therapy protocols:Integrated platforms pairing fractional laser with bipolar radiofrequency are capturing premium pricing in Dubai and Los Angeles cosmetic surgery centers.
Industry Challenges
- Electromagnetic compatibility certification:South Korea's MFDS testing protocols for radiofrequency emission profiles add 4–6 months to product launch timelines.
- Practitioner training standardization:Absence of unified credentialing bodies for non-surgical device operators creates liability exposure and inconsistent patient outcomes.
- Legacy ERP integration:Medical spa software platforms lack native connectivity to device utilization tracking systems, complicating membership billing reconciliation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Non-Surgical Skin Tightening Devices Market |
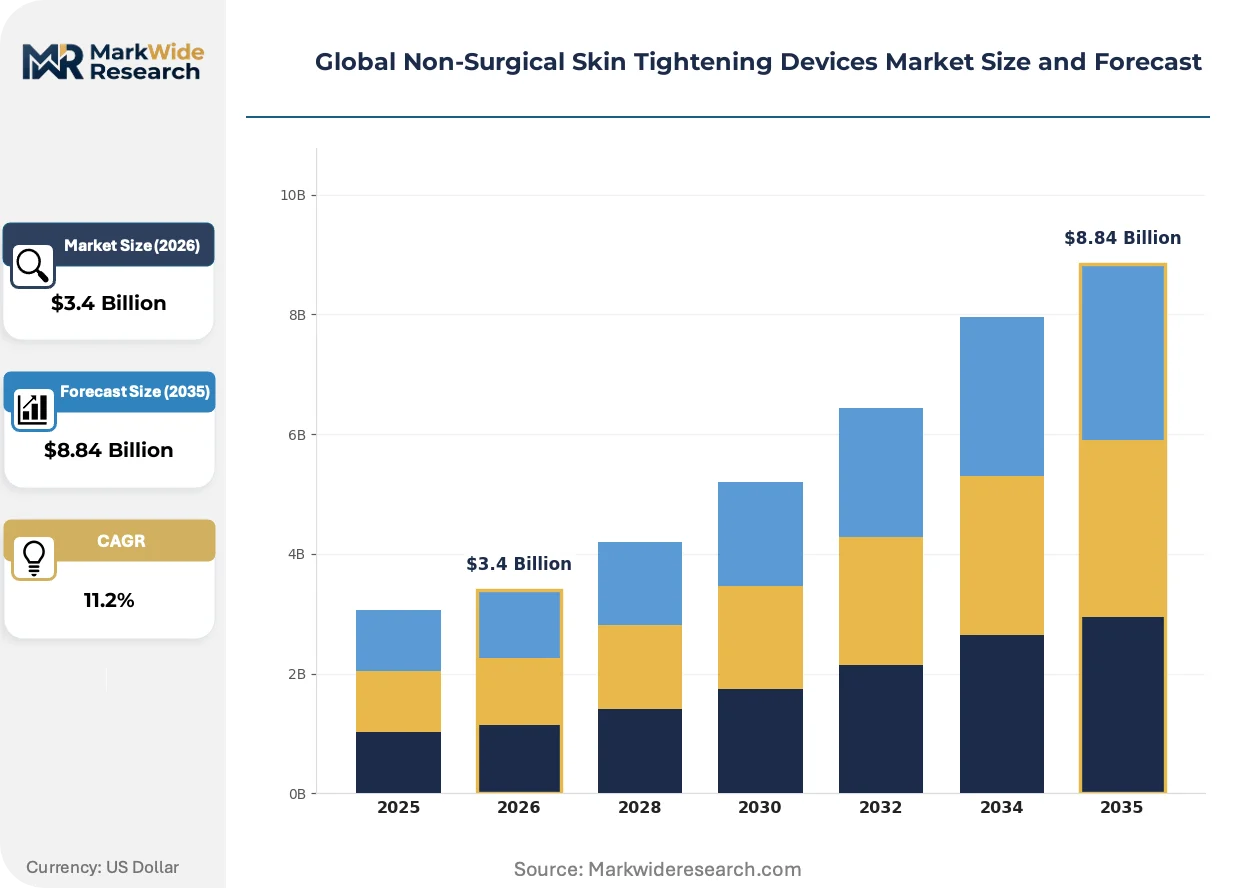
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $8.84 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radiofrequency Devices, Ultrasound Devices, Laser Devices, Infrared Devices Technology: Monopolar, Bipolar, Multipolar, Fractional Application: Facial Rejuvenation, Body Contouring, Wrinkle Reduction, Cellulite Treatment, Scar Tissue Improvement End User: Dermatology Clinics, Medical Spas, Cosmetic Centers, Plastic Surgery Clinics |
| Companies Covered | BTL Industries, Cutera, Syneron Candela, Venus Concept, Lumenis, Hologic, Allergan, Alma Lasers, Fotona, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Non-Surgical Skin Tightening Devices Market Shifts & Advancements
Device architecture is converging toward modular platforms capable of delivering multiple energy modalities through single applicator heads, reducing clinic floor space requirements while expanding treatable indications per capital dollar deployed.
Artificial intelligence-guided treatment mapping is decentralizing expertise requirements for optimal energy delivery patterns. Mid-tier medical spas in Dallas and Toronto are adopting these systems without dedicated on-site plastic surgery oversight. Algorithmic fluence adjustment is compressing training curves for newly certified technicians while standardizing outcomes across operator experience levels.
MDR clinical evidence requirements are forcing manufacturers to maintain prospective patient registries for post-market surveillance. European notified bodies are rejecting 510(k)-equivalent predicate claims without histological endpoint data. Device firms with pre-2021 legacy portfolios are conducting expensive retrospective studies to maintain CE marking validity.
Subscription-based equipment financing is displacing traditional capital purchase models among US dermatology groups. Private equity-backed clinic rollups in Florida and Texas prefer per-procedure leasing arrangements that align device costs with utilization rates. This shift transfers residual value risk to manufacturers while accelerating fleet refresh cycles.
Global Non-Surgical Skin Tightening Devices Market Segmentation
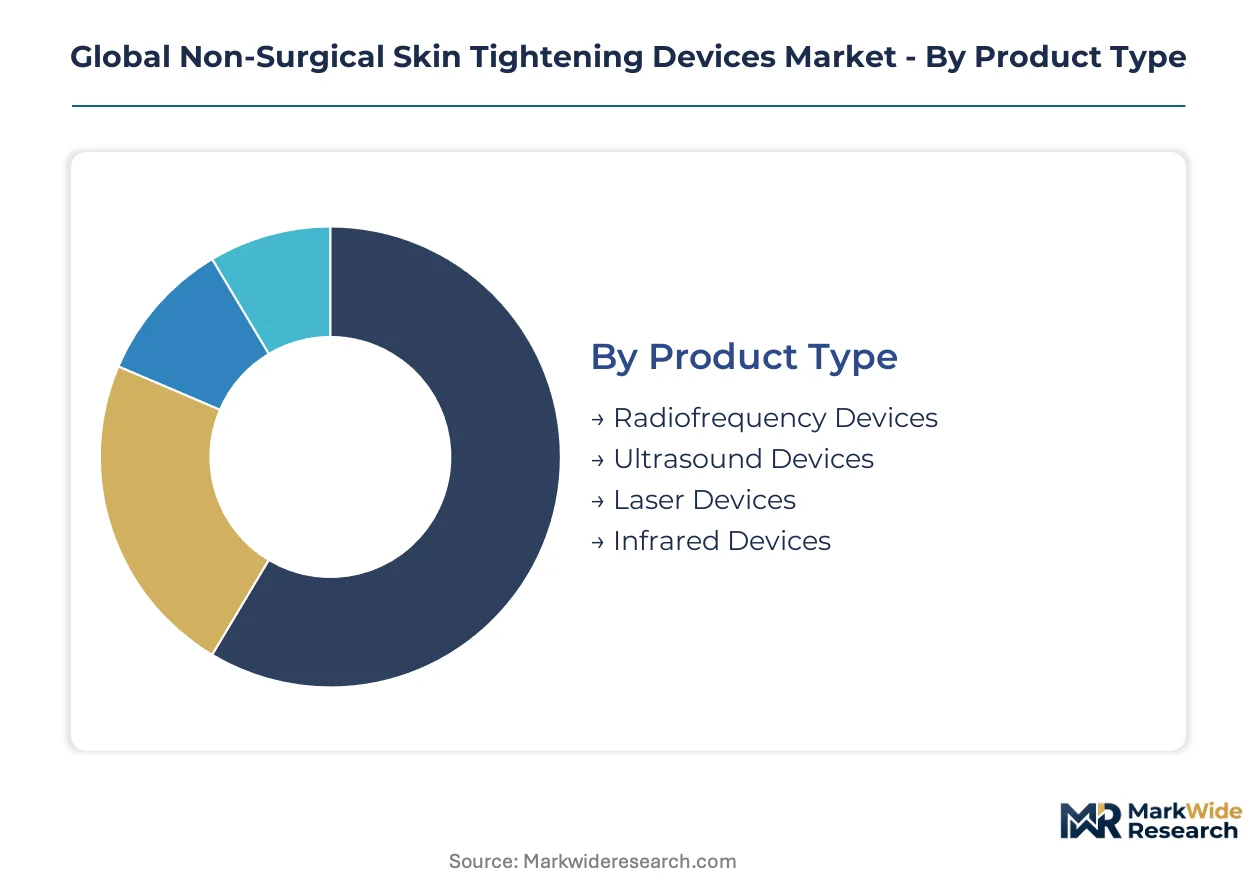
Segmentation across product type, technology, application, and end user reveals how capital allocation and patient flow concentrate among specific configurations. Manufacturers calibrate platform architectures to capture margin pools across distinct clinical workflows and geographic clusters.
Product Type:
Supply concentration among Japanese and German piezoelectric component suppliers shapes device availability and pricing tiers across OEM portfolios.
- Radiofrequency Devices:Electromagnetic energy delivery at 1–6 MHz activates fibroblast collagen synthesis through controlled dermal heating. Demand concentrates in Seoul and Los Angeles medical spas seeking versatile protocols across Fitzpatrick skin types. Capital recovery timelines compress to 18–24 months in high-volume membership clinics.
- Ultrasound Devices:Focused acoustic energy at 1–3 MHz penetrates subcutaneous layers to 4.5 mm depth for body contouring applications. Dubai cosmetic centers deploy these platforms for premium pricing on deep tissue remodeling. Supply constraints on precision transducers limit fleet expansion in mid-tier practices.
- Laser Devices:Fractional and non-ablative wavelengths target epidermal-dermal junction remodeling for fine line reduction.
- Infrared Devices:Broadband light sources at 700–2000 nm provide gentle heating for maintenance protocols in day spa environments.
Today's leader: Radiofrequency Devices. Tomorrow's challenger: Ultrasound Devices.
Technology:
Cost tier differentiation separates premium multipolar platforms from entry-level monopolar systems across capital-constrained independent practices.
- Monopolar:Single electrode configuration with return pad generates deep volumetric heating through high-frequency current paths. German dermatology clinics favor these systems for established facial tightening protocols with predictable thermal profiles.
- Multipolar:Multiple electrode arrays create controlled current density patterns for superficial and mid-dermal treatment zones. South Korean device manufacturers lead integration with muscle stimulation platforms for combination therapy positioning.
- Bipolar:Paired electrodes confine energy delivery to inter-electrode tissue volumes for precise superficial remodeling.
- Fractional:Micro-beam arrays create microscopic thermal columns enabling rapid epidermal recovery with dermal collagen induction.
Multipolar configurations command premium pricing. Fractional modalities are expanding most quickly in combination platform architectures.
Application:
Volume concentration in facial rejuvenation procedures drives device utilization rates and consumable attachment sales across installed fleets.
- Facial Rejuvenation:Periorbital, mid-face, and neck protocols represent the highest procedure frequency across outpatient aesthetic settings. Los Angeles and Seoul medical spas structure membership tiers around quarterly maintenance sessions. FDA 510(k) clearance pathways prioritize indications in this category.
- Body Contouring:Abdomen, flank, and thigh applications leverage deeper energy penetration for adipose tissue remodeling. Dubai cosmetic surgery centers capture premium pricing for pre-event body sculpting packages. Ultrasound platforms dominate this indication due to penetration depth requirements.
- Wrinkle Reduction:Static rhytide treatment concentrates in urban dermatology clinics serving patients aged 45–65.
- Cellulite Treatment:Subdermal fibrous septa targeting requires specialized applicator designs with suction-coupled energy delivery.
- Scar Tissue Improvement:Post-acne and surgical scar remodeling represents a smaller volume indication with higher per-procedure pricing.
Facial Rejuvenation anchors current revenue. Body Contouring shows the steepest expansion trajectory as device capabilities advance.
End User:
Customer type determines procurement patterns, with private equity-backed clinic rollups favoring subscription financing over capital purchase.
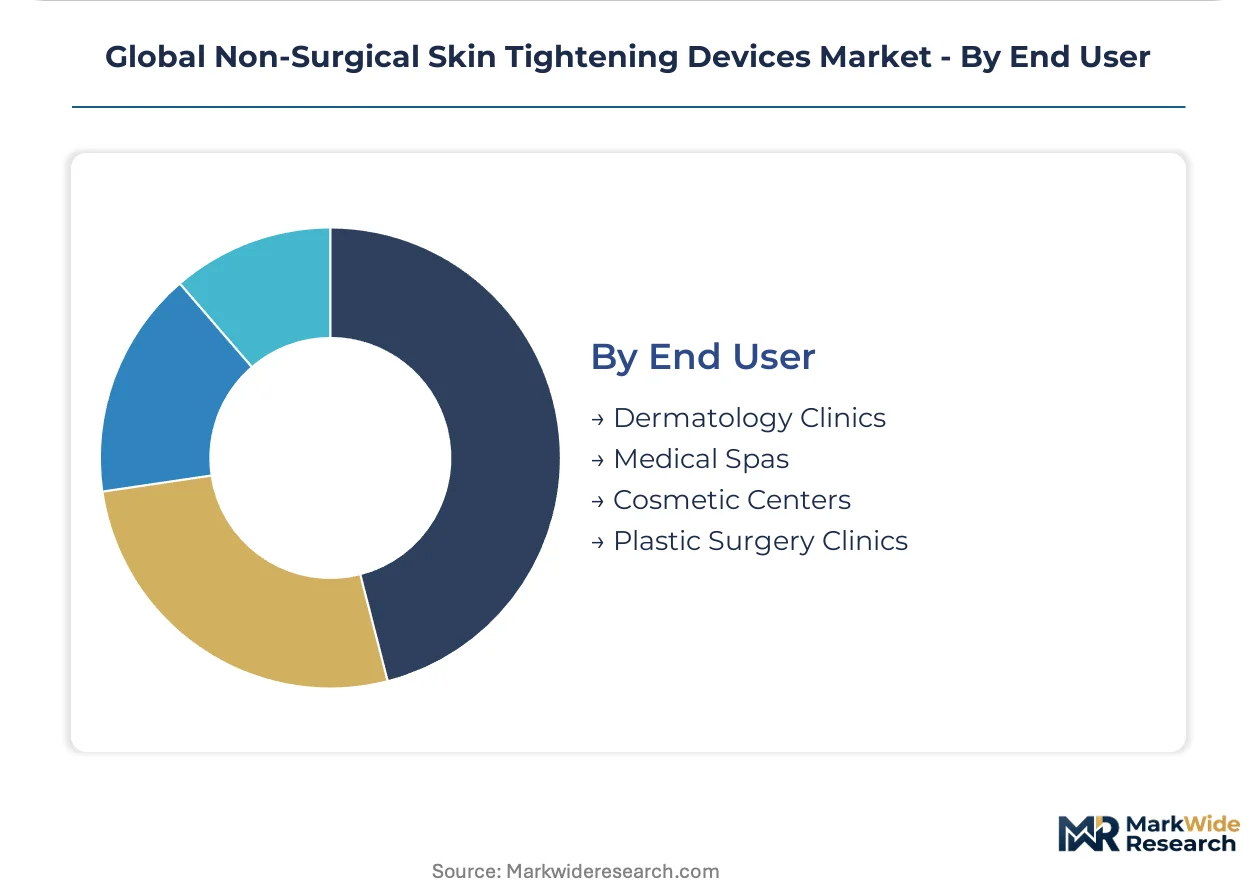
- Dermatology Clinics:Board-certified practitioners drive evidence-based adoption through histological outcome data and peer-reviewed publication. These settings retain the highest procedure volume per device and prefer multipolar radiofrequency with integrated temperature monitoring.
- Medical Spas:Non-physician supervised facilities in Texas and Florida deploy membership-based models aligning device costs with recurring patient visits. EU MDR compliance requirements increasingly influence fleet standardization decisions.
- Cosmetic Centers:Hybrid physician-extender staffing models in Dubai and Los Angeles pursue combination therapy platforms for competitive differentiation.
- Plastic Surgery Clinics:Hospital-affiliated and independent surgical practices integrate non-surgical devices for pre- and post-operative patient management.
Dermatology Clinics lead clinical credibility positioning. Medical Spas are capturing the fastest share expansion through membership economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul's medical spa corridor anchors installed base expansion for multipolar radiofrequency systems, while Los Angeles dermatology groups drive membership-based utilization models. Dubai cosmetic surgery centers capture premium pricing for combination therapy protocols. Regulatory divergence across FDA, EU MDR, and MFDS jurisdictions shapes product launch sequencing and evidence requirements.
United States
Private equity-backed clinic rollups in Florida and Texas favor subscription-based equipment financing over capital purchase. FDA 510(k) premarket notification pathways prioritize facial rejuvenation indications with temperature monitoring safeguards. Los Angeles medical spas structure quarterly membership tiers around maintenance protocols for periorbital and neck applications.
Germany
Dermatology clinics in Munich and Hamburg retain the highest procedure volume per device across European markets. EU Medical Device Regulation clinical evidence standards for Class IIa devices protect premium-tier manufacturers with established post-market surveillance infrastructure. German practitioners favor monopolar configurations with predictable thermal profiles for established facial tightening protocols.
South Korea
Device manufacturers in the Seoul Capital Area lead integration of radiofrequency platforms with muscle stimulation systems for combination therapy positioning. MFDS electromagnetic compatibility testing protocols add four to six months to product launch timelines for radiofrequency emission profiles. Busan-Ulsan corridor clinics deploy these integrated systems for competitive differentiation in body contouring applications.
United Arab Emirates
Dubai cosmetic surgery centers command premium pricing for pre-event body sculpting packages leveraging ultrasound penetration depth. MOHAP medical device registration pathways enable faster market entry than FDA or EU MDR equivalents for Class II aesthetic systems. Abu Dhabi clinics are expanding fleet deployments of fractional laser and bipolar radiofrequency combination platforms.
Brazil
ANVISA regulatory pathways for Class II medical devices remain less stringent than FDA or EU MDR, enabling accelerated market entry for radiofrequency platforms. São Paulo aesthetic clinics represent the largest addressable patient population in Latin America for non-surgical facial rejuvenation. Rio de Janeiro medical spas are adopting membership economics modeled on US and South Korean precedents.
Global Non-Surgical Skin Tightening Devices Market Competitive Landscape
Global majors compete with regional champions across technology integration and regulatory compliance capabilities. Market structure concentrates among diversified energy-based device manufacturers with established notified body relationships and prospective patient registry infrastructure. Three archetypes dominate: premium-tier multipolar platform specialists, mid-tier monopolar generalists, and emerging ultrasound-focused innovators. Competitive moves center on M&A for technology tuck-ins and strategic partnerships for distribution access in Brazil and South Korea.
Within the premium-tier multipolar segment, BTL Industries and Alma Lasers exemplify integrated platform strategies. BTL Industries occupies a position combining muscle stimulation with radiofrequency delivery for combination therapy protocols. Alma Lasers anchors the fractional laser technology leadership tier with diversified energy modality portfolios. Venus Concept sits within the body contouring specialization tier, competing via multipolar radiofrequency systems optimized for high-volume medical spa workflows.
| Leading Market Players |
|---|
| BTL Industries |
| Cutera |
| Syneron Candela |
| Venus Concept |
| Lumenis |
| Hologic |
| Allergan |
| Alma Lasers |
| Fotona |
| Others |
Supply & Pricing Matrix
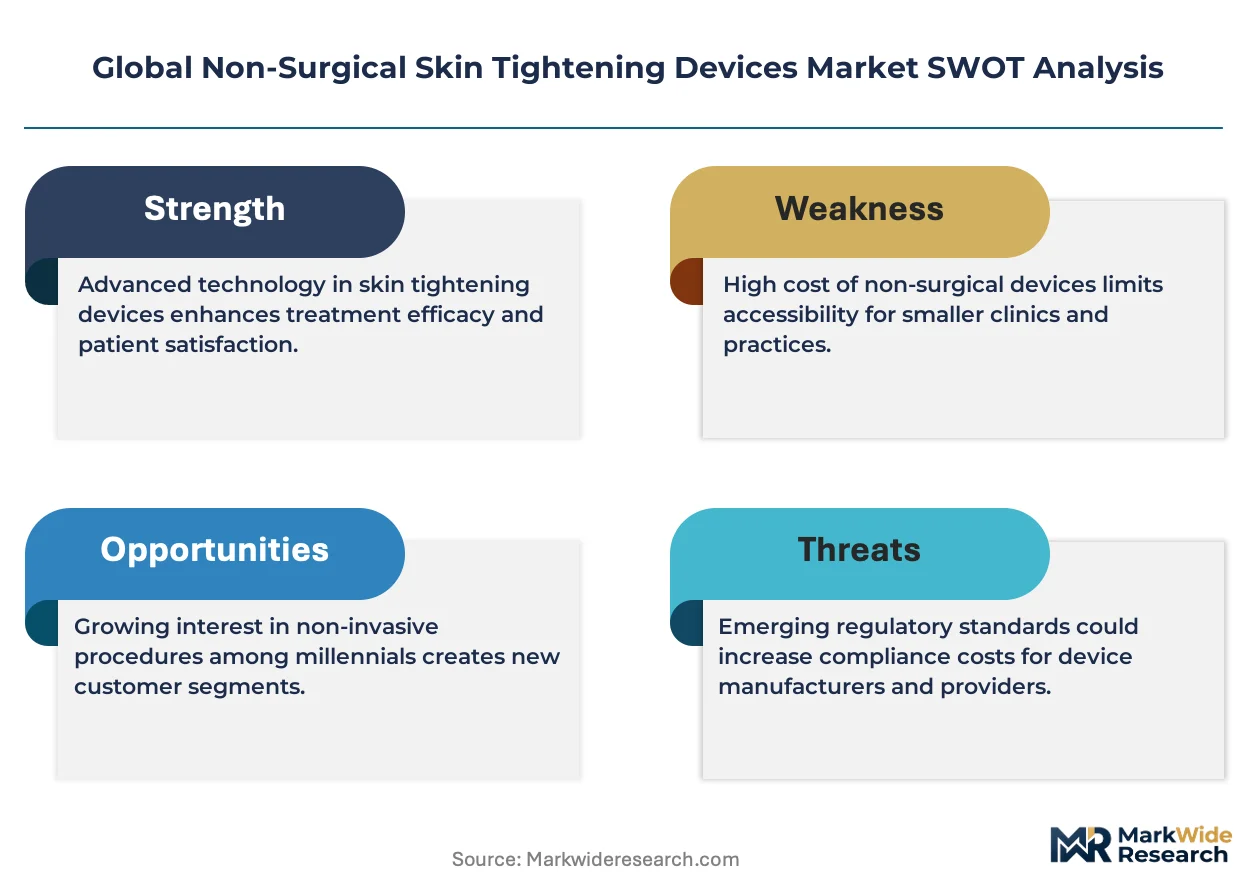
EU MDR clinical evidence mandates gate qualified supply access and premium-tier pricing power, forcing device OEMs to absorb retrospective study costs while tiering offerings by certification completeness. Japanese and German piezoelectric component concentration amplifies this bifurcation, as manufacturers with established notified body relationships capture margin pools unavailable to late entrants.
Pricing Analysis
Input-cost pass-through from precision transducer supply constraints stratifies pricing across three tiers: premium multipolar platforms with integrated muscle stimulation, standard monopolar systems for dermatology workflows, and economy infrared devices for day spa maintenance protocols. Price differentiation hinges on FDA 510(k) clearance tier and EU MDR CE marking completeness, with German and South Korean manufacturers commanding brand premiums. Pricing pressure stems from subscription financing displacement of capital purchase among US clinic rollups, compressing upfront revenue recognition. Independent dermatology practices in Texas and Florida exhibit highest price sensitivity, while Dubai cosmetic centers demonstrate lowest sensitivity due to pre-event package economics.
Supply Chain Analysis
Reverse-logistics flows for transducer refurbishment and applicator head remanufacturing concentrate in Osaka and Munich, extending component lifecycles for premium-tier OEMs while creating secondary supply channels. New production of piezoelectric crystals and radiofrequency generators draws from Japan, Germany, and South Korea, with South Korean manufacturers increasingly integrating muscle stimulation modules in-house. Single-source vulnerability pervades precision transducer supply, as alternative qualified suppliers require 18-month MFDS electromagnetic compatibility recertification. Distribution runs through authorized dealer networks for clinical-grade systems and direct-to-consumer channels for lower-power home-use devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Non-surgical skin tightening devices function as stable compounders, with membership-based medical spa economics generating predictable recurring revenue streams across procedure cycles.
For Market Incumbents: Deepen vertical integration into transducer manufacturing to mitigate Japanese and German supply concentration, while accelerating prospective patient registry infrastructure to defend EU MDR CE marking validity against emerging ultrasound-focused innovators. Prioritize software companion development for AI-guided treatment mapping to differentiate from mid-tier monopolar generalists. For New Entrants and Emerging Players: Launch via subscription financing partnerships with private equity-backed clinic rollups in Florida and Texas, targeting the body contouring application white space where ultrasound penetration depth requirements exceed radiofrequency technical ceilings. Brazil's ANVISA pathway offers fastest regulatory entry for radiofrequency platforms seeking initial revenue traction. For Investors and Strategic Acquirers: Roll-up economics work for regional medical spa chains because membership billing reconciliation complexity creates operational leverage for scaled platforms with native device utilization tracking. The 5-10 year viability window favors platforms with diversified energy modality portfolios over single-technology specialists. Monitor MFDS electromagnetic compatibility testing backlog duration as inflection indicator for Asia-Pacific launch timeline risk.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Post-Market Surveillance Infrastructure | Retrospective patient registry investment protects CE marking validity against notified body scrutiny. |
| AI-Guided Treatment Mapping Development | Algorithmic fluence adjustment compresses technician training curves in mid-tier medical spas. |
| Subscription Equipment Financing Programs | Per-procedure leasing aligns device costs with utilization rates for private equity clinic rollups. |
| Combination Therapy Platform Integration | Fractional laser and bipolar radiofrequency pairing captures premium pricing in Dubai centers. |
| Home-Use Device Channel Expansion | Smartphone-guided protocols open direct-to-consumer revenue previously inaccessible to clinical manufacturers. |
Research Methodology
Multiple input streams — primary interviews with dermatology clinic directors, medical spa operations managers, biomedical engineers at device OEMs, and GPO contracts specialists — were reconciled against secondary validation from FDA 510(k) filings, EU MDR notified body guidance documents, MFDS electromagnetic compatibility standards, and hospital procurement database extracts. Bottom-up procedure volume estimates across Seoul, Los Angeles, Dubai, and São Paulo aesthetic clusters were triangulated with top-down market sizing from capital equipment financing disclosures and membership clinic expansion announcements.
Data-stream reconciliation anchored the analytical framework across the projection horizon, modeling segmentation by product type (radiofrequency, ultrasound, laser, infrared), technology configuration (monopolar, multipolar, bipolar, fractional), application indication (facial rejuvenation, body contouring, wrinkle reduction, cellulite treatment), and end-user archetype (dermatology clinic, medical spa, cosmetic center, plastic surgery clinic). CAGRs were derived from installed base expansion rates and procedure frequency assumptions, with specific weighting for South Korean combination therapy adoption curves and Brazilian ANVISA pathway acceleration.
Forecast precision tightens around the base case; tail outcomes carry wider variance under MFDS testing timeline extensions or EU MDR predicate claim rejection waves. Forecasts reflect assumptions regarding membership model penetration, reimbursement classification stability, and transducer supply continuity. Practitioners should monitor ANVISA regulatory tightening signals and US clinic rollup financing availability for early demand inflection indicators.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Europe Aligner Sheet Market
Medical Devices
Surgical Robotics Performance and Safety Validation Test Platforms Market
Medical Devices
United States Insulin Pumps Market
Medical Devices
Global Robotic Assisted Surgery Systems Market
Medical Devices
Europe Spinal Surgery Devices Market
Medical Devices
Biologic Injectors Market
Medical Devices
Subdural Electrodes Market
Medical Devices
Zygomatic and Pterygoid Implants Market
Medical Devices
Face Mask Device Market
Medical Devices
Global Extremities Market
Medical Devices
Global Canes and Crutches Market
Medical Devices
Ultrasonic Aspirator Market
Medical Devices
Global Medical Device Connectors Market
Medical Devices
Occlusion Microcatheter Market
Medical Devices
Pacemaker Devices Market
Medical Devices
Implant Handpiece Market