
 Global Nasal Cannula Market | 2026-2036
Global Nasal Cannula Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nasal Cannula Market Foresight
The gap between premium silicone cannulas and commodity PVC lines is repositioning procurement criteria across hospital systems and home care networks. ResMed Inc. leverages its sleep apnea ecosystem to bundle high-flow nasal interfaces with device platforms. Fisher & Paykel Healthcare Limited anchors the premium segment through heated humidification integration. Salter Labs competes on manufacturing scale across disposable standard-flow lines.
A nasal cannula is a flexible tube assembly with dual prongs designed to deliver supplemental oxygen or humidified gas directly into the nares, typically constructed from medical-grade polymers with lumen diameters calibrated to flow rates between one and six liters per minute for standard applications and up to fifteen liters for high-flow systems. Its primary purpose is to provide continuous low-to-moderate oxygen delivery with minimal patient discomfort across acute, sub-acute, and chronic care settings. The disposable product category dominates hospital procurement due to infection control protocols, while the pediatric segment commands margin premiums because of specialized sizing requirements and softer material specifications. Home care providers represent the fastest-growing end user channel as reimbursement policies and remote patient monitoring technologies enable decentralized oxygen therapy management.
The U.S. FDA regulates nasal cannulas as Class I or Class II medical devices under 21 CFR 868.5340, mandating biocompatibility testing and material traceability that shapes supplier qualification timelines. Europe's MDR and REACH frameworks impose additional clinical evidence and substance restriction requirements on manufacturers seeking CE marking for polymer components. Stakeholders must monitor how evolving FDA guidance on high-flow nasal oxygen interfaces and the EU's F-Gas Regulation affecting medical-grade polymer feedstocks will reshape material sourcing decisions and competitive positioning.
Market Dynamics
Home care oxygen therapy adoption is compressing hospital procurement cycles as reimbursement frameworks and remote monitoring technologies enable decentralized respiratory management across aging populations.
Growth Catalysts
- FDA Biocompatibility Mandates:Tightened 21 CFR 868.5340 standards for polymer-based devices accelerate transitions toward silicone and latex-free alternatives, creating procurement pull for certified suppliers.
- High-Flow Interface Integration:Heated humidification systems calibrated to fifteen-liter flow rates expand addressable patient populations beyond standard low-flow applications.
- Germany's Reimbursement Density:Chronic respiratory condition coverage frameworks sustain institutional procurement volumes for disposable lines across acute and sub-acute networks.
Market Restraints
- Medical-Grade Polymer Feedstock Volatility:EU F-Gas Regulation restrictions on fluorinated gas use in polymer production create input cost uncertainty for PVC and silicone component manufacturers.
- Supplier Concentration in East Asian Molding:Disposable cannula production clusters in concentrated manufacturing zones expose procurement timelines to single-source geographic risk.
- Standard-Flow Technical Ceiling:Six-liter-per-minute physiological limits for conventional nasal prongs constrain therapy escalation without interface switching.
Strategic Opportunities
- Japan's Home Care Infrastructure:METI-supported decentralized care models and PMDA streamlined device approvals create channel expansion potential for high-flow systems in outpatient settings.
- Pediatric Specialized Sizing:Softer material specifications and dimensional calibration for neonatal populations command margin premiums in underpenetrated acute pediatric segments.
- CE Marking MDR Pathways:Europe's clinical evidence requirements for polymer traceability favor manufacturers with established biocompatibility documentation, consolidating qualification advantages.
Industry Challenges
- Polymer Chemist Talent Scarcity:Formulation expertise for medical-grade silicone-to-skin biocompatibility sits concentrated with specialized compounders, constraining in-house material development.
- ISO 10993 Certification Timelines:Extended cytotoxicity and sensitization testing protocols delay new product launches by twelve to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nasal Cannula Market |
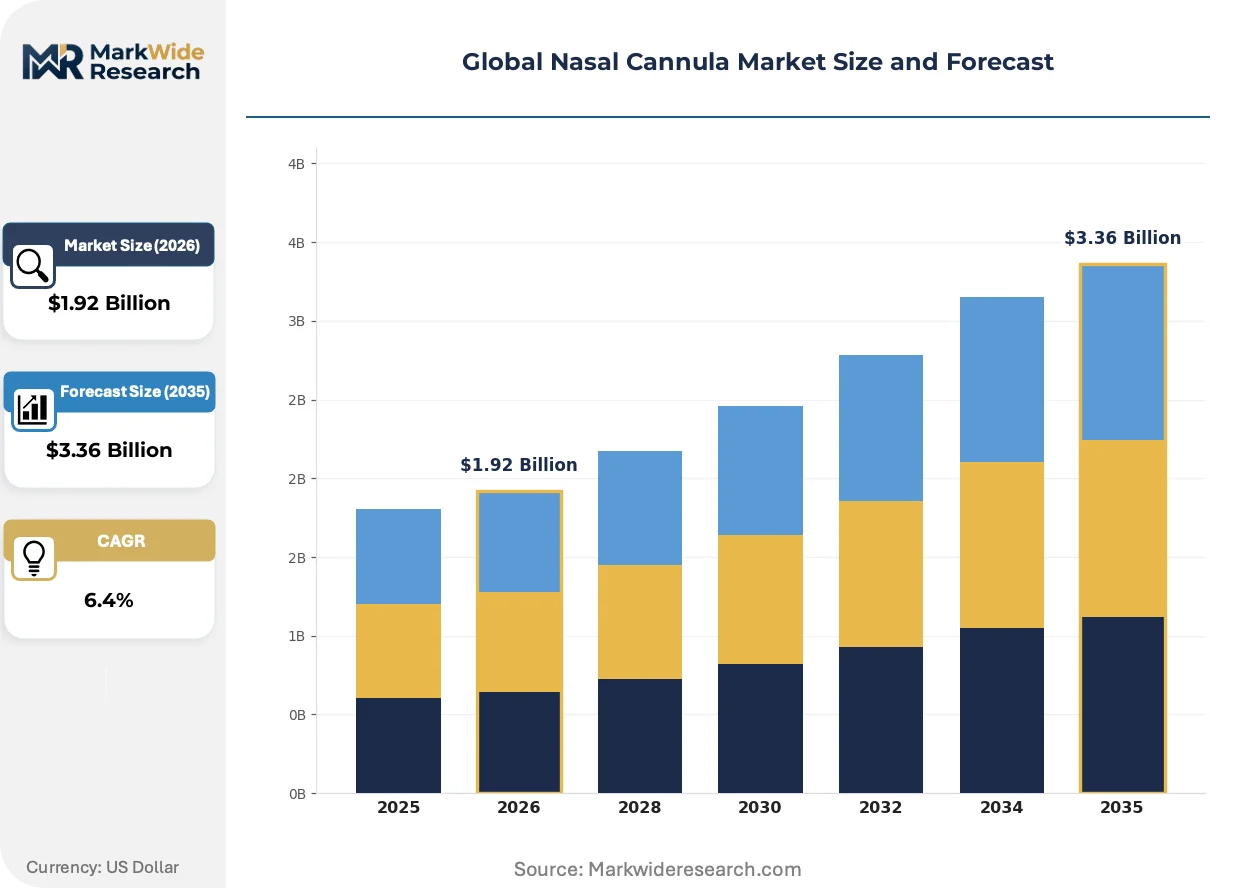
| Market Size in 2026 | $1.92 Billion |
| Market Size in 2035 | $3.36 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Reusable, Pediatric, Adult, Senior Material: PVC, Silicone, Polyurethane, Rubber, Latex-Free Application: Oxygen Therapy, Respiratory Support, Anesthesia, Sleep Apnea Management, Postoperative Care End User: Hospitals, Specialized Clinics, Home Care Providers, Ambulatory Surgery Centers, Long-Term Care Facilities |
| Companies Covered | ResMed Inc., Teleflex Incorporated, Fisher & Paykel Healthcare Limited, Vapotherm Inc., Allied Healthcare Products, Inc., Flexicare Medical Ltd, Salter Labs, Smiths Medical, Drive DeVilbiss Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nasal Cannula Market Shifts & Advancements
Material science advances and regulatory chemistry restrictions are actively reconfiguring competitive advantage around biocompatibility certification rather than manufacturing scale alone.
Silicone nasal prongs calibrated for high-flow oxygen delivery is overtaking PVC alternatives in premium procurement segments. Hospital systems with established infection control protocols specify softer, kink-resistant materials for extended wear applications. This transition compresses margins for commodity-grade manufacturers while rewarding compounders with validated biocompatibility dossiers.
REACH substance restrictions on phthalate plasticizers in polymer medical devices force rapid formulation pivots across European supply chains. Manufacturers must demonstrate SVHC-free material certificates to maintain CE marking validity. Pediatric and long-term care segments face the steepest compliance recertification burdens given extended patient contact durations.
Direct-to-home distribution networks disintermediate traditional durable medical equipment intermediaries as remote patient monitoring platforms integrate oxygen therapy data streams. Home care providers in the United States and Germany now contract directly with manufacturers for scheduled replenishment of disposable lines. This channel compression demands logistics capabilities foreign to legacy hospital-focused suppliers.
Global Nasal Cannula Market Segmentation
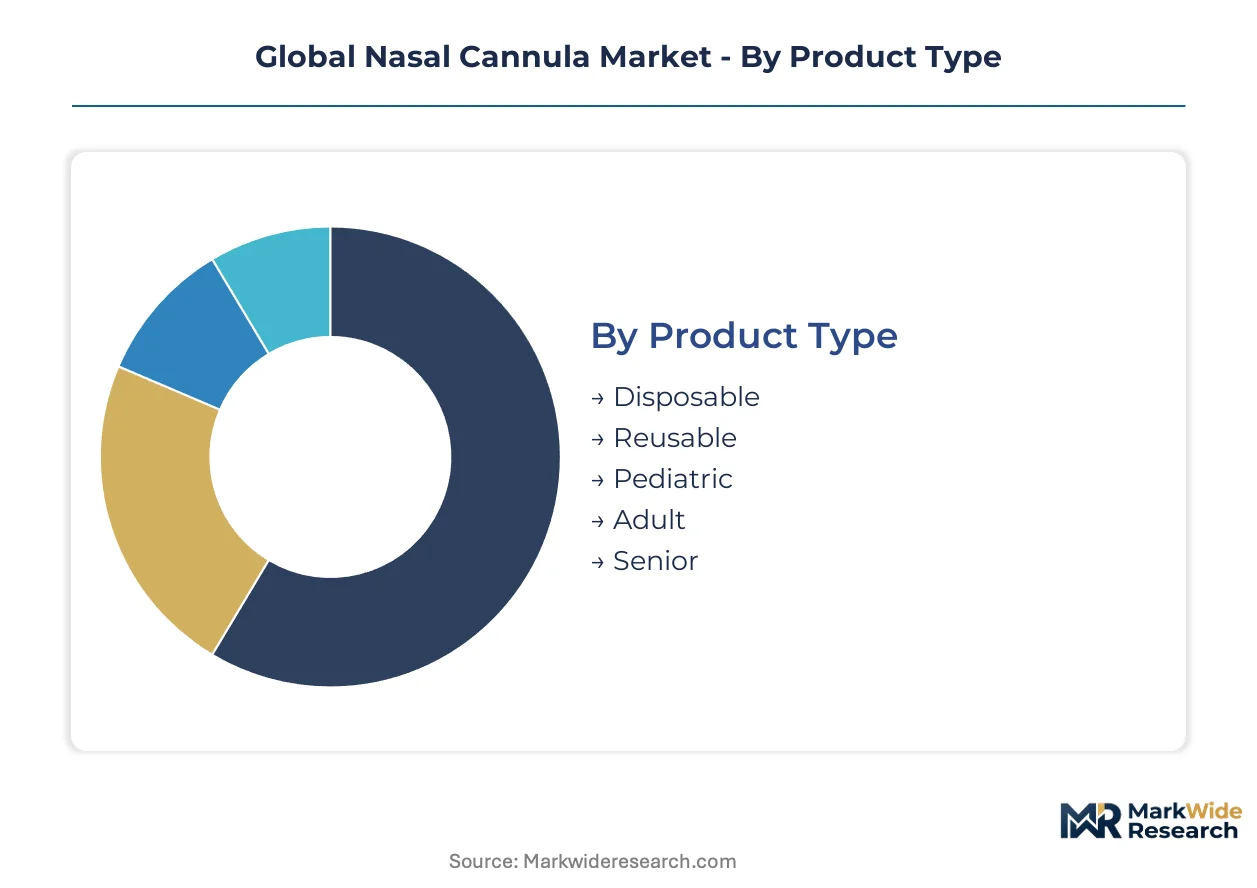
Segmentation in the nasal cannula market reflects divergent clinical requirements across acute care protocols and decentralized respiratory management. Material specifications, patient demographics, and care setting infrastructure create distinct procurement channels with non-overlapping supplier qualification criteria.
Product Type:
Flow rate calibration and wear duration specifications define product architecture across patient populations.
- Disposable:Single-use polymer assemblies dominate hospital procurement under infection control mandates. Demand concentrates in the United States and Germany where reimbursement frameworks prioritize turnover frequency over capital equipment amortization.
- Reusable:Silicone-based lines with sterilization durability serve long-term oxygen therapy patients. Procurement is compressing in home care networks as disposable unit economics improve and biocompatibility certification costs rise.
- Pediatric:Softer durometer specifications and dimensional calibration for neonatal anatomy command margin premiums in acute pediatric segments.
- Adult:Standard-flow configurations between one and six liters per minute constitute the volume baseline across institutional procurement.
- Senior:Extended-wear comfort specifications with kink-resistant lumens address aging populations on continuous oxygen therapy in Japan's home care infrastructure.
Mature deployment sits with Adult configurations. Newer deployment is concentrated in Pediatric and Senior segments with specialized material requirements.
Material:
Regulatory chemistry restrictions and biocompatibility certification timelines reshape compounder competitive position.
- PVC:Commodity-grade polymer with plasticizer-dependent flexibility faces REACH substance restrictions across European supply chains. Manufacturers must demonstrate SVHC-free certificates to maintain CE marking validity.
- Silicone:Medical-grade formulations with validated ISO 10993 dossiers capture premium procurement in high-flow and extended-wear applications. Supply concentrates with specialized compounders possessing in-house cytotoxicity testing capabilities.
- Polyurethane:Kink-resistant alternative with intermediate biocompatibility profiles serves specific high-flow interface integrations.
- Rubber:Legacy material with limited new product development due to sensitization testing burdens.
- Latex-Free:Mandatory specification for pediatric and long-term care segments with extended patient contact durations.
Volume concentration remains with PVC. Value expansion is climbing the fastest in Silicone as FDA biocompatibility mandates accelerate material transitions.
Application:
Clinical indication severity and therapy duration determine interface specification and procurement channel.
- Oxygen Therapy:Continuous low-to-moderate delivery applications from one to fifteen liters per minute constitute the foundational use case across acute and home care settings.
- Respiratory Support:High-flow nasal oxygen systems with heated humidification integration expand addressable patient populations beyond standard physiological limits.
- Anesthesia:Pre-oxygenation and intraoperative supplemental delivery requirements in surgical suites demand specialized connector compatibility.
- Sleep Apnea Management:Interface bundling with positive airway pressure devices creates ecosystem-dependent procurement in integrated device platforms.
- Postoperative Care:Short-duration oxygen weaning protocols in recovery units prioritize disposable economics over extended-wear material specifications.
Established penetration sits with Oxygen Therapy. Steepest expansion trajectory is concentrated in Sleep Apnea Management as remote patient monitoring platforms integrate therapy data streams.
End User:
Channel infrastructure and reimbursement density determine procurement scale and supplier relationship structure.
- Hospitals:Infection control protocols and centralized purchasing departments enforce disposable-only policies with volume contracting.
- Specialized Clinics:Pulmonary function testing and respiratory therapy centers require calibrated flow accuracy for diagnostic applications.
- Home Care Providers:Direct-to-manufacturer replenishment contracts are displacing durable medical equipment intermediaries in the United States and Germany.
- Ambulatory Surgery Centers:Cost-conscious procurement with limited storage infrastructure favors lean inventory and rapid turnover.
- Long-Term Care Facilities:Extended patient contact durations drive latex-free and softer material specifications with compliance documentation requirements.
Procurement volume anchors with Hospitals. Channel expansion is gaining share fastest in Home Care Providers as decentralized respiratory management infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Minneapolis anchors North American respiratory device manufacturing, with supplier networks extending into Ohio and California medical device corridors. FDA 21 CFR 868.5340 enforcement shapes procurement timelines across hospital systems.
United States
Home care oxygen therapy expansion and Medicare reimbursement density drive procurement volumes. FDA biocompatibility mandates under 21 CFR 868.5340 accelerate silicone material transitions. Minneapolis and San Diego clusters concentrate high-flow interface development.
Germany
Chronic respiratory condition coverage frameworks sustain institutional demand for disposable lines. REACH substance restrictions on phthalate plasticizers force rapid PVC formulation pivots. North Rhine-Westphalia medical device manufacturers face steepest compliance recertification burdens.
Japan
METI-supported decentralized care models and aging demographics expand outpatient respiratory management. PMDA streamlined device approvals reduce qualification timelines for high-flow systems. Tokyo-Osaka corridor concentrates pediatric specialized sizing production.
China
Domestic medical polymer compounding capacity scales to meet hospital procurement growth. NMPA Class II device registration requirements shape supplier qualification. Yangtze River Delta molding clusters supply disposable cannula components to Asia-Pacific distributors.
India
CDSCO medical device rules and import substitution policies nurture domestic manufacturing. BIS standards for polymer medical devices create certification entry barriers. Gujarat and Maharashtra industrial corridors attract contract molding investments.
Global Nasal Cannula Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material certification and heated humidification integration. The vendor base stratifies into three tiers: integrated device-platform bundlers, specialized high-flow interface developers, and scale-driven disposable manufacturers. Strategic moves concentrate on M&A for biocompatibility dossiers and backward integration into medical-grade silicone compounding.
Within the integrated-platform tier, ResMed Inc. and Fisher & Paykel Healthcare Limited exemplify ecosystem-dependent positioning. Salter Labs occupies a position among scale-focused disposable manufacturers. These three anchors represent divergent competitive vectors: sleep apnea ecosystem bundling, heated humidification premium positioning, and manufacturing scale across standard-flow lines.
| Leading Market Players |
|---|
| ResMed Inc. |
| Teleflex Incorporated |
| Fisher & Paykel Healthcare Limited |
| Vapotherm Inc. |
| Allied Healthcare Products, Inc. |
| Flexicare Medical Ltd |
| Salter Labs |
| Smiths Medical |
| Drive DeVilbiss Healthcare |
| Others |
Supply & Pricing Matrix
Medical-grade silicone feedstock indices cascade through polymer compounding tiers into three distinct procurement bands: ISO 10993-certified silicone commands premium positioning in high-flow heated humidification systems, while commodity PVC faces margin compression from REACH phthalate restrictions and biocompatibility recertification burdens.
Pricing Analysis
Value-based pricing anchored to patient contact duration and infection control outcomes stratifies procurement across hospital systems and home care networks. Biocompatibility certification grade and heated humidification integration serve as the primary price differentiation drivers, with FDA 21 CFR 868.5340 compliance timelines widening spreads between certified and uncertified suppliers. Cost compression in standard-flow disposable lines intensifies as manufacturing scale advantages concentrate with East Asian molders. Ambulatory surgery centers exhibit the highest price sensitivity due to lean inventory protocols, while long-term care facilities prioritize material specification over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Yangtze River Delta molding clusters for disposable cannula components and specialized German compounders for medical-grade silicone formulations. Raw material dependencies center on polymer feedstocks, plasticizer additives, and heated humidification elements. Tariff exposure on Chinese-molded components poses structural risk to procurement timelines for North American distributors. Distribution runs through durable medical equipment intermediaries in legacy hospital channels, while direct-to-manufacturer replenishment contracts displace traditional wholesalers in United States and German home care networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nasal cannula market sits in a material-transition phase as silicone-based high-flow interfaces displace legacy PVC standard-flow lines across premium procurement segments.
For Market Incumbents: Anchor market position through backward integration into medical-grade silicone compounding capabilities, securing captive supply of ISO 10993-certified formulations against polymer chemist talent scarcity. Defend against ecosystem bundlers like ResMed by deepening hospital system partnerships for heated humidification integration and expanding direct-to-home replenishment infrastructure to match channel compression trends.
For New Entrants and Emerging Players: Launch via direct-to-manufacturer distribution models targeting Japan's METI-supported home care infrastructure, where PMDA streamlined approvals reduce qualification barriers for high-flow systems. White-space opportunities concentrate in pediatric specialized sizing with softer durometer specifications, an underpenetrated acute segment commanding margin premiums. Target Germany's chronic respiratory reimbursement density with SVHC-free material certificates to bypass incumbent REACH compliance advantages.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale silicone compounders with validated biocompatibility dossiers in North Rhine-Westphalia and Minneapolis medical device corridors. Long-term viability over a five-to-ten-year horizon rests on material science capabilities rather than manufacturing scale alone. The signal to watch is FDA guidance evolution on high-flow nasal oxygen interfaces, which would reshape competitive positioning around heated humidification integration.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 10993 Certification Investment | Accelerates silicone material transitions under tightened FDA 21 CFR 868.5340 biocompatibility mandates. |
| Heated Humidification Integration | Captures premium positioning in high-flow oxygen therapy expansion beyond standard-flow physiological limits. |
| Direct-to-Home Distribution Buildout | Disintermediates durable medical equipment channels in United States and German reimbursement-dense markets. |
| Pediatric Specialized Sizing Development | Commands margin premiums through softer durometer specifications for neonatal anatomy requirements. |
| REACH SVHC-Free Material Pivot | Maintains CE marking validity across European supply chains facing phthalate plasticizer restrictions. |
Research Methodology
Independent corroboration across hospital procurement databases, GPO contracts, and CMS Medicare reimbursement filings underwrites the qualitative findings in this study. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and home care provider logistics directors combined with secondary validation from FDA 510(k) filings, EMA MDR submissions, and EU REACH SVHC candidate lists. Bottom-up demand modeling across patient population segments triangulates against top-down manufacturer capacity assessments.
Comparable-period anchoring to historical reference data establishes baseline growth trajectories across the projection horizon. Segmentation dimensions modeled include flow rate calibration, material specification tier, patient demographic, care setting infrastructure, and regional regulatory cluster. CAGRs derive from installed base expansion rates, therapy transition patterns, and reimbursement policy evolution. Forecast inputs incorporate polymer feedstock price volatility indices and medical device approval pipeline velocities.
Regulatory guidance revisions, polymer chemist labor market tightness, and reimbursement policy shifts are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions about material transition timelines and certification backlog durations. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Europe Renal Denervation Devices Market
Medical Devices
Transradial Closure Devices Market
Medical Devices
Germany Contraceptive Devices Market
Medical Devices
Kidney Stone Management Devices Market
Medical Devices
Europe Implantable Medical Devices Market
Medical Devices
United Kingdom Contraceptive Devices Market
Medical Devices
Americas Medical Suction Device Market
Medical Devices
Urine Flow Meters Market
Medical Devices
Respiratory Devices Market
Medical Devices
Global Amniocentesis Needle Market
Medical Devices
Global Coagulation-Hemostasis Analyzer Market
Medical Devices
Intrauterine Devices (IUD) Market
Medical Devices
Global Otoscopes Market
Medical Devices
Global Wheelchair Market
Medical Devices
Asia-Pacific Manual Resuscitators Market
Medical Devices
Organ Care Systems (OCS) Market