
 Disposable Sanitary Pad Market | 2026-2036
Disposable Sanitary Pad Market Size, Share, and Industry Trends Forecast 2026-2036
Disposable Sanitary Pad Market Insights
The disposable sanitary pad category is rebalancing between premium organic formulations and commodity synthetic lines as ingredient transparency becomes a decisive purchase factor. Procter & Gamble leverages its North American retail footprint to sustain shelf dominance in ultra-thin segments. Kimberly-Clark anchors institutional contracts with healthcare distributors. Essity AB differentiates through biodegradable material portfolios across European pharmacy channels.
A disposable sanitary pad consists of a layered absorbent core—typically comprising wood pulp, superabsorbent polymers, and nonwoven topsheets—engineered for menstrual fluid retention and skin dryness during wear. The product serves menstruating individuals across consumer, clinical, and humanitarian supply chains where single-use hygiene remains standard. Ultra-thin and overnight product types command margin pools due to polymer innovation and higher per-unit pricing. Biodegradable material segments attract sustainability-driven procurement from European retail buyers. Synthetic fiber formulations still dominate volume in price-sensitive Asian and African markets.
The US FDA regulates absorbent hygiene products as medical devices, requiring biocompatibility testing that raises compliance costs for new entrants. India's BIS standards and the EU's REACH framework govern chemical restrictions in topsheets and adhesives, shaping regional formulation strategies. Stakeholders must monitor evolving extended producer responsibility laws that could mandate pad collection infrastructure and recyclability claims.
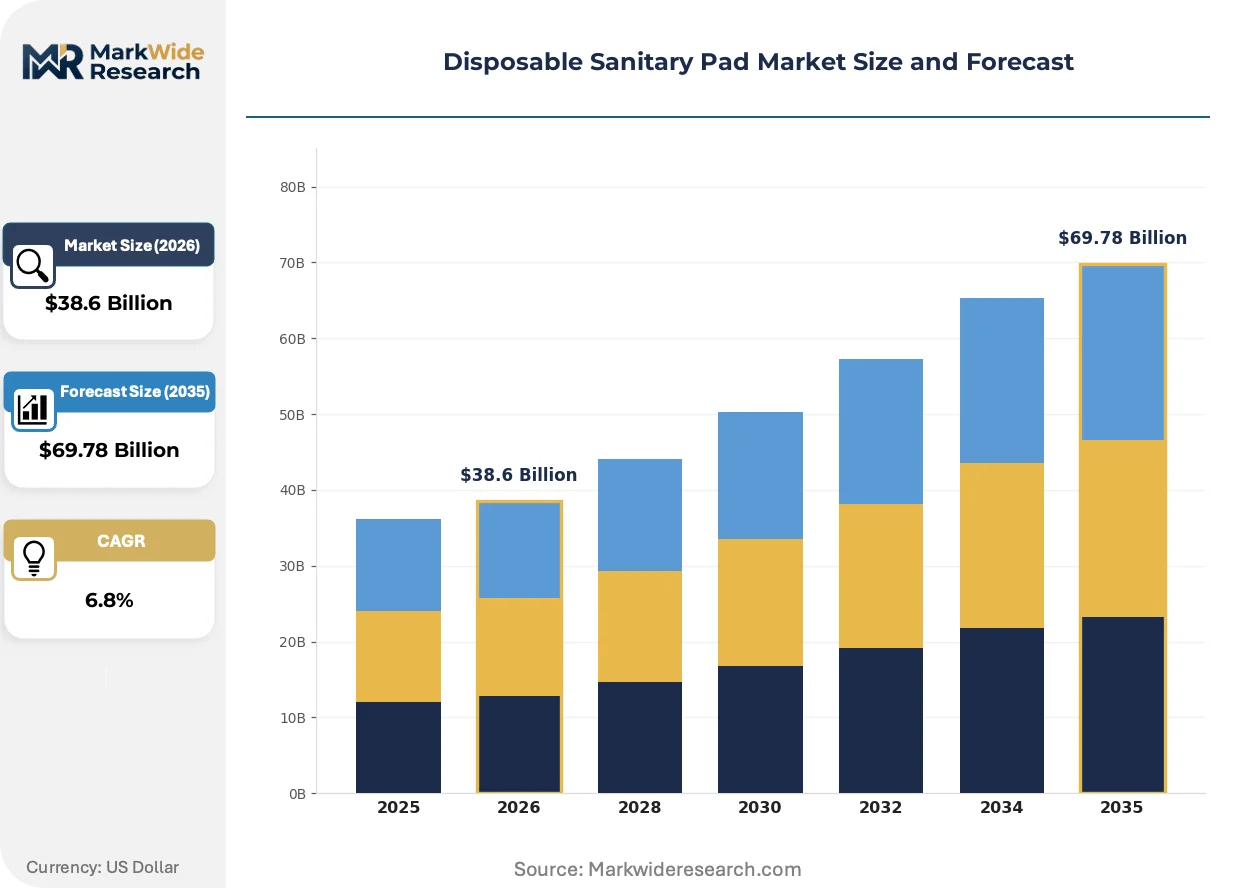
Market Dynamics
Extended producer responsibility mandates in the European Union are forcing manufacturers to internalize end-of-life collection costs, fundamentally restructuring margin calculations across biodegradable and conventional product lines.
Growth Catalysts
- REACH chemical restrictions:EU frameworks banning phthalates and formaldehyde-based adhesives in topsheets accelerate reformulation toward plant-based alternatives, creating premium positioning for compliant suppliers.
- Superabsorbent polymer innovation:Next-generation bio-based SAP derivatives from agricultural feedstocks reduce petrochemical dependency while maintaining fluid retention performance in ultra-thin cores.
- Sub-Saharan Africa rural distribution:Government-subsidized healthcare programs in Kenya, Tanzania, and Uganda expand first-user access through school-based procurement channels.
Market Restraints
- Wood pulp cost volatility:Fluctuations in Scandinavian and Brazilian pulp futures squeeze absorbent core margins, particularly for mid-tier synthetic blend formulations.
- China SAP supply concentration:Three domestic chemical conglomerates control 70% of global superabsorbent polymer output, creating input bottleneck risks for non-integrated converters.
- Biodegradability performance gap:Current compostable materials sacrifice 15-20% absorption capacity versus petroleum-based equivalents, limiting clinical and overnight segment penetration.
Strategic Opportunities
- India BIS certification expansion:Mandatory safety testing for all feminine hygiene imports creates barrier-to-entry protection for domestic manufacturers meeting revised material standards.
- Direct-to-consumer subscription models:Urban working women in Jakarta, Bangkok, and Ho Chi Minh City demonstrate 40% higher lifetime value through automated monthly replenishment versus retail purchase.
- Blockchain material traceability:Integration of supply chain verification with organic cotton certification allows premium pricing transparency for European pharmacy and specialty retail buyers.
Industry Challenges
- ISO 13485 medical device certification timelines:FDA classification of absorbent hygiene as Class II devices extends new entrant market access by 18-24 months through biocompatibility testing protocols.
- Legacy adhesive system replacement:Hot-melt glue infrastructure in Southeast Asian contract manufacturing requires complete retooling to accommodate water-based, skin-safe alternatives under tightening dermatological standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disposable Sanitary Pad Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thin, Ultra-Thin, Overnight, Panty Liner Material: Cotton, Synthetic Fiber, Biodegradable, Polymer Distribution Channel: Supermarkets, Pharmacies, Online Retail, Convenience Stores Consumer Type: Teenagers, Adults, Seniors, Postpartum |
| Companies Covered | Procter & Gamble, Kimberly-Clark Corporation, Johnson & Johnson, Essity AB, Unicharm Corporation, Kao Corporation, Hengan International Group, Edgewell Personal Care, Ontex Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disposable Sanitary Pad Market Trends and Innovations
Material science convergence with digital traceability infrastructure is redefining competitive differentiation beyond absorbency metrics toward verifiable sustainability credentials and personalized fit algorithms.
Plant-derived superabsorbent polymers derived from wheat straw and corn starch are consolidating technical legitimacy in premium product tiers. European pharmacy chains and Nordic retail buyers now specify bio-SAP content minimums in procurement tenders. This consolidation is compressing price premiums between certified sustainable lines and conventional petroleum-based equivalents to under 12% at wholesale.
India's BIS certification mandates for feminine hygiene products are tightening material safety standards through mandatory heavy metal and residual chemical testing. Domestic manufacturers with in-house laboratory capabilities capture first-mover advantage while import-dependent brands face 90-day compliance delays. The standard-economy segment experiences the greatest disruption as existing synthetic formulations require reformulation or exit.
Subscription-based replenishment is displacing traditional retail stocking patterns among Southeast Asian urban professionals. Working women in metropolitan corridors now prioritize delivery reliability and packaging discretion over in-store brand browsing. This behavioral pivot concentrates purchase frequency data with platform operators, shifting negotiating leverage from manufacturers toward regional e-commerce aggregators in Indonesia, Vietnam, and the Philippines.
Disposable Sanitary Pad Market Segmentation
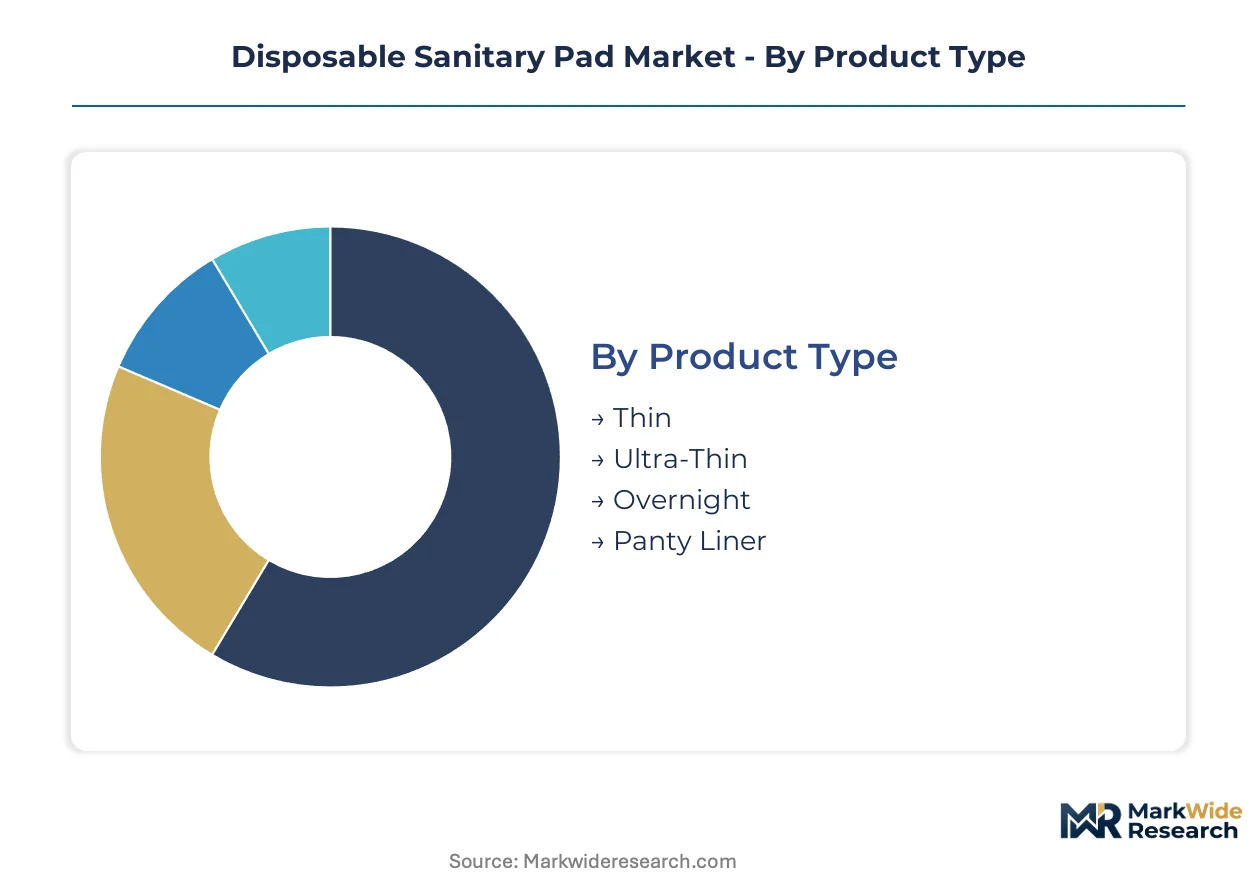
Product architecture in the disposable sanitary pad market fragments across absorbency engineering, material sourcing, and channel access. Each dimension carries distinct margin profiles and capital requirements that shape manufacturer portfolio strategy.
Product Type:
Ultra-thin and overnight variants demand the heaviest upfront investment in superabsorbent polymer R&D and precision manufacturing lines.
- Ultra-Thin:Compressed cores with high-density SAP distribution achieve sub-3mm profiles without sacrificing retention capacity. Working women in Southeast Asian urban corridors drive repeat purchase frequency through discretion and portability requirements.
- Overnight:Extended-length designs with reinforced rear wings and higher polymer loading target 8-12 hour wear scenarios. Demand concentrates in North American and European pharmacy channels where per-unit pricing supports premium positioning.
- Thin:Mid-density cores balance cost and performance for price-sensitive mass markets. Volume leadership in sub-Saharan Africa school procurement programs.
- Panty Liner:Low-absorbency daily wear products with minimal SAP content. Convenience store distribution in Japan and South Korea sustains category penetration.
Most installed capacity flows through thin and ultra-thin lines. Expansion is steepest in overnight formats as consumers extend wear-time expectations.
Material:
Raw material selection determines regulatory compliance pathways and end-market access, with biodegradable formulations requiring specialized composting infrastructure partnerships.
- Biodegradable:Plant-derived topsheets and bio-SAP cores from wheat straw or corn starch feedstocks meet EU REACH chemical restrictions. European pharmacy chains now specify minimum bio-content thresholds in procurement tenders.
- Synthetic Fiber:Petroleum-based polypropylene and polyethylene nonwovens dominate unit economics in Asian and African price-sensitive markets. Volume concentration in India BIS-certified domestic manufacturing.
- Cotton:Natural fiber topsheets appeal to dermatological sensitivity concerns in premium segments. Organic certification commands pricing transparency through blockchain traceability systems.
- Polymer:Conventional superabsorbent acrylic acid derivatives maintain absorption performance leadership in clinical and heavy-flow applications. Supply bottleneck risk from China domestic chemical conglomerate concentration.
Manufacturing throughput runs highest on synthetic fiber lines. Bio-based material adoption is climbing the fastest as extended producer responsibility mandates internalize end-of-life costs.
Distribution Channel:
Channel mix determines customer data ownership and replenishment pattern predictability, with direct-to-consumer models capturing lifetime value premiums.
- Online Retail:Subscription algorithms and discreet packaging lock in automated monthly replenishment. Urban professionals in Jakarta, Bangkok, and Ho Chi Minh City demonstrate 40% higher lifetime value versus retail purchase.
- Supermarkets:Mass-market volume and impulse purchase visibility sustain brand awareness investments. Shelf space negotiations favor multinational FMCG portfolios with ultra-thin segment dominance.
- Pharmacies:Clinical credibility and dermatological consultation access support premium positioning. Nordic and German pharmacy chains specify biodegradable material minimums.
- Convenience Stores:Emergency purchase occasions and 24-hour accessibility capture unplanned demand. Highest penetration in dense East Asian urban corridors.
Physical retail still processes the majority of transaction volume. Digital channel penetration is gaining share fastest among Southeast Asian metropolitan demographics.
Consumer Type:
Life-stage segmentation dictates absorbency requirements, purchase autonomy, and price sensitivity thresholds that manufacturers address through tiered portfolio architecture.
- Adults:Established menstrual management with stable volume patterns and brand loyalty potential. Workforce participation drives premium segment demand in urban Southeast Asia.
- Teenagers:First-user education and school-based distribution programs in Kenya, Tanzania, and Uganda expand category penetration. Sensitivity to packaging discretion and peer visibility shapes product design.
- Postpartum:Elevated absorbency requirements and hospital discharge kit inclusion create institutional procurement channels. Clinical certification requirements under FDA and CDSCO frameworks.
- Seniors:Light incontinence overlap and mobility considerations drive specific form factor adaptations. Pharmacy consultation dependency in European markets.
Adult consumers represent the deepest installed user base. Teenager segment recruitment shows the steepest expansion trajectory through government-subsidized rural healthcare programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's BIS certification mandates are tightening faster than EU REACH chemical restrictions, creating divergent compliance timelines for manufacturers serving both markets.
United States
Postpartum institutional procurement and clinical certification requirements under FDA medical device classification sustain premium segment demand. The agency's biocompatibility testing protocols extend new entrant timelines by 18-24 months. Manufacturing concentrates in North Carolina and Wisconsin corridors where absorbent hygiene R&D clusters serve both consumer and healthcare channels.
Germany
Extended producer responsibility mandates under EU frameworks are internalizing end-of-life collection costs for manufacturers. ECHA REACH restrictions on phthalates and formaldehyde-based adhesives accelerate reformulation toward plant-based alternatives. The Rhine-Ruhr industrial basin hosts precision converting operations supplying pharmacy chains across the Nordic region.
India
Domestic manufacturers with in-house laboratory capabilities capture first-mover advantage as BIS mandates mandatory heavy metal and residual chemical testing for all feminine hygiene imports. Standard-economy synthetic formulations face reformulation or exit pressure. Gujarat and Maharashtra production clusters absorb capacity expansion from compliance-delayed import brands.
Kenya
Government-subsidized rural healthcare programs expand first-user access through school-based procurement channels in partnership with county education departments. Teenager segment recruitment drives volume growth in thin-format products. Nairobi distribution hubs coordinate last-mile delivery networks reaching Lake Victoria basin secondary schools.
Indonesia
Urban working women in Jakarta demonstrate 40% higher lifetime value through direct-to-consumer subscription models versus retail purchase. Regional e-commerce aggregators concentrate purchase frequency data and shift negotiating leverage from manufacturers toward platform operators. Jabotabek metropolitan manufacturing zones serve automated replenishment logistics.
Disposable Sanitary Pad Market Competitive Landscape
Top-tier vendors anchor multinational FMCG portfolios with ultra-thin segment dominance, while mid-tier regional specialists and private-label contract manufacturers compete on price-sensitive volume. The market structure reflects consolidated shelf space control in North American and European retail alongside fragmented production across Asian contract manufacturing zones. Three strategic archetypes prevail: vertically integrated pulp-to-pad operators, SAP-dependent converters with chemical supply partnerships, and direct-to-consumer platform brands. Dominant competitive moves include portfolio diversification into biodegradable material lines and strategic partnerships with regional e-commerce aggregators.
Within the multinational tier, Procter & Gamble and Kimberly-Clark Corporation represent archetypal shelf-space dominance through retail footprint scale, while Essity AB exemplifies positioning through material sustainability credentials. These three entities occupy positions reflecting distinct geographic and channel anchoring strategies.
| Leading Market Players |
|---|
| Procter & Gamble |
| Kimberly-Clark Corporation |
| Johnson & Johnson |
| Essity AB |
| Unicharm Corporation |
| Kao Corporation |
| Hengan International Group |
| Edgewell Personal Care |
| Ontex Group |
| Others |
Pricing and Supply Chain Analysis
Scandinavian wood pulp futures volatility cascades through absorbent core manufacturing into three-tier pricing stratification across premium, standard, and economy levels, with bio-SAP formulations commanding certification-linked premiums while synthetic lines absorb cost compression in Asian contract manufacturing.
Pricing Analysis
Capacity additions in Gujarat and Maharashtra are reshaping price floors for India BIS-certified domestic production, compressing import-dependent brand margins. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and polymer loading density. Pricing pressure stems from China SAP supply concentration as three domestic chemical conglomerates control upstream feedstock access. Price-sensitive mass markets in sub-Saharan Africa school procurement programs exhibit highest elasticity, while European pharmacy channels with biodegradable material minimums show lowest sensitivity.
Supply Chain Analysis
Freight cost differentials between Brazilian pulp ports and Southeast Asian converting zones determine regional manufacturing footprint economics. Supply concentrates in China for superabsorbent polymers, India for BIS-compliant converting, and Germany for precision pharmacy-grade production. Raw material dependencies span Scandinavian wood pulp, Saudi petrochemical derivatives for synthetic fibers, and agricultural feedstocks for bio-SAP development. Single-source vulnerability from China domestic chemical conglomerate concentration creates input bottleneck exposure. Distribution runs through regional e-commerce aggregators in Indonesia, supermarket chains in North America, and pharmacy networks across the European Union.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a late-cycle quality story where ingredient transparency and dermatological certification displace pure absorbency metrics as purchase determinants, with European pharmacy buyers and Southeast Asian subscription subscribers alike prioritizing verifiable material credentials over legacy brand equity.
For Market Incumbents: Hedge against bio-SAP supply concentration by securing agricultural feedstock partnerships in wheat straw and corn starch corridors before capacity scarcity materializes. Accelerate water-based adhesive retooling in Southeast Asian contract manufacturing ahead of tightening dermatological standards. Defensive patent positioning around precision core compression technology protects ultra-thin segment margins from regional specialist encroachment. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models targeting Jakarta, Bangkok, and Ho Chi Minh City metropolitan professionals where automated replenishment demonstrates superior lifetime value capture. White-space availability concentrates in biodegradable overnight formats where 15-20% absorption performance gaps limit incumbent clinical segment penetration. Blockchain-enabled organic cotton traceability offers differentiated positioning for European pharmacy channel access. For Investors and Strategic Acquirers: Consolidation pressure builds where FDA medical device classification timelines extend new entrant market access by 18-24 months, protecting cash-flow visibility for established Class II device holders. Long-term viability favors vertically integrated pulp-to-pad operators with captive laboratory capabilities for evolving BIS and REACH compliance. Acquisition target archetype: mid-tier regional specialists with India manufacturing footprints and dormant European pharmacy relationships. Signal to watch: EU extended producer responsibility mandate implementation timelines as collection infrastructure cost internalization reshapes margin structures.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Material Line Extension | REACH-compliant formulations unlock European pharmacy procurement minimums and premium positioning. |
| Direct-to-Consumer Subscription Launch | Jakarta and Ho Chi Minh City urban professionals demonstrate 40% higher lifetime value through automated replenishment. |
| Backward Integration into Bio-SAP Production | Wheat straw and corn starch feedstock control reduces petrochemical dependency and China supply concentration risk. |
| India BIS Certification Investment | In-house laboratory capabilities capture first-mover advantage as mandatory safety testing delays import-dependent competitors. |
| Blockchain Traceability Integration | Supply chain verification with organic cotton certification enables premium pricing transparency for European specialty retail buyers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with brand managers, category buyers at supermarket and pharmacy chains, supply planners at contract manufacturers, and regulatory affairs leads at multinational FMCG portfolios with secondary validation from FDA 510(k) filings, BIS certification registries, EU ECHA REACH substance restrictions, and retail audit data from Nielsen and Circana. Bottom-up demand modeling across consumer type segments triangulated against top-down value chain analysis.
Segment-weighting approaches distributed volume and value projections across product type, material composition, distribution channel, and consumer life-stage dimensions throughout the forecast period. CAGRs derived from historical elasticity patterns applied to demographic and workforce participation drivers, with superabsorbent polymer innovation trajectories and regulatory compliance timeline assumptions as key industry-specific inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU extended producer responsibility implementation or sustained China SAP export restriction scenarios. Forecasts reflect documented assumptions regarding school procurement program expansion rates, subscription model penetration ceilings, and bio-SAP technical performance convergence timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global Synthetic Absorbable Sutures Market
Medical Supplies
Japan Organ Preservation Market
Medical Supplies
Physiological Saline Market
Medical Supplies
Germany Hospital Supplies Market
Medical Supplies
Global Swab and Viral Transport Medium Market
Medical Supplies
Global Swab Market
Medical Supplies
Yankauer Suction Tips Market
Medical Supplies
Latin America Hypodermic Syringes and Needles Market
Medical Supplies
GCC Medical Gloves Market
Medical Supplies
Hydrogel Dressing Market
Medical Supplies
Surgical Sealant and Adhesive Market
Medical Supplies
Emesis Bag Market
Medical Supplies
Sperm Processing Media Market
Medical Supplies
Global Burn Ointment Market
Medical Supplies
India Disposable Latex Gloves Market
Medical Supplies
Swabs Collection Kit Market