
 Diode Laser Aesthetic Medical Device Market | 2026-2036
Diode Laser Aesthetic Medical Device Market Size, Share, and Industry Trends Forecast 2026-2036
Diode Laser Aesthetic Medical Device Market Insights
Market Context
The capital-intensity gap between established manufacturers and emerging competitors is collapsing as semiconductor foundries standardize pump laser diode sourcing. Alma Lasers leverages vertical integration across its Israel-based manufacturing to sustain margin structures that smaller competitors cannot replicate. Candela Medical anchors its position through dominant channel relationships with US dermatology group purchasing organizations.
Technical Definition and Segment Structure
Diode laser aesthetic medical devices generate coherent light at wavelengths between 800 nm and 1064 nm through electrically pumped semiconductor junctions, converting electrical energy directly into laser emission for selective photothermolysis of melanin, hemoglobin, or water in targeted tissue. Hair removal applications occupy the largest revenue pool within product type segmentation, while skin rejuvenation represents the fastest-expanding category as fractional dual-wavelength systems displace older IPL platforms. Dermatology centers command premium pricing power within end-user segmentation due to physician oversight requirements and higher reimbursement rates for medical-grade procedures versus beauty salon installations.
Regulatory Environment
FDA 510(k) pathways govern US market access for diode laser systems, while the EU Medical Device Regulation mandates notified body certification under stricter clinical evidence requirements than the preceding MDD framework. ISO 13485 quality management certification functions as a baseline procurement filter for institutional buyers across both jurisdictions. Stakeholders must monitor evolving state-level scope-of-practice regulations that determine whether non-physician operators can independently administer laser treatments in clinic settings.
Market Dynamics
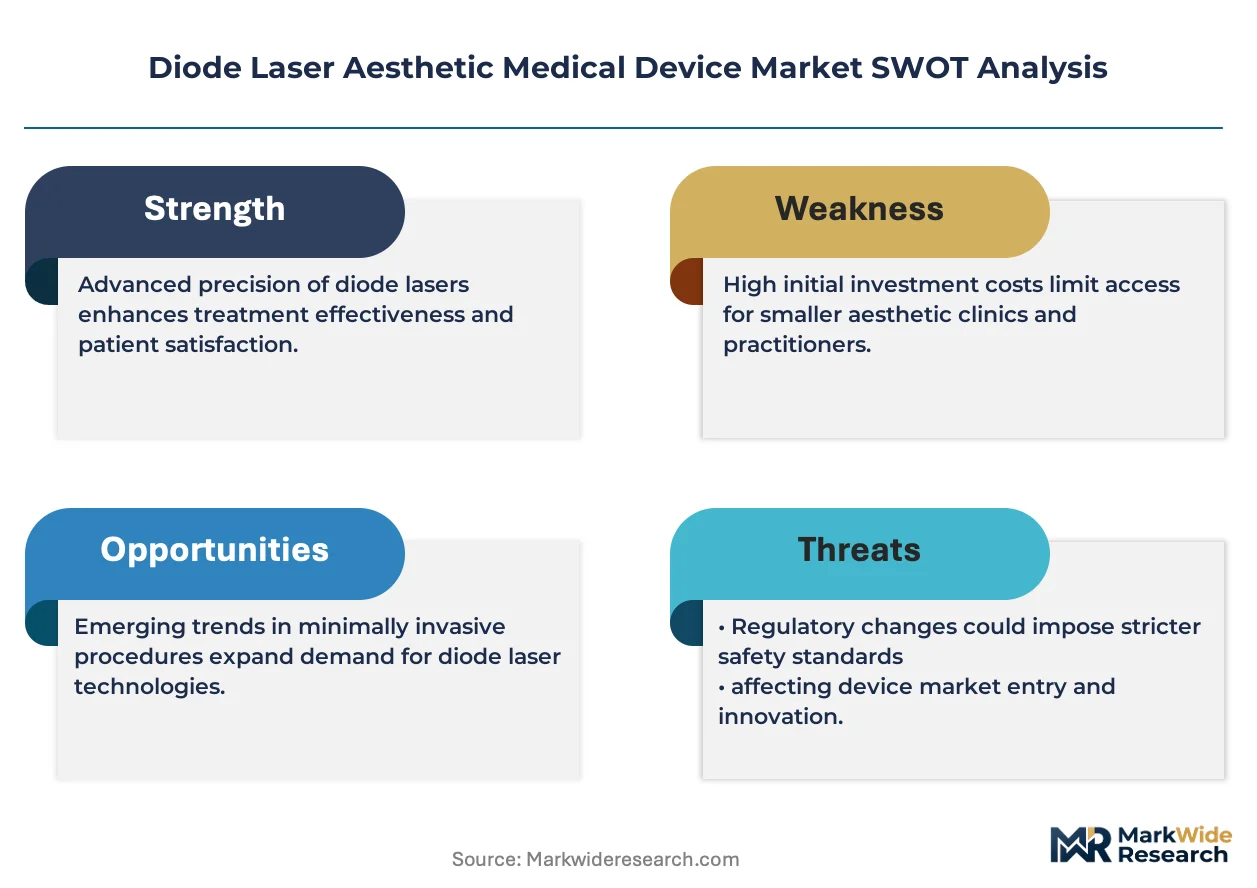
Semiconductor foundry consolidation is compressing pump laser diode pricing, collapsing the capital barrier that once protected established aesthetic device manufacturers from modular competitors assembling systems from standardized optical subassemblies.
Growth Catalysts
- MDR harmonization:The EU Medical Device Regulation's stricter clinical evidence requirements, while burdensome, are accelerating exit of marginal CE-marked competitors and concentrating demand among ISO 13485-certified manufacturers with robust technical documentation.
- Fractional dual-wavelength systems:These platforms simultaneously target melanin and water chromophores, enabling single-session protocols that reduce clinic chair-time and operator labor costs versus sequential IPL treatments.
- Germany's reimbursement clarity:Laser dermatology procedures receive explicit statutory health insurance coverage for medically indicated indications, driving aesthetic clinic density per capita that exceeds France, Italy, and Spain combined.
Market Restraints
- Gallium arsenide wafer supply concentration:Taiwan-based foundries control over 70% of high-power pump laser diode substrate production, exposing device assemblers to single-source geopolitical risk and allocation constraints during semiconductor cycle peaks.
- FDA 510(k) predicate drift:Substantial equivalence determinations for novel wavelength combinations increasingly require prospective clinical data, extending clearance timelines and pre-revenue R&D burn for platform extensions.
- Intense pulsed light substitution:Lower-capital IPL systems from Chinese manufacturers capture price-sensitive beauty salon installations, capping addressable market expansion in non-medical channels.
Strategic Opportunities
- Saudi Arabia's healthcare privatization:Vision 2030 dermatology clinic licensing reforms permit foreign operator majority ownership, creating first-mover advantage for FDA-cleared devices in a market historically dependent on European imports.
- Home-use device regulatory pathway:FDA's de novo classification for consumer diode laser hair removal systems with integrated skin tone sensors opens channel expansion beyond institutional buyers.
- AI-assisted fluence calibration:Machine vision integration with real-time melanin density assessment enables personalized energy delivery, differentiating premium platforms from fixed-parameter competitors.
Industry Challenges
- Laser safety officer certification scarcity:State-level scope-of-practice expansions permitting non-physician operation outpace accredited training program output, creating liability exposure and treatment inconsistency.
- Legacy IPL fleet stranding:Dermatology groups face sunk-cost pressure from depreciated intense pulsed light systems, slowing upgrade cycles despite superior diode laser efficacy data.
- Notified body capacity constraints:EU MDR designation bottlenecks for aesthetic device technical file review extend time-to-market by 8-14 months versus pre-2021 MDD timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diode Laser Aesthetic Medical Device Market |
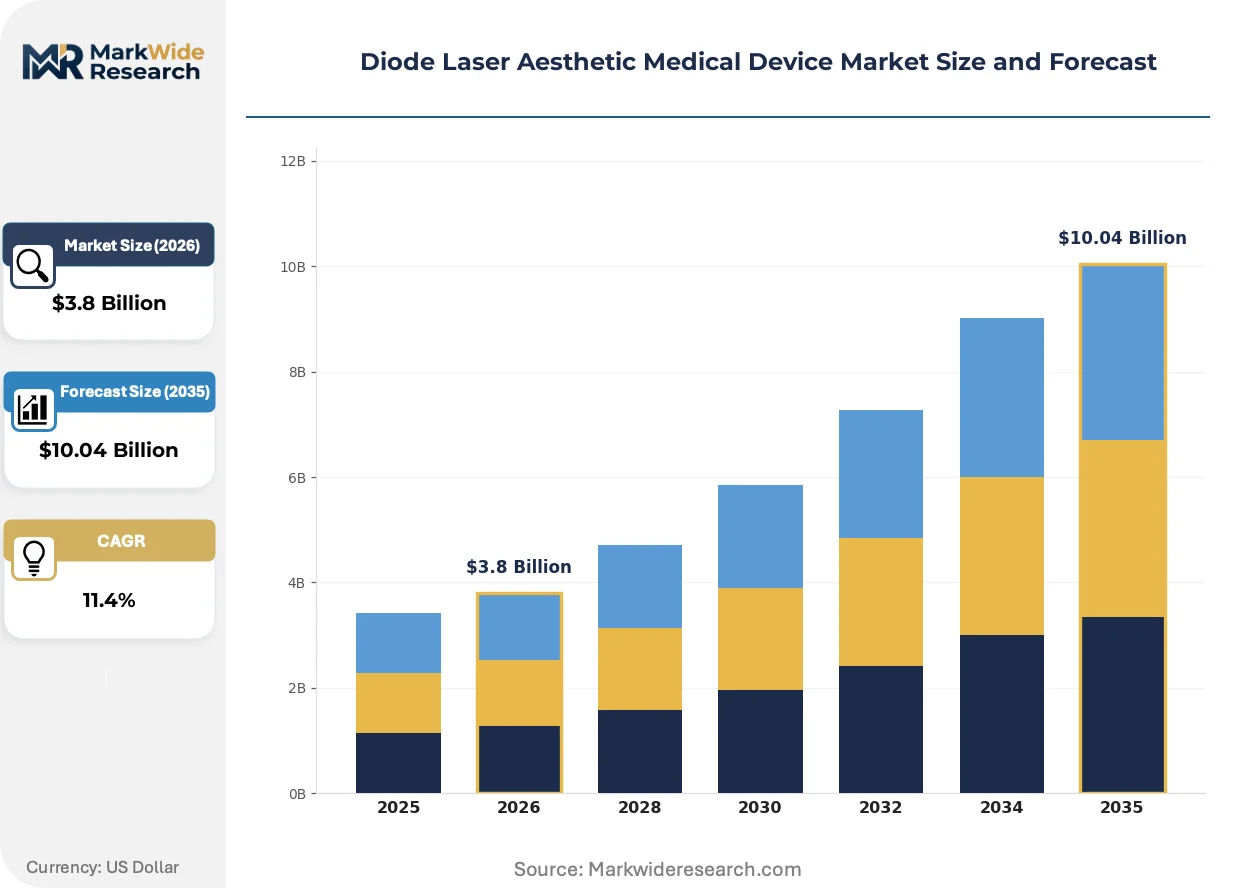
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hair Removal, Skin Rejuvenation, Tattoo Removal, Vascular Lesion Treatment End User: Clinics, Hospitals, Beauty Salons, Dermatology Centers Technology: Continuous Wave, Pulsed Wave, Dual Wavelength, Fractional Laser Application: Anti-Aging, Pigmented Lesion Removal, Acne Scar Treatment, Skin Tightening |
| Companies Covered | Alma Lasers, Lumenis, Candela Medical, Cynosure, Cutera, Asclepion Laser Technologies, El.En. S.p.A., Aerolase, Lutronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diode Laser Aesthetic Medical Device Market Trends and Innovations
Active cooling technologies and intelligent fluence modulation are converging to expand treatable skin type ranges, fundamentally altering patient eligibility criteria that historically excluded darker phototypes from safe laser therapy.
Contact-cooled sapphire windows with integrated thermoelectric regulation are supplanting passive air-cooling systems in high-volume hair removal platforms. US dermatology group purchasing organizations now specify active cooling as a mandatory procurement criterion, compressing margins for manufacturers lacking thermal management intellectual property. The technology is enabling same-device protocols across Fitzpatrick skin types I-VI, collapsing the historical need for wavelength-specific inventory.
The EU Medical Device Regulation's Annex XVI expansion to include active non-implantable devices with aesthetic purposes is reclassifying previously borderline products. Manufacturers must now compile clinical evaluation reports with post-market surveillance data, raising documentation costs. German notified bodies report 40% longer technical file review queues for laser dermatology devices versus 2019 MDD processing times.
Clinic procurement committees are unbundling capital equipment from mandatory service contracts, demanding à-la-carte maintenance pricing. US multi-site dermatology platforms now negotiate remote diagnostics subscriptions separately from hardware acquisition, displacing the traditional bundled lease model. This shift is most visible in Texas and Florida, where private equity-backed clinic rollups standardize procurement across 15-plus locations.
Diode Laser Aesthetic Medical Device Market Segmentation
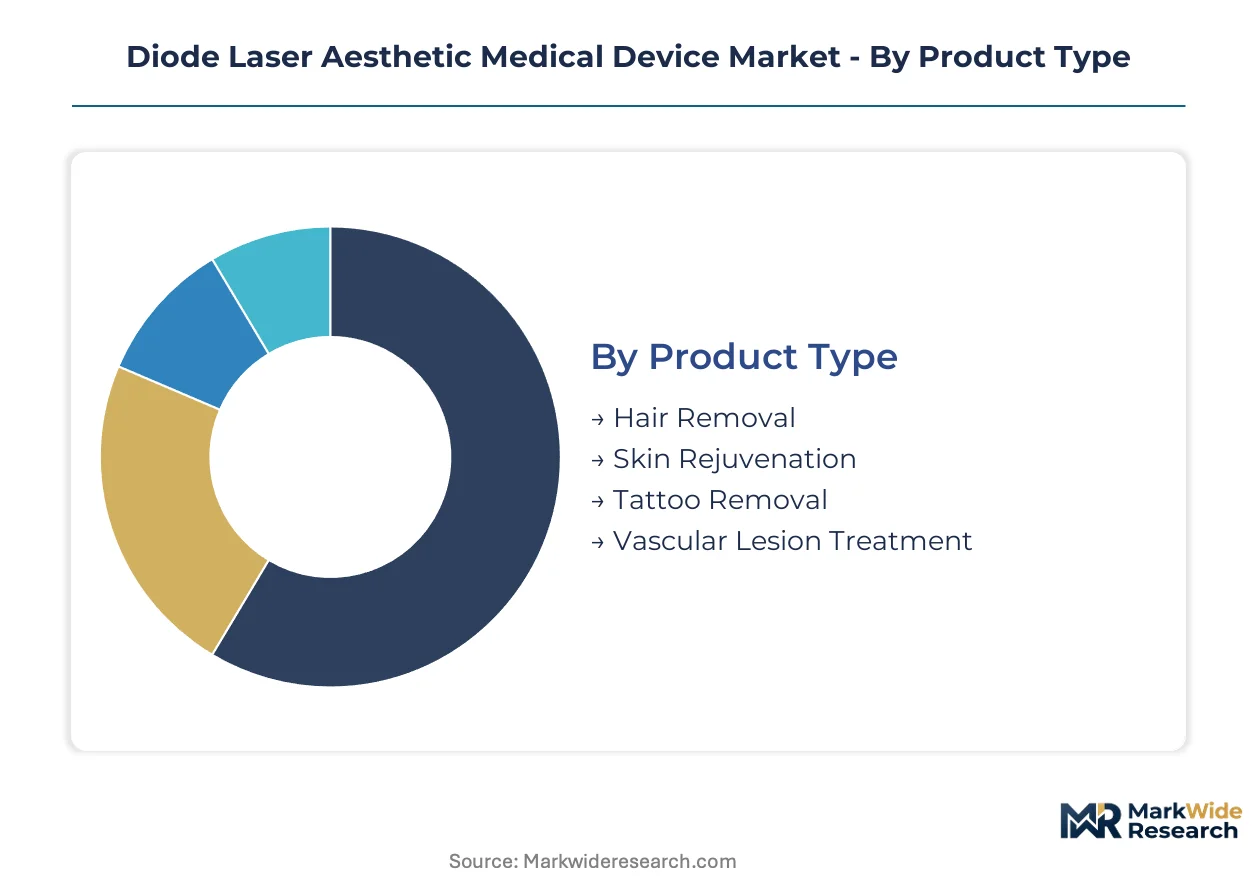
Diode laser aesthetic medical devices fragment across four critical dimensions that determine regulatory pathway complexity, capital intensity, and reimbursement eligibility. Procurement committees weight these taxonomies differently depending on whether the buyer operates under medical supervision or commercial beauty licensing.
Product Type:
FDA 510(k) clearance requirements vary sharply by intended therapeutic claim, with hair removal predicates establishing the fastest review pathway while vascular lesion indications demand more extensive clinical dossiers.
- Hair Removal:Systems targeting melanin chromophores at 800-1064 nm wavelengths dominate installed base volumes. Demand concentrates in US dermatology group purchasing organizations seeking multi-site standardization, constrained by state-level scope-of-practice expansions that outpace laser safety officer certification output.
- Skin Rejuvenation:Fractional dual-wavelength platforms simultaneously address melanin and water absorption peaks, enabling single-session protocols. German aesthetic clinics drive adoption fastest, leveraging statutory health insurance coverage clarity for medically indicated laser dermatology that exceeds reimbursement visibility in France, Italy, or Spain.
- Tattoo Removal:Q-switched and picosecond diode variants target exogenous ink particles across Fitzpatrick skin types I-VI.
- Vascular Lesion Treatment:Hemoglobin-selective wavelengths require precise fluence calibration for safe telangiectasia resolution.
Hair Removal handles the majority of throughput; Skin Rejuvenation is expanding most quickly on share.
End User:
Capital deployment thresholds and operator credentialing requirements create sharp pricing tiers across installation sites, with medical oversight mandates compressing margins in non-clinic channels.
- Dermatology Centers:Physician-supervised facilities command premium pricing power through higher reimbursement rates for medical-grade procedures versus beauty salon installations. Texas and Florida multi-site platforms now negotiate remote diagnostics subscriptions separately from hardware acquisition.
- Clinics:Standalone aesthetic practices represent the volume anchor for fractional dual-wavelength system placements.
- Hospitals:Academic medical centers prioritize research collaboration potential and training program integration over pure acquisition cost.
- Beauty Salons:Non-medical channels face intense substitution pressure from lower-capital IPL systems manufactured in China.
Dermatology Centers capture the highest margin per procedure; Clinics represent the largest addressable unit volume.
Technology:
Semiconductor foundry standardization of pump laser diode sourcing is collapsing the capital-intensity gap between established manufacturers and modular assemblers, reshaping competitive dynamics across emission modalities.
- Fractional Laser:Micro-beam array technology enables controlled thermal injury zones with surrounding tissue preservation. US dermatology group purchasing organizations now specify active cooling as mandatory procurement criteria, compressing margins for manufacturers lacking thermal management intellectual property.
- Dual Wavelength:Simultaneous 755 nm and 1064 nm emission targets multiple chromophores without hardware switching.
- Pulsed Wave:Nanosecond to millisecond pulse duration tuning optimizes selective photothermolysis for varied lesion depths.
- Continuous Wave:Uninterrupted emission suits high-speed hair removal protocols but limits versatility across indication range.
Fractional Laser commands the steepest expansion trajectory; Continuous Wave maintains the largest legacy installed base.
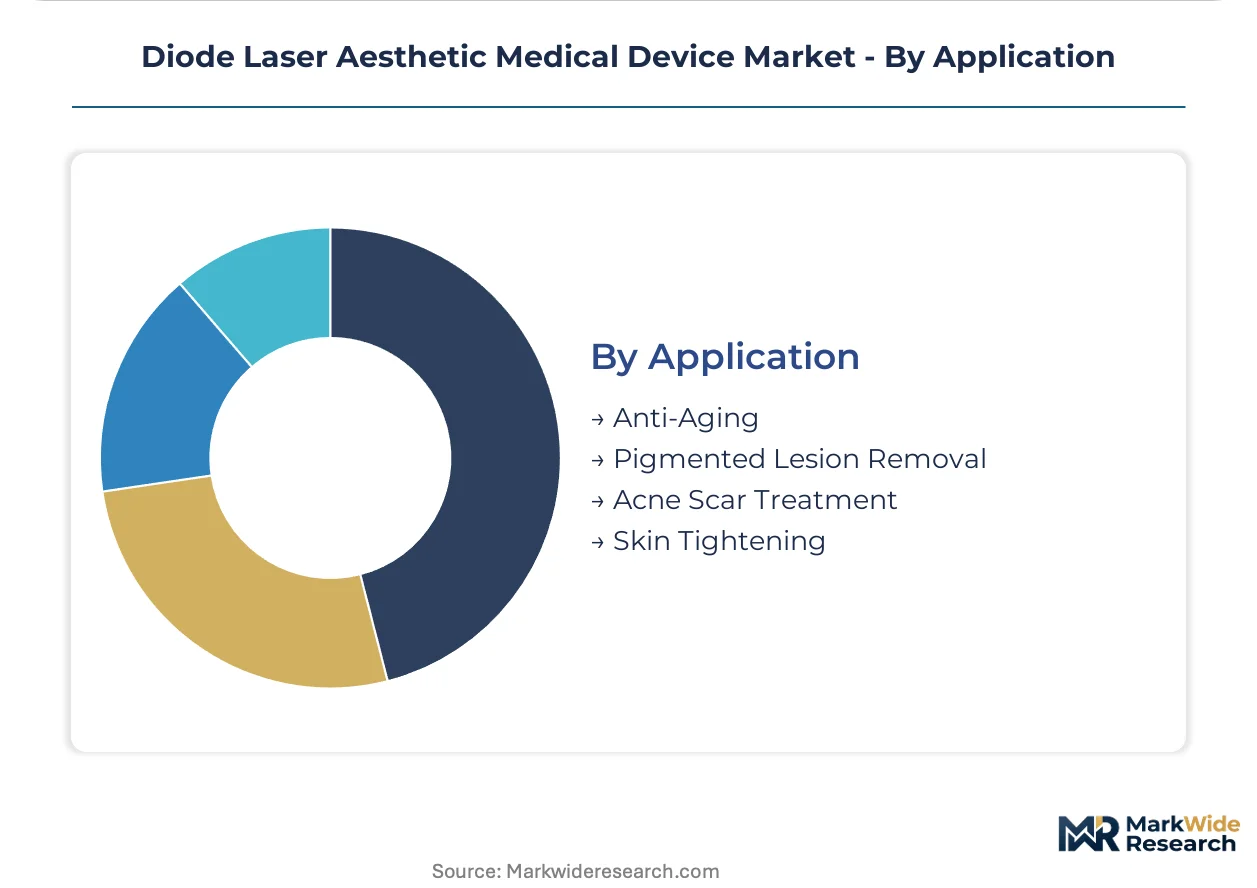
Application:
Clinical evidence requirements under EU MDR Annex XVI reclassification are elevating documentation burdens for aesthetic indications previously operating under lighter regulatory frameworks.
- Anti-Aging:Collagen remodeling through controlled dermal heating addresses rhytides and laxity. German notified bodies report 40% longer technical file review queues for laser dermatology devices versus pre-2021 MDD processing times, delaying market entry for novel anti-aging platforms.
- Acne Scar Treatment:Fractional ablative and non-ablative protocols target atrophic scarring with differential downtime profiles.
- Pigmented Lesion Removal:Melanin-specific wavelengths require integrated skin tone sensors for safe Fitzpatrick IV-VI treatment.
- Skin Tightening:Deep dermal collagen contraction protocols compete with radiofrequency and ultrasound modalities.
Anti-Aging generates the highest average revenue per patient; Acne Scar Treatment is climbing the fastest on procedure volume growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beauty salon buyers in Southeast Asia exhibit acute price sensitivity toward IPL alternatives, while German dermatology centers absorb premium diode laser pricing through statutory reimbursement coverage. This demand-elasticity contrast shapes procurement patterns across major markets.
United States
Texas and Florida multi-site dermatology platforms drive institutional procurement volume, negotiating remote diagnostics subscriptions separately from hardware acquisition. FDA 510(k) clearance pathways compress timelines for established predicate technologies, accelerating market entry for compliant manufacturers. Dallas and Miami aesthetic clinic clusters concentrate demand for fractional dual-wavelength systems with active cooling specifications.
Germany
Statutory health insurance coverage clarity for medically indicated laser dermatology procedures exceeds reimbursement visibility across France, Italy, and Spain combined. EU Medical Device Regulation notified body certification under Annex XVI reclassification elevates documentation burdens for aesthetic device manufacturers. Berlin and Munich aesthetic clinic density per capita anchors European demand concentration for skin rejuvenation platforms.
China
Domestic semiconductor foundry expansion in pump laser diode sourcing collapses capital barriers for modular device assemblers. NMPA medical device registration requirements for imported aesthetic laser systems maintain quality filters while streamlining review timelines for established predicate submissions. Shanghai and Shenzhen manufacturing clusters concentrate optical subassembly production for regional supply chains.
Saudi Arabia
Vision 2030 healthcare privatization reforms permit foreign operator majority ownership in dermatology clinic licensing, creating first-mover advantage for FDA-cleared devices. SFDA medical device registration harmonization with international standards reduces duplicate certification burdens for multinational manufacturers. Riyadh and Jeddah private clinic development corridors concentrate capital deployment for aesthetic medicine infrastructure.
Japan
PMDA medical device approval pathways for diode laser systems maintain rigorous clinical evidence standards that favor established manufacturers with robust technical documentation. METI industrial policy supports domestic photonics manufacturing clusters through targeted R&D subsidies. Tokyo and Osaka metropolitan aesthetic medicine markets concentrate demand for physician-supervised, premium-tier platforms.
Diode Laser Aesthetic Medical Device Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with vertical integration into semiconductor foundry relationships and thermal management intellectual property determining margin sustainability. The capital-intensity gap between established manufacturers and emerging competitors collapses as standardized pump laser diode sourcing becomes ubiquitous. Three archetypes dominate: Israeli and US-based vertically integrated platform developers, German precision-optics specialists, and Korean and Chinese modular assemblers leveraging component standardization. Competitive moves concentrate on M&A for thermal management IP and strategic partnerships with US dermatology group purchasing organizations.
Among Israeli and US-based platform developers, Alma Lasers and Candela Medical exemplify the integrated-leader archetype through captive manufacturing and dominant channel positioning. Lumenis occupies a position within the premium-tier specialist segment. These three anchors demonstrate how geographic concentration of optical engineering talent and proximity to major dermatology procurement clusters shapes competitive positioning.
| Leading Market Players |
|---|
| Alma Lasers |
| Lumenis |
| Candela Medical |
| Cynosure |
| Cutera |
| Asclepion Laser Technologies |
| El.En. S.p.A. |
| Aerolase |
| Lutronic |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation contracts with Taiwan-based gallium arsenide foundries lock in pump laser diode supply visibility while capping unit cost escalation for Israeli and US platform developers. These arrangements simultaneously secure allocation priority during semiconductor cycle peaks and stabilize input pricing for manufacturers assembling high-power aesthetic systems.
Pricing Analysis
After-sales service revenue tiers, particularly remote diagnostics subscriptions and à-la-carte maintenance modules, now drive lifetime value capture beyond hardware margins. Three-tier pricing structure across premium, standard, and economy levels segments by thermal management sophistication and FDA clearance tier. Cost compression in the beauty salon channel intensifies because Chinese IPL manufacturers flood price-sensitive installations with sub-$15,000 alternatives. Dermatology centers exhibit lowest price sensitivity due to reimbursement rate premiums for physician-supervised procedures.
Supply Chain Analysis
Strategic stockpile preferences dominate among German precision-optics specialists buffering against gallium arsenide wafer allocation constraints, while Israeli and US manufacturers favor just-in-time semiconductor sourcing backed by captive foundry relationships. Taiwan, China, and South Korea concentrate pump laser diode substrate and optical subassembly production. Device assemblers draw from gallium arsenide wafers, sapphire cooling windows, and thermoelectric regulation modules. Single-source vulnerability concentrates in Taiwan's 70%-plus share of high-power diode substrate output. Distribution runs through dermatology group purchasing organizations and direct hospital system contracts in the US, specialized aesthetic device distributors in Europe, and government procurement channels in Saudi Arabia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of laser safety officer certification programs relative to expanding state-level scope-of-practice permissions creates operational bottlenecks that constrain clinic throughput and elevate liability exposure. This capability gap favors manufacturers with integrated training ecosystems and certified operator pipelines.
For Market Incumbents: Compound channel control through exclusive remote diagnostics partnerships with Texas and Florida multi-site dermatology platforms, while deepening backward integration into thermoelectric cooling intellectual property to defend margin structures against modular assemblers. The threat of semiconductor foundry standardization eroding capital barriers demands captive supply relationships or equity stakes in gallium arsenide substrate producers. For New Entrants and Emerging Players: Anchor in Saudi Arabia's Vision 2030 privatization corridor, where foreign operator majority ownership reforms create first-mover advantage for FDA-cleared devices against historically European-import-dependent supply chains. The most penetrable segment spans Riyadh and Jeddah private clinic development corridors seeking premium-tier platforms. A go-to-market angle emphasizing AI-assisted fluence calibration with real-time melanin density assessment differentiates against fixed-parameter legacy systems. For Investors and Strategic Acquirers: Capital is best deployed toward Israeli and US-based vertically integrated platform developers with captive manufacturing and dominant GPO channel positioning, as these archetypes sustain margin structures that modular competitors cannot replicate. Long-term viability hinges on thermal management patent portfolios and FDA 510(k) predicate libraries that accelerate platform extension timelines. The signal to watch is EU MDR notified body queue compression, which would indicate regulatory capacity normalization and faster time-to-market for Annex XVI-compliant aesthetic devices.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Predicate Library Expansion | Accelerated clearance timelines compress pre-revenue R&D burn for wavelength combination platforms. |
| EU MDR Annex XVI Compliance Investment | Technical documentation depth filters marginal competitors and concentrates demand among ISO 13485-certified manufacturers. |
| Thermal Management IP Acquisition | Active cooling specifications now mandatory for US dermatology GPO procurement, compressing margins for non-compliant assemblers. |
| Remote Diagnostics Platform Development | Texas and Florida multi-site platforms now unbundle hardware from service contracts, shifting revenue toward recurring subscription models. |
| Saudi Arabia Market Entry Partnership | Vision 2030 licensing reforms permit foreign operator majority ownership, displacing European import dependency in Riyadh and Jeddah corridors. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR notified body certification databases, and semiconductor trade flow records. Interviews with dermatology group purchasing organization contract managers, biomedical engineers at academic medical centers, laser safety officers, and aesthetic clinic procurement directors informed demand-side dynamics. Secondary validation incorporated hospital procurement databases, GPO contract terms, and customs records for pump laser diode and optical subassembly trade. Bottom-up installed base modeling triangulated against top-down market sizing across product type, end user, technology, and application dimensions.
Segmentation dimensions modeled include product type, end user category, emission technology, and application indication, with geographic regulatory clusters capturing FDA, EU MDR, NMPA, PMDA, and SFDA pathway heterogeneity. CAGRs derived from elasticity-adjusted procedure volume projections and capital equipment replacement cycle analysis. Industry-specific forecast inputs incorporated state-level scope-of-practice expansion timelines and EU notified body capacity constraints extending technical file review queues.
Decision-makers should treat outputs as directional under assumptions of stable semiconductor foundry allocation and unaltered FDA 510(k) predicate availability; material deviation would warrant model refresh. Forecasts reflect base-case assumptions regarding reimbursement clarity persistence in Germany and MDR implementation continuity. Revision becomes warranted when Taiwan gallium arsenide wafer supply concentration crosses geopolitical disruption thresholds or FDA substantial equivalence determinations shift toward prospective clinical data requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Elbow Fixation Systems Market
Medical Devices
Central Venous Catheter Market
Medical Devices
Antibiotic-Loaded Bone Cement Market
Medical Devices
Facial Pumps Market
Medical Devices
Atrial Appendage Occluder Market
Medical Devices
Brazil Respiratory Devices Market
Medical Devices
Neuro Ablation Devices Market
Medical Devices
Europe Aligner Sheet Market
Medical Devices
Global Skin Grafting Device Market
Medical Devices
Interventional Oncology Devices Market
Medical Devices
Global Optical Biometry Devices Market
Medical Devices
Colposcopes Market
Medical Devices
Anterior Cervical Fixation Devices Market
Medical Devices
Acoustic Puncture Assist Devices Market
Medical Devices
India Hemostats Market
Medical Devices
Global Stroke Assistive Devices Market