
 Global Advanced Bipolar Direct Energy Device Market | 2026-2036
Global Advanced Bipolar Direct Energy Device Market Size, Share, and Industry Trends Forecast 2026-2036
Global Advanced Bipolar Direct Energy Device Market Foresight
Germany is rewriting competitive dynamics in advanced bipolar direct energy devices through its concentration of precision electrosurgical engineering and component fabrication. Medtronic leverages integrated R&D pipelines across surgical energy platforms to sustain technology leadership in feedback-controlled bipolar systems. Karl Storz SE & Co. KG anchors endoscopic energy delivery through specialized visualization-integrated instruments that dominate minimally invasive procedure suites. B. Braun Melsungen AG competes on manufacturing scale and European hospital channel control, extending its presence across sterile disposable and reusable energy device categories.
Advanced bipolar direct energy devices deliver controlled radiofrequency or electrical current between two active electrodes for tissue coagulation, dissection, or vessel sealing without a return electrode pad, typically operating at frequencies between 300 kHz and 1 MHz with impedance-matched output for thermal precision. Their primary purpose is to enable hemostasis and tissue division in minimally invasive and open surgical procedures with reduced thermal spread compared to monopolar alternatives. Radiofrequency-based systems occupy the largest installed base and margin pool across electrosurgery applications, while plasma and hybrid energy configurations represent the fastest-expanding technology segments as surgeons seek reduced collateral tissue damage in confined anatomical spaces. Endoscopy and gynecology applications concentrate demand growth, driven by procedural volume shifts toward outpatient settings and narrower anatomical access requirements that favor bipolar energy precision.
FDA 510(k) clearance pathways and EU MDR conformity assessment shape product development timelines and clinical evidence requirements for manufacturers seeking market access in the United States and European Union. ISO 13485 quality management standards and IEC 60601-1-2 electromagnetic compatibility requirements further constrain design validation and post-market surveillance obligations across major jurisdictions. Stakeholders must monitor evolving FDA guidance on reusable device reprocessing validation and EU MDR notified body capacity constraints, as these regulatory bottlenecks will determine competitive entry sequencing and commercialization cadence for next-generation energy platforms.
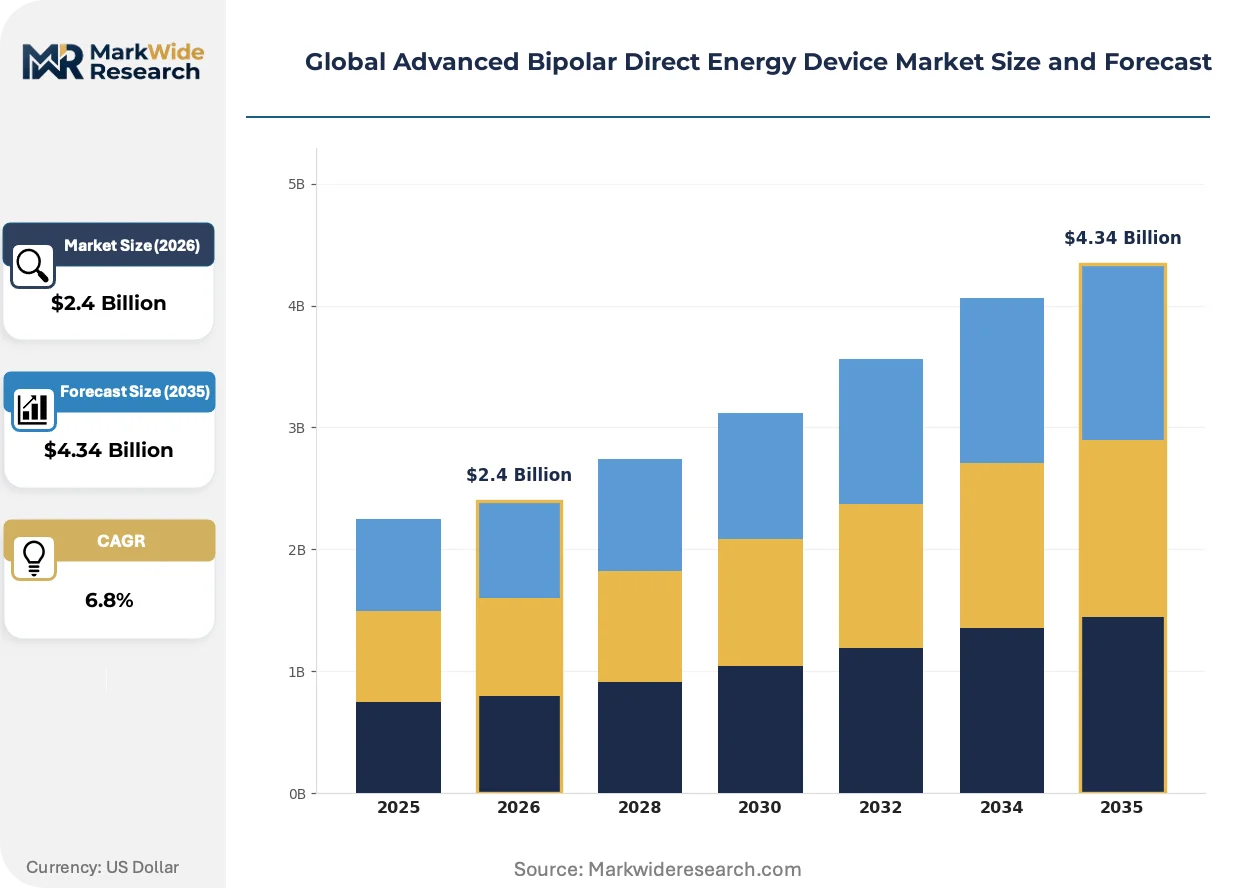
Market Dynamics
EU MDR notified body capacity constraints are compressing commercialization timelines for advanced bipolar direct energy platforms, forcing manufacturers to front-load clinical evidence generation and restructure quality management systems before conformity assessment.
Growth Catalysts
- Ambulatory surgical center volume expansion:Outpatient procedure migration in the United States and Germany is amplifying demand for compact, portable bipolar generators with integrated vessel-sealing algorithms.
- EU MDR Article 61 clinical evidence requirements:Stricter pre-market validation mandates are raising competitive barriers, advantaging incumbents with established PMCF infrastructure and biocompatibility data repositories.
- Radiofrequency impedance-matched output refinement:Real-time tissue feedback systems operating at 400-600 kHz are reducing thermal spread in confined anatomical spaces, accelerating gynecology and endoscopy adoption.
Market Restraints
- Precious metal electrode cost volatility:Tungsten and platinum-group metal price swings in German and Japanese supply chains are compressing gross margins on reusable instrument portfolios.
- Notified body bottleneck concentration:EU MDR technical documentation review queues at TÜV SÜD and BSI are extending time-to-market for Class IIb energy devices by 12-18 months.
- Monopolar legacy system entrenchment:Existing hospital capital equipment and surgeon training investments in conventional electrosurgery platforms create switching friction for bipolar alternatives.
Strategic Opportunities
- India CDSCO accelerated approval pathways:The country's emerging regulatory harmonization with IMDRF standards is opening expedited market access for manufacturers with US FDA 510(k) clearances.
- Plasma-mediated tissue dissection convergence:Hybrid energy platforms combining radiofrequency with argon plasma coagulation are creating new procedure categories in thoracic and hepatobiliary surgery.
- Direct-to-ambulatory surgery center distribution:Bypassing traditional hospital procurement committees through specialized GPO contracts is capturing volume in the United States freestanding facility segment.
Industry Challenges
- Electrosurgical engineer talent scarcity:Specialized RF circuit design and thermal modeling expertise is concentrating in German and Swiss precision manufacturing clusters, constraining R&D scaling elsewhere.
- Reprocessing validation capex intensity:FDA guidance on reusable device cleaning and sterilization validation is forcing multimillion-dollar investments in automated washer-disinfector qualification protocols.
- Legacy generator integration complexity:Backward compatibility requirements with installed bipolar instrument bases are limiting architectural innovation in next-generation feedback control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Advanced Bipolar Direct Energy Device Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radiofrequency, Ultrasonic, Plasma, Laser, Microwave, Cryoablation Application: Electrosurgery, Endoscopy, Ophthalmology, Neurology, Urology, Gynecology End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Diagnostic Laboratories, Academic Institutions, Research Centers Technology: Monopolar Energy, Bipolar Energy, Hybrid Energy, Automated Energy Delivery, Feedback-Controlled Systems |
| Companies Covered | Medtronic, Olympus Corporation, CONMED Corporation, Karl Storz SE & Co. KG, B. Braun Melsungen AG, Johnson & Johnson Services, Inc., BOWA-electronic GmbH & Co. KG, Xcellance Medical Technologies, SYMMETRY SURGICAL INC., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Advanced Bipolar Direct Energy Device Market Shifts & Advancements
Technology convergence between electrosurgical energy delivery and surgical visualization systems is compressing the traditional boundaries between device categories, creating integrated platforms that redefine procedure workflow economics.
Adaptive impedance-sensing algorithms are migrating from fixed-output radiofrequency generators to dynamic tissue-response systems that modulate power delivery in real time. Academic medical centers in Germany and the United States are piloting these platforms in laparoscopic colectomy and hysterectomy procedures. This migration is compressing the competitive relevance of open-loop energy systems that lack closed-loop thermal feedback.
EU MDR Annex XIV post-market clinical follow-up requirements are mandating systematic collection of real-world performance data across implanted and long-term contacting devices. Manufacturers must now maintain active PMCF studies for reusable bipolar instruments, shifting regulatory affairs resources from pre-market dossiers to continuous evidence generation. The sterile disposable segment faces the steepest compliance cost escalation as single-use device turnover complicates longitudinal tracking.
Hospital procurement committees are unbundling energy device contracts from capital equipment agreements, creating separate negotiation tracks for generators, handpieces, and consumable electrodes. German university hospitals and US integrated delivery networks are driving this disaggregation, pressuring vendors to demonstrate standalone value for each component category. The shift is most visible in gynecology service lines where procedure volume variability makes bundled contracts economically unfavorable.
Global Advanced Bipolar Direct Energy Device Market Segmentation
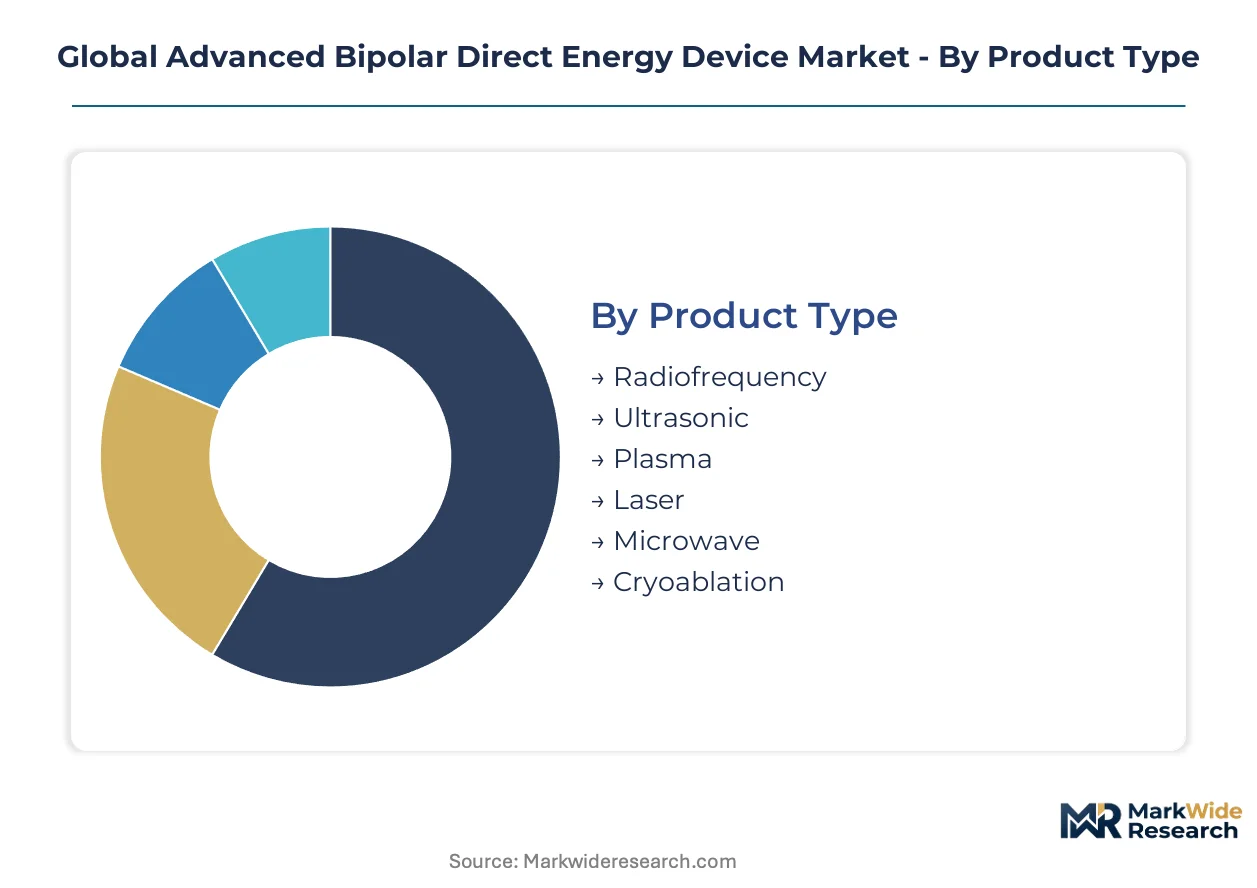
Segmentation in advanced bipolar direct energy devices reveals divergent replacement cycles across product categories, with disposable electrodes turning over monthly while capital generators persist for 7-10 years. Understanding these temporal patterns is critical for forecasting revenue mix and inventory planning across manufacturer portfolios.
Product Type:
Cycle times vary dramatically across energy modalities, from single-use disposable tips replaced per-procedure to capital platforms amortized over thousands of operations.
- Radiofrequency:Dominant installed base utilizing 300 kHz to 1 MHz impedance-matched output for tissue coagulation and vessel sealing. Demand concentrates in German and United States hospital systems seeking backward compatibility with existing instrument libraries while FDA 510(k) pathways sustain incumbent technology leadership.
- Plasma:Argon-mediated tissue dissection combining radiofrequency with inert gas ionization for reduced thermal spread in thoracic and hepatobiliary applications. Academic medical centers in Germany and the United States are piloting hybrid configurations that merge plasma precision with bipolar safety profiles.
- Ultrasonic:Mechanical vibration energy for tissue fragmentation with simultaneous hemostasis through protein denaturation.
- Laser:Coherent light delivery for precise tissue ablation in ophthalmology and dermatology adjunct procedures.
- Microwave:Electromagnetic heating for rapid tissue necrosis in cardiac ablation and oncology applications.
- Cryoablation:Freeze-thaw cycles for targeted tissue destruction in renal and prostate interventions.
Radiofrequency anchors the volume base while plasma gains share at the steepest rate.
Application:
Procedure economics drive divergent technology requirements across surgical specialties, with high-volume elective cases favoring disposable-intensive workflows versus complex oncologic procedures demanding capital platform sophistication.
- Electrosurgery:Open and minimally invasive tissue dissection with hemostasis across general surgery disciplines. German university hospitals and United States integrated delivery networks are unbundling energy contracts from capital agreements, pressuring standalone value demonstration for generators and handpieces.
- Endoscopy:Confined anatomical access procedures requiring reduced thermal spread and integrated visualization. EU MDR Annex XIV post-market clinical follow-up mandates are shifting regulatory resources toward continuous evidence generation for reusable instruments in this high-turnover category.
- Gynecology:Hysterectomy and myomectomy procedures where bipolar vessel sealing reduces blood loss.
- Urology:Prostate and renal interventions leveraging plasma and cryoablation modalities.
- Neurology:Delicate tissue manipulation requiring precise thermal control near critical structures.
- Ophthalmology:Microsurgical applications favoring laser and specialized bipolar micro-instruments.
Electrosurgery commands the largest revenue pool while endoscopy demonstrates the steepest expansion trajectory.
End User:
Procurement authority and reimbursement structures create distinct buying behaviors across facility types, from centralized hospital committees to autonomous ambulatory surgery center administrators.
- Hospitals:Capital-intensive purchasing with 7-10 year generator depreciation schedules and high-volume disposable consumption. German university hospitals are driving contract unbundling trends that separate generator, handpiece, and electrode negotiations.
- Ambulatory Surgical Centers:Freestanding facilities prioritizing compact, portable bipolar generators with integrated vessel-sealing algorithms. United States outpatient migration is amplifying demand for streamlined energy platforms with rapid turnover economics.
- Specialty Clinics:Focused procedure volumes in ophthalmology, urology, and gynecology with specialized instrument requirements.
- Academic Institutions:Research-oriented procurement emphasizing adaptive impedance-sensing algorithms and pilot program participation.
- Diagnostic Laboratories:Limited direct energy device utilization primarily for biopsy and minor intervention support.
- Research Centers:Preclinical and clinical trial infrastructure for next-generation energy platform validation.
Hospitals retain the dominant installed base while ambulatory surgical centers are climbing the fastest in new unit placements.
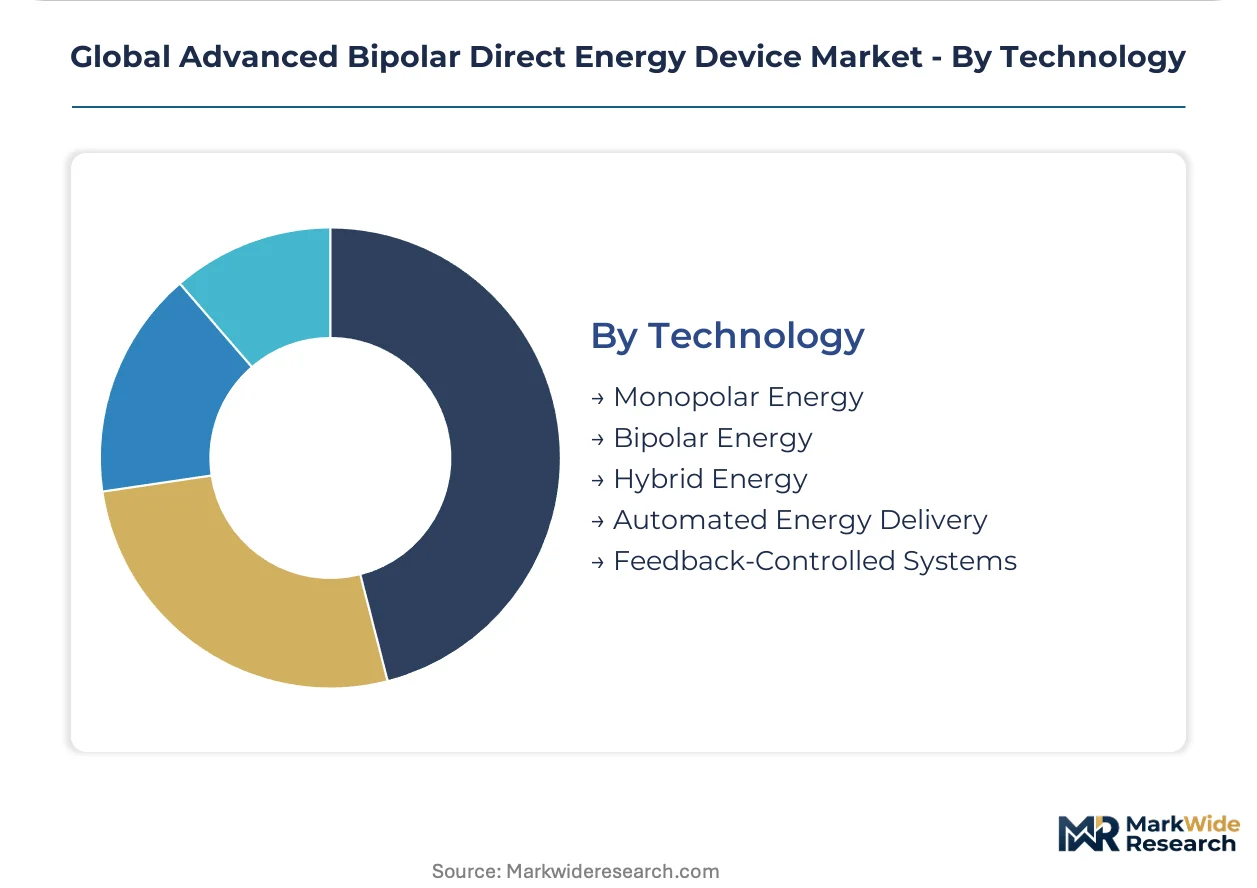
Technology:
Control architectures differentiate competitive positioning, with closed-loop feedback systems commanding premium pricing against open-loop legacy alternatives.
- Bipolar Energy:Current flow confined between two active electrodes eliminating return pad requirements and reducing thermal spread. Real-time tissue feedback systems operating at 400-600 kHz are accelerating adoption in confined anatomical spaces.
- Feedback-Controlled Systems:Dynamic impedance-sensing algorithms modulating power delivery based on tissue response. Migration from fixed-output generators is compressing competitive relevance of open-loop alternatives lacking closed-loop thermal management.
- Monopolar Energy:Legacy single-electrode configuration with return pad dependency retaining entrenched installed base.
- Hybrid Energy:Convergent platforms combining radiofrequency with argon plasma or ultrasonic modalities for procedure-specific optimization.
- Automated Energy Delivery:Pre-programmed tissue recognition algorithms reducing surgeon-dependent technique variation.
Bipolar energy anchors current revenue concentration while feedback-controlled systems are expanding most quickly as replacement demand accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision electrosurgical engineering clusters concentrate in southern Germany and the US Upper Midwest, with regulatory complexity in the European Union compressing commercialization timelines for manufacturers lacking established notified body relationships.
United States
Ambulatory surgery center volume migration amplifies demand for portable bipolar generators with integrated vessel-sealing algorithms. FDA 510(k) clearance pathways sustain incumbent technology leadership while guidance on reusable device reprocessing validation forces multimillion-dollar qualification investments. The Minneapolis-St. Paul corridor anchors Medtronic's integrated R&D pipelines for feedback-controlled surgical energy platforms.
Germany
University hospital procurement committees are unbundling energy device contracts from capital equipment agreements, pressuring standalone value demonstration. EU MDR Article 61 clinical evidence requirements and Annex XIV post-market clinical follow-up mandates raise competitive barriers for manufacturers lacking PMCF infrastructure. Tuttlingen and Melsungen precision manufacturing clusters anchor Karl Storz SE & Co. KG and B. Braun Melsungen AG production of visualization-integrated and sterile disposable energy systems.
Japan
Academic medical centers in Tokyo and Osaka pilot adaptive impedance-sensing algorithms in laparoscopic colectomy procedures, compressing relevance of open-loop energy alternatives. PMDA harmonization with IMDRF standards streamlines market access for manufacturers with established FDA clearances. Nagoya-area precision electronics fabricators supply RF circuit components for next-generation thermal feedback systems.
India
CDSCO accelerated approval pathways for manufacturers with US FDA 510(k) clearances are opening expedited market access for imported energy platforms. Central government PLI scheme incentives for medical device manufacturing are attracting component assembly investments. Hyderabad and Bengaluru emerging as contract research hubs for electrosurgical device clinical validation.
China
NMPA regulatory harmonization with international standards is reducing time-to-market for bipolar energy platforms with prior FDA or CE marking. Domestic hospital procurement favoring localized supply chains is pressuring multinational manufacturers toward joint venture manufacturing arrangements. Suzhou and Shenzhen precision instrument clusters are scaling electrosurgical handpiece production for regional consumption.
Global Advanced Bipolar Direct Energy Device Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in electrode fabrication and generator subassembly. The vendor base stratifies across three tiers: diversified medical technology conglomerates with full surgical energy portfolios, mid-cap precision instrument specialists with regional channel control, and niche component fabricators supplying tungsten electrodes and RF circuitry. Consolidation pressure concentrates among platform players seeking visualization-integration capabilities, while component specialists defend position through precious metal supply relationships and sterilization validation expertise.
Among diversified platform manufacturers, Medtronic and Johnson & Johnson Services, Inc. exemplify integrated surgical energy system providers with global hospital channel access. Olympus Corporation occupies a position at the convergence of endoscopic visualization and energy delivery, representing the visualization-integrated archetype. Karl Storz SE & Co. KG and B. Braun Melsungen AG anchor the German precision manufacturing tier, with the former exemplifying specialized endoscopic instrument engineering and the latter representing scaled sterile disposable production.
| Leading Market Players |
|---|
| Medtronic |
| Olympus Corporation |
| CONMED Corporation |
| Karl Storz SE & Co. KG |
| B. Braun Melsungen AG |
| Johnson & Johnson Services, Inc. |
| BOWA-electronic GmbH & Co. KG |
| Xcellance Medical Technologies |
| SYMMETRY SURGICAL INC. |
| Others |
Supply & Pricing Matrix
The Rhine-Alpine freight corridor's container cost volatility feeds directly into finished-device pricing power at German manufacturing clusters, compressing margins on tungsten electrode imports while amplifying price differentiation between CE-marked premium systems and standard-tier alternatives sold into cost-sensitive ambulatory channels.
Pricing Analysis
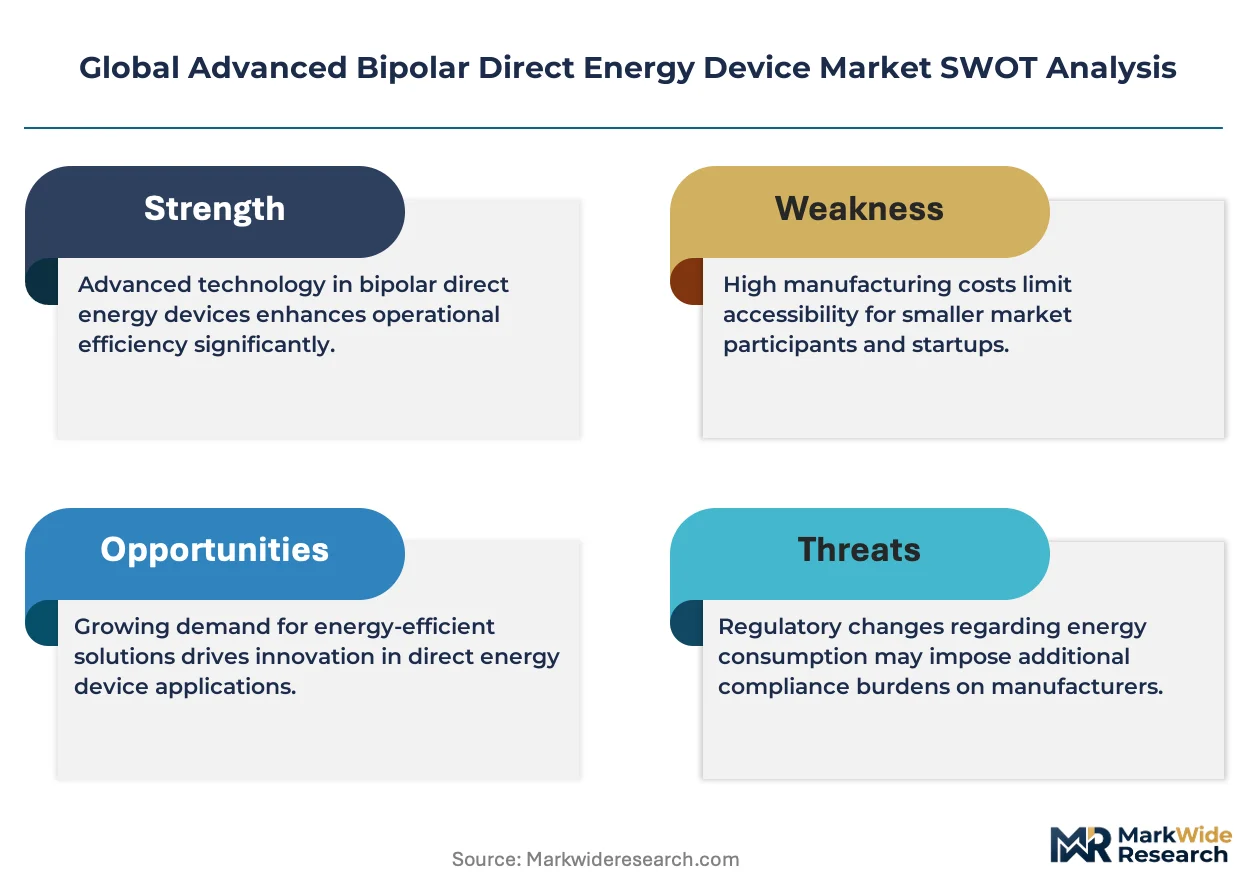
EU MDR Article 61 dictates the pricing tier structure across the European market, separating validated Class IIb systems with PMCF infrastructure from entry-level alternatives lacking biocompatibility data repositories. Price differentiation hinges on certification grade (FDA 510(k) versus CE marking tier) and vertical integration depth in electrode fabrication. Pricing pressure stems from precious metal cost volatility in Japanese supply chains, with ambulatory surgical centers exhibiting highest price sensitivity and academic medical centers demonstrating lowest.
Supply Chain Analysis
Swiss and southern German precision electronics foundries hold captive capacity for RF circuit components and impedance-matching subassemblies, with Nagoya-area fabricators supplying secondary thermal feedback modules. Geographic supply concentration centers on Germany, Switzerland, and Japan for critical electrosurgical engineering inputs. Raw material dependencies include tungsten electrodes, platinum-group metal contacts, and specialized ceramic insulators. Single-source vulnerability in EU MDR notified body capacity creates regulatory chokepoint risk. Distribution runs through hospital procurement committees and specialized GPO contracts for ambulatory channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory-moat story where EU MDR conformity assessment infrastructure creates entrenched switching costs for hospital systems, locking in incumbents with established PMCF databases and biocompatibility validation protocols.
For Market Incumbents: Pre-empt emerging entrant challenges by deepening backward integration into tungsten electrode supply through Swiss and German precision manufacturing clusters, while accelerating FDA 510(k) pathway investments to capture India CDSCO harmonization benefits before notified body bottlenecks ease.
For New Entrants and Emerging Players: Build out plasma-mediated hybrid energy platforms for thoracic and hepatobiliary surgery white space, targeting United States ambulatory surgical centers through direct GPO contracting that bypasses traditional hospital procurement committees.
For Investors and Strategic Acquirers: Visualization-integrated instrument specialists with established Karl Storz-style endoscopic energy delivery capabilities represent the most defensible acquisition archetype. Long-term viability hinges on regulatory entrenchment depth rather than technology differentiation alone. Monitor EU MDR notified body capacity expansion as the critical inflection signal for competitive entry sequencing.
| Strategic Initiative | Industry Significance |
|---|---|
| PMCF Infrastructure Investment | EU MDR Annex XIV compliance creates sustainable competitive barriers for reusable instrument portfolios. |
| FDA 510(k) Dual Clearance Strategy | Parallel US and EU regulatory pathways accelerate India CDSCO market access through IMDRF harmonization. |
| Visualization-Integration Partnership | Convergence with endoscopic systems redefines workflow economics in German university hospital suites. |
| Ambulatory GPO Contracting | Direct-to-ASC distribution captures United States outpatient migration volume outside hospital procurement. |
| Precious Metal Supply Hedging | Tungsten and platinum-group price volatility management stabilizes gross margins on reusable electrode lines. |
Research Methodology
The analysis maps radiofrequency, plasma, ultrasonic, and hybrid energy sub-sectors, each validated through electrosurgical engineers, hospital purchasing committee members, biomedical equipment specialists, and GPO contracts managers. Primary interviews with German and United States precision manufacturing clusters combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and electrosurgical device trade flow data. Bottom-up segmentation modeling triangulates against top-down macroeconomic healthcare expenditure trends.
Assumptions held fixed include EU MDR notified body capacity constraints and FDA guidance on reusable device reprocessing validation; variables stress-tested across precious metal price bands and ambulatory surgical center volume migration rates. The projection horizon spans product replacement cycles from single-use disposable electrodes through 7-10 year generator depreciation schedules. CAGRs derive from impedance-sensing algorithm adoption curves and plasma-hybrid configuration penetration in thoracic applications. Modeled dimensions include energy modality, surgical application specialty, end-user facility type, and control architecture tier.
Stress conditions across tungsten supply volatility, EU MDR notified body queue lengths, and United States outpatient reimbursement policy were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions with acknowledged sensitivity to regulatory timeline compression in India and China. Quarterly review of notified body capacity indicators, ambulatory surgery center construction permits, and electrosurgical engineer hiring patterns in German clusters is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Peripheral Vascular Devices and Accessories Market
Medical Devices
Invisible Orthodontics Market
Medical Devices
Manometry System Market
Medical Devices
Soft Tissue Markers Market
Medical Devices
Rigid Laparoscope Market
Medical Devices
Mexico Spinal Surgery Devices Market
Medical Devices
Neurofeedback Systems Market
Medical Devices
United States Minimally Invasive Surgery Device Market
Medical Devices
Global Nebulizers Market
Medical Devices
Carotid Artery Stents Market
Medical Devices
Superficial Radiation Therapy System Market
Medical Devices
Foot and Ankle Allograft Market
Medical Devices
Motorized Prosthesis Market
Medical Devices
Latin America Breast Biopsy Needle Market
Medical Devices
North America Electric Wheelchair Market
Medical Devices
Absorbable Antibacterial Envelope Market