
 Global Gynecology Robotic Surgery Market | 2026-2036
Global Gynecology Robotic Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
Global Gynecology Robotic Surgery Market Foresight
Buyer concentration among academic medical centers and specialized surgery centers is shifting as ambulatory surgical facilities fragment the customer base across outpatient settings. Intuitive Surgical dominates installed base expansion through its da Vinci ecosystem and training infrastructure. CMR Surgical competes on capital-light flexible platforms designed for smaller hospital footprints. Medtronic leverages its existing surgical navigation portfolio to extend robotic capabilities into gynecologic workflows.
Gynecology robotic surgery encompasses computer-assisted surgical platforms that translate surgeon hand movements into precise micro-movements of instruments inside the patient, typically operating through 8-12 mm trocar ports with 3D visualization at 10x magnification. These systems enable minimally invasive hysterectomy, myomectomy, and endometriosis resection with reduced blood loss and shorter recovery periods compared to laparotomy. Robotic surgical systems capture the largest capital expenditure pool while instrumentation generates recurring revenue through single-use instrument arms. Hysterectomy represents the most mature procedure segment with established reimbursement, whereas endometriosis resection shows the fastest procedural growth as diagnostic rates improve. Software platforms increasingly differentiate vendor offerings through AI-powered surgical analytics and remote proctoring capabilities.
The FDA governs premarket notification and PMA pathways for robotic surgical systems in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements through notified body conformity assessments. Japan's PMDA maintains distinct pharmaceutical and medical device agency review standards that shape market entry sequencing for Asian expansion. Stakeholders must monitor evolving cybersecurity standards for connected surgical platforms and shifting hospital capital allocation priorities between robotics and alternative minimally invasive technologies.
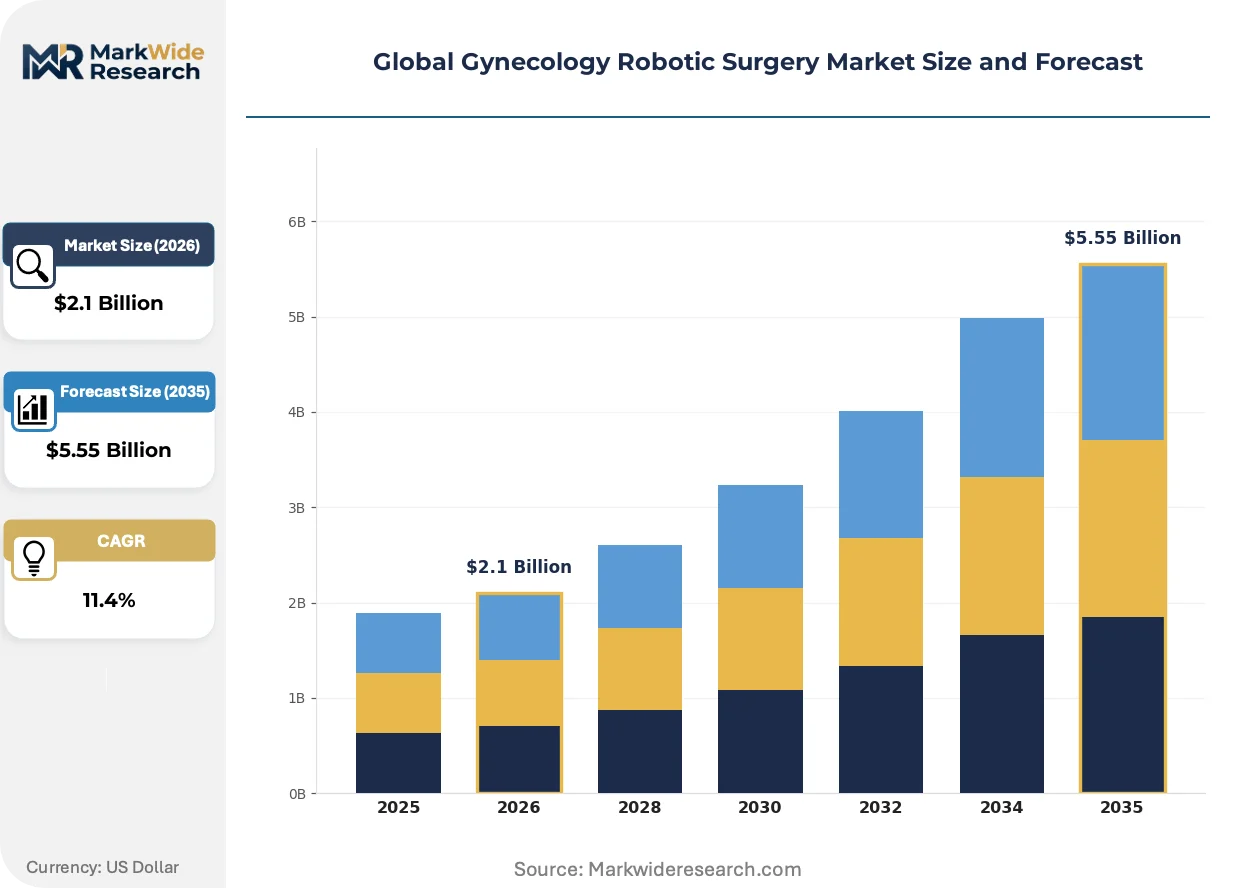
Market Dynamics
The FDA's streamlined premarket review pathways for surgical robotics are compressing device clearance timelines while academic medical centers accelerate platform deployment for minimally invasive hysterectomy and myomectomy procedures. This regulatory acceleration is reshaping capital allocation priorities across hospital systems.
Growth Catalysts
- Reimbursement frameworks:The United States, Germany, and Japan maintain favorable reimbursement structures for robotic-assisted gynecologic surgery, directing hospital procurement toward platform adoption. Academic medical centers leverage these frameworks to justify capital expenditure on da Vinci and competing systems.
- AI-powered surgical analytics:Software platforms incorporating machine learning for intraoperative guidance and post-procedure review are differentiating vendor offerings. Remote proctoring capabilities expand training access beyond traditional fellowship programs.
- Endometriosis diagnostic rates:Improved detection protocols in tertiary care centers are expanding the addressable patient population for robotic resection procedures. This procedural segment demonstrates faster volume growth than established hysterectomy volumes.
Market Restraints
- Capital intensity:Robotic surgical systems require substantial upfront expenditure alongside recurring instrumentation costs through single-use instrument arms. Smaller hospital footprints face constrained access to procurement financing.
- EU Medical Device Regulation:Stricter clinical evidence requirements through notified body conformity assessments are extending market entry timelines for new platform entrants. The MDR imposes documentation burdens that favor incumbent manufacturers with established technical files.
- Skilled surgeon availability:Robotic credentialing programs remain concentrated at academic medical centers, limiting platform deployment in community hospital settings where laparoscopic expertise dominates.
Strategic Opportunities
- Ambulatory surgical facilities:Outpatient settings are fragmenting the traditional academic medical center customer base, creating demand for flexible, capital-light robotic platforms designed for smaller footprints.
- CMR Surgical's Versius system:Modular, portable configurations enable point-of-care deployment outside traditional operating room infrastructure. This architecture addresses space constraints in European and Asian healthcare facilities.
- Cybersecurity standards evolution:Connected surgical platforms face emerging compliance requirements for data protection and network integrity. Vendors investing in hardened system architectures gain competitive positioning in procurement evaluations.
Industry Challenges
- Training pipeline constraints:Robotic surgery fellowships produce insufficient qualified surgeons to match platform installation growth. Simulation-based credentialing programs require validation against clinical outcome metrics.
- Integration with legacy surgical navigation:Hospitals with existing Medtronic or Brainlab navigation infrastructure face workflow friction when overlaying robotic platforms. Interoperability standards remain underdeveloped across vendor ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Gynecology Robotic Surgery Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $5.55 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Surgical Systems, Instrumentation, Imaging Systems, Software Platforms Procedure Type: Hysterectomy, Myomectomy, Endometriosis Resection, Pelvic Organ Prolapse Repair, Oophorectomy End User: Specialized Surgery Centers, Academic Medical Centers, Ambulatory Surgical Facilities, Community Hospitals Deployment Model: On-Premises, Cloud-Based, Hybrid Solutions, Managed Services |
| Companies Covered | Intuitive Surgical, Titan Medical, CMR Surgical, Medtronic, Stryker, Johnson & Johnson, avateramedical, TransEnterix, Olympus Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Gynecology Robotic Surgery Market Shifts & Advancements
Digital surgery ecosystems are converging robotic hardware with cloud-based analytics platforms, compressing the feedback loop between intraoperative performance and post-procedure quality improvement. This integration is redefining how surgical outcomes are measured and optimized.
Haptic feedback systems are unifying force-sensing instrumentation with surgeon console interfaces, enabling tissue manipulation with tactile precision previously unavailable in robotic platforms. Gynecologic surgeons at academic medical centers are adopting these enhanced consoles for complex myomectomy procedures. The technology is unifying open surgical tactile experience with minimally invasive access, reducing conversion rates to laparotomy.
Japan's PMDA has established distinct review standards for robotic surgical systems that diverge from pharmaceutical-focused agency precedent, creating specialized pathways for device-digital combination products. This regulatory architecture accelerates clearance for platforms incorporating AI-assisted suturing algorithms. Asian market entry sequencing now prioritizes Japan as a regulatory reference point for regional expansion.
Hospital procurement committees are consolidating vendor relationships through multi-year service agreements that bundle platform maintenance, instrumentation supply, and surgeon training into single-contract structures. Ambulatory surgery centers are displacing traditional capital purchase models with per-procedure leasing arrangements. This shift is most visible in United States metropolitan markets where outpatient hysterectomy volumes are migrating from inpatient settings.
Global Gynecology Robotic Surgery Market Segmentation
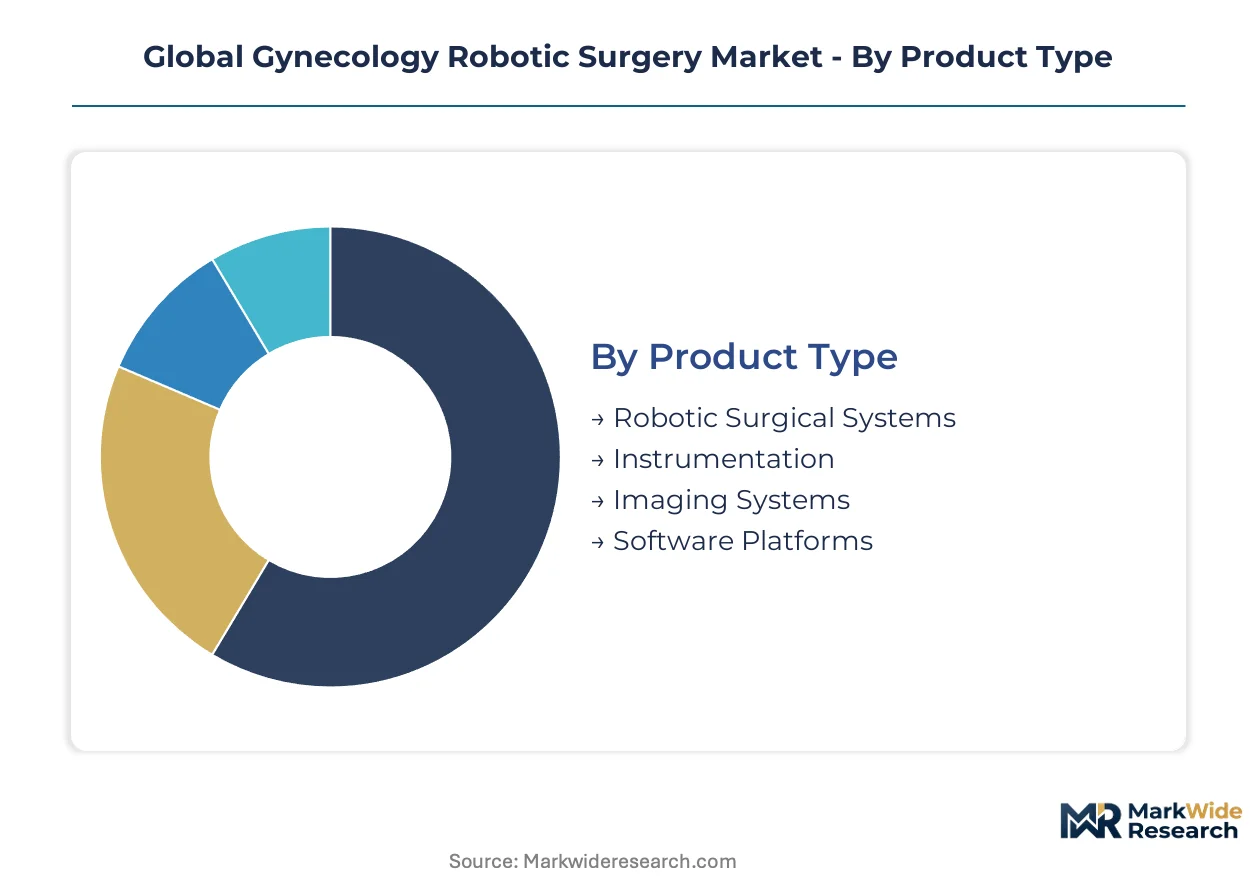
Segmentation in gynecology robotic surgery reveals distinct capital allocation patterns across hardware, consumables, and digital infrastructure. Hospital procurement committees evaluate segments through different investment horizons—platforms demand multi-year depreciation schedules while instrumentation generates recurring expenditure. Understanding these structural differences shapes vendor go-to-market strategies and partnership negotiations.
Product Type:
Capital intensity varies dramatically across this category, with robotic surgical systems requiring seven-figure upfront commitments versus software platforms that deploy through subscription models.
- Robotic Surgical Systems:Computer-assisted platforms with surgeon consoles, patient-side carts, and instrument arms operating through 8-12 mm trocar ports. Demand concentrates at academic medical centers in the United States and Germany where reimbursement frameworks justify capital expenditure through procedure volume guarantees.
- Instrumentation:Single-use instrument arms, end effectors, and trocar assemblies generating recurring revenue per procedure. Smaller hospital footprints in Japan face constrained procurement financing for instrument inventory, slowing platform adoption outside tertiary centers.
- Imaging Systems:3D visualization towers and camera control units providing 10x magnification for operative fields.
- Software Platforms:Cloud-based analytics and remote proctoring modules differentiating vendor ecosystems through AI-powered surgical guidance.
Most installed capacity flows through Robotic Surgical Systems. Expansion is steepest in Software Platforms.
Procedure Type:
Procedure maturity determines reimbursement stability and training infrastructure investment, with established interventions attracting capital allocation over emerging applications.
- Hysterectomy:Minimally invasive uterine removal through robotic-assisted total or supracervical approaches. Academic medical centers in the United States drive volume concentration through established fellowship programs and favorable CMS reimbursement schedules.
- Myomectomy:Fibroid resection preserving uterine integrity through precise tissue manipulation. Demand clusters at specialized surgery centers in Germany where fertility-preserving outcomes command premium pricing.
- Endometriosis Resection:Deep infiltrating lesion removal requiring advanced suturing capabilities.
- Pelvic Organ Prolapse Repair:Sacrocolpopexy and mesh placement procedures with longer operative durations.
- Oophorectomy:Ovarian removal procedures typically combined with hysterectomy workflows.
Procedure volume concentrates in Hysterectomy. Steepest expansion trajectory belongs to Endometriosis Resection.
End User:
Customer scale and capital access differentiate procurement patterns, with large integrated systems negotiating enterprise contracts versus independent facilities seeking flexible terms.
- Academic Medical Centers:Tertiary care institutions with fellowship programs, research mandates, and high-volume referral networks. These facilities in Japan prioritize platforms with training infrastructure and remote proctoring capabilities.
- Specialized Surgery Centers:Dedicated gynecologic facilities with concentrated robotic expertise and streamlined workflows. United States metropolitan markets show these centers capturing outpatient hysterectomy volumes migrating from inpatient settings.
- Ambulatory Surgical Facilities:Outpatient settings with space constraints favoring capital-light, modular configurations.
- Community Hospitals:Smaller general acute care facilities with laparoscopic-dominated surgical programs and limited robotic credentialing.
Platform deployment concentrates at Academic Medical Centers. Fastest share gains occur in Ambulatory Surgical Facilities.
Deployment Model:
IT infrastructure sophistication and data governance requirements shape adoption, with regulated health systems prioritizing control over connectivity.
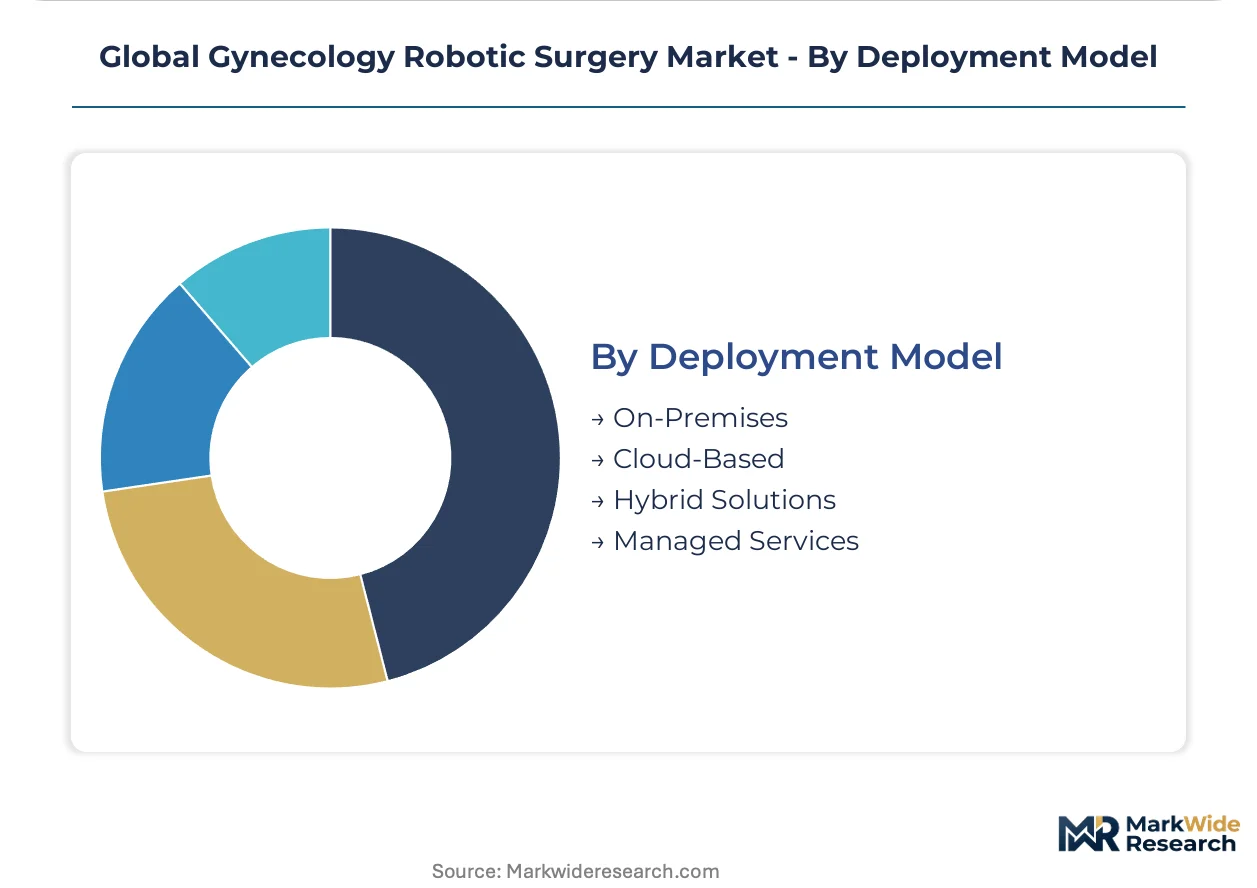
- On-Premises:Local server installations with full data sovereignty and offline operational capability. German hospital systems favor this model under GDPR and MDR cybersecurity requirements for connected surgical platforms.
- Cloud-Based:Fully hosted deployments with automatic software updates and centralized analytics. United States academic medical centers adopt these for multi-site outcome benchmarking.
- Hybrid Solutions:Mixed architectures keeping sensitive patient data local while enabling cloud analytics.
- Managed Services:Outsourced IT operations with vendor-managed maintenance and cybersecurity monitoring.
Current infrastructure concentrates in On-Premises installations. Cloud-Based deployments are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's reimbursement frameworks favor robotic-assisted gynecologic surgery more aggressively than Japan's PMDA-regulated pathway, yet both markets concentrate platform deployment at academic medical centers with established fellowship programs.
United States
Academic medical centers in metropolitan markets drive hysterectomy volumes through favorable CMS reimbursement schedules and established robotic credentialing programs. The FDA's streamlined premarket review pathways compress device clearance timelines for surgical robotics platforms. Boston and Houston surgical clusters anchor multi-site outcome benchmarking through cloud-based analytics deployments.
Germany
Specialized surgery centers command premium pricing for fertility-preserving myomectomy outcomes through precise tissue manipulation capabilities. The EU Medical Device Regulation imposes stricter clinical evidence requirements through notified body conformity assessments. Munich and Berlin hospital systems favor on-premises installations under GDPR cybersecurity requirements for connected surgical platforms.
Japan
Tertiary care institutions prioritize platforms with training infrastructure and remote proctoring capabilities for surgeon credentialing expansion. The PMDA maintains distinct review standards for robotic surgical systems that diverge from pharmaceutical-focused agency precedent. Tokyo and Osaka academic medical centers serve as regulatory reference points for Asian market entry sequencing.
United Kingdom
NHS procurement committees evaluate capital-light, modular configurations for space-constrained European healthcare facilities. The MHRA aligns with EU MDR transitional provisions while establishing independent post-Brexit conformity assessment pathways. London and Manchester surgical networks fragment outpatient hysterectomy volumes across ambulatory settings.
India
Private hospital chains in metropolitan markets justify capital expenditure through procedure volume guarantees and medical tourism positioning. The CDSCO accelerates market entry timelines for platforms with established FDA or CE markings through abbreviated review pathways. Delhi-NCR and Mumbai clusters concentrate installed base expansion among tier-1 healthcare facilities.
Global Gynecology Robotic Surgery Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across capital intensity tiers, producing a consolidated structure around established installed bases and fragmented challenger positions. Incumbent manufacturers leverage multi-year service agreements bundling platform maintenance, instrumentation supply, and surgeon training into single-contract structures. Two strategic archetypes dominate: ecosystem-integrated platform vendors with training infrastructure and modular, capital-light challengers designed for smaller hospital footprints. Competitive moves concentrate on geographic expansion into Asian markets and technology licensing for AI-powered surgical analytics.
Within the ecosystem-integrated tier, Intuitive Surgical and Medtronic occupy positions that exemplify divergent approaches to platform deployment. Intuitive Surgical anchors the installed base expansion archetype through its da Vinci ecosystem and training infrastructure concentration. Medtronic represents the surgical navigation extension model, leveraging existing portfolio relationships to extend robotic capabilities into gynecologic workflows. CMR Surgical sits within the capital-light challenger archetype, with modular configurations enabling point-of-care deployment outside traditional operating room infrastructure.
| Leading Market Players |
|---|
| Intuitive Surgical |
| Titan Medical |
| CMR Surgical |
| Medtronic |
| Stryker |
| Johnson & Johnson |
| avateramedical |
| TransEnterix |
| Olympus Corporation |
| Others |
Supply & Pricing Matrix
Captive instrumentation manufacturing by Intuitive Surgical and Medtronic anchors supply positions and pricing power across the gynecology robotic surgery ecosystem. This vertical control over single-use instrument arms locks recurring revenue streams while insulating platform vendors from third-party margin compression.
Pricing Analysis
Capacity additions in Germany and Japan are reshaping price floors for robotic surgical platforms as regional assembly operations reduce import duty burdens. The market operates through a hybrid pricing structure combining seven-figure capital purchase or per-procedure leasing with recurring instrumentation expenditure. Price differentiation rests on FDA clearance tier and bundled training infrastructure, with academic medical centers showing lowest price sensitivity due to volume guarantees while ambulatory surgical facilities face acute capital constraints.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and Japan coordinate hub-and-spoke deployment of patient-side carts and instrument arms to hospital systems. Component sourcing draws from precision motor suppliers in Switzerland, optical sensor manufacturers in Japan, and semiconductor fabricators in Taiwan. Single-source vulnerability concentrates in high-definition camera modules, while downstream distribution runs through vendor-managed inventory agreements with integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gynecology robotic surgery functions as a regulatory compounder where FDA streamlined review pathways and EU MDR transitional provisions accelerate platform clearance velocity and sustain procurement demand.
For Market Incumbents: Acquire simulation-based training assets to address credentialing pipeline constraints that limit platform deployment growth. Consolidate remote proctoring capabilities to defend against CMR Surgical's modular challengers, while securing backward integration into haptic feedback sensor production to protect component margins from Taiwan supply volatility.
For New Entrants and Emerging Players: Cloud-native surgical analytics platforms offer technology-first wedge positioning against installed-base incumbents. Target ambulatory surgical facilities in United States metropolitan markets with capital-light subscription models, leveraging per-procedure leasing structures that bypass hospital capital committee approval cycles.
For Investors and Strategic Acquirers: Roll-up economics work for software-enabled service layers because hospital procurement committees increasingly bundle training, maintenance, and analytics into multi-year vendor contracts. Monitor endometriosis diagnostic rate trajectories at tertiary care centers as the primary inflection signal for procedural volume expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Multi-year service agreements with United States integrated delivery networks lock in instrumentation recurring revenue. |
| FDA Submission | Streamlined premarket notification pathways compress clearance timelines for AI-assisted suturing algorithms. |
| CE Marking Pathway | EU MDR conformity assessments through notified bodies extend market entry timelines but favor incumbents with technical files. |
| Software Companion Development | Cloud-based analytics modules differentiate vendor ecosystems through intraoperative guidance and post-procedure benchmarking. |
| Reimbursement Strategy | CMS schedule alignment for robotic-assisted hysterectomy codes determines academic medical center procurement prioritization. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down surgical platform shipment tracking forms the analytical core. Primary interviews with gynecologic surgeons, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers combined with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital capital expenditure disclosures, and EU MDR notified body certificates.
Historical trendline analysis across installed base expansion, procedure volume migration, and instrumentation consumption patterns informed projection frameworks. Segmentation dimensions modeled include product type, procedure category, end-user scale, and deployment architecture. CAGRs derived from procedure volume elasticity against reimbursement schedule changes and platform adoption S-curves, with surgical navigation integration rates and AI module attach rates serving as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to cybersecurity standard evolution and training pipeline bottlenecks. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Dialysis Catheters Market
Medical Devices
Neurothrombectomy Devices Market
Medical Devices
Europe Medical Devices Market
Medical Devices
Continuous Bladder Irrigation Devices Market
Medical Devices
Mexico Respiratory Devices Market
Medical Devices
Veno-Venous Extracorporeal Life Support (VV ECLS) Devices Market
Medical Devices
Cardiac Resynchronization Therapy (CRT) Devices Market
Medical Devices
Prescription Goggles Market
Medical Devices
Global Pneumatic Tourniquets Market
Medical Devices
North America Advanced Drug Delivery Systems Market
Medical Devices
Smart Bassinet Market
Medical Devices
Memory Implants Market
Medical Devices
Medical Device Complaint Management Market
Medical Devices
Middle East and Africa Vagus Nerve Stimulation Market
Medical Devices
Asia-Pacific Arthroscopy Devices Market
Medical Devices
Intracranial Pressure (ICP) Monitoring Devices Market