
 Transcatheter Pacing System Market | 2026-2036
Transcatheter Pacing System Market Size, Share, and Industry Trends Forecast 2026-2036
Transcatheter Pacing System Market Analytics
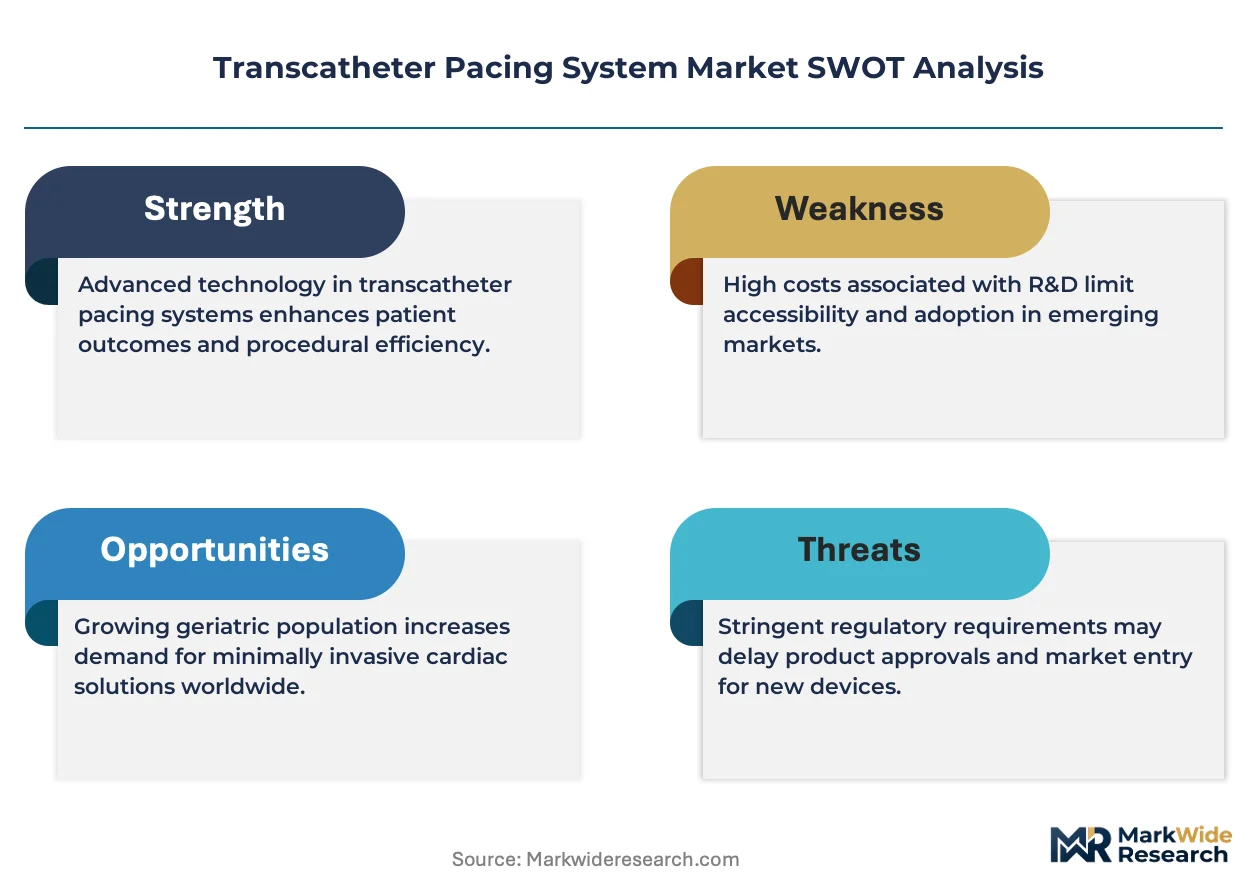
Hospital procurement consortiums is reshaping how transcatheter pacing systems reach end users, with centralized contracting favoring vendors with broad cath-lab portfolios. Medtronic PLC leverages its integrated structural heart ecosystem to secure multi-year supply agreements with IDNs. Abbott Laboratories anchors its position through wireless communication-enabled devices that align with MRI-conditional workflow demands. Boston Scientific Corporation competes on electrophysiology study integration, bundling pacing with mapping platforms.
A transcatheter pacing system delivers electrical stimulation directly to myocardial tissue via catheter-based deployment, eliminating thoracotomy and enabling battery-powered or wireless energy transfer through miniaturized electrodes positioned in the right ventricle or atrium. The device serves patients with bradycardia or conduction disorders who face elevated surgical risk from conventional transvenous leads. Leadless pacing systems command premium positioning due to elimination of lead-related complications and reduced extraction burden, while temporary pacing systems retain volume concentration in emergency resuscitation settings where rapid deployment outweighs longevity requirements. Cardiac resynchronization therapy represents a developing margin pool as dual-chamber leadless synchronization achieves technical feasibility.
FDA premarket notification and EU MDR conformity assessment govern device safety and clinical evidence thresholds, with the EU AI Act beginning to shape algorithm-enabled rhythm detection features. Japan's PMDA and China's NMPA impose additional localization requirements for wireless communication protocols and battery chemistry disclosures. Stakeholders must monitor evolving MRI-conditional labeling expansions and health technology assessment body positions on leadless versus transvenous cost-effectiveness.
Market Dynamics
Leadless miniaturization is compressing procedural complexity and expanding eligible patient pools beyond traditional surgical candidates, forcing cath-lab operators to retrain workflows around catheter-based deployment rather than transvenous lead placement.
Growth Catalysts
- EU MDR conformity pathways:Streamlined CE marking for Class III active implantable devices accelerates commercial timelines for manufacturers with established quality management systems.
- Cardiology clinics:Outpatient procedural volumes are rising as same-day discharge protocols reduce hospital bed utilization and lower total episode costs.
- Battery chemistry advances:Solid-state energy storage extends device longevity beyond ten years, reducing replacement burden and revision surgery rates.
Market Restraints
- Precious metal input costs:Platinum-iridium electrode pricing volatility compresses gross margins on premium leadless devices during supply tightness.
- Single-source sterilization capacity:Ethylene oxide contract sterilization concentrates in Midwestern US industrial corridors, creating geographic vulnerability for just-in-time inventory models.
- Transvenous lead extraction infrastructure:Limited specialized centers capable of complex lead management procedures restrict patient referral networks for device upgrades.
Strategic Opportunities
- Japan's PMDA localization mandates:Wireless protocol certification requirements create first-mover advantage for manufacturers investing in domestic clinical trial infrastructure.
- Dual-chamber leadless synchronization:Atrioventricular communication technology convergence with subcutaneous ICD platforms opens cardiac resynchronization therapy segments.
- Direct-to-hospital distribution:Bypassing traditional distributor markups through consignment inventory models captures margin in concentrated IDN purchasing environments.
Industry Challenges
- Electrophysiology fellowship training gaps:Leadless device implantation requires specialized catheter manipulation skills that residency programs have not standardized.
- ISO 14155 clinical investigation timelines:Extended follow-up periods for safety endpoints delay regulatory submissions and compress competitive windows.
- Legacy EMR integration:Wireless telemetry data formats lack interoperability with existing cardiac monitoring platforms, forcing custom interface development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transcatheter Pacing System Market |
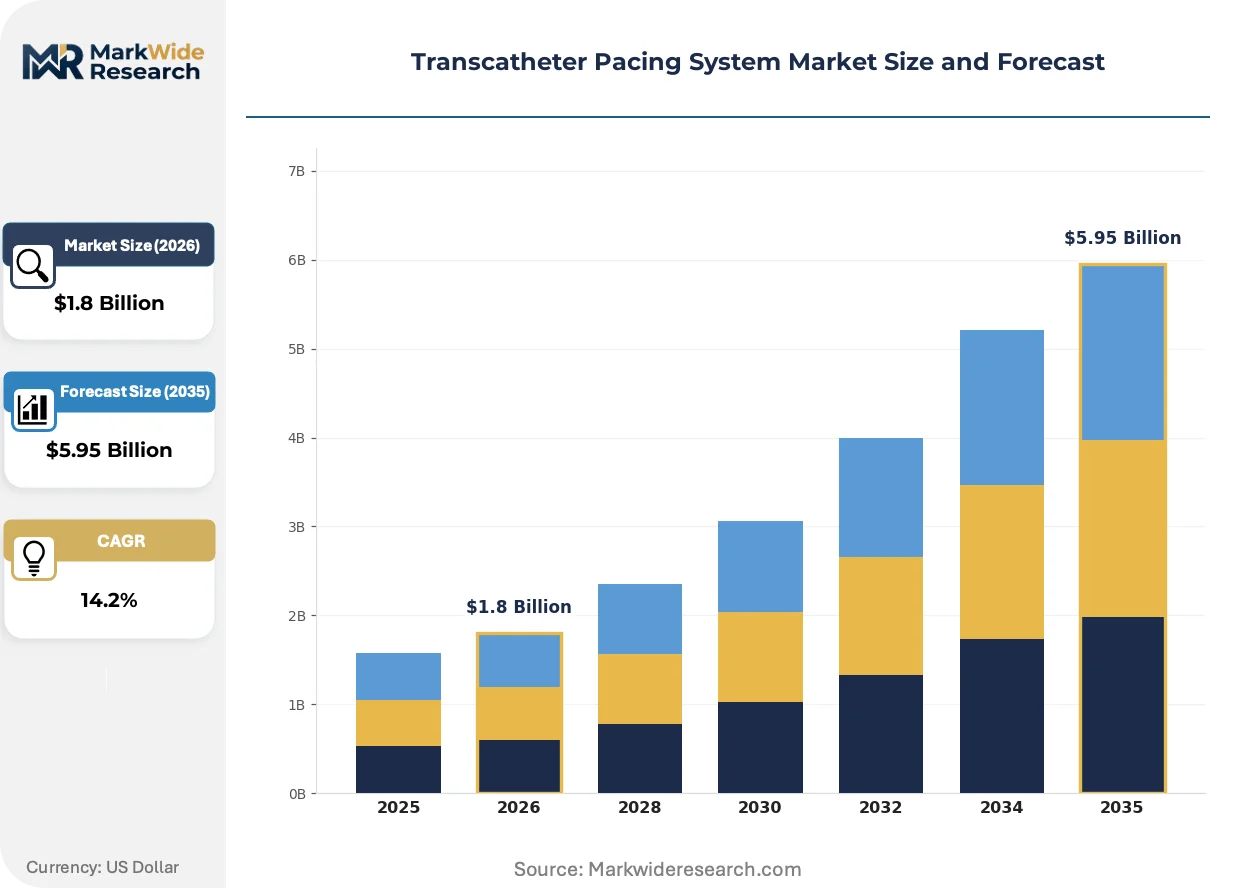
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Temporary Pacing Systems, Permanent Pacing Systems, Leadless Pacing Systems, Cardiac Resynchronization Therapy Technology: Electrical Stimulation, Magnetic Resonance Imaging Compatible, Wireless Communication, Low-Voltage Technology End User: Hospitals, Ambulatory Surgical Centers, Cardiology Clinics, Research Institutions Application: Bradycardia Treatment, Atrial Fibrillation Management, Electrophysiology Studies, Emergency Resuscitation |
| Companies Covered | Medtronic PLC, Abbott Laboratories, Boston Scientific Corporation, EBR Systems Inc., Biotronik SE & Co. KG, MicroPort Scientific Corporation, Lepu Medical Technology Co., Ltd, Osypka AG, Integer Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transcatheter Pacing System Market Evolving Landscape
Algorithm-enabled rhythm detection and remote monitoring architectures are redefining how device performance is validated and reimbursed, shifting evidence requirements from acute safety to longitudinal outcomes data.
Subcutaneous ICD technology is virtualizing the traditional transvenous defibrillator market by eliminating lead-related complications while preserving shock therapy capability. Electrophysiology departments in German university hospitals are adopting hybrid protocols that stage leadless pacing with subcutaneous defibrillation for complete lead-free arrhythmia management. This convergence is virtualizing the historical separation between bradycardia and tachycardia device categories, compressing vendor portfolios into unified rhythm management platforms.
EU AI Act algorithmic risk classification is imposing new conformity assessment burdens on machine-learning-enabled arrhythmia detection features. Manufacturers must now document training data provenance and performance drift monitoring protocols before CE marking updates. Dual-chamber leadless systems with autonomous AV synchronization algorithms face elevated scrutiny under Class IIa medical device software rules, extending approval timelines by twelve to eighteen months.
Hospital procurement consortiums are consolidating purchasing authority into centralized contracting offices that bundle pacing devices with mapping systems and ablation catheters. Integrated delivery networks in the United States are displacing individual physician preference items with standardized device formularies tied to outcomes guarantees. This concentration is most visible in Texas and Florida health systems where cath-lab service line consolidation has reduced active vendor relationships from six to two per IDN.
Transcatheter Pacing System Market Segmentation
Segmentation in transcatheter pacing reveals how clinical risk stratification, reimbursement pathways, and cath-lab infrastructure reshape procurement patterns across device categories. Understanding these divisions exposes where premium pricing holds and where commoditization pressures concentrate.
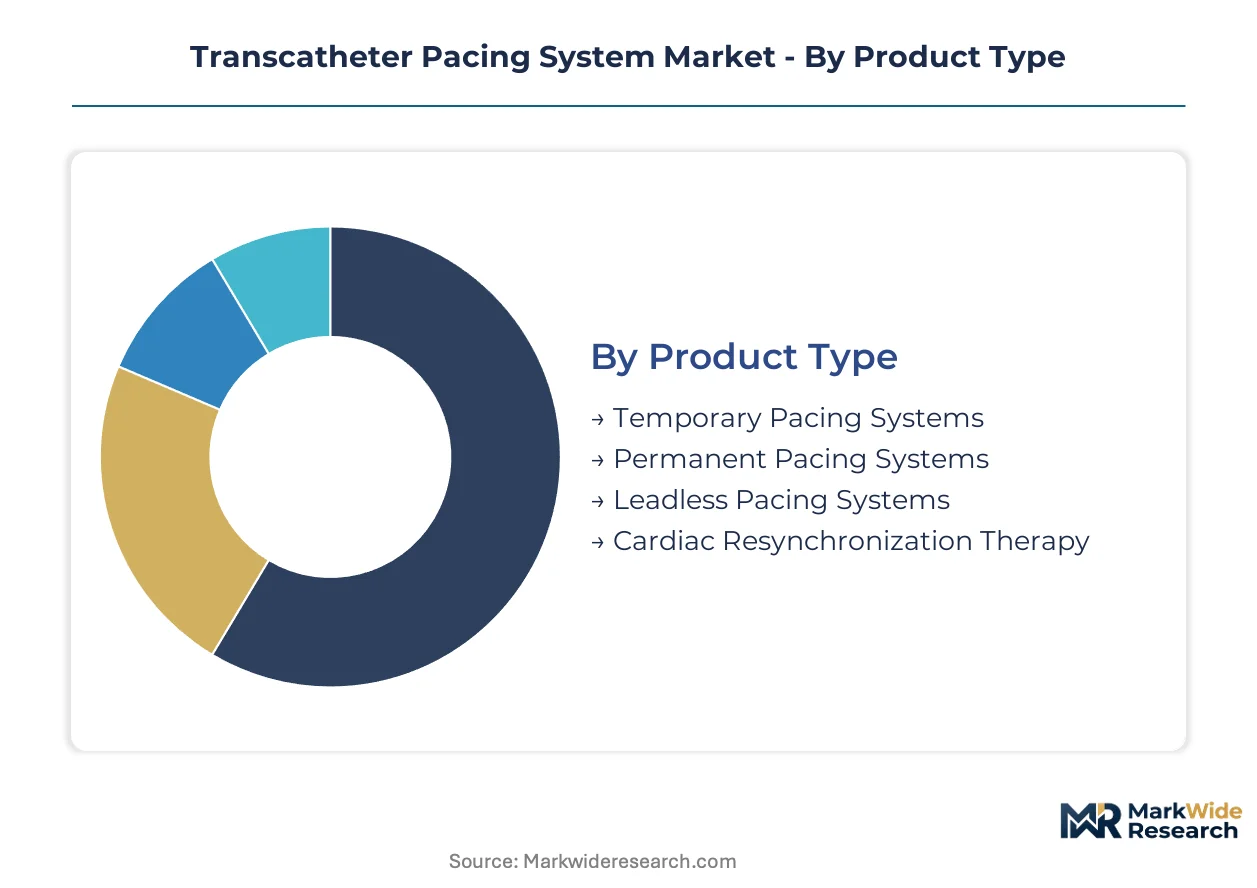
Product Type:
The use-case spectrum spans emergency stabilization through permanent rhythm management, with each tier commanding distinct clinical evidence requirements and replacement economics.
- Leadless Pacing Systems:Miniaturized devices deploy directly into right ventricular myocardium via femoral catheter access, eliminating lead-related endocarditis and extraction risks. Demand concentrates in United States academic medical centers where same-day discharge protocols reduce episode costs and justify premium reimbursement.
- Permanent Pacing Systems:Transvenous lead-based devices with subcutaneous pulse generators remain the volume anchor in Germany and Japan due to established implantation training pathways and broad MRI-conditional labeling. Reimbursement stability in statutory health systems sustains manufacturer margins despite lead complication liabilities.
- Temporary Pacing Systems:External pulse generators with transcutaneous or transvenous leads dominate emergency resuscitation workflows where rapid deployment outweighs longevity requirements.
- Cardiac Resynchronization Therapy:Biventricular pacing systems address heart failure with reduced ejection fraction through coordinated septal and lateral wall activation.
Established volume favors permanent pacing systems; emerging adoption favors leadless pacing systems.
Technology:
Cost tier differentiation separates premium-positioned modalities from standard-of-care alternatives, with regulatory labeling driving reimbursement bandwidth.
- Magnetic Resonance Imaging Compatible:Devices engineered with ferromagnetic shielding and lead insulation modifications permit full-body MRI scanning without device deactivation, commanding price premiums in United States integrated delivery networks where outpatient imaging volume is high.
- Wireless Communication:Radiofrequency or Bluetooth-enabled telemetry permits remote monitoring of battery status, arrhythmia burden, and lead integrity through patient home transmitters, reducing in-person clinic visits and supporting value-based contracting with Medicare Advantage plans.
- Electrical Stimulation:Conventional voltage-output pacing through endocardial or epicardial electrodes constitutes the baseline technology tier with mature reimbursement codes.
- Low-Voltage Technology:Energy-efficient circuit design extends battery longevity through reduced current drain during capture.
MRI-conditional labeling captures premium tier pricing; wireless telemetry expands fastest into accountable care contracts.
End User:
Customer type concentration determines distribution economics, with procurement authority shifting from individual electrophysiologists toward centralized supply chain offices.
- Cardiology Clinics:Outpatient facilities specializing in electrophysiology procedures drive leadless system adoption through streamlined same-day discharge protocols and lower facility fees compared to hospital-based implantation, particularly in Florida and Texas health systems with consolidated cath-lab service lines.
- Hospitals:Academic medical centers and community hospitals retain complex case referrals including device upgrades, lead extractions, and combined procedures with structural heart interventions, sustaining higher reimbursement rates under inpatient diagnosis-related group codes.
- Ambulatory Surgical Centers:Medicare-certified ASCs gain pace for low-complexity generator changes and single-chamber implants with reduced overhead structures.
- Research Institutions:Clinical trial sites and academic research organizations generate early feasibility data for novel leadless configurations and dual-chamber synchronization algorithms.
Hospital infrastructure anchors procedure complexity; cardiology clinics are climbing the fastest in leadless volume share.
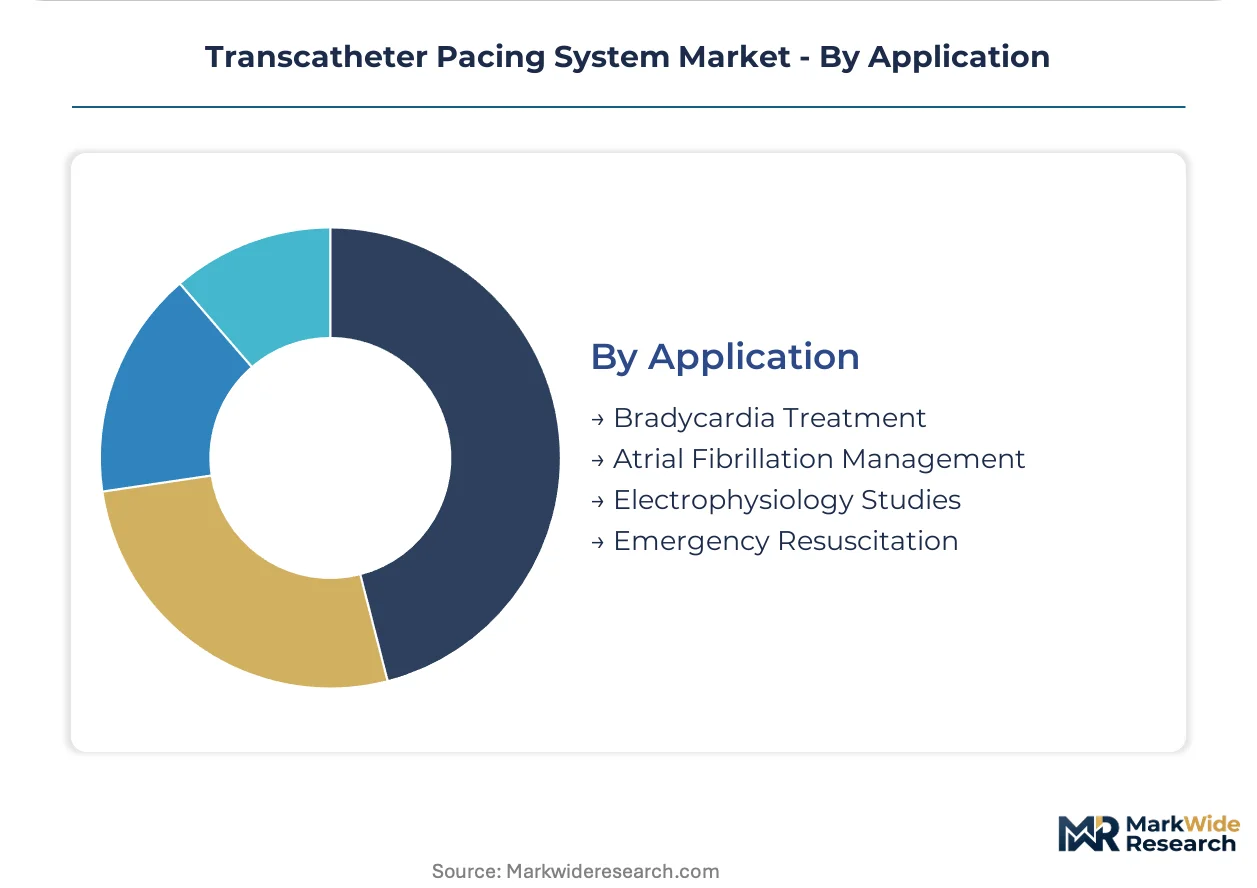
Application:
Application segmentation tracks how rhythm disorder severity and acuity reshape device selection criteria and implantation setting.
- Bradycardia Treatment:Symptomatic sinus node dysfunction and atrioventricular block constitute the foundational indication for permanent pacing, with leadless systems penetrating high-risk surgical candidates and anticoagulated patients where lead extraction hazards are prohibitive.
- Atrial Fibrillation Management:Rate control through AV node ablation with subsequent pacemaker dependency creates demand for reliable ventricular capture, with Japanese electrophysiology departments favoring leadless backup following pulmonary vein isolation failures.
- Electrophysiology Studies:Diagnostic and therapeutic catheter ablation procedures utilize temporary pacing for programmed stimulation and arrhythmia induction.
- Emergency Resuscitation:Transcutaneous and transvenous temporary pacing stabilizes hemodynamically unstable bradycardia in emergency departments and critical care units.
Bradycardia treatment sustains installed base economics; atrial fibrillation management applications are gaining share fastest as ablation-to-pacemaker pathways mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Cleveland Clinic catheterization laboratory network anchors United States demand for transcatheter pacing procedures, while Japan's Tokyo-Osaka high-speed rail corridor enables rapid device distribution across its aging population centers.
United States
Integrated delivery networks in Texas and Florida consolidate cath-lab purchasing authority into centralized supply chain offices. FDA premarket approval pathways for Class III active implantable devices mandate extended clinical follow-up periods that delay novel leadless system launches. The Mayo Clinic Rochester campus generates early feasibility data for dual-chamber leadless synchronization algorithms through its electrophysiology fellowship training program.
Germany
Statutory health insurance reimbursement stability sustains manufacturer margins for permanent transvenous pacing systems despite lead complication liabilities. EU MDR conformity assessment under the Medical Device Regulation tightens evidence requirements for wireless communication-enabled devices. University hospital electrophysiology departments in Munich and Heidelberg adopt hybrid protocols staging leadless pacing with subcutaneous defibrillation.
Japan
PMDA localization mandates for wireless protocol certification create first-mover advantage for manufacturers investing in domestic clinical trial infrastructure. METI industrial policy supports battery chemistry research partnerships between device manufacturers and domestic materials suppliers. The Osaka-Kobe medical device manufacturing cluster concentrates sterilization capacity and precision machining capabilities for miniaturized electrode production.
China
NMPA registration requirements for wireless communication protocols and battery chemistry disclosures extend regulatory timelines for foreign manufacturers. The Shanghai Zhangjiang Hi-Tech Park hosts domestic catheter assembly operations serving regional hospital procurement consortiums. Provincial health commissions in Guangdong and Jiangsu pilot value-based reimbursement pilots for outpatient leadless implantation procedures.
Transcatheter Pacing System Market Competitive Landscape
On the supply side, the industry is consolidating around integrated structural heart ecosystems that bundle pacing devices with mapping systems and ablation catheters. Three strategic archetypes dominate: diversified medical technology conglomerates with broad cath-lab portfolios, specialized electrophysiology device manufacturers with focused rhythm management platforms, and emerging regional players leveraging domestic regulatory pathways. Competitive moves concentrate on multi-year supply agreements with integrated delivery networks and algorithm-enabled rhythm detection capabilities that satisfy EU AI Act conformity requirements.
Among diversified medical technology conglomerates, Medtronic PLC and Abbott Laboratories occupy positions as archetypal integrated platform vendors. Boston Scientific Corporation exemplifies the electrophysiology-focused specialist model. These three anchors represent the competitive tension between breadth-driven procurement consolidation and depth-driven clinical workflow integration.
| Leading Market Players |
|---|
| Medtronic PLC |
| Abbott Laboratories |
| Boston Scientific Corporation |
| EBR Systems Inc. |
| Biotronik SE & Co. KG |
| MicroPort Scientific Corporation |
| Lepu Medical Technology Co., Ltd |
| Osypka AG |
| Integer Holdings Corporation |
| Others |
Value Network & Pricing Analysis
The Minneapolis-St. Paul medical device manufacturing corridor concentrates ethylene oxide sterilization capacity and precision machining for platinum-iridium electrodes, creating geographic chokepoints that downstream manufacturers leverage into volume-tiered pricing power. Cath-lab procurement consortiums exploit this concentration to extract multi-year contracting concessions from vendors with limited alternative sterilization pathways.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs transcatheter pacing system procurement. Premium positioning attaches to MRI-conditional labeling and wireless telemetry capabilities, while standard tiers capture permanent transvenous systems with established reimbursement codes. Cost compression in the economy tier intensifies as temporary pacing systems face commoditization from Asian manufacturers. Integrated delivery networks exhibit highest price sensitivity through centralized formulary control, whereas academic medical centers prioritize clinical outcomes over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk assessment for battery chemistry components and wireless communication modules. Manufacturing concentration rests on Germany, Japan, and the United States for precision electrode fabrication and sterilization services. Platinum-iridium alloys and solid-state battery substrates constitute critical raw material dependencies. Single-source sterilization vulnerability in Midwestern US industrial corridors threatens just-in-time inventory models. Distribution runs through direct-to-hospital consignment arrangements that bypass traditional distributor markups in concentrated IDN purchasing environments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The transcatheter pacing system market functions as a defensive-moat arena where FDA premarket approval pathways and EU MDR conformity requirements create regulatory entrenchment that protects incumbent positions. Switching costs for cath-lab operators trained on specific catheter deployment protocols reinforce this structural advantage.
For Market Incumbents: Entrench market position through backward integration into sterilization capacity and captive supply of platinum-iridium electrode substrates. Secure multi-year supply agreements with Texas and Florida integrated delivery networks before dual-chamber leadless systems achieve regulatory clearance. Threaten margin compression from emerging regional players in China leveraging NMPA domestic pathway advantages.
For New Entrants and Emerging Players: China's provincial health commissions in Guangdong and Jiangsu present underpenetrated outpatient leadless implantation corridors where value-based reimbursement pilots reduce incumbent lock-in. Target cardiology clinic segments in Japan's Tokyo-Osaka corridor where PMDA wireless protocol certification creates first-mover windows for algorithm-enabled rhythm detection platforms. Pursue direct-to-hospital distribution models that displace incumbent consignment relationships.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors electrophysiology-focused specialists with integrated mapping-pacing platforms over diversified conglomerates with diluted R&D allocation. Long-term viability hinges on algorithmic differentiation under EU AI Act conformity frameworks. Acquisition target archetype: mid-cap device manufacturers with approved dual-chamber leadless synchronization algorithms and established Japanese clinical trial infrastructure. Signal to monitor: FDA premarket approval timeline compression for wireless telemetry-enabled systems.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Conformity Pathway | CE marking under Medical Device Regulation tightens evidence thresholds for wireless-enabled leadless devices. |
| Hospital System Partnership | Multi-year supply agreements with Texas and Florida IDNs secure formulary positioning against competitor bundling. |
| Software Companion Development | Algorithm-enabled rhythm detection features face EU AI Act Class IIa scrutiny extending approval timelines. |
| Reimbursement Strategy | Medicare Advantage value-based contracting for remote monitoring expands wireless telemetry adoption. |
| FDA Submission | Premarket approval pathways for dual-chamber leadless systems mandate extended clinical follow-up periods. |
Research Methodology
A standing panel of electrophysiologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers provided ongoing calibration against operating reality. Primary interviews with these stakeholders combined with secondary validation from FDA 510(k) filings, EU MDR notified body opinions, hospital procurement databases, and CMS Medicare claims data. Bottom-up device shipment modeling and top-down cath-lab procedure volume estimates were triangulated to constrain forecast variance.
Scenario-bracketing framed analytical outputs across conservative, baseline, and aggressive adoption pathways without specifying discrete timeline anchors. Segmentation dimensions modeled included product type tier, technology modality, end-user facility category, and application severity across the projection horizon. CAGRs were derived from installed base dynamics and replacement cycle economics. Forecast inputs incorporated battery chemistry longevity improvements and MRI-conditional labeling expansion rates.
The forecast holds incumbent behavior within observed patterns; aggressive pricing moves by Chinese regional manufacturers or accelerated EU AI Act enforcement would shift outcomes materially. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Medical Mobility Aid Market
Medical Devices
Pulmonary Heart Valve Replacement Market
Medical Devices
Nanomedical Devices Market
Medical Devices
Global High-Flow Nasal Cannula Market
Medical Devices
Minimally Invasive Neurosurgery Devices Market
Medical Devices
Endodontic Files Market
Medical Devices
Adult Water Flosser Market
Medical Devices
Leadless Pacing Systems Market
Medical Devices
Implantable Neurostimulators Market
Medical Devices
United Kingdom Drug Delivery Devices Market
Medical Devices
Gastric Bands Market
Medical Devices
X-Ray Positioning Devices Market
Medical Devices
Disposable Contact Lenses Market
Medical Devices
Global Prefilled Auto Injectors Market
Medical Devices
India Static Compression Therapy Market
Medical Devices
Aesthetic Devices Market