
 Magnetic Ablation Catheter Market | 2026-2036
Magnetic Ablation Catheter Market Size, Share, and Industry Trends Forecast 2026-2036
Magnetic Ablation Catheter Market Insights
Buyer concentration in the Magnetic Ablation Catheter Market is pivoting toward large integrated health systems and specialized cardiac centers that command procurement scale across multiple sites. Medtronic leverages its integrated electrophysiology ecosystem to secure long-term supply agreements with major hospital networks. Boston Scientific sustains competitive intensity through dedicated magnetic navigation R&D programs. Abbott anchors its position via broad catheter portfolio breadth that spans diagnostic and therapeutic applications.
A magnetic ablation catheter employs electromagnetic field guidance to steer a flexible catheter tip through cardiac chambers with sub-millimeter precision, typically incorporating nickel-titanium alloy construction and real-time location tracking for targeted radiofrequency or cryothermal lesion delivery. The primary commercial purpose is to treat cardiac arrhythmias—particularly atrial fibrillation—with reduced fluoroscopic exposure and enhanced procedural reproducibility. Radiofrequency systems occupy the dominant revenue position due to established reimbursement pathways and broad operator familiarity, while cryoablation segments are gaining fastest traction among newer centers seeking simplified single-shot pulmonary vein isolation workflows. Cardiology therapy areas command the deepest margin pools as repeat procedure volumes and device upgrade cycles concentrate spending within electrophysiology departments.
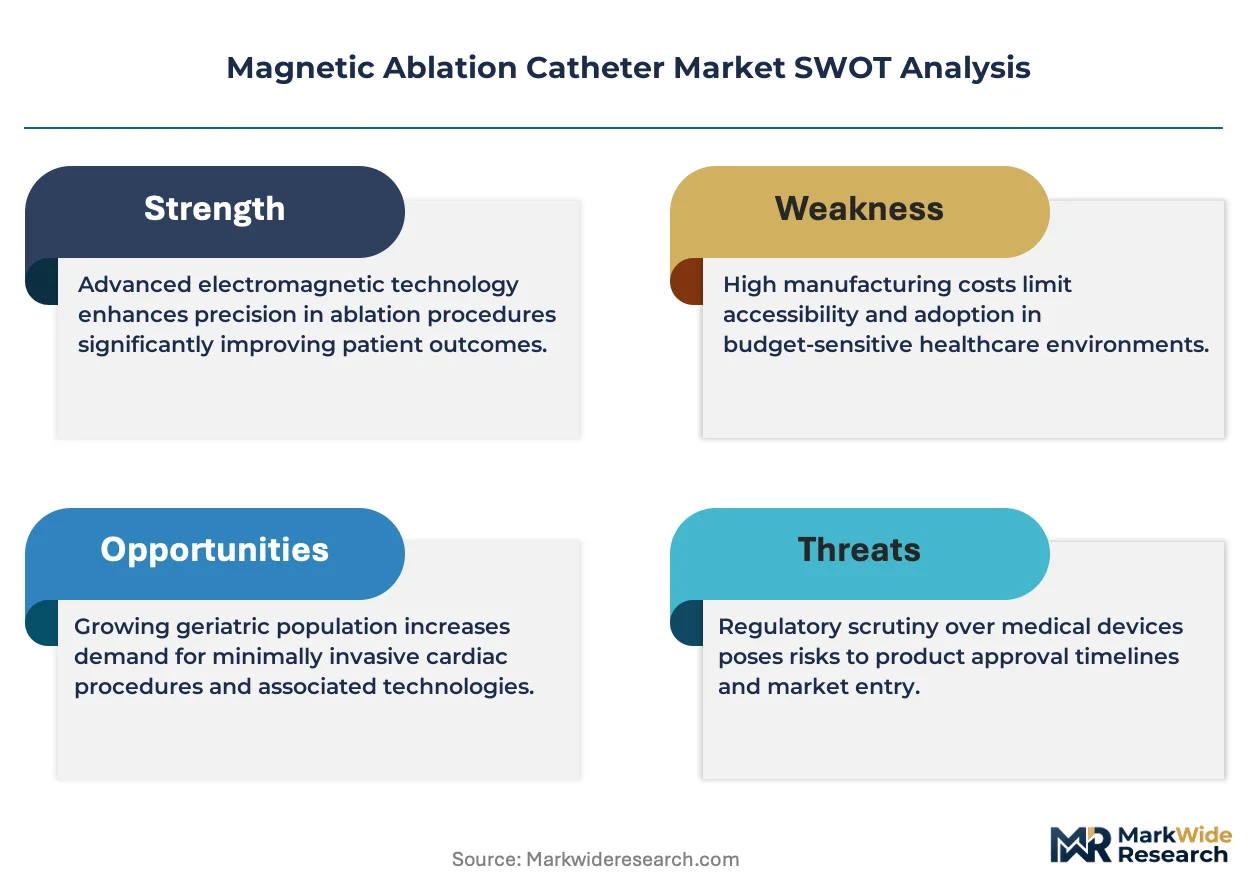
FDA premarket notification requirements and CE marking under the EU Medical Device Regulation shape product development timelines and clinical evidence thresholds for magnetic catheter systems. The EU AI Act and FDA software-as-medical-device guidance are extending compliance scope to algorithmic components in magnetic navigation platforms. Stakeholders must monitor evolving interoperability standards between magnetic navigation systems and third-party mapping technologies.
Market Dynamics
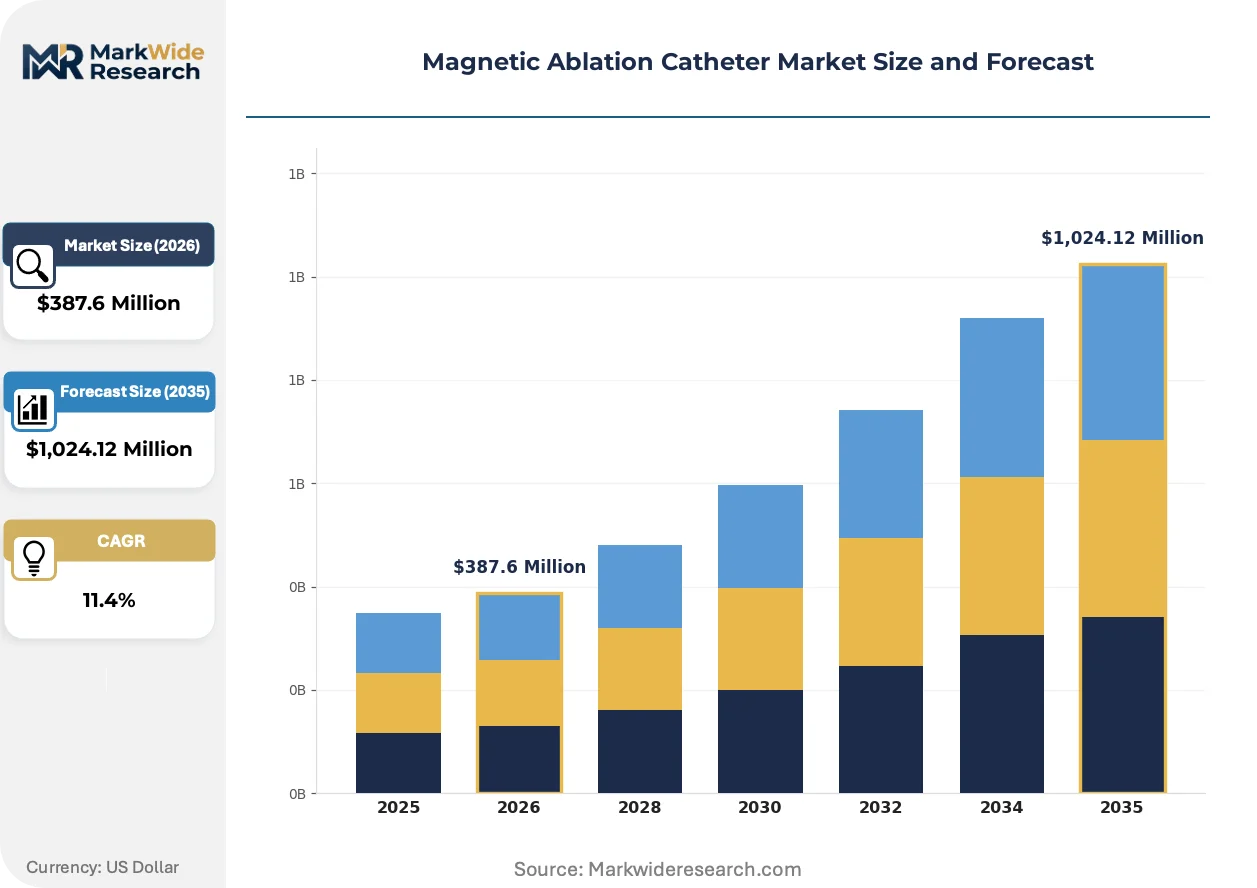
The magnetic ablation catheter market pivots on the tension between procedural volume expansion in tertiary cardiac centers and the capital intensity required to deploy magnetic navigation infrastructure at scale.
Growth Catalysts
- EU Medical Device Regulation:The MDR's enhanced clinical evidence requirements are filtering out marginal catheter suppliers, concentrating procurement among validated magnetic navigation platforms that meet post-market surveillance mandates.
- Atrial fibrillation prevalence:Aging demographics across Germany, Japan, and the United States are expanding the addressable patient pool for catheter ablation procedures that magnetic guidance systems target.
- Nickel-titanium alloy advances:Improved shape-memory catheter construction enables tighter curvature radii and enhanced torque response, expanding anatomical reach during pulmonary vein isolation.
Market Restraints
- Capital equipment concentration:Magnetic navigation system hardware requires seven-figure facility investments, limiting deployment to integrated health networks with centralized procurement authority.
- Neodymium supply vulnerability:Rare earth magnet sourcing concentrates in Chinese processing facilities, exposing catheter manufacturers to export quota volatility and geopolitical supply disruption.
- Fluoroscopy dependency reduction:Magnetic guidance reduces but does not eliminate X-ray exposure, creating hybrid workflow complexity that slows full adoption in cost-constrained centers.
Strategic Opportunities
- Outpatient migration:Ambulatory surgical centers in the United States are gaining CMS reimbursement for select electrophysiology procedures, opening a channel previously blocked by facility fee structures.
- AI navigation convergence:Machine learning trajectory prediction layered onto magnetic field control is compressing operator learning curves and enabling procedure standardization across experience levels.
- Japan's super-aging policy:METI reimbursement incentives for minimally invasive cardiac interventions are accelerating magnetic platform adoption in prefectural medical centers outside Tokyo and Osaka.
Industry Challenges
- Electrophysiologist training pipelines:Magnetic navigation proficiency requires dedicated fellowship exposure that remains unevenly distributed across accredited programs, constraining operator supply.
- FDA software-as-medical-device compliance:Algorithmic components in magnetic navigation platforms now require standalone 510(k) pathways, extending development timelines and documentation burdens.
- Legacy mapping integration:Proprietary magnetic navigation protocols create interoperability friction with third-party electroanatomic mapping systems already deployed in target catheterization labs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnetic Ablation Catheter Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radiofrequency, Cryoablation, Microwave, Laser, Ultrasound Therapy Area: Cardiology, Oncology, Neurology, Pulmonology, Urology End User: Cardiac Centers, Cancer Clinics, Neurological Institutes, Pulmonary Hospitals, Urology Facilities Deployment Type: Hospital-Based, Ambulatory Surgery Centers, Specialized Clinics, Research Institutes |
| Companies Covered | Medtronic, Boston Scientific, Abbott, Johnson & Johnson MedTech, Siemens Healthineers, Koninklijke Philips, GE HealthCare, MicroPort Scientific, Biotronik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnetic Ablation Catheter Market Trends and Innovations
Magnetic catheter technology is undergoing a platform shift from operator-dependent manual steering to algorithm-assisted navigation, with regulatory frameworks and procurement models adapting to capture the efficiency gains.
Robotic magnetic catheter steering is automating tip positioning through closed-loop electromagnetic field modulation, reducing hand-tremor artifacts during lesion delivery. Tertiary cardiac centers in Germany and the United States are deploying these systems for complex atrial flutter cases where anatomical variability challenges conventional manual approaches. The technology is automating procedure standardization, compressing the experience gradient between senior electrophysiologists and early-career operators.
CE marking under the EU AI Act now extends to predictive trajectory algorithms embedded in magnetic navigation software, requiring documented training data provenance and performance validation across patient phenotypes. Manufacturers must maintain algorithm version control and post-deployment monitoring systems that track real-world navigation accuracy. Cryoablation catheter segments face the steepest compliance curve due to the combined thermal and magnetic control variables in their regulatory submissions.
Integrated health systems are consolidating electrophysiology device procurement under value-based contracting frameworks that bundle magnetic navigation hardware, disposable catheters, and procedural support into multi-year agreements. This displaces the traditional transactional purchase model where hospitals acquired capital equipment and consumables through separate budget lines. The shift is most visible in United States hospital networks seeking to lock in magnetic platform standardization across multiple sites while capping per-procedure costs.
Magnetic Ablation Catheter Market Segmentation
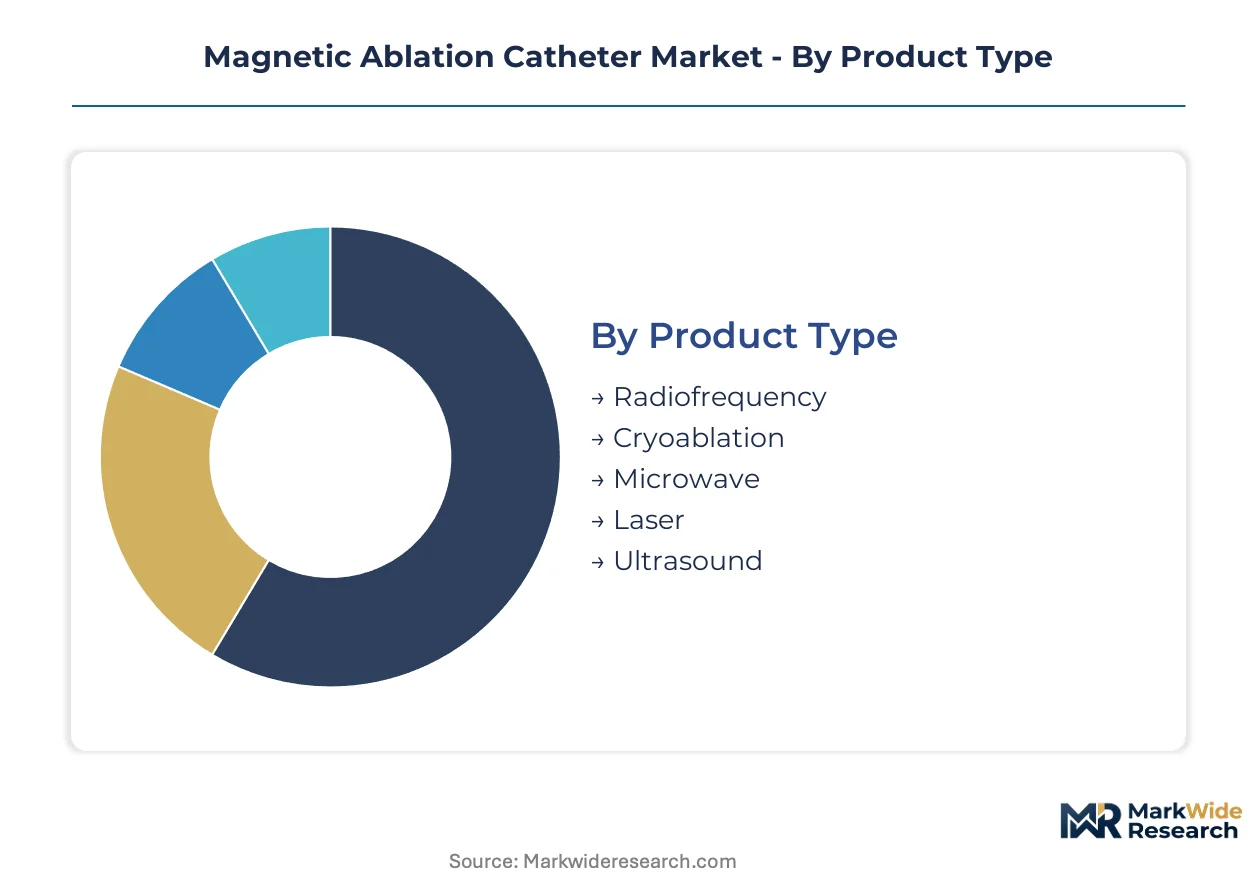
Segmentation in the magnetic ablation catheter market reveals how regulatory pathways, procedural economics, and site-level infrastructure requirements fragment commercial opportunity across distinct technology and customer configurations.
Product Type:
FDA 510(k) and CE marking under MDR impose divergent clinical evidence burdens across thermal modalities, with radiofrequency systems facing streamlined predicate pathways while cryoablation navigates more extensive safety dossiers.
- Radiofrequency:Nickel-titanium alloy construction delivers resistive heating through tip electrodes at 450-500 kHz frequency. Demand concentrates in United States tertiary cardiac centers where established CPT reimbursement codes and operator familiarity sustain procedural volume leadership.
- Cryoablation:Nitrous oxide or argon-based cooling achieves transmural lesions through thermal conductivity rather than resistive heating. Adoption accelerates in German hospital networks seeking single-shot pulmonary vein isolation workflows that compress procedure times for atrial fibrillation cases.
- Microwave:Electromagnetic energy at 915 MHz or 2.45 GHz generates deeper tissue penetration than radiofrequency alternatives.
- Laser:Optical fiber delivery of 980 nm or 1064 nm wavelength energy enables precise photothermal ablation with minimal collateral damage.
- Ultrasound:High-intensity focused acoustic waves create thermal coagulation without electrode-tissue contact requirements.
Radiofrequency sits at the top of the volume ranking, with Cryoablation climbing the fastest.
Therapy Area:
Reimbursement intensity and procedure repeat rates create stark margin differentiation across clinical applications, with cardiac arrhythmia interventions commanding premium device economics.
- Cardiology:Atrial fibrillation ablation drives catheter consumption through repeat procedure requirements and magnetic navigation platform upgrades. United States electrophysiology departments generate the deepest revenue pools as aging demographics expand the addressable patient base.
- Oncology:Tumor ablation applications leverage magnetic guidance for percutaneous liver and kidney lesion targeting. Japanese cancer centers are deploying these systems under METI reimbursement incentives for minimally invasive oncological interventions.
- Neurology:Magnetic resonance-guided focused ultrasound addresses essential tremor and Parkinson's disease through non-invasive thalamic lesioning.
- Pulmonology:Bronchoscopic ablation of malignant airway lesions employs catheter-based thermal destruction with electromagnetic navigation assistance.
- Urology:Renal denervation and prostate ablation procedures utilize magnetic catheter steering for anatomical precision in confined pelvic spaces.
Cardiology commands the largest revenue share, while Oncology gains share fastest as tumor ablation protocols mature.
End User:
Procurement authority and capital allocation flexibility determine site-level adoption velocity, with integrated health systems leveraging multi-site standardization against standalone facility constraints.
- Cardiac Centers:Dedicated electrophysiology suites with magnetic navigation infrastructure perform high-volume ablation procedures. German tertiary centers lead European deployment as regional referral hubs consolidate complex arrhythmia cases.
- Cancer Clinics:Outpatient oncology facilities integrate magnetic ablation for percutaneous tumor treatment alongside systemic therapy programs. United States ambulatory cancer centers are gaining CMS facility fee recognition for select image-guided ablation procedures.
- Neurological Institutes:Academic medical centers combine magnetic navigation with intraoperative imaging for functional neurosurgery applications.
- Pulmonary Hospitals:Thoracic specialty centers deploy electromagnetic bronchoscopy platforms for peripheral lung lesion access.
- Urology Facilities:High-volume prostate and kidney centers incorporate magnetic catheter systems for focal therapy programs.
Cardiac Centers anchor installed base concentration, with Cancer Clinics expanding most quickly as ablation migrates outpatient.
Deployment Type:
Site classification shapes capital equipment financing structures and disposable catheter contract terms, with hospital-based procurement dominating magnetic platform economics.
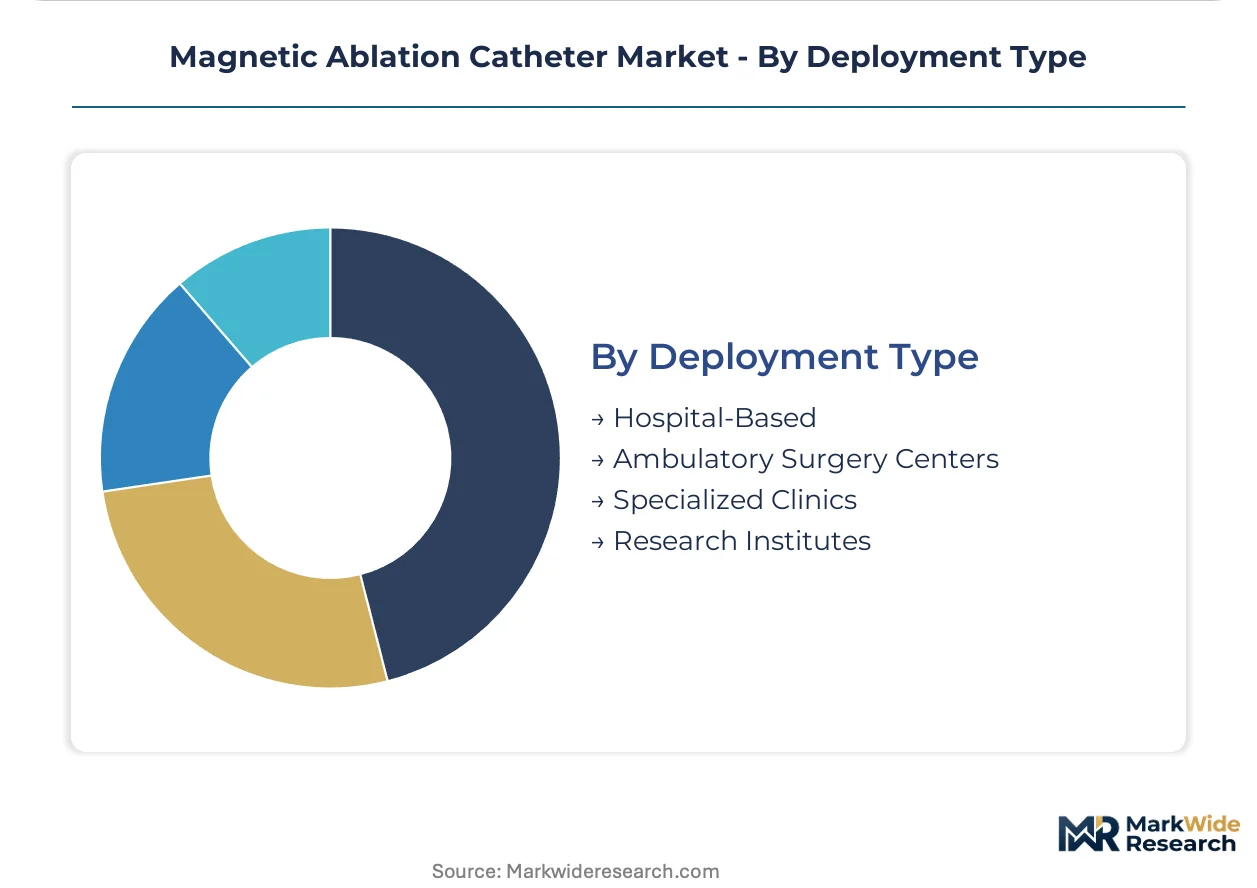
- Hospital-Based:Integrated delivery networks negotiate multi-year magnetic navigation agreements bundling hardware, catheters, and technical support. United States health systems exploit centralized procurement to standardize platforms across 5-15 affiliated catheterization laboratories.
- Ambulatory Surgery Centers:Freestanding electrophysiology facilities in the United States are securing CMS reimbursement for select ablation procedures previously restricted to hospital outpatient departments.
- Specialized Clinics:Single-specialty cardiac or oncology practices access magnetic navigation through equipment leasing and per-procedure catheter purchasing arrangements.
- Research Institutes:Academic centers drive algorithm development and clinical trial enrollment for next-generation magnetic navigation systems.
Hospital-Based deployment retains the dominant volume position, with Ambulatory Surgery Centers showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States cardiac centers deploy magnetic navigation platforms at triple the density of Japanese prefectural hospitals, yet Tokyo's super-aging policy accelerates per-capita adoption faster than any Western market.
United States
Tertiary cardiac centers in Cleveland Clinic and Mayo Clinic networks drive magnetic ablation catheter procurement through value-based contracting with integrated health systems. FDA premarket notification requirements under 510(k) pathways shape product development timelines for electromagnetic navigation software. The Texas Medical Center in Houston anchors the highest procedural volume concentration outside the Northeast corridor.
Germany
University hospitals in Munich and Heidelberg lead European adoption of cryoablation magnetic systems for single-shot pulmonary vein isolation workflows. CE marking under the EU Medical Device Regulation filters marginal suppliers from procurement lists at Baden-Württemberg cardiac centers. The Berlin-Brandenburg region concentrates magnetic navigation R&D partnerships between Charité hospital networks and industrial clusters.
Japan
METI reimbursement incentives for minimally invasive cardiac interventions accelerate magnetic platform deployment in prefectural medical centers beyond Tokyo and Osaka. PMDA approval pathways for software-as-medical-device components extend documentation burdens for algorithmic navigation systems. The Nagoya medical corridor in Aichi Prefecture emerges as the fastest-growing hub for electrophysiology infrastructure investment.
China
NMPA registration requirements for Class III medical devices create extended clinical evidence thresholds for foreign magnetic catheter manufacturers seeking market access. Domestic hospital procurement in Shanghai and Beijing favors magnetic navigation platforms with localized algorithm training datasets. The Yangtze River Delta medical device cluster in Jiangsu Province concentrates catheter manufacturing partnerships.
United Kingdom
NICE technology appraisals for atrial fibrillation ablation procedures determine magnetic catheter reimbursement eligibility across NHS England cardiac networks. MHRA post-Brexit regulatory divergence from EU MDR creates parallel compliance tracks for electromagnetic navigation systems. The London-Southeast corridor concentrates private hospital investment in magnetic platforms outside NHS procurement frameworks.
Magnetic Ablation Catheter Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the magnetic ablation catheter market, creating a tiered structure where scale-driven portfolios face pressure from nimble technology licensors. The vendor base clusters around three strategic archetypes: integrated electrophysiology ecosystem builders, dedicated magnetic navigation R&D houses, and diversified medical technology conglomerates with catheter divisions. M&A activity concentrates on algorithmic navigation software assets, while strategic partnerships dominate hardware-software integration challenges.
Within the integrated ecosystem tier, Medtronic and Boston Scientific occupy positions that exemplify bundled hardware-consumable contracting models with major hospital networks. Abbott anchors the diversified medical technology archetype through broad catheter portfolio breadth spanning diagnostic and therapeutic applications. These three companies represent the dominant competitive anchors against which regional specialists and emerging technology licensors position alternative magnetic navigation architectures.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific |
| Abbott |
| Johnson & Johnson MedTech |
| Siemens Healthineers |
| Koninklijke Philips |
| GE HealthCare |
| MicroPort Scientific |
| Biotronik |
| Others |
Pricing and Supply Chain Analysis
Integrated health system procurement consolidation across United States hospital networks is forcing magnetic catheter manufacturers toward multi-year bundled contracts that compress per-procedure margins while demanding guaranteed supply continuity. This buyer-side pressure cascades into supply chain restructuring, with vendors absorbing inventory risk to lock in platform standardization deals.
Pricing Analysis
Capacity additions in China's Yangtze River Delta medical device cluster are reshaping price floors for nickel-titanium alloy catheter components. Three-tier pricing structure across premium navigation platforms, standard magnetic systems, and economy manual alternatives dominates contract negotiations. Price differentiation rests on FDA 510(k) clearance tier and real-time algorithmic tracking capability. Cost compression in the economy tier is intensifying because Chinese domestic manufacturers are qualifying for CE marking under MDR. Ambulatory surgery centers exhibit highest price sensitivity; tertiary cardiac centers with captive electrophysiology volumes show lowest.
Supply Chain Analysis
Dual-sourcing mandates from German university hospital networks require magnetic navigation platform vendors to qualify secondary suppliers for critical electromagnetic coil assemblies. Geographic supply concentrates in China for rare earth magnet processing, Germany for precision electromagnetic hardware, and United States for algorithmic navigation software. Raw material dependencies center on neodymium-iron-boron magnets, nickel-titanium shape-memory alloys, and specialized copper windings. Single-source vulnerability in Chinese rare earth export quotas exposes manufacturers to geopolitical disruption. Distribution runs through integrated health system GPO contracts and direct hospital procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where reimbursement tightening and MDR compliance burdens favor validated platforms over marginal suppliers. Demand is shifting toward cryoablation systems with simplified single-shot workflows that command premium positioning.
For Market Incumbents: Deepen algorithmic navigation software moats through PMDA and FDA software-as-medical-device parallel submissions, locking in regulatory lead time against emerging entrants. Expand backward integration into nickel-titanium alloy forging to offset Chinese rare earth magnet price volatility. Defensive priority centers on cryoablation segment share as German hospital networks consolidate procurement. For New Entrants and Emerging Players: Launch via per-procedure leasing models targeting United States ambulatory surgery centers blocked by seven-figure capital barriers. White-space concentrates in oncology tumor ablation applications where magnetic guidance penetration lags cardiology. Prefectural Japanese medical centers outside Tokyo offer fastest regulatory pathway through METI reimbursement incentives. Go-to-market angle should emphasize AI trajectory prediction that compresses operator training requirements. For Investors and Strategic Acquirers: Asymmetric upside sits with algorithmic navigation software licensors lacking captive catheter manufacturing. Long-term viability favors assets with FDA 510(k) predicate pathways and installed base concentration in integrated United States health systems. Acquisition target archetype: mid-cap magnetic platform specialists with cryoablation regulatory dossiers and German university hospital reference sites. Signal to watch is CMS reimbursement expansion for outpatient electrophysiology procedures.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR clinical evidence requirements filter marginal suppliers from European procurement lists. |
| Hospital System Partnership | Value-based contracting with Cleveland Clinic-type networks locks in multi-site platform standardization. |
| Software Companion Development | AI trajectory algorithms now require standalone 510(k) pathways under FDA guidance. |
| Reimbursement Strategy | CMS facility fee recognition for ambulatory centers opens channel previously blocked to magnetic platforms. |
| Backward Integration | In-house nickel-titanium alloy forging reduces exposure to Chinese rare earth export quota volatility. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with electrophysiologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers with secondary validation against FDA 510(k) filings, EMA MDR submission databases, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up catheter volume modeling and top-down magnetic navigation platform deployment estimates were triangulated for convergence.
Historical reference periods anchored the forecast window to established procedural volume baselines and capital equipment replacement cycles across the analysis window. Segmentation dimensions modeled include thermal modality, therapy area specialization, end-user facility type, and deployment setting. CAGRs were derived from procedure volume elasticity to demographic drivers and platform upgrade cycle timing. Industry-specific inputs incorporated electrophysiologist training pipeline capacity and MDR post-market surveillance compliance burdens.
Forecast precision tightens around the base case; tail outcomes carry wider variance under PMDA software-as-medical-device documentation delays or Chinese rare earth export restriction scenarios. Forecasts reflect documented assumptions regarding reimbursement stability and magnetic navigation interoperability standardization. Deviation in CMS ambulatory surgery center facility fee expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
US Prefilled Syringes Market
Medical Devices
Actigraphy Sensors and Polysomnography Devices Market
Medical Devices
Artificial Ventilation and Anesthesia Masks Market
Medical Devices
Canada Spinal Surgery Devices Market
Medical Devices
Wireless Neurofeedback Device Market
Medical Devices
Drug and Gene Delivery Devices Market
Medical Devices
Breast Pump Flange Market
Medical Devices
Ingestible Thermometers Market
Medical Devices
Luer Lock Connector Market
Medical Devices
Global Trauma Devices Market
Medical Devices
Global Large Volume Wearable Injectors Market
Medical Devices
Skull Deformity Implants Market
Medical Devices
Global Ureteroscopes Market
Medical Devices
Mandibular Advancement Devices Market
Medical Devices
North America Biopsy Devices Market
Medical Devices
Global Cardiac Pacemakers Market