
 MIS Sacroiliac Joint Fusion Market | 2026-2036
MIS Sacroiliac Joint Fusion Market Size, Share, and Industry Trends Forecast 2026-2036
MIS Sacroiliac Joint Fusion Market Intelligence
Divergent investment in extensive clinical trial data versus broad portfolio manufacturing scale is rotating competitive positioning among device makers. SI-BONE specializes in building a deep evidence base specifically for its triangular implant system to secure payer coverage. Medtronic, conversely, leverages its established spine surgery distribution channels and brand recognition to compete across a wider range of orthopedic solutions. Globus Medical differentiates through its integrated ecosystem of imaging, robotics, and implants.
Minimally invasive sacroiliac joint fusion is a surgical procedure designed to stabilize the SI joint and alleviate pain stemming from its dysfunction or degeneration. The technique involves placing biocompatible titanium implants or screws across the joint to promote fusion. Its primary purpose is to offer a durable solution for chronic lower back pain unresponsive to conservative treatments. Implant devices and screw systems are the principal product types, while Ambulatory Surgical Centers are a high-growth end-user segment due to procedural efficiencies.
Regulatory pathways from the US FDA and the European Union's Medical Device Regulation (MDR) dictate market access. These bodies require extensive clinical evidence demonstrating safety and efficacy, which directly influences R&D costs and timelines for new devices. The key decision for device manufacturers centers on balancing investment in next-generation technologies like robotic assistance against the cost of generating the clinical data required for expanded reimbursement approval.
Market Dynamics
The central dynamic shaping the market is the strategic divergence between device manufacturers. This tension pits investment in deep, single-product clinical evidence against leveraging broad-portfolio manufacturing scale and established distribution channels to compete across orthopedic surgery.
Growth Catalysts
- Favorable Reimbursement:The establishment of specific CPT codes for minimally invasive SI joint fusion in the United States creates a clear pathway for payment, encouraging adoption by providers and coverage by payers.
- Robotic Integration:The incorporation of robotic assistance and advanced navigation systems into surgical workflows enhances implant placement accuracy and consistency, attracting surgeons and hospitals seeking to improve procedural outcomes.
- Ambulatory Surgical Centers:A procedural shift towards Ambulatory Surgical Centers (ASCs) is expanding access. These facilities favor the efficiency and lower overhead of minimally invasive techniques, creating a high-growth end-user segment.
Market Restraints
- High Device and Procedure Costs:The premium price of biocompatible titanium implants and associated instrumentation, combined with the specialized nature of the surgery, can limit patient access and create reimbursement challenges in some healthcare systems.
- Stringent Regulatory Hurdles:Extensive clinical data requirements from bodies like the US FDA and under the European Union's MDR create high barriers to entry, increasing R&D costs and extending timelines for new device approvals.
- Conservative Treatment Preference:A significant portion of patients with chronic lower back pain are managed with non-surgical options like physical therapy and injections, posing a persistent substitution threat to surgical intervention.
Strategic Opportunities
- Geographic Expansion:There is significant opportunity in developed Asia-Pacific markets like Japan and Australia, where aging demographics and rising incidence of degenerative spine conditions create new demand for durable pain solutions.
- Advanced Material Science:The development of 3D-printed porous implants and surface technologies that mimic bone structure presents an opportunity to accelerate and improve the biological fusion process, offering a key differentiator.
- Direct-to-ASC Sales Models:Creating specialized sales and logistics channels that cater directly to the needs of high-volume Ambulatory Surgical Centers can bypass traditional hospital purchasing committees and capture a growing procedural volume.
Industry Challenges
- Surgical Training Gap:A shortage of surgeons proficient in MIS SI joint fusion techniques necessitates significant investment in comprehensive education and training programs by device manufacturers to ensure safe and effective adoption.
- Clinical Evidence Generation:The long-term, resource-intensive process of conducting robust clinical trials to prove superiority or non-inferiority against alternative treatments is a major operational challenge for market participants.
- System Interoperability:Ensuring seamless integration of proprietary navigation and robotic systems with diverse, pre-existing hospital imaging equipment, such as C-arms and CT scanners, remains a significant technical hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MIS Sacroiliac Joint Fusion Market |
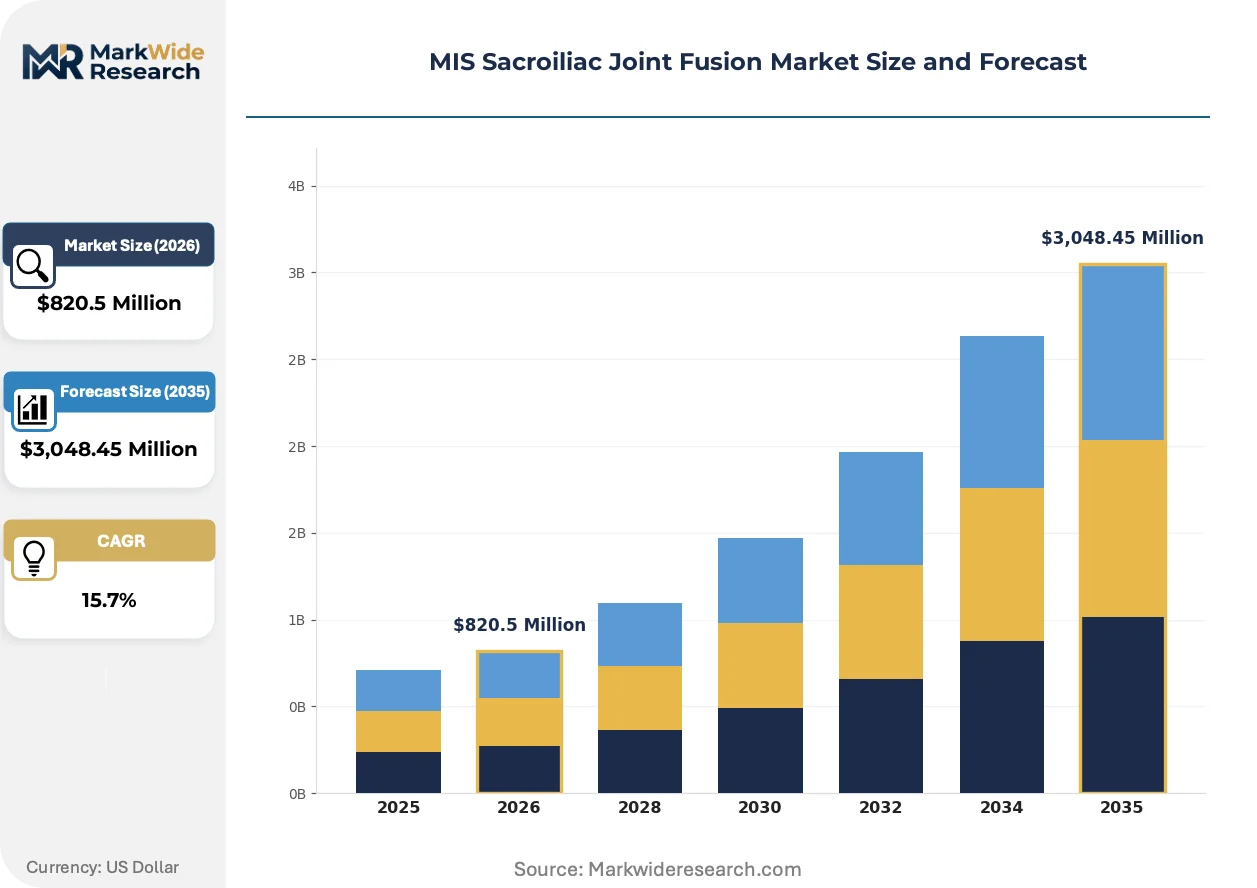
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $3,048.45 Million |
| CAGR (2026 – 2036) | 15.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Screw Systems, Rod Systems, Implant Devices, Surgical Kits Technology: Open Surgery, Minimally Invasive Techniques, Robotic Assistance, Imaging Guidance End User: Hospitals, Ambulatory Surgical Centers, Orthopedic Clinics, Rehabilitation Centers Delivery Mode: In-Person, Telehealth, Outpatient, Home Care |
| Companies Covered | SI-BONE, Medtronic, Globus Medical, Orthofix Medical, Camber Spine Technologies, CoreLink Surgical, Life Spine, PainTEQ, CornerLoc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MIS Sacroiliac Joint Fusion Market Strategic Shifts & Innovations
Digitalization is reshaping the surgical environment for sacroiliac joint fusion, with a focus on integrating robotics, imaging, and data analytics. This convergence is moving the field toward more predictable, evidence-based procedures that can be standardized across different providers and settings.
Robotic-assisted surgical systems provide surgeons with real-time, three-dimensional guidance for precise implant placement. Ambulatory Surgical Centers are increasingly adopting these platforms to enhance procedural reproducibility and reduce reliance on fluoroscopy. This automation is decomposing the traditional dependency on a surgeon's tactile feel and experience alone, standardizing the technical execution of the surgery.
The European Union's Medical Device Regulation (MDR) has elevated the standards for clinical evidence and post-market surveillance. This policy directly increases the cost and complexity of gaining and maintaining market access in Europe. Implant system manufacturers are most affected, now required to invest more heavily in long-term patient follow-up studies to support their CE marking.
Payer and provider purchasing decisions are shifting to prioritize long-term clinical and economic value over initial device cost. This value-based healthcare model disrupts traditional sales cycles that were heavily influenced by individual surgeon preference and relationships. The trend is most visible in the United States, where large hospital networks and insurers negotiate contracts based on data demonstrating improved patient outcomes and lower total cost of care.
MIS Sacroiliac Joint Fusion Market Segmentation
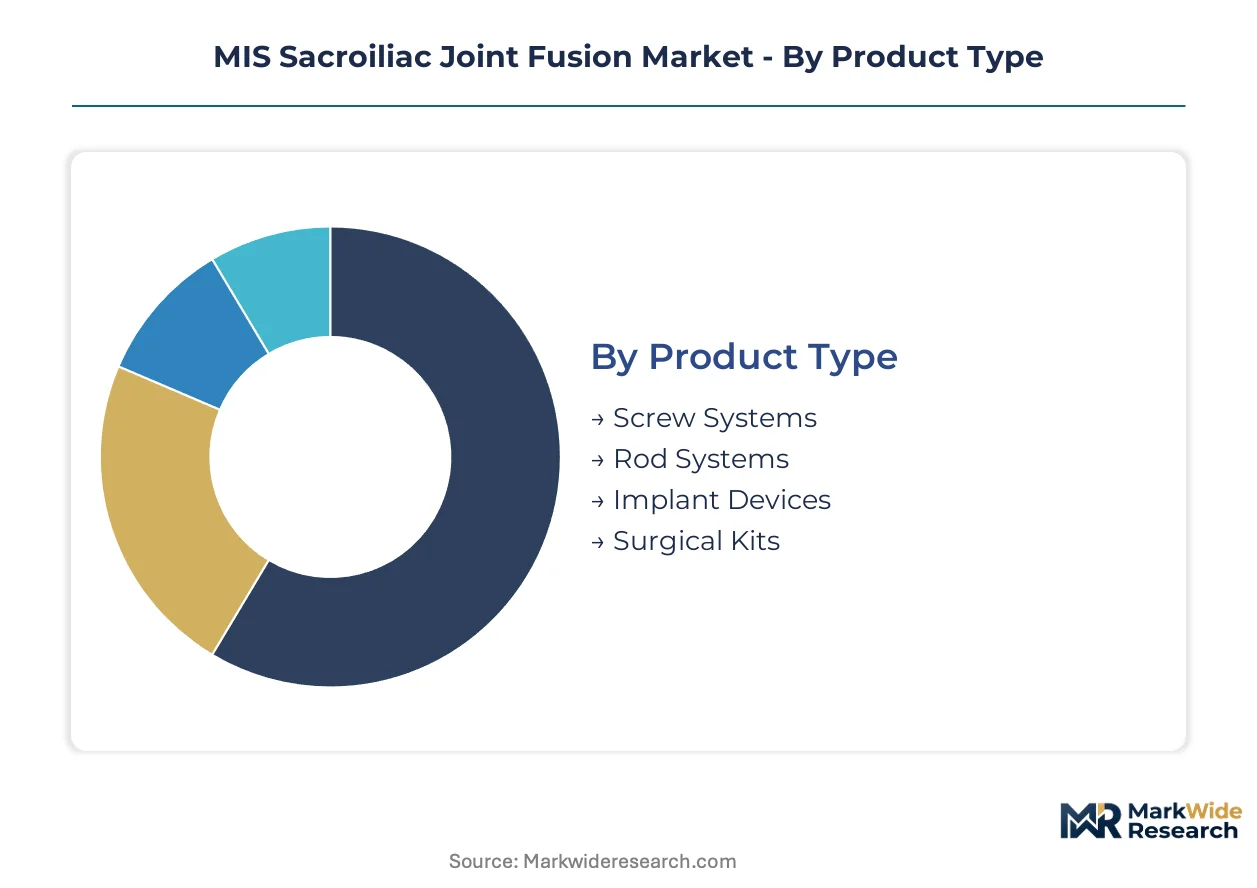
Segmentation within the MIS sacroiliac joint fusion market reveals distinct product preferences and evolving surgical approaches. Understanding these divisions helps device manufacturers tailor their offerings to specific clinical needs and procedural workflows, impacting strategic investment and market penetration efforts.
Product Type:
The MIS sacroiliac joint fusion market faces significant substitution pressure from non-surgical pain management options, influencing product type demand.
- Implant Devices:These are biocompatible structures, often made of titanium, designed to span and stabilize the sacroiliac joint. Demand concentrates in the United States, where favorable reimbursement structures accelerate market penetration for these durable solutions.
- Screw Systems:These systems typically involve cannulated titanium screws inserted across the joint to provide immediate stability and promote fusion. Ambulatory Surgical Centers increasingly adopt these systems due to their procedural efficiency and reduced patient recovery times.
- Rod Systems:These devices utilize a rod and screw construct to provide multi-level stabilization, often employed in more complex spinal fusion cases.
- Surgical Kits:These comprehensive packages include all necessary instruments and implants for a specific MIS SI joint fusion procedure, streamlining surgical preparation.
Implant Devices retains volume leadership; Screw Systems holds the steepest expansion curve.
Technology:
The application of different technologies in MIS sacroiliac joint fusion directly impacts procedural accuracy and surgeon adoption rates.
- Minimally Invasive Techniques:These approaches involve small incisions and specialized instrumentation to reduce tissue disruption and patient recovery time. Robotic assistance technologies are a key technical driver for enhancing precision in these procedures.
- Robotic Assistance:Robotic systems provide real-time, three-dimensional guidance for precise implant placement, enhancing consistency and reducing reliance on fluoroscopy. Ambulatory Surgical Centers are increasingly adopting these platforms to improve procedural reproducibility.
- Open Surgery:This traditional method involves a larger incision to directly visualize the sacroiliac joint, typically reserved for complex cases or when MIS techniques are contraindicated.
- Imaging Guidance:Intraoperative imaging modalities such as fluoroscopy and CT navigation assist surgeons in precise placement of implants during SI joint fusion procedures.
Demand for Minimally Invasive Techniques remains strong, while Robotic Assistance is rapidly gaining traction.
End User:
Patient demographics and provider infrastructure define the customer types utilizing MIS sacroiliac joint fusion services.
- Ambulatory Surgical Centers:These facilities specialize in outpatient surgical procedures, favoring the efficiency and lower overhead of minimally invasive techniques for SI joint fusion. A procedural shift towards these centers is expanding access.
- Hospitals:These institutions serve as traditional hubs for complex surgical interventions, offering comprehensive care for patients undergoing sacroiliac joint fusion. Established spine surgery distribution channels serve these larger facilities.
- Orthopedic Clinics:These specialized clinics focus on musculoskeletal conditions, often referring patients for SI joint fusion or providing pre- and post-operative care.
- Rehabilitation Centers:These centers provide physical therapy and recovery programs for patients post-surgery, supporting functional restoration after SI joint fusion.
The market exhibits a clear shift towards Ambulatory Surgical Centers due to procedural efficiencies, though Hospitals continue to serve a substantial patient base.
Delivery Mode:
The maturity level of care pathways influences the preferred delivery modes for sacroiliac joint fusion services.
- Outpatient:This delivery mode emphasizes performing procedures without an overnight hospital stay, aligning with the efficiency benefits of minimally invasive SI joint fusion. Ambulatory Surgical Centers are primary providers for outpatient fusion.
- In-Person:This traditional delivery method involves direct physical interaction between the patient and healthcare provider for consultation, surgery, and follow-up appointments. This remains the standard for all surgical interventions.
- Telehealth:This mode leverages digital communication technologies for remote consultations and post-operative monitoring, enhancing patient convenience and access in certain phases of care.
- Home Care:Post-surgical care and rehabilitation services delivered in the patient's home environment support recovery and reduce the need for extended facility stays.
Growth in Outpatient is driven by efficiency and cost-effectiveness, while In-Person maintains its foundational role.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for MIS sacroiliac joint fusion procedures varies significantly by region, with some markets demonstrating higher price sensitivity while others prioritize advanced technology and clinical outcomes. Healthcare infrastructure and government policies directly influence the adoption rates of these specialized surgical techniques. Investment in surgeon training and facility upgrades also shapes regional market dynamics.
United States
Favorable reimbursement structures for minimally invasive procedures drive strong demand for SI joint fusion in the United States. The US FDA requires extensive clinical evidence for device approval, influencing R&D timelines for manufacturers. Major medical device clusters in states like California and Massachusetts foster innovation in implant design and robotic assistance technologies.
Germany
Germany exhibits a robust demand for advanced orthopedic solutions due to an aging population and a well-established healthcare system. The European Union's MDR sets stringent requirements for market access, impacting device manufacturers operating in the country. Cities such as Munich and Berlin are centers for medical technology research and development, attracting specialized talent.
Japan
Technological sophistication and a focus on long-term patient outcomes characterize the Japanese market for MIS SI joint fusion. Japan's PMDA rigorously evaluates medical devices for safety and efficacy before market entry. Tokyo and Osaka host significant medical device manufacturing and research facilities, driving local innovation.
Australia
Rising incidence of degenerative spine conditions and increasing patient awareness contribute to market expansion in Australia. The TGA regulates medical devices, requiring comprehensive data for product registration and post-market surveillance. Major metropolitan areas like Sydney and Melbourne serve as key hubs for orthopedic surgical centers.
India
Expanding healthcare infrastructure and a growing middle class are increasing access to advanced surgical treatments in India. The CDSCO oversees medical device approvals, balancing patient access with regulatory oversight. Cities such as Chennai and Hyderabad are emerging as medical tourism destinations, attracting patients for specialized procedures.
MIS Sacroiliac Joint Fusion Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the competitive structure of the MIS sacroiliac joint fusion market. This tiered landscape reflects varying strategic approaches to product development and market penetration. Deep evidence-based specialists and broad-portfolio manufacturers represent distinct archetypes within this market. Strategic partnerships aimed at technology integration and portfolio diversification are common competitive moves.
Within the integrated leader archetype, Medtronic leverages its established spine surgery distribution channels and brand recognition across a wide range of orthopedic solutions. Globus Medical exemplifies an integrated ecosystem provider, differentiating through its combination of imaging, robotics, and implants. SI-BONE occupies a position as a deep evidence specialist, focusing on building extensive clinical data for its specific triangular implant system to secure payer coverage.
| Leading Market Players |
|---|
| SI-BONE |
| Medtronic |
| Globus Medical |
| Orthofix Medical |
| Camber Spine Technologies |
| CoreLink Surgical |
| Life Spine |
| PainTEQ |
| CornerLoc |
| Others |
Cost & Logistics Intelligence
Manufacturing scale economies in biocompatible titanium implants and robotic systems shape both supply concentration and price floors in the MIS sacroiliac joint fusion market. This dynamic influences market entry barriers and competitive intensity for device manufacturers.
Pricing Analysis
Lifetime service and maintenance contracts for robotic platforms drive significant after-sales revenue for device manufacturers. The dominant pricing structure increasingly reflects a value-based healthcare model, prioritizing long-term patient outcomes over initial device cost. Price differentiation stems from robust clinical evidence supporting implant efficacy and the level of robotic integration offered. Pricing pressure stems from large hospital networks and insurers negotiating contracts based on demonstrated cost-effectiveness. Ambulatory Surgical Centers exhibit higher price sensitivity compared to traditional hospitals seeking comprehensive surgical solutions.
Supply Chain Analysis
Logistics costs, including specialized freight for sensitive medical devices, influence the final pricing of MIS SI joint fusion products. Geographic supply concentration for advanced components primarily resides in the United States, Germany, and Japan due to specialized manufacturing capabilities. Raw material dependencies include medical-grade titanium alloys and precision electronic components for robotic systems. Regulatory hurdles from the US FDA and European MDR present a structural supply chain risk, increasing lead times for new product introductions. Distribution runs through established spine surgery channels for larger players and specialized direct-to-ASC sales models for focused providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The MIS sacroiliac joint fusion market requires a robust substitution defense against non-surgical pain management options. Incumbents must navigate the persistent threat of patients opting for conservative treatments before surgical intervention.
For Market Incumbents: Fortify existing market positions by deepening clinical evidence for long-term patient outcomes, particularly against the substitution threat from conservative treatments. Invest strategically in next-generation robotic assistance technologies to enhance procedural accuracy and surgeon adoption. Expand comprehensive surgeon training programs to overcome the surgical training gap and ensure safe, effective device utilization. Control distribution channels by offering integrated solutions that cater to the evolving needs of both hospitals and Ambulatory Surgical Centers.
For New Entrants and Emerging Players: Certification fast-tracks in specific regional markets, such as developed Asia-Pacific nations like Japan and Australia, offer penetrable white-space opportunities. Target Ambulatory Surgical Centers with cost-effective, procedurally efficient screw systems and comprehensive surgical kits. Differentiate through advanced material science, such as 3D-printed porous implants, providing a unique go-to-market angle. Focus on generating specific clinical data for niche applications to secure early reimbursement and market access.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated ecosystem providers offering robotic platforms and long-term service contracts. This market presents long-term viability, driven by aging demographics and the persistent need for durable chronic lower back pain solutions. Acquisition targets should include deep evidence specialists with strong payer coverage or innovative material science companies with proprietary implant designs. The signal to watch is the expansion of reimbursement approvals for novel robotic-assisted techniques, indicating broader market acceptance and growth potential.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Evidence Generation | Robust data secures payer coverage and drives surgeon confidence in new implant systems. |
| Robotic System Integration | Enhances surgical precision and consistency, attracting high-volume Ambulatory Surgical Centers. |
| Direct-to-ASC Sales Model | Captures growing procedural volume by bypassing traditional hospital purchasing committees. |
| Advanced Material R&D | Develops next-generation implants with superior osteointegration properties for improved fusion. |
| Geographic Market Expansion | Accesses new demand in developed Asia-Pacific markets with rising degenerative spine conditions. |
Research Approach
Operator-level perspectives from orthopedic surgeons, hospital administrators, device R&D leads, and regulatory specialists anchored the qualitative base of this analysis. Primary interviews were conducted to gather first-hand insights, which were then validated against extensive secondary data sources. These included US FDA filings, European Union MDR guidelines, peer-reviewed medical journal publications, and relevant industry association reports. This approach ensured a comprehensive understanding, triangulating findings from both bottom-up and top-down perspectives.
Sensitivity analysis framed the quantitative modeling, assessing how various market drivers and restraints influence growth trajectories across the analysis window. The analytical framework incorporated segmentation dimensions including product type, technology, end-user, delivery mode, and geographic region. Compound Annual Growth Rates (CAGRs) were derived through a blend of historical data analysis and expert consensus, projecting future market expansion. Key industry-specific forecast inputs included the incidence of sacroiliac joint dysfunction and the adoption rates of robotic assistance technologies.
The analysis sits within stated boundaries; outcomes outside significant macroeconomic shifts or unforeseen regulatory reversals would require recalibration. Forecasts reflect assumptions regarding technological advancements and healthcare spending patterns. Unforeseen changes in reimbursement policies or rapid competitive disruption represent specific risk factors that could necessitate a revision of projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Medical Manifolds Market
Medical Devices
North America Refractive Surgery Devices Market
Medical Devices
Thyroid Ablation Devices Market
Medical Devices
Global Artificial Organ and Bionic Implants Market
Medical Devices
Smart Pills Technology Market
Medical Devices
Kirschner Wires Market
Medical Devices
LASIK Eye Surgery Devices Market
Medical Devices
Japan Ultrasound Devices Market
Medical Devices
Wireless Neurofeedback Device Market
Medical Devices
3D Medical Imaging Devices Market
Medical Devices
Anesthesia Face Masks Market
Medical Devices
Minimally Invasive Laser Therapy Devices Market
Medical Devices
Neurovascular Microcatheter Market
Medical Devices
Global Nerve Monitoring System Market
Medical Devices
Central Venous Catheter Market
Medical Devices
Sacroiliac Joint Fusion Market