
 Bone Growth Stimulators Market | 2026-2036
Bone Growth Stimulators Market Size, Share, and Industry Trends Forecast 2026-2036
Bone Growth Stimulators Market Analysis
Hospital procurement consolidation in North America is realigning vendor selection criteria toward bundled spine program contracts. Zimmer Biomet leverages its integrated trauma and extremities portfolio to anchor multi-year supply agreements with integrated delivery networks. Orthofix Medical Inc. competes through specialized bone healing portfolios that target ambulatory surgery center channels. Enovis sustains R&D intensity in electrical stimulation platforms to differentiate against implant-centric competitors.
Bone growth stimulators are non-invasive or implantable devices that deliver electrical currents, ultrasound waves, or electromagnetic fields to activate cellular osteogenic pathways, typically operating at frequencies between 20-200 kHz for capacitive coupling and 1.5 MHz for low-intensity pulsed ultrasound systems. Their primary commercial purpose is to accelerate fracture union, reduce non-union rates, and enhance spinal fusion outcomes without secondary surgical harvest of autograft bone. Electrical stimulators occupy the largest revenue pool due to decades of clinical validation and broad payer coverage, while ultrasound stimulators represent the fastest-expanding segment driven by portable device designs and home care migration. Spinal fusion applications command premium pricing corridors, whereas fracture healing serves the highest absolute procedure volume across hospital and orthopedic clinic settings.
The FDA's 510(k) premarket notification framework and the EU Medical Device Regulation's Class IIa classification requirements govern device clearance pathways and clinical evidence standards in their respective markets. Health Canada's Medical Devices Bureau and Japan's PMDA impose additional country-specific quality system audits that shape multinational market entry sequencing. Stakeholders must monitor evolving CMS national coverage determinations for electrical bone growth stimulation, as reimbursement policy shifts will directly alter physician prescribing behavior and capital allocation across device categories.
Market Dynamics
Hospital procurement consolidation across the United States is compressing vendor panels and forcing manufacturers toward bundled spine program contracts that span multiple device categories. Integrated delivery networks now demand multi-year supply agreements with price transparency and outcome guarantees, fundamentally restructuring how bone growth stimulators reach orthopedic surgeons and ambulatory surgery centers.
Growth Catalysts
- Statutory health insurance expansion:Germany's statutory health insurance funds now reimburse non-invasive fracture healing devices for delayed union cases, removing prior authorization barriers that constrained patient access.
- Ultrasound portability advances:Miniaturized low-intensity pulsed ultrasound systems enable home-based treatment protocols, shifting care delivery from hospital settings to patient residences.
- CMS national coverage determinations:Medicare's evolving coverage stance for electrical bone growth stimulation directly expands addressable patient populations for spinal fusion applications.
Market Restraints
- 510(k) clinical evidence requirements:The FDA's substantial equivalence standard demands comparative trial data that extends product development timelines and elevates regulatory compliance costs.
- Autograft substitution persistence:Iliac crest bone graft harvest remains the gold standard for spinal fusion in many academic medical centers, limiting device penetration in high-volume fusion centers.
- Reimbursement rate compression:Medicare's hospital outpatient prospective payment system applies downward pressure on device allowances, squeezing margin structures for manufacturers.
Strategic Opportunities
- Ambulatory surgery center channel expansion:Outpatient spinal fusion migration creates demand for portable stimulation devices that integrate with same-day discharge protocols.
- EU MDR Class IIa pathway optimization:Manufacturers who master the Medical Device Regulation's clinical evaluation requirements gain preferential market access across Germany, France, and Italy.
- Capacitive-ultrasound hybrid platforms:Convergence of electrical and acoustic stimulation modalities promises single-device solutions for complex non-union cases.
Industry Challenges
- Biostatistics talent scarcity:The specialized expertise required for FDA premarket notification submissions and EU clinical evaluation reports commands premium compensation and extends hiring cycles.
- Legacy health record integration:Device connectivity standards vary across Epic, Cerner, and Meditech deployments, complicating remote patient monitoring implementations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bone Growth Stimulators Market |
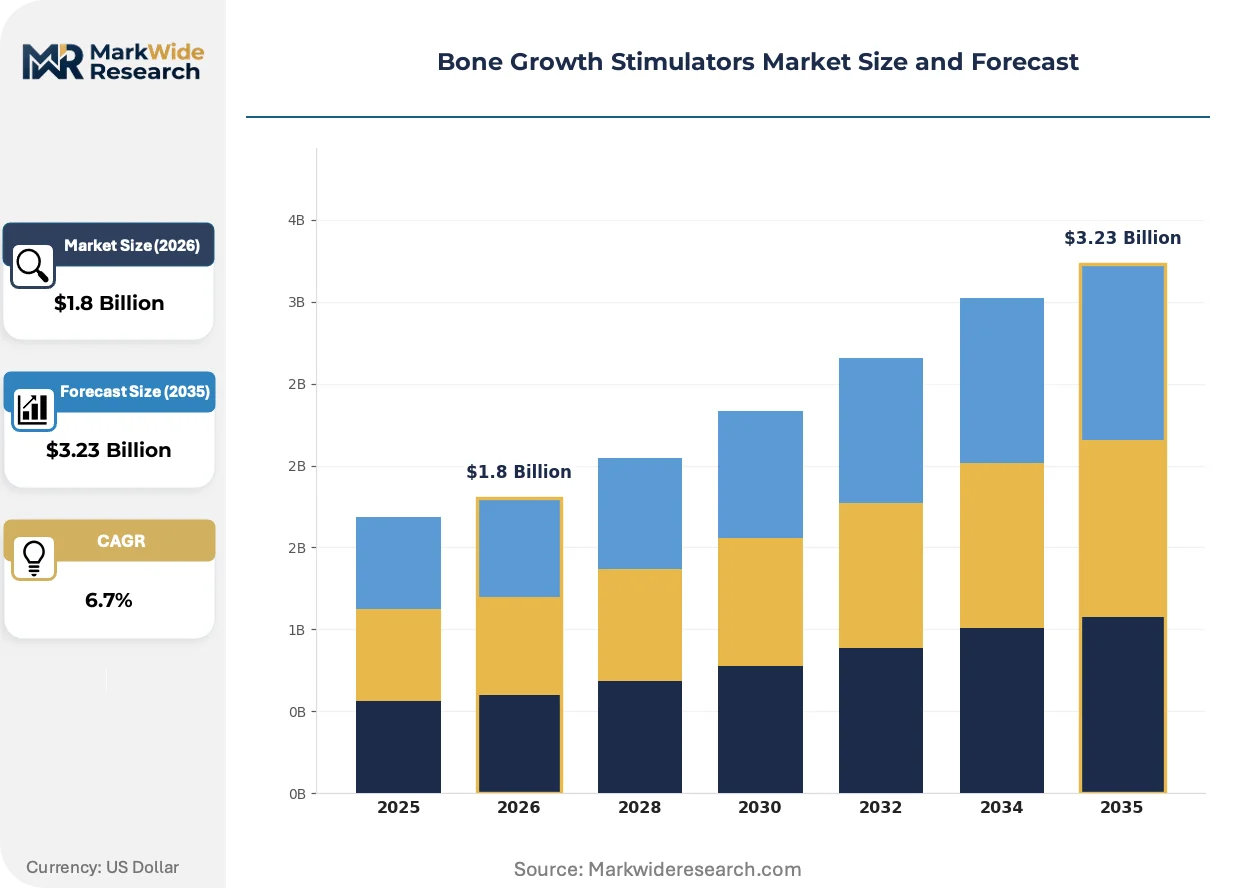
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrical Stimulators, Ultrasound Stimulators, Combined Stimulators, Magnetic Field Devices End User: Hospitals, Orthopedic Clinics, Rehabilitation Centers, Home Care Settings Technology: Electromagnetic Therapy, Low-Intensity Pulsed Ultrasound, Capacitive Coupling, Piezoelectric Devices Application: Fracture Healing, Spinal Fusion, Osteogenesis, Non-Union Treatment |
| Companies Covered | Zimmer Biomet, Orthofix Medical Inc., Enovis, Bioventus, Medtronic plc, Stryker, DePuy Synthes, Arthrex, Inc., ZimVie, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bone Growth Stimulators Market Emerging Trajectories
Digital health integration and miniaturization are actively transforming how bone growth stimulators deliver therapy and capture clinical evidence. These forces are compressing treatment cycles while expanding the settings where fracture healing can occur.
Low-intensity pulsed ultrasound technology is converging with wearable form factors and Bluetooth-enabled patient monitoring platforms. Orthopedic clinics in Germany and the United States are adopting these systems for home-based delayed union protocols. This convergence is compressing the traditional boundary between clinical supervision and self-administered therapy, forcing manufacturers to develop companion apps and cloud-based adherence tracking.
The EU Medical Device Regulation's Class IIa classification requirements are elevating clinical evidence standards for electrical stimulation platforms. Manufacturers must now submit post-market surveillance data and periodic safety update reports that exceed prior Medical Device Directive obligations. Spinal fusion applications face the steepest compliance burden, as notified bodies demand extended follow-up data for implantable adjunct devices.
Integrated delivery networks in the United States are consolidating vendor relationships around bundled spine program contracts that span implants, biologics, and stimulation devices. Hospital procurement committees now evaluate total episode cost rather than device unit price, favoring suppliers who can deliver across multiple product categories. This concentration is most visible in the southeastern United States, where regional health systems have reduced their approved bone growth stimulator vendors from six to two over the past eighteen months.
Bone Growth Stimulators Market Segmentation
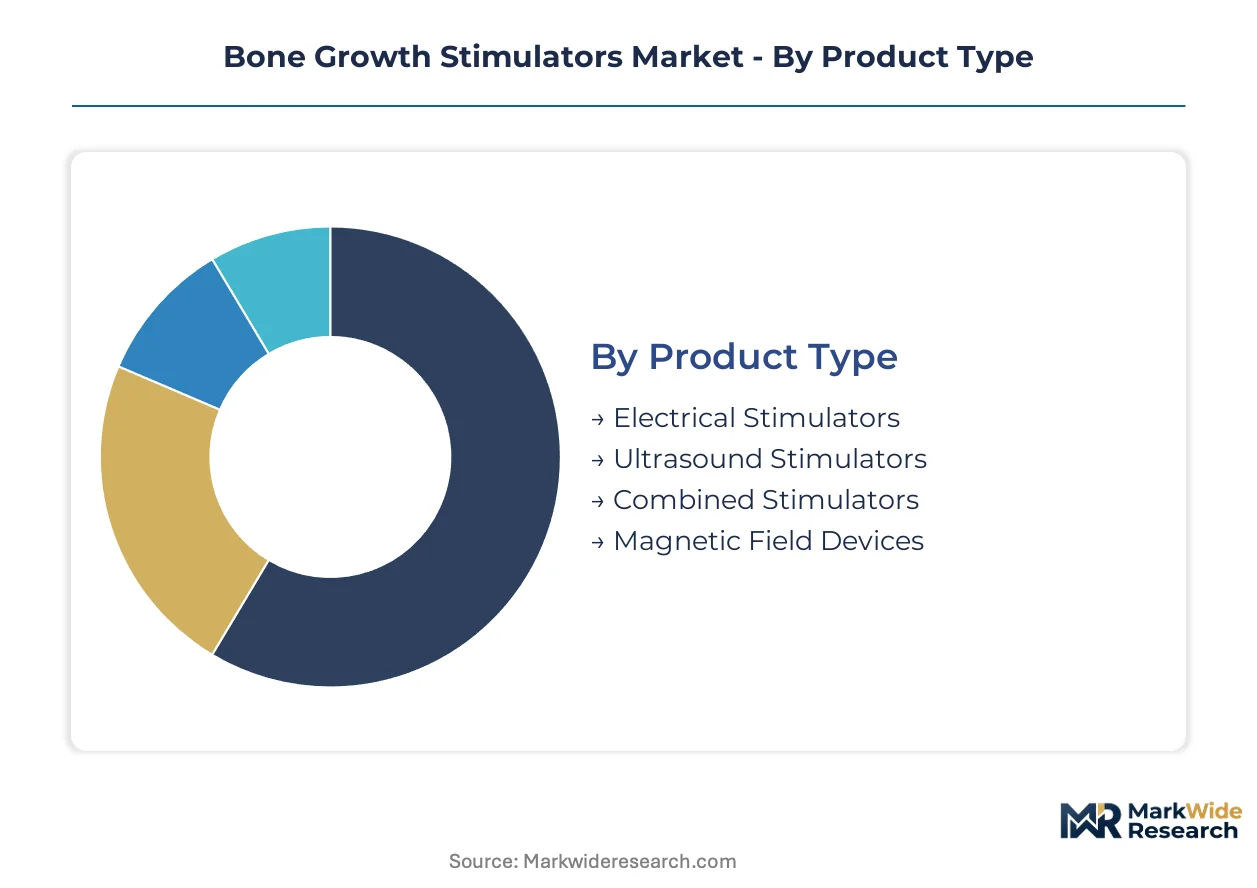
Segmentation in the bone growth stimulators market reveals how technology platforms, clinical settings, and therapeutic applications create distinct commercial battlegrounds. Each dimension carries unique regulatory pathways, reimbursement profiles, and competitive intensity that shape manufacturer resource allocation.
Product Type:
Supply concentration favors established electrical platforms, yet portable ultrasound designs are redrawing manufacturing footprints toward consumer electronics hubs.
- Electrical Stimulators:These devices deliver pulsed electromagnetic fields or direct current through external coils or implanted electrodes, typically operating at 20-200 kHz for capacitive coupling applications. Demand concentrates in United States hospital systems where CMS national coverage determinations support spinal fusion adjunct use, though Medicare's hospital outpatient prospective payment system compresses margin structures.
- Ultrasound Stimulators:Low-intensity pulsed ultrasound systems at 1.5 MHz frequency penetrate bone tissue to activate mechanotransduction pathways in osteoblasts. German statutory health insurance funds now reimburse these devices for delayed union cases, removing prior authorization barriers that previously constrained patient access in Europe's largest orthopedic market.
- Combined Stimulators:Hybrid platforms integrating electrical and acoustic modalities target complex non-union cases with refractory healing biology.
- Magnetic Field Devices:Static and time-varying magnetic field generators serve niche applications in veterinary and emerging market settings.
Today's leader: Electrical Stimulators. Tomorrow's challenger: Ultrasound Stimulators.
End User:
Cost tier stratification separates capital-intensive hospital installations from disposable home care units, with ambulatory surgery centers emerging as the contested middle ground.
- Hospitals:Academic medical centers and community hospitals deploy both invasive and non-invasive systems for inpatient spinal fusion and complex trauma cases. Integrated delivery networks in the southeastern United States have consolidated approved vendors from six to two, compressing procurement leverage toward multi-year bundled contracts.
- Orthopedic Clinics:Outpatient facilities prescribe portable stimulation devices for fracture healing protocols, with Germany and United States clinics adopting Bluetooth-enabled adherence tracking platforms.
- Rehabilitation Centers:Post-acute settings manage device rental programs for extended non-union treatment courses.
- Home Care Settings:Patient-directed therapy delivery demands simplified interfaces and cloud-based remote monitoring integration with Epic and Cerner deployments.
Volume concentrates in Hospitals. Margin expansion tracks toward Home Care Settings.
Technology:
Application specificity determines which physics platform dominates—spinal fusion favors electromagnetic penetration while superficial fractures yield to acoustic energy.
- Electromagnetic Therapy:Pulsed electromagnetic field generators induce microcurrents in bone tissue without direct electrode contact. United States FDA 510(k) clearance pathways favor this modality due to decades of predicate device availability.
- Low-Intensity Pulsed Ultrasound:Mechanical energy transmission at 1.5 MHz accelerates callus formation in delayed unions. Miniaturization trends enable wearable form factors that shift treatment from clinical supervision to patient residences.
- Capacitive Coupling:External electrode pairs create electric fields across fracture gaps for non-invasive stimulation.
- Piezoelectric Devices:Stress-generated electrical potentials from implanted materials serve specialized orthopedic applications.
Clinical validation favors Electromagnetic Therapy. Design innovation concentrates in Low-Intensity Pulsed Ultrasound.
Application:
Procedure volume and pricing power diverge sharply—fracture healing serves the highest case counts while spinal fusion commands premium reimbursement corridors.
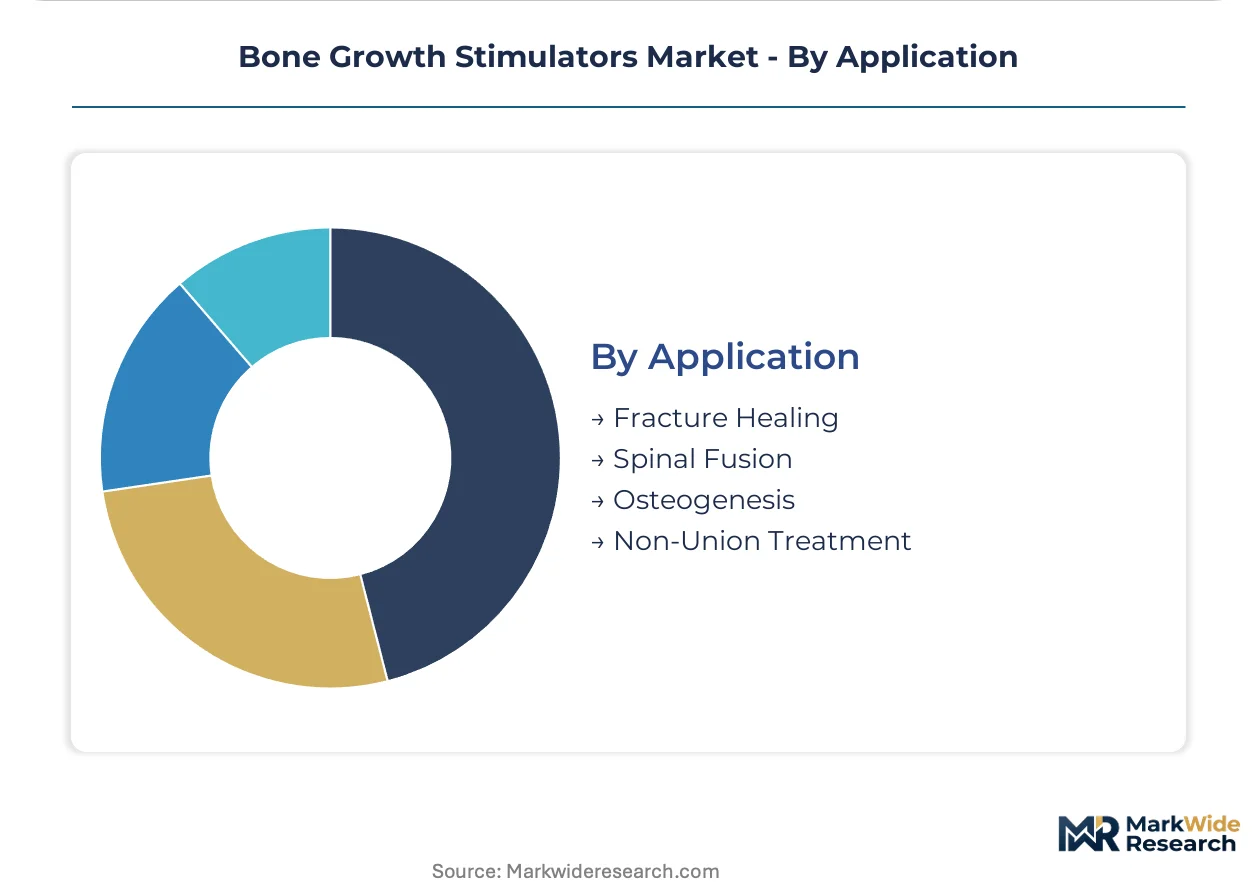
- Fracture Healing:External stimulation devices address delayed unions and fresh fractures across trauma and extremities cases. German reimbursement expansion for non-invasive devices has removed access barriers for statutory health insurance beneficiaries.
- Spinal Fusion:Adjunct stimulation reduces pseudarthrosis rates in lumbar and cervical fusion procedures. United States Medicare coverage determinations directly expand addressable populations, though autograft harvest persistence in academic centers limits device penetration.
- Osteogenesis:Distraction osteogenesis and limb lengthening procedures utilize implantable stimulation systems.
- Non-Union Treatment:Refractory cases combine multiple modalities, driving demand for hybrid platform development.
Revenue concentration anchors in Spinal Fusion. Volume expansion tracks toward Fracture Healing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's statutory health insurance expansion for non-invasive fracture healing devices outpaces United States Medicare coverage evolution, while Japan's PMDA maintains distinct clinical evidence requirements that shape manufacturer market entry sequencing.
United States
Hospital procurement consolidation across integrated delivery networks compresses vendor panels from six to two approved suppliers in southeastern regional health systems. FDA 510(k) premarket notification pathways govern Class II medical device clearances, with CMS national coverage determinations directly expanding addressable populations for spinal fusion applications. Minneapolis and Warsaw, Indiana anchor orthopedic device manufacturing clusters where multi-year bundled supply agreements now dominate hospital contracting.
Germany
Statutory health insurance funds reimburse non-invasive fracture healing devices for delayed union cases, eliminating prior authorization barriers that previously constrained patient access. EU Medical Device Regulation Class IIa classification requirements elevate clinical evidence standards beyond prior Medical Device Directive obligations. Berlin and Munich concentrate orthopedic research institutions where post-market surveillance data submission requirements reshape product development timelines.
Japan
PMDA quality system audits impose country-specific compliance burdens that extend multinational market entry sequencing beyond FDA or EU pathways. METI industrial policy supports domestic medical device innovation through targeted R&D subsidies. Osaka and Tokyo metropolitan areas host specialized orthopedic clinics adopting portable stimulation devices for home-based treatment protocols.
United Kingdom
NHS procurement frameworks emphasize total episode cost evaluation over device unit pricing, favoring suppliers with multi-category portfolios. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR standards while introducing separate conformity assessment requirements. London and Manchester medical centers drive adoption of Bluetooth-enabled adherence tracking platforms for outpatient fracture healing.
China
NMPA medical device registration requirements demand in-country clinical trials for Class II stimulation devices, extending approval timelines versus 510(k) pathways. Provincial healthcare security administration reimbursement catalogs vary across urban centers, creating fragmented market access. Beijing and Shanghai tertiary hospitals pilot digital health integration with electronic medical record systems from domestic technology vendors.
Bone Growth Stimulators Market Vendor Landscape
United States producers anchor one tier; European specialists hold differentiated positions through regulatory mastery and regional reimbursement expertise. Market structure concentrates around integrated trauma and extremities portfolios, with three strategic archetypes dominating: diversified orthopedic conglomerates, specialized bone healing pure-plays, and electrical stimulation technology developers. Competitive moves center on multi-year supply agreement capture and ambulatory surgery center channel expansion.
Among diversified orthopedic conglomerates, Zimmer Biomet and Stryker exemplify scale-driven positioning through integrated delivery network contract anchoring. Orthofix Medical Inc. occupies the specialized pure-play archetype, representing focused portfolio strategies targeting ambulatory channels. Enovis sits within the technology-differentiated tier, embodying R&D intensity in electrical stimulation platforms against implant-centric alternatives.
| Leading Market Players |
|---|
| Zimmer Biomet |
| Orthofix Medical Inc. |
| Enovis |
| Bioventus |
| Medtronic plc |
| Stryker |
| DePuy Synthes |
| Arthrex, Inc. |
| ZimVie |
| Others |
Supply Flow & Price Mechanics
EU MDR post-market surveillance mandates gate qualified supply access and premium-tier pricing corridors for electrical stimulation platforms, compressing vendor eligibility to manufacturers with Berlin and Munich clinical evaluation capabilities while elevating reimbursement-grade device price floors.
Pricing Analysis
Capacity additions in Germany's orthopedic manufacturing corridor are reshaping price floors for ultrasound stimulators as domestic producers exploit statutory health insurance reimbursement expansion. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared spinal fusion systems from CE-marked fracture healing devices and unlicensed emerging market alternatives. Cost compression in the standard tier is intensifying because Medicare's hospital outpatient prospective payment system squeezes device allowances. Academic medical centers exhibit lowest price sensitivity due to outcome guarantee requirements, while ambulatory surgery centers negotiate aggressively on per-unit costs.
Supply Chain Analysis
Piezoelectric ceramic supply rests on Japanese specialty material producers and German precision electronics manufacturers, with final assembly concentrating in Warsaw, Indiana and Minneapolis orthopedic clusters. Key inputs include titanium electrode substrates, biocompatible polymer housings, and Bluetooth-enabled microcontroller units. Single-source vulnerability concentrates in Japanese ceramic resonator supply for ultrasound transducers. Distribution runs through integrated delivery network procurement committees and specialized orthopedic distributor networks serving hospital systems and ambulatory surgery centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: manufacturers capturing Germany's statutory health insurance reimbursement expansion command premium pricing unavailable in Medicare-constrained United States channels.
For Market Incumbents: Anticipate ambulatory surgery center channel consolidation by securing multi-year bundled spine program contracts before procurement panels narrow vendor rosters. Invest in EU MDR Class IIa clinical evaluation capabilities to defend premium positioning against emerging ultrasound competitors. Vertical integration into capacitive coupling electrode production mitigates titanium substrate cost volatility. For New Entrants and Emerging Players: Begin with portable low-intensity pulsed ultrasound systems targeting Germany's home care reimbursement corridor, where statutory health insurance funds removed prior authorization barriers. The most penetrable white space sits in Bluetooth-enabled adherence tracking platforms for orthopedic clinic outpatient protocols. Go-to-market leverage: partner with domestic German distributors possessing statutory health insurance fund relationships. For Investors and Strategic Acquirers: Roll-up economics work for specialized bone healing pure-plays because integrated delivery network procurement consolidation demands multi-category suppliers capable of spanning implants, biologics, and stimulation devices. Long-term viability favors platforms with FDA 510(k) predicate device libraries and EU MDR notified body relationships. Watch CMS national coverage determination revisions for electrical bone growth stimulation as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Optimization | Accelerates Class II device clearance timelines against EU MDR clinical evaluation burdens. |
| Hospital System Partnership | Secures multi-year bundled supply agreements with integrated delivery network procurement committees. |
| Software Companion Development | Enables Bluetooth-enabled adherence tracking integration with Epic and Cerner electronic medical record deployments. |
| Reimbursement Strategy | Captures Germany statutory health insurance expansion for non-invasive fracture healing devices. |
| CE Marking Pathway | Unlocks preferential market access across Germany, France, and Italy under EU MDR Class IIa classification. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining orthopedic surgeon interviews, hospital purchasing committee discussions, GPO contracts manager consultations, and biomedical engineer feedback with secondary validation against FDA 510(k) filings, CMS national coverage determination records, EU MDR notified body documentation, and statutory health insurance reimbursement catalogs. Bottom-up procedure volume estimates and top-down manufacturer revenue triangulation anchored market sizing.
Segment-weighted modeling applied product type, end user channel, technology platform, and application dimensions across the analysis window. CAGRs derived from procedure volume elasticity to demographic aging patterns, reimbursement policy shifts, and ambulatory surgery center migration trends. Forecast inputs incorporated EU MDR compliance cost trajectories and Medicare hospital outpatient prospective payment system revision schedules.
Caveats apply where FDA 510(k) substantial equivalence standard revisions or EU MDR notified body capacity constraints could materially shift the outlook. Forecasts embed assumptions regarding statutory health insurance reimbursement stability and integrated delivery network procurement consolidation velocity. A small set of named triggers—CMS coverage determination reversals, EU MDR transition deadline extensions, and ambulatory surgery center same-day discharge protocol adoption rates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Drug and Gene Delivery Devices Market
Medical Devices
North America Vagus Nerve Stimulation Market
Medical Devices
North America Advanced Drug Delivery Systems Market
Medical Devices
Blood Lancet Market
Medical Devices
Pen Injectors Market
Medical Devices
Internal Nasal Dilators Market
Medical Devices
Global Artificial Limbs Market
Medical Devices
Global Cardiopulmonary Resuscitation Device Market
Medical Devices
Asia-Pacific Wearable Medical Devices Market
Medical Devices
Flow Cytometry Products Market
Medical Devices
Asia-Pacific Electrophysiology Market
Medical Devices
Global Sternal Closure Systems Market
Medical Devices
Respiratory Devices Market
Medical Devices
Allergic Rhinitis Treatment Device Market
Medical Devices
Global Coronary Artery Bypass Graft Devices Market
Medical Devices
3D Printed Prosthetics Market