
 Global Transradial Access Market | 2026-2036
Global Transradial Access Market Size, Share, and Industry Trends Forecast 2026-2036
Global Transradial Access Market Foresight
The gap between premium hydrophilic-coated sheaths and commodity uncoated alternatives is shifting procurement criteria in cath labs worldwide. Terumo Corporation leverages its radial-specific guidewire portfolio to sustain leadership in Japanese and European catheterization networks. Medtronic anchors its position through integrated hemostasis management systems that span closure to post-procedural monitoring. Boston Scientific Corporation differentiates via specialized guiding catheter geometries optimized for complex coronary anatomies.
Transradial access denotes percutaneous entry through the radial artery at the wrist, typically utilizing 5-7 French sheaths and hydrophilic-coated catheters to minimize vascular complications during cardiac or peripheral interventions. Guiding catheters command concentrated margin pools due to technical complexity in torque response and backup support, while hemostatic devices represent the fastest-expanding category as ambulatory protocols shorten observation windows. Diagnostic catheterization procedures retain the largest volume share, though percutaneous coronary intervention applications generate disproportionate value per procedure through device intensity.
FDA 510(k) pathways and EU MDR conformity assessments shape device approval timelines and clinical evidence requirements for transradial platforms. Japan's PMDA and China's NMPA impose distinct biocompatibility and sterilization standards that fragment regulatory strategy for multinational manufacturers. Stakeholders must monitor reimbursement parity between radial and femoral approaches across national health systems, as payment policy determines cath lab conversion economics and device adoption velocity.
Market Dynamics
Radial-first protocols in cardiac catheterization laboratories are compressing femoral access volumes and redistributing device procurement toward wrist-entry specialized portfolios. This procedural pivot alters hemostasis device specifications, catheter torque requirements, and operator training investments across hospital systems.
Growth Catalysts
- EU MDR compliance pathways:Stricter hemostasis device standards under EU MDR are accelerating quality upgrades across European cath lab networks, favoring manufacturers with robust clinical evidence packages.
- Japan's PMDA radial expansion:Cardiac centers in Tokyo and Osaka are scaling transradial programs for complex coronary interventions, creating concentrated demand for specialized guiding catheter geometries.
- Hydrophilic coating technology:Coated sheaths reduce vascular spasm rates and enable same-day discharge protocols, aligning with ambulatory surgery center expansion in the United States.
Market Restraints
- Nitinol and polymer input volatility:Specialized catheter materials face supply concentration from Japanese and German specialty metallurgy suppliers, compressing margins on standard sheath lines.
- Operator learning curve barriers:Transradial technique requires distinct catheter manipulation skills; training program costs and proctoring requirements slow conversion in underpenetrated hospital systems.
- Reimbursement parity gaps:National health systems in several European countries maintain payment equivalence between radial and femoral approaches, removing financial incentive for procedural conversion.
Strategic Opportunities
- China's NMPA pathway acceleration:Domestic cardiac center construction in Shanghai and Beijing creates whitespace for radial-specific device portfolios meeting localized biocompatibility standards.
- Integrated hemostasis-to-monitoring systems:Convergence of closure devices with wireless post-procedural monitoring enables ambulatory protocol expansion beyond traditional observation windows.
- Peripheral artery disease applications:Transradial access for lower limb interventions remains underdeveloped, offering procedural volume expansion outside coronary dominance.
Industry Challenges
- ISO 13485 certification timelines:Quality management system audits for radial-specific device lines extend approval cycles, delaying market entry for portfolio extensions.
- Legacy femoral infrastructure lock-in:Cath labs with sunk investments in femoral-dedicated imaging tables and compression devices face capital reconfiguration costs to support radial-first workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Transradial Access Market |
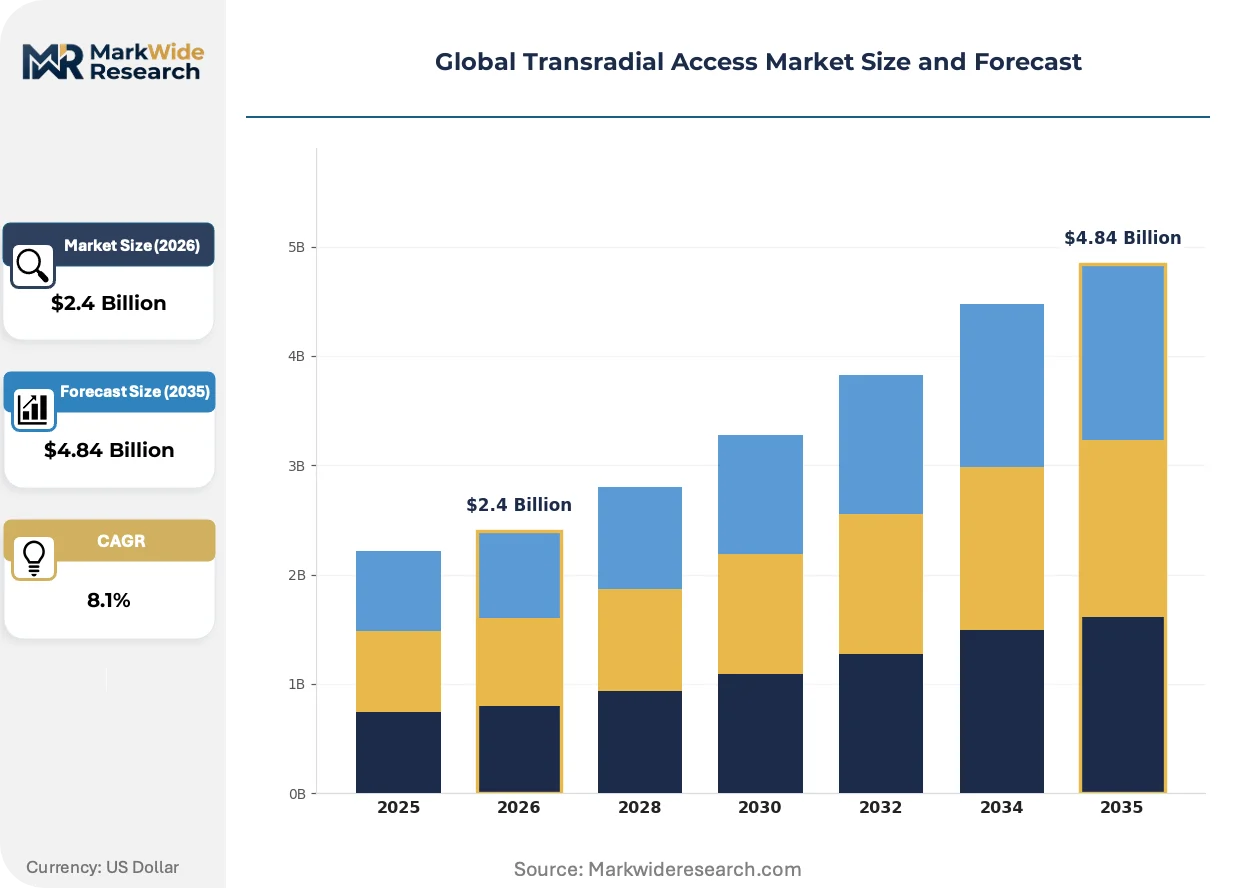
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.84 Billion |
| CAGR (2026 – 2036) | 8.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Diagnostic Catheterization, Percutaneous Coronary Intervention, Peripheral Intervention, Neurovascular Intervention Device Type: Guiding Catheters, Diagnostic Catheters, Sheaths, Guidewires, Hemostatic Devices End User: Cardiac Centers, Specialty Clinics, Ambulatory Surgical Centers, Research Institutes Deployment Setting: Inpatient Facilities, Outpatient Facilities, Hybrid Operating Rooms, Catheterization Laboratories |
| Companies Covered | Terumo Corporation, Medtronic, Boston Scientific Corporation, Becton Dickinson and Company, Edwards Lifesciences Corporation, Teleflex Incorporated, Merit Medical Systems, AngioDynamics, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Transradial Access Market Shifts & Advancements
Device miniaturization and smart hemostasis technologies are converging to enable outpatient cardiac intervention protocols that bypass traditional overnight observation. These shifts compress the care continuum and redistribute value capture across the procedure ecosystem.
Ultrathin hydrophilic-coated sheaths in 4-5 French sizes are overtaking standard 6-7 French configurations in diagnostic catheterization volumes. Ambulatory surgery centers in Florida and Texas are adopting these profiles for same-day discharge protocols. The format reduction is compressing contrast volume requirements and enabling cost-per-procedure declines that accelerate radial-first conversion economics.
FDA 510(k) pathways for hemostasis devices are tightening clinical evidence requirements through enhanced biocompatibility testing mandates. Manufacturers must now submit expanded sterilization validation data and extended follow-up safety profiles. Closure device categories face the steepest documentation burdens, with review timelines extending for novel compression mechanisms.
Hospital procurement departments are consolidating radial access device purchasing under cardiovascular service line contracts rather than discrete product category bids. This bundling compresses vendor count and privileges suppliers with integrated sheath-catheter-closure portfolios. The shift is most pronounced in United States integrated delivery networks and German hospital federations seeking standardization across multi-site cath lab operations.
Global Transradial Access Market Segmentation
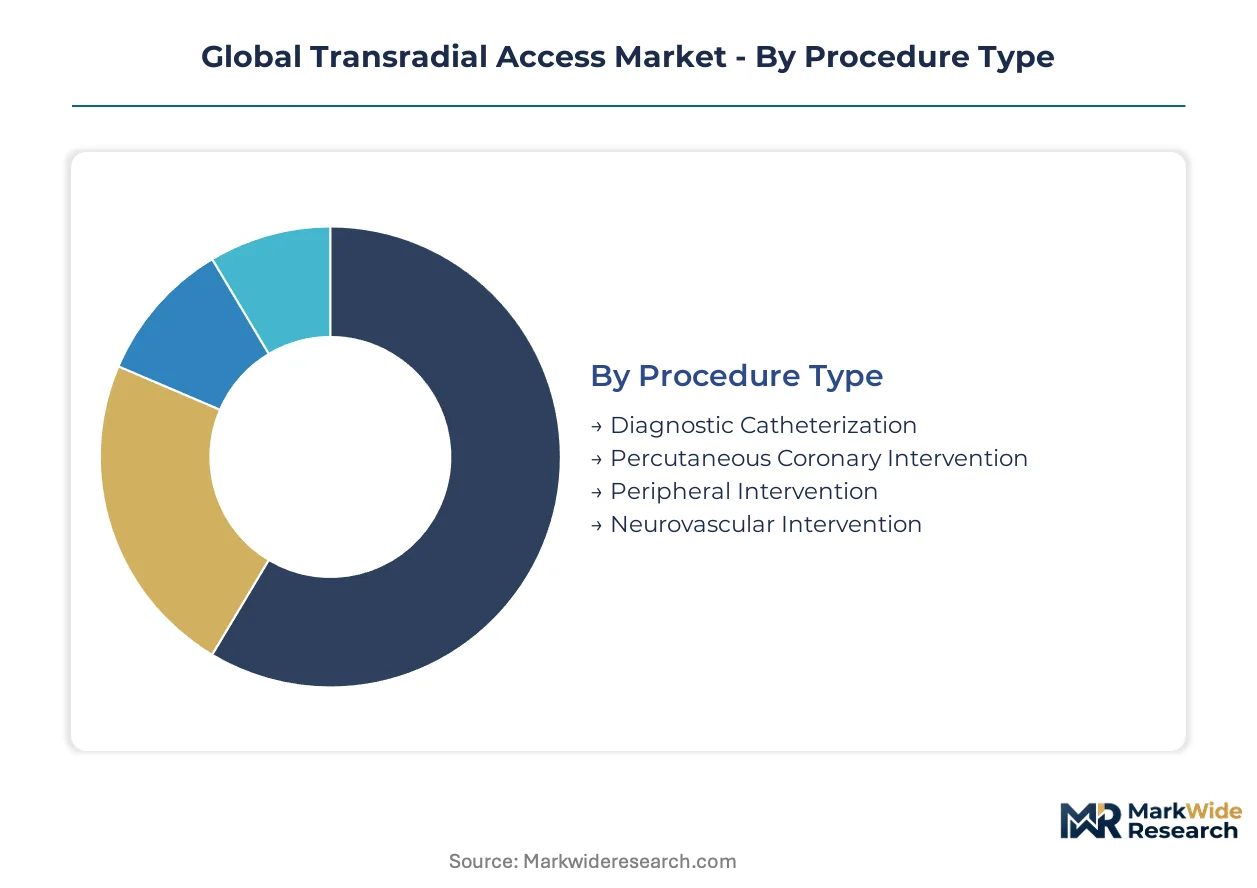
Transradial access markets fragment across procedural complexity, device specification, and care setting economics. Each segmentation axis reveals distinct procurement patterns and technology requirements that reshape vendor positioning and cath lab investment priorities.
Procedure Type:
Technical complexity and reimbursement intensity separate high-volume screening procedures from interventional interventions requiring specialized catheter torque response.
- Diagnostic Catheterization:Standard 5-6 French sheath configurations dominate screening volumes for coronary artery disease assessment. Demand concentrates in United States ambulatory surgery centers where same-day discharge protocols maximize facility throughput.
- Percutaneous Coronary Intervention:Complex lesion crossing requires 6-7 French guiding catheter backup support and hydrophilic-coated sheath systems. German and Japanese cardiac centers drive specification intensity through radial-first conversion programs for acute coronary syndrome cases.
- Peripheral Intervention:Lower limb arterial access via radial entry remains technically underdeveloped with limited operator training infrastructure.
- Neurovascular Intervention:Cerebral catheterization demands ultra-low profile 4-5 French systems with enhanced trackability through tortuous anatomy.
Mature deployment sits with Diagnostic Catheterization. Newer deployment is concentrated in Neurovascular Intervention.
Device Type:
Margin concentration follows technical differentiation, with torque-responsive components capturing premium positioning against commodity sheath lines.
- Guiding Catheters:Specialized backup support geometries and torque transmission characteristics command concentrated margin pools. Japanese catheterization networks in Tokyo and Osaka prioritize these specifications for complex coronary anatomies.
- Hemostatic Devices:Compression bands, vascular closure systems, and wireless monitoring convergence enable ambulatory protocol expansion. United States integrated delivery networks are consolidating procurement under cardiovascular service line contracts that favor integrated closure-to-monitoring portfolios.
- Sheaths:Hydrophilic-coated variants in 4-7 French sizes enable vascular spasm reduction and same-day discharge economics.
- Diagnostic Catheters:Standard torque response specifications serve high-volume screening applications with compressed price positioning.
- Guidewires:Radial-specific tip load and lubricious coating configurations facilitate lesion crossing in tortuous subclavian anatomy.
Volume leadership rests with Sheaths. Value capture is climbing the fastest in Hemostatic Devices.
End User:
Capital intensity and procedure mix determine device specification requirements across institutional settings.
- Cardiac Centers:High-volume coronary intervention programs in Germany and Japan drive radial-first protocol standardization and integrated device portfolio adoption.
- Ambulatory Surgical Centers:Florida and Texas facilities are compressing observation windows through 4-5 French sheath miniaturization and wireless hemostasis monitoring.
- Specialty Clinics:Peripheral diagnostic volumes concentrate in independent settings with limited interventional backup capability.
- Research Institutes:Clinical trial infrastructure supports novel device validation under FDA 510(k) and EU MDR pathways.
Procurement standardization is most advanced in Cardiac Centers. Specification experimentation is concentrated in Ambulatory Surgical Centers.
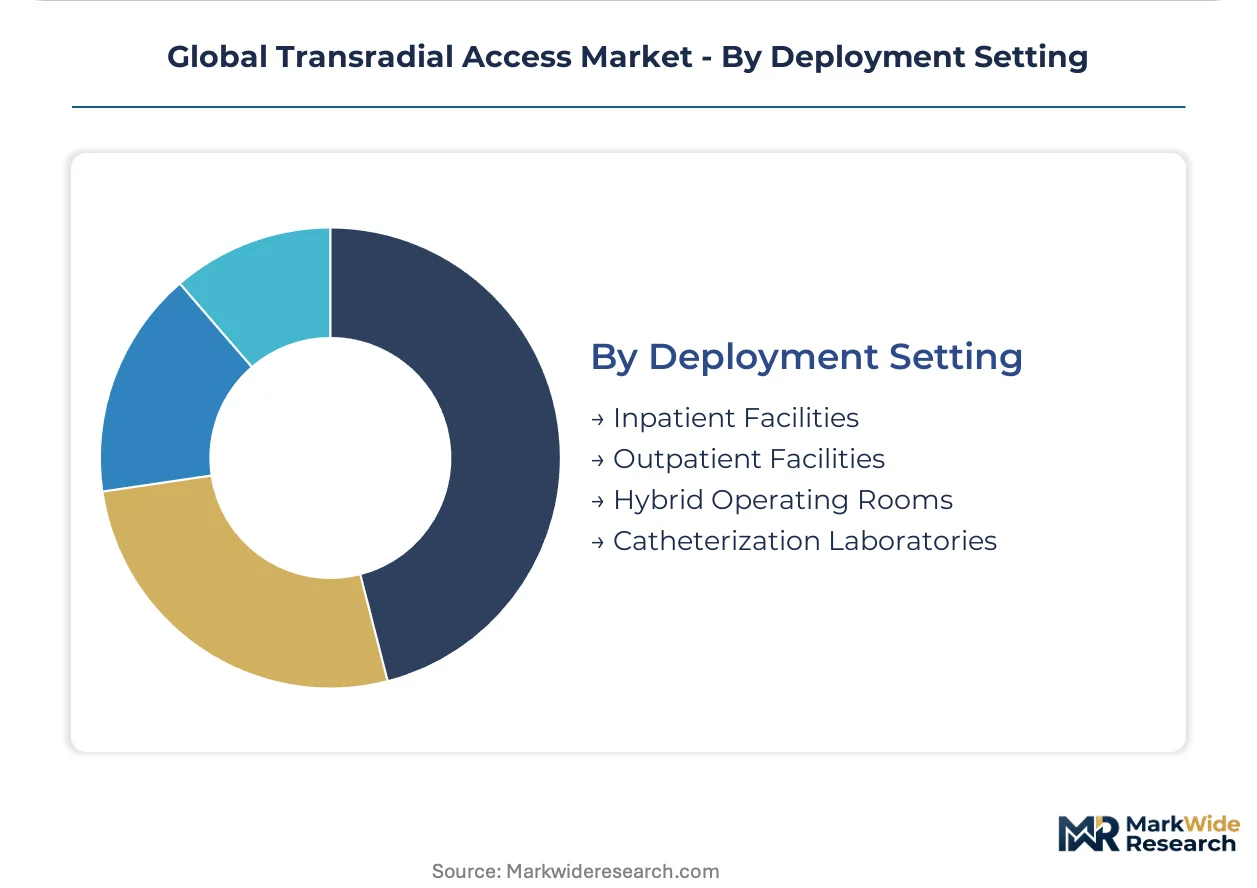
Deployment Setting:
Physical infrastructure constraints and reimbursement classification reshape device format requirements across care locations.
- Catheterization Laboratories:Dedicated imaging tables and radiation shielding configurations in United States hospital systems support high-complexity intervention volumes with full device portfolio utilization.
- Outpatient Facilities:Compressed space footprints and rapid turnover requirements favor miniaturized sheath formats and disposable hemostasis systems.
- Inpatient Facilities:Overnight observation capability supports traditional 6-7 French configurations without same-day discharge pressure.
- Hybrid Operating Rooms:Surgical backup integration enables complex peripheral and structural heart interventions via radial access.
Volume concentration remains in Catheterization Laboratories. Fastest format innovation is occurring in Outpatient Facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo and Osaka cardiac centers anchor transradial adoption intensity across Japan's catheterization networks, with specialized guiding catheter specifications driving procurement patterns. German cath lab federations in Munich and Berlin standardize radial-first protocols through integrated device contracts. United States ambulatory surgery centers in Florida and Texas compress observation windows via miniaturized sheath formats.
United States
FDA 510(k) pathways for hemostasis devices tighten clinical evidence requirements through enhanced biocompatibility testing mandates. Ambulatory surgery centers in Florida and Texas adopt 4-5 French sheath configurations for same-day discharge protocols. Integrated delivery networks consolidate radial access purchasing under cardiovascular service line contracts.
Germany
EU MDR compliance pathways accelerate quality upgrades across European cath lab networks through stricter hemostasis device standards. Cardiac centers in Munich and Berlin drive radial-first protocol standardization for complex coronary interventions. Hospital federations seek standardization across multi-site cath lab operations.
Japan
PMDA radial expansion programs scale transradial access for complex coronary interventions in Tokyo and Osaka cardiac centers. Specialized guiding catheter geometries command concentrated demand for tortuous subclavian anatomy navigation. Domestic catheterization networks prioritize torque-responsive backup support specifications.
China
NMPA pathway acceleration creates whitespace for radial-specific device portfolios meeting localized biocompatibility standards. Domestic cardiac center construction in Shanghai and Beijing concentrates demand for hydrophilic-coated sheath systems. National health system reimbursement parity influences cath lab conversion economics.
United Kingdom
NHS procurement frameworks evaluate radial versus femoral reimbursement equivalence across cardiac catheterization programs. London and Manchester hospital trusts assess radial-first workflow reconfiguration against legacy femoral infrastructure investments. Clinical commissioning groups monitor ambulatory protocol expansion for cost-per-procedure optimization.
Global Transradial Access Market Competitive Landscape
Premium-margin players sit above commodity-margin players across coating technology and hemostasis integration capabilities. The vendor base stratifies into three tiers: integrated portfolio suppliers capturing cardiovascular service line contracts, specialized guidewire and catheter manufacturers, and regional sheath producers competing on price. Strategic archetypes include full-stack integrators, radial-specific technology specialists, and ambulatory-focused miniaturization leaders. Dominant competitive moves span M&A for hemostasis-to-monitoring convergence and capacity expansion for hydrophilic coating production.
Among Japan-based medical technology fabricators, Terumo Corporation exemplifies the radial-specific specialist archetype through its concentrated presence in domestic and European catheterization networks. Medtronic and Boston Scientific Corporation represent the integrated portfolio tier, with the former anchoring hemostasis management system positioning and the latter occupying specialized guiding catheter geometry development. These three entities collectively illustrate the competitive tension between regional specialization and global scale in transradial device procurement.
| Leading Market Players |
|---|
| Terumo Corporation |
| Medtronic |
| Boston Scientific Corporation |
| Becton Dickinson and Company |
| Edwards Lifesciences Corporation |
| Teleflex Incorporated |
| Merit Medical Systems |
| AngioDynamics |
| Abbott Laboratories |
| Others |
Supply & Pricing Matrix
Captive coating production in Japan and Germany anchors both supply security and premium pricing power for hydrophilic sheath manufacturers serving radial-first cath lab networks. This backward integration into polymer formulation and surface treatment technology insulates integrated portfolio suppliers from commodity price volatility while enabling value capture through differentiated spasm-reduction performance.
Pricing Analysis
Throughput-based pricing tied to same-day discharge protocol economics dominates ambulatory surgery center procurement in Florida and Texas. Three-tier pricing structure across premium hydrophilic-coated, standard uncoated, and economy bulk configurations separates vendors based on EU MDR certification tier and wireless hemostasis integration depth. Cost compression in standard sheath lines is intensifying because nitinol input volatility from Japanese specialty metallurgy suppliers compresses margins. Price sensitivity concentrates in United States integrated delivery networks consolidating under cardiovascular service line contracts, while German hospital federations prioritize torque-responsive guiding catheter specifications over unit cost.
Supply Chain Analysis
Workforce availability constraints in Japanese precision polymer processing and German nitinol wire drawing limit capacity expansion for hydrophilic coating and torque-transmission components. Manufacturing concentrates in Japan, Germany, and United States medical device corridors, with specialized catheter extrusion drawing from Japanese polymer formulation, German metallurgy, and domestic sterilization validation infrastructure. Single-source vulnerability in hydrophilic polymer resin supply creates concentration risk for coating-dependent sheath lines. Distribution runs through hospital procurement committees and GPO contracts rather than distributor networks, privileging direct manufacturer relationships with cardiac center supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
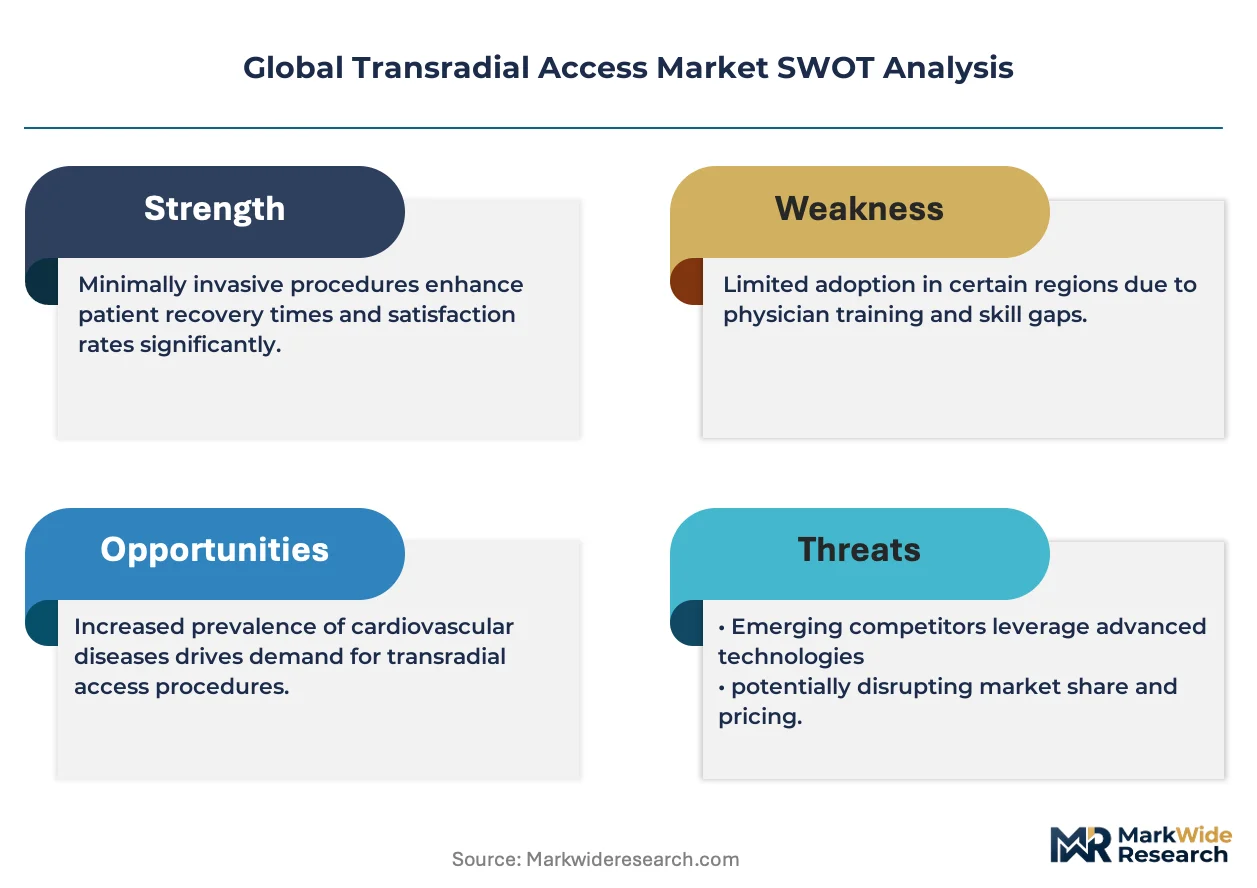
This market reads as a cost-of-compliance story where EU MDR clinical evidence requirements and FDA 510(k) biocompatibility testing mandates erect barrier-to-entry moats favoring manufacturers with pre-existing regulatory dossiers and quality management system certifications.
For Market Incumbents: Deploy integrated hemostasis-to-monitoring portfolio bundling to capture cardiovascular service line contracts and displace point-product competitors. Consolidate hydrophilic coating capacity in Japan and Germany to secure nitinol and polymer input access against emerging Asian suppliers. Counter ambulatory surgery center price compression through wireless post-procedural monitoring value-adds that justify premium positioning. For New Entrants and Emerging Players: Launch via peripheral artery disease radial access applications where operator training infrastructure remains underdeveloped and incumbent portfolios lack specialized configurations. Target China's NMPA pathway acceleration whitespace in Shanghai and Beijing cardiac center construction, emphasizing localized biocompatibility validation. Pursue ambulatory-focused miniaturization leadership in 4-5 French sheath formats for same-day discharge protocol adoption. For Investors and Strategic Acquirers: Exit pathways concentrate in hemostasis-to-monitoring convergence acquisitions by integrated device manufacturers seeking ambulatory protocol expansion capabilities. Long-term viability hinges on regulatory dossier depth and coating technology differentiation rather than commodity manufacturing scale. Watch reimbursement parity shifts in European national health systems as the inflection signal for cath lab conversion velocity and device adoption acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Clinical Evidence Investment | Accelerates quality upgrades across German cath lab networks through stricter hemostasis device standards. |
| Hydrophilic Coating Capacity Expansion | Secures nitinol and polymer input access in Japan and Germany against supply concentration risks. |
| Wireless Hemostasis Monitoring Integration | Enables ambulatory protocol expansion beyond traditional observation windows in United States facilities. |
| China NMPA Localization Strategy | Captures whitespace in Shanghai and Beijing cardiac center construction with biocompatibility-compliant portfolios. |
| Peripheral Intervention Portfolio Development | Addresses technically underdeveloped lower limb arterial access applications outside coronary dominance. |
Research Methodology
FDA 510(k) clearance databases, EU MDR conformity assessment records, and hospital procurement contract filings formed the secondary backbone for device adoption and regulatory pathway analysis. Primary interviews with cath lab directors, biomedical engineers, GPO contracts managers, and interventional cardiologists validated technology substitution patterns and training program investment priorities. Bottom-up procedure volume modeling across diagnostic catheterization, percutaneous coronary intervention, and peripheral intervention segments combined with top-down market sizing triangulation.
Bottom-up modeling anchored volume projections across procedure type, device specification, and care setting dimensions throughout the forecast period. Segmentation analysis tracked sheath French size adoption, hydrophilic coating penetration, and hemostasis device category growth across cardiac centers, ambulatory surgical centers, and outpatient facilities. CAGRs derived from procedure volume intensity, reimbursement parity evolution, and cath lab infrastructure investment cycles. Forecast inputs incorporated operator training program expansion rates and ambulatory protocol regulatory clearance timelines.
Reimbursement parity reversals, nitinol supply disruptions, and EU MDR audit timeline extensions are the dominant revision risks to transradial access device adoption trajectories. Forecasts reflect assumptions regarding radial-first protocol conversion economics and ambulatory surgery center regulatory classification stability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Ambulatory Polysomnography (Psg) Systems Market
Medical Devices
Germany Contraceptive Devices Market
Medical Devices
Bare Metal Stents Market
Medical Devices
Brazil Ultrasound Devices Market
Medical Devices
Low Vision Aids Market
Medical Devices
Global Adult and Pediatric Hemoconcentrators Market
Medical Devices
Soft Contact Lenses Market
Medical Devices
North America Vagus Nerve Stimulation Market
Medical Devices
Digital Impression System Market
Medical Devices
TMJ Implants Market
Medical Devices
Transcranial Magnetic Stimulator for Depression Requisition Market
Medical Devices
Membrane Oxygenators Market
Medical Devices
China Aesthetic Devices Market
Medical Devices
Cardiac Implants Market
Medical Devices
Global Operating Microscopes Market
Medical Devices
Global Dermatome Device Market