
 Platelet Concentration Systems Market | 2026-2036
Platelet Concentration Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Platelet Concentration Systems Market Outlook
Glass blood-collection tubes is restructuring cost structures across platelet concentration workflows as polymer alternatives gain traction in high-throughput settings. Stryker Corporation leverages its orthopedic implant franchise to bundle platelet concentration hardware with surgical navigation platforms. Zimmer Biomet Holdings Inc. anchors its position through dedicated sales channels into ambulatory surgery centers. Terumo Corporation differentiates via integrated blood management systems that span collection through reinfusion.
Platelet concentration systems are medical devices that isolate and concentrate platelets from autologous or donor blood through centrifugal force, membrane filtration, or combined mechanical processing, typically achieving platelet yields of three to ten times baseline concentration for therapeutic reinfusion. These systems serve primarily to produce platelet-rich plasma or platelet-poor plasma for clinical applications in wound healing, bone graft augmentation, and soft-tissue repair. Automated systems command premium positioning due to closed-loop processing that reduces contamination risk and operator variability, while manual systems retain share in cost-sensitive research environments where protocol flexibility outweighs throughput needs. Orthopedic surgery represents the fastest-growing application segment as sports medicine practices expand outpatient biologic augmentation procedures.
The FDA regulates platelet concentration systems as Class II medical devices requiring 510(k) premarket notification, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for devices handling blood-derived therapeutic substances. ISO 13485 quality management certification has become a baseline requirement for vendor qualification by hospital procurement committees. Stakeholders must monitor evolving reimbursement codes for autologous blood product preparation, as coverage determinations by CMS and parallel bodies directly influence capital equipment purchasing cycles.
Market Dynamics
FDA's evolving guidance on human cells, tissues, and cellular and tissue-based products is compressing device classification timelines while elevating clinical validation burdens for platelet concentration system manufacturers.
Growth Catalysts
- Sports medicine expansion:Orthopedic surgery suites in hospital settings are standardizing autologous blood processing protocols for outpatient biologic augmentation procedures.
- EU Medical Device Regulation:Stricter clinical evidence requirements for blood-derived therapeutic substances are accelerating ISO 13485 certification adoption across vendor qualification processes.
- Closed-loop automation:Automated platelet concentration systems are displacing manual protocols in academic medical centers due to reduced contamination risk and operator variability.
Market Restraints
- Polymer input volatility:Glass blood-collection tube substitution with polymer alternatives exposes manufacturers to petrochemical price swings and supply chain reconfiguration costs.
- Reimbursement uncertainty:CMS coverage determinations for autologous blood product preparation create capital equipment purchasing cycle freezes across ambulatory surgical centers.
- Centrifuge technical ceiling:Mechanical processing yield plateaus at ten times baseline concentration limit membrane filtration approaches for higher throughput demands.
Strategic Opportunities
- Japan biologics corridor:PMDA's streamlined regenerative medicine approval pathways are opening dedicated sales channel development for platelet-rich plasma preparation hardware.
- Wound healing pivot:Soft-tissue repair applications outside orthopedics represent underpenetrated clinical segments with expanding outpatient procedure volumes.
- Integrated blood management:Convergence of collection-through-reinfusion systems with surgical navigation platforms enables bundled hardware-software contracting models.
Industry Challenges
- 510(k) submission expertise:FDA Class II medical device notification requirements demand specialized regulatory affairs talent scarce in mid-cap device manufacturers.
- Legacy system integration:Hospital information system connectivity for automated platelet concentration workflows requires costly interoperability certification and IT infrastructure retrofitting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Platelet Concentration Systems Market |
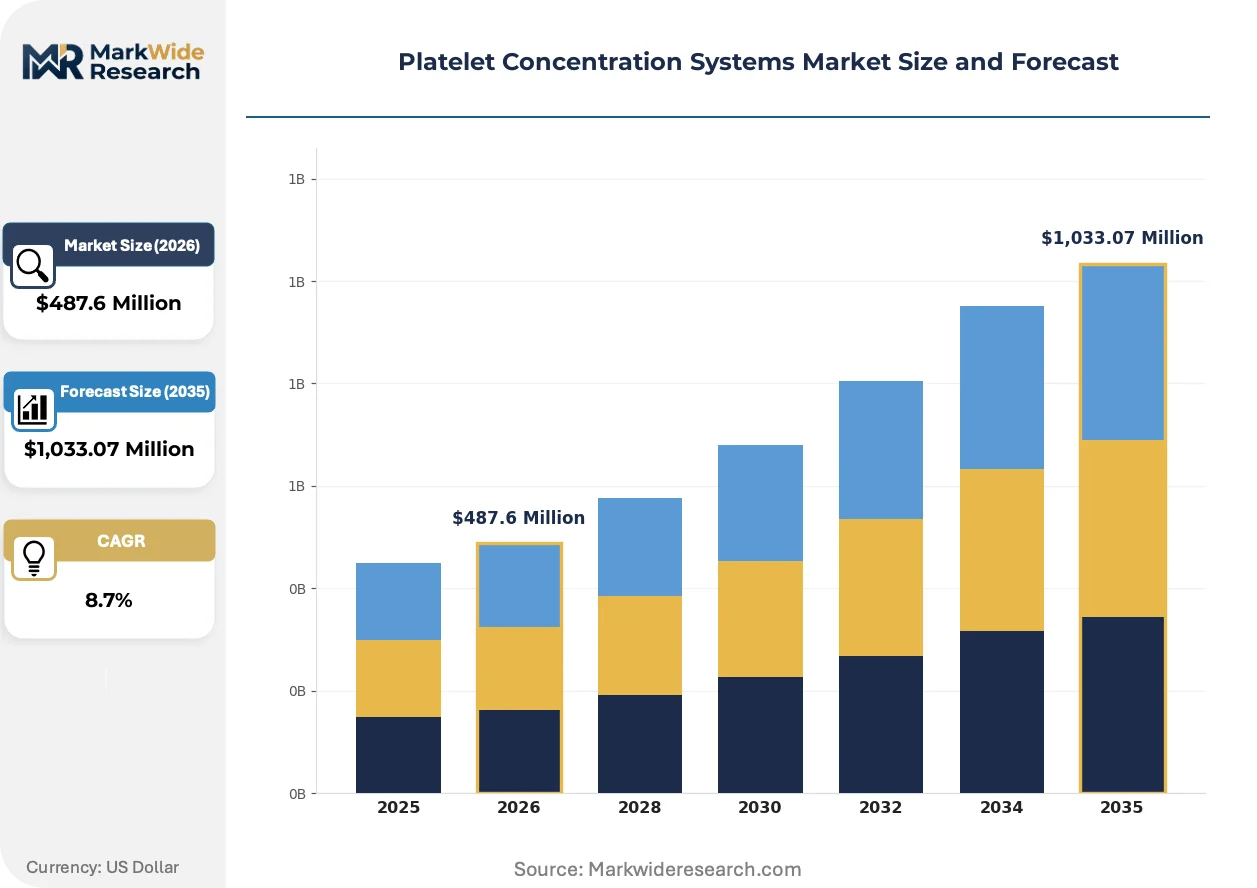
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centrifugation Systems, Filtration Systems, Automated Systems, Manual Systems End User: Hospitals, Blood Banks, Research Institutes, Academic Institutions Technology: Blood Component Separation, Platelet Collection, Activation Method, Storage Solutions Application: Transfusion Medicine, Orthopedic Surgery, Cardiovascular Procedures, Regenerative Medicine |
| Companies Covered | Arthrex, Inc., Stryker Corporation, Zimmer Biomet Holdings Inc., Terumo Corporation, Johnson & Johnson, EmCyte Corporation, Harvest Technologies Corp., Haemonetics Corporation, Arteriocyte Medical Systems, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Platelet Concentration Systems Market Strategic Shifts
Platelet concentration workflows are absorbing membrane filtration advances alongside centrifugal force refinement, reshaping yield optimization and contamination control across processing architectures.
Membrane filtration technology is absorbing secondary separation duties from pure centrifugation systems in high-throughput hospital laboratories. Academic medical centers in the United States are adopting hybrid mechanical processing units at accelerated replacement cycles. This convergence is absorbing cost premiums from standalone automated systems while compressing manual protocol retention in research environments.
EU Medical Device Regulation clinical evidence requirements are forcing blood-derived therapeutic substance handlers into extended validation timelines. Manufacturers serving European orthopedic surgery centers are restructuring quality management systems to meet notified body scrutiny levels. Class IIa device reclassifications are absorbing compliance resources most intensely among mid-scale automation vendors without captive clinical trial infrastructure.
Ambulatory surgical center procurement committees are consolidating vendor relationships around integrated blood management system suppliers. Single-source contracting for collection-through-reinfusion capabilities is displacing fragmented device purchasing across sports medicine practices. This concentration is absorbing price negotiation leverage into group purchasing organizations most visible in United States metropolitan hospital networks.
Platelet Concentration Systems Market Segmentation
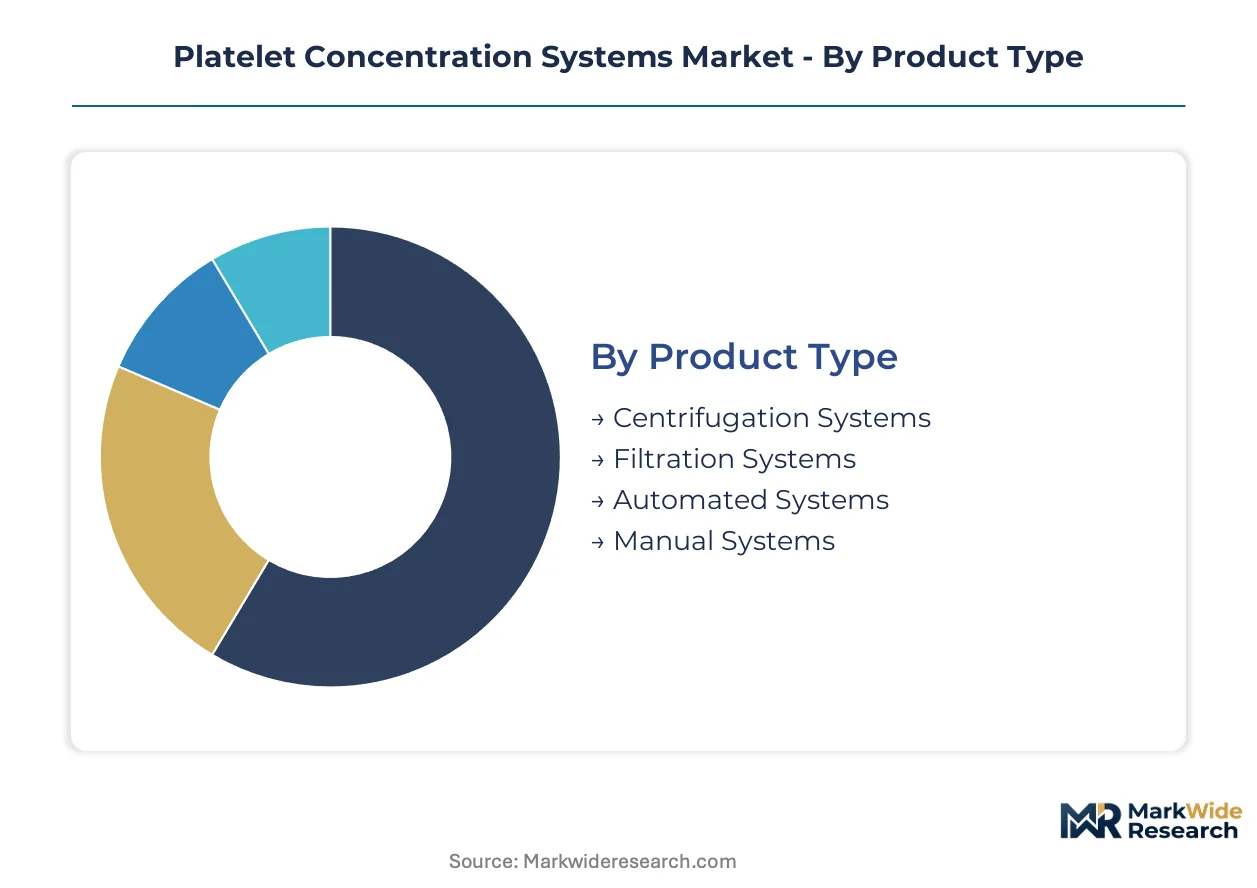
Segmentation in platelet concentration systems reveals how processing architecture, clinical setting, and therapeutic intent reshape procurement priorities across healthcare delivery networks. Manufacturers calibrate feature sets against the tension between throughput demands in blood banks and precision requirements in orthopedic suites.
Product Type:
Centrifugal force remains the dominant separation physics, though membrane filtration is absorbing secondary duties in high-volume settings.
- Centrifugation Systems:These devices exploit density differentials through controlled rotational force, typically achieving three-to-ten-fold platelet concentration in closed chambers. Demand concentrates in United States academic medical centers where standardization protocols favor mechanical reliability over protocol flexibility. FDA 510(k) clearance timelines for new centrifuge designs compress competitive refresh cycles.
- Automated Systems:Closed-loop architectures integrate collection, processing, and reinfusion in single-device workflows, eliminating open-handling contamination vectors. Ambulatory surgical centers in metropolitan United States hospital networks prioritize these units for outpatient orthopedic procedures where operator variability reduction justifies capital premiums.
- Filtration Systems:Membrane-based separation captures platelets through pore-size selectivity without rotational mechanics, enabling gentler processing of fragile cellular components.
- Manual Systems:Open-protocol designs retain share in research environments where investigator-driven protocol modification outweighs throughput efficiency.
Mature deployment sits with Centrifugation Systems. Newer deployment is concentrated in Automated Systems.
End User:
Procurement authority fragments across capital equipment committees, blood service operators, and principal investigator laboratories with divergent validation requirements.
- Hospitals:Integrated delivery networks command the largest installed base, with orthopedic surgery suites driving replacement demand for hybrid processing units. United States hospital procurement committees bundle platelet concentration hardware with surgical navigation platforms under single-source contracts.
- Blood Banks:High-throughput collection centers prioritize membrane filtration integration for donor platelet apheresis, where yield optimization directly impacts inventory economics. EU blood establishments face extended MDR clinical evidence timelines for device requalification.
- Research Institutes:Protocol flexibility requirements sustain manual system retention where investigator customization outweighs regulatory compliance burdens.
- Academic Institutions:Dual clinical-research missions drive hybrid procurement patterns, with ISO 13485 certification serving as baseline vendor qualification threshold.
Revenue concentration favors Hospitals. Fastest capability expansion is occurring in Blood Banks.
Technology:
Processing workflows decompose into discrete technical modules that vendors integrate with varying degrees of vertical control.
- Blood Component Separation:Density-gradient and membrane-based approaches compete for dominance, with centrifugal force retaining cost advantages at scale while filtration gains traction in platelet-sensitive applications.
- Platelet Collection:Automated apheresis systems command premium positioning in commercial blood services, where collection efficiency directly impacts unit economics.
- Activation Method:Calcium chloride, thrombin, and photoactivation protocols differentiate therapeutic potency for specific clinical indications, with orthopedic surgeons standardizing activation parameters for bone graft augmentation.
- Storage Solutions:Temperature-controlled preservation and agitation systems extend platelet viability from hours to days, enabling inventory buffering in centralized blood facilities.
Technical maturity clusters around Blood Component Separation. Innovation investment is concentrating in Activation Method optimization.
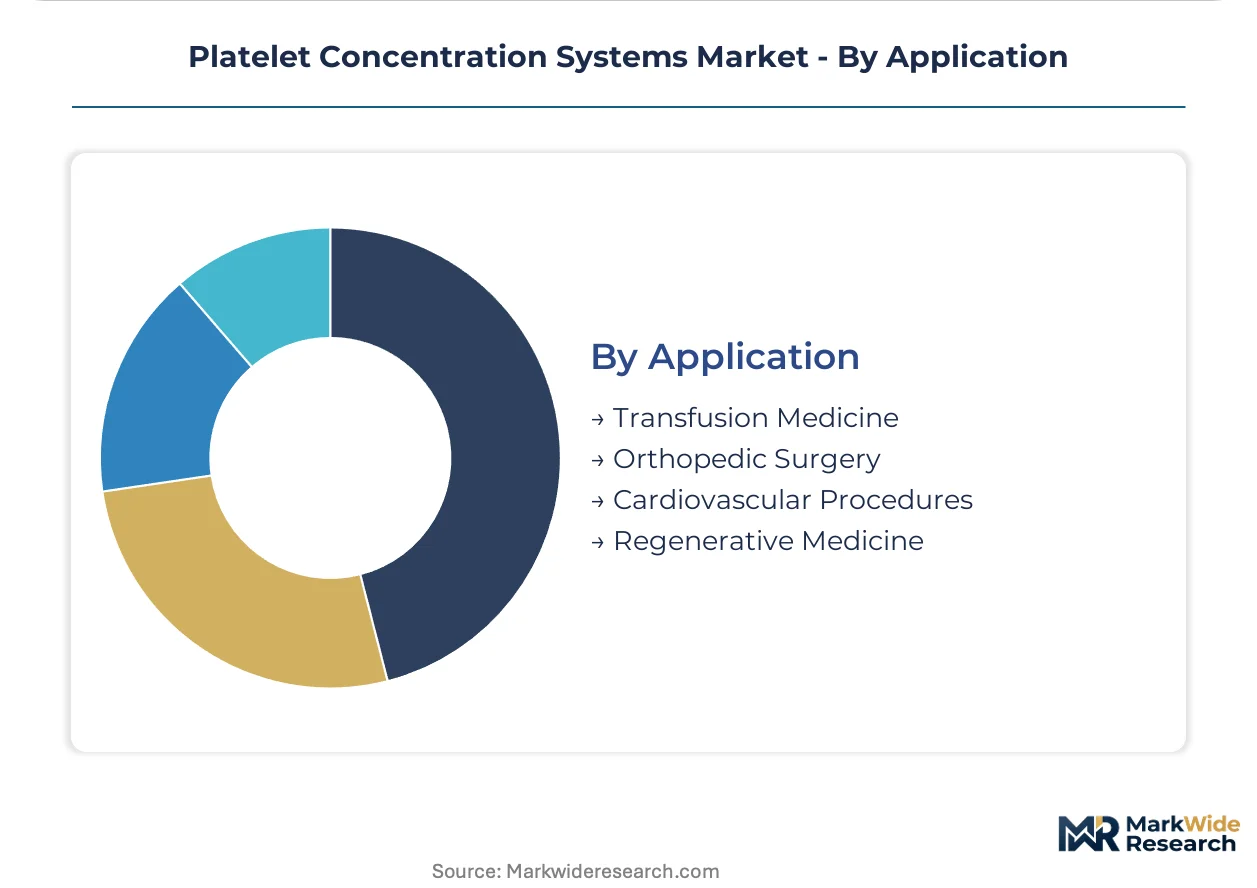
Application:
Clinical indication shapes regulatory pathway, reimbursement code, and outcome validation burden for device manufacturers.
- Orthopedic Surgery:Sports medicine practices in United States outpatient settings are standardizing autologous platelet-rich plasma for soft-tissue repair and bone graft augmentation. CMS coverage determinations for biologic augmentation procedures directly influence capital equipment purchasing cycles.
- Regenerative Medicine:PMDA's streamlined approval pathways in Japan are accelerating dedicated sales channel development for platelet-derived therapeutic products, with wound healing applications expanding beyond traditional orthopedic boundaries.
- Transfusion Medicine:Allogeneic platelet concentrate preparation for hemorrhage management and oncology support remains the volume foundation of blood banking operations.
- Cardiovascular Procedures:Platelet gel applications in sternal wound healing and vascular access site management represent niche adoption with procedure-specific protocol development.
Established volume sits with Transfusion Medicine. Steepest expansion trajectory belongs to Regenerative Medicine.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospital procurement committees command the largest capital equipment budgets for autologous blood processing hardware. Academic medical centers in metropolitan networks are standardizing closed-loop automated systems for outpatient orthopedic suites.
United States
Ambulatory surgical centers in Texas and Florida are expanding biologic augmentation capabilities for sports medicine practices. FDA 510(k) clearance pathways for Class II medical devices compress competitive refresh cycles for centrifugation system vendors. The Greater Boston cluster anchors regenerative medicine research with hybrid clinical-research procurement patterns.
Germany
EU Medical Device Regulation clinical evidence requirements are restructuring quality management systems for blood-derived therapeutic device handlers. Notified body scrutiny timelines extend device requalification schedules for orthopedic surgery centers. The Baden-Württemberg medical technology corridor concentrates ISO 13485 certification expertise among mid-scale automation vendors.
Japan
PMDA streamlined regenerative medicine approval pathways are accelerating dedicated sales channel development for platelet-rich plasma preparation hardware. METI industrial policy supports biologics corridor infrastructure in the Kanto region. Tokyo academic hospitals are adopting hybrid mechanical processing units at accelerated replacement cycles.
United Kingdom
NHS procurement frameworks are consolidating vendor relationships around integrated blood management system suppliers for orthopedic surgery networks. MHRA post-Brexit regulatory alignment creates parallel validation requirements for EU-exporting manufacturers. The Oxford-Cambridge-London golden triangle concentrates research institute demand for manual protocol flexibility.
Australia
TGA medical device approval pathways are absorbing EU MDR clinical evidence standards for blood processing equipment imports. Public hospital networks in New South Wales and Victoria are bundling platelet concentration hardware with surgical navigation platforms. The Melbourne biomedical precinct anchors regenerative medicine trial infrastructure for wound healing applications.
Platelet Concentration Systems Market Competitive Environment
Strategic partnerships dominate the current landscape as device manufacturers seek surgical platform integration. The vendor base clusters around three tiers: diversified orthopedic conglomerates with captive distribution, dedicated blood management specialists with ISO-certified quality systems, and regional automation vendors serving cost-sensitive research environments. Two archetypes define positioning: hardware-software bundlers leveraging implant franchises, and collection-through-reinfusion integrators capturing ambulatory surgery center consolidation. M&A activity and technology licensing agreements represent the primary competitive vectors.
Among diversified orthopedic conglomerates, Stryker Corporation and Zimmer Biomet Holdings Inc. exemplify the bundling archetype, anchoring positions through surgical navigation platform integration. Terumo Corporation occupies a distinct tier as a blood management specialist with vertically integrated collection-through-reinfusion capabilities. These three entities represent the structural concentration visible in procurement committee vendor consolidation across United States metropolitan hospital networks.
| Leading Market Players |
|---|
| Arthrex, Inc. |
| Stryker Corporation |
| Zimmer Biomet Holdings Inc. |
| Terumo Corporation |
| Johnson & Johnson |
| EmCyte Corporation |
| Harvest Technologies Corp. |
| Haemonetics Corporation |
| Arteriocyte Medical Systems, Inc. |
| Others |
Value Chain & Pricing Dynamics
EU MDR sustainability and traceability mandates for blood-derived therapeutic devices gate qualified supplier access and premium-tier pricing for manufacturers serving orthopedic surgery networks. ISO 13485 certification tiers separate vendors eligible for bundled hospital contracts from price-competitive alternatives locked into research segments.
Pricing Analysis
High-volume blood banks transact on per-unit processing economics while orthopedic suites absorb capital premiums for closed-loop automation. Three-tier pricing structure across premium automated, standard centrifugation, and economy manual levels tracks FDA 510(k) clearance status and after-sales service bundling. Cost compression in standard-tier centrifugation systems intensifies as polymer tube substitution erodes glass-based cost advantages. Ambulatory surgical centers exhibit acute price sensitivity against academic medical centers prioritizing contamination-risk reduction.
Supply Chain Analysis
Biomedical engineering talent scarcity in Massachusetts and Baden-Württemberg constrains automated system assembly capacity for vendors serving United States and EU hospital networks. Component sourcing concentrates on German precision motors, Japanese optical sensors, and United States polymer tubing. Petrochemical feedstock volatility for polycarbonate blood-contact materials creates margin instability for disposable kit manufacturers. Distribution runs through group purchasing organizations consolidating ambulatory surgery center demand in metropolitan United States markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane filtration technology is displacing pure centrifugation architectures in high-throughput settings, compressing legacy device refresh cycles and forcing portfolio repositioning across installed bases.
For Market Incumbents: Deepen backward integration into polymer blood-contact material production to insulate margins from petrochemical volatility threatening disposable kit economics. Anchor hospital information system interoperability certification to defend replacement demand against software-native entrants targeting automated workflow integration. For New Entrants and Emerging Players: Ambulatory surgery center group purchasing organizations represent the most penetrable channel for automated system vendors lacking orthopedic implant bundling relationships. Target wound healing applications outside traditional sports medicine with simplified activation protocols requiring minimal surgeon retraining. For Investors and Strategic Acquirers: FDA 510(k) clearance backlog expansion is the leading indicator that regulatory affairs capability scarcity will drive acquisition premiums for mid-scale automation vendors with captive submission expertise. Focus on blood management specialists with ISO 13485 infrastructure and PMDA Japan market access as durable platform assets across the regenerative medicine expansion window.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Compressed clearance timelines capture orthopedic surgery suite replacement cycles before competitive refresh. |
| CE Marking Pathway Investment | MDR clinical evidence preparation secures EU blood establishment requalification against notified body scrutiny. |
| Hospital System Partnership | Single-source contracting with integrated delivery networks locks out fragmented device competitors. |
| Software Companion Development | Hospital information system connectivity enables interoperability certification for automated workflow adoption. |
| Reimbursement Strategy | CMS coverage determination alignment unlocks capital equipment purchasing cycles at ambulatory surgical centers. |
Study Parameters
FDA 510(k) premarket notification databases, EU MDR notified body technical documentation, and hospital procurement contract registries formed the secondary backbone. Primary interviews with orthopedic surgeons, blood bank operations directors, biomedical engineers, and GPO contracts managers validated processing protocol preferences and capital budgeting timelines. Bottom-up unit economics modeling across centrifugation, filtration, and automated system architectures combined with top-down therapeutic procedure volume projections.
Historical trendline analysis of platelet concentration system shipments tracked replacement cycle compression and technology transition velocity across the analysis window. Segmentation modeling incorporated processing architecture, clinical setting tier, activation method, and regional regulatory cluster dimensions. CAGRs derived from installed base expansion rates and average selling price trajectory assumptions, with membrane filtration adoption curves and CMS reimbursement code updates as critical forecast inputs.
Several conditions sit outside the modeled scope, including PMDA regulatory pathway revisions, polymer supply chain disruptions, and orthopedic implant vendor bundling strategy shifts. Forecasts reflect documented assumptions regarding outpatient procedure migration and automated system contamination risk valuation. Material deviation in FDA guidance evolution or EU MDR implementation timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Supraglottic Airway Devices Market
Medical Devices
Walkers and Rollators Market
Medical Devices
Midline Catheters Market
Medical Devices
Global Self-Injection Device Market
Medical Devices
Respiratory Inhaler Devices Market
Medical Devices
Medical Hydrophilic Coatings Market
Medical Devices
Therapeutic Contact Lenses Market
Medical Devices
Venturi Mask Market
Medical Devices
Light Therapy Beauty Devices Market
Medical Devices
China Minimally Invasive Surgery Devices Market
Medical Devices
Global Medical Device Labeling Market
Medical Devices
Global Angiography Devices Market
Medical Devices
Artificial Cornea and Corneal Implant Market
Medical Devices
Neuro Ablation Devices Market
Medical Devices
US Wearable Medical Devices Market
Medical Devices
Neurotech Devices Market