
 Artificial Eye Lenses Market | 2026-2036
Artificial Eye Lenses Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Eye Lenses Market Analytics
Asset-light manufacturing partnerships and third-party lens foundry arrangements is tilting competitive dynamics toward firms that outsource production while retaining brand and distribution control. Alcon leverages vertical integration across material synthesis and finished lens production to sustain margin capture. Johnson & Johnson Vision Care anchors its position through R&D intensity in presbyopia-correcting platforms. STAAR Surgical Company specializes in collagen copolymer materials for its proprietary implantable phakic lens segment.
Artificial eye lenses are implantable optical devices, typically constructed from hydrogel, silicone, or acrylic polymers with specific refractive indices and dioptric powers, designed to replace or supplement the eye's natural crystalline lens to restore visual acuity. Monofocal lenses dominate procedural volumes due to established reimbursement codes and surgical familiarity, while toric variants command premium positioning by addressing concurrent astigmatism correction. Multifocal and accommodative designs represent the fastest-growing product trajectory as patients seek spectacle independence following cataract extraction or refractive lens exchange.
The FDA's 510(k) clearance framework and the EU Medical Device Regulation (MDR) Class III designation impose clinical evidence requirements that shape development timelines and market access for novel intraocular platforms. ISO 11979 standards govern biocompatibility, optical performance, and mechanical stability testing protocols that manufacturers must satisfy before commercial distribution. Stakeholders must monitor evolving reimbursement decisions by CMS and national health technology assessment bodies, as these determinations directly influence surgeon adoption rates and patient out-of-pocket exposure for premium lens categories.
Market Dynamics
The artificial eye lenses market pivots on the tension between presbyopia-correcting platform adoption and the durability of monofocal reimbursement codes, with CMS coverage determinations acting as the decisive arbiter of surgeon behavior and patient access to premium optical categories.
Growth Catalysts
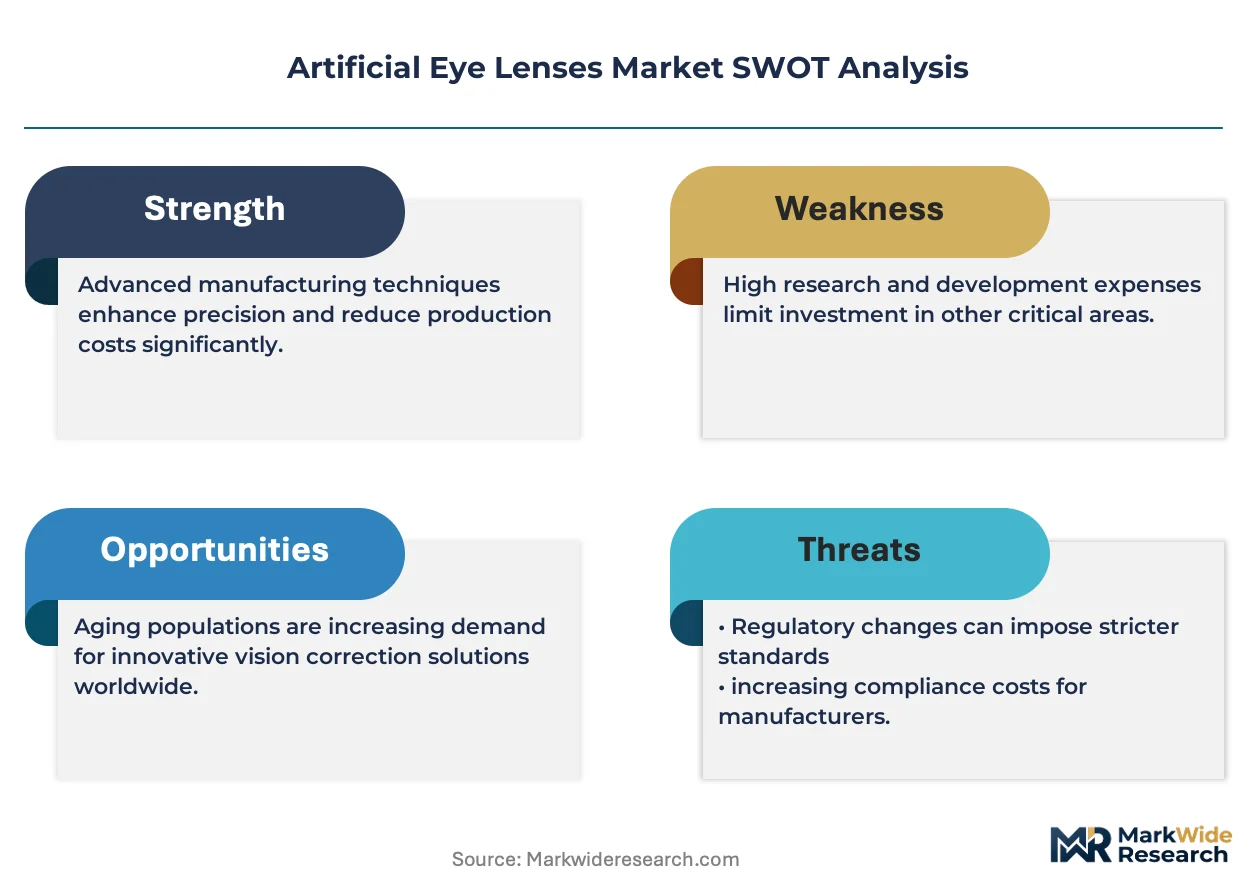
- FDA 510(k) Pathway Refinements:Streamlined premarket notification procedures for intraocular lens modifications accelerate iterative product launches and compress development-to-revenue cycles for established manufacturers.
- Collagen Copolymer Material Advances:Biocompatible implantable phakic lenses with enhanced oxygen permeability expand the addressable patient pool to younger myopic demographics previously excluded from refractive correction.
- Japan's Super-Aged Society:METI-targeted healthcare infrastructure investments in ophthalmic surgical capacity drive procedure volume expansion in the world's most aged national population.
Market Restraints
- Acrylic Polymer Feedstock Concentration:Optical-grade hydrophobic acrylic monomer supply concentrates among a handful of specialty chemical producers in Germany and Japan, creating input cost volatility and qualification bottlenecks.
- EU MDR Class III Designation:Enhanced clinical evidence requirements for novel intraocular platforms extend regulatory timelines and elevate documentation burdens relative to the prior Medical Device Directive framework.
- Spectacle-Corrected Monofocal Substitution:Postoperative spectacle dependence remains acceptable to cost-sensitive patient segments, particularly where supplemental private insurance for premium lenses is unavailable.
Strategic Opportunities
- India's Cataract Surgery Backlog:Government-funded national blindness control programs and expanding private ophthalmology chains create volume upside in a market with substantial unmet surgical need.
- Teleophthalmology Pre-Screening Integration:Remote diagnostic platforms are compressing referral pathways and enabling lens counseling prior to clinic arrival, reshaping patient education and premium conversion.
- Extended Depth of Focus Convergence:Wavefront-optimized optics combined with femtosecond laser-assisted delivery systems are opening intermediate vision correction as a distinct premium category between monofocal and multifocal designs.
Industry Challenges
- Refractive Surgeon Training Bottlenecks:Premium lens implantation demands specialized biometry interpretation and toric alignment techniques that outpace fellowship program output in several metropolitan surgical markets.
- ISO 11979-7 Stability Testing Duration:Accelerated aging protocols for foldable lens materials require 24-month minimum validation cycles that constrain product refresh rates and tie up R&D capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Eye Lenses Market |
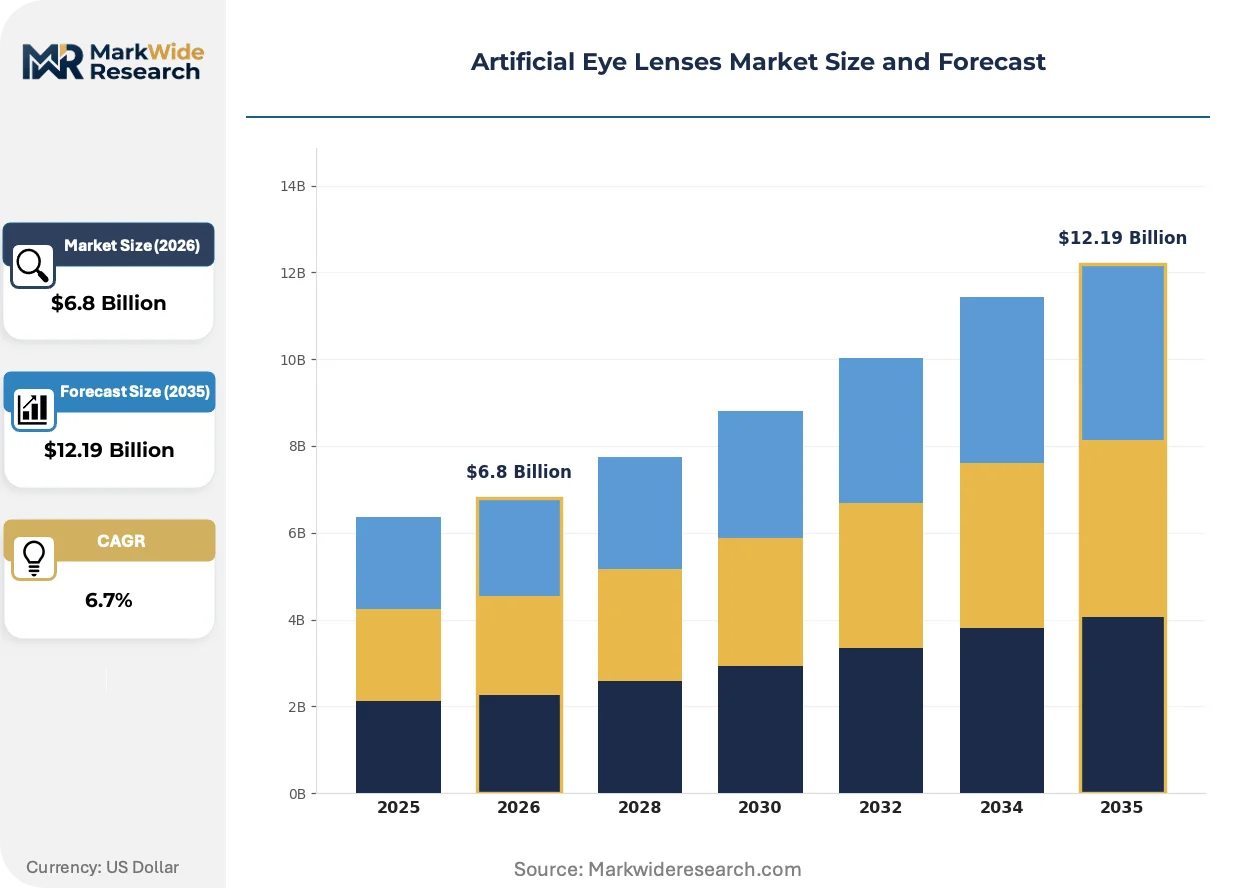
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.19 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monofocal, Multifocal, Toric, Accommodative End User: Ophthalmology Clinics, Hospitals, Ambulatory Surgical Centers, Patients Material: Hydrogel, Silicone, PMMA, Biocompatible Polymers Technology: Laser-Assisted, Manual Surgery, Computerized, Image-Guided |
| Companies Covered | Alcon, Johnson & Johnson Vision Care, Carl Zeiss Meditec AG, Bausch & Lomb, HOYA Corporation, Rayner, STAAR Surgical Company, Lenstec, EyeKon Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Eye Lenses Market Evolving Landscape
Active materials science breakthroughs and regulatory harmonization efforts are compressing the innovation cycle for optical implants, while patient expectations for spectacle independence reshape competitive differentiation beyond raw visual acuity metrics.
Extended depth of focus lenses distribute light across multiple focal points through proprietary echelette designs rather than discrete zones, enabling intermediate computer vision without the halo trade-offs of diffractive multifocals. Academic medical centers in the United States and South Korea are piloting these platforms for presbyopic patients with high screen-time requirements. The technology is migrating from premium self-pay segments toward broader reimbursement negotiations as intermediate vision gains recognition as a functional necessity.
The EU Medical Device Regulation's post-market surveillance requirements now mandate systematic collection of real-world performance data for Class III implantable devices, including intraocular lenses. Manufacturers must establish periodic safety update reports and trend analysis protocols that extend far beyond pre-market clinical trial obligations. Small and mid-sized lens producers without established pharmacovigilance infrastructure face disproportionate compliance costs, accelerating consolidation toward firms with captive regulatory affairs capabilities.
Direct-to-consumer financing platforms are unbundling premium lens selection from traditional insurance pre-authorization workflows, allowing patients to self-fund upgrades through installment structures at the point of surgical scheduling. Ophthalmology clinic chains in Brazil and Mexico have pioneered this model, with specialty medical lenders now entering the United States market. This channel innovation is most visible in metropolitan areas where high-deductible health plans have shifted substantial out-of-pocket burden to commercially insured patients.
Artificial Eye Lenses Market Segmentation
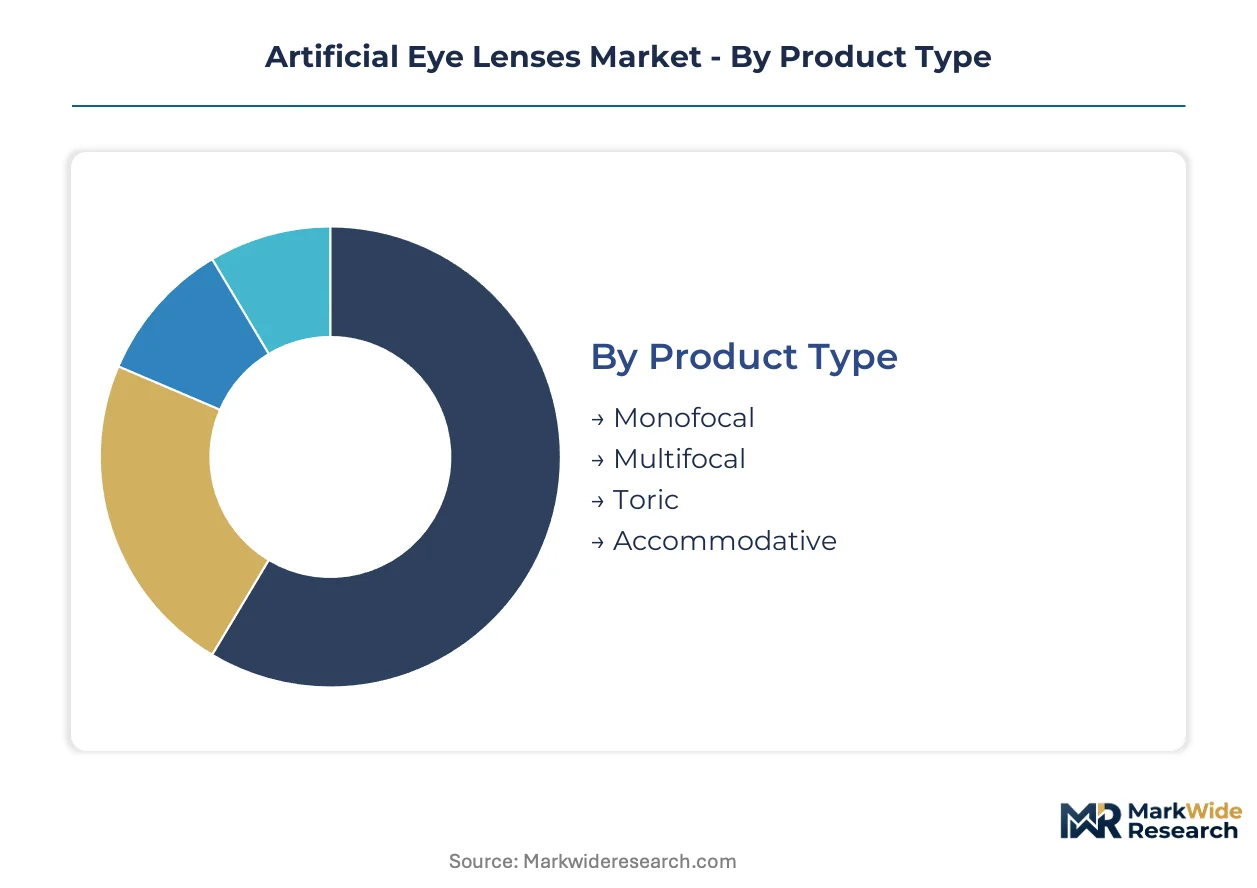
Artificial eye lens segmentation reveals how reimbursement structures, surgical venue economics, and material biocompatibility requirements fragment commercial opportunity across distinct patient access pathways and technology readiness levels.
Product Type:
The use-case spectrum spans spectacle-corrected basic vision restoration through advanced presbyopia management, with each tier commanding different reimbursement codes and surgeon training investments.
- Monofocal:Single-focus optics manufactured from hydrophobic acrylic or silicone elastomers deliver reliable distance vision correction at standardized reimbursement rates. Volume concentrates in United States Medicare-covered cataract procedures where cost sensitivity dominates patient selection, though supplemental spectacle dependence limits premium conversion.
- Multifocal:Diffractive or refractive zone designs distribute light across multiple focal planes to reduce postoperative spectacle reliance. Adoption is climbing fastest among commercially insured United States patients in metropolitan surgical markets where out-of-pocket financing platforms have proliferated.
- Toric:Cylindrical power incorporation addresses preexisting corneal astigmatism concurrent with cataract extraction.
- Accommodative:Mechanically flexible haptic designs attempt to restore near vision through simulated ciliary muscle response.
Established volume favors Monofocal; emerging adoption favors Multifocal.
End User:
Cost tier stratification separates high-volume institutional purchasers from fragmented self-pay channels, reshaping distribution economics and patient education requirements.
- Ophthalmology Clinics:Dedicated surgical facilities with captive patient flow dominate premium lens penetration through direct counseling and bundled pricing. United States metropolitan markets show the highest concentration of presbyopia-correcting platform adoption.
- Hospitals:Integrated health systems leverage purchasing scale for standardized monofocal procurement, though administrative complexity slows premium category uptake. Japan's super-aged society is driving hospital-based surgical capacity expansion through METI-targeted infrastructure investments.
- Ambulatory Surgical Centers:Medicare-certified outpatient venues optimize throughput for high-volume cataract extraction with same-day discharge protocols.
- Patients:Direct-to-consumer channels are emerging in Brazil and Mexico through specialty medical lenders financing premium upgrades outside traditional insurance workflows.
Institutional procurement concentrates in Hospitals; margin capture concentrates in Ophthalmology Clinics.
Material:
Supply concentration among German and Japanese specialty chemical producers shapes input cost structures and qualification timelines for finished lens manufacturers.
- Hydrogel:Water-absorbing polymer networks with high biocompatibility profile dominated early foldable lens generations. Demand persists in emerging markets where cost minimization overrides optical performance optimization.
- Silicone:Elastomeric materials with superior oxygen permeability and glistening-free optical clarity command premium positioning in presbyopia-correcting platforms. United States and South Korean academic medical centers favor silicone for extended depth of focus pilot programs.
- PMMA:Rigid polymethyl methacrylate persists in specific phakic intraocular lens applications requiring structural stability.
- Biocompatible Polymers:Collagen copolymer formulations enable implantable phakic lenses for younger myopic demographics previously excluded from refractive correction.
Legacy volume rests with Hydrogel; technology migration favors Silicone.
Technology:
Application maturity separates established manual techniques from capital-intensive automation requiring substantial surgeon retraining and facility investment.
- Laser-Assisted:Femtosecond laser platforms enable precise corneal incisions, capsulotomy, and lens fragmentation with reduced phacoemulsification energy. United States metropolitan markets show highest penetration where capital equipment amortization aligns with premium procedure volumes.
- Manual Surgery:Conventional phacoemulsification with handheld instrumentation retains dominance in cost-constrained settings and developing markets. India's national blindness control programs rely on manual techniques to address surgical backlog.
- Computerized:Digital biometry integration and IOL power calculation algorithms reduce refractive prediction error.
- Image-Guided:Real-time intraoperative aberrometry and tomography refine toric alignment and lens positioning.
Volume concentration remains with Manual Surgery; technology upgrade cycles favor Laser-Assisted.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in optical-grade polymers and finished intraocular lenses tilt toward net-import positions in surgical volume centers, while Germany and Japan maintain export surpluses in specialty acrylic monomers. Currency-adjusted procurement costs are reshaping distribution economics across major ophthalmology markets.
United States
Medicare reimbursement codes for cataract extraction drive procedural volume concentration, with metropolitan surgical clusters in Florida, California, and Texas accounting for disproportionate premium lens adoption. The FDA's 510(k) premarket notification pathway accelerates iterative product launches for established manufacturers. Academic medical centers in Boston and the San Francisco Bay Area pilot extended depth of focus platforms for presbyopic patients with high screen-time requirements.
Germany
Optical-grade hydrophobic acrylic monomer production concentrates among specialty chemical producers in the Rhine-Ruhr and Bavarian industrial corridors, creating supply bottlenecks for finished lens manufacturers worldwide. The EU Medical Device Regulation's Class III designation for intraocular lenses imposes enhanced clinical evidence requirements that extend regulatory timelines. Stuttgart and Munich host precision optics clusters where femtosecond laser-assisted surgical platforms achieve highest penetration rates.
Japan
METI-targeted healthcare infrastructure investments expand ophthalmic surgical capacity in response to the world's most aged national population, with hospital-based procedure volumes climbing steadily. The PMDA's alignment with international harmonization initiatives streamlines approval pathways for novel intraocular platforms. Tokyo and Osaka metropolitan areas concentrate presbyopia-correcting lens adoption among commercially insured patient segments.
India
Government-funded national blindness control programs address substantial cataract surgery backlog in rural and semi-urban districts, relying on manual phacoemulsification techniques to maximize throughput. The CDSCO's medical device registration framework is converging toward international standards, though state-level procurement variations persist. Private ophthalmology chains in Delhi-NCR, Maharashtra, and Karnataka are integrating teleophthalmology pre-screening to compress referral pathways.
Brazil
Direct-to-consumer financing platforms pioneered by clinic chains in São Paulo and Rio de Janeiro unbundle premium lens selection from traditional insurance pre-authorization workflows, enabling self-funded upgrades through installment structures. ANVISA's regulatory framework for Class III implantable devices requires local clinical trial data for novel platforms, extending market access timelines. Specialty medical lenders are proliferating in metropolitan markets where high-deductible health plans shift out-of-pocket burden to commercially insured patients.
Artificial Eye Lenses Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in material synthesis and optical foundry operations. Market structure tilts toward consolidation among vertically integrated manufacturers with captive polymer production, while asset-light competitors outsource fabrication to third-party lens foundries. Three archetypes dominate: full-stack producers controlling material-to-finished-lens value chains, R&D-intensive platform developers prioritizing presbyopia-correcting optics, and regional distributors leveraging local regulatory relationships. Competitive moves center on backward integration into optical-grade monomer supply and strategic partnerships with femtosecond laser platform manufacturers.
Among vertically integrated manufacturers, Alcon and Johnson & Johnson Vision Care exemplify the full-stack archetype with in-house control over material synthesis and finished lens production. STAAR Surgical Company occupies a specialist position within the implantable phakic lens segment. Carl Zeiss Meditec AG represents the precision optics heritage common to German market participants, with geographic origin in Oberkochen signaling long-established competence in optical system integration.
| Leading Market Players |
|---|
| Alcon |
| Johnson & Johnson Vision Care |
| Carl Zeiss Meditec AG |
| Bausch & Lomb |
| HOYA Corporation |
| Rayner |
| STAAR Surgical Company |
| Lenstec |
| EyeKon Medical |
| Others |
Value Network & Pricing Analysis
German and Japanese specialty chemical producers dominate optical-grade hydrophobic acrylic monomer supply, concentrating margin capture upstream while finished lens manufacturers compete on brand differentiation and surgical training relationships downstream.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the artificial eye lenses market. Price differentiation hinges on FDA 510(k) clearance tier and surgeon training certification level, with toric and multifocal platforms commanding substantial premiums over monofocal baselines. Pricing pressure stems from CMS reimbursement compression on standard cataract procedures, squeezing margins for hospital procurement channels. Cost-sensitive government programs in India and Brazil exhibit highest price sensitivity, while United States metropolitan ophthalmology clinics show lowest sensitivity due to direct-to-consumer financing proliferation.
Supply Chain Analysis
Optical-grade acrylic monomer feedstock concentrates in Germany, Japan, and select United States specialty chemical corridors, with finished lens fabrication dispersing to Ireland, Singapore, and United States medical device hubs. Raw material dependencies center on hydrophobic acrylic polymers, silicone elastomers, and collagen copolymer formulations. Single-source vulnerability in German monomer supply creates qualification bottlenecks for new market entrants. Distribution runs through ophthalmology clinic chains and hospital purchasing committees, with ambulatory surgical centers gaining share through Medicare-certified outpatient volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The artificial eye lenses market functions as a service-attach opportunity where postoperative toric alignment services and extended depth of focus optimization consultations expand faster than hardware shipment growth alone.
For Market Incumbents: Pre-empt regulatory documentation burdens by establishing captive pharmacovigilance infrastructure ahead of EU MDR Class III periodic safety update mandates, while securing backward integration into optical-grade monomer supply through strategic partnerships with Rhine-Ruhr and Bavarian chemical producers to defend against feedstock cost volatility. For New Entrants and Emerging Players: India's government-funded national blindness control programs represent the most penetrable entry point for economy-tier monofocal volume, while Brazil's direct-to-consumer financing platforms offer premium segment access without traditional insurance pre-authorization barriers; pursue teleophthalmology pre-screening partnerships to compress referral pathways and enable lens counseling prior to clinic arrival. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed ophthalmology clinic chains lacking captive regulatory affairs capabilities, where EU MDR compliance costs are accelerating consolidation toward firms with established documentation infrastructure; monitor CMS reimbursement determinations on extended depth of focus categories as the decisive inflection signal for premium platform viability.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates iterative product launches for established manufacturers through streamlined premarket notification. |
| CE Marking Pathway | EU MDR Class III designation imposes enhanced clinical evidence requirements extending regulatory timelines. |
| Hospital System Partnership | Integrated health systems leverage purchasing scale for standardized monofocal procurement volume. |
| Software Companion Development | Digital biometry integration reduces refractive prediction error and enables premium conversion. |
| Reimbursement Strategy | CMS coverage determinations act as decisive arbiter of surgeon behavior and patient access. |
Research Methodology
The analysis maps monofocal, multifocal, toric, and accommodative lens platforms, each validated through cataract surgeons, ophthalmology clinic procurement directors, biomedical engineers, and GPO contracts managers, combining primary interviews with secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, EU MDR technical documentation, and ISO 11979 biocompatibility standards, with bottom-up procedure volume triangulation against top-down manufacturer shipment data.
Forecasts hold fixed FDA regulatory pathway stability and CMS reimbursement code structures while varying presbyopia-correcting platform adoption curves, cataract surgery volume growth, and material substitution patterns across silicone, hydrogel, and acrylic polymer segments; CAGRs derive from segmented procedure volume projections calibrated against aging demographic trajectories and surgical capacity expansion in Japan, United States, and India.
Practitioners should monitor FDA 510(k) pathway refinements, EU MDR post-market surveillance enforcement intensity, and CMS national coverage determinations on extended depth of focus lenses for early signals requiring forecast revision; cross-checking against hospital procurement database benchmarks and GPO contract pricing indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Medical Radiation Shielding Market
Medical Devices
Pectus Bar Market
Medical Devices
Global Medical Device Security Market
Medical Devices
Defibrillator Pads Market
Medical Devices
Europe Ultrasound Devices Market
Medical Devices
Global Hydrocephalus Shunts Market
Medical Devices
Surgical Display Market
Medical Devices
Veterinary Ultrasound Devices Market
Medical Devices
Disposable Lancets Market
Medical Devices
South Africa Neurology Devices Market
Medical Devices
Radiofrequency Skin Rejuvenation Devices Market
Medical Devices
Germany Artificial Organs and Bionics Market
Medical Devices
Photorejuvenation Devices Market
Medical Devices
GCC Organ Preservation Market
Medical Devices
Ehealth Devices Market
Medical Devices
Osteotomy Plates Market