
 Home Dialysis Systems Market | 2026-2036
Home Dialysis Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Home Dialysis Systems Market Intelligence
Aftermarket service revenue is rewriting profit allocation across the home dialysis value chain. Fresenius Medical Care leverages its vertically integrated consumables network to capture recurring revenue streams. Baxter International anchors its position through peritoneal dialysis fluid logistics and patient training infrastructure. Outset Medical differentiates via simplified user interfaces that reduce caregiver dependency.
Home dialysis systems encompass portable and stationary medical devices that perform blood purification or peritoneal fluid exchange outside clinical facilities, typically operating at blood flow rates of 200–400 mL/min for hemodialysis and utilizing biocompatible synthetic membranes with ultrafiltration coefficients exceeding 20 mL/h/mmHg. These systems serve end-stage renal disease patients requiring regular solute clearance and fluid management without facility-based supervision. Hemodialysis equipment commands the dominant equipment type position due to established reimbursement codes and physician familiarity, while IoT-enabled devices represent the fastest-expanding technology segment as remote monitoring capabilities reduce hospitalization risk and enable predictive intervention protocols. Peritoneal dialysis sustains steady penetration in markets where water infrastructure constraints limit hemodialysis machine deployment.
FDA premarket notification requirements and the EU Medical Device Regulation shape device validation timelines, while Medicare's ESRD Prospective Payment System directly influences patient eligibility criteria and provider investment decisions. Japan's PMDA enforces stringent electrical safety standards for home-use renal equipment that exceed general medical device benchmarks. Stakeholders must monitor evolving interoperability mandates that will determine which connected platforms achieve preferred network status with payers.
Market Dynamics
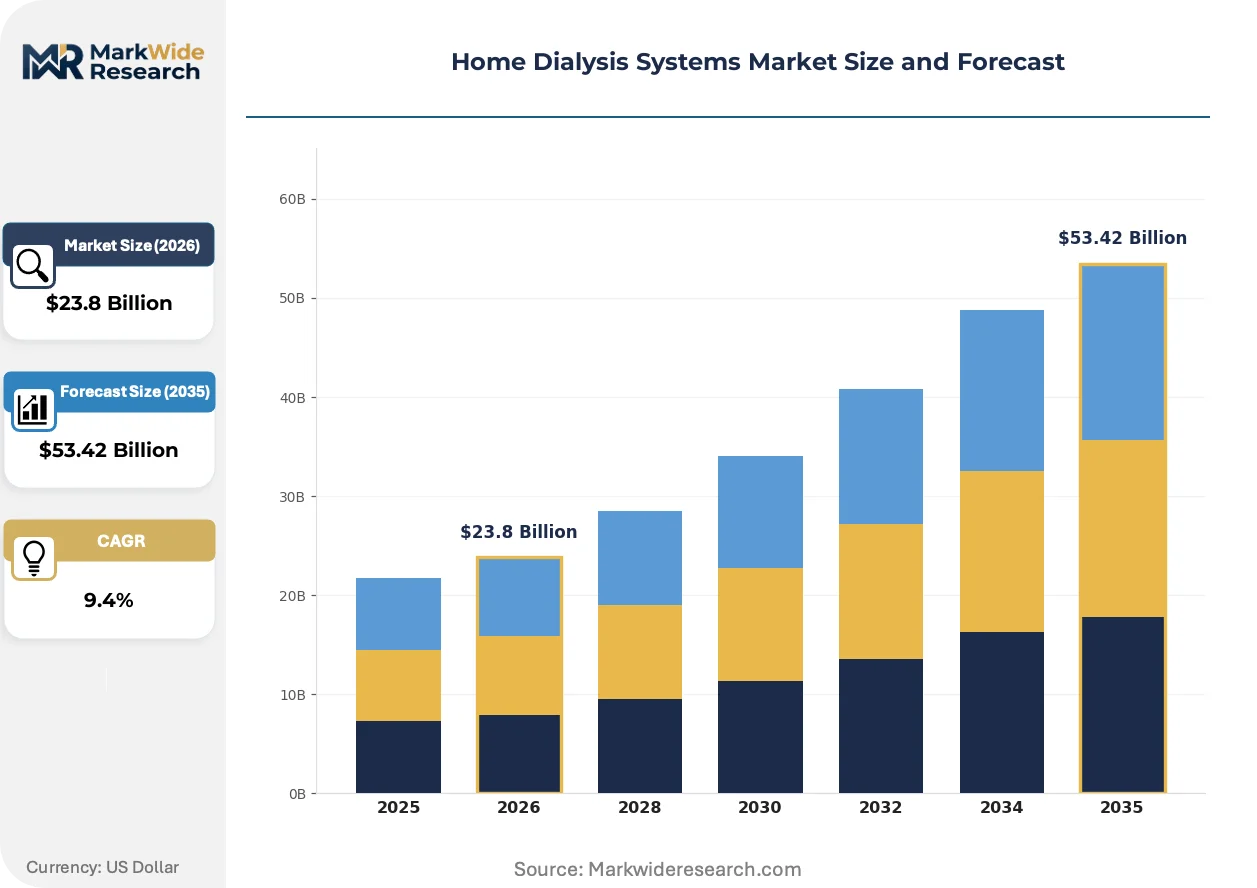
Medicare's bundled payment expansion is restructuring provider economics toward home-based renal therapy, compressing reimbursement differentials between in-center and residential treatment modalities while accelerating capital deployment into portable hemodialysis infrastructure.
Growth Catalysts
- ESRD Prospective Payment System:Medicare's reimbursement framework eliminates facility-based payment premiums, redirecting patient volume toward home modalities. Homecare providers capture margin expansion through reduced overhead structures.
- IoT-enabled remote monitoring:Connected devices transmit real-time treatment data to clinical teams, enabling predictive intervention protocols that reduce hospitalization incidence. Physician practices adopt these platforms for risk-contract performance.
- Water infrastructure constraints:Markets with unreliable municipal supply or limited dialysis center density sustain peritoneal dialysis penetration as the viable alternative to hemodialysis machine deployment.
Market Restraints
- Biocompatible membrane supply concentration:Synthetic membrane production clusters among limited polymer suppliers, exposing device manufacturers to polysulfone and polyethersulfone price volatility.
- PMDA electrical safety standards:Japan's home-use renal equipment requirements exceed general medical device benchmarks, extending validation timelines and increasing certification costs for market entry.
- Caregiver dependency threshold:Hemodialysis systems require vascular access maintenance and anticoagulant management that exceeds unassisted patient capability, limiting addressable population to those with residential support.
Strategic Opportunities
- EU Medical Device Regulation harmonization:MDR compliance creates preferred supplier status for connected platforms achieving interoperability certification, concentrating procurement toward validated device ecosystems.
- Simplified user interface design:Reduced training burden expands candidate pools to patients with lower health literacy or limited caregiver availability, opening underpenetrated demographic segments.
- Peritoneal dialysis fluid logistics optimization:Automated delivery scheduling and inventory management systems reduce patient supply burden, improving therapy adherence in dispersed geographies.
Industry Challenges
- Nephrology nursing specialization gap:Home dialysis training requires vascular access assessment and complication triage competencies that generalist nurses rarely possess, constraining program scale-up velocity.
- Interoperability mandate compliance:Evolving data exchange standards between device platforms and electronic health record systems demand continuous software validation investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Dialysis Systems Market |
| Market Size in 2026 | $23.8 Billion |
| Market Size in 2035 | $53.42 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Peritoneal Dialysis, Hemodialysis, Automated Home Dialysis, Home Hemodialysis End User: Patients, Caregivers, Hospitals, Homecare Providers Equipment Type: Dialysis Machines, Catheters, Dialyzers, Accessories Technology: Continuous Ambulatory Peritoneal Dialysis, Online Hemodiafiltration, Portable Dialysis Units, IoT-Enabled Devices |
| Companies Covered | Fresenius Medical Care, Baxter International Inc., DaVita, Outset Medical, Quanta Dialysis Technologies, Cantel Medical, Nipro Corporation, B. Braun Melsungen, AWAK Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Dialysis Systems Market Strategic Shifts & Innovations
Digital infrastructure is compressing the physical footprint of renal replacement therapy while regulatory frameworks accelerate validation requirements for connected medical devices. Three developments dominate competitive positioning.
Cloud-based treatment analytics platforms aggregate blood flow rate, ultrafiltration volume, and alarm frequency data from distributed home units. Dialysis providers deploy these systems to manage population health contracts with Medicare Advantage plans. This architecture is virtualizing the traditional clinical oversight model, enabling single nurses to monitor dozens of simultaneous treatments.
The FDA's premarket notification pathway for portable hemodialysis devices has tightened cybersecurity validation requirements following interconnected medical device guidance updates. Manufacturers now embed encryption protocols and access controls earlier in development cycles. Smaller device companies face capital constraints meeting these documentation burdens, advantaging established players with regulatory affairs infrastructure.
Homecare providers now unbundle after-sales service from equipment procurement, contracting directly with third-party technical service organizations for device maintenance and patient training. This procurement pattern shifts margin capture from manufacturers to specialized service networks. The United States exhibits the most advanced service unbundling, where Medicare's consolidated billing rules incentivize operational separation of device and service reimbursement.
Home Dialysis Systems Market Segmentation
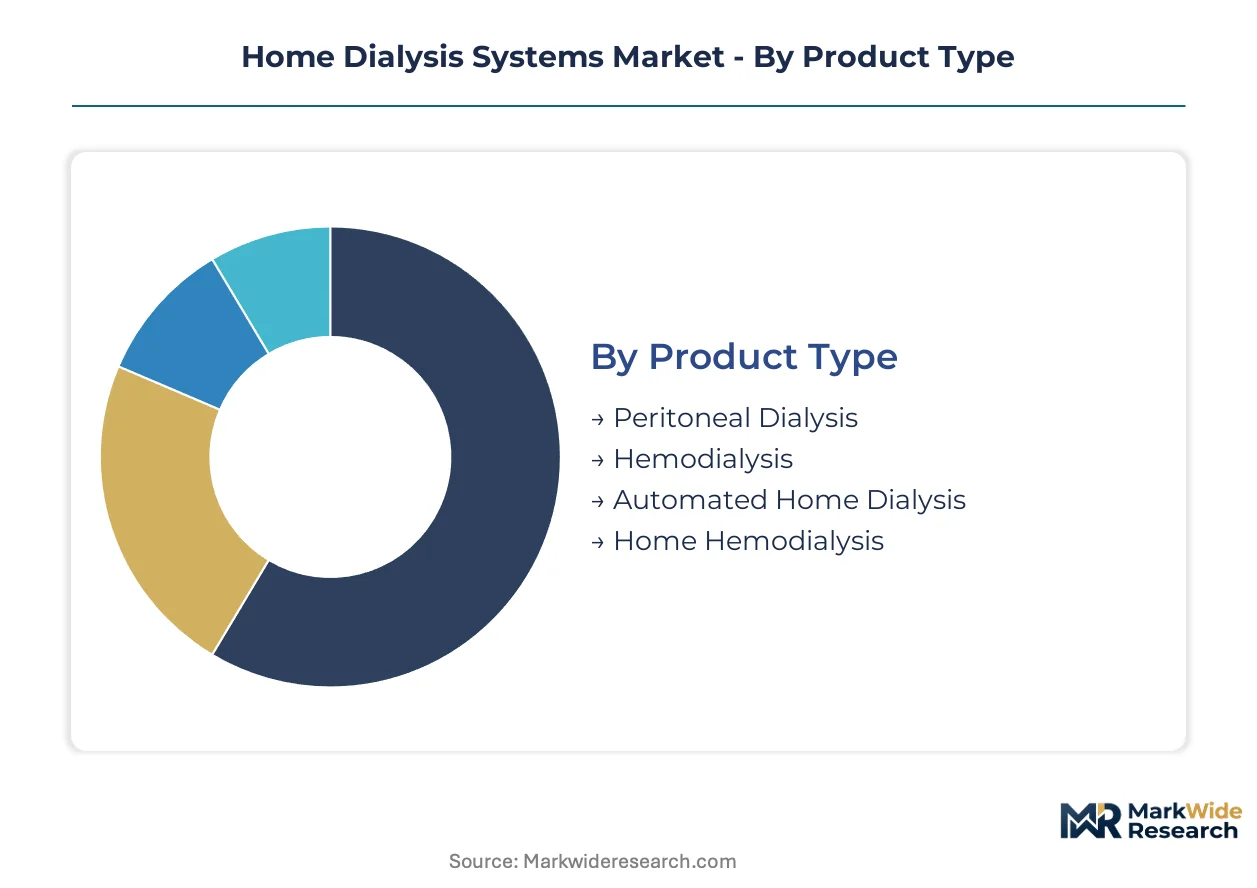
Segmentation in home dialysis systems determines reimbursement pathways, regulatory validation requirements, and capital deployment strategies. Equipment manufacturers prioritize segments with established Medicare billing codes, while emerging technology categories reshape competitive positioning through remote monitoring capabilities.
Product Type:
Mature modalities dominate revenue concentration while emerging formats reshape patient eligibility criteria.
- Hemodialysis:Blood purification systems operate at 200–400 mL/min flow rates using biocompatible synthetic membranes with ultrafiltration coefficients exceeding 20 mL/h/mmHg. Medicare's ESRD Prospective Payment System incentivizes home-based hemodialysis through bundled reimbursement parity with in-center treatment.
- Peritoneal Dialysis:Fluid exchange therapy utilizes the peritoneal membrane for solute clearance without vascular access requirements. Water infrastructure constraints in dispersed geographies sustain penetration where hemodialysis machine deployment faces logistical barriers.
- Automated Home Dialysis:Cyclers deliver overnight peritoneal exchanges with programmable fill and drain cycles.
- Home Hemodialysis:Compact systems designed specifically for residential installation with simplified water treatment.
Hemodialysis handles the majority of throughput; automated home dialysis is gaining share fastest among patient-managed modalities.
End User:
Cost tier stratification separates institutional procurement from patient-directed acquisition patterns.
- Homecare Providers:Specialized agencies deliver device installation, maintenance, and clinical training under Medicare consolidated billing rules. Reimbursement framework shifts toward outpatient renal care accelerate capital deployment into portable infrastructure.
- Patients:Direct system operators require simplified interfaces to manage vascular access maintenance and anticoagulant protocols without continuous supervision.
- Caregivers:Residential support personnel assist with treatment setup and alarm response.
- Hospitals:Acute care facilities transition stable patients to home modalities under readmission reduction programs.
Homecare providers command the dominant procurement volume; patients represent the steepest expansion trajectory as self-care eligibility broadens.
Equipment Type:
Margin concentration varies sharply between capital equipment and recurring consumables.
- Dialysis Machines:Stationary and portable hemodialysis units incorporate blood pumps, dialysate delivery systems, and safety monitors. FDA premarket notification pathways for home-use devices have tightened cybersecurity validation requirements.
- Dialyzers:Hollow-fiber membrane cartridges execute solute clearance through diffusion and convection.
- Catheters:Vascular and peritoneal access devices enable therapy initiation.
- Accessories:Bloodlines, dialysate concentrates, and disposables generate recurring revenue streams.
Dialysis machines anchor capital expenditure budgets; accessories deliver the most predictable recurring revenue profile.
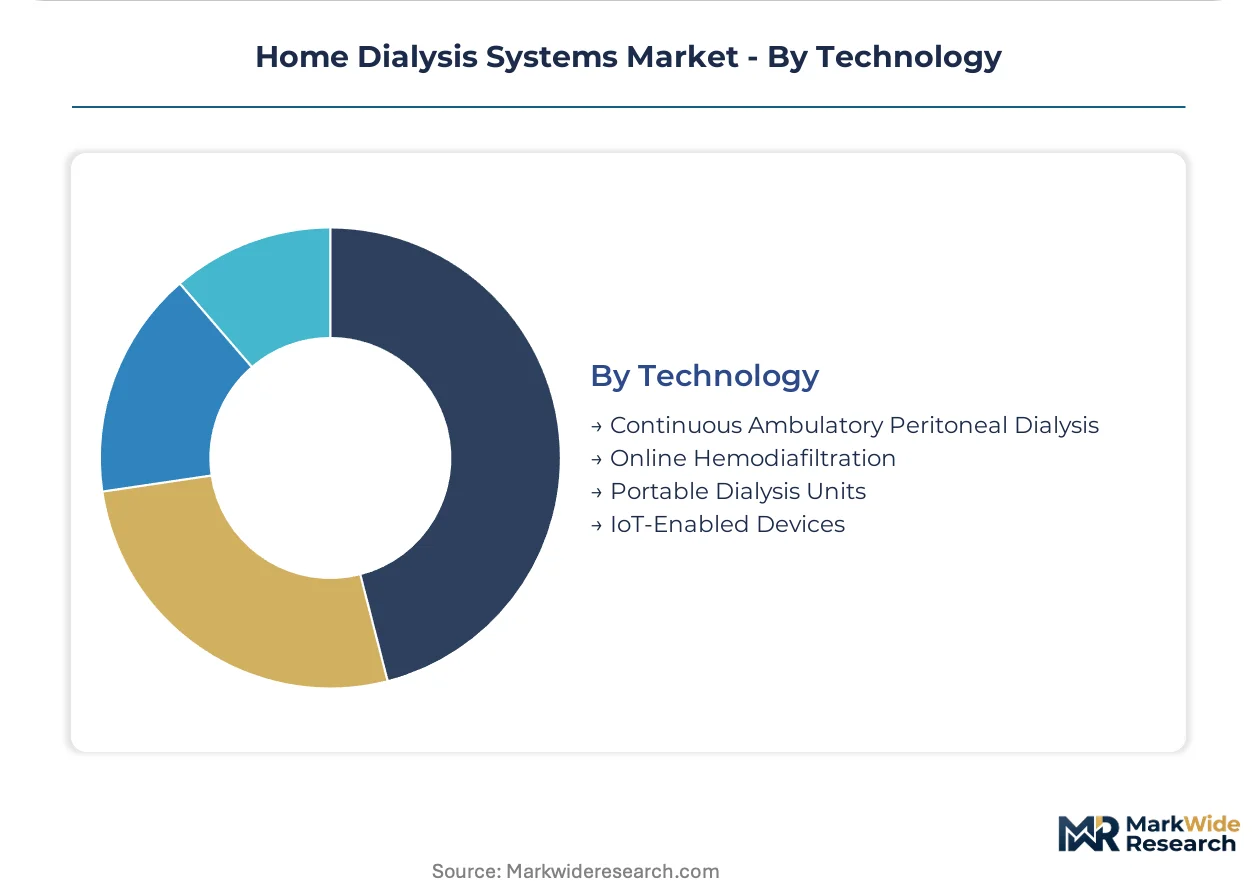
Technology:
Application focus separates continuous therapies from intermittent treatment formats.
- IoT-Enabled Devices:Connected platforms transmit real-time blood flow rate, ultrafiltration volume, and alarm frequency data to clinical teams. Cloud-based analytics enable predictive intervention protocols that reduce hospitalization incidence under Medicare Advantage risk contracts.
- Portable Dialysis Units:Battery-operated systems enable travel and workplace treatment flexibility.
- Continuous Ambulatory Peritoneal Dialysis:Manual fluid exchanges performed throughout waking hours without machine dependency.
- Online Hemodiafiltration:Advanced convective clearance technique requiring ultrapure dialysate generation.
IoT-enabled devices are climbing the fastest on provider adoption timelines; continuous ambulatory peritoneal dialysis maintains steady penetration in water-constrained markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity diverges sharply across geographies. Medicare's bundled payment parity in the United States compresses reimbursement differentials and accelerates home modality uptake, while cash-pay markets in emerging economies face steeper patient cost barriers that slow device penetration despite clinical need.
United States
Medicare's ESRD Prospective Payment System eliminates facility-based payment premiums, redirecting patient volume toward home hemodialysis and peritoneal modalities. The FDA's tightened cybersecurity validation requirements for interconnected home-use devices extend premarket notification timelines. Boston and Minneapolis anchor device development clusters where manufacturers embed encryption protocols earlier in product cycles.
Germany
The EU Medical Device Regulation's interoperability mandates concentrate procurement toward validated device ecosystems with connected platform certification. Germany's statutory health insurance funds negotiate bundled reimbursement rates that favor outpatient renal care transitions. The Rhine-Ruhr and Baden-Württemberg regions host technical service networks that unbundle after-sales maintenance from equipment procurement.
Japan
PMDA electrical safety standards for home-use renal equipment exceed general medical device benchmarks, extending validation timelines and increasing certification costs for market entry. Japan's aging demographic sustains peritoneal dialysis penetration where caregiver-assisted home therapy addresses nursing shortage constraints. Osaka and Tokyo metropolitan areas concentrate dialysis provider networks deploying IoT-enabled remote monitoring platforms.
China
NMPA regulatory pathways for portable hemodialysis devices prioritize electrical safety and biocompatibility documentation aligned with GB standards. Water infrastructure constraints in tier-3 and tier-4 cities sustain peritoneal dialysis as the viable alternative to hemodialysis machine deployment. The Yangtze River Delta and Pearl River Delta clusters concentrate domestic device assembly and dialyzer membrane production.
Brazil
ANVISA registration requirements for home-use renal equipment demand local clinical validation studies that extend market entry timelines for foreign manufacturers. Brazil's dispersed geography and uneven dialysis center density favor peritoneal dialysis fluid logistics optimization over capital-intensive hemodialysis infrastructure. São Paulo and Rio de Janeiro anchor private insurance-funded home therapy programs with automated delivery scheduling systems.
Home Dialysis Systems Market Key Industry Players
Vertically integrated multinationals and specialized technology developers split the market between recurring consumables dominance and user interface innovation. Consolidation pressures concentrate procurement toward validated device ecosystems with regulatory affairs infrastructure. Three archetypes define competitive positioning: integrated dialysis providers controlling consumables supply chains, technology specialists simplifying patient-directed operation, and logistics-anchored peritoneal dialysis fluid networks. Dominant competitive moves include backward integration into membrane polymer supply and strategic partnerships with Medicare Advantage plans for risk-contract performance.
Among integrated therapy providers, Fresenius Medical Care and Baxter International occupy positions anchored by vertically integrated consumables networks and patient training infrastructure. Outset Medical exemplifies the technology specialist archetype through simplified user interface design that reduces caregiver dependency and expands self-care eligibility. These three companies represent distinct strategic vectors: captive supply chain control, logistics-anchored service delivery, and patient-directed product simplification.
| Leading Market Players |
|---|
| Fresenius Medical Care |
| Baxter International Inc. |
| DaVita |
| Outset Medical |
| Quanta Dialysis Technologies |
| Cantel Medical |
| Nipro Corporation |
| B. Braun Melsungen |
| AWAK Technologies |
| Others |
Cost & Logistics Intelligence
Trans-Pacific freight corridors connecting polysulfone polymer producers in Germany to dialyzer assembly plants in China transmit cost volatility directly into membrane pricing tiers, concentrating margin pressure on device manufacturers while enabling aftermarket service providers to capture differentiated value through technical support bundling.
Pricing Analysis
After-sales revenue tiers spanning replacement membranes, preventive maintenance contracts, and remote monitoring subscriptions generate lifetime values exceeding original equipment sales by substantial multiples. Three-tier pricing structure across premium FDA-cleared systems, standard CE-marked devices, and economy-grade regional alternatives stratifies procurement decisions, with certification grade and geographic delivery cost as primary differentiation drivers. Cost compression in consumables is intensifying because biocompatible membrane supply concentrates among limited polymer suppliers. Homecare providers exhibit lowest price sensitivity due to Medicare reimbursement insulation, while cash-pay patients in emerging markets face acute affordability constraints.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for hollow-fiber membrane sourcing. Manufacturing concentrates in Germany, China, and Japan, with polysulfone resin, polyethersulfone polymer, and medical-grade adhesives as critical input dependencies. Single-source vulnerability in specialized membrane extrusion equipment amplifies disruption exposure. Distribution runs through vertically integrated dialysis providers controlling consumables logistics, third-party medical device distributors serving independent clinics, and direct-to-provider contracts for automated peritoneal dialysis fluid delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent device manufacturers face substitution pressure from wearable artificial kidney technologies that promise continuous renal replacement without vascular access, requiring defensive repositioning around service integration and regulatory moats.
For Market Incumbents: Entrench market position through backward integration into membrane polymer production and captive supply of dialyzer cartridges, neutralizing raw material cost volatility. Deepen clinical training infrastructure investments to raise switching costs for homecare providers. FDA cybersecurity validation requirements for interconnected devices create regulatory moats that disadvantage capital-constrained challengers.
For New Entrants and Emerging Players: Brazil's dispersed geography and uneven dialysis center density offers white-space expansion for automated peritoneal dialysis fluid logistics platforms. India's tier-3 cities present comparable infrastructure gaps favoring water-independent modalities. Target simplified user interface development to reduce caregiver dependency and expand self-care eligibility pools. Partner with regional Medicare Advantage plans for risk-contract performance validation.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical device conglomerates seeking to divest non-core renal assets amid portfolio rationalization. Long-term viability hinges on recurring revenue visibility from consumables and monitoring subscriptions rather than capital equipment cyclicality. Monitor FDA premarket notification clearance timelines for portable hemodialysis devices as inflection indicators for competitive positioning shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Membrane Polymers | Captive supply of polysulfone resin neutralizes price volatility from German chemical suppliers. |
| FDA Premarket Notification Pathway | Cybersecurity validation requirements for home-use devices extend timelines but deepen regulatory moats. |
| Medicare Advantage Risk Contracting | IoT-enabled remote monitoring platforms reduce hospitalization incidence under capitated reimbursement. |
| Automated Peritoneal Dialysis Fluid Logistics | Inventory management systems improve therapy adherence in Brazil's geographically dispersed markets. |
| Simplified User Interface Development | Reduced training burden expands candidate pools to patients with limited caregiver availability. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured interviews with nephrologists, homecare agency administrators, biomedical engineers, and GPO contracts managers, cross-referenced against FDA 510(k) filings, CMS Medicare reimbursement databases, EU MDR notified body certificates, and hospital procurement records. Bottom-up patient volume estimates by modality and top-down equipment shipment data were triangulated to validate market sizing.
Calibration against historical Medicare claims data and equipment installation records anchored projection assumptions across the analysis window. Segmentation dimensions modeled include therapy modality, equipment type, technology architecture, end-user procurement channel, and regional regulatory cluster. CAGRs were derived from patient population epidemiology, reimbursement trajectory modeling, and technology adoption curve analysis, with IoT penetration rates and home therapy transition velocities as critical forecast inputs.
Practitioners should monitor FDA cybersecurity guidance updates, Medicare bundled payment expansion velocity, and PMDA electrical safety standard revisions for early signals requiring forecast adjustment. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Handheld Ultrasound Devices Market
Medical Devices
Global Sacral Nerve Stimulation Market
Medical Devices
Wearable ECG Sensor Market
Medical Devices
Canada Digital X-Ray Devices Market
Medical Devices
Electrosurgery Accessories Market
Medical Devices
Bioactive Fillings Market
Medical Devices
Global Automatic Pill Dispenser Market
Medical Devices
Global Electromyography Devices Market
Medical Devices
Prefilled Syringes Market
Medical Devices
Intravaginal Device Market
Medical Devices
Microwave Ablation Devices Market
Medical Devices
Intrathecal Pumps Market
Medical Devices
Global Vascular Access Devices Market
Medical Devices
Disposable EEG Electrode Market
Medical Devices
Contact and Intraocular Lenses Market
Medical Devices
Carotid Artery Stents Market