
 Global Pediatric Medical Devices Market | 2026-2036
Global Pediatric Medical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pediatric Medical Devices Market Foresight
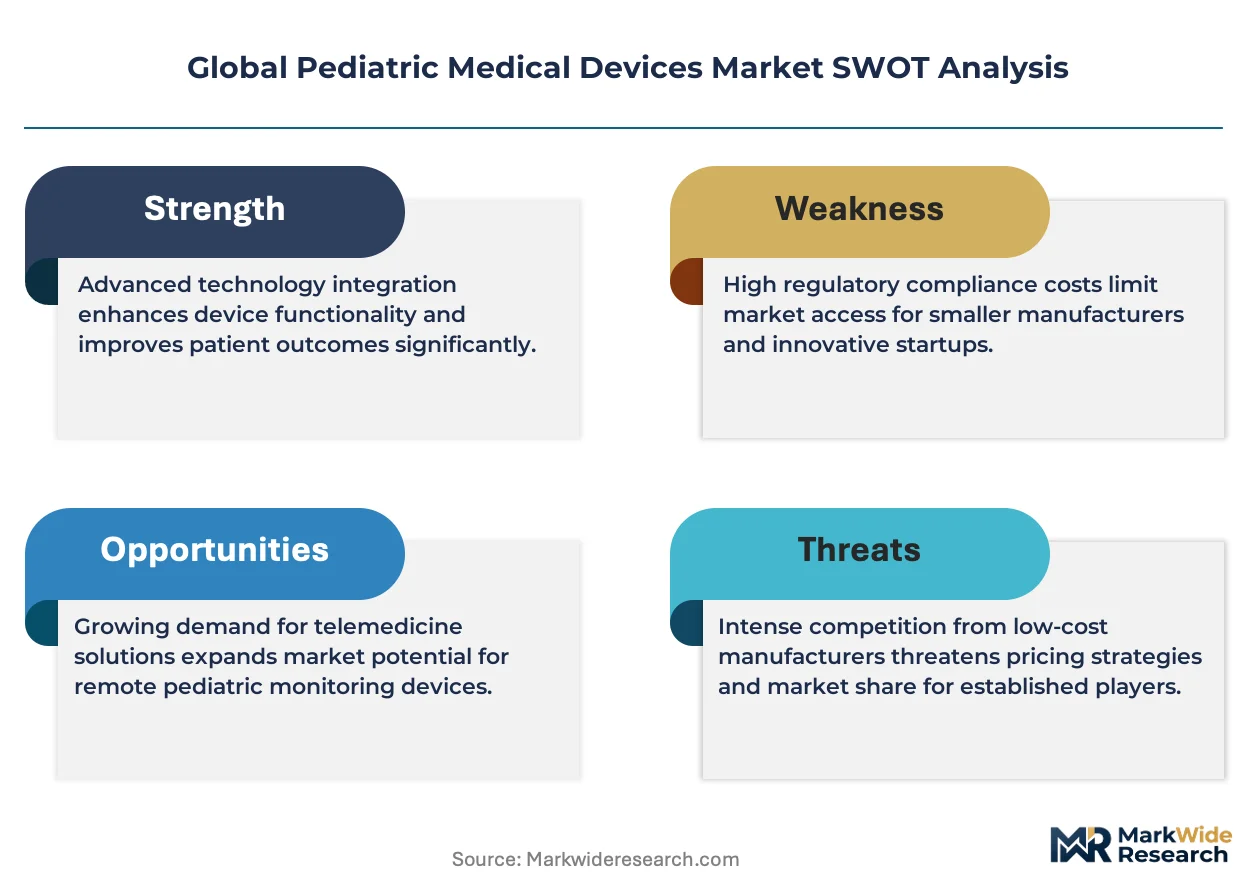
Neonatal intensive care is hardening as the dominant end-use vertical for pediatric device procurement. Medtronic plc leverages its deep portfolio of neonatal monitoring systems to anchor North American hospital networks. Abbott Laboratories competes through specialized pediatric cardiac devices that sustain high R&D intensity across its vascular division. Koninklijke Philips N.V. differentiates via integrated critical care ecosystems that dominate European children's hospital infrastructure.
Pediatric medical devices encompass instruments, apparatus, and machines engineered to dimensions, physiological tolerances, and safety profiles specific to infants, children, and adolescents, typically employing biocompatible polymers and miniaturized sensor arrays manufactured through precision molding and microfabrication processes. These devices serve diagnostic, therapeutic, and monitoring functions across clinical settings where adult-equivalent technologies risk patient harm due to scale or dosage mismatch. Neonatal monitoring systems command the largest revenue pool among product types, reflecting sustained capital expenditure in level III and IV nurseries. Pediatric cardiology represents the fastest-expanding therapy area, driven by congenital heart defect intervention volumes and catheter-based procedure migration from open surgery. Home healthcare deployment is capturing incremental growth as reimbursement frameworks broaden for remote pediatric respiratory and infusion management.
The FDA's Humanitarian Device Exemption and Pediatric Device Consortia program shape U.S. market access by lowering trial burdens for rare pediatric conditions, while the EU Medical Device Regulation imposes stricter clinical evidence requirements that filter smaller manufacturers from European distribution. Japan's PMDA maintains distinct pediatric review pathways that accelerate approval timelines for neonatal critical care innovations relative to standard device categories. Stakeholders must monitor evolving reimbursement parity between hospital and home-based pediatric device deployment as payers recalibrate cost-of-care models.
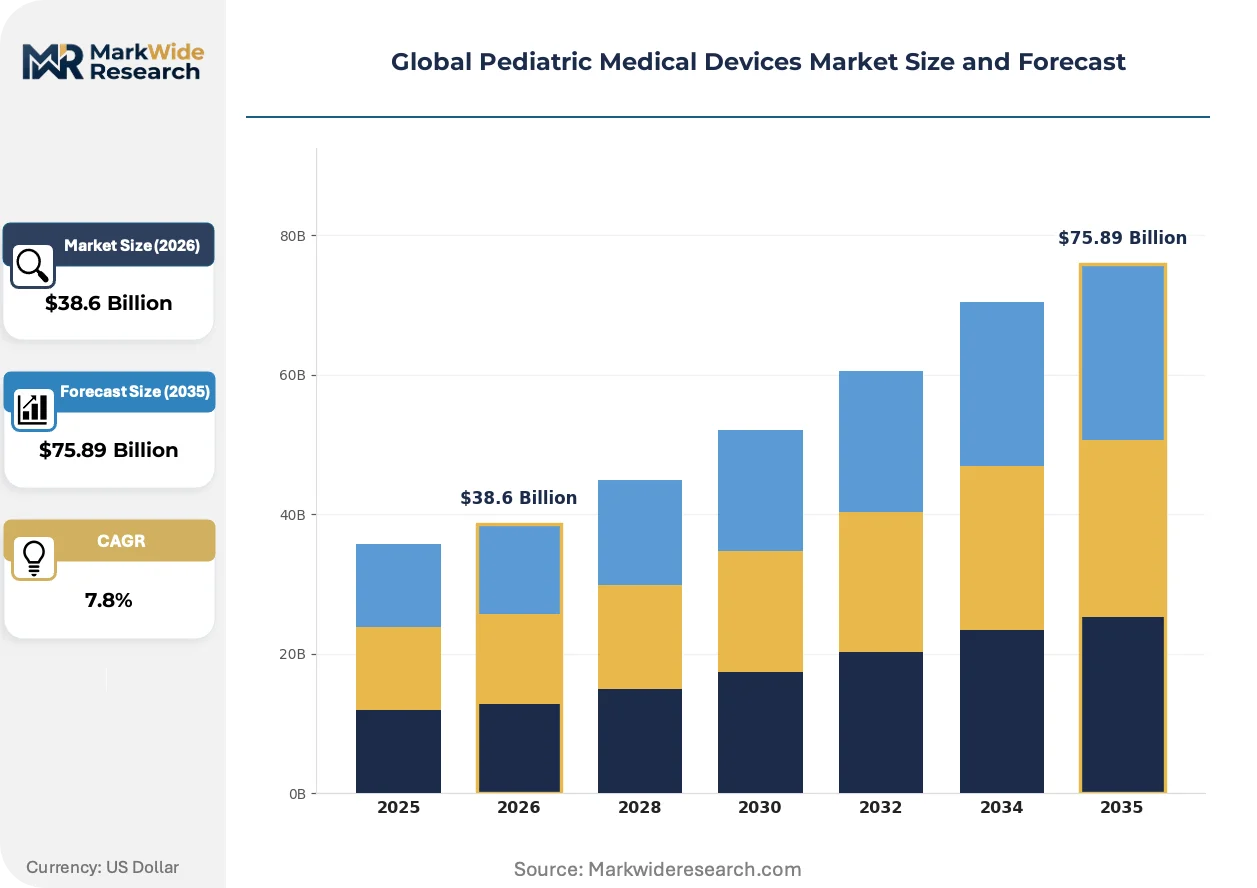
Market Dynamics
The FDA's Pediatric Device Consortia program is compressing development timelines for neonatal critical care technologies, while procurement concentration among United States children's hospital networks intensifies vendor consolidation pressures across the value chain.
Growth Catalysts
- Neonatal ICU capital expansion:Level III and IV nurseries in the United States, Germany, and Japan are deepening monitoring system procurement as congenital intervention volumes rise.
- PMDA accelerated review pathways:Japan's distinct pediatric approval tracks compress timelines for neonatal critical care innovations relative to standard device categories.
- Catheter-based procedure migration:Minimally invasive pediatric cardiology techniques are displacing open surgery volumes across European and North American tertiary centers.
Market Restraints
- Biocompatible polymer cost volatility:Medical-grade silicone and specialized thermoplastics face input price instability from semiconductor-adjacent chemical feedstock competition.
- EU MDR clinical evidence burden:The Medical Device Regulation's stricter evidentiary requirements filter smaller manufacturers from European distribution channels.
- Pediatric-specific miniaturization limits:Sensor array density constraints in sub-millimeter form factors restrict diagnostic precision for neonatal neurological monitoring.
Strategic Opportunities
- Home healthcare reimbursement expansion:United States payer recalibration of cost-of-care models is broadening remote pediatric respiratory and infusion management coverage.
- Integrated critical care ecosystems:Convergence of monitoring hardware with cloud-native analytics platforms creates white space for hospital-at-home service models.
- Humanitarian Device Exemption leverage:The FDA's rare disease pathway lowers trial burdens for conditions affecting under 8,000 patients annually.
Industry Challenges
- Pediatric biomedical engineering talent scarcity:Specialized expertise in neonatal physiology-device interface design concentrates within academic medical center incubators.
- Multi-jurisdiction certification complexity:Simultaneous FDA, PMDA, and EMA approval timelines create regulatory coordination friction for mid-cap manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pediatric Medical Devices Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $75.89 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infusion Pumps, Pediatric Ventilators, Neonatal Monitoring Systems, Pediatric Catheters, Pediatric Surgical Instruments Therapy Area: Neonatology, Pediatric Cardiology, Pediatric Orthopedics, Pediatric Neurology, Pediatric Respiratory Care End User: Children’s Hospitals, Specialty Clinics, Pediatric Diagnostic Labs, Ambulatory Surgery Centers, Rehabilitation Centers Deployment: Hospital-Based, Home Healthcare, Mobile Health Units, Telemedicine Platforms, School Health Programs |
| Companies Covered | Medtronic plc, Abbott Laboratories, Boston Scientific Corporation, GE Healthcare, Koninklijke Philips N.V., Stryker Corporation, Cardinal Health, Inc., F. Hoffmann-La Roche Ltd., Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pediatric Medical Devices Market Shifts & Advancements
Wearable neonatal monitoring platforms are consolidating diagnostic functionality into single-form-factor devices, compressing the traditional multi-modality bedside equipment footprint across children's hospital infrastructure.
Microfabricated sensor arrays are consolidating pulse oximetry, respiratory rate detection, and temperature monitoring into adhesive patch formats. Level IV nurseries in the United States and Germany are piloting these systems for continuous cardiorespiratory surveillance. The technology is consolidating vendor relationships as hospitals reduce discrete device procurement in favor of integrated platform contracts.
The EU Medical Device Regulation's post-market surveillance requirements are extending clinical evidence obligations throughout product lifecycles. Manufacturers serving European children's hospitals must maintain active safety registries beyond initial CE marking. Pediatric cardiology implantables face the steepest compliance cost escalation, prompting restructuring of European distribution strategies among mid-scale device firms.
Hospital procurement committees are bundling device acquisition with multi-year service and analytics subscriptions. Children's hospital networks in Japan and the United States are negotiating enterprise-wide monitoring platform deployments rather than unit-by-unit capital purchases. This contract structure shift is most visible among level III nursery operators seeking operational expenditure predictability.
Global Pediatric Medical Devices Market Segmentation
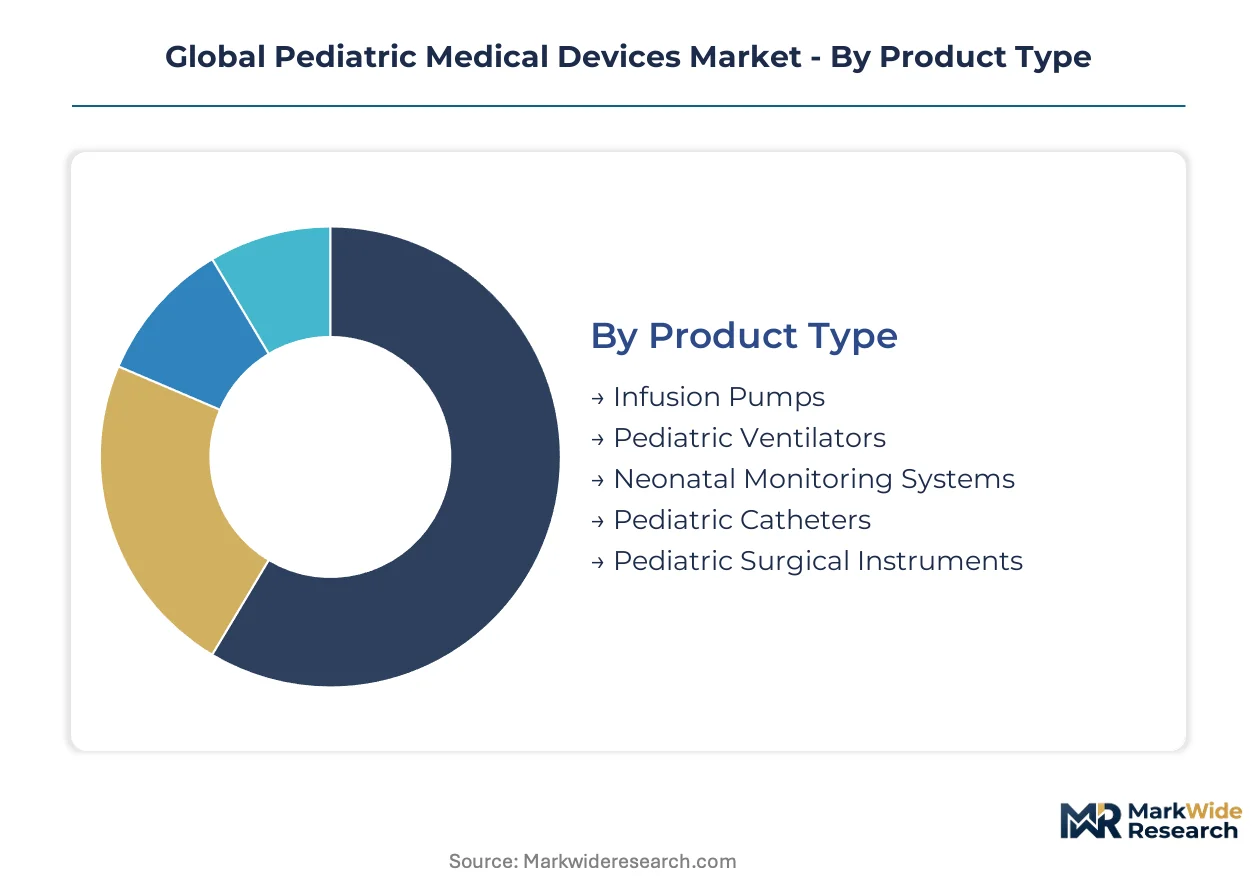
Pediatric device segmentation reveals how regulatory pathways, clinical settings, and patient mobility requirements fragment procurement patterns across the value chain. Manufacturers must align certification strategies with specific segment burdens to optimize market access timelines.
Product Type:
FDA Humanitarian Device Exemption eligibility varies sharply across product categories, with neonatal monitoring systems and pediatric catheters commanding distinct clinical evidence requirements versus infusion pumps and ventilators.
- Neonatal Monitoring Systems:Pulse oximetry, cardiorespiratory tracking, and temperature sensing consolidated into bedside and wearable form factors. Level III and IV nurseries in the United States and Germany drive procurement as congenital intervention volumes expand.
- Pediatric Catheters:Miniaturized vascular and urinary access devices engineered for neonatal through adolescent anatomical ranges. Minimally invasive cardiology procedure migration across European tertiary centers sustains demand acceleration.
- Infusion Pumps:Precision fluid delivery systems with dose-error reduction software for pediatric pharmacology.
- Pediatric Ventilators:Pressure-limited respiratory support with lung-protective ventilation modes.
- Pediatric Surgical Instruments:Scaled laparoscopic and open surgery tools for pediatric anatomical tolerances.
Neonatal monitoring systems sit at the top of the volume ranking, with pediatric catheters climbing the fastest.
Therapy Area:
Cost tier stratification separates high-acuity neonatology and cardiology segments from lower-intensity orthopedics and rehabilitation-focused neurology applications.
- Neonatology:Critical care interventions for premature and term infants spanning respiratory support, thermal regulation, and nutritional delivery. Capital expenditure concentrates in United States children's hospital networks with level IV nursery designations.
- Pediatric Cardiology:Congenital heart defect diagnosis, catheter-based intervention, and surgical correction. Japan's PMDA accelerated review pathways compress approval timelines for structural heart innovations relative to standard device categories.
- Pediatric Orthopedics:Growth-plate-sparing implants and external fixation for trauma and deformity correction.
- Pediatric Neurology:Seizure monitoring, shunt systems, and neurostimulation for developmental disorders.
- Pediatric Respiratory Care:Asthma management, cystic fibrosis therapy, and home ventilation support.
Neonatology captures the highest absolute spending, while pediatric cardiology gains share fastest on procedure volume expansion.
End User:
Customer type determines procurement committee composition, with children's hospitals employing centralized capital planning versus ambulatory surgery centers favoring unit-level acquisition authority.
- Children's Hospitals:Tertiary pediatric centers with level III and IV nurseries, cardiac catheterization labs, and specialized surgical suites. United States networks consolidate vendor relationships through enterprise-wide monitoring platform contracts spanning multi-year service and analytics subscriptions.
- Ambulatory Surgery Centers:Outpatient facilities performing pediatric orthopedic, ENT, and ophthalmic procedures. Reimbursement parity expansion for same-day discharge drives device procurement for lower-acuity interventions.
- Specialty Clinics:Focused pediatric cardiology, neurology, and endocrinology outpatient practices.
- Pediatric Diagnostic Labs:Imaging, pathology, and genetic testing facilities serving referral networks.
- Rehabilitation Centers:Post-acute and developmental therapy facilities for mobility and cognitive recovery.
Children's hospitals dominate capital deployment, with ambulatory surgery centers expanding most quickly on outpatient migration.
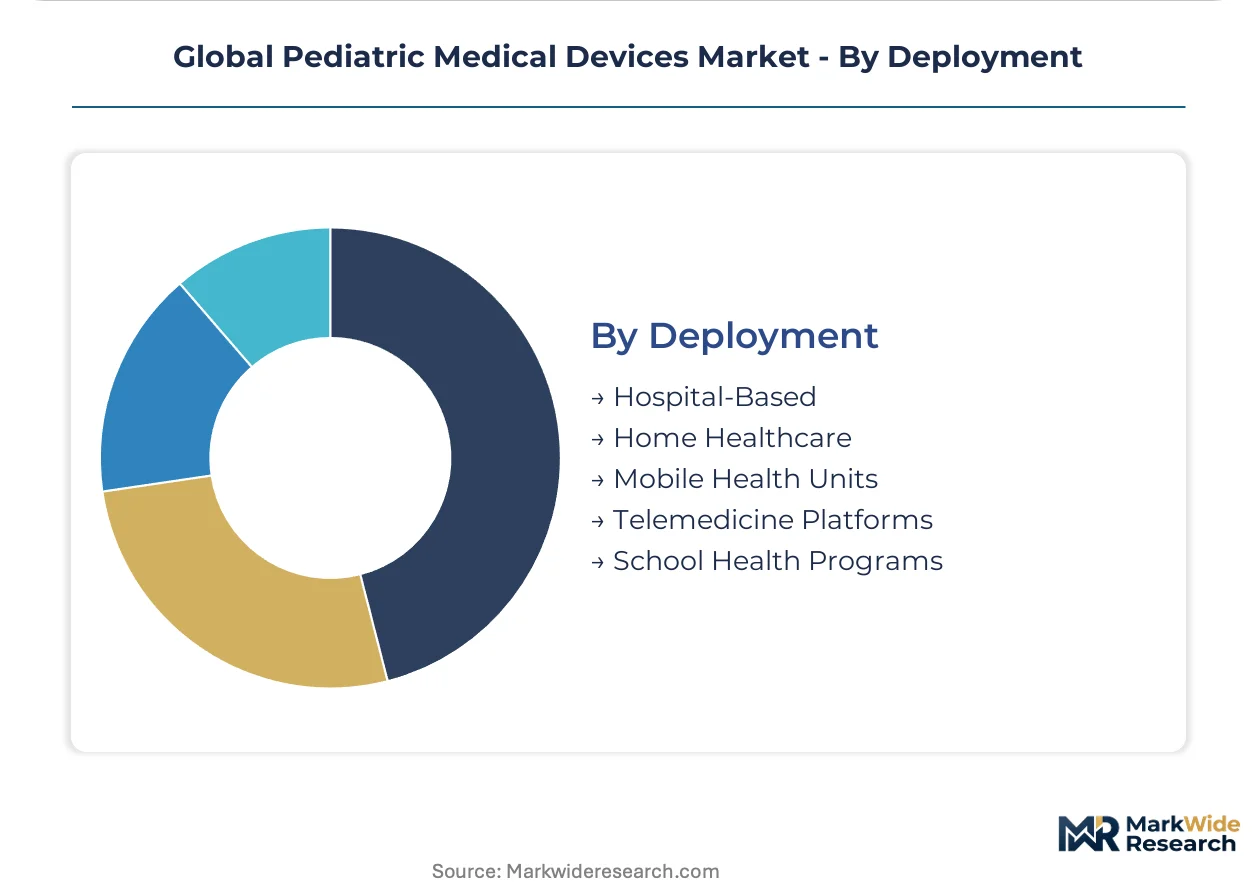
Deployment:
Application setting dictates regulatory and reimbursement complexity, with hospital-based deployment facing established frameworks versus home healthcare navigating evolving remote care codes.
- Hospital-Based:Inpatient and emergency department device utilization with continuous clinical oversight. EU MDR post-market surveillance requirements extend clinical evidence obligations throughout product lifecycles for manufacturers serving European children's hospitals.
- Home Healthcare:Remote pediatric respiratory and infusion management with caregiver training and telehealth backup. United States payer recalibration of cost-of-care models broadens reimbursement coverage for hospital-at-home service models.
- Mobile Health Units:Screening and acute stabilization services for underserved geographic areas.
- Telemedicine Platforms:Remote diagnostic interpretation and care coordination infrastructure.
- School Health Programs:On-site medication delivery and emergency response equipment for chronic conditions.
Hospital-based deployment retains the largest installed base, while home healthcare shows the steepest expansion trajectory on reimbursement framework evolution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as manufacturers relocate assembly operations to jurisdictions with streamlined pediatric device approval pathways and lower cost-of-compliance structures. The FDA's Humanitarian Device Exemption and Japan's PMDA accelerated review tracks create distinct competitive positioning for firms willing to navigate multi-jurisdiction certification complexity.
United States
Level III and IV nurseries in children's hospital networks are deepening capital expenditure on integrated monitoring platforms as congenital intervention volumes expand. The FDA's Pediatric Device Consortia program compresses development timelines for neonatal critical care technologies. Boston and the Research Triangle anchor specialized biomedical engineering talent pools that concentrate device-interface design expertise.
Germany
European tertiary pediatric centers are migrating toward minimally invasive cardiology procedures that sustain demand for miniaturized catheter systems. The EU Medical Device Regulation imposes stricter clinical evidence requirements that filter smaller manufacturers from distribution channels. The Baden-Württemberg medical technology cluster houses precision molding capabilities serving neonatal sensor array production.
Japan
PMDA maintains distinct pediatric review pathways that accelerate approval timelines for neonatal critical care innovations relative to standard device categories. Tokyo and Osaka metropolitan children's hospitals are piloting wearable monitoring platforms that consolidate multi-modality diagnostic functionality. Procurement committees are negotiating enterprise-wide platform contracts spanning multi-year service subscriptions.
China
Domestic manufacturers are expanding capacity in biocompatible polymer processing as NMPA streamlines review pathways for priority pediatric indications. The Yangtze River Delta concentration of precision molding suppliers supports cost-competitive sensor housing production. Shanghai and Suzhou medical device parks are attracting foreign joint ventures seeking regulatory arbitrage in Asia-Pacific distribution.
India
CDSCO is aligning pediatric device registration requirements with international standards to accelerate market access for imported neonatal critical care technologies. Mumbai and Bangalore medical device manufacturing zones are developing assembly capabilities for cost-optimized infusion and respiratory support systems. Private children's hospital chains are expanding level III nursery capacity in tier-1 metropolitan markets.
Global Pediatric Medical Devices Market Competitive Landscape
Strategic partnerships dominate the current landscape as device manufacturers seek to bundle hardware acquisition with cloud-native analytics subscriptions and multi-year service obligations. The vendor base organizes around three archetypes: diversified health technology conglomerates with integrated critical care ecosystems, specialized cardiovascular device firms with deep pediatric cardiology expertise, and mid-scale monitoring specialists pursuing hospital-at-home service model expansion. M&A activity and technology licensing agreements represent the primary competitive vectors as firms defend positioning across procurement committee vendor consolidation pressures.
Within the diversified health technology tier, Medtronic plc and Koninklijke Philips N.V. occupy positions anchoring enterprise-wide platform contract negotiations with United States and European children's hospital networks. Abbott Laboratories exemplifies the specialized cardiovascular archetype, with its vascular division sustaining high R&D intensity across pediatric cardiac device development. These three firms represent the competitive core around which mid-scale specialists and regional fabricators must position for procurement committee consideration.
| Leading Market Players |
|---|
| Medtronic plc |
| Abbott Laboratories |
| Boston Scientific Corporation |
| GE Healthcare |
| Koninklijke Philips N.V. |
| Stryker Corporation |
| Cardinal Health, Inc. |
| F. Hoffmann-La Roche Ltd. |
| Siemens Healthineers |
| Others |
Supply & Pricing Matrix
Children's hospital network procurement committees concentrate purchasing power through enterprise-wide monitoring platform contracts that compress vendor margins into multi-year subscription bundles spanning hardware acquisition and cloud-native analytics services. This buyer concentration forces manufacturers to absorb upfront device costs against deferred service revenue streams, reshaping cash flow structures across the pediatric device value chain.
Pricing Analysis
Direct-to-hospital distributor margins compress pricing transparency as GPO contracts aggregate volume across United States children's hospital networks. Three-tier pricing structure across premium, standard, and economy levels separates FDA Humanitarian Device Exemption-tier innovations from CE-marked European equivalents and cost-optimized Asian-manufactured alternatives. Pricing pressure stems from procurement committee bundling demands that force hardware discounting against multi-year service obligations. Ambulatory surgery centers exhibit highest price sensitivity due to unit-level acquisition authority versus children's hospitals with centralized capital planning.
Supply Chain Analysis
FDA 510(k) and EU MDR certification gates filter component suppliers from medical-grade silicone and precision-molded sensor housing markets. Germany, Japan, and the United States anchor biocompatible polymer processing capabilities, while China concentrates cost-optimized injection molding for non-critical housings. Medical-grade silicone, specialized thermoplastics, and microfabricated sensor arrays constitute critical input dependencies. Single-source vulnerability concentrates in semiconductor-adjacent chemical feedstocks facing electronics industry demand competition. Distribution runs through specialized medical device distributors serving hospital procurement committees and GPO contract fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory-arbitrage dynamics position Japan's PMDA accelerated review pathways against the EU MDR's stricter clinical evidence burden, creating cost-of-compliance differentials that reward multi-jurisdiction certification strategies.
For Market Incumbents: Acquire pediatric biomedical engineering talent pools concentrated within Boston and Research Triangle academic medical center incubators. Consolidate cloud-native analytics platform capabilities to defend against hospital-at-home service model entrants. Backward integration into biocompatible polymer processing mitigates input price volatility from semiconductor feedstock competition. For New Entrants and Emerging Players: The premium-economy tier price gap in neonatal monitoring systems offers white-space entry through wearable patch-format devices bypassing capital-intensive bedside equipment procurement. Target United States home healthcare reimbursement expansion as the most penetrable deployment segment. Pursue FDA Humanitarian Device Exemption pathway for rare pediatric conditions to compress trial burdens and accelerate market access. For Investors and Strategic Acquirers: Diversified health technology conglomerates are the most active acquirer in this space, seeking integrated critical care ecosystem capabilities. Mid-scale monitoring specialists with hospital-at-home service model infrastructure represent prime acquisition targets. Watch PMDA approval timeline compression versus EU MDR compliance cost escalation as the inflection signal for geographic production footprint shifts.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Humanitarian Device Exemption Pathway | Accelerates market entry for rare pediatric conditions affecting under 8,000 patients annually. |
| CE Marking Pathway under EU MDR | Imposes extended post-market surveillance obligations that filter smaller manufacturers from European distribution. |
| Hospital System Partnership | Locks in enterprise-wide monitoring platform contracts spanning multi-year service and analytics subscriptions. |
| Software Companion Development | Enables cloud-native analytics integration for hospital-at-home service model expansion. |
| Reimbursement Strategy | Captures United States payer recalibration of cost-of-care models for remote pediatric respiratory management. |
Research Methodology
Multiple input streams — primary interviews with hospital purchasing committee members, biomedical engineers, and GPO contracts managers; secondary validation against FDA 510(k) filings, PMDA approval databases, and hospital procurement records; and trade data reconciliation — were triangulated through bottom-up and top-down approaches. The analysis cross-references manufacturer revenue disclosures with capital expenditure patterns across United States, German, and Japanese children's hospital networks.
Historical shipment data and expert panel input were cross-referenced to build the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, therapy area, end user, and deployment setting alongside regulatory pathway cluster. CAGRs were derived from slope analysis of historical trajectory versus forward-looking procedure volume assumptions and reimbursement framework evolution.
The model assumes a particular technology adoption path; alternative pathways for wearable neonatal monitoring consolidation would alter the outlook. Forecasts reflect assumptions regarding FDA Pediatric Device Consortia program continuity and EU MDR enforcement intensity. Deviation in Japan PMDA review timeline compression would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
BFS Syringes Market
Medical Devices
Smart Syringe Pumps Market
Medical Devices
United States Ultrasound Devices Market
Medical Devices
Kidney Stone Management Devices Market
Medical Devices
Bionic Devices Market
Medical Devices
Wearable Atrial Fibrillation Detection Devices Market
Medical Devices
Global Intraosseous Devices Market
Medical Devices
Radiotherapy Devices Market
Medical Devices
Transport Chairs Market
Medical Devices
Veterinary Equipment and Disposables Market
Medical Devices
Global Implantable Cardiac Monitor Market
Medical Devices
Global Retinoscopes Market
Medical Devices
IVF Time-Lapse Imaging Devices Market
Medical Devices
Subcutaneous Drug Delivery Devices Market
Medical Devices
North America Electrophysiology Market
Medical Devices
Global Hyperbaric Oxygen Therapy (HBOT) Devices Market