
 Medical Pendant Market | 2026-2036
Medical Pendant Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Pendant Market Analysis
Leasing-based procurement for surgical infrastructure is narrowing the competitive field to vendors with balance-sheet depth and service networks. Dräger leverages captive financing arms to lock in multi-year hospital contracts. STERIS anchors its position through integrated operating room packages that bundle pendants with sterilization workflows. Ondal Medical Systems specializes in ceiling supply units for hybrid operating theaters across European health systems.
A medical pendant is a ceiling-mounted articulated arm system that routes medical gases, electrical power, and data communications to clinical workstations, typically supporting loads of 200–600 kg with swivel ranges of 340 degrees. Its primary purpose is to eliminate floor-based clutter in critical care environments while ensuring uninterrupted utility delivery during surgical procedures. Active pendants dominate revenue as they incorporate motorized positioning and integrated monitoring interfaces that command premium placement in tertiary hospitals. Wireless connectivity segments expand fastest as Bluetooth-enabled pendants reduce installation complexity and enable real-time asset tracking within clinical workflow management platforms.
FDA electrical safety standards and EU MDR device classification shape product development cycles and market access requirements for pendant manufacturers serving regulated jurisdictions. IEC 60601-1 third-edition compliance for medical electrical systems forces redesigns of power distribution modules in ceiling supply units. Stakeholders must monitor how evolving cybersecurity frameworks for connected clinical devices reshape certification burdens and procurement criteria for smart pendant systems.
Market Dynamics
Leasing-based procurement for surgical infrastructure concentrates vendor selection around balance-sheet depth and service network density, compressing the competitive field to established capital equipment providers with captive financing capabilities.
Growth Catalysts
- Operating room modernization mandates:Health systems in Germany and China accelerate ceiling supply unit replacements as hybrid theater construction expands surgical throughput capacity.
- FDA electrical safety standards:Stricter enforcement of IEC 60601-1 third-edition compliance forces hospital infrastructure upgrades, creating replacement demand for legacy power distribution modules.
- Wireless connectivity integration:Bluetooth-enabled pendants reduce installation complexity and enable real-time asset tracking within clinical workflow management platforms.
Market Restraints
- Stainless steel and aluminum input volatility:Articulated arm fabrication depends on metal commodity pricing that swings with energy cost fluctuations and trade policy shifts.
- Certification timeline friction:EU MDR device classification extends product registration cycles for ceiling supply units seeking European market access.
- Fixed infrastructure substitution:Wall-mounted gas delivery systems retain cost advantage in smaller surgical suites and ambulatory centers with limited ceiling load capacity.
Strategic Opportunities
- Underpenetrated ambulatory surgical centers:Outpatient facilities in the United States represent whitespace for scaled-down pendant configurations with reduced load ratings.
- Modular retrofit kits:Technology convergence between motorized positioning systems and legacy manual pendants enables upgrade pathways without full infrastructure replacement.
- India PLI scheme for medical devices:Domestic manufacturing incentives attract component suppliers to establish captive production of articulated joints and gas valve assemblies.
Industry Challenges
- Electromechanical technician scarcity:Servicing motorized pendant systems requires specialized training in hydraulic positioning and medical gas plumbing that outpaces vocational program output.
- Legacy operating room integration:New ceiling supply units must interface with decades-old hospital HVAC and electrical infrastructure without triggering full facility recertification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Pendant Market |
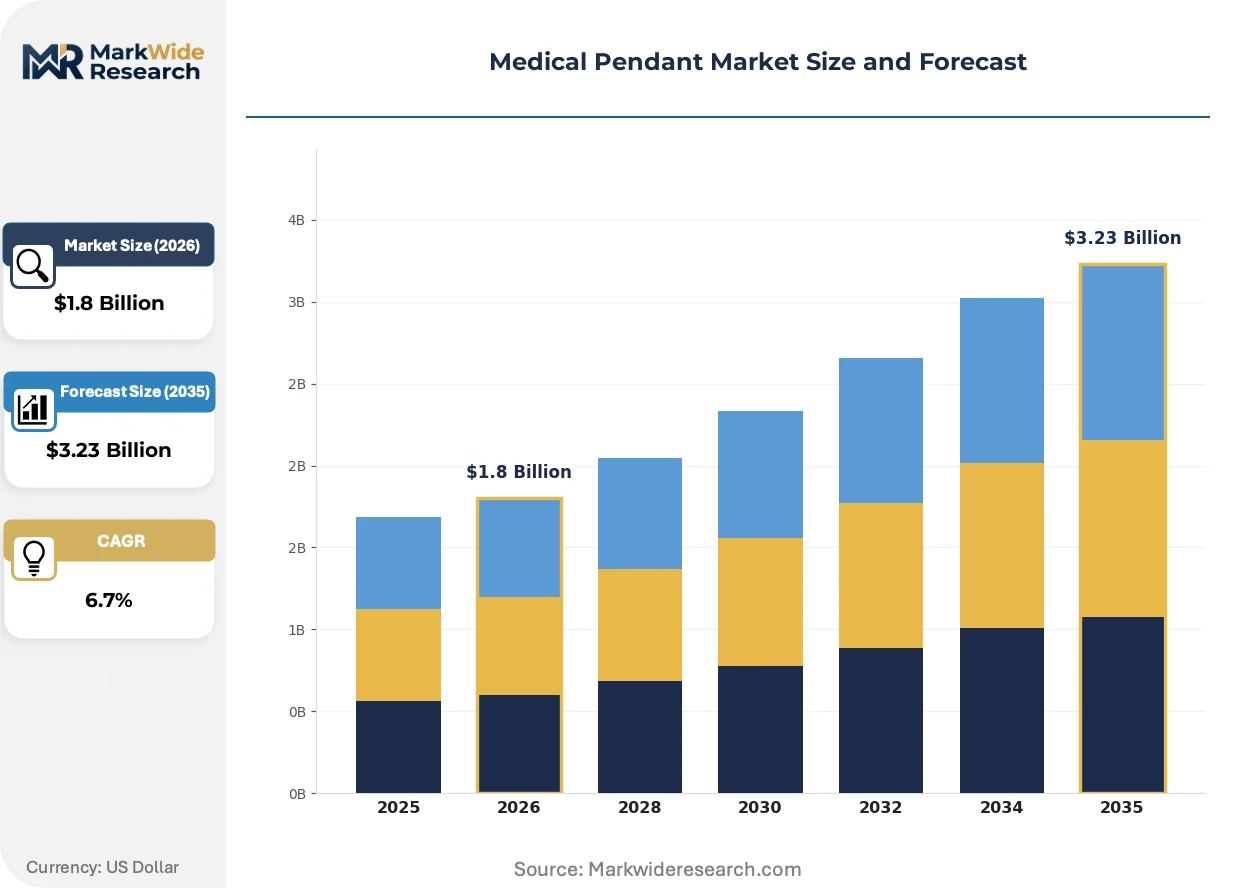
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active, Passive, Wireless, Wired End User: Hospitals, Clinics, Nursing Homes, Home Care Technology: Bluetooth, RF, Infrared, Zigbee Application: Emergency Response, Patient Monitoring, Workflow Management, Communication |
| Companies Covered | Dräger, Mindray, STERIS, Ondal Medical Systems, Heal Force, Brandon Medical, BeaconMedaes, Skytron, Starkstrom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Pendant Market Emerging Trajectories
Digital twin technology and predictive maintenance protocols are reconfiguring how health systems manage ceiling-mounted clinical infrastructure, compressing total cost of ownership calculations and reshaping vendor selection criteria.
Cloud-based pendant monitoring platforms are virtualizing traditional service contracts by enabling remote diagnostics of motorized positioning systems and gas flow sensors. Tertiary hospitals in North America deploy these interfaces to schedule preventive maintenance before mechanical failure disrupts surgical schedules. This virtualization is compressing after-sales revenue models from reactive repair calls toward subscription-based uptime guarantees.
EU MDR Article 10 technical documentation requirements are extending design verification timelines for ceiling supply units seeking CE marking renewal. Manufacturers serving European health systems must demonstrate clinical evidence of electrical safety performance under third-edition IEC standards. Active pendant configurations with integrated monitoring interfaces face heightened scrutiny compared to passive mechanical alternatives.
Hospital procurement departments are unbundling installation and commissioning from equipment purchase, creating standalone service contracts for ceiling infrastructure projects. General contractors and specialized medical gas plumbers now compete directly with original equipment vendors for project margin. This unbundling is most visible in United States health systems pursuing design-build delivery models for operating room expansion projects.
Medical Pendant Market Segmentation
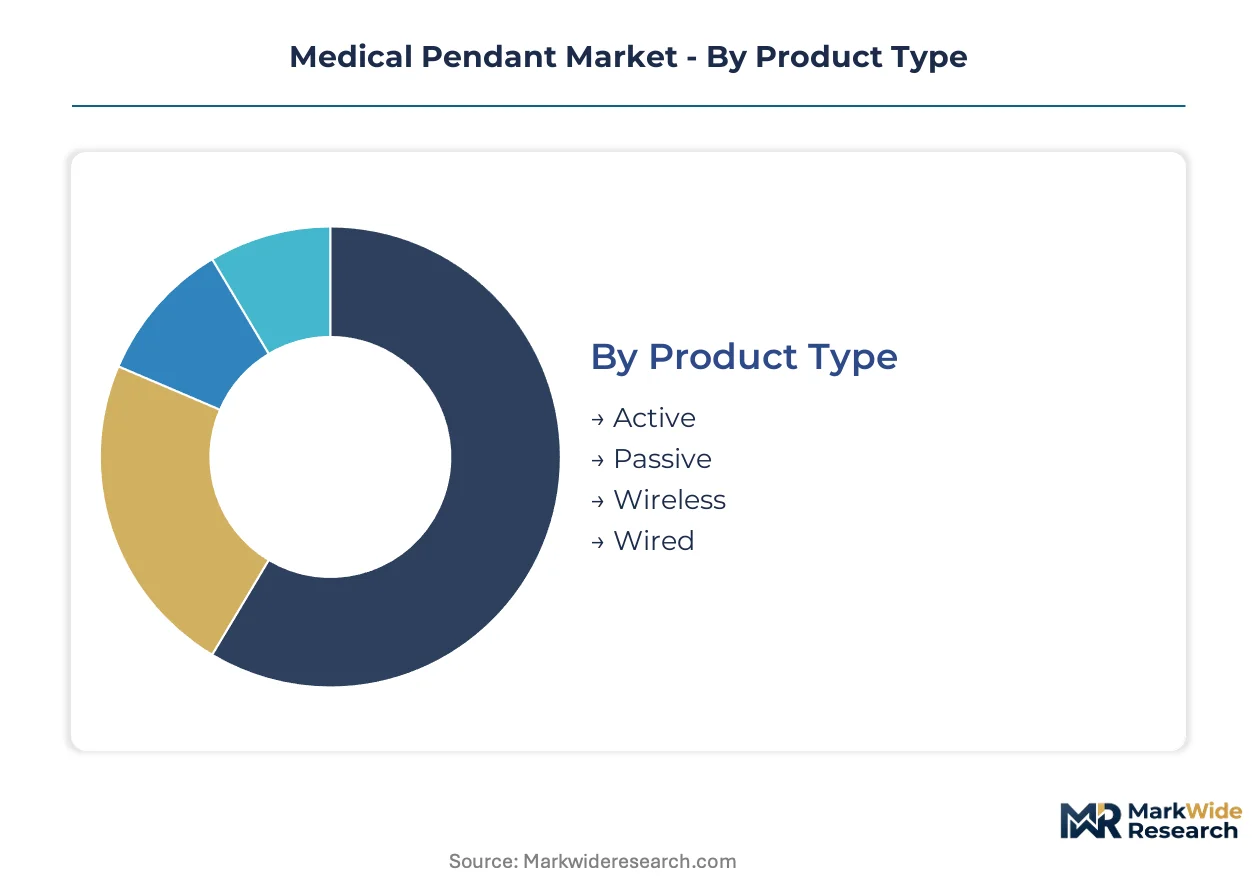
Medical pendant segmentation reveals distinct replacement cycles across product architectures, with motorized systems turning over every 7-10 years while passive mechanical units extend to 15-year lifespans. Technology choices and end-user scale further stratify procurement velocity and vendor engagement models.
Product Type:
Replacement cycles vary dramatically across this category, with active systems demanding capital refresh every decade while passive installations persist through multiple facility renovation cycles.
- Active:Motorized positioning systems with integrated monitoring interfaces command premium placement in tertiary hospitals. German health systems drive concentrated demand as hybrid operating theater construction accelerates ceiling infrastructure modernization.
- Passive:Manual mechanical arms without powered articulation serve cost-constrained surgical suites and ambulatory centers. Smaller Chinese hospitals favor these units where budget limitations restrict capital equipment procurement.
- Wireless:Bluetooth-enabled configurations reduce installation complexity and enable real-time asset tracking within clinical workflow platforms. These systems are climbing the fastest in new construction projects.
- Wired:Traditional hardwired power and data connections persist in legacy facility retrofits where electromagnetic interference concerns dominate infrastructure planning.
Passive pendants dominate installed base across mature health systems. Wireless configurations are where expansion concentrates.
End User:
Facility scale dictates procurement sophistication, with large hospitals deploying integrated ceiling systems while smaller settings prioritize standalone, portable alternatives.
- Hospitals:Multi-disciplinary medical centers with 500+ beds deploy complex pendant arrays supporting 200-600 kg loads across operating theaters, ICUs, and emergency departments. North American tertiary facilities anchor global demand amid stricter electrical safety code enforcement.
- Clinics:Outpatient surgical centers and specialty practices require scaled-down configurations with reduced load ratings and simplified gas delivery specifications.
- Nursing Homes:Long-term care facilities utilize patient lift pendants and basic monitoring systems rather than full surgical infrastructure.
- Home Care:Residential settings deploy lightweight, battery-powered alert systems distinct from institutional ceiling-mounted architectures.
Hospitals capture the dominant share of capital expenditure. Clinics represent the steepest expansion trajectory as ambulatory surgery volume displaces inpatient procedures.
Technology:
Connectivity protocols segment by installation economics and cybersecurity posture, with low-power options gaining traction in retrofit-constrained environments.
- Bluetooth:Short-range wireless standard enables plug-and-play pendant commissioning without structural cable runs. United States health systems prioritize this protocol for rapid deployment in design-build operating room projects.
- RF:Radio frequency systems penetrate physical barriers more effectively than optical alternatives, suiting sprawling hospital campuses with distributed clinical zones.
- Infrared:Line-of-sight dependent technology persists in legacy installations where electromagnetic spectrum congestion limits wireless coexistence.
- Zigbee:Mesh networking protocol supports battery-efficient sensor arrays for environmental monitoring and equipment location tracking.
RF protocols anchor legacy installed base. Bluetooth is gaining share fastest as FDA cybersecurity guidance reshapes procurement criteria for connected clinical devices.
Application:
Functional purpose determines pendant specification complexity, with life-safety applications demanding redundant systems while administrative workflows tolerate single-point failures.
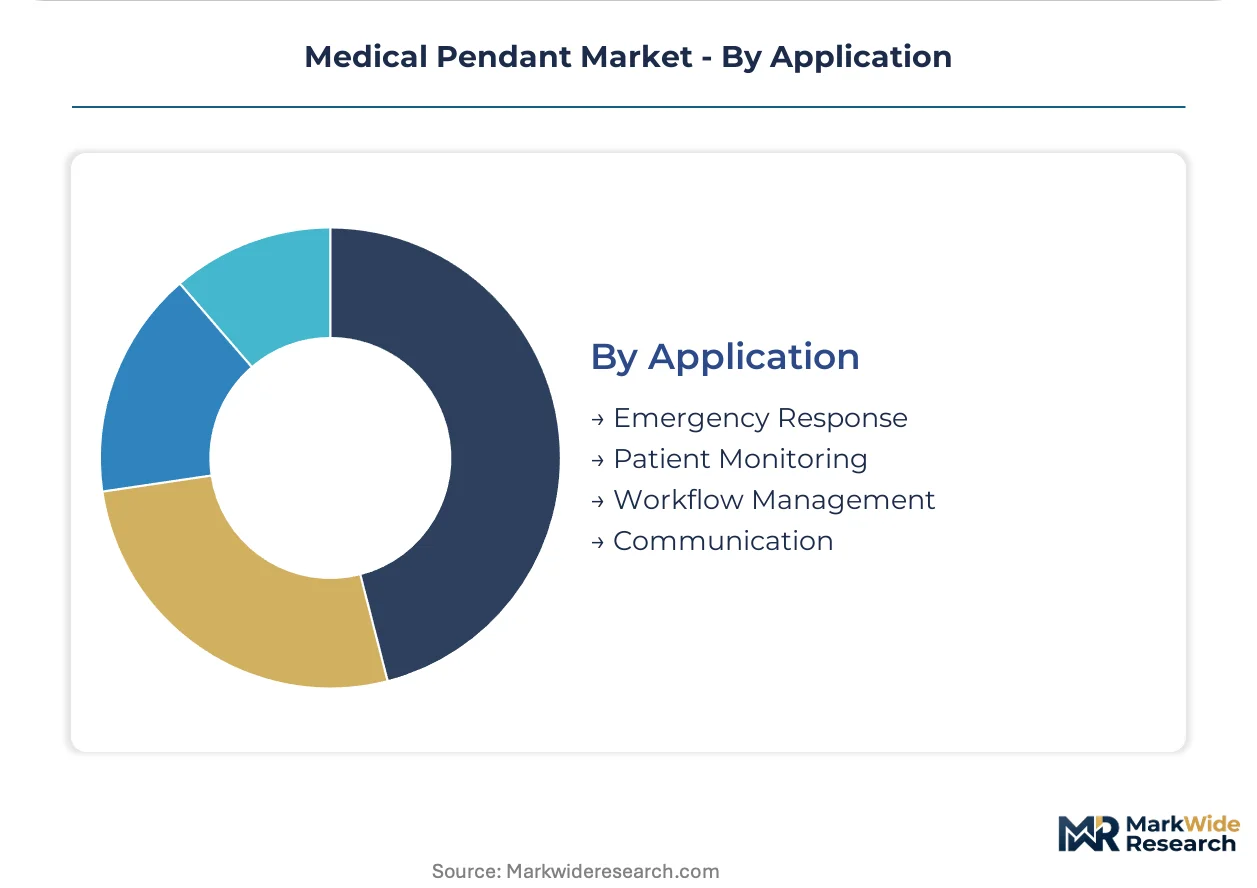
- Emergency Response:Crash cart and resuscitation bay pendants require immediate utility availability with fail-safe power distribution. These systems face the most stringent IEC 60601-1 third-edition compliance verification.
- Patient Monitoring:Continuous physiological surveillance depends on uninterrupted data and electrical connectivity to bedside telemetry arrays.
- Workflow Management:Asset tracking and staff communication systems prioritize wireless flexibility over mechanical load capacity.
- Communication:Nurse call integration and intercom functions represent the lowest-specification tier, often deployed through separate infrastructure from gas-bearing pendants.
Patient monitoring applications dominate current deployment. Emergency response is where specification intensity and replacement urgency concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical pendant trade flows reflect concentrated manufacturing in Germany and China against import-dependent hospital infrastructure upgrades across North America and emerging Asian health systems. Export volumes from European fabricators service Middle Eastern and Latin American modernization programs, while Chinese producers increasingly supply domestic replacement cycles and Southeast Asian expansion projects.
United States
Hospital construction and operating room retrofitting drives pendant procurement across tertiary care networks, with design-build delivery models accelerating ceiling infrastructure deployment. FDA enforcement of IEC 60601-1 third-edition electrical safety standards forces replacement of legacy power distribution modules in aging facilities. The Texas Medical Center in Houston anchors concentrated demand as hybrid theater construction expands surgical throughput capacity across the Gulf Coast health corridor.
Germany
Operating room modernization mandates from regional health ministries accelerate ceiling supply unit replacements in university hospitals and municipal surgical centers. EU MDR device classification and CE marking renewal requirements extend design verification timelines for active pendant configurations with integrated monitoring interfaces. The Rhine-Ruhr metropolitan region concentrates fabrication activity, with Düsseldorf and Cologne hosting specialized electromechanical component suppliers serving European health system procurement.
China
Domestic hospital infrastructure investment and tiered medical institution upgrading programs expand motorized pendant deployment in provincial capitals and prefecture-level cities. NMPA medical device registration requirements and GB standards for medical electrical systems shape product localization strategies for multinational vendors. The Yangtze River Delta region, centered on Shanghai and Suzhou, hosts the densest concentration of pendant assembly operations and articulated joint component manufacturing.
India
Public hospital modernization under the Ayushman Bharat scheme and private hospital chain expansion create replacement demand for ceiling-mounted gas delivery systems in metropolitan surgical centers. The PLI scheme for medical devices attracts component suppliers to establish captive production of gas valve assemblies and motorized positioning modules. Maharashtra and Karnataka anchor procurement concentration, with Mumbai and Bangalore health systems deploying hybrid theater configurations in new specialty hospital construction.
Japan
Aging hospital infrastructure and seismic retrofit requirements drive pendant replacement cycles in tertiary facilities, with METI industrial standards shaping electromechanical safety specifications. PMDA medical device quality management system requirements extend certification timelines for imported active pendant systems. The Kanto region, encompassing Tokyo and surrounding prefectures, concentrates both demand and specialized service technician training programs for motorized ceiling supply unit maintenance.
Medical Pendant Market Vendor Landscape
On the supply side, the industry is consolidating around capital equipment providers with captive financing capabilities and dense service networks, compressing the vendor field from fragmented mechanical fabricators toward integrated surgical infrastructure specialists. Three archetypes dominate: diversified medical technology conglomerates with full operating room portfolios, specialized ceiling supply unit manufacturers with regional installation expertise, and emerging Asian producers leveraging cost-advantaged component sourcing. Competitive intensity centers on multi-year leasing contract capture and aftermarket service contract bundling rather than equipment pricing alone.
Among diversified European-based medical technology groups, Dräger and STERIS exemplify the integrated infrastructure archetype, leveraging balance-sheet depth to lock in hospital contracts through captive financing and bundled sterilization workflow packages. Ondal Medical Systems occupies a specialist position focused on ceiling supply units for hybrid operating theaters, representing the dedicated pendant engineering tier against broader surgical equipment portfolios. These three anchors illustrate how vendor selection criteria have shifted toward total cost-of-ownership calculations and uptime guarantee structures.
| Leading Market Players |
|---|
| Dräger |
| Mindray |
| STERIS |
| Ondal Medical Systems |
| Heal Force |
| Brandon Medical |
| BeaconMedaes |
| Skytron |
| Starkstrom |
| Others |
Supply Flow & Price Mechanics
Undercapacity in German electromechanical component fabrication is compressing supplier margins while elevating pricing leverage for ceiling supply unit assemblers with captive joint production. This utilization asymmetry rewards balance-sheet-heavy vendors who can absorb input volatility through long-term service contracts rather than transactional equipment sales.
Pricing Analysis
Hospital procurement committees anchor a project-based pricing structure where capital equipment purchases unbundle from installation and commissioning contracts. Price differentiation hinges on IEC 60601-1 third-edition certification tier and after-sales uptime guarantee duration. Pricing pressure stems from ambulatory surgical centers demanding scaled-down configurations with reduced load ratings. Small Chinese hospitals exhibit the highest price sensitivity, while North American tertiary facilities prioritize total cost-of-ownership over unit economics.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for motorized positioning module sourcing. Component concentration centers on Germany for precision electromechanical joints, China for aluminum extrusion and gas valve assemblies, and Japan for hydraulic positioning systems. Raw material dependencies draw from stainless steel billet, medical-grade aluminum, and specialized pneumatic tubing. Single-source vulnerability persists in high-torque servo motor supply. Distribution runs through regional medical gas plumbing contractors and specialized hospital infrastructure generalists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through health system consolidation and multi-year leasing contract aggregation, compressing vendor margins while elevating procurement sophistication.
For Market Incumbents: Harden service network density in tertiary hospital corridors to defend against emerging Asian producers with cost-advantaged component sourcing. Deepen backward integration into articulated joint manufacturing to offset stainless steel input volatility. Lock in multi-year uptime guarantee contracts before procurement committees unbundle installation from equipment purchase. For New Entrants and Emerging Players: Ambulatory surgical centers in the United States represent the most penetrable entry point, with outpatient facilities demanding scaled-down pendant configurations absent from incumbent catalogs. India's PLI scheme for medical devices offers tariff-advantaged manufacturing positioning for regional Asian expansion. Pursue design-build contractor partnerships rather than direct hospital sales to bypass established GPO contract barriers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across active pendant configurations with integrated monitoring interfaces, favoring scaled producers over specialized mechanical fabricators. Target acquisition archetypes include regional ceiling supply unit specialists with dense European installation footprints and proprietary motorized positioning IP. Monitor EU MDR Article 10 technical documentation timeline extensions as an inflection signal for European market access difficulty.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compliance accelerates market access for active pendant configurations across German university hospitals. |
| Hospital System Partnership | Multi-year leasing contracts with captive financing lock in replacement cycles and compress competitor field. |
| Backward Integration | In-house production of gas valve assemblies insulates margin from stainless steel commodity swings. |
| Software Companion Development | Cloud-based monitoring platforms virtualize service contracts toward subscription-based uptime guarantees. |
| Reimbursement Strategy | Alignment with CMS outpatient procedure expansion captures ambulatory surgical center procurement velocity. |
Methodological Framework
The analysis maps active pendant systems, passive mechanical configurations, and wireless connectivity segments, each validated through hospital procurement managers, biomedical engineers, GPO contracts managers, and electromechanical service technicians. Primary interviews with surgical infrastructure planners and secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, hospital construction permit records, and trade flow customs data support bottom-up and top-down triangulation.
Forecast assumptions hold fixed regulatory enforcement timelines and metal commodity price bands while varying health system capital expenditure cycles and ambulatory surgery volume displacement rates. Segmentation dimensions span product architecture, end-user facility scale, connectivity protocol, and application functional purpose. CAGRs derive from installed base turnover modeling and replacement cycle compression analysis, with inputs including operating room modernization mandate schedules and IEC standard adoption curves.
Practitioners should monitor EU MDR design verification timeline extensions and NMPA medical device registration backlog shifts for early signals of market access friction. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
US Peripheral Vascular Devices and Accessories Market
Medical Devices
Vaginal Specula Market
Medical Devices
Pipetting Systems Market
Medical Devices
US Medical Sector Contract Electronic Manufacturing Market
Medical Devices
Global Lenses for Myopia Control Market
Medical Devices
Global Brain Monitoring Devices Market
Medical Devices
Global Joint Pain Injections Market
Medical Devices
Prosthetic Disc Nucleus Market
Medical Devices
Neuromodulation Market
Medical Devices
Neuro Navigation System Market
Medical Devices
Global Robotic Wheelchairs Market
Medical Devices
Intravaginal Device Market
Medical Devices
Global Surgical Navigation System Market
Medical Devices
Cervical Dilators Market
Medical Devices
Global Intraoral Cameras Market
Medical Devices
Patient Warming Devices Market