
 US Medical Display Monitors Market | 2026-2036
US Medical Display Monitors Market Size, Share, and Industry Trends Forecast 2026-2036
US Medical Display Monitors Market Intelligence
The US medical display monitors market is decoupling into two distinct strata: premium diagnostic-grade panels certified for grayscale calibration and luminance stability versus commodity surgical displays purchased on price-per-inch. Barco leverages its captive grayscale sensor technology to command premium positioning in radiology reading rooms. EIZO sustains leadership in color-critical ophthalmology applications through factory-level uniformity correction.
Medical display monitors are precision-calibrated visualization devices engineered to meet DICOM Part 14 grayscale standard and luminance thresholds exceeding 500 cd/m² for diagnostic confidence. These instruments render medical images from radiography, endoscopy, and surgical navigation systems with pixel-level accuracy that directly impacts clinical decision quality. LED-backlit LCD panels occupy the dominant installed base due to proven reliability and lower total cost of ownership, while OLED technology is penetrating surgical suites where true black levels enhance tissue differentiation. Diagnostic centers represent the fastest-growing end-user channel as decentralized imaging networks replace centralized hospital radiology departments.
FDA 510(k) clearance requirements and DICOM compliance standards enforced by the agency shape product development timelines and limit market access for uncertified imports. The National Electrical Manufacturers Association maintains the DICOM standard that governs grayscale presentation consistency across display generations. State-level certificate-of-need regulations in Texas and Florida influence capital equipment purchasing cycles for hospital systems. Stakeholders must monitor how AI-assisted diagnostic workflows alter display resolution and color depth requirements beyond current regulatory baselines.
Market Dynamics
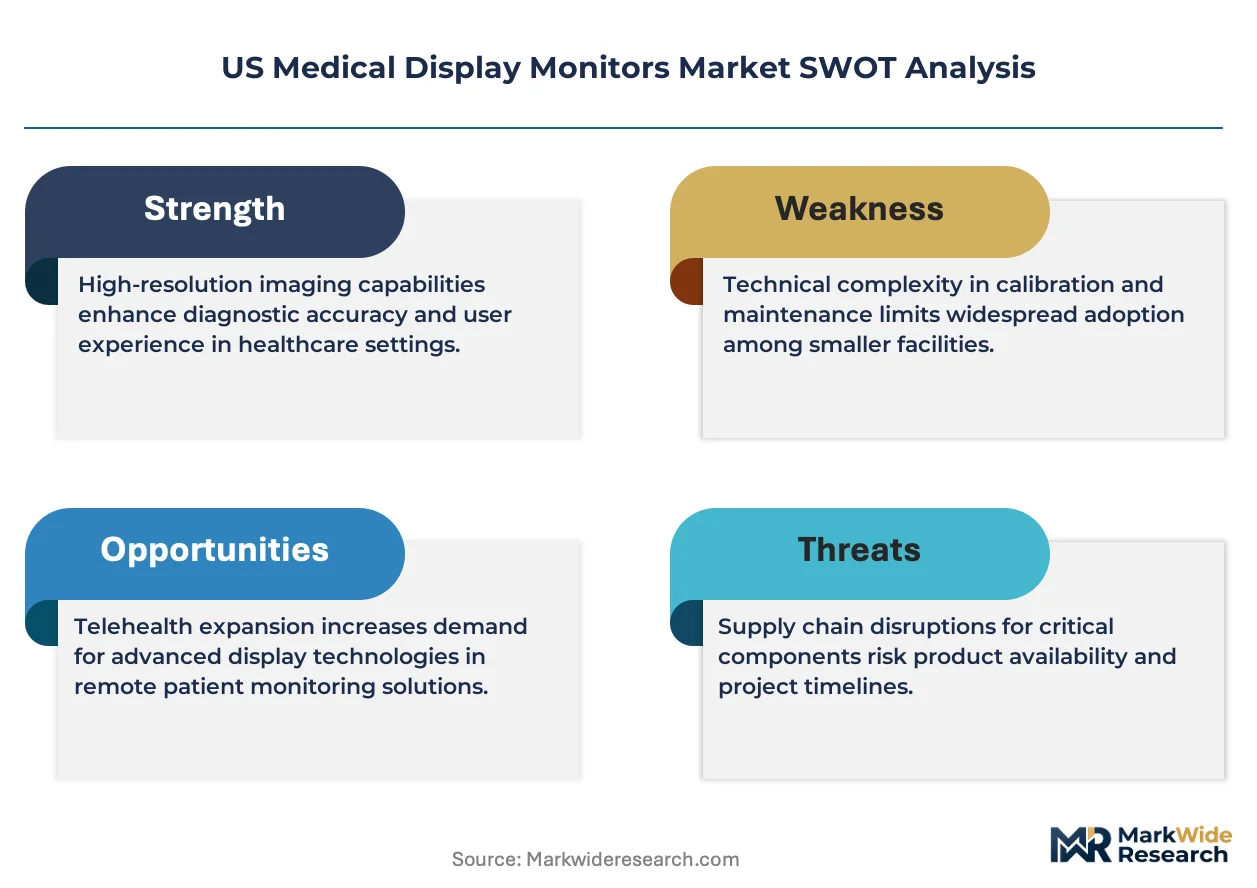
FDA 510(k) clearance timelines for 3D and 4K surgical displays are compressing product refresh cycles while diagnostic centers demand higher luminance stability for AI-assisted radiology workflows.
Growth Catalysts
- Texas certificate-of-need regulations:Hospital system consolidation in Dallas and Houston is triggering bulk procurement of imaging infrastructure.
- 4K surgical modality adoption:Ambulatory surgical centers in Florida are replacing aging HD panels to meet new visualization standards.
- DICOM Part 14 compliance mandates:California's large health systems enforce grayscale calibration protocols that accelerate certified display turnover.
Market Restraints
- Panel supply concentration:Korean and Taiwanese LCD substrate manufacturers control 85% of high-brightness medical-grade panel supply.
- OLED technical limitations:Burn-in susceptibility and luminance decay rates restrict deployment in continuous-use radiology reading rooms.
- FDA clearance friction:510(k) documentation requirements for novel display technologies extend time-to-market by 14-18 months.
Strategic Opportunities
- AI-assisted diagnostic convergence:Integration of machine learning overlays with high-resolution displays creates new product categories for pathology and radiology.
- Arizona imaging hub expansion:Phoenix and Tucson health systems are building decentralized diagnostic networks requiring distributed display deployments.
- Subscription-based calibration services:Remote luminance monitoring and automated DICOM compliance checking unlock recurring revenue streams.
Industry Challenges
- Grayscale calibration expertise scarcity:Qualified biomedical engineering technicians capable of maintaining DICOM compliance are concentrated in coastal metropolitan areas.
- Legacy PACS integration complexity:Newer high-bit-depth displays face compatibility friction with hospital picture archiving systems installed during the 2010-2015 wave.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Medical Display Monitors Market |
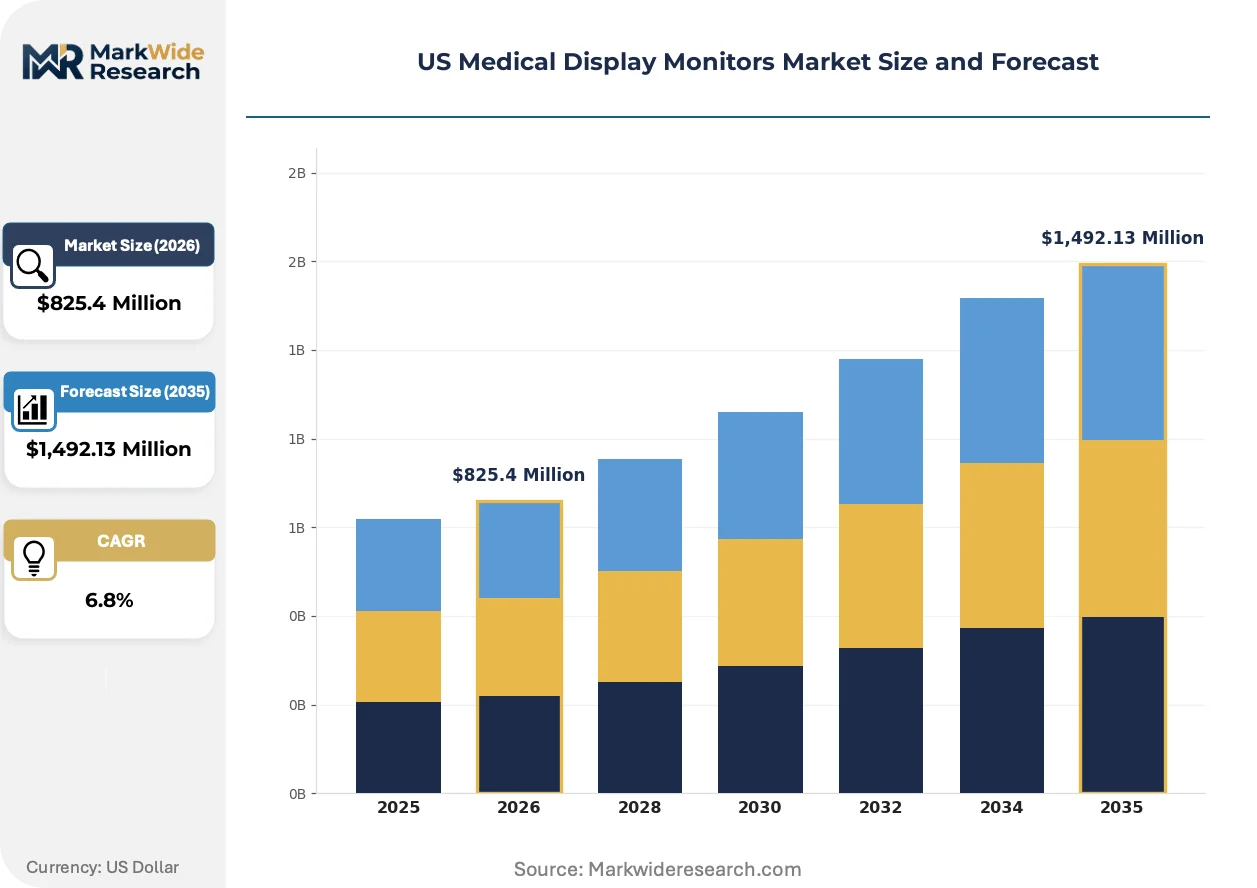
| Market Size in 2026 | $825.4 Million |
| Market Size in 2035 | $1,492.13 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LCD, LED, OLED, CRT Application: Radiology, Surgery, Endoscopy, Ophthalmology End User: Hospitals, Clinics, Research Institutes, Diagnostic Centers Technology: Wireless, Wired, 4K, 3D |
| Companies Covered | Barco, LG Electronics, EIZO, Stryker, Steris, HP Development Company, Sony, Dell Technologies, NEC Display Solutions, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Medical Display Monitors Market Strategic Shifts & Innovations
Display technology evolution and regulatory pathway acceleration are compressing competitive windows while procurement centralization reshapes vendor relationships across US health systems.
Mini-LED backlighting is consolidating control over local dimming zones in diagnostic-grade panels. Texas Medical Center radiology departments are adopting these arrays to achieve contrast ratios exceeding 1,000,000:1 for subtle tissue differentiation. The technology is consolidating premium positioning against conventional edge-lit LCDs by enabling luminance uniformity within 3% deviation across the viewing area.
FDA's evolving 510(k) predicate device framework for 3D surgical displays is shortening clearance timelines for manufacturers with established quality systems. The agency's increased reliance on international standards harmonization reduces redundant testing burdens. California-based surgical device vendors are responding by accelerating 4K modality submissions to capture replacement demand in academic medical centers.
Consolidated procurement through integrated delivery networks is displacing hospital-level purchasing autonomy. Banner Health and Kaiser Permanente are negotiating enterprise-wide display contracts with standardized calibration protocols. This concentration is most visible in the Southwest, where multi-state health systems leverage volume commitments to extract extended warranty and remote monitoring provisions from vendors.
US Medical Display Monitors Market Segmentation
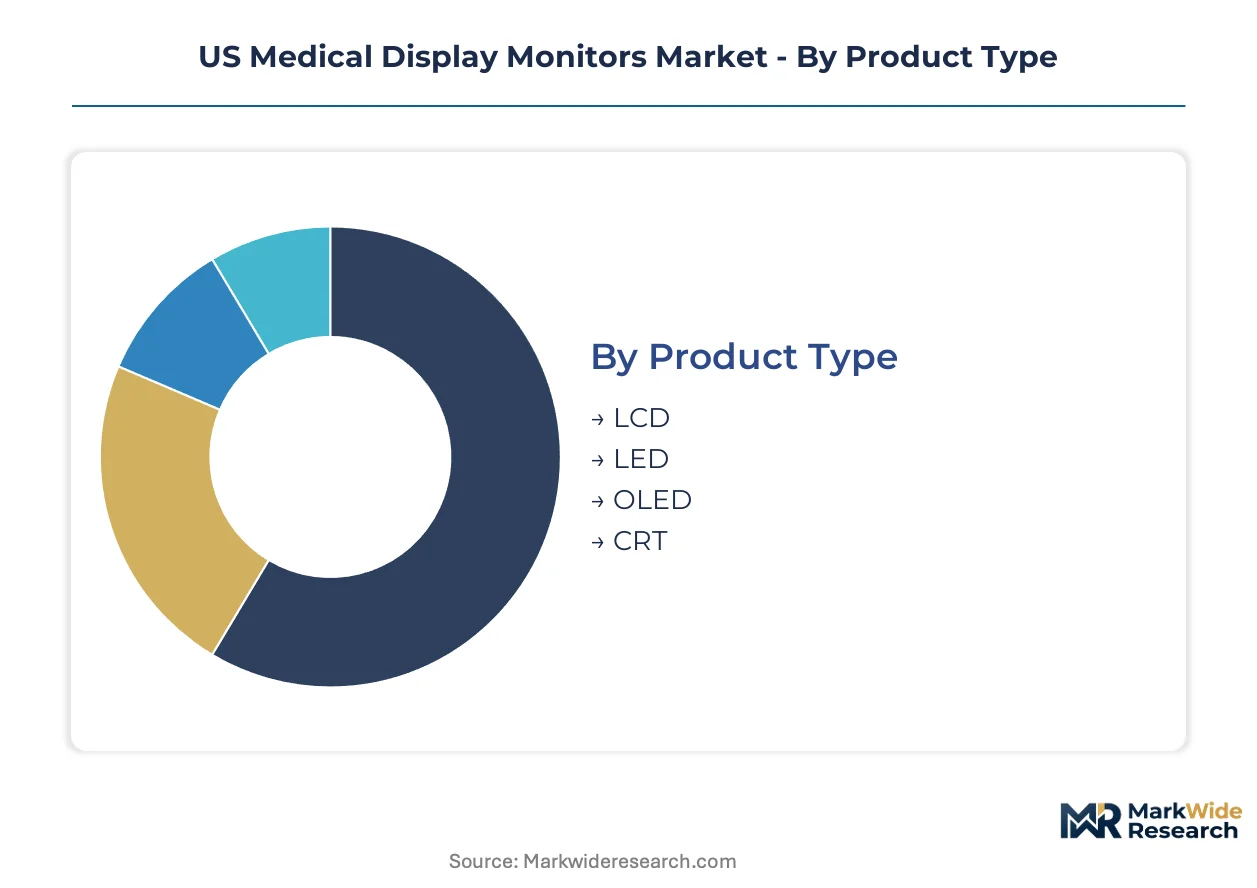
Medical display monitor procurement splits sharply between precision-calibrated diagnostic instruments and volume-oriented surgical panels. Technology selection, application requirements, and end-user infrastructure maturity create distinct purchasing strata with diverging margin profiles and replacement cycles.
Product Type:
Customization intensity varies from commodity LCD assemblies to factory-calibrated OLED stacks requiring individualized luminance mapping.
- LCD:LED-backlit LCD panels dominate installed base through proven reliability and lower total cost of ownership. Texas Medical Center and Kaiser Permanente systems standardize on these for general radiology workstations.
- LED:Edge-lit and full-array LED backlights enable localized dimming for contrast-critical applications. California academic medical centers specify these for pathology and mammography reading rooms where luminance uniformity requirements exceed conventional LCD capability.
- OLED:Self-emissive pixels deliver true black levels and infinite contrast ratios. Deployment concentrates in Florida ambulatory surgical centers where tissue differentiation during endoscopic procedures justifies premium positioning despite burn-in susceptibility concerns.
- CRT:Legacy cathode-ray tube technology persists in isolated budget-constrained settings. Replacement cycles in rural Texas clinics and aging Veterans Affairs facilities represent final phase-out demand.
Most installed capacity flows through LCD. Expansion is steepest in OLED.
Application:
Clinical workflow intensity dictates resolution, color depth, and calibration frequency requirements across use cases.
- Radiology:Grayscale-calibrated panels meeting DICOM Part 14 standards for mammography, CT, and MRI interpretation. FDA 510(k) clearance pathways and AI-assisted diagnostic convergence in California health systems drive certified display turnover.
- Surgery:High-brightness panels with anti-reflective coatings for operating room illumination conditions. Banner Health and Houston Methodist consolidate procurement of 4K surgical displays through enterprise-wide standardization.
- Endoscopy:Compact form factors with rapid response times for gastrointestinal and laparoscopic visualization. Arizona diagnostic hub expansion creates distributed deployment demand across Phoenix and Tucson outpatient networks.
- Ophthalmology:Color-critical panels with factory-level uniformity correction for retinal imaging and surgical microscopy. EIZO maintains segment leadership through specialized calibration protocols.
Radiology commands the premium tier by certification requirement. Surgery shows the steepest volume expansion trajectory.
End User:
Capital allocation authority and infrastructure maturity separate centralized hospital procurement from decentralized diagnostic network purchasing.
- Hospitals:Enterprise-scale deployments with integrated PACS infrastructure and biomedical engineering support. Certificate-of-need regulations in Texas and Florida accelerate consolidation-driven bulk purchasing.
- Clinics:Smaller-scale installations prioritizing cost efficiency over advanced calibration capabilities. Subscription-based remote monitoring services unlock recurring revenue from this price-sensitive segment.
- Research Institutes:Experimental 3D and 4K modality adoption for clinical trial visualization. NIH-funded centers in California and Massachusetts drive early-stage technology validation.
- Diagnostic Centers:Decentralized imaging networks replacing centralized hospital radiology departments. Fastest-growing channel as Arizona, Texas, and Florida health systems build distributed screening infrastructure.
Hospitals retain the largest installed base. Diagnostic centers are gaining share fastest.
Technology:
Connectivity architecture and resolution tiers segment procurement between legacy infrastructure compatibility and next-generation visualization standards.
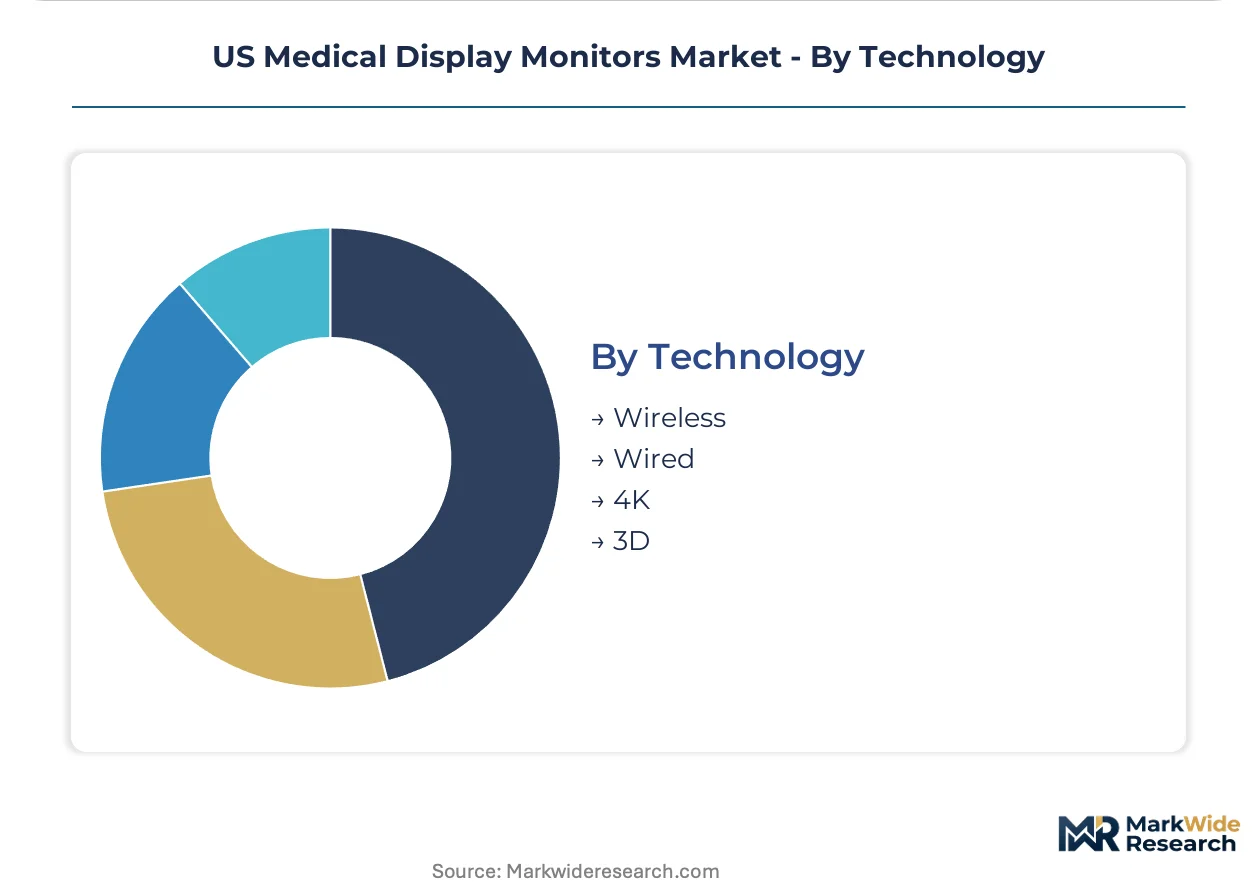
- Wireless:Wi-Fi and proprietary protocols enabling flexible operating room configurations and mobile cart deployments. Surgical suites in Florida ambulatory centers adopt these for rapid room reconfiguration.
- Wired:DVI, DisplayPort, and HDMI connections dominating radiology reading rooms where signal stability and latency sensitivity override flexibility requirements. Legacy PACS integration complexity favors established connectivity standards.
- 4K:Ultra-high-definition panels with 3840×2160 resolution for surgical navigation and pathology. FDA clearance timeline compression for 4K modalities accelerates replacement of aging HD panels in academic medical centers.
- 3D:Stereoscopic displays for surgical planning and interventional guidance. Predicate device framework evolution reduces 510(k) documentation burdens for established manufacturers.
Wired connections dominate radiology infrastructure. 4K resolution shows the steepest adoption curve in surgical applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California health systems outspend Texas facilities on diagnostic-grade displays per capita, while Florida ambulatory networks drive faster surgical panel replacement cycles than Northeast hospital consolidations.
California
Kaiser Permanente and Stanford Health Care enforce DICOM Part 14 calibration protocols that accelerate certified display turnover. FDA 510(k) clearance pathways for 4K modalities concentrate submission activity among Los Angeles and San Francisco device vendors. Silicon Valley imaging AI startups partner with Palo Alto medical centers to validate high-bit-depth visualization requirements.
Texas
Certificate-of-need regulations trigger bulk procurement waves as Houston Methodist and Baylor Scott & White consolidate imaging infrastructure. State-level CON approvals for new diagnostic centers in Dallas-Fort Worth require DICOM-compliant display specifications. Texas Medical Center radiology departments standardize on LED-backlit LCD panels for mammography and CT interpretation workstations.
Florida
Ambulatory surgical centers in Miami and Tampa replace aging HD panels with 4K surgical displays to meet new visualization standards. State health facility licensing rules mandate minimum luminance thresholds for operating room equipment. Orlando health system procurement centralization extracts extended warranty provisions from vendors through volume commitments.
Arizona
Phoenix and Tucson health systems build decentralized diagnostic networks requiring distributed display deployments across outpatient screening sites. Banner Health negotiates enterprise-wide contracts with standardized calibration protocols. Mayo Clinic Arizona anchors precision imaging infrastructure that demands grayscale-calibrated panels for remote radiology interpretation.
New York Metro
Academic medical centers in Manhattan and Long Island drive early-stage 3D modality validation for surgical planning applications. New York State Department of Health facility codes influence capital equipment specifications for hospital construction projects. Memorial Sloan Kettering and NYU Langone consolidate procurement through integrated delivery network structures.
US Medical Display Monitors Market Key Industry Players
Top-tier vendors anchor the diagnostic-grade segment, while price-sensitive surgical display procurement favors scale-driven electronics manufacturers. The market structure splits between precision-calibration specialists and volume-oriented panel assemblers. Strategic archetypes include captive grayscale technology holders, factory-calibration service providers, and diversified electronics conglomerates. Competitive moves center on enterprise contract consolidation and remote monitoring service bundling.
Within the precision-calibration tier, Barco and EIZO exemplify divergent specialization vectors. Barco occupies a position anchored in radiology grayscale sensor technology. EIZO represents factory-level uniformity correction capabilities for color-critical applications. LG Electronics sits within the diversified electronics archetype, leveraging display manufacturing scale across medical and commercial segments.
| Leading Market Players |
|---|
| Barco |
| LG Electronics |
| EIZO |
| Stryker |
| Steris |
| HP Development Company |
| Sony |
| Dell Technologies |
| NEC Display Solutions |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up diagnostic imaging specialists anchor supply discipline through captive calibration service networks, translating DICOM compliance mandates into recurring revenue streams that insulate premium-tier pricing from commodity-panel volatility.
Pricing Analysis
Bundled calibration-as-a-service contracts versus unbundled hardware-only transactions define the pricing architecture. Three-tier pricing structure across FDA-certified diagnostic, surgical-grade, and economy replacement tiers separates enterprise health systems from ambulatory clinics. Price differentiation rests on luminance stability certification and remote monitoring inclusion. Cost compression in economy LCD tiers is intensifying because Korean panel manufacturers are prioritizing automotive and consumer allocations. Clinics exhibit highest price sensitivity; integrated delivery networks accept premium positioning for standardized enterprise protocols.
Supply Chain Analysis
Single-source vulnerability sits with Korean and Taiwanese LCD substrate manufacturers controlling high-brightness medical-grade panel output. Raw material dependencies include indium tin oxide for transparent electrodes, quantum dot phosphors for color gamut extension, and specialized optical films for luminance uniformity. Tariff exposure on Taiwanese semiconductor-grade components presents structural risk. Distribution runs through GPO contracts and direct OEM relationships with health system procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA 510(k) clearance pathway acceleration for 4K surgical modalities compounds replacement demand, positioning the market as a regulatory compounder where compliance investment directly converts to procurement authorization.
For Market Incumbents: To counter OLED burn-in limitations in radiology reading rooms, Barco and EIZO should deepen captive grayscale sensor technology moats while expanding subscription calibration services to clinic-tier buyers. Backward integration into LED backlighting modules secures supply continuity against Korean panel allocation shifts. For New Entrants and Emerging Players: Rural diagnostic centers in Texas and Arizona represent an underserved buyer archetype with fragmented procurement and limited biomedical engineering support. White-space entry points include portable wireless displays for mobile cart deployments and remote DICOM compliance monitoring services sold on per-screen monthly fees. For Investors and Strategic Acquirers: Valuations sit cheapest among factory-calibration service providers lacking enterprise GPO contracts but holding FDA 510(k) predicate device clearances. Long-term viability hinges on AI-assisted diagnostic workflow integration extending display replacement cycles. Watch FDA guidance on 3D surgical display predicates as inflection signal for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Compressed clearance timelines for 4K modalities capture replacement demand in Banner Health and Kaiser Permanente systems. |
| Hospital System Partnership | Enterprise-wide contracts with standardized calibration protocols displace hospital-level purchasing autonomy in Southwest markets. |
| Software Companion Development | AI overlay integration with high-bit-depth panels creates new product categories for pathology and radiology workflows. |
| Reimbursement Strategy | CMS technical fee schedule alignment for AI-assisted diagnostics drives diagnostic center procurement authorization. |
| CE Marking Pathway | International standards harmonization reduces redundant testing burdens for manufacturers with established quality systems. |
Research Approach
Bottom-up diagnostic center deployment modeling reconciled against top-down panel manufacturer shipment tracking forms the analytical core of this study. Primary interviews with hospital purchasing committee chairs, biomedical engineering directors, GPO contracts managers, and radiology department heads combined with secondary validation from FDA 510(k) filings, hospital procurement databases, CMS Medicare reimbursement data, and DICOM standard committee records. Triangulation across stakeholder perspectives and supply-side metrics ensures coverage of both demand authorization and manufacturing constraint dimensions.
Historical trendline analysis of replacement cycle compression and technology substitution patterns informs the projection framework. Segmentation dimensions modeled include product type, application intensity, end-user capital allocation authority, and technology connectivity architecture across the analysis window. CAGR derivation incorporates FDA clearance velocity, certificate-of-need approval timelines, and AI diagnostic workflow penetration assumptions. Forecast inputs include Korean and Taiwanese panel allocation shifts and decentralized diagnostic network buildout rates in Arizona, Texas, and Florida.
Underlying measurement precision varies by segment; diagnostic-grade panel demand carries tighter precision than commodity surgical display forecasts due to DICOM compliance documentation requirements. Forecasts reflect assumptions about FDA predicate device framework evolution and health system consolidation trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Prostate Biopsy Devices Market
Medical Devices
Incubator Devices Market
Medical Devices
Home Sleep Apnea Testing Devices Market
Medical Devices
Cranial Stabilization Devices Market
Medical Devices
Global Stereotactic Surgery Devices Market
Medical Devices
Active Humidifier Devices Market
Medical Devices
Percutaneous Nephrostomy Catheters Market
Medical Devices
Medical Cyclotron Market
Medical Devices
Controlled-Release Drug Delivery Technology Market
Medical Devices
North America Medical Device Regulatory Affairs Market
Medical Devices
Hearing Aid with Lithium-Ion Battery Market
Medical Devices
Global Keratometers Market
Medical Devices
High Volume Dispensing Systems Market
Medical Devices
General Surgical Devices Market
Medical Devices
Pacemaker/Defibrillator Lead Extraction Kits Market
Medical Devices
Medical Smart Glasses Market