
 Concentrator O2 Devices Market | 2026-2036
Concentrator O2 Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Concentrator O2 Devices Market Outlook
A shift from outsourced component procurement to captive manufacturing of compressor assemblies and sieve beds is hardening among established suppliers. Koninklijke Philips N.V. leverages in-house production of precision valves and molecular sieve canisters to protect margin pools on portable units. CAIRE Inc. anchors its position through vertical integration into oxygen sensor calibration and firmware development for altitude-compensating devices. Jiangsu Yuyue Medical Equipment & Supply Co., Ltd. competes on manufacturing scale, operating dedicated assembly lines that supply domestic hospital procurement tenders and export channels simultaneously.
An oxygen concentrator extracts ambient air, compresses it through a molecular sieve bed to separate nitrogen from oxygen, and delivers concentrated oxygen at flow rates typically ranging from 0.5 to 10 liters per minute with purity levels of 87% to 96%. These devices serve patients with chronic obstructive pulmonary disease, interstitial lung disease, and other hypoxemic conditions by replacing heavy cylinder-based oxygen delivery with continuous or pulse-dose supply from a fixed or mobile unit. Portable concentrators are displacing stationary systems in revenue contribution as ambulatory patient protocols expand and battery energy density improves, though stationary units retain volume dominance in institutional settings where high-flow continuous delivery remains non-negotiable. PSA technology occupies the dominant share of installed units due to its reliability at moderate flow rates and lower capital cost relative to cryogenic separation, while membrane separation systems differentiate in niche military and aviation applications where vibration tolerance and rapid start-up matter more than oxygen purity.
FDA 510(k) premarket notification requirements and EU MDR technical documentation obligations shape product development timelines and clinical evidence burdens for manufacturers seeking market access in the United States and Europe. ISO 80601-2-69 standards for oxygen concentrator safety and electromagnetic compatibility testing add compliance layers that favor firms with dedicated regulatory affairs teams and established quality management systems. Japan's PMDA enforces Japan Industrial Standards alignment for electrical medical devices, creating a separate certification track that rewards early entrants with local testing partnerships. Stakeholders must monitor how reimbursement recalibration for home oxygen therapy in Medicare and national health insurance schemes alters patient cost-sharing and provider purchasing incentives.
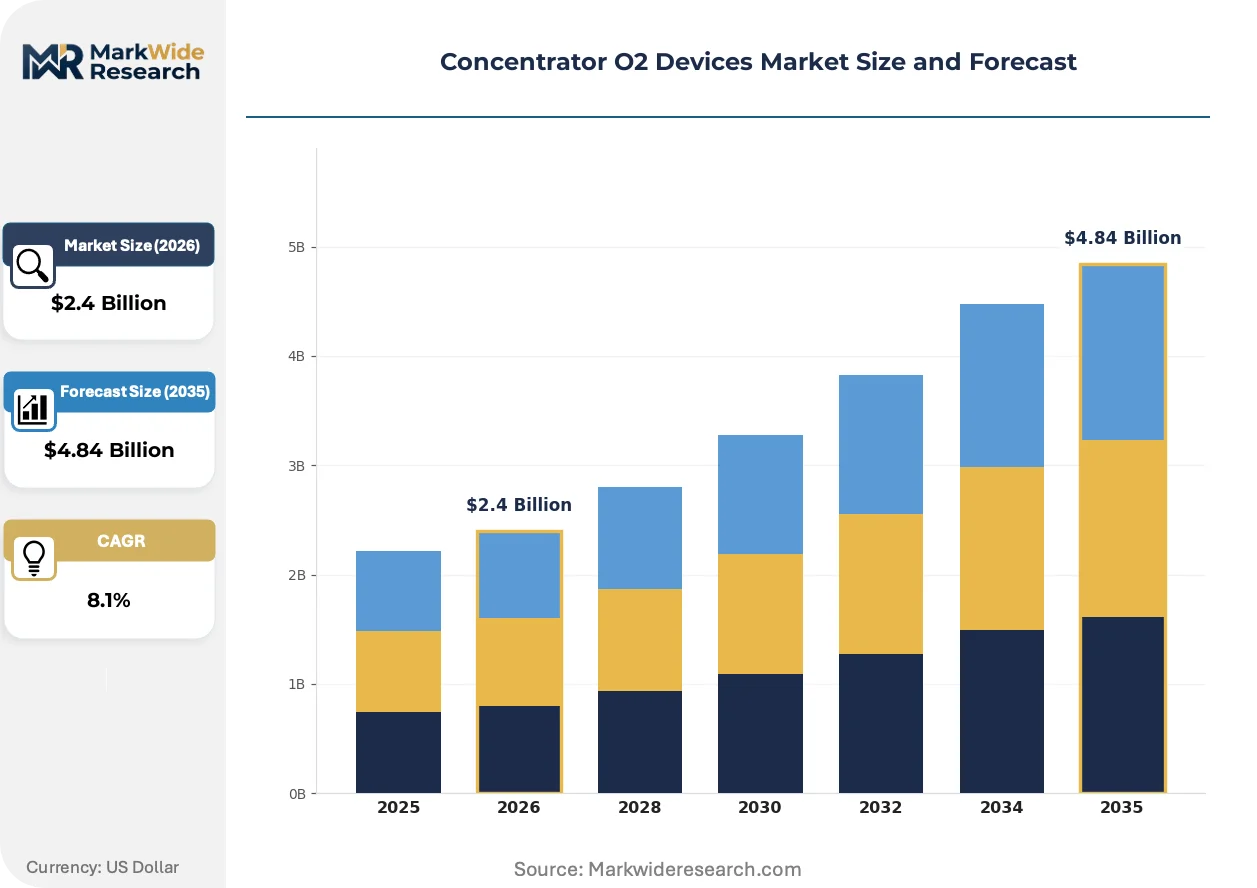
Market Dynamics
Portable oxygen concentrators are compressing replacement cycles for stationary units as ambulatory care protocols expand, forcing suppliers to rebalance R&D portfolios toward battery-optimized pulse-dose systems.
Growth Catalysts
- Medicare home oxygen reimbursement stability:Predictable coverage for long-term oxygen therapy sustains patient access and provider fleet investment in the United States.
- Pressure swing adsorption (PSA) reliability:Mature sieve bed technology lowers service intervals and supports 24/7 continuous operation in institutional settings.
- Japan's PMDA streamlined electrical device pathways:Alignment with JIS standards accelerates market entry for manufacturers with established quality systems.
Market Restraints
- Lithium-ion battery cost volatility:Portable unit margins compress when cell prices spike, squeezing mid-tier suppliers without captive cell sourcing.
- EU MDR technical documentation burdens:Clinical evidence requirements for pulse-dose delivery systems extend approval timelines and raise compliance costs.
- Cryogenic oxygen substitution in high-flow settings:Liquid oxygen systems retain cost advantages for patients requiring above-10-liters-per-minute continuous delivery.
Strategic Opportunities
- India's hospital procurement modernization:Centralized tendering under the Ayushman Bharat scheme creates volume consolidation for qualified suppliers.
- Altitude-compensating firmware convergence:Integration of barometric pressure sensors with pulse-dose algorithms enables portable use in mountainous regions.
- Direct-to-patient subscription channels:Bypassing durable medical equipment distributors captures margin and builds recurring revenue relationships.
Industry Challenges
- ISO 80601-2-69 electromagnetic compatibility testing:Specialized chamber facilities and protocol expertise create bottlenecks for smaller manufacturers.
- Molecular sieve bed regeneration chemistry:Zeolite degradation modeling requires materials science talent scarce outside established industrial gas firms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Concentrator O2 Devices Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.84 Billion |
| CAGR (2026 – 2036) | 8.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Stationary, Liquid, Other End User: Hospitals, Homecare, Rehabilitation Centers, Long-term Care Facilities Technology: PSA, Membrane Separation, Cryogenic, Others Distribution Channel: Direct Sales, Retail, Online, Distributors |
| Companies Covered | Koninklijke Philips N.V., Inogen, Inc., CAIRE Inc., Drive DeVilbiss Healthcare, Invacare Corporation, ResMed Inc., Chart Industries, Inc., React Health, Jiangsu Yuyue Medical Equipment & Supply Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Concentrator O2 Devices Market Strategic Shifts
Solid-state oxygen sensing and adaptive pulse-dose algorithms are redefining device intelligence, while regulatory harmonization pressures and ambulatory care expansion reshape competitive requirements across manufacturing and distribution.
Solid-state electrochemical sensors are integrating into portable concentrator feedback loops to replace galvanic cell oxygen analyzers. Homecare providers in Germany and Japan are specifying these sensors in fleet refresh tenders to reduce calibration labor. The technology is integrating real-time purity verification with altitude compensation, compressing the performance gap between stationary and portable platforms.
EU MDR post-market surveillance obligations are tightening adverse event reporting timelines for oxygen concentrator manufacturers. Technical documentation must now include clinical performance data for pulse-dose modes, extending product development cycles. Class IIa device re-certification is absorbing disproportionate resources at firms with legacy 93/42/EEC approvals, advantaging entrants who built MDR-compliant systems from inception.
Hospital procurement consortia are consolidating oxygen therapy device purchasing across integrated delivery networks. Group purchasing organizations in the United States are unbundling device acquisition from maintenance contracts, forcing manufacturers to price service separately. This behavior is most visible in the southeastern states, where regional health systems are centralizing respiratory equipment standardization.
Concentrator O2 Devices Market Segmentation
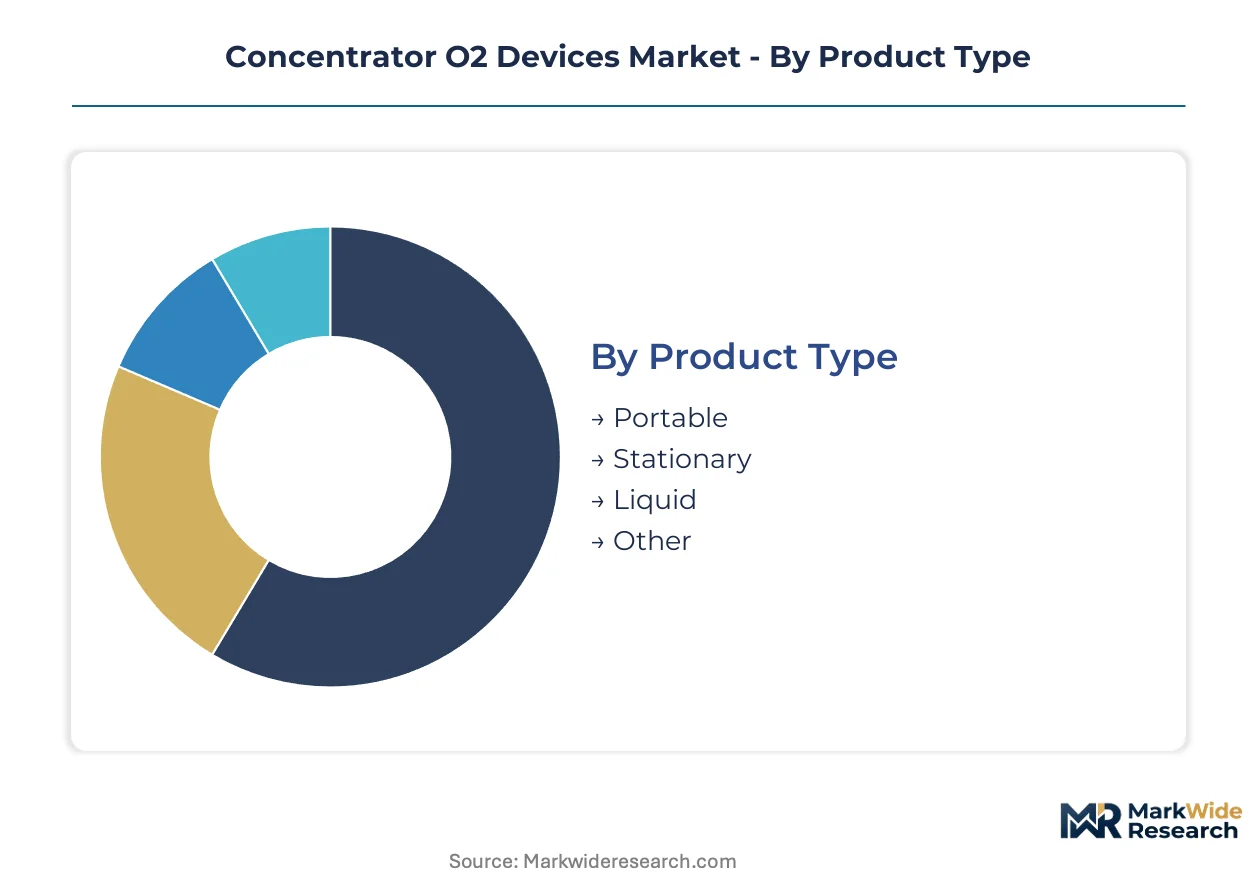
Concentrator O2 Devices Market segmentation reveals divergent upgrade cycles across mobility classes and care settings. Replacement priorities shift between institutional bulk procurement and individual patient ambulatory needs, reshaping supplier portfolio allocations.
Product Type:
Upgrade cycles vary sharply between stationary infrastructure and portable fleet refreshes, with battery chemistry improvements accelerating replacement timelines for mobile units.
- Portable:Battery-optimized pulse-dose systems now achieve 8-hour operation on single charge cycles. Demand concentrates among Medicare home oxygen beneficiaries in the United States seeking ambulatory independence; FAA portable oxygen device approvals for commercial aviation expand addressable use cases.
- Stationary:Continuous-flow systems delivering 5-10 liters per minute remain the institutional default for high-acuity hypoxemia. Hospital procurement in Germany and Japan favors 10-year service life specifications; PSA sieve bed degradation drives predictable replacement scheduling.
- Liquid:Cryogenic reservoir systems serve patients above 10 LPM continuous demand where concentrator economics fail. Homecare providers in mountainous regions of Japan maintain liquid backup for altitude-compromised concentrator output.
- Other:Transfill systems and hybrid concentrator-reservoir combinations address niche high-flow ambulatory requirements. Military aviation applications specify rapid-start membrane alternatives.
Volume placements concentrate in Stationary systems; the faster expansion belongs to Portable.
End User:
Cost tier differentiation separates capital-intensive institutional procurement from patient-directed homecare acquisition, with reimbursement mechanisms governing access thresholds.
- Hospitals:Integrated delivery networks standardize on single-vendor fleet contracts covering stationary and portable units. Group purchasing organizations in the southeastern United States unbundle device acquisition from preventive maintenance agreements.
- Homecare:Durable medical equipment suppliers manage Medicare oxygen therapy reimbursement flows, absorbing patient cost-sharing risk. Direct-to-patient subscription channels are emerging to capture distributor margins.
- Rehabilitation Centers:Transitional care facilities require portable-dominant fleets supporting patient mobility during pulmonary recovery protocols.
- Long-term Care Facilities:Nursing home operators prioritize stationary units with centralized alarm monitoring; staffing shortages drive demand for low-maintenance PSA systems.
Procurement scale peaks in Hospitals; the steepest expansion trajectory is Homecare.
Technology:
Application requirements dictate technology selection, with flow rate demands and purity tolerances filtering available separation methods.
- PSA:Zeolite molecular sieve beds adsorb nitrogen under pressure swing cycles, delivering 87-96% oxygen purity at 0.5-10 LPM. Institutional demand in the United States and Germany favors PSA reliability; sieve bed regeneration chemistry extends service intervals to 20,000+ hours.
- Membrane Separation:Polymeric fiber bundles separate oxygen by differential permeation, trading purity for vibration tolerance and instant startup. Aviation and military specifications in Japan prioritize membrane systems for helicopter medevac roles.
- Cryogenic:Liquid oxygen production via air liquefaction and fractional distillation serves centralized supply hubs. High-flow home patients above 10 LPM continuous demand retain liquid cost advantages.
- Others:Electrochemical and chemical oxygen generation systems occupy emergency backup niches. Chemical oxygen generators serve aircraft emergency descent protocols.
Installed base dominance rests with PSA; membrane systems are gaining share fastest in specialized mobility applications.
Distribution Channel:
Customer type and geography determine channel selection, with regulatory compliance burdens filtering participant eligibility.
- Direct Sales:Manufacturers contract directly with hospital procurement consortia and integrated delivery networks. EU MDR technical documentation requirements favor established suppliers with dedicated regulatory affairs teams.
- Retail:Pharmacy chains and medical equipment storefronts serve cash-pay portable concentrator demand. India's Ayushman Bharat scheme is consolidating tender volumes toward qualified direct suppliers.
- Online:E-commerce platforms facilitate patient-directed portable unit purchases outside reimbursement channels. FDA 510(k) clearance status becomes a visible differentiator in search-filtered selection.
- Distributors:Regional durable medical equipment networks manage Medicare billing complexity and patient training obligations. Distributor margins compress as manufacturers build direct-to-patient subscription capabilities.
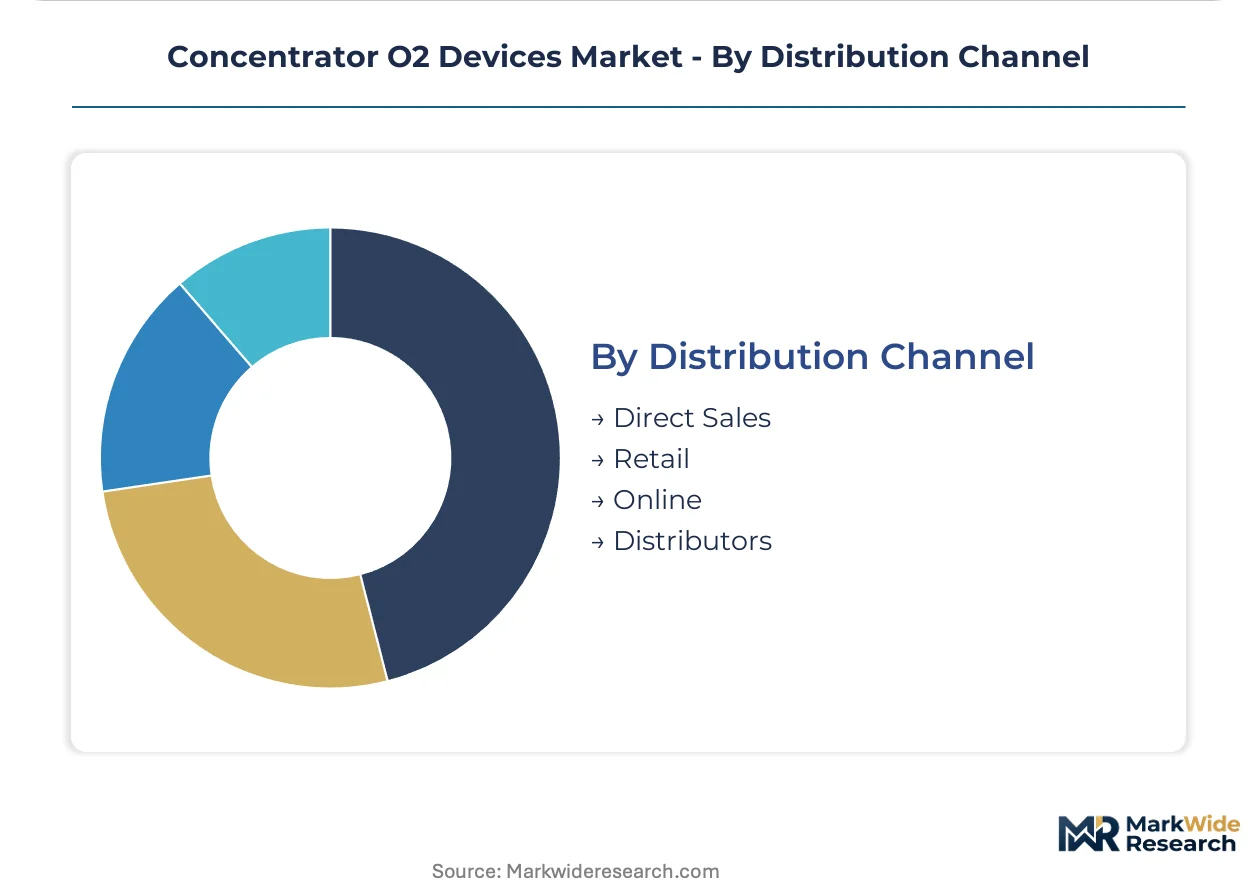
Transaction volume flows through Distributors; Online channels are climbing the fastest as patient self-direction increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zeolite mining clusters in Wyoming and Colorado supply molecular sieve beds to concentrator manufacturers worldwide. Japan's precision valve fabrication centers and Germany's compressor assembly corridors anchor component sourcing for premium portable units. Patient reimbursement stability and regulatory harmonization determine where device deployment accelerates fastest.
United States
Medicare's long-term oxygen therapy reimbursement sustains fleet replacement cycles among homecare providers. FDA 510(k) clearance pathways enforce electromagnetic compatibility standards under ISO 80601-2-69. Minneapolis-St. Paul hosts concentrator distributors managing Medicare billing complexity across the upper Midwest.
Germany
Hospital procurement consortia standardize on 10-year service life specifications for PSA stationary systems. EU MDR technical documentation obligations extend approval timelines for pulse-dose delivery modes. Baden-Württemberg's industrial gas equipment corridor supplies precision compressor assemblies to portable unit manufacturers.
Japan
Aging demographics drive replacement demand for altitude-compensating portable devices in mountainous prefectures. PMDA enforces JIS standard alignment for electrical medical device certification. Osaka-Kobe's medical equipment cluster specializes in oxygen sensor calibration and firmware development.
India
Ayushman Bharat centralized tendering consolidates hospital procurement volumes for qualified suppliers. CDSCO medical device rules tighten import registration requirements for oxygen concentrators. Gujarat's medical device manufacturing zone operates dedicated assembly lines serving domestic tenders and export channels.
China
Hospital procurement modernization under healthcare infrastructure expansion drives stationary unit demand. NMPA oversees Class II medical device registration for oxygen concentrators. Jiangsu province's precision manufacturing corridor produces compressor valves and sieve bed canisters for domestic and export markets.
Concentrator O2 Devices Market Competitive Environment
Global majors compete with regional champions across regulatory compliance capabilities and manufacturing scale. The vendor base stratifies into three tiers: diversified health technology conglomerates with captive component production, mid-scale specialists concentrating on portable pulse-dose innovation, and regional fabricators competing on tender pricing. Dominant competitive moves include backward integration into molecular sieve supply and direct-to-patient subscription channel development bypassing traditional distributors.
Within the diversified health technology tier, Koninklijke Philips N.V. and ResMed Inc. exemplify archetypes combining regulatory affairs depth with multi-product respiratory portfolios. CAIRE Inc. anchors the specialist segment with vertical control over oxygen sensor calibration and altitude-compensating firmware. Jiangsu Yuyue Medical Equipment & Supply Co., Ltd. represents the scale-driven regional fabricator archetype, operating dedicated assembly lines that simultaneously supply domestic hospital tenders and export channels.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| Inogen, Inc. |
| CAIRE Inc. |
| Drive DeVilbiss Healthcare |
| Invacare Corporation |
| ResMed Inc. |
| Chart Industries, Inc. |
| React Health |
| Jiangsu Yuyue Medical Equipment & Supply Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Lithium carbonate price volatility cascades through concentrator manufacturing, compressing margins on portable units with high battery content while amplifying cost advantages for stationary PSA systems with minimal electronic components.
Pricing Analysis
Warranty and preventive maintenance bundling separates premium supplier contracts from unbundled transactional sales. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance status, ISO 80601-2-69 certification tier, and captive sieve bed production. Cost compression in mid-tier portable units intensifies because lithium-ion cell sourcing lacks vertical integration. Homecare providers absorbing Medicare reimbursement risk exhibit highest price sensitivity; hospital procurement consortia with 10-year service life specifications show lowest.
Supply Chain Analysis
Dual-sourcing mandates from hospital procurement consortia force qualification of backup zeolite molecular sieve suppliers in Wyoming and Colorado alongside primary Chinese sources. Compressor valve assemblies draw from Baden-Württemberg's precision engineering corridor and Osaka-Kobe's medical equipment cluster. Single-source vulnerability concentrates in lithium-ion battery cells from East Asian manufacturers. Distribution runs through durable medical equipment networks managing Medicare billing complexity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around regulatory compliance capabilities, with EU MDR technical documentation burdens and FDA 510(k) clearance pathways forcing sub-scale fabricators toward exit or acquisition.
For Market Incumbents: Hedge against lithium cost volatility through captive battery pack assembly partnerships and long-term cell offtake agreements. Deepen backward integration into molecular sieve regeneration chemistry to protect margin pools from zeolite price swings. Reinforce hospital procurement consortia relationships by unbundling device acquisition from maintenance pricing.
For New Entrants and Emerging Players: Enter via India's Ayushman Bharat centralized tendering, where qualification requirements favor manufacturing scale over legacy brand presence. Target altitude-compensating portable firmware for mountainous prefectures in Japan, where PMDA pathways reward early entrants with local testing partnerships. Pursue direct-to-patient subscription channels bypassing distributor margin capture.
For Investors and Strategic Acquirers: The window for entry favors mid-scale specialists with vertical control over oxygen sensor calibration and firmware development. Long-term viability hinges on reimbursement stability in Medicare and national health insurance schemes. Watch for recalibration of home oxygen therapy payment rates as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates market access for pulse-dose delivery systems in Medicare reimbursement channels. |
| CE Marking Pathway | MDR technical documentation compliance extends timelines but locks out non-compliant competitors. |
| Hospital System Partnership | Integrated delivery network fleet contracts secure volume commitments across stationary and portable units. |
| Software Companion Development | Altitude-compensating firmware with barometric pressure sensors enables mountainous region penetration. |
| Reimbursement Strategy | Medicare oxygen therapy coverage stability determines patient access and provider fleet investment cycles. |
Study Parameters
Independent corroboration across regulatory filings, hospital procurement databases, and CMS Medicare data underwrites the qualitative findings. Primary interviews with biomedical engineers, GPO contracts managers, homecare provider procurement leads, and FDA regulatory affairs specialists combined with secondary validation from FDA 510(k) clearances, EU MDR technical documentation, and ISO 80601-2-69 test reports. Bottom-up and top-down triangulation anchored volume estimates.
Comparable historical replacement cycles for stationary PSA systems and portable pulse-dose units anchored the forecast window. The analytical framework modeled mobility class, technology type, end-user setting, and reimbursement channel segmentation throughout the forecast period. CAGRs derived from installed base turnover rates, battery chemistry improvement curves, and ambulatory care protocol expansion trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under lithium-ion commodity price spikes and reimbursement recalibration events. Deviation in Medicare home oxygen therapy payment rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Ovulation Microscope Market
Medical Devices
Penile Implants Market
Medical Devices
Brazil Angioplasty Devices Market
Medical Devices
Drug Delivery Devices Market
Medical Devices
Global Artificial Organ and Bionic Implants Market
Medical Devices
Cardioscope Market
Medical Devices
Specimen Retrieval Nets Market
Medical Devices
North America Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Steam Inhaler Devices Market
Medical Devices
Oxygenator Market
Medical Devices
Global Traumatic Brain Injury Assessment and Management Devices Market
Medical Devices
Global Capillary Blood Collection Devices Market
Medical Devices
Artificial Retina Market
Medical Devices
Global Tumor Tracking Systems Market
Medical Devices
Global Self-Injection Device Market
Medical Devices
Saudi Arabia Artificial Organs and Bionic Implants Market