
 Digital Impression System Market | 2026-2036
Digital Impression System Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Impression System Market Intelligence
Subscription-based software platforms are realigning the value proposition beyond initial hardware sales, favoring companies with strong digital ecosystems. Align Technology, Inc. leverages its integrated system for its dominant clear aligner business. The Straumann Group competes by offering a broad portfolio of both scanners and downstream restorative solutions. 3Shape A/S differentiates through its open architecture software, which appeals to dental professionals seeking flexibility in their clinical workflows.
A digital impression system is a medical device that captures the three-dimensional topography of intraoral structures, including teeth and gingiva. These systems use technologies like structured light or laser scanning to generate a digital model with micron-level accuracy. Intraoral scanners represent the core hardware component and highest value segment. Within applications, orthodontics and implantology drive volume, demanding high precision for treatment planning and surgical guide fabrication.
Market access is contingent on navigating stringent medical device regulations. Manufacturers must secure clearance from bodies like the US Food and Drug Administration (FDA) and obtain CE marking under the Medical Device Regulation (MDR) in Europe. Compliance with China's National Medical Products Administration (NMPA) is also critical for market entry. The key decision for vendors revolves around balancing proprietary, closed ecosystems against open-architecture strategies to maximize adoption.
Market Dynamics
The central force shaping the market is the strategic divergence between open-architecture software platforms and closed, vertically integrated ecosystems. This competition dictates technology adoption pathways, workflow flexibility, and long-term vendor-customer relationships within specialized dental practices across the United States and Europe.
Growth Catalysts
- AI in Treatment Planning:The integration of artificial intelligence algorithms into CAD software enhances diagnostic accuracy and automates treatment planning for orthodontics and implantology, improving clinical efficiency and outcomes.
- Clear Aligner Demand:Strong patient preference for clear aligners, particularly in the United States, necessitates the high-precision digital impressions that intraoral scanners provide, directly fueling scanner sales into orthodontic clinics.
- Specialized Clinic Expansion:A rising number of dental practices specializing in high-value procedures like implantology and cosmetic dentistry are investing in digital workflows to improve precision, reduce chair time, and enhance the patient experience.
Market Restraints
- High Initial Investment:The significant upfront capital cost for intraoral scanner hardware and associated software licenses remains a substantial barrier for smaller, independent dental practices and clinics in developing economies.
- Regulatory Compliance Hurdles:Navigating the stringent and often lengthy clearance processes of regulatory bodies, such as the FDA in the US and obtaining CE marking under MDR in Europe, delays market entry for new devices.
- Interoperability Issues:In open-architecture systems, dental professionals can face technical challenges with data compatibility and workflow integration between scanners and third-party CAD/CAM software or milling machines.
Strategic Opportunities
- Teledentistry Integration:Incorporating intraoral scanners into teledentistry platforms enables remote patient monitoring and consultation for orthodontic treatments, opening a new service delivery model for dental practices.
- Emerging Market Penetration:Dental markets in Brazil and India, characterized by a growing middle class and increasing investment in private healthcare infrastructure, represent significant untapped geographies for scanner adoption.
- Portable and Wireless Devices:Development of more compact, lightweight, and wireless intraoral scanners can expand usage into multi-operatory clinics, mobile dentistry, and educational institutions by improving ease of use and flexibility.
Industry Challenges
- Digital Workflow Training:A skills gap exists among dental assistants and technicians, requiring significant training and education from manufacturers to ensure effective and consistent use of digital impression systems and associated software.
- Data Management and Security:Managing large 3D scan files and ensuring their secure storage and transmission in compliance with patient data privacy regulations like HIPAA presents a significant operational and IT challenge for dental clinics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Impression System Market |
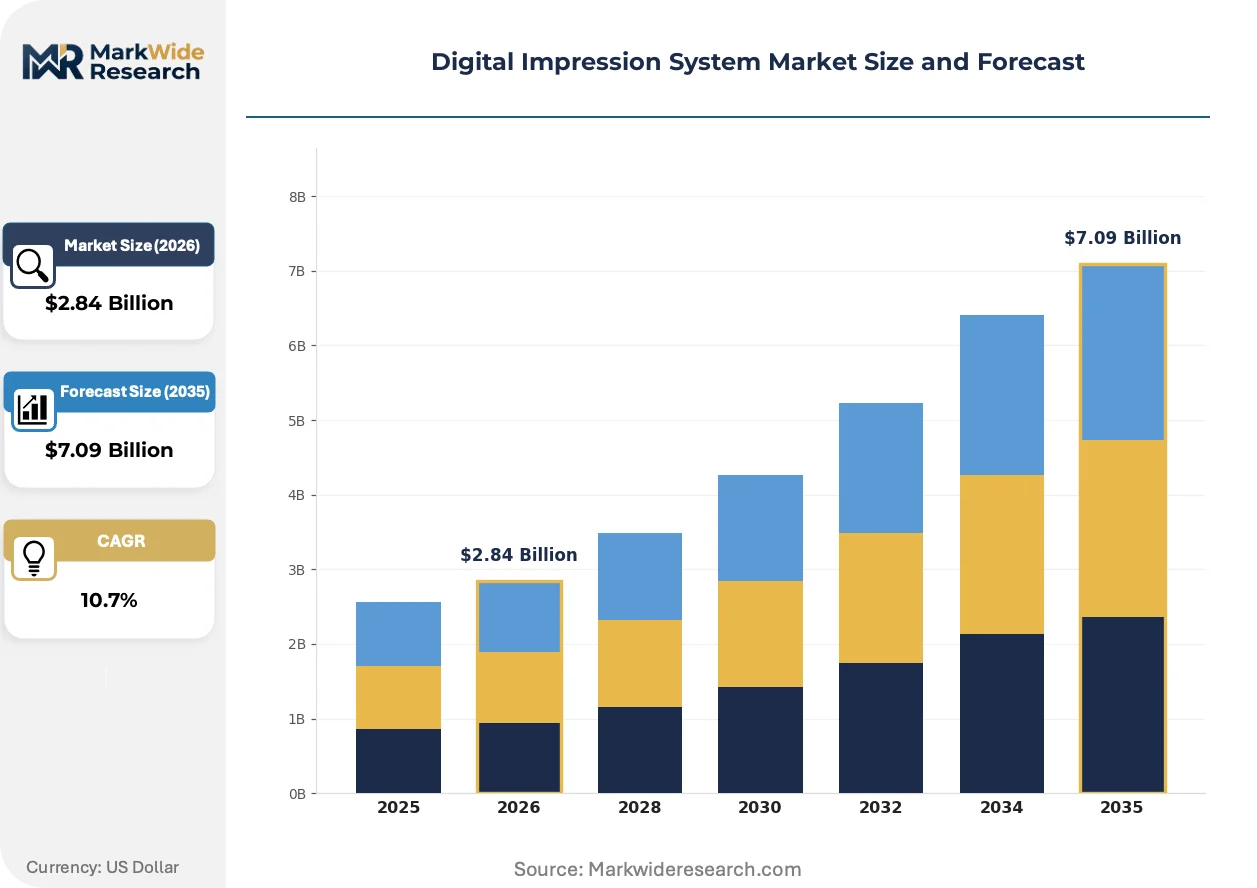
| Market Size in 2026 | $2.84 Billion |
| Market Size in 2035 | $7.09 Billion |
| CAGR (2026 – 2036) | 10.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intraoral Scanners, Desktop Scanners, Impression Trays, Software Platforms, Accessories Technology: Optical Scanning, Laser Scanning, Photogrammetry, Structured Light, Blue Light Technology Application: Orthodontics, Prosthodontics, Oral Surgery, Implantology, Periodontics End User: Dental Labs, Orthodontic Clinics, Oral Surgery Centers, Dental Academic Institutions |
| Companies Covered | Planmeca Oy, Straumann Group, Dentsply Sirona, GC Corporation, Medit Co., Ltd., 3Shape A/S, Carestream Dental LLC, Ivoclar Vivadent AG, Align Technology, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Impression System Market Strategic Shifts & Innovations
Software intelligence and workflow automation are fundamentally altering the clinical and business models for digital dentistry. This evolution moves value from the initial hardware transaction to the ongoing data-driven services that enhance diagnostic and restorative outcomes for patients.
Artificial Intelligence in Diagnostics
AI-powered analysis software is a key innovation for processing intraoral scan data. Orthodontic and prosthodontic clinics are rapidly adopting this for automated diagnostics and quality checks. The technology is automating critical parts of treatment design, reducing the need for manual adjustments and shortening planning cycles for clinicians.
Stricter Device Regulation
The European Union's Medical Device Regulation (MDR) has increased compliance burdens for all manufacturers. This regulation mandates more rigorous clinical evidence and post-market surveillance for devices like intraoral scanners. Consequently, companies targeting the EU must allocate significant resources to data generation and documentation to secure or maintain their CE marking.
Subscription-Based Models
A behavioral shift toward subscription-based software models is gaining traction over one-time hardware purchases. This model disrupts the traditional capital equipment sales cycle, allowing practices to adopt new technology as an operational expense. This trend is most visible in North America, where Dental Service Organizations (DSOs) favor scalable, predictable software-as-a-service platforms.
Digital Impression System Market Segmentation
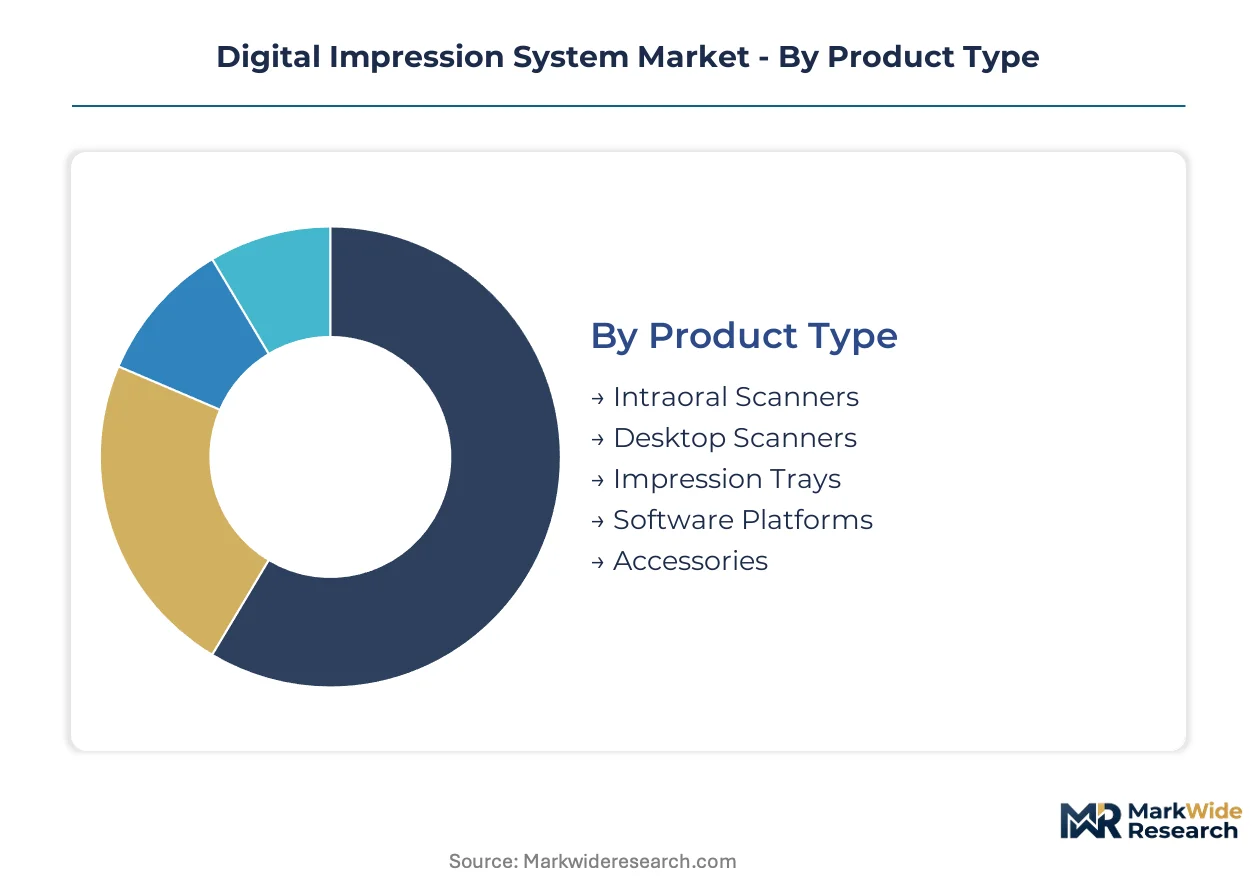
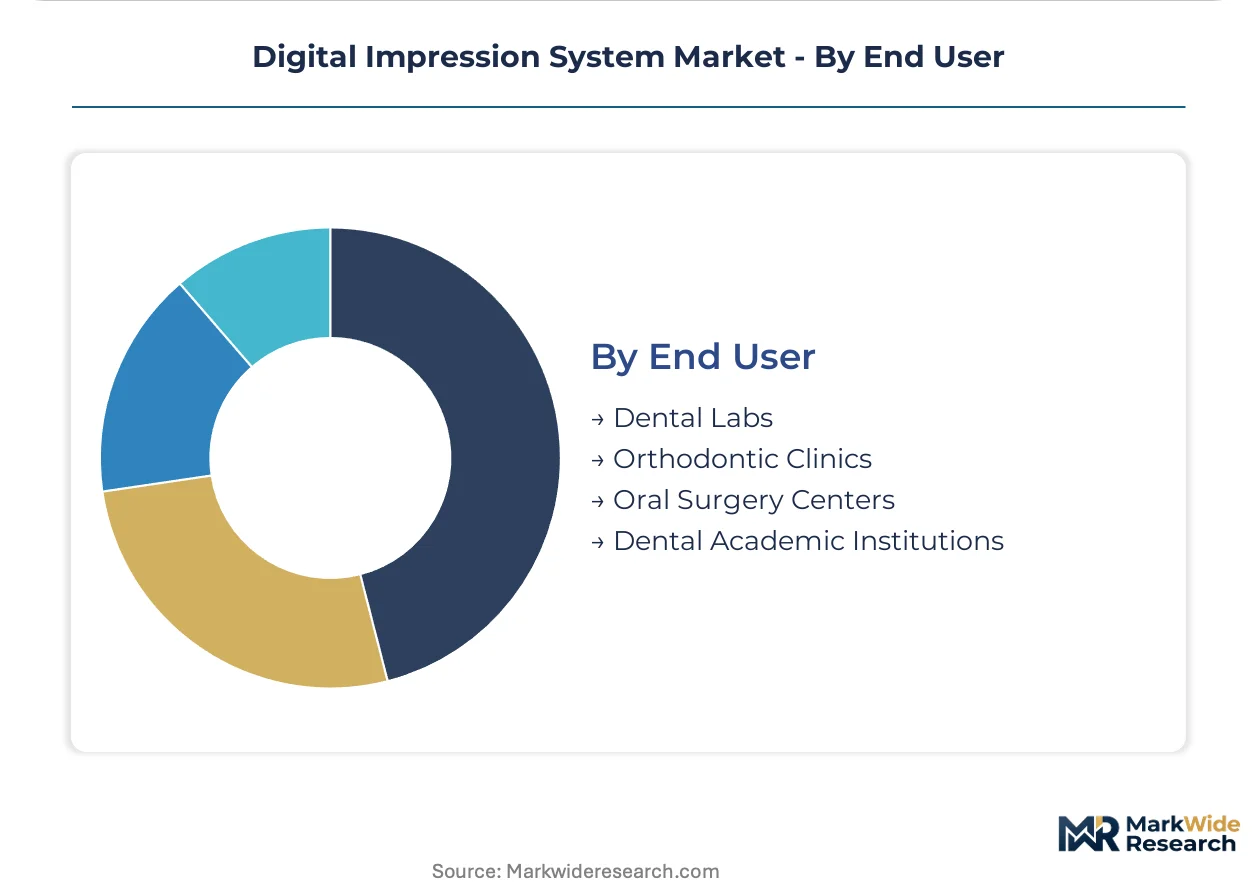
The Digital Impression System market structure reflects diverse product offerings, underlying technologies, key applications, and end-user requirements. Understanding these segments provides clarity on where investment flows and where technological advancements are creating new value propositions for dental professionals.
Product Type:
Dental practices evaluate product types based on their specific clinical needs and desired workflow integration.
- Intraoral Scanners:These handheld devices capture 3D images of teeth and soft tissues directly within the patient's mouth. Demand concentrates in orthodontic clinics, where precision is paramount for clear aligner workflows.
- Software Platforms:These digital ecosystems integrate scan data, facilitate treatment planning, and manage patient records. Their value proposition extends beyond initial hardware, favoring companies with strong digital ecosystems.
- Desktop Scanners:These laboratory-based devices digitize physical impressions or models for indirect digital workflows.
- Impression Trays:Traditional trays are still used to capture physical impressions, especially in settings without digital scanner access.
- Accessories:This segment includes calibration tools, disposable sleeves, charging stations, and various components supporting scanner operation.
Volume sits with Intraoral Scanners; growth tilts toward Software Platforms.
Technology:
The choice of scanning technology depends on the required precision, speed, and specific clinical application.
- Structured Light:This technology projects specific light patterns onto the object and analyzes the deformation to create 3D models. It offers high accuracy, making it suitable for complex restorative and orthodontic cases.
- Optical Scanning:This broad category encompasses various light-based methods to capture surface geometry. It forms the foundation for many intraoral and desktop scanning systems, offering versatility across dental applications.
- Laser Scanning:This method uses laser beams to measure distances and generate precise 3D data, often employed for industrial-grade accuracy in laboratory settings.
- Photogrammetry:This technique constructs 3D models from multiple overlapping 2D images, finding niche applications in specific dental imaging scenarios.
- Blue Light Technology:A variation of structured light, blue light improves scanning accuracy and speed, particularly beneficial for capturing detailed tooth surface data.
Structured Light technology sees widespread adoption, while Blue Light Technology is gaining share fastest due to its enhanced performance.
Application:
Clinical applications dictate the specific features and precision levels required from digital impression systems.
- Orthodontics:This segment utilizes digital impressions for diagnosis, treatment planning, and fabrication of clear aligners and retainers. High patient preference for clear aligners in the United States directly fuels scanner sales.
- Implantology:Digital systems are critical for precise implant placement planning, surgical guide fabrication, and custom abutment design. This application demands micron-level accuracy for successful outcomes.
- Prosthodontics:This involves digital impressions for crowns, bridges, dentures, and veneers, streamlining the restorative workflow.
- Oral Surgery:Digital models assist in planning complex surgical procedures, including jaw reconstruction and guided extractions.
- Periodontics:Digital scans aid in assessing periodontal health, monitoring tissue changes, and planning regenerative procedures.
Orthodontics drives significant volume, with Implantology experiencing substantial expansion.
End User:
The operational model and scale of dental practices influence their investment in digital impression systems.
- Orthodontic Clinics:These specialized practices are early and heavy adopters of digital impression systems due to the precision required for clear aligner workflows. The United States exhibits a high density of these clinics.
- Dental Labs:These facilities process digital impression data to fabricate dental prosthetics and appliances. They leverage digital workflows for efficiency and accuracy in production.
- Oral Surgery Centers:These centers use digital impressions for pre-surgical planning, custom guide creation, and post-operative assessment.
- Dental Academic Institutions:These institutions integrate digital impression systems into their curricula for training future dental professionals and conducting research.
Orthodontic Clinics represent the largest end-user segment, with Dental Labs also demonstrating strong system utilization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global digital impression system market exhibits a clear divide between advanced consumption hubs and emerging production and adoption centers. Highly developed economies drive demand for precision dental solutions, while developing nations are rapidly integrating these technologies into their healthcare infrastructure. This dynamic shapes regional investment and market penetration strategies.
United States
The United States drives significant demand due to strong patient preference for clear aligners and expanding specialized dental clinics. FDA clearance is a critical market access requirement for new digital impression systems. Innovation in AI-powered diagnostic software concentrates in tech hubs like Silicon Valley and Boston.
Germany
Germany demonstrates robust adoption of digital impression systems, particularly in prosthodontics and implantology applications. CE marking under the Medical Device Regulation (MDR) ensures product quality and safety for the European market. Dental technology manufacturing clusters in cities such as Cologne and Berlin focus on advanced scanner development.
China
China represents a significant growth opportunity, driven by a growing middle class and increasing investment in private healthcare infrastructure. Compliance with China's National Medical Products Administration (NMPA) is critical for manufacturers targeting this market. Major metropolitan areas such as Shanghai and Beijing are witnessing rapid expansion of digital dental practices.
India
India's expanding private healthcare sector and rising dental tourism contribute to the uptake of digital impression systems. The Central Drugs Standard Control Organization (CDSCO) oversees medical device regulations within the country. Cities such as Mumbai and Bangalore are emerging as centers for digital dentistry adoption and professional training.
Brazil
Brazil's growing middle class and increasing investment in dental care fuel demand for digital impression systems. ANVISA, the national health regulatory agency, governs the approval and commercialization of medical devices in the country. São Paulo and Rio de Janeiro lead in the adoption of advanced dental technologies within specialized clinics.
Digital Impression System Market Key Industry Players
Capital-heavy producers compete with asset-light software developers within the digital impression system market, creating a distinct competitive dynamic. The market exhibits a tiered structure, with established medical device conglomerates operating alongside specialized software providers and emerging hardware innovators. Key strategic archetypes include integrated solution providers offering end-to-end workflows, open-architecture innovators emphasizing flexibility, and hardware-focused manufacturers. Companies frequently engage in strategic partnerships to expand digital ecosystems and pursue targeted acquisitions for technology integration and market access.
Integrated solution providers, such as Align Technology, Inc., leverage their proprietary digital ecosystems to support dominant clear aligner businesses and streamline treatment planning. The Straumann Group occupies a position as a comprehensive dental solutions provider, offering a broad portfolio encompassing both scanners and downstream restorative solutions for various applications. Denmark-based 3Shape A/S exemplifies an open-architecture strategy, appealing to dental professionals seeking flexibility in their clinical workflows and compatibility with diverse third-party systems. These companies anchor different segments of the market by balancing hardware and software offerings, influencing technology adoption pathways and long-term customer relationships.
| Leading Market Players |
|---|
| Planmeca Oy |
| Straumann Group |
| Dentsply Sirona |
| GC Corporation |
| Medit Co., Ltd. |
| 3Shape A/S |
| Carestream Dental LLC |
| Ivoclar Vivadent AG |
| Align Technology, Inc. |
| Others |
Cost & Logistics Intelligence
Established medical device conglomerates influence the digital impression system market, shaping both component supply availability and strategic pricing decisions. Their integrated ecosystems often dictate the cost structure for downstream dental practices.
Pricing Analysis
Margin tightening in the hardware segment reflects intense competition among intraoral scanner manufacturers. Subscription-based software models dominate, offering predictable operational expenses for dental practices and shifting value from initial sales to ongoing services. Price differentiation stems from scanner precision, robust software ecosystems, and comprehensive after-sales support. Smaller independent dental practices exhibit higher price sensitivity compared to large Dental Service Organizations, which prioritize scalable, integrated solutions and long-term value.
Supply Chain Analysis
Reverse logistics for digital impression systems primarily involve device returns for repair or component refurbishment, particularly for high-value optical parts. Component manufacturing centers in countries like Germany, the United States, and China, sourcing specialized optical components, microprocessors, and high-grade polymers. A key structural risk involves single-source vulnerability for proprietary scanning technologies. Downstream distribution relies heavily on specialized medical device distributors and direct sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The digital impression system market functions as a cost-of-compliance story, where stringent regulations like the EU Medical Device Regulation (MDR) create a significant barrier-to-entry moat. This ensures only compliant players can effectively compete across major geographies.
For Market Incumbents:Acquire specialized AI software firms to enhance diagnostic capabilities and automate treatment planning. Incumbents should deepen their digital ecosystems to counter the threat of open-architecture software platforms. Investing in global regulatory compliance for new device iterations is a critical lever for market defense. Consolidate market share through strategic partnerships with large Dental Service Organizations.
For New Entrants and Emerging Players:Smaller, independent dental practices in emerging markets represent a significant underserved buyer archetype for digital impression systems. Target this segment with cost-effective, portable, and wireless intraoral scanners. Penetrate geographies like Brazil and India by offering subscription-based software models tailored to their operational expenditure preferences. A strong go-to-market angle involves integrating teledentistry platforms for remote patient monitoring.
For Investors and Strategic Acquirers:Distressed-cycle entries favor specialized software developers in Europe, particularly those struggling with Medical Device Regulation compliance. The digital impression system market offers long-term viability, driven by increasing digital adoption in dentistry. Acquisition targets should include companies with robust AI algorithms or strong intellectual property in structured light technology. A key signal to watch is the rate of regulatory clearances for new AI-powered diagnostic tools.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Software Integration | Enhances diagnostic accuracy for orthodontics and automates treatment planning for clinicians. |
| CE Marking Investment | Secures market access and ensures product quality for the European Union market. |
| Portable Scanner Development | Expands usage into multi-operatory clinics and mobile dentistry, improving ease of use. |
| Teledentistry Platform Partnership | Enables remote patient monitoring for orthodontic treatments, opening new service delivery models. |
| Subscription Model Expansion | Shifts value proposition from hardware sales to ongoing data-driven services for Dental Service Organizations. |
Research Approach
Document review covered regulatory filings, industry association publications, and academic journals, complemented by interviews with dental professionals and medical device engineers. Primary research engaged clinic administrators and regulatory affairs specialists. The analysis combined bottom-up data collection with top-down market sizing, ensuring comprehensive triangulation of findings.
The quantitative model generated volume and value projections across the analysis window, segmented by product type, technology, application, and end-user. Compound Annual Growth Rates were derived from historical data analysis and future trend extrapolation. Key forecast inputs included clear aligner adoption rates in orthodontics and the speed of AI integration into diagnostic software platforms.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory changes and technological disruptions. These forecasts reflect underlying assumptions regarding market evolution. Practitioners should monitor new medical device regulations and AI advancements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Spine Positioning Devices Market
Medical Devices
Global Suture Anchor Devices Market
Medical Devices
Medical Pendant Market
Medical Devices
Stool Management Systems Market
Medical Devices
Extended Wear Contact Lens Market
Medical Devices
Electroencephalography (EEG) Amplifier System Market
Medical Devices
Catheter Coatings Market
Medical Devices
Global Hysteroscope Market
Medical Devices
Power Smart Bed Market
Medical Devices
Air Compressor Nebulizer Market
Medical Devices
Global Interspinous Spacers Market
Medical Devices
Asthma Device Market
Medical Devices
Transilluminators Market
Medical Devices
Intravenous Line Connectors Market
Medical Devices
Metered Dose Squeeze Dispenser Market
Medical Devices
General Surgery Devices Market