
 Transit Cards Market | 2026-2036
Transit Cards Market Size, Share, and Industry Trends Forecast 2026-2036
Transit Cards Market Intelligence
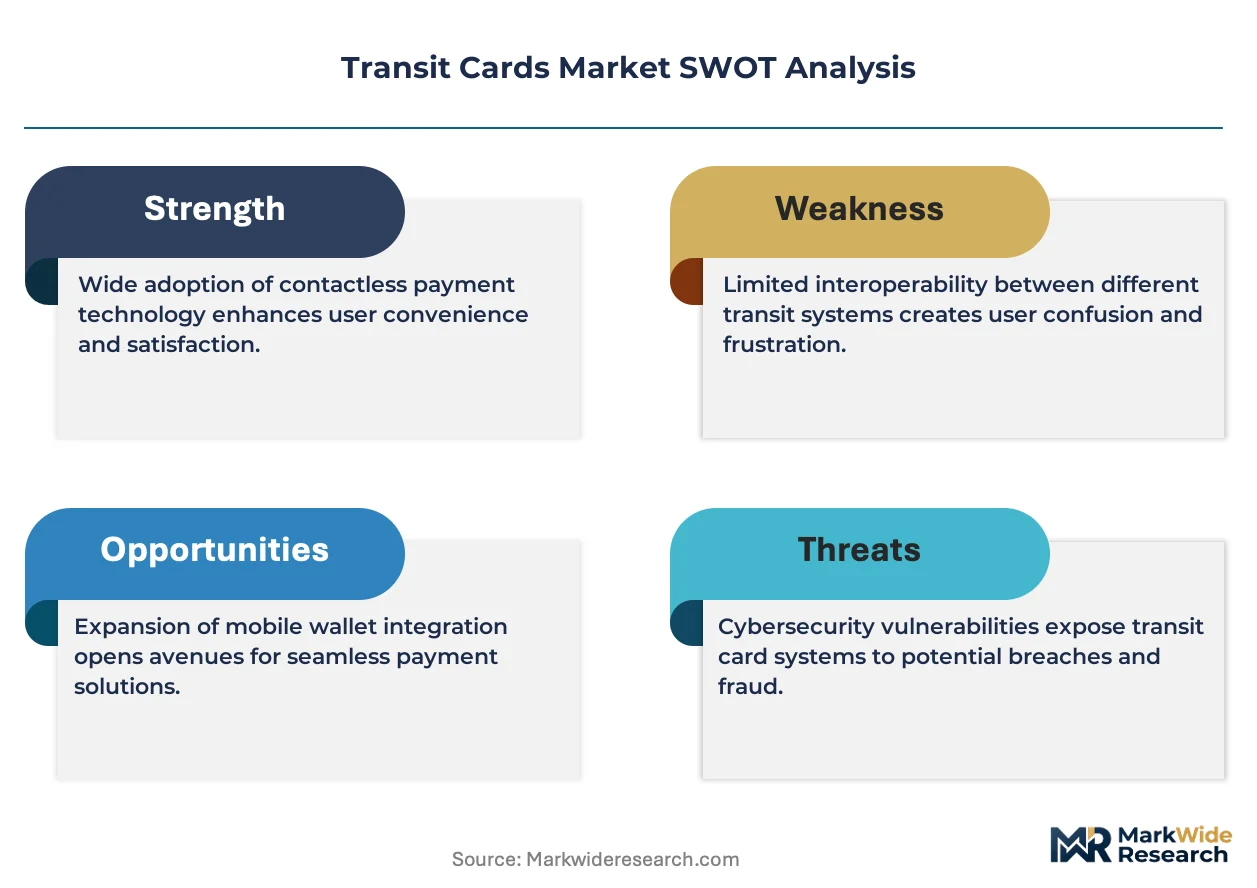
The EU AI Act is broadening the cost-of-entry calculus for transit card systems that process commuter biometric or behavioral data. NXP Semiconductors leverages its chip-level security architecture to anchor European contactless deployments. Cubic Transportation Systems competes through integrated account-based fare platforms that span multiple transit modes. Giesecke+Devrient specializes in polycarbonate card bodies with embedded holographic elements for anti-counterfeiting.
Transit cards are payment credentials manufactured from PVC, polycarbonate, or PET substrates, embedding RFID antennae, NFC chips, or magnetic stripes to authenticate fare payment across rail, bus, and multimodal networks. The contactless cards segment leads value generation due to higher unit costs and replacement cycles tied to EMV compliance, while QR code technology grows fastest in emerging deployments where smartphone penetration outpaces card infrastructure. Monthly passes concentrate margin pools through subscription-based revenue predictability, whereas single journey tickets face structural compression from digital wallet displacement.
REACH restricts phthalate plasticizers in card substrates across European manufacturing, while ETSI standards govern NFC interoperability thresholds. The EU Green Deal pushes transit authorities toward recycled-content card bodies, reshaping supplier qualification criteria. Stakeholders must monitor whether account-based mobility platforms will obsolete physical card issuance or merely shift chip demand into wearable and embedded form factors.
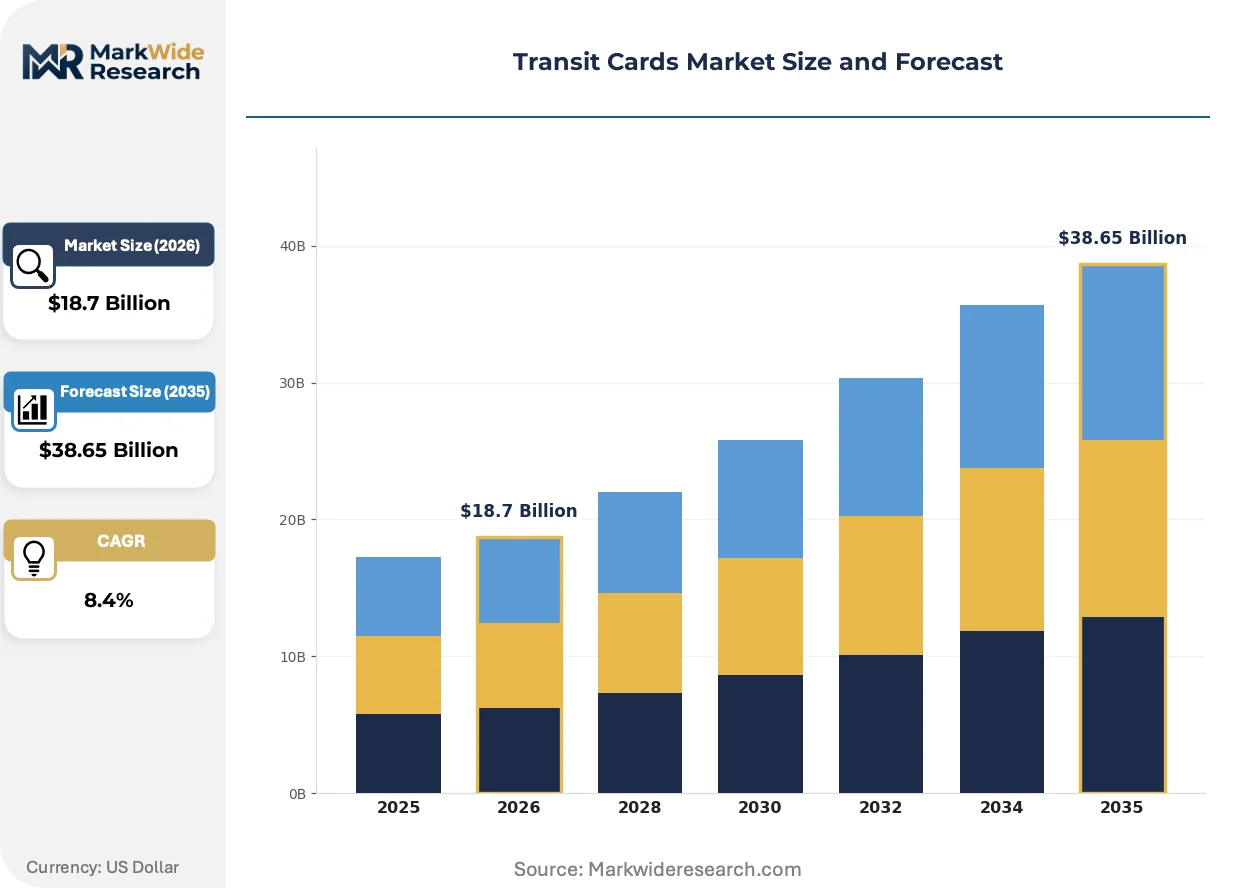
Market Dynamics
Account-based mobility platforms are compressing physical card issuance cycles while simultaneously fragmenting chip demand across wearables, vehicle-embedded transponders, and smartphone secure elements, forcing substrate suppliers to diversify form factor capabilities.
Growth Catalysts
- EU Green Deal recycled-content mandates:Transit authorities in Germany, France, and the United Kingdom now require post-consumer rPET or recycled polycarbonate in card bodies, opening qualification slots for sustainable substrate specialists.
- Urban commuter rail modernization:Contactless fare collection upgrades across metropolitan networks are replacing magnetic stripe legacy systems with dual-interface EMV-compliant cards.
- F-Gas Regulation compliance:The European Union's phasedown of hydrofluorocarbons in manufacturing processes is accelerating laser-etching adoption for card personalization, displacing solvent-based thermal transfer.
Market Restraints
- PVC substrate cost volatility:Petrochemical feedstock fluctuations and energy-intensive chlor-alkali production concentrate margin pressure on low-end single-journey ticket manufacturers.
- NFC chip supply concentration:Advanced secure element fabrication depends on a concentrated foundry base in East Asia, creating single-source vulnerability for European card integrators.
- GDPR data-handling friction:Biometric-enabled transit cards face extended procurement timelines as authorities negotiate processor liability for commuter behavioral data storage.
Strategic Opportunities
- Wearable form factor expansion:Ring and bracelet payment credentials using miniaturized NFC antennas target fitness-conscious commuters in Germany and the Netherlands.
- Vehicle-embedded toll interoperability:DSRC and C-V2X convergence enables single-chip solutions spanning congestion charging, parking, and transit fare deduction.
- REACH phthalate substitution incentives:Bio-based plasticizer development for flexible card substrates attracts public R&D funding in France and Nordic markets.
Industry Challenges
- EMV certification timeline compression:Transit-specific application testing for contactless payment interoperability creates 12-18 month deployment delays for new card programs.
- Legacy system integration complexity:Backward compatibility requirements with decades-old fare gates and validators constrain antenna design and power-harvesting efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transit Cards Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stored Value Cards, Monthly Passes, Single Journey Tickets, Contactless Cards Technology: RFID, NFC, Magnetic Stripe, QR Code End User: Commuters, Tourists, Students, Seniors Distribution Channel: Online, Retail Outlets, Kiosks, Ticket Offices |
| Companies Covered | Oberthur Technologies, Identiv, Giesecke+Devrient, Cubic Transportation Systems, ASK Technology, NXP Semiconductors, Thales Group, Scheidt & Bachmann, Infineon Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transit Cards Market Strategic Shifts & Innovations
Chip-level security architectures and substrate material science are converging to redefine authentication durability and environmental credentials across European transit networks.
Polycarbonate card bodies with embedded holographic diffractive elements are automating visual authentication at fare gates, eliminating manual inspector verification. Urban rail operators in Paris and London are adopting these substrates for multi-year validity passes. The technology is automating anti-counterfeiting assurance while extending replacement cycles beyond PVC alternatives.
REACH substance restrictions on phthalate plasticizers are forcing substrate reformulation across European manufacturing. Card producers must qualify bio-based or citrate alternatives without compromising flex durability. German and French suppliers are accelerating testing programs to maintain CE marking compliance ahead of 2025 enforcement milestones.
Subscription-based mobility-as-a-service bundling is restructuring how transit authorities procure credential volumes. Annual pass commitments now dominate tender specifications in the Netherlands and Belgium, displacing spot purchasing of single-journey ticket blanks. This consolidation favors integrators with account-based platform capabilities and compresses margins for pure card manufacturers.
Transit Cards Market Segmentation
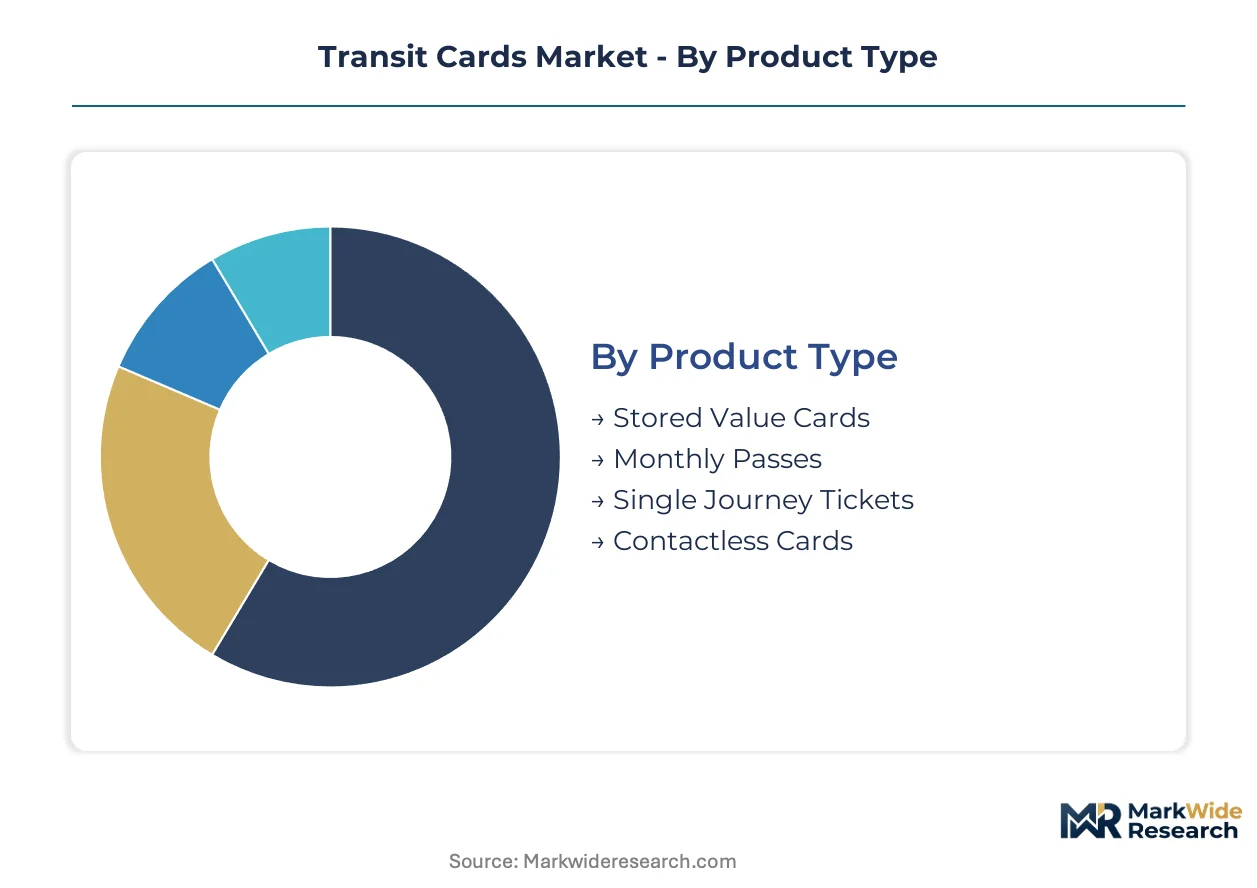
Transit card procurement patterns diverge sharply between high-frequency commuter subscriptions and sporadic tourist purchases. Material specifications, chip architectures, and personalization workflows all pivot on which segment dominates a given authority's tender.
Product Type:
Volume concentrates in low-unit-cost single-ride credentials, while margin pools concentrate in durable multi-year passes with embedded security features.
- Contactless Cards:Dual-interface EMV-compliant substrates with polycarbonate or rPET bodies and laser-etched personalization. Demand clusters in Germany, France, and the United Kingdom where rail operators modernize legacy gates for open-loop payment interoperability.
- Monthly Passes:Subscription-based credentials with extended validity cycles and holographic anti-counterfeiting elements. Procurement in the Netherlands and Belgium now favors integrators with account-based platform capabilities, compressing margins for pure card manufacturers.
- Stored Value Cards:Reloadable balance credentials common in urban bus networks with closed-loop systems.
- Single Journey Tickets:Thin PVC or paper-based disposable formats facing structural displacement from smartphone QR codes.
Mature deployment sits with Monthly Passes. Newer deployment is concentrated in Contactless Cards.
Technology:
Authentication protocols split between legacy infrastructure compatibility and next-generation mobility platform integration.
- NFC:Near-field communication chips enabling tap-and-go fare validation with smartphone interoperability. Urban rail operators in Paris and London specify NFC for multi-modal account-based platforms, though EMV certification timelines stretch 12-18 months.
- QR Code:Optical authentication printed on paper or displayed on mobile screens. Smartphone penetration outpaces card infrastructure in emerging deployments, making this the steepest expansion trajectory for technology adoption.
- RFID:Radio-frequency identification for closed-loop systems with proprietary encoding schemes.
- Magnetic Stripe:Legacy encoding on polyester substrates, now restricted to backward-compatible fare gates scheduled for replacement.
Established infrastructure relies on RFID. Platform modernization is driving NFC and QR Code adoption fastest.
End User:
Usage frequency and fare elasticity determine credential durability requirements and subsidy structures.
- Commuters:Daily riders generating predictable transaction volumes and highest lifetime value per credential. German and UK authorities negotiate bulk chip procurement for this segment, prioritizing durability over unit cost.
- Students:Discount-eligible users with seasonal usage patterns and higher loss rates. French transit authorities embed photo identification and term-date validation, requiring specialized personalization workflows.
- Tourists:Short-duration visitors purchasing day-passes or visitor cards with simplified refund terms.
- Seniors:Eligibility-based concession travelers with distinct peak-hour restrictions and free-travel zones.
Revenue stability comes from Commuters. Volume volatility concentrates in Tourists.
Distribution Channel:
Fulfillment economics shift between fixed infrastructure costs and per-transaction digital overhead.
- Ticket Offices:Staffed counters with personalized card issuance and account troubleshooting. Labor-intensive operations persist in France and Germany for complex concession eligibility verification.
- Kiosks:Self-service machines dispensing standard-format credentials with cash and card payment acceptance. Paris Metro and London Underground maintain extensive kiosk networks for unbanked riders.
- Online:Direct-to-consumer fulfillment with postal delivery or mobile wallet provisioning. Dutch operators lead in account-based platform migration, reducing physical card issuance.
- Retail Outlets:Third-party convenience store and supermarket partnerships for top-up services.
Fixed infrastructure investment centers on Kiosks. Channel shift momentum favors Online provisioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany, France, and the United Kingdom as these markets modernize legacy rail infrastructure for open-loop payment interoperability. Contactless fare collection upgrades drive substrate procurement across metropolitan networks. The EU Green Deal and F-Gas Regulation reshape supplier qualification criteria through recycled-content mandates and manufacturing process restrictions.
Germany
Urban commuter rail operators in Berlin, Munich, and Hamburg are replacing magnetic stripe systems with dual-interface EMV-compliant cards. The KBA and federal transport ministry enforce strict interoperability standards under ETSI frameworks. Bavaria and North Rhine-Westphalia concentrate manufacturing partnerships where laser-etching personalization displaces solvent-based thermal transfer methods.
France
Paris Metro and RATP lead polycarbonate card adoption with holographic diffractive elements for multi-year validity passes. ANSM and CNIL extend procurement timelines for biometric-enabled credentials through GDPR liability negotiations. The Île-de-France region anchors demand for subscription-based mobility-as-a-service bundling that restructures annual pass commitments.
United Kingdom
Transport for London's account-based platform migration compresses physical card issuance while fragmenting chip demand across wearables and smartphone secure elements. UK regulators enforce REACH phthalate restrictions on PVC substrates while pushing post-consumer rPET requirements. London and the Southeast concentrate kiosk network maintenance for unbanked rider access.
Netherlands
Dutch operators lead online provisioning and direct-to-consumer fulfillment, reducing physical card issuance through mobile wallet integration. The national transport authority mandates CE marking compliance for NFC interoperability thresholds. Randstad metropolitan networks concentrate demand for ring and bracelet payment credentials targeting fitness-conscious commuters.
Belgium
STIB-MIVB and regional operators consolidate annual pass procurement around integrators with account-based platform capabilities. Belgian authorities align with EU Green Deal recycled-content mandates for polycarbonate and rPET card bodies. Brussels anchors tender specifications that compress margins for pure card manufacturers while favoring full-service mobility platforms.
Transit Cards Market Key Industry Players
European producers anchor the secure element and substrate tier; East Asian foundry specialists hold chip fabrication concentration. The vendor base splits between consolidated semiconductor suppliers and fragmented card integrators competing on personalization speed and sustainability credentials. Three archetypes dominate: chip-level security architects, polycarbonate substrate specialists with holographic capabilities, and account-based platform integrators spanning multimodal networks. Competitive moves center on laser-etching capacity expansion for F-Gas compliance and strategic partnerships with mobility-as-a-service operators.
Within the semiconductor tier, NXP Semiconductors and Infineon Technologies exemplify chip-level security architects leveraging hardware-based encryption for European contactless deployments. Giesecke+Devrient occupies a position among polycarbonate substrate specialists, representing durable card body manufacturing with embedded anti-counterfeiting elements. Cubic Transportation Systems anchors the account-based platform integrator archetype, sitting within the convergence of fare collection hardware and software-defined mobility services.
| Leading Market Players |
|---|
| Oberthur Technologies |
| Identiv |
| Giesecke+Devrient |
| Cubic Transportation Systems |
| ASK Technology |
| NXP Semiconductors |
| Thales Group |
| Scheidt & Bachmann |
| Infineon Technologies |
| Others |
Cost & Logistics Intelligence
EU Green Deal recycled-content mandates gate qualified supply for premium-tier card body contracts, restricting participation to substrate specialists with certified post-consumer rPET or polycarbonate streams while compressing margins for conventional PVC manufacturers unable to meet procurement thresholds.
Pricing Analysis
Short lead-time premiums of 15-25% apply to emergency personalization orders for annual pass renewals, while spot inventory of standard dual-interface cards trades at modest discounts. Three-tier pricing structure across premium polycarbonate multi-year credentials, standard EMV-compliant contactless cards, and economy PVC single-journey tickets reflects durability grade and certification complexity. Cost compression in the economy tier is intensifying as QR code smartphone authentication displaces disposable card volumes. Municipal transport authorities in Germany and France exhibit lowest price sensitivity for subscription-based annual passes, whereas tourist-oriented day-pass programs in Southern European markets face acute budget constraints.
Supply Chain Analysis
Regional distribution centers in the Netherlands and Belgium coordinate hub-and-spoke fulfillment for card personalization equipment and substrate blanks across Northern European transit authorities. Secure element fabrication concentrates in Taiwan and South Korea, while polycarbonate substrate extrusion anchors in Germany and France. Raw material dependencies span phthalate-free plasticizers, laser-etchable overlay films, and holographic diffractive foils. Single-source vulnerability in advanced NFC chip foundries creates procurement risk for European card integrators. Distribution runs through bonded logistics partnerships serving RATP, Transport for London, and Deutsche Bahn with just-in-time personalization workflows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foundry capacity constraints in East Asian secure element production prop pricing power for qualified substrate suppliers, creating a supply-constrained market structure favoring incumbents with established foundry relationships.
For Market Incumbents: Anticipate accelerated displacement of physical card issuance by account-based mobility platforms and diversify into wearable form factors and vehicle-embedded transponder integration. Defensive consolidation through backward integration into laser-etching personalization capacity addresses F-Gas Regulation compliance requirements. Capacity addition in recycled polycarbonate substrate manufacturing secures qualification for EU Green Deal mandates. For New Entrants and Emerging Players: Begin with white-space targeting of bio-based plasticizer development for REACH-compliant flexible substrates, where French and Nordic public R&D funding reduces capital barriers. The ring and bracelet wearable segment in the Netherlands and Germany offers lowest competitive density. A direct-to-consumer online fulfillment partnership with Dutch transport operators provides viable go-to-market positioning. For Investors and Strategic Acquirers: STIB-MIVB's consolidation of annual pass procurement around full-service mobility platforms is the leading indicator that pure card manufacturing margins face structural compression. Long-term viability centers on integrators with account-based software capabilities spanning multimodal networks. Acquisition target archetypes include laser-etching personalization specialists and sustainable substrate developers with certified recycled-content streams. Watch for biometric-enabled credential procurement timeline extensions under GDPR liability negotiations as the inflection signal for regulatory-driven market restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Laser-Etching Capacity Expansion | F-Gas Regulation compliance displaces solvent-based thermal transfer in German manufacturing clusters. |
| Recycled Substrate Qualification | Post-consumer rPET certification opens tender participation for EU Green Deal-mandated transit authorities. |
| Wearable Form Factor Development | Miniaturized NFC antennas target fitness-conscious commuter segments in Randstad metropolitan networks. |
| Account-Based Platform Integration | Software-defined mobility services compress pure card issuance while capturing subscription revenue pools. |
| Secure Element Foundry Partnership | Long-term offtake agreements with Taiwan and South Korean fabricators mitigate single-source supply risk. |
Research Approach
Multi-period observation of contactless fare collection deployment timelines, EMV certification completion rates, and recycled-content procurement thresholds anchored the trend analysis, supplemented by interviews with transit authority procurement directors, card personalization facility managers, semiconductor supply chain specialists, and mobility-as-a-service platform architects. Secondary validation drew from ETSI interoperability standards documentation, REACH substance restriction enforcement notices, EU Green Deal implementation progress reports, and customs data for polycarbonate and PVC substrate trade flows. Bottom-up credential volume modeling triangulated against top-down transit operator expenditure disclosures.
Segment-weighting across product type, technology protocol, end-user frequency, and distribution channel dimensions structured the analytical framework across the projection horizon. CAGRs derived from fitted growth curves applied to disclosed procurement volumes and replacement cycle assumptions. Industry-specific forecast inputs incorporated EMV migration timelines for legacy magnetic stripe systems and biometric authentication adoption curves under GDPR liability frameworks.
Underlying measurement precision varies by segment; contactless card volume forecasts carry tighter precision than emerging wearable form factor projections due to established procurement reporting. Forecasts reflect assumptions regarding regulatory enforcement consistency, foundry capacity expansion, and transit authority budget allocation stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Tanzania Mobile Money Market
Payments
POS Terminals Market
Payments
Gift Card and Incentive Card Market
Payments
Cryptocurrency Payment Apps Market
Payments
Mobile POS Market
Payments
North America Payments Market
Payments
United States Electronic Toll Collection Market
Payments
Southeast Asia POS Terminal Market
Payments
China Prepaid Cards Market
Payments
North America Payment Analytics Software Market
Payments
Cross-Border Payment Platform Market
Payments
Saudi Arabia Gift Card and Incentive Card Market
Payments
Japan Payments Market
Payments
United Kingdom Real Time Payments Market
Payments
US Gift Card and Incentive Card Market
Payments
Mobile Point of Sale Devices (Mpos) Market