
 North America Payments Market | 2026-2036
North America Payments Market Size, Share, and Industry Trends Forecast 2026-2036
North America Payments Market Analytics
Multi-source processor relationships is decoupling from legacy single-vendor dependencies across North American financial institutions. Visa Inc. anchors its position through tokenization standards that secure card-not-present transactions. Stripe Inc. competes by embedding checkout infrastructure directly into software platforms used by small businesses. Fiserv Inc. extends its reach through core banking integrations that lock in depository institutions.
Payments encompass the electronic transfer of monetary value between transacting parties using encrypted protocols, settlement networks, and risk-scoring algorithms that verify identity and authorize fund movement in milliseconds. The primary commercial purpose centers on reducing friction in commerce while minimizing counterparty default exposure for merchants and issuers. Mobile wallet and contactless payment segments are capturing volume from physical card swipes as NFC-enabled terminals reach saturation at quick-service restaurants and transit systems. Subscription billing commands disproportionate margin attention because recurring revenue models generate predictable interchange streams with lower customer acquisition costs than one-time transaction processing.
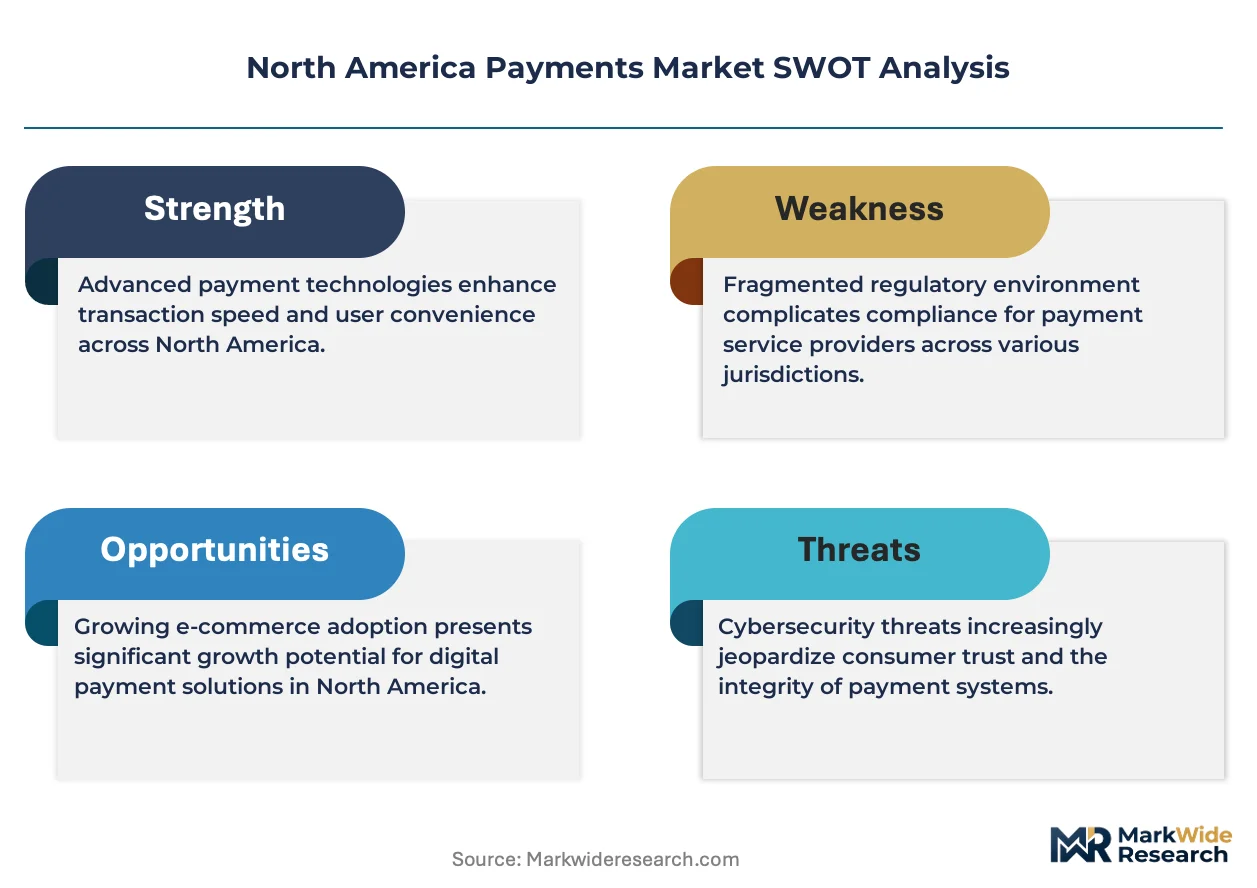
The Federal Reserve, Office of the Comptroller of the Currency, and Financial Transactions and Reports Analysis Centre of Canada shape market access through licensing requirements, capital reserves, and anti-money-laundering surveillance mandates that elevate compliance costs for new entrants. The Consumer Financial Protection Bureau's scrutiny of overdraft and late fee practices is redirecting issuer revenue models toward interchange and data monetization. Stakeholders must monitor how open banking rulemakings in both countries alter data portability obligations and third-party aggregator permissions.
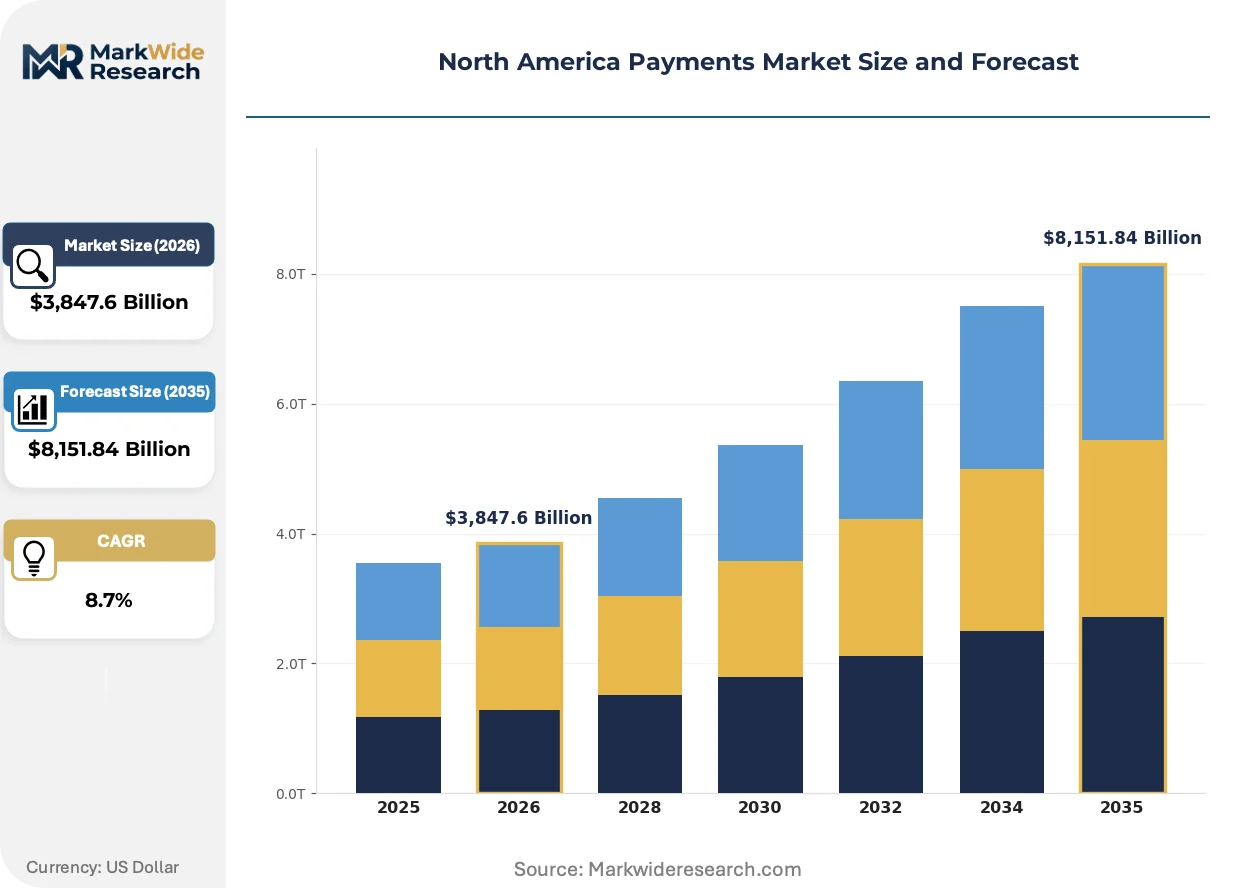
Market Dynamics
Real-time payment infrastructure deployment by the Federal Reserve and Payments Canada is forcing wholesale modernization of legacy batch settlement systems across United States and Canadian financial institutions. This structural shift compresses processing windows from days to seconds, demanding new core banking investments and API architectures.
Growth Catalysts
- FedNow Service:The Federal Reserve's instant payment rail eliminates settlement risk for peer-to-peer transfers and corporate treasury operations, accelerating adoption among credit unions and community banks.
- Software-as-a-Service billing:Subscription revenue platforms generate recurring payment volumes with lower churn and higher authorization rates than one-time transaction processing.
- Contactless terminal saturation:NFC-enabled point-of-sale hardware at quick-service restaurants and transit systems is converting cash and mag-stripe volume to tap-to-pay protocols.
Market Restraints
- Interchange compression:The Consumer Financial Protection Bureau's scrutiny of swipe fees is capping issuer revenue per transaction, squeezing network economics.
- Core banking vendor concentration:Three legacy processors dominate depository institution technology stacks, creating switching costs that slow modernization.
- Cross-border friction:Divergent anti-money-laundering surveillance mandates between FinCEN and FINTRAC fragment compliance workflows for Canada-United States remittances.
Strategic Opportunities
- Open banking rulemakings:Data portability obligations under Consumer Financial Protection Bureau proposals will unlock account aggregation services for fintech entrants.
- Embedded finance convergence:Payment acceptance APIs are integrating with vertical SaaS platforms used by contractors, healthcare providers, and professional services.
- Underpenetrated B2B payments:Paper check usage persists in United States commercial transactions, creating white space for electronic invoice and supply chain finance automation.
Industry Challenges
- Real-time fraud detection talent:Machine learning engineers with payments risk-scoring expertise command premium compensation, constraining issuer hiring pipelines.
- Legacy system API integration:COBOL-based core banking platforms require middleware layers that introduce latency and failure points into instant payment workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Payments Market |
| Market Size in 2026 | $3,847.6 Billion |
| Market Size in 2035 | $8,151.84 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Card, Debit Card, Mobile Wallet, Bank Transfer Transaction Type: Online Payment, In-Store Payment, Subscription Billing, Peer-to-Peer Payment Customer Segment: Retail Customers, Small Businesses, Enterprises, Nonprofits Technology: Contactless Payment, Tokenization, Blockchain, NFC Technology |
| Companies Covered | Fiserv Inc., Stripe Inc., Visa Inc., Amazon.com Inc., Apple Inc., Mastercard Incorporated, Block Inc., Google LLC, PayPal Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Payments Market Evolving Landscape
Tokenization protocols and artificial intelligence risk engines are converging to redefine authentication standards across card-not-present channels. These forces are compressing fraud windows while expanding merchant acceptance of remote transactions.
Network tokenization is rewriting security architecture for e-commerce transactions by replacing primary account numbers with device-bound credentials. Large merchants and digital marketplaces are adopting these standards to reduce PCI compliance scope and chargeback rates. This technology is rewriting liability allocation between issuers and acquirers, shifting fraud burden toward token vault operators.
The Consumer Financial Protection Bureau's open banking proposals are mandating standardized data sharing APIs between depository institutions and third-party aggregators. This regulatory framework forces banks to surrender transaction history portability that previously locked customers into proprietary ecosystems. Community banks and credit unions in the United States face the steepest compliance timelines, with larger institutions already piloting connectivity layers.
Recurring revenue models are displacing one-time transaction processing as the preferred merchant pricing structure. Software platforms serving healthcare practices, fitness studios, and professional services are bundling payment acceptance with subscription management tools. This shift is most visible in United States small business segments, where churn reduction and predictable cash flow outweigh interchange optimization.
North America Payments Market Segmentation
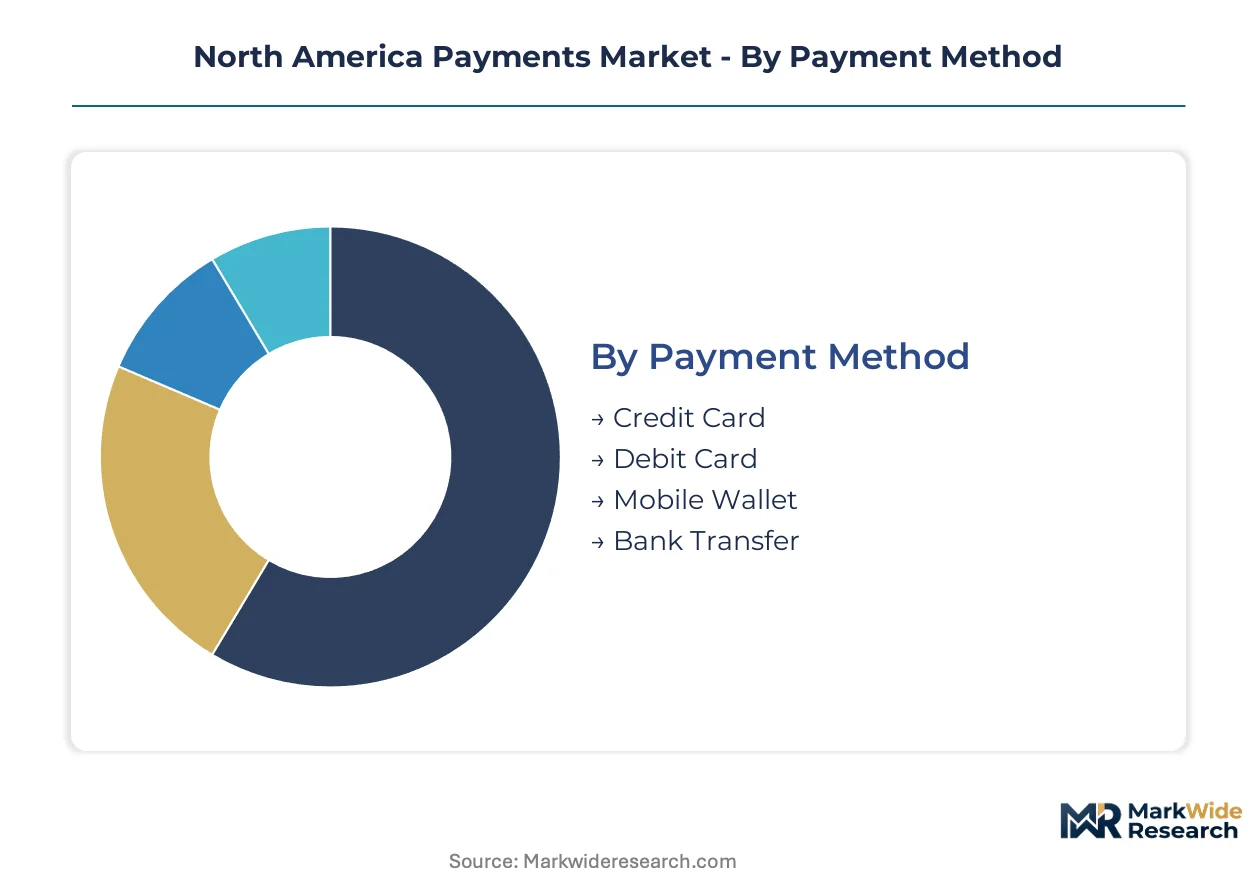
Payment infrastructure investments vary dramatically across segment boundaries, with real-time rails and tokenization vaults demanding capital commitments that reshape competitive entry barriers. Understanding these structural divisions reveals where margin pools concentrate and which technology bets carry the highest deployment risk.
Payment Method:
Credit card networks require the heaviest upfront investment in tokenization infrastructure and compliance architecture, creating natural moats around incumbent positions.
- Credit Card:Revolving credit instruments carry interchange premiums that fund rewards programs and fraud prevention layers. Demand concentrates among enterprise merchants seeking chargeback protection and consumer loyalty leverage.
- Debit Card:Direct account-linked instruments bypass credit risk but face stricter interchange caps under regulatory scrutiny. PIN and signature variants split between grocery chains and fuel retailers across the United States and Canada.
- Mobile Wallet:Device-bound credential storage is displacing physical card presentation at quick-service restaurants and transit systems. Token provisioning costs and biometric authentication investments define competitive economics.
- Bank Transfer:ACH and wire protocols serve B2B invoice settlement and high-value treasury operations. FedNow deployment is accelerating real-time account-to-account adoption among credit unions.
Credit card infrastructure absorbs the bulk of installed processing capacity; mobile wallet volume is expanding most quickly.
Transaction Type:
Subscription billing commands disproportionate engineering resources for retry logic and dunning management, separating platform-native providers from commodity processors.
- Online Payment:Card-not-present transactions rely on 3D Secure protocols and device fingerprinting to mitigate fraud exposure. E-commerce marketplaces and SaaS platforms drive authorization volume.
- In-Store Payment:EMV chip and NFC tap protocols dominate physical retail with sub-300-millisecond authorization requirements. Big-box retailers and pharmacy chains anchor terminal deployment.
- Subscription Billing:Recurring revenue models demand vaulting infrastructure for credential storage and automated retry sequences. Healthcare practices and fitness studios prioritize churn reduction over interchange optimization.
- Peer-to-Peer Payment:Instant settlement between consumer accounts relies on debit rail integration and social graph verification. Venmo and Cash App ecosystems capture domestic transfer volume.
In-store payment infrastructure retains the largest share of merchant acceptance points; subscription billing features the steepest expansion trajectory among software platforms.
Customer Segment:
Enterprise relationships require dedicated implementation teams and custom API integrations, elevating sales cycles and account management costs relative to self-serve channels.
- Retail Customers:Individual consumers select payment instruments based on rewards yield and mobile app experience. Contactless preference is reshaping quick-service restaurant checkout flows.
- Small Businesses:Merchant service providers compete on settlement speed and integrated accounting software connectivity. Contractors and professional services firms prioritize invoice automation.
- Enterprises:Large merchants negotiate bespoke interchange arrangements and demand token vault control. Treasury departments require multi-currency support and supply chain finance integration.
- Nonprofits:Donation processing platforms emphasize recurring gift management and donor data portability. Religious organizations and educational institutions anchor this segment.
Retail customer transaction count dominates aggregate volume; enterprise accounts deliver the highest revenue per relationship.
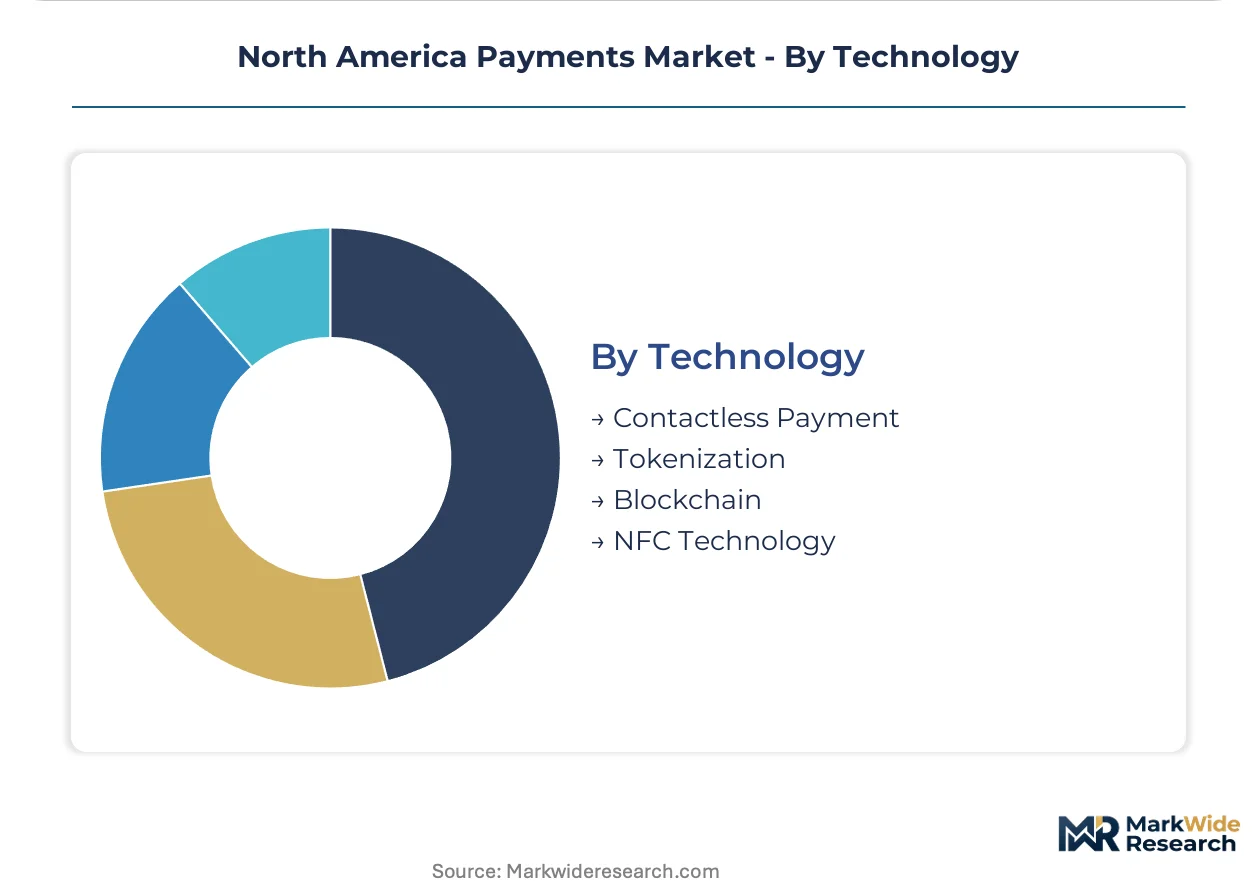
Technology:
Tokenization deployments demand specialized cryptographic infrastructure and HSM investments that separate qualified providers from reseller intermediaries.
- Contactless Payment:NFC field communication enables tap-to-pay at saturated terminal bases across United States quick-service restaurants. Transit system deployments in New York and Vancouver anchor municipal adoption.
- Tokenization:Primary account number substitution reduces PCI compliance scope and shifts fraud liability toward vault operators. Large digital marketplaces are mandating network token standards.
- Blockchain:Distributed ledger settlement remains peripheral to mainstream clearing, with pilot programs in cross-border remittance corridors. Regulatory uncertainty constrains depository institution participation.
- NFC Technology:Near-field radio protocols enable device-to-terminal communication at 13.56 MHz with sub-10-centimeter range. Smartphone penetration and terminal refresh cycles drive deployment timing.
Contactless payment terminals absorb the bulk of hardware refresh investment; tokenization implementation is climbing the fastest among e-commerce merchants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley venture capital flows and Toronto-Waterloo fintech clusters anchor payment innovation density across the continent. Regional deployment patterns concentrate infrastructure investment in coastal metropolitan corridors while interior markets follow with lagged adoption cycles.
United States
Enterprise SaaS billing platforms and quick-service restaurant chains drive merchant acceptance volume. The Consumer Financial Protection Bureau's open banking rulemakings mandate standardized data sharing APIs. New York City anchors network token vault deployments while San Francisco Bay Area fintechs pilot embedded finance convergence.
Canada
Credit union modernization and transit system contactless adoption accelerate real-time payment migration. Payments Canada's retail payment system overhaul compresses settlement windows to seconds. Toronto concentrates core banking vendor relationships while Vancouver anchors municipal NFC transit deployments.
Mexico
Remittance corridor digitization and unbanked population mobile wallet penetration expand addressable market. Banco de México's SPEI instant payment infrastructure extends real-time rails to smaller financial institutions. Mexico City anchors fintech venture formation while northern border states concentrate cross-border commerce integration.
North America Payments Market Competitive Landscape
Global majors compete with regional champions across network infrastructure and merchant acquiring dimensions. Network incumbents anchor positions through tokenization standards and interchange economics while fintech disruptors embed checkout flows into vertical software platforms. Three archetypes dominate: card network operators with vault infrastructure, full-stack merchant acquirers with SaaS integration, and platform-native payment enablers with developer-centric APIs. Competitive moves concentrate on core banking vendor lock-in and open banking connectivity layer construction.
Within the network operator tier, Visa Inc. and Mastercard Incorporated anchor global token standards while Fiserv Inc. exemplifies core banking integration strategies. Stripe Inc. occupies the platform-native archetype with embedded checkout infrastructure. These entities represent divergent bets on whether merchant relationships or issuer technology stacks capture superior margin retention.
| Leading Market Players |
|---|
| Fiserv Inc. |
| Stripe Inc. |
| Visa Inc. |
| Amazon.com Inc. |
| Apple Inc. |
| Mastercard Incorporated |
| Block Inc. |
| Google LLC |
| PayPal Holdings Inc. |
| Others |
Value Network & Pricing Analysis
Enterprise SaaS platforms and quick-service restaurant chains anchor merchant acquiring demand across the United States and Canada, locking in subscription-based pricing models that bundle interchange optimization with vault infrastructure. This buyer concentration rewards providers who embed payment acceptance into vertical software workflows rather than compete on transactional spreads alone.
Pricing Analysis
Service bundling separates providers who include token vault management and fraud scoring from those who unbundle these capabilities as premium add-ons. Three-tier pricing structure across premium, standard, and economy levels stratifies by transaction volume commitment and API integration depth. Price differentiation rests on settlement speed guarantees and chargeback liability allocation. Pricing pressure stems from the Consumer Financial Protection Bureau's interchange scrutiny, compressing issuer revenue per swipe. Small businesses exhibit the highest price sensitivity, while enterprise merchants prioritize token control and custom routing over rate minimization.
Supply Chain Analysis
Direct-to-merchant channels handle hyperscale enterprise demand, while ISO networks and software platform partnerships aggregate small-business volume across dispersed geographies. Hardware manufacturing concentrates in Taiwan, South Korea, and China for NFC terminal chipsets and secure element modules. Core banking software development draws from India, Ireland, and the United States for engineering talent pools. Supply chain risk centers on single-source vulnerability for cryptographic hardware security modules used in token vault operations. Distribution runs through core banking vendor relationships that lock depository institutions into multi-year service agreements with elevated switching costs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where control over token vault infrastructure and core banking API layers determines margin retention. Players are pursuing downstream leverage through embedded finance convergence into vertical SaaS platforms.
For Market Incumbents: Deploy token vault control as the primary defensive mechanism against platform-native disruptors. Deepen core banking integration through multi-year service agreements that elevate switching costs for credit unions and community banks. Acquire specialized fraud-scoring engineering teams to address the talent scarcity constraining real-time risk infrastructure deployment. Consolidate merchant acquiring relationships through SaaS platform partnerships that bundle payment acceptance with subscription management tools. For New Entrants and Emerging Players: API-first developer experience serves as the critical wedge against legacy processor incumbents. Target underpenetrated B2B invoice automation where paper check persistence creates immediate displacement opportunity. Focus initial deployment on contractor and professional services verticals where churn reduction outweighs interchange optimization in vendor selection. Pursue open banking connectivity layer construction ahead of Consumer Financial Protection Bureau data portability mandates. For Investors and Strategic Acquirers: The window for entry favors platform-native payment enablers with established vertical SaaS distribution. Long-term viability hinges on whether merchant relationships or issuer technology stacks capture superior economics through the forecast horizon. Monitor FedNow adoption velocity among credit unions as the signal for real-time payment infrastructure investment inflection. Acquisition targets should demonstrate embedded finance API integration with at least two vertical software categories.| Strategic Initiative | Industry Significance |
|---|---|
| Token Vault Infrastructure Expansion | Network token standards shift fraud liability toward vault operators, rewarding early HSM capacity deployment. |
| Vertical SaaS Platform Integration | Embedded checkout APIs capture merchant relationships at the point of software procurement decision. |
| FedNow Connectivity Layer Development | Real-time rail integration separates modernized credit unions from batch-dependent competitors. |
| Open Banking API Standardization | Consumer Financial Protection Bureau mandates force data portability that unlocks aggregator business models. |
| Core Banking Vendor Consolidation | Middleware acquisition reduces COBOL legacy dependency for instant payment workflow deployment. |
Research Methodology
Independent corroboration across primary interviews with payment network executives, core banking vendor product managers, merchant acquiring sales directors, and fintech platform engineers underwrites the qualitative findings. Secondary validation draws from Federal Reserve payment system reports, Payments Canada modernization disclosures, SEC 10-K filings from listed processors, and Consumer Financial Protection Bureau rulemaking dockets. Bottom-up transaction volume modeling triangulates against top-down market sizing from interchange flow analysis.
Rate-of-change decomposition separates volume growth from pricing evolution across the analysis window. Segmentation dimensions include payment method, transaction type, customer segment, and technology deployment tier. CAGRs derive from historical trajectory analysis adjusted for structural shifts including FedNow deployment timing and open banking regulatory implementation. Forecast inputs incorporate real-time payment infrastructure investment cycles and SaaS billing platform penetration curves.
Several conditions sit outside the modeled scope, including unanticipated regulatory intervention on interchange caps, core banking vendor insolvency events, and cryptocurrency stablecoin corridor disruption. Practitioners should monitor FedNow transaction volume reporting and Consumer Financial Protection Bureau open banking final rule publication for early signals of forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Asia-Pacific Payments Market
Payments
Sweden POS Terminals Market
Payments
Africa Virtual Cards Market
Payments
Smart Home Payments Market
Payments
Portugal POS Terminals Market
Payments
Singapore Gift Card and Incentive Card Market
Payments
Denmark Payments Market
Payments
North America Payment Gateway Market
Payments
Cloud Billing Market
Payments
Philippines Remittance Market
Payments
Germany POS Terminal Market
Payments
Asia-Pacific Payment Analytics Software Market
Payments
In-Vehicle Payment Services Market
Payments
Canada Mobile Payments Market
Payments
Canada Payment Gateway Market
Payments
Asia Pacific POS Terminal Market