
 USA Travelers Insurance Market | 2026-2036
USA Travelers Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
USA Travelers Insurance Market Insights
Embedded parametric triggers and real-time claims APIs is tilting product architecture toward instant fulfillment models. Allianz leverages its global assistance infrastructure to sustain competitive positioning in medical evacuation and trip cancellation segments. Chubb Limited anchors high-net-worth vacationer policies with specialized concierge services and elevated coverage ceilings. American International Group competes through its commercial travel accident portfolio, targeting Fortune 500 accounts with integrated risk management tools.
Travelers insurance constitutes short-duration accident and health coverage, plus trip-specific financial protection, underwritten through admitted and surplus lines carriers and distributed via direct, broker, and embedded travel-booking channels. Policy forms specify per-trip medical limits, evacuation cost ceilings, and pre-existing condition lookback periods that determine claims admissibility. Single Trip policies dominate premium volume among occasional vacationers, while Annual Multi-Trip products generate superior retention economics from frequent business travelers. Online Platforms are capturing distribution share fastest, though Brokers retain pricing power in corporate accounts and complex itinerary coverage.
NAIC model laws and state-level insurance department rate filings shape product form standardization across admitted carriers, while surplus lines regulation permits customized coverage for excluded perils. The SEC's investment adviser oversight extends to travel insurance administrators offering bundled trip-protection products with advisory services. Stakeholders must monitor evolving state-by-state regulatory divergence on parametric trigger definitions and embedded distribution partnerships.
Market Dynamics
Embedded parametric triggers and real-time claims APIs are compressing settlement timelines from weeks to minutes, forcing carriers to rebuild core systems around instant fulfillment architectures rather than traditional adjudication workflows.
Growth Catalysts
- Post-pandemic corporate mobility rebound:Business travelers are expanding coverage purchases as Fortune 500 firms restore pre-2020 travel budgets and duty-of-care obligations intensify.
- NAIC model law standardization:The National Association of Insurance Commissioners disclosure mandates are reducing policy comparison friction and accelerating purchase decisions across state lines.
- Hurricane corridor risk elevation:Florida and California outbound volumes combined with climate-driven trip disruption frequency are elevating attachment rates in high-exposure coastal markets.
Market Restraints
- Medical cost inflation volatility:Evacuation and foreign hospitalization claims exposure ties directly to healthcare input costs that carriers cannot fully hedge.
- Surplus lines capacity concentration:Customized coverage for excluded perils depends on a thin cohort of non-admitted carriers with limited reinsurance backing.
- Parametric trigger definition fragmentation:State-by-state regulatory divergence on automatic payout thresholds creates compliance complexity and product filing delays.
Strategic Opportunities
- Embedded distribution partnerships:Travel-booking platforms and airline checkout flows represent underpenetrated channels where coverage attaches at point-of-sale without separate purchase friction.
- Annual multi-trip retention economics:Frequent business traveler segments offer superior lifetime value through automatic renewal structures and reduced acquisition cost per policy.
- SEC oversight clarity:Investment adviser rules extending to bundled trip-protection products create compliance benchmarks that favor scaled administrators with existing regulatory infrastructure.
Industry Challenges
- Legacy core system integration:Real-time API architectures require rebuilding policy administration platforms that many carriers operate on decades-old batch-processing infrastructure.
- Pre-existing condition lookback adjudication:Claims admissibility disputes generate operational overhead and customer friction at precisely the moment of maximum policyholder stress.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | USA Travelers Insurance Market |
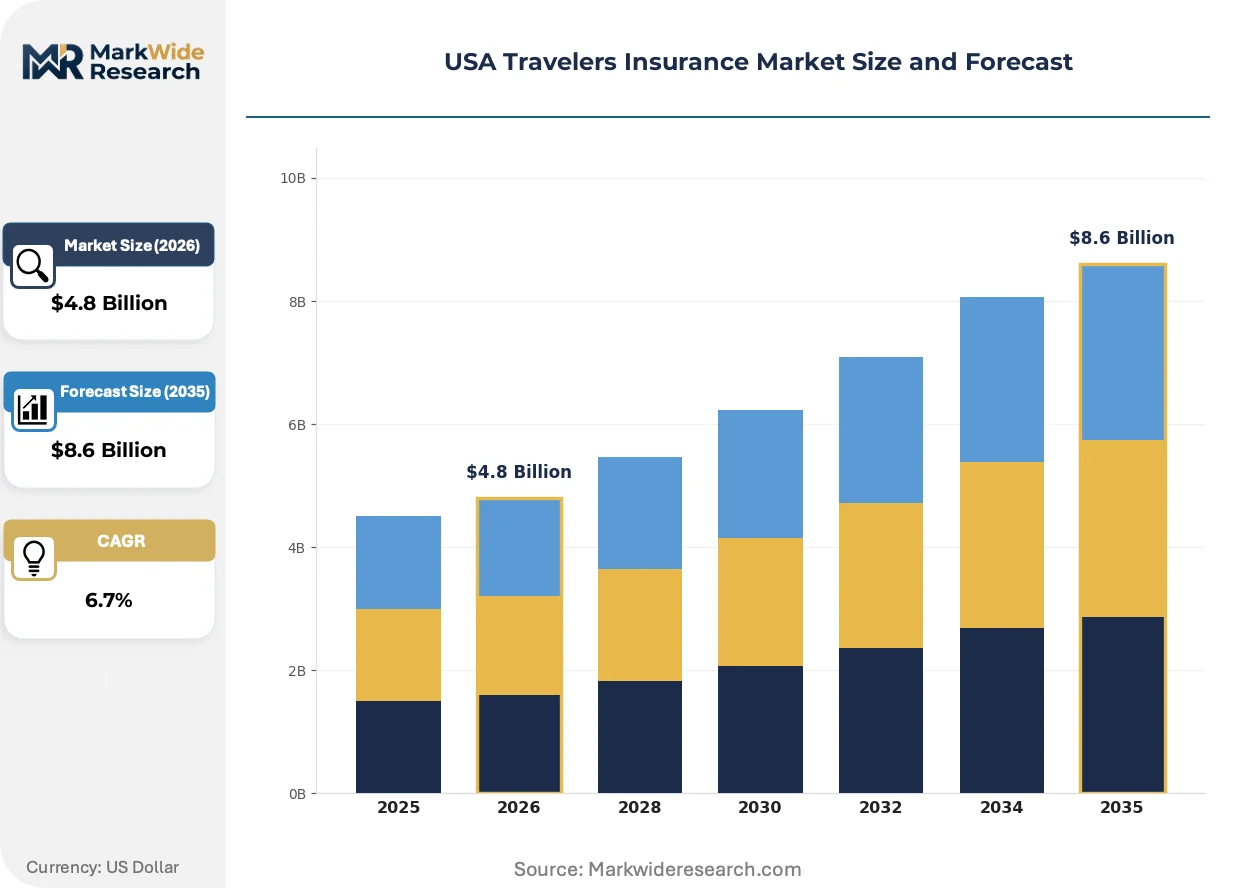
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Single Trip, Annual Multi-Trip, Comprehensive, Limited Coverage Level: Basic, Standard, Premium, Elite Customer Type: Business Travelers, Vacationers, Students, Seniors Distribution Channel: Direct Sales, Online Platforms, Travel Agents, Brokers |
| Companies Covered | Allianz, American International Group, AXA, USI Insurance Services, Seven Corners, Travel Insured International, Zurich, Nationwide Mutual Insurance Company, Chubb Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
USA Travelers Insurance Market Trends and Innovations
Instant fulfillment architectures are replacing batch-processing claims workflows, with three convergent developments compressing the entire value chain from purchase through payout.
Parametric weather triggers is collapsing the traditional claims investigation cycle for trip cancellation and interruption coverage. Carriers embedding NOAA storm-track data and flight-status APIs are triggering automatic payouts to policyholders within hours of qualifying events. Florida and Gulf Coast travelers now expect settlement completion before physical return from disrupted itineraries.
NAIC model laws are mandating standardized benefit triggers and plain-language disclosures across admitted carriers. State insurance departments in California, New York, and Texas are aligning filing requirements, reducing product development cycle times for multi-state programs. Surplus lines carriers face competitive pressure to match this transparency even where formal compliance is optional.
Business traveler procurement patterns are consolidating coverage selection authority within corporate risk management functions rather than individual employee choice. Fortune 500 accounts are negotiating master policies with integrated duty-of-care tracking and centralized billing, displacing the retail single-trip purchase model. This concentration is most visible in technology and financial services verticals with high international travel intensity.
USA Travelers Insurance Market Segmentation
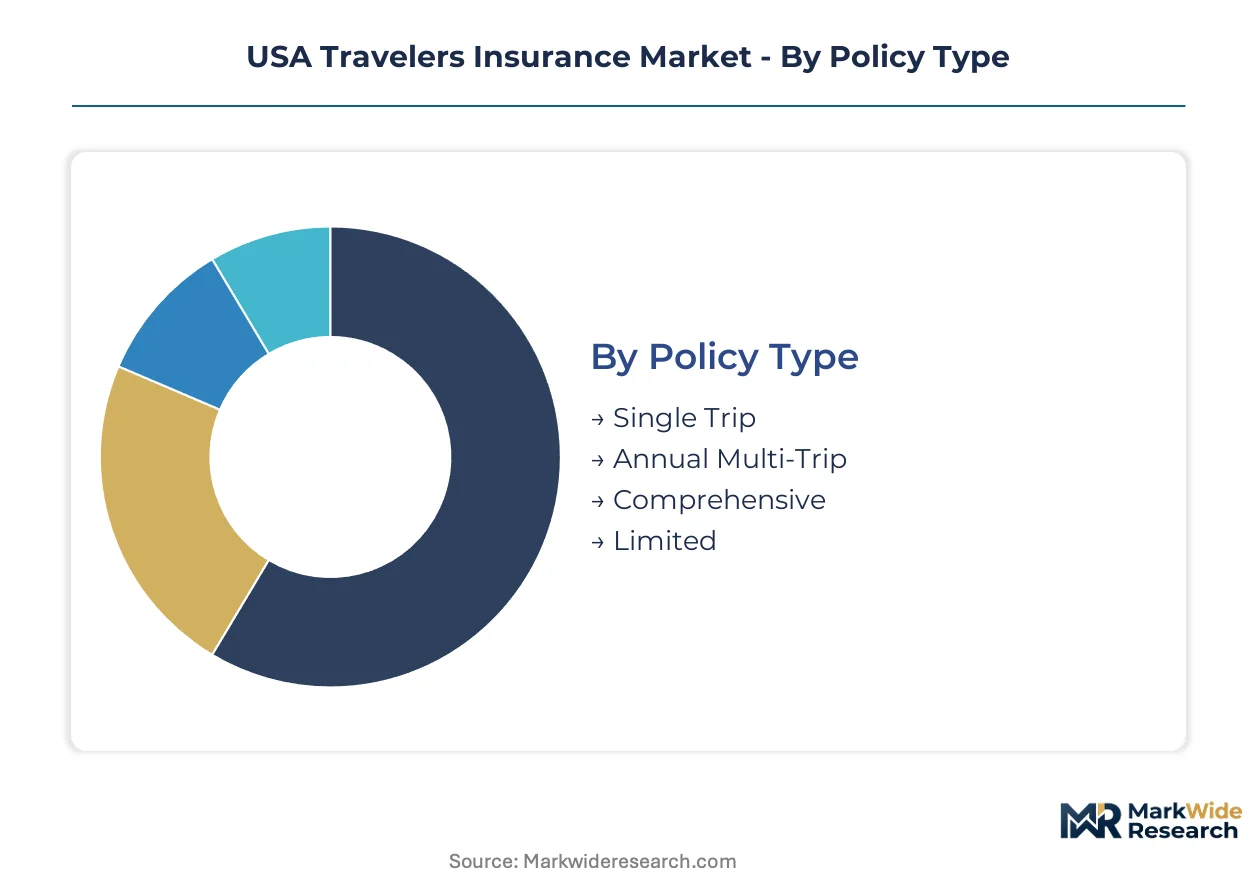
Travelers insurance products must align coverage duration, benefit depth, and distribution access with distinct risk profiles and purchase behaviors. Segmentation reveals where carriers can optimize pricing precision and reduce acquisition friction across divergent customer journeys.
Policy Type:
Cost tier structures separate occasional purchasers from high-frequency travelers with fundamentally different claims exposure and renewal economics.
- Single Trip:Short-duration coverage activated per itinerary with defined departure and return dates. Florida and California outbound vacationers drive attachment here, where hurricane-related disruption risks elevate purchase intent at point-of-sale.
- Annual Multi-Trip:12-month blanket protection for unlimited journeys within geographic limits and per-trip duration caps. Corporate risk managers at Fortune 500 firms are consolidating procurement authority here, displacing individual employee purchases with master policy structures.
- Comprehensive:Bundled medical, evacuation, cancellation, and baggage protection in unified policy forms. NAIC model law standardization is compressing development cycles for these complex products.
- Limited:Narrow peril coverage targeting specific risks like trip cancellation only or medical-only protection. Price-sensitive segments use these as entry points before upgrade pathways.
Single Trip holds installed capacity. Annual Multi-Trip is rotating up the share rankings.
Coverage Level:
Benefit ceilings and service tiers stratify customers by evacuation cost tolerance and concierge service expectations.
- Basic:Entry-tier medical limits and standard evacuation ceilings with minimal ancillary services. Students and budget vacationers concentrate here, though claims disputes over pre-existing condition lookbacks generate operational friction.
- Standard:Mid-range benefit limits with 24/7 assistance hotlines and streamlined claims workflows. Online Platforms are capturing distribution share fastest in this tier through embedded checkout integrations.
- Premium:Elevated medical ceilings, private evacuation options, and dedicated case managers. High-net-worth vacationers in coastal hurricane corridors attach here for trip disruption protection.
- Elite:Unlimited medical evacuation, concierge medical referrals, and family reunification services. Chubb Limited anchors positioning here through specialized service infrastructure.
Premium holds installed capacity. Elite is climbing the fastest.
Customer Type:
Travel frequency and duty-of-care obligations create divergent procurement patterns and lifetime value profiles.
- Business Travelers:Employees traveling on corporate authorization with employer-purchased or reimbursed coverage. Post-pandemic mobility rebound is restoring pre-2020 travel budgets and intensifying duty-of-care tracking requirements.
- Vacationers:Leisure travelers purchasing discretionary protection for personal itineraries. Florida and California residents show elevated attachment due to climate-driven disruption exposure.
- Students:Educational program participants requiring semester-long or academic-year coverage. Study abroad administrators are consolidating placement decisions with preferred carrier partnerships.
- Seniors:Travelers aged 65+ with elevated medical risk profiles and pre-existing condition complications. Medicare exclusion gaps for foreign hospitalization drive demand here.
Business Travelers holds installed capacity. Vacationers is gaining share fastest.
Distribution Channel:
Customer acquisition cost and policy complexity determine which channels dominate each segment.
- Direct Sales:Carrier-owned websites and call centers capturing price-comparison shoppers. Real-time API architectures are compressing quote-to-bind timelines here.
- Online Platforms:Travel-booking sites and airline checkout flows embedding coverage at point-of-sale. This channel is expanding most quickly as parametric triggers enable instant fulfillment without separate purchase friction.
- Travel Agents:Human advisors bundling coverage with itinerary planning for complex multi-destination trips. Seniors and first-time international travelers rely here for explanation of pre-existing condition clauses.
- Brokers:Independent intermediaries retaining pricing power in corporate accounts and complex itinerary coverage. Fortune 500 risk managers negotiate master policies through this channel.
Brokers holds installed capacity. Online Platforms is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Florida and California outbound corridors drive premium concentration, with hurricane disruption exposure elevating attachment rates along coastal departure zones. Texas and New York Metro follow as secondary volume centers, while Mountain West leisure corridors expand fastest post-pandemic.
Florida
Hurricane-related trip cancellation exposure concentrates demand in Miami-Dade, Broward, and Orange County corridors. The state's Office of Insurance Regulation enforces surplus lines disclosure requirements that align with NAIC model law standards. Orlando's tourism infrastructure anchors embedded distribution partnerships with airline and cruise checkout flows.
California
Earthquake and wildfire evacuation coverage drives premium attachment in Los Angeles and San Francisco departure markets. The California Department of Insurance mandates plain-language benefit trigger disclosures that compress policy comparison friction. San Diego's biotech corridor generates business traveler volume through corporate risk management procurement.
Texas
Energy sector corporate mobility sustains annual multi-trip policy demand in Houston and Dallas-Fort Worth. The Texas Department of Insurance maintains admitted carrier filing requirements that standardize pre-existing condition lookback periods. Austin's technology cluster is consolidating coverage selection authority within Fortune 500 risk management functions.
New York Metro
Financial services international travel intensity supports premium-tier medical evacuation coverage demand. The New York State Department of Financial Services enforces investment adviser oversight rules that extend to bundled trip-protection products. Manhattan's corporate headquarters concentration anchors master policy negotiations with integrated duty-of-care tracking.
Pacific Northwest
Technology sector remote-work flexibility is expanding leisure travel frequency across Washington and Oregon. State insurance departments in Olympia and Salem align with NAIC disclosure mandates for admitted carrier standardization. Seattle's aerospace and software corridors represent underpenetrated embedded distribution opportunities at point-of-sale.
USA Travelers Insurance Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented tier structures. Admitted carriers with multi-state filing capacity face surplus lines competitors offering customized excluded-peril coverage. Strategic archetypes include global assistance infrastructure operators, high-net-worth concierge service specialists, and commercial risk management integrators. Competitive moves concentrate on embedded distribution partnerships and real-time claims API development.
Among global assistance infrastructure operators, Allianz and Zurich represent archetype leaders with medical evacuation and trip cancellation positioning. Chubb Limited occupies the high-net-worth specialist tier. American International Group anchors commercial travel accident portfolio concentration. These three exemplify divergent competitive vectors across the market structure.
| Leading Market Players |
|---|
| Allianz |
| American International Group |
| AXA |
| USI Insurance Services |
| Seven Corners |
| Travel Insured International |
| Zurich |
| Nationwide Mutual Insurance Company |
| Chubb Limited |
| Others |
Pricing and Supply Chain Analysis
Miami-Dade and Orlando's insurance administrator clusters concentrate policy administration capacity, feeding pricing power to carriers with embedded distribution partnerships at Florida's cruise and airline departure nodes. Parametric trigger standardization across these hubs compresses development costs, while real-time claims API deployment creates tiered service economics that separate instant-settlement premiums from traditional adjudication discounts.
Pricing Analysis
Legacy batch-processing infrastructure versus cloud-native instant fulfillment architectures drives a generational pricing gap in policy administration costs. Three-tier pricing structure across premium, standard, and economy levels stratifies by evacuation ceiling height and concierge service depth, with medical inflation volatility pressuring mid-tier margins most acutely. Corporate risk managers at Fortune 500 firms show lowest price sensitivity due to duty-of-care liability exposure, while budget vacationers in hurricane corridors drive economy-tier volume.
Supply Chain Analysis
Extended payment terms from travel-booking platforms to insurance administrators stretch working capital requirements for mid-tier carriers competing on embedded distribution. Policy administration draws from Ireland and India for back-office processing, with medical evacuation networks anchored in South Africa and Singapore for geographic coverage density. Single-source vulnerability concentrates in NOAA data feed licensing for parametric triggers, while distribution runs through airline checkout flows, cruise line partnerships, and corporate broker channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Real-time claims API development talent and parametric trigger actuarial expertise sit in short supply relative to carrier digitization timelines, creating capability bottlenecks that favor scaled administrators with existing infrastructure investments.
For Market Incumbents: Entrench competitive positioning through exclusive embedded distribution partnerships with major airline and cruise checkout platforms, while accelerating legacy core system replacement to match instant fulfillment economics from cloud-native entrants. Vertical integration into medical evacuation airlift capacity secures service differentiation against reinsurance-dependent competitors. For New Entrants and Emerging Players: Pacific Northwest technology corridor corporate accounts offer underpenetrated annual multi-trip policy white space, with Seattle's aerospace and software clusters lacking established master policy relationships. Target study abroad program administrators at mid-tier universities for semester-long coverage placement, leveraging NAIC model law standardization to compress multi-state filing timelines versus incumbent compliance overhead. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because embedded distribution control points are concentrating among three channel archetypes, with medical evacuation network ownership representing the scarcest complementary asset. Watch for parametric trigger definition convergence across state insurance departments as the inflection signal for multi-state program scalability premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Distribution Partnership | Airline and cruise checkout integration captures policyholders at point-of-sale without separate purchase friction. |
| Real-Time Claims API Development | Instant fulfillment architectures compress settlement timelines from weeks to minutes for competitive differentiation. |
| Medical Evacuation Network Expansion | Owned airlift capacity reduces reinsurance dependency and elevates service tier positioning in premium segments. |
| Parametric Trigger Standardization | NOAA data feed integration enables automatic payout workflows that reduce operational overhead and customer friction. |
| Annual Multi-Trip Retention Program | Corporate master policy structures lock in Fortune 500 accounts with automatic renewal and centralized billing economics. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with insurance carrier product executives, travel-booking platform partnership directors, corporate risk managers, and state insurance department filing officers; and secondary validation through NAIC model law documentation, SEC investment adviser oversight filings, state insurance department rate filings, and airline-cruise industry partnership disclosures. Bottom-up policy volume estimates triangulated against top-down premium projections.
Forecast inputs span policy type segmentation, coverage level tiers, customer type archetypes, and distribution channel dynamics across the analysis window. CAGRs derive from regression against historical attachment rate trends, corporate travel budget restoration patterns, and parametric trigger adoption curves. Modeled inputs include hurricane frequency projections for Florida and California corridors, medical cost inflation assumptions, and embedded distribution penetration rates by travel-booking platform.
The forecast holds incumbent behavior within observed patterns; aggressive technology investment or exclusive distribution lock-ups by scaled administrators would shift outcomes beyond projected ranges. Macroeconomic recession impacting corporate travel budgets, state-by-state regulatory divergence on parametric definitions, or catastrophic hurricane seasons exceeding modeled frequency would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Europe Car Insurance Market
Insurance
Crop Insurance Market
Insurance
United States Commercial Insurance Market
Insurance
North America Family Floater Health Insurance Market
Insurance
Asia-Pacific Critical Illness Insurance Market
Insurance
Singapore Property and Casualty Insurance Market
Insurance
Earthquake Insurance Market
Insurance
Cybersecurity Insurance Market
Insurance
Germany Property and Casualty Insurance Market
Insurance
Single Trip Travel Insurance Market
Insurance
Self Funded Insurance Market
Insurance
Reinsurance Market
Insurance
Auto Compulsory Insurance Market
Insurance
United Kingdom Car Insurance Market
Insurance
Global Cargo Transportation Insurance Market
Insurance
Saudi Arabia Property and Casualty Insurance Market