
 Tanzania Mobile Money Market | 2026-2036
Tanzania Mobile Money Market Size, Share, and Industry Trends Forecast 2026-2036
Tanzania Mobile Money Market Intelligence
Software-defined wallet features and API-based merchant integrations is restructuring what mobile money providers monetize in Tanzania. M-Pesa Tanzania leverages its agent network density to sustain dominance in rural corridors. Airtel Money competes through bundled voice-data-money offerings that anchor subscriber retention. HaloPesa differentiates by targeting diaspora remittance corridors with competitive forex positioning.
Tanzania mobile money denotes electronic financial services delivered via mobile devices, enabling real-time fund transfers, bill settlement, and merchant payments through USSD sessions, native applications, or SMS gateways without requiring traditional bank account ownership. Its primary commercial purpose is financial inclusion for the unbanked population while reducing cash handling costs for micro-merchants. Peer-to-Peer transfers occupy the largest transaction volume pool, though Mobile Payments to merchants represent the fastest-growing revenue segment as POS integration expands. The Unbanked user segment drives absolute user growth, while Corporations generate the highest per-transaction value and margin concentration.
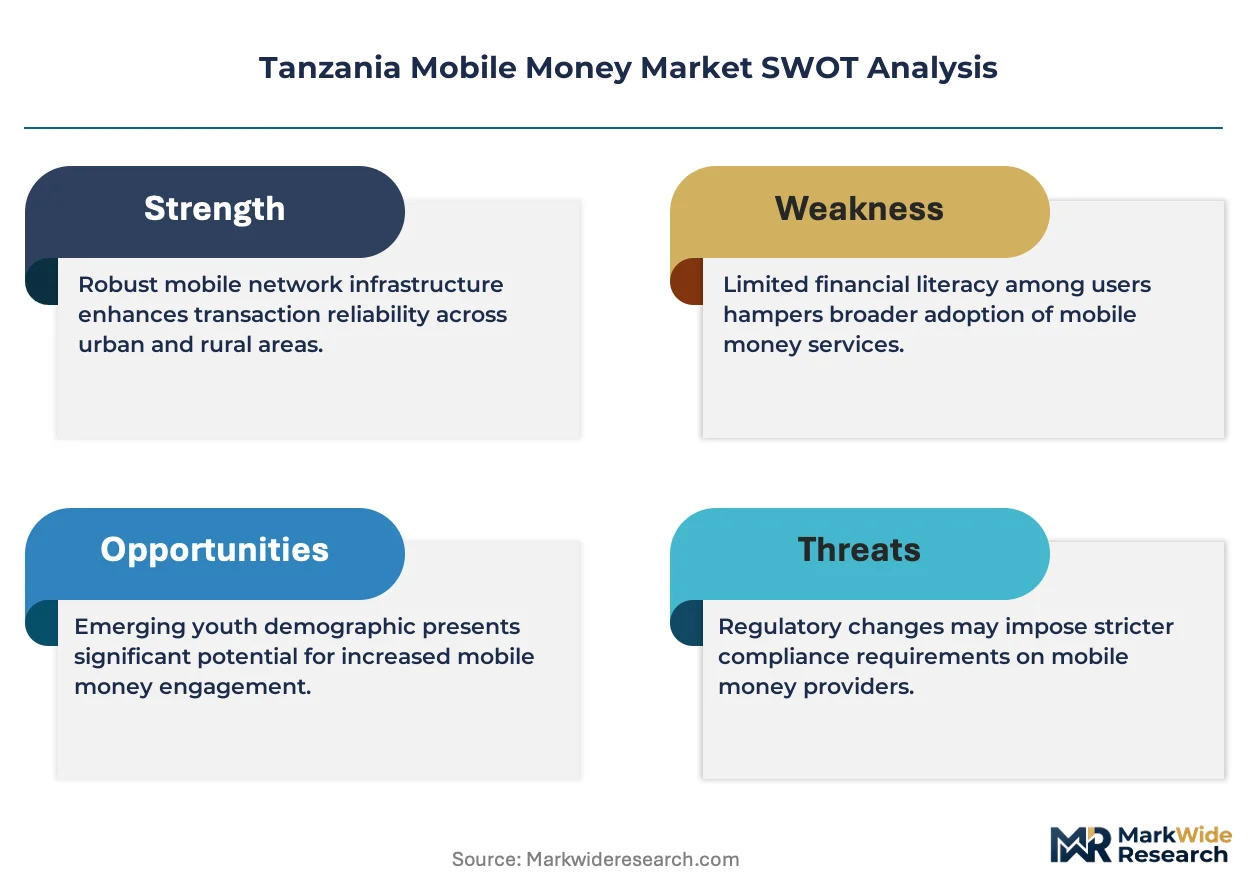
The Bank of Tanzania enforces licensing frameworks under the National Payment Systems Act, while the Tanzania Communications Regulatory Authority governs telecom interoperability standards that shape platform access and pricing parity. These regulators mandate agent network compliance, consumer fund protection, and transaction reporting thresholds that determine market entry feasibility. Stakeholders must monitor pending central bank digital currency pilots and evolving data localization requirements that could redraw competitive boundaries for platform operators.
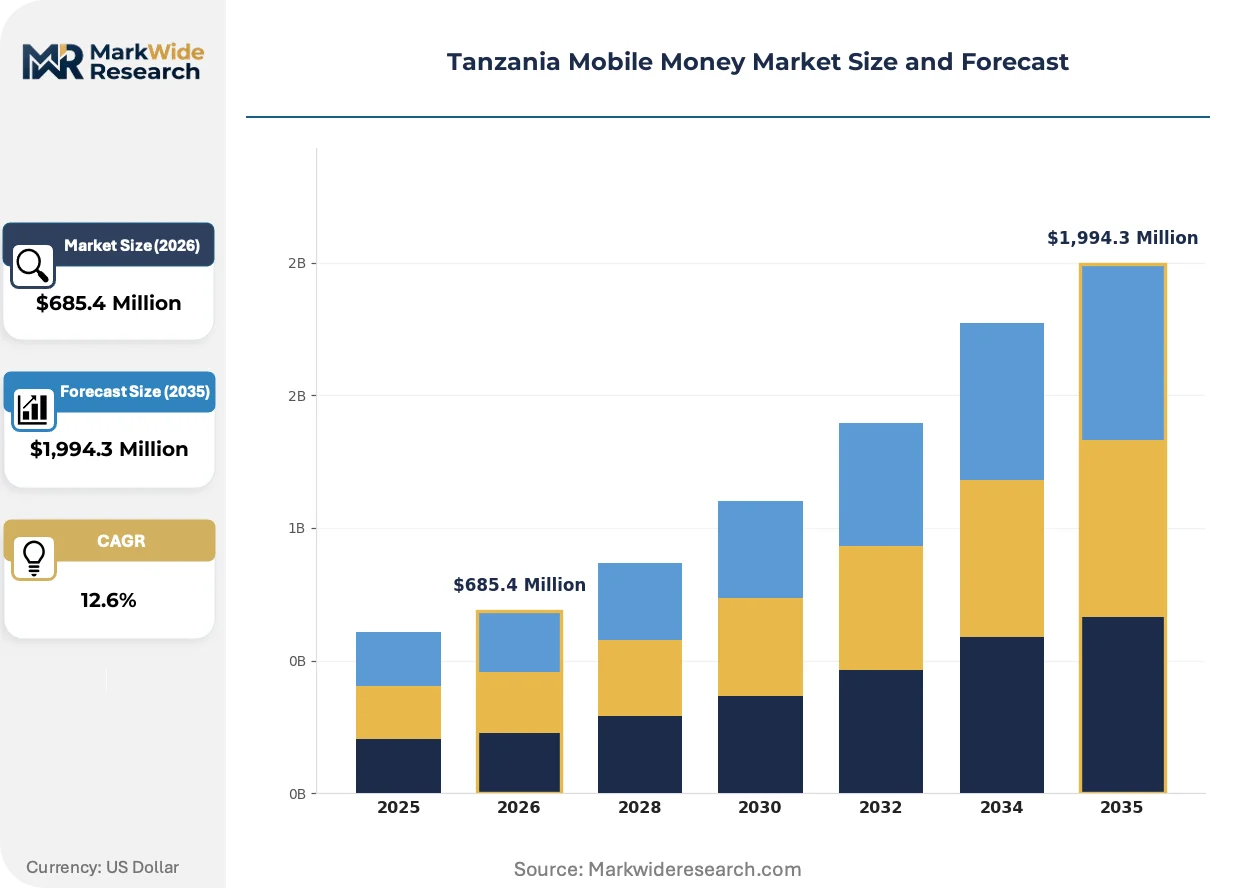
Market Dynamics
Agent network density in Dar es Salaam's metropolitan corridor is concentrating transaction liquidity and reshaping how mobile money providers compete for merchant payment volume.
Growth Catalysts
- National Payment Systems Act reforms:The Bank of Tanzania's tightening licensing requirements are accelerating consolidation among compliant digital financial service providers.
- Small business merchant integration:Urban micro-retailers are adopting POS-linked mobile payment acceptance to reduce cash handling costs.
- Diaspora remittance corridors:Competitive forex positioning on inbound transfers from East African Community neighbors is expanding addressable transaction pools.
Market Restraints
- Agent liquidity management costs:Float requirements for rural agent networks consume working capital and compress unit economics in low-density corridors.
- Telecom infrastructure concentration:USSD gateway reliability depends on two dominant mobile network operators, creating single-point vulnerability.
- Interoperability settlement delays:Cross-platform fund transfers face technical friction that degrades user experience versus closed-loop alternatives.
Strategic Opportunities
- Arusha and Mwanza urban corridors:Secondary city merchant payment penetration remains underdeveloped relative to Dar es Salaam's density.
- API-based embedded finance:Non-financial platforms in agriculture and logistics are integrating wallet functionality through standardized interfaces.
- Central bank digital currency pilots:Pending Bank of Tanzania initiatives could redraw settlement infrastructure and tiered provider access.
Industry Challenges
- Agent training and retention:High turnover in rural agent networks degrades service consistency and compliance adherence.
- Legacy core banking integration:Traditional financial institutions face technical debt when connecting to real-time mobile money rails.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tanzania Mobile Money Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,994.3 Million |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Peer-to-Peer, Mobile Payments, Bill Payments, Remittances User Segment: Individuals, Small Businesses, Corporations, Unbanked Transaction Size: Micro, Small, Medium, Large Technology: USSD, Mobile App, SMS, Web Portal |
| Companies Covered | HaloPesa, SelcomPesa, M-Pesa Tanzania, Z-Pesa, TTCL Pesa, Mixx by Yas, AzamPesa, Tanz-Pay, Airtel Money, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tanzania Mobile Money Market Strategic Shifts & Innovations
Software-defined wallet architectures are displacing monolithic platform designs and enabling faster feature deployment cycles across Tanzania's mobile money infrastructure.
API-based merchant integration is modularizing how payment functionality embeds into non-financial applications. Agricultural supply chain platforms in the Lake Zone are adopting these interfaces to enable input financing and produce settlement. This modularity is compressing time-to-market for specialized wallet features and fragmenting provider control over user touchpoints.
The Bank of Tanzania's evolving agent network compliance mandates are tightening operational standards for cash-in/cash-out liquidity management. Micro-merchant aggregators must now maintain real-time transaction reporting thresholds that increase back-office overhead. Tier-2 providers in Dodoma and Mbeya are responding by consolidating agent management under centralized super-agent structures.
Buyer preference is rotating toward bundled voice-data-money offerings that reduce switching friction between telecom and financial services. Urban subscribers in Dar es Salaam's Kinondoni and Ilala districts are consolidating spend under single-provider ecosystems. This concentration is visible most acutely among salaried employees receiving wages through mobile disbursement.
Tanzania Mobile Money Market Segmentation
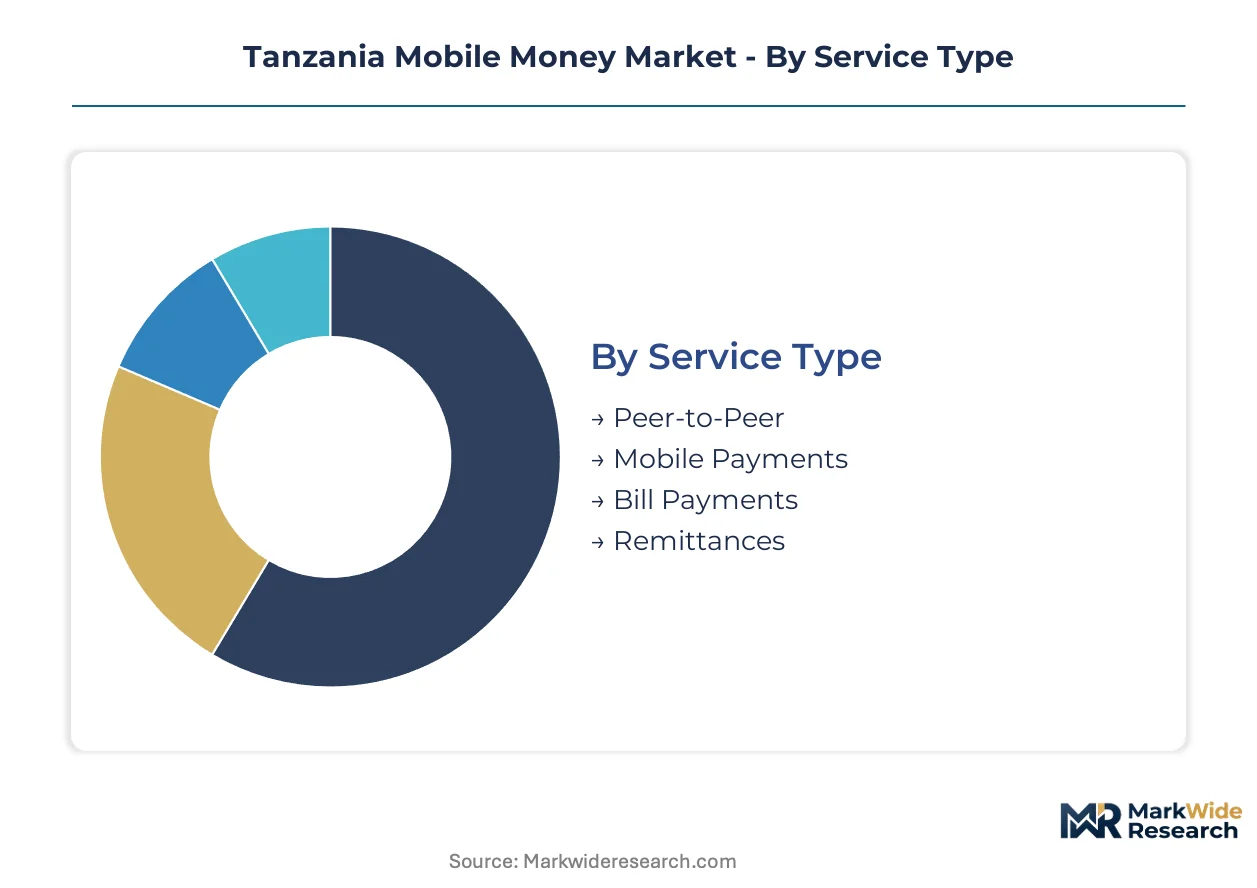
Mobile money providers in Tanzania monetize distinct user behaviors and transaction patterns through segmented service architectures. Each category reflects different capital requirements, regulatory exposure, and margin profiles that shape competitive positioning across Dar es Salaam's corridors and secondary urban centers.
Service Type:
Capital intensity varies sharply across service types, with merchant payment infrastructure demanding the heaviest upfront investment in POS integration and agent liquidity pools.
- Peer-to-Peer:Fund transfers between individual wallets through USSD sessions or native applications. Dar es Salaam's Kinondoni and Ilala districts concentrate absolute transaction volume, driven by informal sector wage disbursement patterns and family support networks.
- Mobile Payments:Merchant-facing transactions at retail points of sale. Micro-retailers in urban centers adopt these to reduce cash handling costs, though POS hardware subsidies and merchant onboarding expenses compress provider margins in the near term.
- Bill Payments:Utility and service settlement through integrated billing APIs. Tanzania Electric Supply Company and Dar es Salaam Water and Sewerage Authority integrations anchor demand.
- Remittances:Cross-border fund flows, particularly from East African Community neighbors. Competitive forex positioning distinguishes diaspora-focused providers.
Most installed capacity flows through Peer-to-Peer. Expansion is steepest in Mobile Payments.
User Segment:
Customer acquisition costs and lifetime value diverge substantially across user types, with corporate onboarding requiring dedicated relationship management infrastructure.
- Individuals:Salaried employees and informal workers conducting personal financial transactions. Dar es Salaam's metropolitan corridor dominates user density, where bundled voice-data-money offerings reduce churn.
- Small Businesses:Micro-retailers and service providers accepting digital payments. These users generate merchant payment volume growth but require intensive agent network support for cash-in/cash-out liquidity.
- Corporations:Formal enterprises disbursing wages and settling supplier invoices. Per-transaction values and margins concentrate here, though sales cycles extend due to procurement complexity.
- Unbanked:Population segments without traditional bank account ownership. Rural corridors in Dodoma and Mbeya drive absolute user growth, constrained by agent liquidity management costs and USSD gateway reliability.
Individual wallets constitute the broadest installed base. Corporate adoption is gaining share fastest.
Transaction Size:
Revenue per transaction and fraud exposure scale non-linearly with transaction value, shaping risk management and KYC tiering investments.
- Micro:Transactions below daily wage thresholds, typically conducted via USSD. Agent network density in Dar es Salaam enables high-frequency, low-margin volume.
- Small:Mid-range transfers covering household expenses and small merchant purchases. Mobile app penetration concentrates this segment among smartphone owners.
- Medium:Business payments and larger family remittances. SMS gateway fallback supports feature phone users in secondary cities.
- Large:Corporate disbursements and property settlements. Real-time settlement infrastructure and enhanced authentication requirements elevate provider technology costs.
Micro transactions dominate absolute volume. Medium-value flows are climbing the fastest as merchant integration deepens.
Technology:
Platform architecture investments determine feature velocity and interoperability reach across Tanzania's dual-operator network infrastructure.
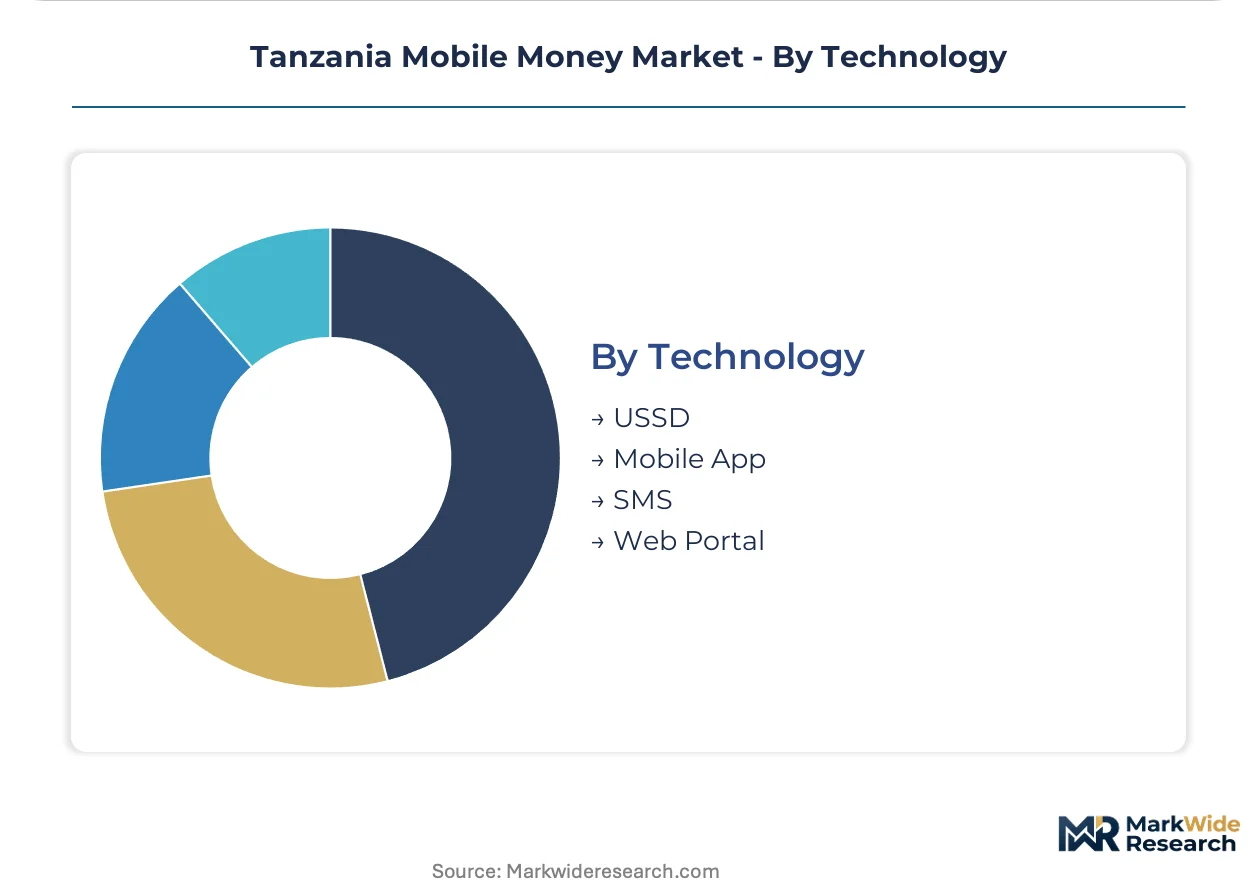
- USSD:Session-based menus accessible on all mobile devices. Dominates rural penetration where smartphone adoption lags, though gateway reliability depends on concentrated telecom infrastructure.
- Mobile App:Native smartphone applications with biometric authentication and rich interfaces. Urban subscriber retention hinges on app experience quality.
- SMS:Text-message commands for basic transactions. Serves as failover during network congestion and for legacy feature phones.
- Web Portal:Browser-based access for corporate treasurers and high-volume users. Requires internet connectivity that concentrates in metropolitan corridors.
USSD sessions carry the heaviest transaction load. Mobile App adoption is expanding most quickly among Dar es Salaam's salaried demographic.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are minimal in Tanzania's mobile money sector given the Bank of Tanzania's uniform licensing framework, yet sub-regional variation in agent density and merchant integration creates localized competitive advantages that providers exploit through differential infrastructure investment.
Dar es Salaam Metropolitan Corridor
Kinondoni and Ilala districts concentrate merchant payment volume through dense agent networks and POS-linked retail integration. The National Payment Systems Act mandates real-time transaction reporting that elevates compliance costs for micro-merchant aggregators. Salaried employees receiving wage disbursements through mobile platforms drive bundled voice-data-money adoption in this corridor.
Arusha Urban Corridor
Tourism-dependent merchant activity and agricultural supply chain settlements generate distinct transaction patterns requiring specialized wallet features. The Bank of Tanzania's interoperability standards apply uniformly, yet gateway reliability gaps degrade cross-platform fund transfers relative to Dar es Salaam. Agricultural input financing platforms in the surrounding Lake Zone are piloting API-based embedded finance integrations.
Mwanza Lake Zone Hub
Fishing industry value chains and cross-border trade with Uganda anchor remittance and merchant payment demand. Agent liquidity management costs compress unit economics in this secondary urban center compared to Dar es Salaam's density. Produce settlement platforms are adopting standardized payment interfaces to reduce cash handling in agricultural supply chains.
Dodoma Central Corridor
Government wage disbursement programs and public sector payment integrations drive corporate mobile money adoption. The Bank of Tanzania's agent network compliance mandates have prompted tier-2 providers to consolidate under centralized super-agent structures. Micro-merchant penetration remains underdeveloped relative to coastal urban centers.
Mbeya Southern Highlands
Coffee and tea export settlement cycles create seasonal transaction spikes requiring flexible liquidity management. Rural agent network turnover degrades service consistency despite National Payment Systems Act training requirements. USSD gateway dependence on concentrated telecom infrastructure creates single-point vulnerability in this corridor.
Tanzania Mobile Money Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with telecom-affiliated platforms commanding subscriber ecosystems while independent wallet providers carve niche positions in remittance corridors. Market structure tilts toward consolidated dominance by MNO-anchored platforms with dense agent networks, though regulatory licensing thresholds under the National Payment Systems Act are accelerating tier-2 consolidation. Three archetypes define competitive positioning: telecom-integrated ecosystems, diaspora-focused forex specialists, and super-agent consolidators. Dominant competitive moves include bundled service offerings that reduce subscriber churn and API-based partnerships that embed wallet functionality into non-financial platforms.
Within the telecom-integrated tier, M-Pesa Tanzania and Airtel Money exemplify ecosystem-driven retention strategies through agent network density and bundled voice-data-money offerings. HaloPesa occupies a distinct position targeting diaspora remittance corridors with competitive forex positioning. These three providers represent divergent archetypes—MNO-anchored scale, MNO-anchored bundling, and independent specialization—that collectively illustrate how competitive advantage sources fragment across Tanzania's mobile money infrastructure.
| Leading Market Players |
|---|
| HaloPesa |
| SelcomPesa |
| M-Pesa Tanzania |
| Z-Pesa |
| TTCL Pesa |
| Mixx by Yas |
| AzamPesa |
| Tanz-Pay |
| Airtel Money |
| Others |
Cost & Logistics Intelligence
Agent liquidity float requirements flow from rural cash-in/cash-out operations through to merchant payment pricing tiers, compressing margins for tier-2 providers in secondary corridors while concentrating pricing power with Dar es Salaam's dense agent networks.
Pricing Analysis
Retailer markup on POS hardware subsidies separates premium merchant aggregators from economy-tier rural agents. Pricing stratifies across premium bundled voice-data-money offerings, standard per-transaction fees, and economy USSD session rates. Cost compression in rural corridors is intensifying because agent network density dilutes per-transaction economics. Small businesses in metropolitan Kinondoni and Ilala districts exhibit lowest price sensitivity, while unbanked users in Dodoma and Mbeya drive volume through micro-transaction thresholds.
Supply Chain Analysis
Single-source vulnerability sits with USSD gateway infrastructure concentrated under two dominant mobile network operators. Platform technology draws from South African and Kenyan software vendors, with POS hardware sourcing from Chinese manufacturers. Supply chain risk centers on telecom infrastructure concentration that degrades failover resilience. Distribution runs through hierarchical super-agent structures consolidating rural liquidity management under centralized oversight.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Tanzania's mobile money sector rests on API-based embedded finance adoption that shifts revenue from transactional fees to platform licensing premiums.
For Market Incumbents: Extend agent network density advantages into Arusha and Mwanza corridors before regulatory licensing thresholds under the National Payment Systems Act harden further. Consolidate tier-2 competitors in Dodoma and Mbeya through super-agent acquisition to neutralize rural liquidity management cost disadvantages. Threats from diaspora-focused forex specialists require defensive bundling of remittance functionality into core wallet architectures. For New Entrants and Emerging Players: API-based embedded finance partnerships with agricultural supply chain platforms in the Lake Zone offer the most penetrable white-space entry. Target produce settlement and input financing workflows in Mwanza's fishing and cross-border trade corridors. Go-to-market leverage rests on standardized payment interface certification that accelerates integration timelines versus incumbent legacy architectures. For Investors and Strategic Acquirers: Consolidation pressure builds where agent network compliance costs under Bank of Tanzania mandates exceed working capital capacity of tier-2 providers. Long-term viability favors platforms with software-defined wallet architectures enabling rapid feature deployment cycles. Acquisition target archetypes include super-agent consolidators with rural network coverage and API-first specialists with agricultural sector penetration. Signal to monitor: central bank digital currency pilot announcements that redraw settlement infrastructure access tiers.| Strategic Initiative | Industry Significance |
|---|---|
| API-Based Embedded Finance Integration | Agricultural supply chain platforms in Lake Zone adopt wallet functionality for input financing settlements. |
| Super-Agent Network Consolidation | Centralized liquidity management structures reduce compliance overhead under National Payment Systems Act mandates. |
| Diaspora Remittance Corridor Expansion | Competitive forex positioning captures inbound flows from East African Community neighbors. |
| Software-Defined Wallet Architecture Migration | Modular platform designs accelerate merchant payment feature deployment cycles. |
| Secondary City Merchant Payment Penetration | Arusha and Mwanza urban corridors remain underdeveloped relative to Dar es Salaam density. |
Research Approach
Multiple input streams — primary interviews with mobile money platform executives, agent network operators, and Bank of Tanzania regulatory officials; secondary validation through National Payment Systems Act filings, Tanzania Communications Regulatory Authority interoperability standards, and telecom operator annual disclosures; plus customs data on POS hardware imports — were reconciled through bottom-up transaction volume modeling and top-down revenue triangulation.
Data-stream reconciliation across the projection horizon applied segmentation dimensions spanning service type, user segment, transaction size tier, and technology platform. CAGRs were derived from fitted growth curves anchored to disclosed agent network expansion rates and merchant onboarding trajectories. Industry-specific forecast inputs included USSD session reliability metrics and super-agent consolidation velocity in secondary urban corridors.
The model assumes a particular technology adoption path; alternative pathways for central bank digital currency infrastructure would alter the outlook. Forecasts reflect assumptions regarding regulatory licensing enforcement consistency and telecom infrastructure investment continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
In Vehicles Payment Market
Payments
Canada Prepaid Cards Market
Payments
Global Telecom Billing and Revenue Management Market
Payments
Canada Real Time Payments Market
Payments
South Africa Real Time Payments Market
Payments
South Africa Gift Card and Incentive Card Market
Payments
Vehicle Toll Collection and Access System Market
Payments
Europe Clearing Houses and Settlements Market
Payments
Cryptocurrency Payment Apps Market
Payments
Digital Transaction Management Market
Payments
Africa Virtual Cards Market
Payments
Global Mobile Payment Technology Market
Payments
Middle East & North Africa Digital Payments Market
Payments
Croatia POS Terminals Market
Payments
Mobile Payment Security Software Market
Payments
Singapore Payments Market