
 Saudi Arabia Gift Card and Incentive Card Market | 2026-2036
Saudi Arabia Gift Card and Incentive Card Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Gift Card and Incentive Card Market Analytics
Saudi fintech infrastructure is pivoting toward prepaid instrument digitization, creating fresh issuance capacity for domestic card programs. Amazon.sa leverages its logistics density to anchor online gift card redemption across the Kingdom. STC Pay competes through mobile-wallet integration with reloadable closed-loop products. Virgin Megastore specializes in experiential gifting tied to entertainment verticals, occupying a defensible niche in physical retail channels.
Gift cards and incentive cards are prepaid stored-value instruments, typically magnetic-stripe or chip-embedded, that transfer purchasing power from issuer to bearer without requiring bank-account linkage; their primary commercial purpose is to lock in future spending, capture float revenue, and enable targeted corporate rewards. Closed-loop configurations dominate margin pools because merchants retain breakage and control redemption ecosystems, while open-loop instruments are expanding fastest as SAMA-licensed fintechs embed them into digital wallets. Corporate clients represent the most concentrated demand segment, with bulk procurement from HR departments and government agencies driving volume.
SAMA's electronic payments framework and anti-money-laundering directives shape product standards by mandating KYC verification for reloadable instruments and capping anonymous transaction thresholds. The Ministry of Commerce's consumer protection regulations enforce disclosure of expiry terms and dormancy fees, directly influencing program design. Stakeholders must monitor how SAMA's evolving stablecoin and central bank digital currency experiments could displace traditional prepaid float models.
Market Dynamics
SAMA's fintech licensing wave is compressing issuance timelines for prepaid instruments, forcing traditional banks and new entrants to compete on digital onboarding speed rather than branch density.
Growth Catalysts
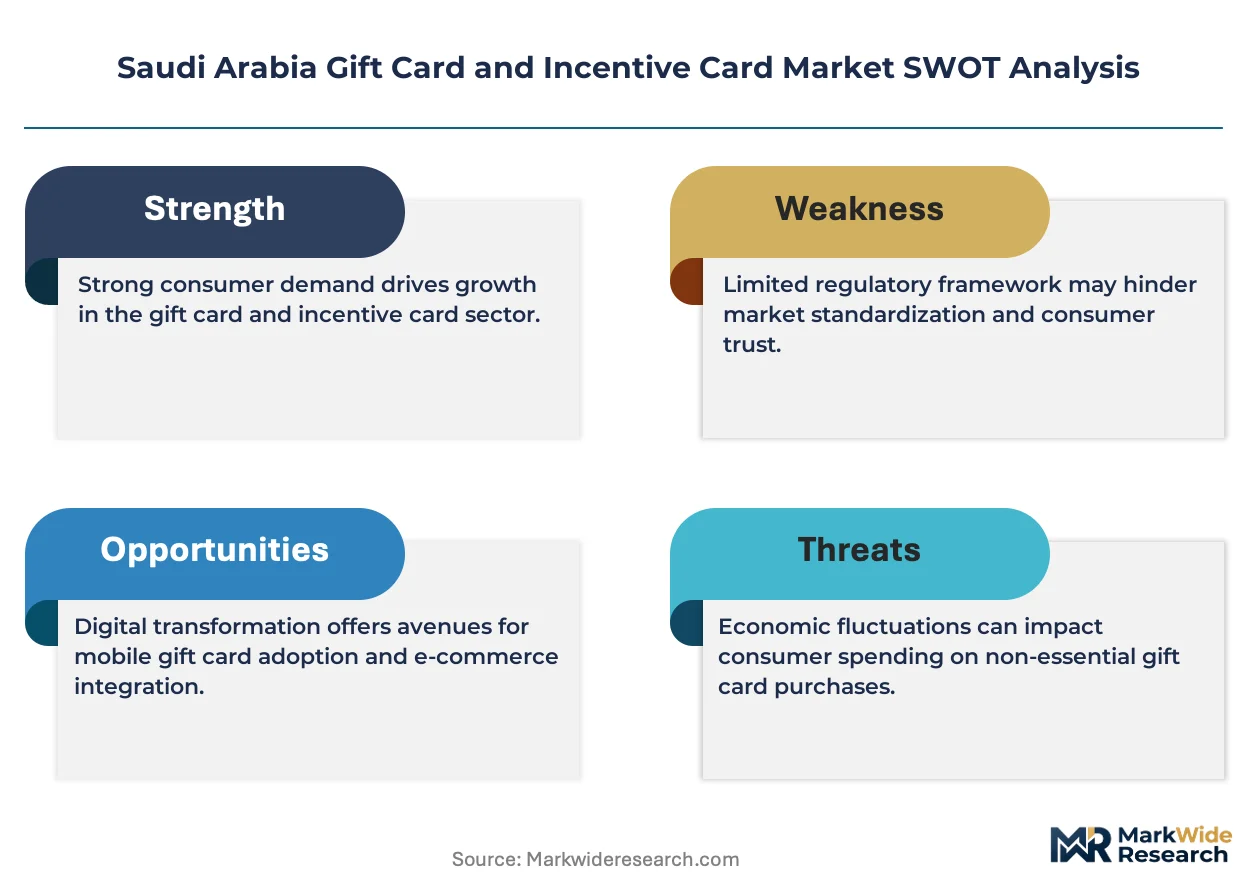
- Vision 2030 workforce mandates:Corporate HR departments across Riyadh and Jeddah are expanding prepaid incentive programs to meet localization targets, creating sustained bulk procurement demand for reloadable corporate gift instruments.
- SAMA electronic payments framework:The central bank's regulatory push for digital payments has accelerated open-loop card issuance by licensed fintechs, embedding prepaid products into mobile wallet ecosystems.
- Experiential gifting verticals:Entertainment and lifestyle merchants are deploying closed-loop configurations to capture breakage revenue and control redemption ecosystems in physical retail channels.
Market Restraints
- KYC verification requirements:SAMA mandates identity verification for reloadable instruments, adding friction to customer acquisition and increasing compliance costs for issuers targeting anonymous transaction segments.
- Breakage accounting uncertainty:Dormancy fee disclosure rules from the Ministry of Commerce limit revenue recognition flexibility, compressing margin pools for programs dependent on unredeemed balances.
- Float model displacement risk:SAMA's ongoing central bank digital currency experiments threaten traditional prepaid float mechanics by enabling direct central bank liability instruments.
Strategic Opportunities
- Government agency procurement:Bulk incentive programs for public sector workforce retention remain underpenetrated relative to private corporate deployment, offering volume expansion potential.
- Mobile-wallet convergence:Integration of NFC-enabled prepaid credentials with STC Pay and competing digital wallets creates new issuance channels beyond physical card distribution.
- Regulatory sandbox participation:SAMA's fintech licensing regime offers approved entities expedited market entry for experimental prepaid product structures.
Industry Challenges
- AML compliance talent scarcity:Issuers struggle to recruit sufficient compliance personnel capable of navigating SAMA's evolving anti-money-laundering directives for stored-value instruments.
- Legacy core banking integration:Traditional financial institutions face technical debt when connecting prepaid card management systems to decades-old transaction processing infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Gift Card and Incentive Card Market |
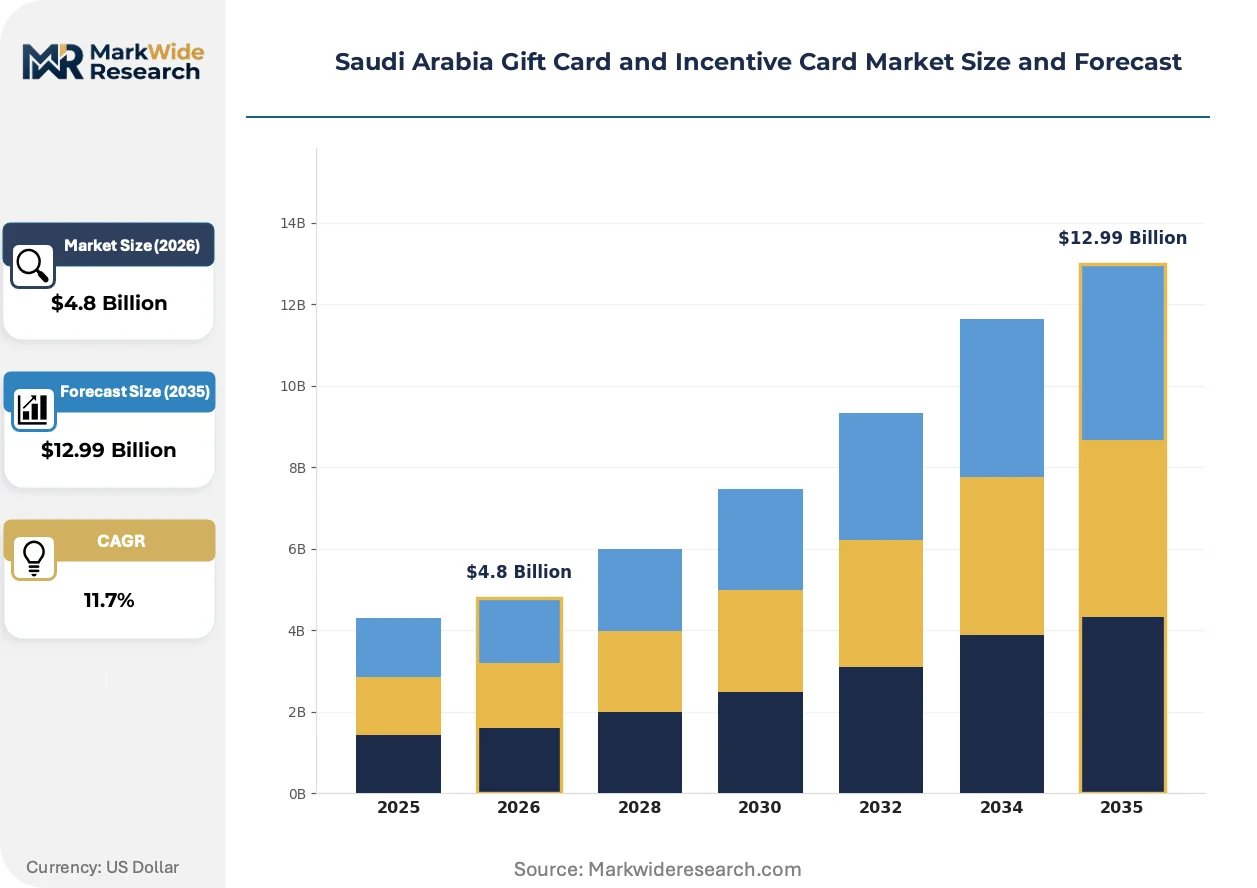
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Card Type: Closed Loop, Open Loop, Reloadable, Non-reloadable Industry Vertical: Retail, Travel, Entertainment, E-commerce Customer Segment: Corporate Clients, Individual Consumers, Non-profit Organizations, Government Agencies Distribution Channel: Online, Retail Stores, Mobile Apps, Direct Sales |
| Companies Covered | Virgin Megastore, Tango Card, Amazon.sa, Alyce, Swile, STC Pay, Carrefour Saudi, Qwikcilver, Jarir Bookstore, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Gift Card and Incentive Card Market Evolving Landscape
Prepaid instrument architecture is pivoting from magnetic-stripe and chip-embedded physical cards toward tokenized digital credentials, with implications for issuance economics and customer lifecycle management.
Tokenization infrastructure is electrifying credential provisioning by replacing static card numbers with dynamically generated payment tokens. SAMA-licensed fintechs are adopting this technology to enable instant digital issuance through mobile applications. The shift is compressing time-to-revenue for new programs while reducing physical manufacturing and distribution costs across the Kingdom.
SAMA's anti-money-laundering directives are tightening verification thresholds for reloadable instruments, mandating stepped-up authentication before balance thresholds trigger. Issuers must reconfigure customer onboarding workflows to accommodate document upload and biometric validation. Corporate bulk procurement programs face particular adjustment costs as they balance administrative efficiency against compliance rigor.
Enterprise buyers are consolidating vendor relationships for prepaid incentive programs, shifting from fragmented merchant-specific closed-loop arrangements toward single-platform open-loop solutions. HR departments in Riyadh's enterprise corridor are driving this consolidation to simplify reconciliation and expand recipient choice. The pattern is most pronounced in technology and professional services verticals with dispersed workforce populations.
Saudi Arabia Gift Card and Incentive Card Market Segmentation
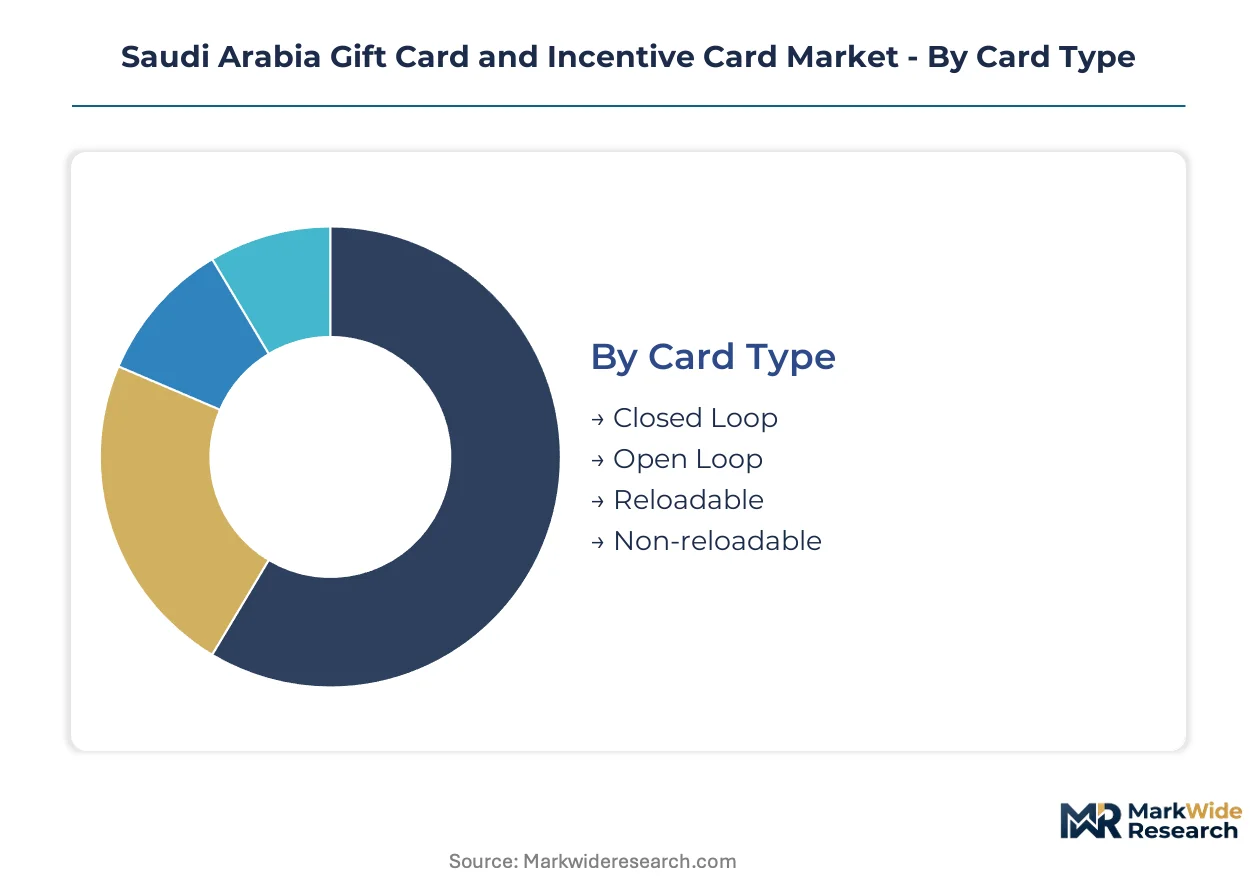
Saudi Arabia's gift card market fragments across four structural dimensions that determine issuance economics, compliance burden, and customer acquisition strategy. Each category reflects distinct procurement patterns shaped by SAMA's regulatory framework and Vision 2030 workforce mandates.
Card Type:
Issuers differentiate products by redemption scope and balance management capabilities, with margin structure and regulatory treatment varying sharply across configurations.
- Closed Loop:Single-merchant instruments with proprietary redemption ecosystems. Retail and entertainment merchants in Riyadh and Jeddah favor these configurations to capture breakage revenue and lock in future spending. SAMA's lighter KYC requirements for non-reloadable variants reduce customer acquisition friction.
- Open Loop:Network-branded credentials accepted across multiple merchants. SAMA-licensed fintechs are embedding these into mobile wallets, accelerating issuance through digital onboarding rather than physical distribution.
- Reloadable:Instruments permitting multiple balance top-ups. Corporate HR departments across the Kingdom favor these for sustained incentive programs, though stepped-up KYC verification adds compliance overhead.
- Non-reloadable:Single-load products with fixed denominations. These dominate consumer gifting occasions and anonymous transaction segments where identity verification thresholds remain minimal.
Closed Loop leads volumes today; Open Loop is gaining share fastest.
Industry Vertical:
Merchant category determines breakage rates, redemption velocity, and the viability of experiential versus transactional value propositions.
- Retail:Department stores and hypermarkets anchor physical gift card distribution, with bulk procurement from corporate clients driving volume concentration in Riyadh's enterprise corridor.
- Travel:Airlines and hospitality providers issue closed-loop instruments for loyalty program integration. Jeddah's proximity to religious tourism routes creates specialized demand for pilgrimage-related gifting.
- Entertainment:Cinemas, gaming venues, and experiential merchants deploy closed-loop products to control redemption ecosystems and capture margin from unredeemed balances.
- E-commerce:Digital-native merchants leverage tokenized credentials for instant issuance through mobile applications, compressing time-to-revenue versus physical card programs.
Retail dominates transaction volumes; E-commerce shows the steepest expansion trajectory.
Customer Segment:
Buyer organizational structure dictates procurement scale, reconciliation complexity, and compliance requirements for KYC and anti-money-laundering protocols.
- Corporate Clients:HR departments and procurement functions purchasing bulk incentive instruments. These buyers are consolidating vendor relationships toward single-platform open-loop solutions to simplify administration.
- Individual Consumers:Occasional purchasers for personal gifting. Mobile wallet integration is shifting this segment from physical retail purchase toward digital issuance channels.
- Non-profit Organizations:Charitable entities distributing prepaid assistance. SAMA's verification mandates create particular friction for programs targeting beneficiaries without formal identification.
- Government Agencies:Public sector workforce retention programs. This segment remains underpenetrated relative to private corporate deployment, offering volume expansion potential for compliant issuers.
Corporate Clients anchor revenue concentration; Government Agencies present the largest untapped procurement pool.
Distribution Channel:
Channel selection determines customer acquisition cost, issuance speed, and the technical infrastructure required for credential provisioning.
- Online:Web-based purchase with email or SMS delivery. Tokenization infrastructure enables instant digital issuance, eliminating physical manufacturing and logistics costs.
- Retail Stores:Physical point-of-sale display and activation. Merchants in Jeddah's retail-tech ecosystem maintain this channel for experiential gifting occasions requiring tangible presentation.
- Mobile Apps:In-application purchase with wallet integration. STC Pay and competing digital wallets are consolidating this channel through NFC-enabled credential provisioning.
- Direct Sales:Relationship-based bulk procurement for corporate and government accounts. Issuers compete on digital onboarding speed and API integration with client HR systems.
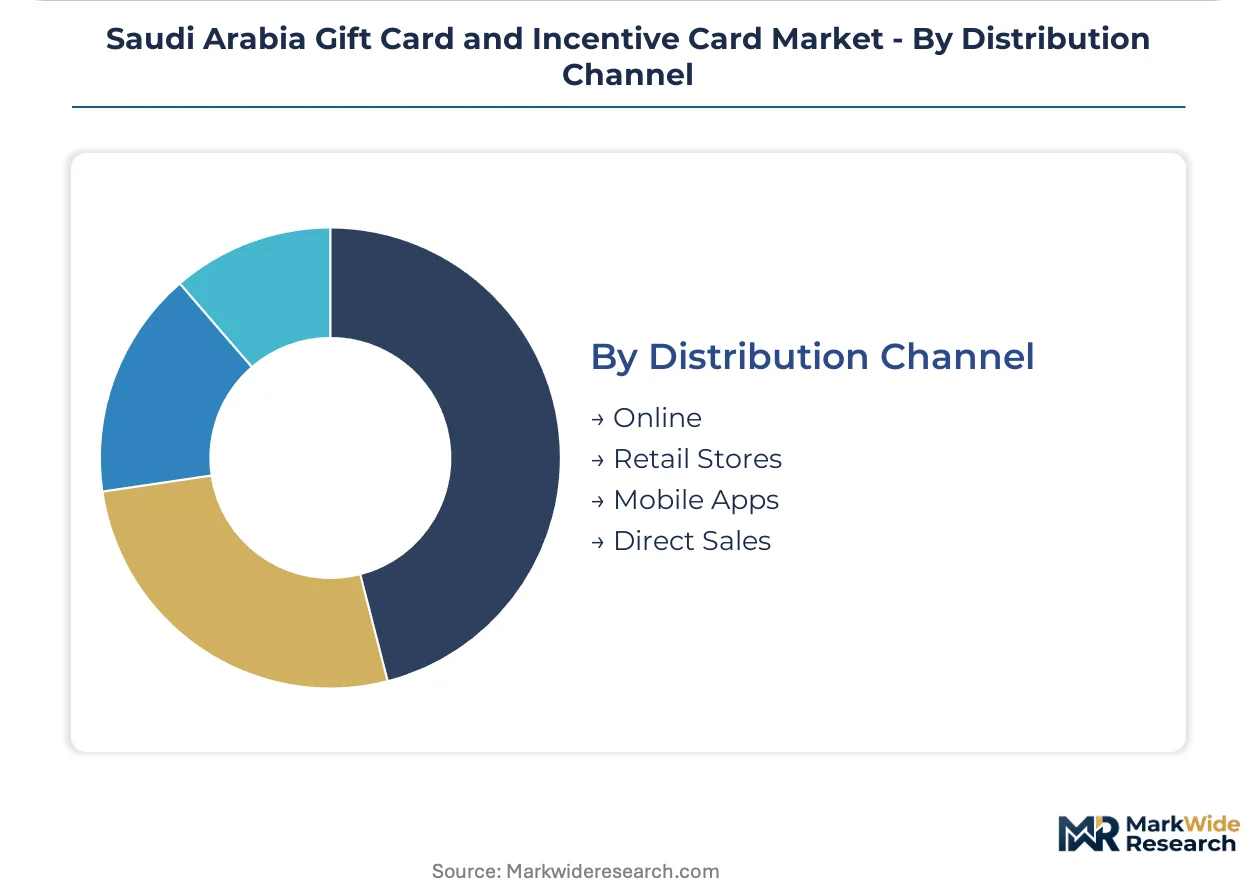
Retail Stores maintain the widest reach; Mobile Apps are climbing the fastest as wallet penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping prepaid instrument issuance across the Kingdom as fintech licensing costs vary between SAMA's sandbox framework and conventional banking charters. Production gravity shifts toward jurisdictions with streamlined digital onboarding protocols.
Riyadh
Corporate HR departments in Riyadh's enterprise corridor drive bulk procurement of reloadable incentive instruments for workforce localization mandates. SAMA's electronic payments framework accelerates open-loop card issuance through licensed fintechs. The King Abdullah Financial District anchors digital wallet integration with NFC-enabled credential provisioning.
Jeddah
Jeddah's retail-tech ecosystem concentrates closed-loop gift card distribution for experiential gifting occasions. The Ministry of Commerce enforces dormancy fee disclosure rules that compress margin recognition flexibility. Red Sea coastal logistics clusters support physical card manufacturing and fulfillment for pilgrimage-related gifting verticals.
Eastern Province
Energy sector employers in the Eastern Province deploy prepaid incentive programs for expatriate workforce retention amid Saudization targets. SAMA's anti-money-laundering directives mandate stepped-up KYC verification for reloadable instruments. Dhahran's corporate headquarters cluster drives direct sales procurement of corporate gift instruments.
NEOM Northwest
NEOM's experimental regulatory zone attracts fintech sandbox participants testing tokenized prepaid credentials. SAMA's stablecoin experiments threaten traditional float mechanics for stored-value instruments. The linear city's digital infrastructure project anchors mobile-wallet convergence trials for government disbursement programs.
Saudi Arabia Gift Card and Incentive Card Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue mobile-wallet integration and tokenized credential architectures. The vendor base stratifies across three maturity tiers: legacy retailers with physical distribution dominance, SAMA-licensed fintechs with digital onboarding velocity, and multinational platform operators with logistics density. Strategic archetypes include closed-loop specialists capturing breakage revenue, open-loop enablers embedding instruments into wallet ecosystems, and corporate program administrators consolidating vendor relationships. Competitive moves concentrate on API integration with client HR systems and regulatory sandbox participation for expedited product approval.
Among platform-based operators, Amazon.sa exemplifies logistics-anchored redemption infrastructure, while STC Pay occupies a position within the mobile-wallet convergence tier. Virgin Megastore represents the closed-loop specialist archetype with experiential gifting control over physical retail channels.
| Leading Market Players |
|---|
| Virgin Megastore |
| Tango Card |
| Amazon.sa |
| Alyce |
| Swile |
| STC Pay |
| Carrefour Saudi |
| Qwikcilver |
| Jarir Bookstore |
| Others |
Value Network & Pricing Analysis
Tokenized credential provisioning bifurcates issuance economics between instant digital delivery and legacy physical card manufacturing, compressing margins in the latter while enabling premium pricing for API-integrated corporate programs. SAMA-licensed fintechs exploit this divergence through mobile-wallet convergence, whereas traditional banks absorb stranded costs from decades-old core banking infrastructure.
Pricing Analysis
Distributor margins in physical retail channels absorb breakage revenue sharing between merchants and program administrators, while direct-to-corporate API integrations command premium pricing for bulk reloadable instruments. Price differentiation hinges on KYC compliance tier—stepped-up verification for reloadable products adds per-account overhead—and redemption ecosystem control, with closed-loop specialists capturing unredeemed balance pools. Pricing pressure intensifies in the non-reloadable consumer segment as digital issuance eliminates manufacturing and logistics costs. Government agencies exhibit lowest price sensitivity due to procurement rigidity, while individual consumers in Jeddah's retail-tech ecosystem demonstrate highest elasticity to dormancy fee disclosure.
Supply Chain Analysis
Single-source vulnerability sits with EMV chip and magnetic-stripe card manufacturing concentrated in China, South Korea, and Taiwan, where specialized secure-element foundries dominate credential production. Raw material dependencies include PVC substrate, embedded antenna substrates for contactless credentials, and holographic security overlays. Supply chain risk centers on logistics chokepoints through Red Sea coastal clusters serving pilgrimage-related gifting verticals. Distribution runs through three parallel channels: direct sales for corporate bulk procurement, retail point-of-sale display networks, and instant digital provisioning via STC Pay and competing mobile wallets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SAMA's regulatory sandbox compresses issuance timelines, creating margin expansion through faster program deployment and reduced compliance overhead for approved fintech architectures.
For Market Incumbents: Hedge against float model displacement by accelerating tokenized credential pilots before SAMA's central bank digital currency experiments mature. Defensive consolidation should prioritize API integration capabilities with Riyadh enterprise corridor HR systems, while vertical integration into mobile-wallet infrastructure reduces dependence on third-party distribution.
For New Entrants and Emerging Players: NFC-enabled credential provisioning offers the clearest technology-first wedge into underpenetrated government agency procurement, where bulk incentive programs for public sector workforce retention remain fragmented across legacy vendors. White-space targets include NEOM's experimental regulatory zone for sandbox participation and Eastern Province energy sector employers seeking expatriate retention solutions.
For Investors and Strategic Acquirers: Consolidation pressure builds where AML compliance talent scarcity constrains issuance scale for mid-tier fintechs lacking dedicated compliance infrastructure. Long-term viability favors acquirers of SAMA-licensed entities with demonstrated sandbox approval velocity and established corporate API relationships. The signal to watch is SAMA's stablecoin implementation timeline, which would disintermediate traditional prepaid float mechanics.
| Strategic Initiative | Industry Significance |
|---|---|
| API Integration with HR Systems | STC Pay and Amazon.sa compete on digital onboarding speed for Riyadh corporate procurement consolidation. |
| SAMA Sandbox Participation | Expedited regulatory approval enables experimental tokenized product structures before CBDC displacement. |
| Mobile-Wallet Convergence | NFC credential provisioning through STC Pay compresses time-to-revenue versus physical distribution. |
| Closed-Loop Experiential Gifting | Virgin Megastore captures breakage revenue through entertainment vertical redemption ecosystem control. |
| Corporate Vendor Consolidation | Single-platform open-loop solutions simplify reconciliation for HR departments across dispersed workforces. |
Research Methodology
Bottom-up corporate procurement modeling reconciled against top-down fintech issuance tracking forms the analytical core of this study. Primary interviews with SAMA licensing officers, prepaid program administrators at major banks, HR procurement leads in Riyadh's enterprise corridor, and mobile-wallet product managers at STC Pay were combined with secondary validation from SAMA electronic payments framework directives, Ministry of Commerce consumer protection regulations, and fintech licensing disclosure databases. Trade data on secure-element imports and corporate incentive program expenditure patterns provided supply-side cross-checks against demand-side survey inputs.
Historical trendline analysis of prepaid instrument issuance velocity informed projection modeling across card type, industry vertical, customer segment, and distribution channel dimensions. Segmentation modeling incorporated reloadable versus non-reloadable configurations, closed-loop merchant categories versus open-loop network acceptance, and digital versus physical credential provisioning. CAGRs were derived from elasticity-adjusted penetration curves for corporate HR incentive programs and mobile-wallet adoption rates, with sensitivity testing against SAMA regulatory timeline scenarios.
The model holds under continued fintech licensing expansion and stable AML directive interpretation; deviation in CBDC implementation pace or KYC verification threshold tightening would shift issuance economics. Forecasts reflect assumptions about workforce localization mandate intensity and digital wallet penetration trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
India Payments Market
Payments
Indonesia Mobile Payments Market
Payments
Asia-Pacific Payment Gateway Market
Payments
Europe Digital Transaction Management (DTM) Market
Payments
United Arab Emirates Real Time Payments Market
Payments
Mobile Point of Sale (POS) Market
Payments
Canada Mobile Payments Market
Payments
Global Point of Sale Terminals Market
Payments
Germany Payments Market
Payments
Digital Transaction Management Market
Payments
Buy Now Pay Later Market
Payments
Digital Remittance Service Market
Payments
Asia Pacific Mobile Wallet Market
Payments
Brazil Real Time Payments Market
Payments
APAC Mobile Payments Market
Payments
Global Bitcoin Payments Ecosystem Market