
 United States Electronic Toll Collection Market | 2026-2036
United States Electronic Toll Collection Market Size, Share, and Industry Trends Forecast 2026-2036
United States Electronic Toll Collection Market Intelligence
Subscription-based transponder replenishment and account management is hardening into the core revenue layer for toll technology vendors. Kapsch TrafficCom leverages its end-to-end platform deployments across multiple state turnpike authorities. TransCore sustains dominance in RFID tag manufacturing and roadside reader infrastructure. Cubic Corporation anchors its position through integrated back-office systems that handle transaction clearing for regional tolling consortiums.
Electronic toll collection comprises automated systems that identify vehicles and process payments without requiring drivers to stop, typically employing microwave radio frequency identification at 5.8 GHz or dedicated short-range communication protocols with read ranges up to 30 feet. The primary purpose is to reduce traffic congestion, eliminate manual toll booth labor, and enable dynamic congestion pricing on managed lanes. RFID technology leads transaction volumes across existing installations but mobile app-based tolling represents the fastest expansion vector as smartphone penetration enables account provisioning without physical transponder distribution. Cloud-based deployment models are displacing on-premise data centers among mid-sized toll operators seeking to offload infrastructure maintenance. Government agencies constitute the most price-sensitive buyer segment while private concessions capture superior margins through integrated payment method ecosystems spanning transponder, credit card, and mobile wallet options.
The Federal Highway Administration oversees tolling interoperability mandates under MAP-21 and subsequent reauthorization acts, compelling state agencies to adopt compatible systems. State regulators including the Texas Department of Transportation and Florida Turnpike Enterprise enforce local technical standards that influence procurement specifications. The National Highway Traffic Safety Administration's vehicle-to-infrastructure communication guidelines shape DSRC implementation roadmaps. Stakeholders must weigh the transition timeline from proprietary transponder networks toward open-payment architectures that accept third-party mobile wallets without dedicated accounts.
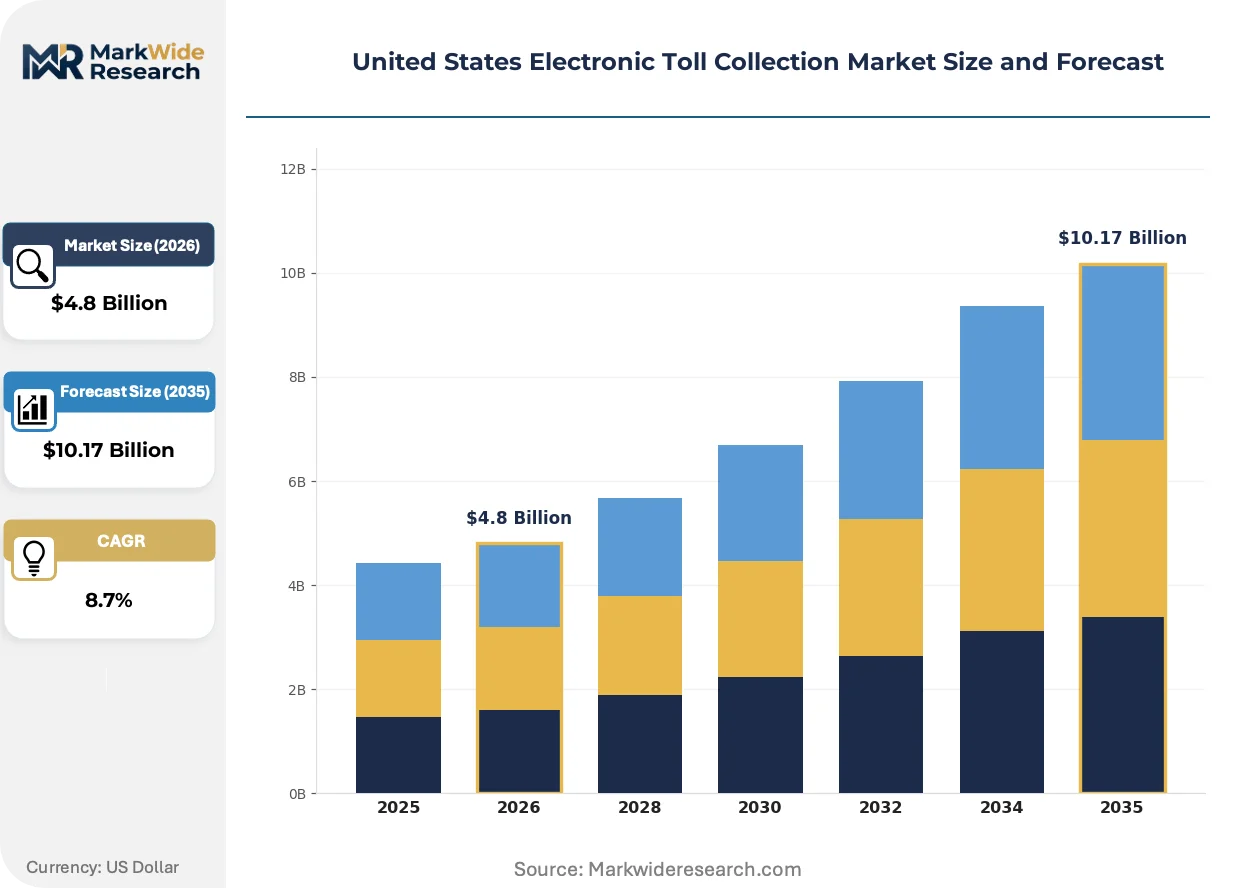
Market Dynamics
The Infrastructure Investment and Jobs Act's dedicated funding streams for intelligent transportation systems are accelerating state-level procurement cycles for multi-lane free-flow tolling infrastructure, compressing vendor qualification timelines and favoring integrated platform providers over component specialists.
Growth Catalysts
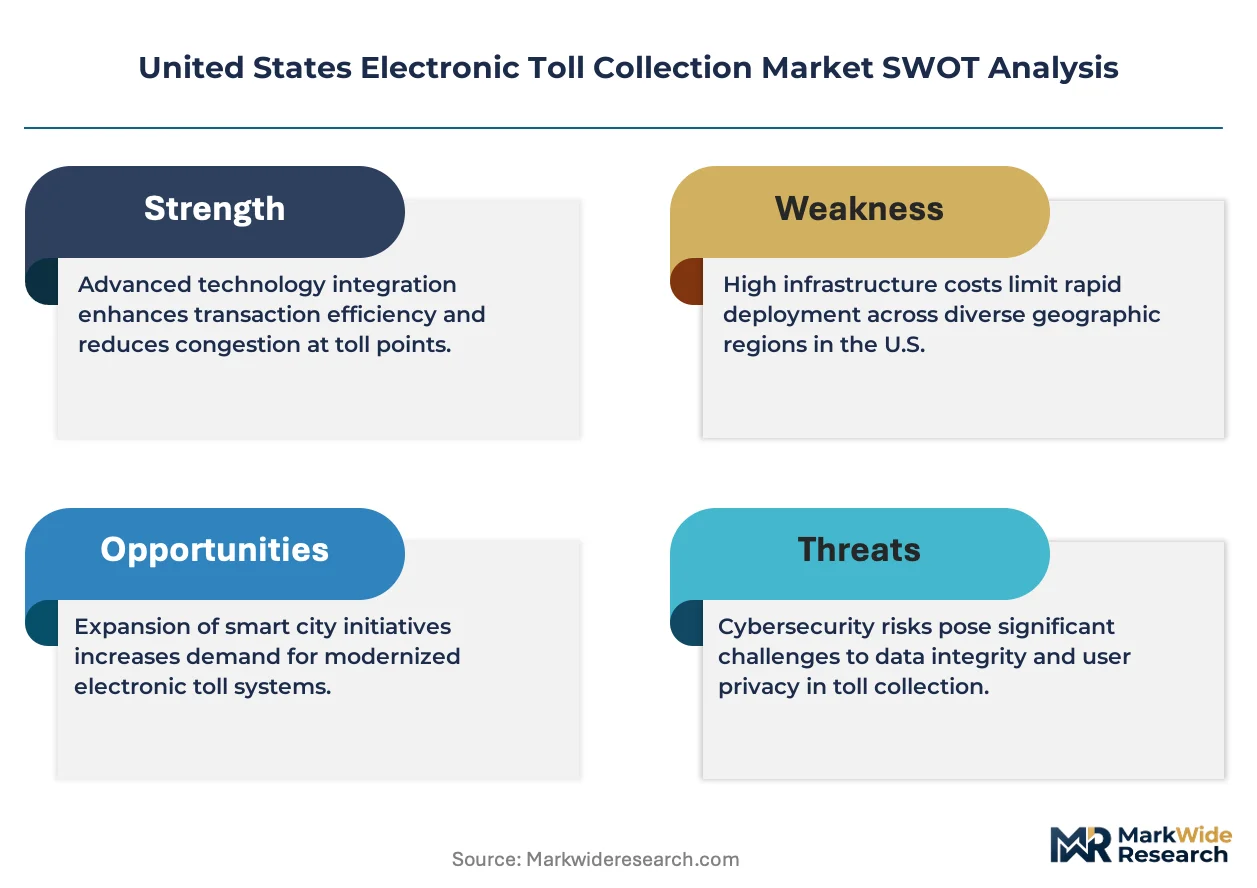
- Interoperability Mandates:The Federal Highway Administration's enforcement of MAP-21 compatibility requirements compels state turnpike authorities to upgrade proprietary systems, generating replacement demand for unified transponder networks.
- Managed Lane Expansion:California, Florida, and Texas transportation departments are converting existing HOV corridors to dynamic congestion-priced lanes, requiring variable tolling infrastructure with real-time rate adjustment capabilities.
- Cloud Migration:Mid-sized toll operators are abandoning on-premise data centers for hosted transaction processing platforms, reducing capital barriers to system modernization and accelerating deployment velocity.
Market Restraints
- Semiconductor Supply Concentration:RFID reader modules and vehicle transponder chipsets depend on concentrated Asian foundry capacity, exposing procurement timelines to geopolitical supply disruptions.
- Legacy System Interdependence:State agencies operate decades-old toll accounting platforms with embedded technical debt, creating integration friction that extends deployment schedules and inflates customization costs.
- Mobile Wallet Substitution:Smartphone-based toll payment applications bypass physical transponder requirements entirely, threatening recurring hardware revenue streams for established equipment vendors.
Strategic Opportunities
- Rural Interstate Corridors:Secondary highway segments in Montana, Wyoming, and the Dakotas remain predominantly cash-tolled, presenting greenfield deployment opportunities for all-electronic systems.
- Vehicle-to-Infrastructure Convergence:DSRC and C-V2X protocol integration enables direct vehicle-toll-gantry communication without windshield-mounted hardware, collapsing account provisioning friction.
- Integrated Mobility Platforms:Parking, transit fare, and toll payment consolidation into single-account ecosystems creates recurring revenue expansion beyond core highway transactions.
Industry Challenges
- Cybersecurity Talent Scarcity:Transportation agencies face acute shortages of specialists capable of securing real-time financial transaction networks against ransomware and payment fraud vectors.
- Legacy Migration Complexity:Back-office system replacements require parallel operation periods that strain operational budgets and demand simultaneous staff retraining across multiple technical domains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Electronic Toll Collection Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: RFID, ANPR, DSRC, Mobile App Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing End User: Government Agencies, Toll Operators, Private Concessions, Municipalities Payment Method: Transponder, Credit Card, Mobile Wallet, Prepaid Account |
| Companies Covered | Conduent, Cubic Corporation, TransCore, EFKON, Neology, Kapsch TrafficCom, Thales Group, Raytheon Technologies, Siemens, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Electronic Toll Collection Market Strategic Shifts & Innovations
Cloud-native transaction processing architectures are displacing mainframe-dependent legacy platforms, enabling toll operators to provision capacity dynamically during peak travel periods without permanent infrastructure investment.
Multi-protocol roadside readers capable of simultaneous RFID, DSRC, and license plate optical capture are consolidating transaction hardware footprints at tolling points. State transportation departments in Texas and Florida are deploying these unified detection systems to reduce gantry complexity and maintenance scheduling overhead. The technology is consolidating vendor relationships around full-stack platform providers rather than specialized component suppliers.
The National Highway Traffic Safety Administration's vehicle-to-infrastructure communication guidelines are mandating DSRC capability as standard equipment in new vehicle classes. Automakers must now pre-install compatible hardware, eliminating consumer-facing transponder distribution costs for toll authorities. Heavy-duty trucking fleets operating across interstate corridors are the first segment compelled to activate these embedded payment credentials.
Transportation agencies are unbundling transaction processing from equipment procurement, awarding separate contracts for roadside infrastructure and back-office clearing services. This procurement model change fragments incumbent vendor relationships and opens entry points for specialized software providers. The shift is most visible in regional tolling consortiums across the Northeast and Midwest seeking to aggregate volume across multiple state boundaries.
United States Electronic Toll Collection Market Segmentation
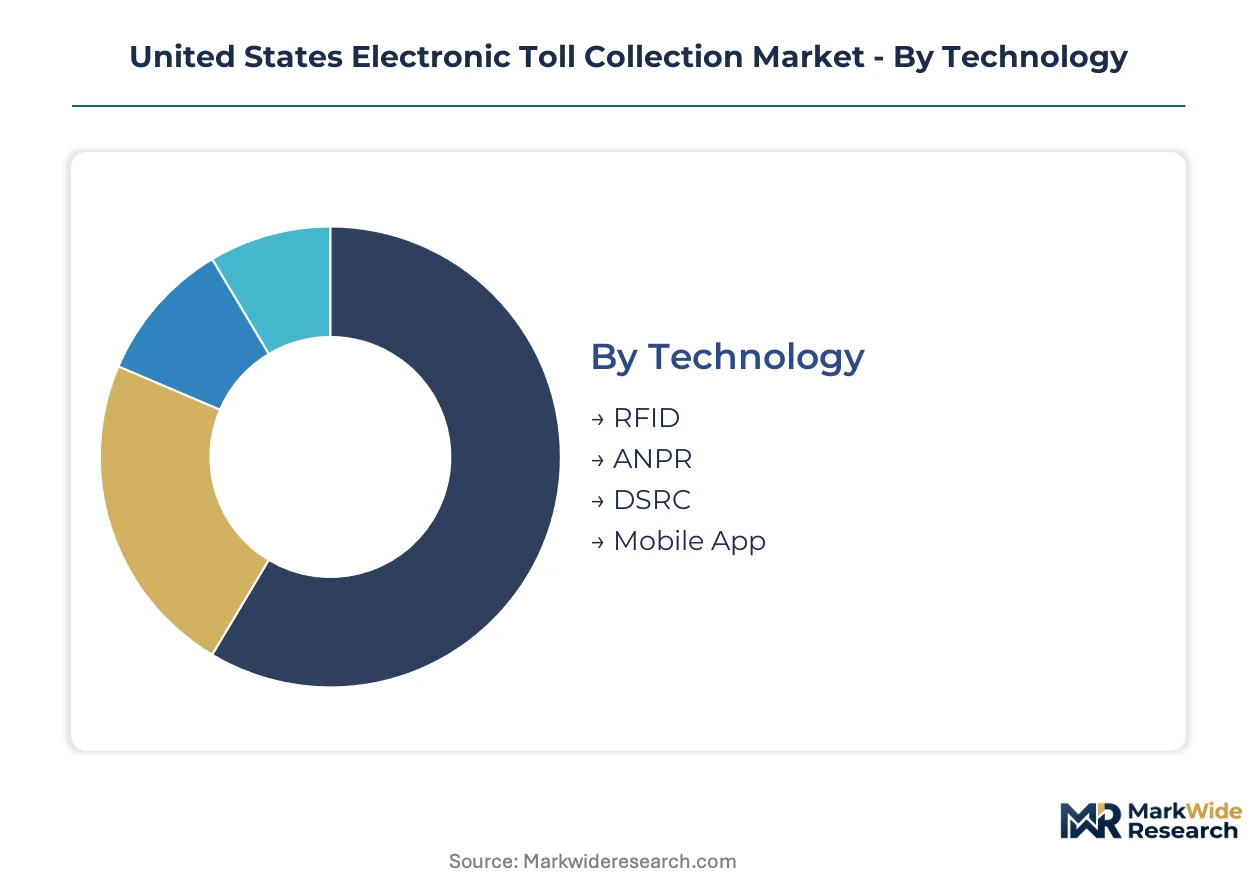
Technology deployment choices in electronic toll collection determine capital intensity, operational flexibility, and interoperability reach across state transportation networks. Procurement specifications vary sharply between legacy system upgrades and greenfield installations, creating distinct vendor qualification pathways.
Technology:
Standardization pressure from federal interoperability mandates compresses proprietary differentiation, yet performance specifications diverge across corridor traffic densities and weather exposure zones.
- RFID:Microwave radio frequency identification at 5.8 GHz dominates existing gantry infrastructure across California, Florida, and Texas turnpike systems. State transportation departments specify read ranges up to 30 feet for multi-lane free-flow configurations. Equipment refresh cycles concentrate in Sun Belt corridors where transponder penetration exceeds national averages.
- ANPR:Automatic number plate recognition employs optical character capture for license plate matching against account databases, serving as backup authentication where windshield transponders fail. Demand clusters in managed lane enforcement and violation processing workflows where secondary verification reduces revenue leakage.
- DSRC:Dedicated short-range communication enables direct vehicle-to-infrastructure payment credentialing without physical transponder distribution. NHTSA guidelines are mandating factory-installed capability in new vehicle classes.
- Mobile App:Smartphone-based toll payment bypasses hardware provisioning entirely through GPS corridor detection and automated account charging.
Most installed capacity flows through RFID. Expansion is steepest in Mobile App deployment.
Deployment:
Capital constraints and cybersecurity risk tolerance divide procurement patterns between asset-heavy state agencies and concession-operated corridors seeking operational agility.
- On-Premise:Legacy mainframe-dependent platforms persist among large turnpike authorities with sunk infrastructure investments and specialized operational staff. Texas Department of Transportation maintains captive data centers for transaction clearing across regional consortiums.
- Cloud-Based:Hosted transaction processing eliminates permanent infrastructure investment for mid-sized operators, enabling dynamic capacity provisioning during peak travel periods. Florida Turnpike Enterprise pilots elastic compute for seasonal volume spikes.
- Hybrid:Split architectures retain sensitive financial data on-premise while offloading analytics and reporting to hosted environments. Municipal toll bridge operators favor this model for compliance segmentation.
- Edge Computing:Distributed processing at roadside gantries reduces latency for real-time congestion pricing adjustments and immediate violation flagging.
Cloud-Based deployment is gaining share fastest among new procurements. On-Premise systems still handle the majority of annual transaction volume.
End User:
Budget cycle timing and revenue model structure create divergent procurement priorities across public and tolling entity categories.
- Government Agencies:State transportation departments operate under federal funding timelines and public procurement statutes, prioritizing interoperability compliance and lifecycle cost minimization. The Infrastructure Investment and Jobs Act accelerates their intelligent transportation system investments.
- Toll Operators:Regional authorities managing specific corridor networks balance transaction volume growth against operational expenditure control, driving demand for integrated platform solutions.
- Private Concessions:Investor-owned toll road operators capture superior margins through integrated payment ecosystems spanning transponder, credit card, and mobile wallet acceptance.
- Municipalities:City and county bridge authorities face acute capital constraints, favoring modular deployments with minimal customization.
Private Concessions deploy the most payment method diversity. Government Agencies represent the largest aggregate procurement volume.
Payment Method:
Account provisioning friction and recurring revenue durability differentiate customer acquisition economics across credential types.
- Transponder:Windshield-mounted RFID tags generate recurring hardware refresh revenue and lock-in through proprietary account relationships. Distribution logistics concentrate costs in rural address fulfillment.
- Credit Card:Open-payment architectures accepting standard card networks eliminate dedicated account requirements, reducing enrollment friction for occasional users. Interchange fees compress margins versus transponder transactions.
- Mobile Wallet:Apple Pay and Google Pay integration enables one-tap enrollment without separate toll authority account creation. Smartphone penetration enables fastest account growth among occasional corridor users.
- Prepaid Account:Stored-value balances minimize per-transaction processing costs and reduce payment failure rates for high-frequency commuters.
Transponder-linked Prepaid Accounts retain the highest transaction share. Mobile Wallet integration is climbing the fastest as smartphone-based enrollment displaces physical distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage in toll technology procurement concentrates vendor activity in states with accelerated federal funding timelines and permissive public-private partnership statutes. The Infrastructure Investment and Jobs Act creates compliance-cost gaps between jurisdictions with mature intelligent transportation system frameworks and those with legacy procurement barriers.
California
Managed lane expansion along Interstate 680 and State Route 91 drives demand for dynamic congestion pricing infrastructure. The California Department of Transportation enforces stringent environmental review timelines under CEQA that compress vendor deployment windows. The San Francisco Bay Area hosts concentrated pilot programs for vehicle-to-infrastructure integration.
Texas
The Texas Department of Transportation operates the nation's largest regional tolling consortium across Central Texas Turnpike System corridors. State legislation permits long-term concession agreements that attract private capital for greenfield beltway construction. Dallas-Fort Worth Metroplex agencies lead procurement of multi-protocol roadside reader systems.
Florida
Florida Turnpike Enterprise manages all-electronic conversion across 500+ miles of existing toll infrastructure. State statutes mandate interoperability with neighboring Georgia and North Carolina systems under Southeastern tolling compacts. The Orlando metropolitan cluster hosts cloud-native transaction processing pilots for seasonal volume elasticity.
New York
The Metropolitan Transportation Authority's bridge and tunnel crossings generate the highest per-lane transaction density in North America. New York State Department of Transportation regulations enforce legacy system compatibility requirements that extend procurement cycles. The Hudson Valley corridor presents replacement demand for obsolete gantry equipment.
Pennsylvania
Pennsylvania Turnpike Commission debt restructuring drives cost-minimization priorities in back-office system procurement. State enabling legislation restricts public-private partnership structures compared to neighboring jurisdictions. The Philadelphia suburban ring maintains elevated transponder penetration rates among commuter corridors.
United States Electronic Toll Collection Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated platform providers capturing premium positioning in state-level procurements while component specialists compete on price in municipal bridge authorities. Market structure tilts toward consolidation around full-stack vendors capable of unified transponder networks, roadside infrastructure, and cloud-based transaction clearing. Three archetypes dominate: end-to-end platform operators, RFID hardware specialists, and back-office software providers. Competitive dynamics center on vertical integration into adjacent mobility services and strategic partnerships with automotive OEMs for embedded payment credentialing.
Within the integrated platform tier, Kapsch TrafficCom and Cubic Corporation exemplify the vendor archetype consolidating state turnpike relationships through multi-year deployment contracts. TransCore occupies a distinct position as an RFID infrastructure anchor with manufacturing concentration in roadside reader hardware. These three entities represent the competitive core around which mid-sized operators and specialized software entrants position for procurement fragmentation.
| Leading Market Players |
|---|
| Conduent |
| Cubic Corporation |
| TransCore |
| EFKON |
| Neology |
| Kapsch TrafficCom |
| Thales Group |
| Raytheon Technologies |
| Siemens |
| Others |
Cost & Logistics Intelligence
Performance-tier bifurcation between integrated platform providers and component specialists shapes both procurement economics and sourcing configurations across state turnpike authorities and municipal operators. Premium positioning attaches to vendors bundling transponder networks, roadside infrastructure, and cloud clearing services, while commodity competition concentrates in standalone RFID hardware and legacy back-office maintenance contracts.
Pricing Analysis
Distributor margins on transponder hardware compress pricing transparency for mid-sized toll operators purchasing through systems integrators. Three-tier pricing structure across premium, standard, and economy levels reflects capability bundling, with premium tiers incorporating real-time congestion pricing modules and predictive maintenance analytics. Pricing pressure stems from mobile wallet substitution eliminating recurring hardware refresh cycles. Government agencies exhibit highest price sensitivity due to federal funding timelines and public procurement statutes, while private concessions absorb premium pricing for integrated payment ecosystem control.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Texas Department of Transportation and Florida Turnpike Enterprise for multi-protocol roadside reader systems. Semiconductor fabrication for RFID chipsets and DSRC modules concentrates in Taiwan, South Korea, and China, with packaging and final assembly distributed across Mexico and domestic US facilities. Raw material dependencies span gallium arsenide substrates, high-frequency ceramic capacitors, and specialized aluminum alloys for gantry structures. Single-source vulnerability in advanced RF component supply exposes deployment schedules to geopolitical disruption. Distribution runs through regional systems integrators serving state transportation consortiums and direct vendor relationships with large turnpike authorities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States Electronic Toll Collection Market compounds steadily as federal interoperability mandates generate replacement demand across state proprietary systems. Infrastructure Investment and Jobs Act funding locks in procurement velocity through the forecast window.
For Market Incumbents: Anticipate mobile wallet substitution eroding transponder hardware revenue by accelerating DSRC and C-V2X embedded payment credential partnerships with automotive OEMs. Defensive consolidation moves center on acquiring specialized cloud-native transaction processing firms to offset back-office unbundling trends, and deepening captive manufacturing of RFID reader modules to reduce Asian foundry exposure. Vertical control over roadside infrastructure deployment capacity anchors state procurement relationships against specialized software entrants. For New Entrants and Emerging Players: Mid-market price-point gaps between Kapsch TrafficCom premium platform contracts and municipal bridge authority commodity hardware purchases create entry space for modular cloud-based clearing services. Rural interstate corridors in Montana, Wyoming, and the Dakotas present the most penetrable geography with predominantly cash-tolled infrastructure requiring greenfield all-electronic deployment. Go-to-market positioning as elastic transaction processing specialists for seasonal volume spikes distinguishes entrants from incumbent capital-intensive platform bundling. For Investors and Strategic Acquirers: Consolidation pressure builds where cloud-native back-office specialists fragment procurement relationships previously captured by integrated platform vendors. Long-term viability favors vendors controlling vehicle-to-infrastructure protocol roadmaps as NHTSA guidelines mandate factory-installed DSRC capability. Acquisition target archetypes include mid-sized toll operators with captive data center assets convertible to hosted service revenue models. Signal to watch: state transportation department unbundling of roadside infrastructure from transaction clearing contracts accelerates beyond Florida and Northeast consortium pilots.| Strategic Initiative | Industry Significance |
|---|---|
| DSRC Protocol Integration | NHTSA mandates embed toll payment capability directly into new vehicle classes, eliminating transponder distribution logistics. |
| Cloud-Native Platform Migration | Florida Turnpike Enterprise pilots elastic compute for seasonal volume spikes, reducing permanent infrastructure investment. |
| Multi-Protocol Reader Deployment | Texas DOT consolidates RFID, DSRC, and ANPR detection at single gantries, compressing vendor relationships around full-stack providers. |
| Embedded Payment Partnership | Automotive OEM pre-installation of compatible hardware collapses account provisioning friction for toll authorities. |
| Rural Corridor Greenfield Buildout | Secondary highway segments in Montana and Wyoming present uncontested all-electronic deployment opportunities. |
Research Approach
Bottom-up toll operator transaction volume modeling reconciled against top-down intelligent transportation system infrastructure deployment tracking forms the analytical core of this study. Primary interviews with state transportation procurement officers, turnpike authority operations directors, toll technology vendor account executives, and systems integration project managers combined with secondary validation against FHWA tolling interoperability filings, state DOT capital improvement plans, and NHTSA vehicle-to-infrastructure guideline documents. Triangulation across stakeholder perspectives and documentary sources ensures segmentation integrity across technology, deployment, and end-user dimensions.
Historical trendline analysis of toll lane mileage expansion and transponder penetration rates established baseline growth parameters across the projection horizon. The analytical framework models segmentation across technology protocol, deployment architecture, end-user entity type, and payment method credential, with CAGRs derived from infrastructure investment cycle timing and federal funding authorization patterns. Industry-specific forecast inputs include Infrastructure Investment and Jobs Act allocation schedules, state-level public-private partnership enabling legislation variation, and NHTSA equipment mandate phase-in timelines.
The model assumes a particular technology adoption path; alternative pathways for C-V2X protocol displacement of DSRC would alter the outlook for embedded payment credentialing economics. Forecasts reflect assumptions regarding federal funding continuity, semiconductor supply chain normalization, and state procurement cycle acceleration. Periodic stress-testing of base assumptions is recommended against Infrastructure Investment and Jobs Act reauthorization risk, mobile wallet penetration velocity, and geopolitical disruption to Asian foundry capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
UK Virtual Cards Market
Payments
Convergent Billing Market
Payments
Romania POS Terminals Market
Payments
Spain Payment Gateway Market
Payments
Cross-Border Payment Platform Market
Payments
Global Gift Card Market
Payments
Mobile Card Reader Market
Payments
Master Recharge API Market
Payments
Brazil Real Time Payments Market
Payments
Global Utility Billing Software Market
Payments
China Prepaid Cards Market
Payments
Vietnam Payments Market
Payments
Payment Security Market
Payments
France Buy Now Pay Later Services Market
Payments
Payment Processing Solutions Market
Payments
Greece POS Terminals Market