
 Banking Smart Cards Market | 2026-2036
Banking Smart Cards Market Size, Share, and Industry Trends Forecast 2026-2036
Banking Smart Cards Market Insights
Subscription-based card personalization and lifecycle management services are shifting how vendors monetize banking relationships beyond hardware shipment. Thales Group leverages its secure element manufacturing to sustain integrated offerings across EMV and biometric portfolios. IDEMIA anchors European banking smart card supply through certified personalization bureau networks. Giesecke+Devrient differentiates via government-grade security credentials that extend into dual-interface commercial banking products.
Banking smart cards are secure payment credentials manufactured with embedded microcontrollers, typically operating on ISO/IEC 7816 contact interfaces or ISO/IEC 14443 contactless radio frequencies, designed to authenticate cardholder identity and encrypt transaction data during retail and ATM interactions. Contactless cards dominate volume shipments in mature European markets while dual-interface products capture expanding margin pools in Asia-Pacific retail banking upgrades. Biometric authentication technology leads R&D allocation among tier-one suppliers, though tokenization infrastructure attracts fintech partnerships seeking software-defined security layers.
EMVCo standards, PCI DSS certification requirements, and country-level central bank mandates collectively shape product roadmaps and market access conditions for banking smart card vendors. EMA guidelines in Europe and RBI directives in India enforce stringent data protection and domestic personalization requirements that filter supplier eligibility. Stakeholders must monitor regulatory divergence between biometric data privacy frameworks and open banking API standards to anticipate compliance-driven procurement cycles.
Market Dynamics
Central bank mandates for fraud reduction across Southeast Asia are forcing retail banks into accelerated EMV migration cycles, compressing supplier lead times and reshaping procurement priorities toward dual-interface biometric portfolios.
Growth Catalysts
- EMV chip mandates:Central banks in Indonesia, Thailand, and Vietnam enforce phased deadlines for contact card replacement. Domestic issuers scramble to secure personalization bureau capacity ahead of penalty clauses.
- Contactless limit expansion:European payment networks raise tap-to-pay thresholds to fifty euros. Dual-interface card shipments accelerate as issuers consolidate contact and contactless credentials on single secure elements.
- Biometric authentication R&D:Fingerprint sensor integration into payment cards reaches production viability. Tier-one suppliers allocate capital toward ISO/IEC 14443-compliant biometric modules.
Market Restraints
- Secure element supply concentration:Wafer fabrication for EMV microcontrollers clusters in Taiwan and South Korea. Geopolitical friction threatens just-in-time delivery schedules for European personalization bureaus.
- Gold and copper price volatility:Laminate substrates and antenna plating rely on precious metal inputs. Input cost spikes compress hardware margins before long-term supply contracts renegotiate.
- Tokenization substitution:Smartphone-based digital wallets bypass physical card issuance entirely. Younger demographics in Nordic markets skip card products for native mobile payment credentials.
Strategic Opportunities
- Rural India unpenetrated issuance:Jan Dhan Yojana financial inclusion targets two hundred million unbanked adults. Regional rural banks seek low-cost EMV cards with domestic RuPay branding.
- Subscription personalization services:Lifecycle management contracts replace one-time hardware sales. Vendors capture recurring revenue through remote applet updates and reissuance logistics.
- Open banking API convergence:PSD2-mandated data sharing in Europe creates demand for cards with dynamic authentication. Secure elements bridge physical credentials and digital account access.
Industry Challenges
- Biometric data privacy compliance:GDPR Article 9 restrictions on special category data complicate fingerprint template storage. Issuers face divergent national interpretations across EU member states.
- Personalization bureau certification backlog:EMVCo security evaluation queues stretch eighteen months. New market entrants cannot access tier-one bank procurement cycles without accredited facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Banking Smart Cards Market |
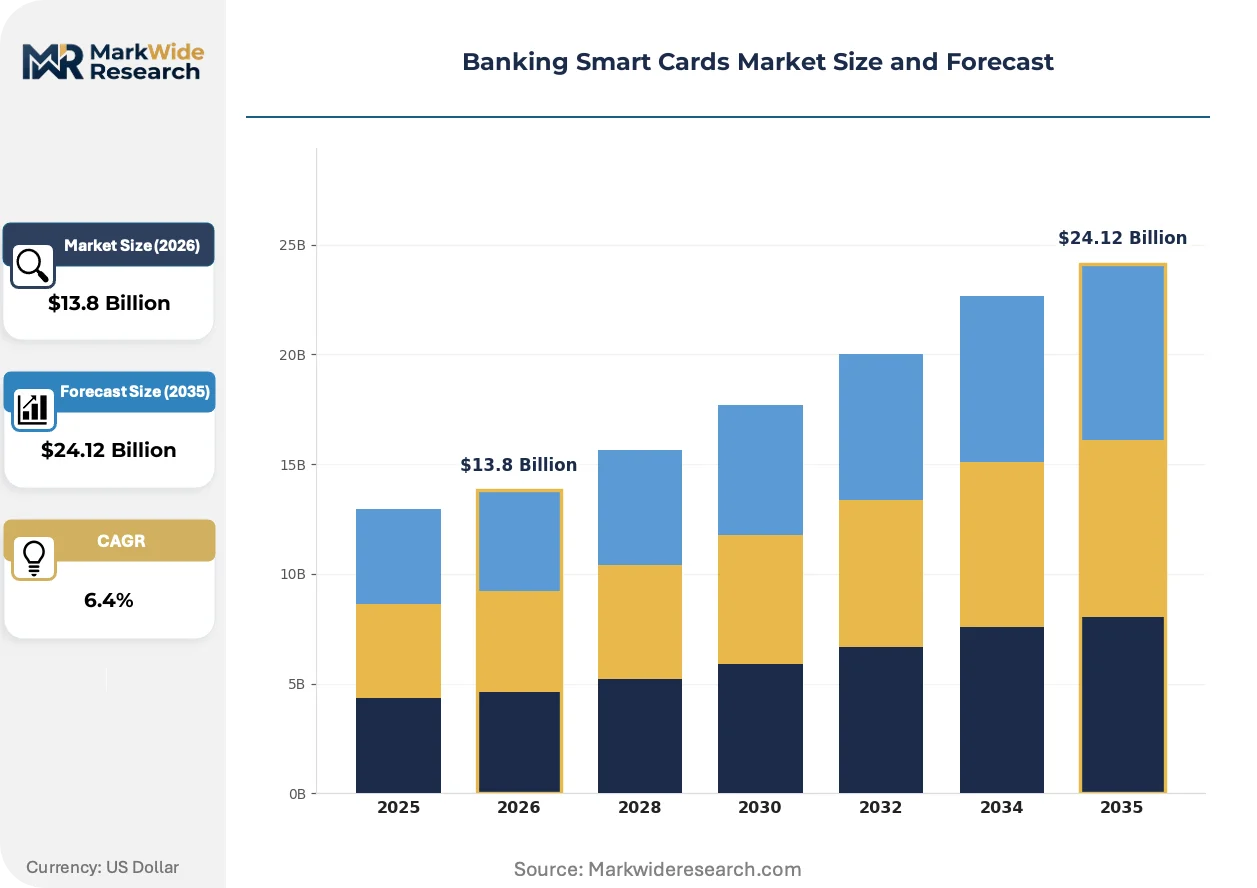
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $24.12 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Card Type: Contact, Contactless, Dual Interface, EMV Chip, Magnetic Stripe Technology: Near Field Communication, Secure Element, Biometric Authentication, Blockchain Integration, Tokenization Application: Retail Payments, ATM Transactions, Access Control, Loyalty Programs, E-Governance End User: Retail Banks, Credit Unions, Payment Processors, Financial Technology Firms, Corporate Treasury |
| Companies Covered | Thales Group, IDEMIA, Giesecke+Devrient, Infineon Technologies AG, NXP Semiconductors, CPI Card Group, HID Global Corporation, Visa Inc., Mastercard Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Banking Smart Cards Market Trends and Innovations
Authentication architecture is bifurcating between hardware-rooted security in physical cards and software-defined trust layers in digital wallets, forcing suppliers to defend credential relevance across both domains.
Biometric payment cards is rewriting competitive positioning in premium banking segments. Fingerprint-on-card modules from Norwegian and French sensor specialists reach price points viable for mass-market platinum products. Swiss and Singaporean private banks pilot vein-pattern recognition for ultra-high-net-worth clients, compressing the authentication step to sub-second verification without PIN entry.
India's RBI directive on domestic data localization for payment systems is forcing infrastructure reconfiguration. International card schemes must route transaction processing through Mumbai-based data centers, raising compliance costs for foreign personalization bureaus. Domestic vendors with captive Indian facilities capture incremental share in public sector bank tenders previously dominated by European suppliers.
Bank procurement patterns are fragmenting across centralized group tenders and subsidiary-level vendor selection. Large European banking groups consolidate smart card purchasing at headquarters level to extract volume discounts, while Asia-Pacific retail banks delegate authority to country operations with distinct local certification requirements. Procurement friction peaks in markets like Indonesia where central bank mandates override group-level standardization efforts.
Banking Smart Cards Market Segmentation
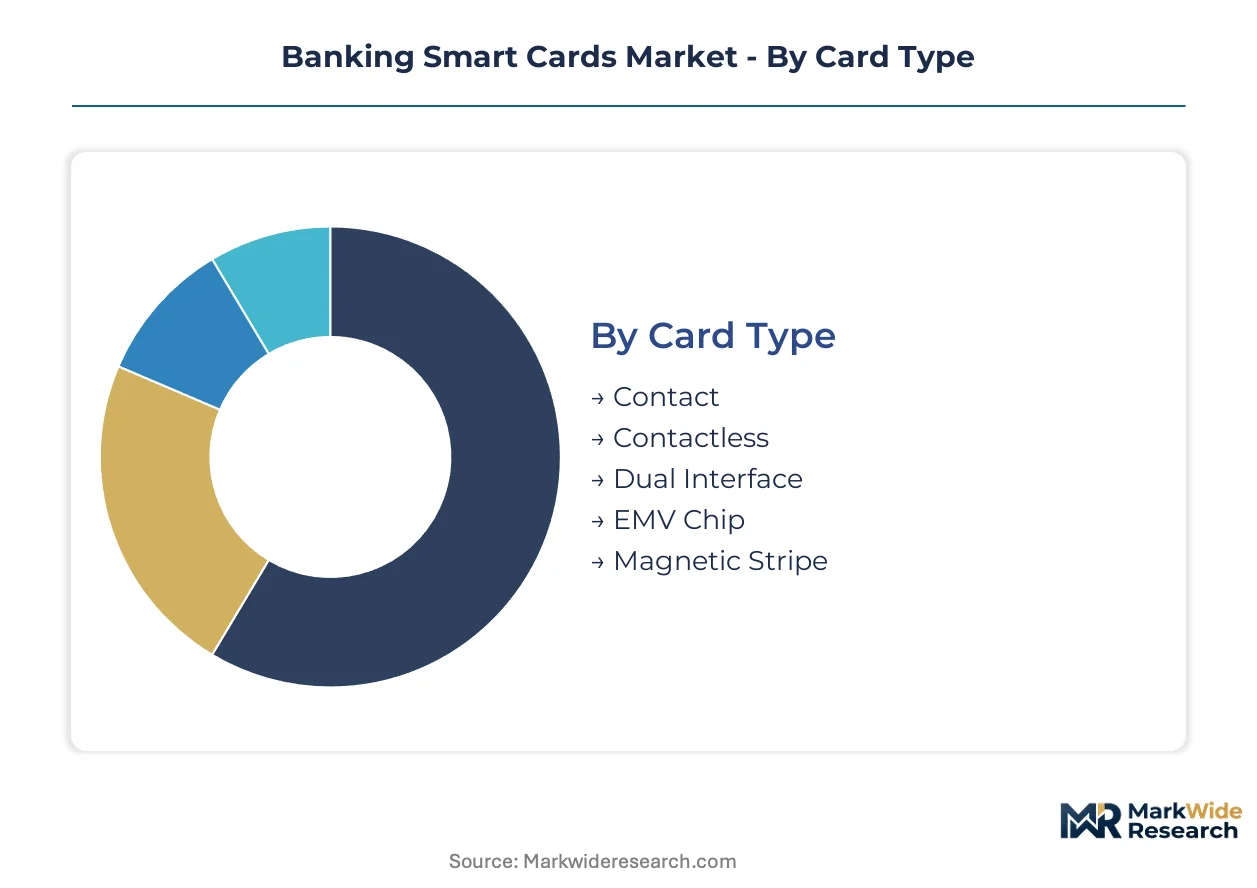
Banking smart card segmentation reveals how procurement priorities diverge across fraud prevention mandates, contactless infrastructure maturity, and biometric authentication readiness. Suppliers must align portfolio investments with these structural demand fractures rather than treating issuance as a homogeneous hardware play.
Card Type:
Issuers differentiate procurement by interface capability required for local payment infrastructure and regulatory compliance timelines.
- Contact:ISO/IEC 7816-compliant cards with physical chip interfaces remain mandatory for ATM-heavy markets and offline authorization environments. Demand concentrates in rural India and Southeast Asia where Indonesia's central bank enforces phased EMV migration deadlines.
- Contactless:Single-interface ISO/IEC 14443 products dominate European volume shipments where tap-to-pay thresholds have expanded. French and German retail banks consolidate procurement around this format for transit-integrated payment ecosystems.
- Dual Interface:Unified secure elements supporting both contact and contactless protocols capture premium positioning in Asia-Pacific retail banking upgrades.
- EMV Chip:Microcontroller-based credentials with Europay-Mastercard-Visa compliance form the baseline security layer across all mandated migration markets.
- Magnetic Stripe:Legacy fallback encoding persists in markets with incomplete terminal infrastructure or transit system backward-compatibility requirements.
Volume sits with Contactless; growth tilts toward Dual Interface.
Technology:
R&D allocation splits between hardware-rooted security modules and software-defined trust architectures that bridge physical and digital credential domains.
- Near Field Communication:Short-range radio protocols enable tap-to-pay functionality at transit gates and retail terminals. Deployment concentrates in Singapore and South Korea where transit-payment integration drives dual-use card issuance.
- Secure Element:Tamper-resistant hardware chips store cryptographic keys and payment credentials. Wafer fabrication concentration in Taiwan and South Korea shapes supply availability for European personalization bureaus.
- Biometric Authentication:Fingerprint-on-card modules reach production viability for premium banking segments. Swiss private banks pilot vein-pattern recognition for ultra-high-net-worth clients.
- Blockchain Integration:Distributed ledger anchoring for credential verification remains experimental in pilot programs.
- Tokenization:Dynamic credential substitution enables smartphone wallet compatibility and reduces fraud exposure in e-commerce channels.
Investment flows heaviest into Secure Element capacity; Biometric Authentication climbs the fastest.
Application:
Use-case segmentation tracks how card credentials extend beyond pure payment into identity verification and service access domains.
- Retail Payments:Point-of-sale transaction authorization remains the core volume driver across all card formats. European networks raising contactless limits accelerate dual-interface deployment for consolidated credential management.
- ATM Transactions:Cash withdrawal and balance inquiry functions require contact interface reliability in low-connectivity environments. Rural Indian banks under Jan Dhan Yojana inclusion targets prioritize EMV chip migration for ATM security.
- Access Control:Physical building entry and secure facility authentication leverage card-based identity verification.
- Loyalty Programs:Multi-application cards integrate payment with points accumulation and merchant rewards.
- E-Governance:National ID and social service access credentials embed banking functionality for financial inclusion.
Retail Payments commands installed base; E-Governance expands most quickly.
End User:
Procurement authority fragments between centralized group purchasing and distributed country-level vendor selection with distinct certification requirements.
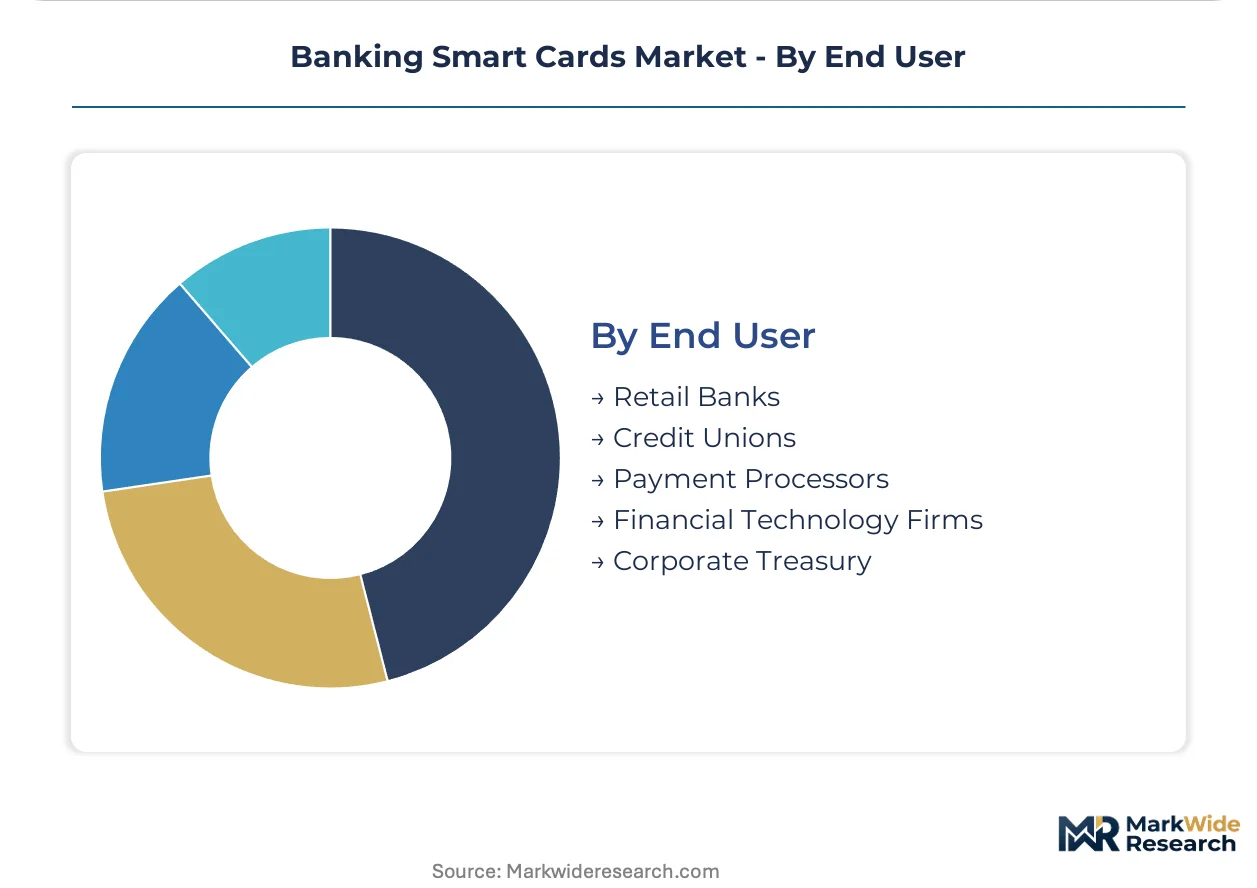
- Retail Banks:Large European banking groups consolidate smart card purchasing at headquarters level to extract volume discounts. Asia-Pacific operations delegate authority to country subsidiaries with local personalization bureau mandates.
- Credit Unions:Member-owned financial cooperatives prioritize cost-efficient EMV migration with domestic branding requirements. Indian regional rural banks seek low-cost RuPay-certified products under RBI localization directives.
- Payment Processors:Network operators and transaction acquirers influence card specification through certification and interoperability standards.
- Financial Technology Firms:Digital-native entrants drive demand for tokenization infrastructure and API-integrated credential management.
- Corporate Treasury:Multinational enterprises procure commercial card programs with integrated expense management and travel booking functionality.
Retail Banks anchor procurement volume; Financial Technology Firms reshape fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's Jurong Innovation District anchors secure element testing and personalization bureau certification for Asia-Pacific banking card deployment. European personalization networks concentrate in Munich and Amsterdam. North American EMV migration concentrates in Chicago and Toronto processing centers.
Indonesia
Bank Indonesia mandates full EMV chip migration by 2026 for all debit and credit products. Domestic personalization bureau capacity constraints force regional rural banks into competitive tendering for certified vendor slots. Jakarta's Cikarang industrial corridor hosts new secure element finishing facilities from European suppliers.
Germany
Contactless payment thresholds at 50 euros accelerate dual-interface card reissuance across Sparkassen and cooperative banking networks. BaFin supervision enforces strict data localization for biometric template storage in premium banking products. Munich hosts Giesecke+Devrient headquarters and EMVCo-certified personalization infrastructure serving Central European issuers.
India
Reserve Bank of India directives mandate domestic data localization for all payment system operators. Jan Dhan Yojana financial inclusion targets drive EMV card issuance toward 200 million unbanked adults. Mumbai's BKC financial district anchors transaction processing infrastructure that foreign schemes must route through.
France
CNIL biometric data guidance complicates fingerprint-on-card deployment for high-net-worth private banking segments. Thales Group leverages domestic secure element manufacturing to sustain integrated EMV and biometric portfolios. Paris-Saclay technology cluster hosts sensor specialists advancing vein-pattern recognition modules.
United States
CPI Card Group anchors North American EMV personalization through Denver and Toronto facilities serving regional bank consolidations. Community bank mergers compress vendor selection timelines toward integrated procurement platforms. Chicago's financial technology corridor attracts tokenization infrastructure partnerships between card manufacturers and digital wallet operators.
Banking Smart Cards Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the banking smart card value chain. Wafer fabrication concentrates in Taiwan and South Korea while European personalization bureaus handle secure element finishing and card body lamination. Three archetypes dominate: integrated secure element-to-card vendors, pure-play personalization specialists, and semiconductor-focused component suppliers. Capacity expansion and biometric module R&D represent the dominant competitive moves as contactless limits rise across European networks.
Within the integrated tier, Thales Group and IDEMIA exemplify end-to-end secure element and personalization capabilities. Giesecke+Devrient occupies a distinct position bridging government credential expertise into commercial banking products. Among semiconductor-focused suppliers, Infineon Technologies AG and NXP Semiconductors anchor the secure element layer that feeds downstream card manufacturing. These five entities collectively represent the concentration points through which EMVCo certification, central bank mandates, and biometric authentication roadmaps flow.
| Leading Market Players |
|---|
| Thales Group |
| IDEMIA |
| Giesecke+Devrient |
| Infineon Technologies AG |
| NXP Semiconductors |
| CPI Card Group |
| HID Global Corporation |
| Visa Inc. |
| Mastercard Incorporated |
| Others |
Pricing and Supply Chain Analysis
Central bank EMV mandates across Indonesia, Thailand, and Vietnam are compressing procurement timelines and forcing personalization bureau capacity commitments that reshape supplier pricing power and contract structures.
Pricing Analysis
Cost-down pressure on dual-interface biometric cards accelerates because tier-one banks consolidate volume tenders and demand lifecycle service bundling. Three-tier pricing structure across premium biometric, standard EMV, and economy contact-only levels stratifies by certification tier and personalization bureau proximity. Price erosion runs through economy contact-card tiers as domestic Indian vendors undercut European suppliers on RuPay-certified volume contracts. Regional rural banks exhibit highest price sensitivity; Swiss private banking segments absorb biometric premiums without volume negotiation.
Supply Chain Analysis
Freight cost spikes on semiconductor wafer shipments from Taiwan and South Korea to European personalization bureaus are compressing just-in-time delivery economics. Secure element fabrication concentrates in Taiwan, South Korea, and Germany; laminate substrates draw from copper and gold suppliers facing commodity volatility. Single-source vulnerability sits with Taiwan-based foundry capacity for EMV microcontroller wafers. Distribution runs through certified personalization bureaus in Munich, Amsterdam, and Singapore before downstream bank issuance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market occupies a hardware-to-service transition where biometric authentication modules displace PIN-entry legacy cards across premium banking segments.
For Market Incumbents: Lock in personalization bureau certification slots ahead of EMVCo evaluation queue bottlenecks. Secure wafer supply agreements with Taiwanese foundries to hedge geopolitical friction. Defend margin pools by integrating lifecycle management subscriptions that reduce hardware-only commoditization risk from tokenization substitutes. For New Entrants and Emerging Players: Capture rural Indian EMV issuance under Jan Dhan Yojana inclusion targets where domestic RuPay certification requirements filter out European incumbents. Pursue regional rural bank procurement delegated outside centralized group tenders. Lead with low-cost contact-card platforms priced below biometric-capable competitor offerings. For Investors and Strategic Acquirers: Re-rating potential sits with biometric module specialists given fingerprint-on-card production viability and ISO/IEC 14443 compliance standardization. Long-term viability hinges on bridging physical credential and digital wallet authentication architectures. Watch EMVCo certification queue lengths as inflection signal for personalization bureau scarcity value.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Module R&D Partnership | Fingerprint-on-card integration with Thales and IDEMIA accelerates premium banking product pipelines. |
| Domestic Personalization Bureau Certification | RBI-mandated data localization in Mumbai filters supplier eligibility for Indian public sector tenders. |
| Subscription Service Platform Launch | Lifecycle management contracts with remote applet updates capture recurring revenue from European issuers. |
| Secure Element Capacity Expansion | Wafer fabrication investment in Taiwan hedges supply concentration risk for EMV microcontroller demand. |
| Tokenization Infrastructure Partnership | API-integrated credential management with fintech wallets bridges physical and digital authentication domains. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with personalization bureau operations directors, EMV certification specialists, central bank payment system officers, and regional rural bank procurement heads validated demand assumptions. EMVCo security evaluation databases, RBI circulars on data localization, and European Banking Authority payment reports supplied secondary triangulation alongside bottom-up card shipment modeling and top-down banking sector spend analysis.
Segmentation-level modeling captured card type, interface technology, application use-case, and end-user procurement authority dimensions across the projection horizon. CAGRs derived from regression analysis against EMV migration mandate timelines and contactless limit expansion schedules. Biometric authentication adoption curves and tokenization substitution rates fed scenario-weighted outputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to central bank mandate delays, biometric data privacy regulatory divergence, and smartphone wallet penetration acceleration. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Credit Intermediation Market
Banking
UK Banking as a Service Market
Banking
North America Challenger Banks Market
Banking
Banking Maintenance Support and Services Market
Banking
France Data Analytics in Banking Market
Banking
Asia-Pacific Challenger Banks Market
Banking
Australia Data Analytics in Banking Market
Banking
Third-Party Banking Software Market
Banking
Saudi Arabia Retail Banking Market
Banking
Smart Banking Solutions Market
Banking
Europe Data Analytics in Banking Market
Banking
Middle East and Africa Neobanking Market
Banking
Bank Guarantee Market
Banking
Australia Neobanking Market
Banking
UK Retail Banking Market
Banking
China Retail Banking System Market