
 Southeast Asia POS Terminal Market | 2026-2036
Southeast Asia POS Terminal Market Size, Share, and Industry Trends Forecast 2026-2036
Southeast Asia POS Terminal Market Analytics
Restaurant chains across Southeast Asia are repositioning payment infrastructure as dine-in and delivery channels merge. NCR Corporation leverages its fixed POS heritage to anchor enterprise hospitality accounts across Bangkok and Singapore. StoreHub Sdn Bhd specializes in cloud-native systems for mid-market F&B operators in Malaysia. PAX Technology Ltd dominates hardware supply for contactless-enabled terminals deployed in Indonesian retail chains.
A POS terminal integrates payment processing hardware with software to authenticate and settle card, mobile wallet, and QR code transactions through EMV chips, NFC antennas, and encrypted communication protocols. The device serves as the terminal node in merchant acquiring networks, capturing transaction data and routing it to payment processors. Mobile POS and cloud-based POS represent the fastest-expanding product categories as micro-merchants and pop-up retailers abandon fixed countertop installations. Contactless payment technology leads transaction volume growth, though chip-and-pin terminals still occupy the largest installed base across legacy supermarket and hospitality deployments.
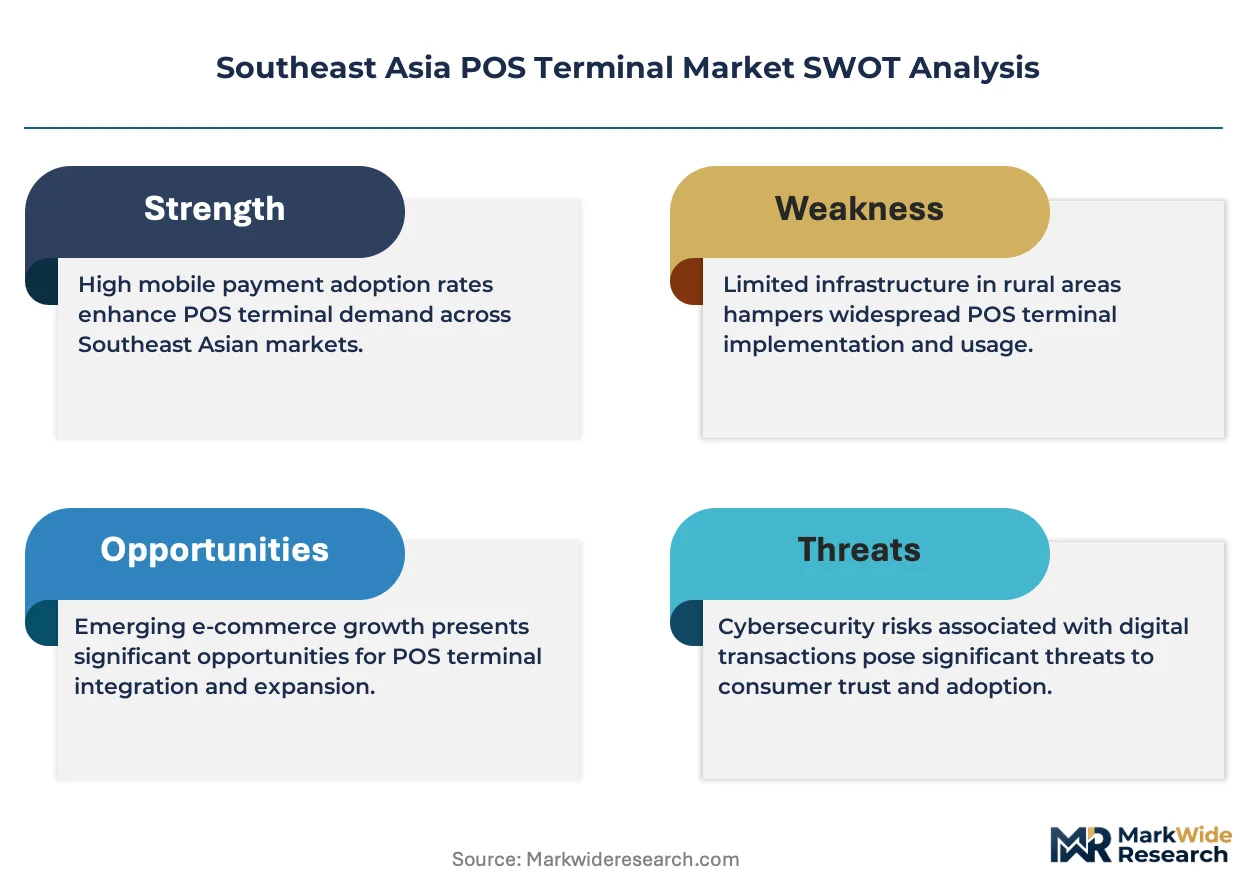
Bank Negara Malaysia enforces QR code interoperability standards that mandate terminal compatibility across domestic payment rails, directly shaping hardware procurement specifications. Thailand's Bank of Thailand and Indonesia's Bank Indonesia both supervise payment system licensing that governs which terminal vendors qualify for national merchant acquiring programs. Singapore's Monetary Authority of Asia maintains cybersecurity certification requirements for POS devices handling cross-border transactions. Stakeholders must monitor how divergent national certification timelines affect multi-country rollout strategies and supplier qualification costs.
Market Dynamics
QR code payment interoperability mandates across Southeast Asian monetary authorities are forcing terminal hardware redesign cycles, compressing vendor certification timelines and reshaping procurement specifications for merchant acquirers.
Growth Catalysts
- Bank Negara Malaysia QR Standards:The central bank's interoperability framework mandates unified terminal compatibility across domestic payment rails, accelerating hardware refresh cycles for Malaysian retailers.
- Cloud-Native POS Migration:Mid-market F&B operators in Thailand and Vietnam are abandoning fixed installations for tablet-based systems, expanding addressable hardware volumes.
- Indonesian Retail Corridor Concentration:Merchant acquiring networks are densifying terminal deployment across Jakarta and Surabaya, creating clustered demand pools for contactless-enabled devices.
Market Restraints
- Semiconductor Component Volatility:NFC controller and secure element chip supply concentrates with Taiwanese and South Korean foundries, exposing terminal manufacturers to input cost swings.
- Divergent National Certification Timelines:Bank Indonesia, Bank of Thailand, and Bank Negara Malaysia operate non-harmonized device approval processes, fragmenting supplier qualification costs across the region.
- Smartphone-Based Payment Substitution:Soft POS applications running on merchant-owned devices threaten dedicated terminal volumes among micro-merchants and pop-up retailers.
Strategic Opportunities
- Philippines Digital Payment Acceleration:The central bank's national QR code standardization program creates terminal replacement demand among unbanked merchant segments.
- Cross-Border Transaction Certification:Singapore's cybersecurity requirements for terminals handling regional payment flows position compliant vendors for premium pricing in financial hub deployments.
- Convergence of POS and Inventory Systems:Restaurant chains are unifying payment terminals with kitchen display systems and stock management platforms, opening integrated solution contracts.
Industry Challenges
- Multi-Jurisdiction Compliance Engineering:Terminal vendors must architect hardware capable of satisfying Bank Indonesia's licensing, Bank Negara Malaysia's interoperability, and Singapore's cybersecurity standards simultaneously.
- Legacy System Integration Friction:Enterprise hospitality operators in Bangkok and Singapore maintain decade-old property management systems that resist API connectivity with modern cloud POS architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southeast Asia POS Terminal Market |
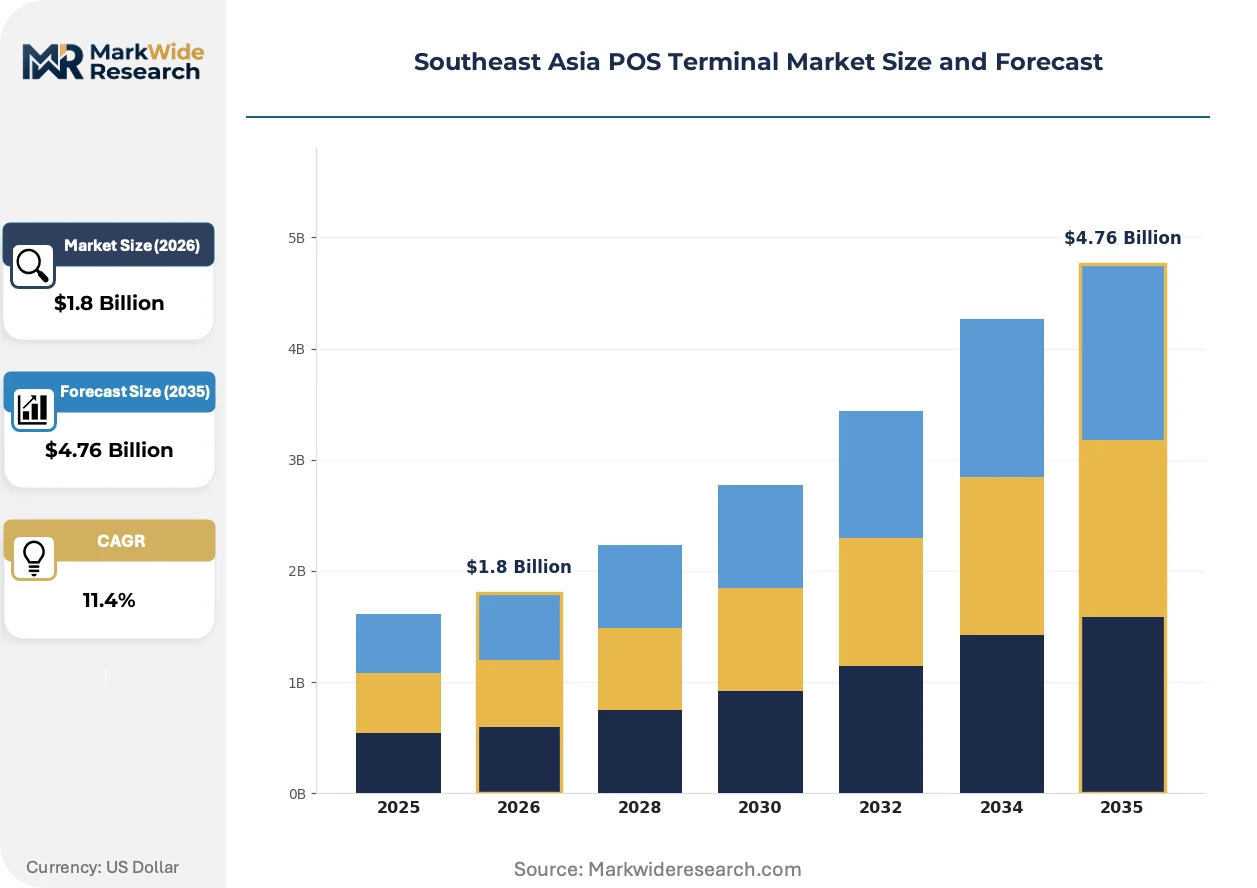
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed POS, Mobile POS, Self-Service Terminals, Cloud-Based POS End User: Retail Chains, Restaurants, Hospitality, Supermarkets Deployment: On-Premise, Cloud, Hybrid, Mobile Payment Technology: Contactless, Chip & Pin, Magnetic Stripe, Mobile Wallets |
| Companies Covered | Shopify Inc, StoreHub Sdn Bhd, NCR Corporation, Verifone Systems LLC, iMetrics Pte Ltd, Toshiba Tec Corporation, Qashier Pte Ltd, PAX Technology Ltd, Samsung Electronics Co Ltd, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southeast Asia POS Terminal Market Evolving Landscape
Payment terminal architecture is converging with merchant software stacks as hardware vendors reposition from device suppliers to platform enablers. Three developments are compressing traditional category boundaries.
Android-based open-platform terminals are unifying payment acceptance with third-party application hosting. Indonesian retail chains and Malaysian F&B operators are adopting these devices to run loyalty programs, inventory modules, and accounting tools on shared hardware. This convergence is collapsing the distinction between dedicated payment terminals and general-purpose merchant tablets.
Bank Negara Malaysia's 2023 QR interoperability enforcement is mandating hardware backward compatibility across DuitNow, GrabPay, and Touch n Go eWallet rails. Terminal manufacturers must embed multiple domestic payment schemas in single devices, increasing firmware complexity. Malaysian merchant acquirers are responding by consolidating vendor relationships around suppliers with proven multi-rail certification.
Subscription-based hardware provisioning is displacing outright terminal purchases among Southeast Asian micro-merchants. Payment service providers in Vietnam and the Philippines are bundling devices with transaction processing fees, eliminating upfront capital barriers. This model is most visible among street vendors and wet market stallholders previously excluded from formal acquiring networks.
Southeast Asia POS Terminal Market Segmentation
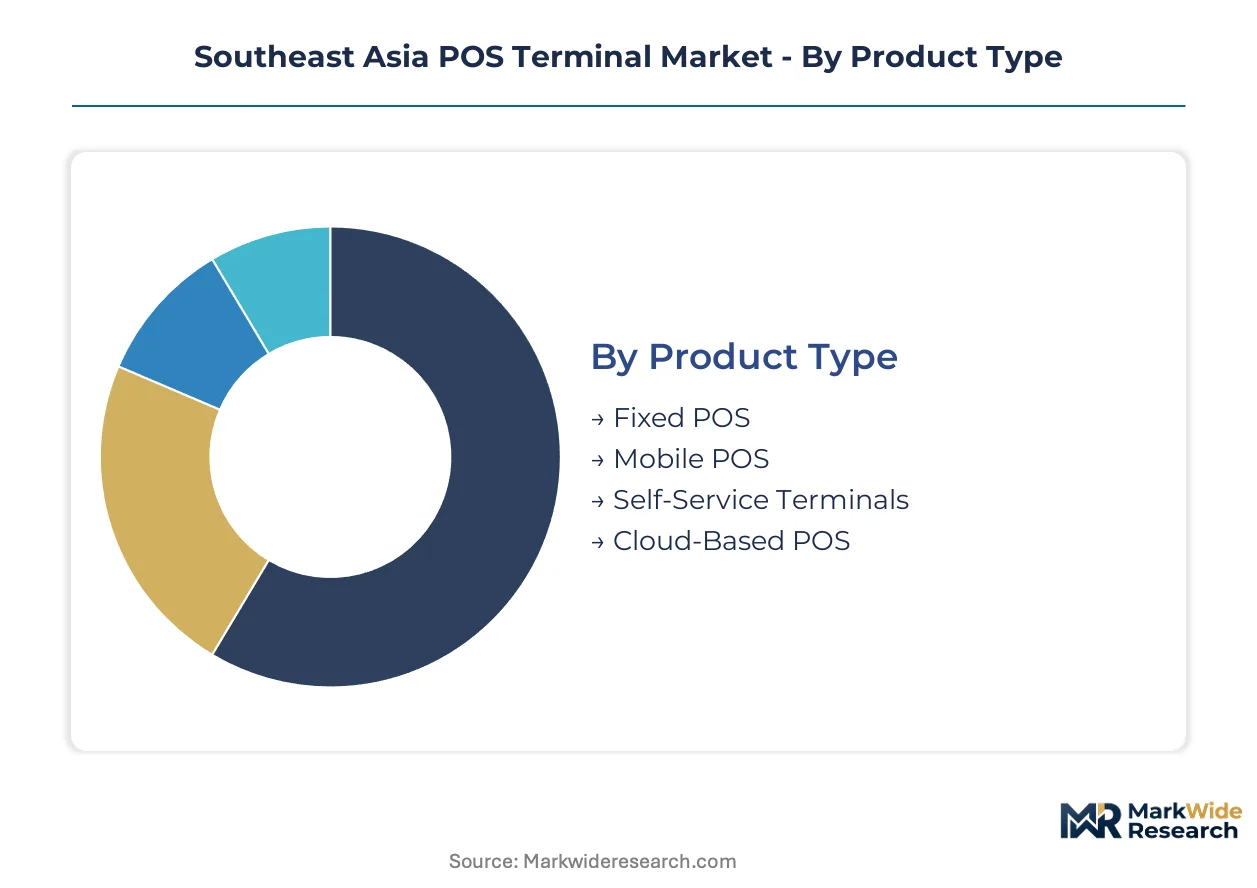
POS terminal segmentation in Southeast Asia reflects divergent infrastructure maturity across merchant tiers. Procurement patterns split between enterprise operators demanding integrated systems and micro-merchants prioritizing low-friction deployment.
Product Type:
Hardware form factor determines integration depth with merchant software stacks and payment rails.
- Fixed POS:Countertop units with Ethernet connectivity and receipt printers dominate Jakarta supermarket chains and Singapore hospitality venues. Bank Negara Malaysia's QR interoperability mandates are forcing firmware upgrades across Malaysia's installed base of legacy fixed terminals.
- Mobile POS:Tablet-based systems with Bluetooth card readers and battery operation are displacing fixed installations across Bangkok and Ho Chi Minh City F&B operators. Cloud-native architecture enables real-time menu updates and split-bill functionality for restaurant chains merging dine-in and delivery channels.
- Self-Service Terminals:Kiosk-format devices with touchscreen ordering and integrated payment capture quick-service restaurant deployment in Singapore and Kuala Lumpur shopping districts.
- Cloud-Based POS:Browser-accessible platforms running on merchant hardware reduce capital expenditure for Vietnamese street vendors and Philippine wet market stallholders entering formal acquiring networks.
Fixed POS leads volumes today; mobile POS is gaining share fastest.
End User:
Vertical-specific workflows shape terminal specification requirements and replacement cycles.
- Retail Chains:Multi-lane checkout environments in Indonesia's Jakarta-Surabaya corridor demand contactless-enabled terminals with inventory system APIs. Dense terminal deployment creates clustered demand pools for hardware vendors with regional service networks.
- Restaurants:Tableside payment and kitchen display integration drive tablet-based adoption across Thailand's mid-market F&B segment. Split settlement between dine-in, takeaway, and delivery channels requires software-agnostic hardware platforms.
- Hospitality:Property management system integration challenges constrain upgrade timelines for decade-old Bangkok and Singapore hotel installations.
- Supermarkets:High-volume transaction processing and loyalty program integration sustain demand for robust fixed terminals with thermal printing and barcode scanning.
Retail chains anchor procurement volumes; restaurants show steepest expansion trajectory.
Deployment:
Infrastructure control preferences separate enterprise operators from asset-light micro-merchants.
- On-Premise:Local server architecture with dedicated terminal networks persists among Singapore financial institutions and Malaysian department stores requiring transaction data sovereignty.
- Cloud:Fully hosted platforms with API-accessible terminals enable rapid multi-location rollout for Vietnamese coffee chains and Indonesian convenience store networks.
- Hybrid:Edge-processing terminals with cloud backup balance latency sensitivity and scalability for Thailand's quick-service restaurant operators.
- Mobile:Smartphone-dependent soft POS applications threaten dedicated terminal volumes among Philippine tricycle drivers and Indonesian ojek payment collectors.
On-premise retains enterprise share; cloud deployment climbs fastest among mid-market entrants.
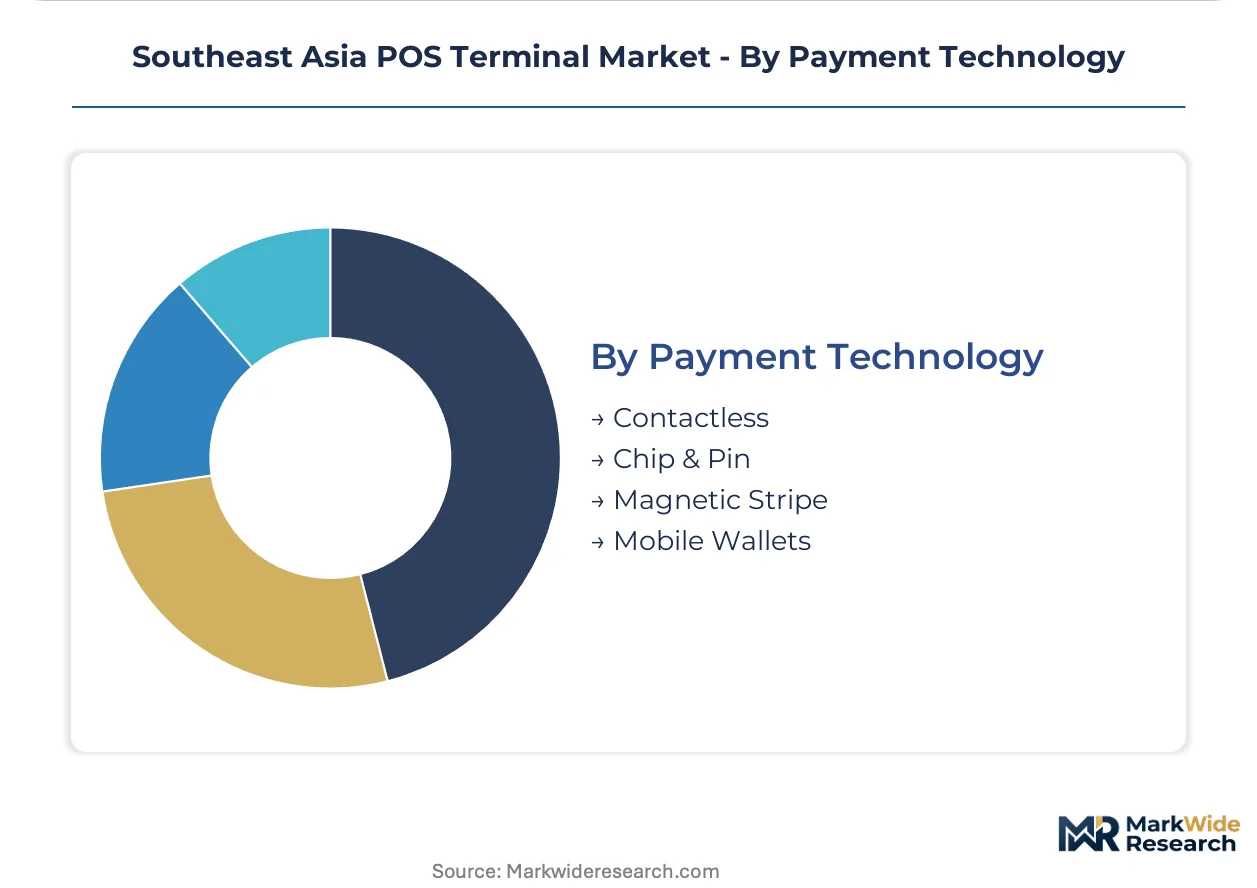
Payment Technology:
Transaction authentication method determines hardware component requirements and certification complexity.
- Contactless:NFC antenna-equipped terminals with sub-500 millisecond tap-to-pay response dominate new procurement across Malaysian retail corridors. Bank Negara Malaysia's interoperability enforcement mandates backward compatibility across DuitNow, GrabPay, and Touch n Go eWallet rails.
- Chip & Pin:EMV-compliant devices with secure element chips retain largest installed base across legacy Bangkok hospitality and Singapore supermarket deployments.
- Magnetic Stripe:Swipe-capable readers persist for international card compatibility in Vietnam's tourism-dependent merchant segments.
- Mobile Wallets:QR code scanning modules and app-to-app payment triggers require camera integration and firmware flexibility for Indonesia's rapidly diversifying digital payment landscape.
Chip & Pin dominates legacy installations; contactless authentication expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Jakarta-Surabaya retail corridor anchors terminal procurement volumes across Southeast Asia, with Indonesian merchant acquirers densifying contactless-enabled device deployment through clustered urban networks.
Indonesia
Bank Indonesia supervises payment system licensing that governs terminal vendor qualification for national merchant acquiring programs. Jakarta and Surabaya concentrate retail chain procurement, creating demand pools for hardware with inventory system APIs. Cloud-native migration accelerates among convenience store networks seeking rapid multi-location rollout.
Malaysia
Bank Negara Malaysia enforces QR code interoperability standards mandating unified terminal compatibility across DuitNow, GrabPay, and Touch n Go eWallet rails. Kuala Lumpur shopping districts drive self-service kiosk deployment for quick-service restaurants. Hardware refresh cycles compress as retailers upgrade legacy fixed terminals for multi-rail firmware compliance.
Thailand
Bank of Thailand licenses payment systems that determine which terminal vendors qualify for national merchant acquiring programs. Bangkok F&B operators abandon fixed installations for tablet-based systems with real-time menu updates. Mid-market restaurant chains merge dine-in and delivery channels through cloud-native architectures.
Vietnam
Payment service providers bundle devices with transaction processing fees to eliminate upfront capital barriers for street vendors. Ho Chi Minh City F&B operators drive mobile POS adoption through Bluetooth card readers and battery-operated tablets. Subscription-based hardware provisioning expands among wet market stallholders entering formal acquiring networks.
Singapore
The Monetary Authority of Singapore maintains cybersecurity certification requirements for POS devices handling cross-border transactions. Enterprise hospitality operators in decade-old hotel installations face property management system integration friction. Compliant vendors command premium pricing for financial hub deployments handling regional payment flows.
Southeast Asia POS Terminal Market Competitive Landscape
Strategic partnerships dominate the current landscape as terminal vendors reposition from device suppliers to platform enablers. The vendor base fragments across hardware specialists, cloud-native software providers, and integrated solution architects. Three archetypes define competitive positioning: legacy fixed POS incumbents with enterprise hospitality accounts, cloud-native specialists serving mid-market F&B operators, and hardware manufacturers supplying contactless-enabled devices for retail chains. Portfolio diversification and geographic expansion represent the dominant competitive moves as suppliers seek multi-country certification coverage.
Within the integrated solution tier, NCR Corporation and Toshiba Tec Corporation exemplify legacy incumbents leveraging fixed POS heritage to anchor enterprise accounts. StoreHub Sdn Bhd occupies a position among cloud-native specialists targeting mid-market operators. PAX Technology Ltd represents the hardware manufacturing archetype, supplying contactless-enabled terminals for Indonesian retail deployment.
| Leading Market Players |
|---|
| Shopify Inc |
| StoreHub Sdn Bhd |
| NCR Corporation |
| Verifone Systems LLC |
| iMetrics Pte Ltd |
| Toshiba Tec Corporation |
| Qashier Pte Ltd |
| PAX Technology Ltd |
| Samsung Electronics Co Ltd |
| Others |
Value Network & Pricing Analysis
Bank Negara Malaysia's QR interoperability enforcement gates qualified supply for premium-tier terminal access across Malaysian retail networks, compressing hardware refresh timelines while elevating firmware-certified devices above commodity alternatives. Merchant acquirers in Jakarta and Bangkok face parallel certification barriers that stratify procurement pools between multi-rail-compliant suppliers and price-pressured legacy vendors.
Pricing Analysis
Distributor margins compress as hardware vendors bypass regional intermediaries to serve Indonesian retail chains and Singapore hospitality groups directly. Subscription-based SaaS tiers now dominate Vietnamese and Philippine micro-merchant segments, eliminating upfront capital barriers while embedding processing fees. Price differentiation rests on Bank Indonesia licensing status and Singapore cybersecurity certification tier. Cost compression in standard-grade terminals intensifies as smartphone-based soft POS alternatives erode dedicated device volumes. Street vendors and wet market stallholders exhibit highest price sensitivity; Singapore financial institutions and Malaysian department stores accept premium positioning for cross-border transaction compliance.
Supply Chain Analysis
Dual-sourcing requirements from merchant acquirers in Thailand and Malaysia mandate multi-supplier qualification for NFC controllers and secure element chips, fragmenting procurement across Taiwanese and South Korean foundries. Terminal assembly concentrates in China, Malaysia, and Vietnam, with firmware customization anchoring in Singapore and Jakarta. Raw material dependencies span EMV chip modules, Bluetooth antenna arrays, and thermal printing mechanisms. Single-source vulnerability in Taiwanese semiconductor supply exposes manufacturers to input cost volatility. Distribution runs through payment service providers bundling devices with acquiring services, bypassing traditional electronics wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Southeast Asia POS terminal market reads as a late-cycle quality story where Bank Negara Malaysia's interoperability mandate and Singapore's cybersecurity certification are concentrating procurement around specification-compliant vendors. Demand is shifting toward premium-tier terminals capable of simultaneous multi-rail authentication and cross-border transaction handling.
For Market Incumbents: Lock in certification moats across Bank Indonesia, Bank Negara Malaysia, and Singapore's Monetary Authority simultaneously to forestall hardware redesign cycles that favor agile competitors. Prioritize backward integration into secure element chip sourcing to offset Taiwanese foundry concentration. Defend enterprise hospitality accounts in Bangkok and Singapore against cloud-native specialists through property management system API partnerships. For New Entrants and Emerging Players: Payment service providers in Vietnam and the Philippines represent the most penetrable channel partner type, with subscription-based hardware provisioning creating white-space among street vendors previously excluded from formal acquiring. Target Indonesian convenience store networks seeking rapid multi-location cloud rollout without legacy system friction. Position around Android-based open-platform terminals that collapse distinctions between payment hardware and merchant tablets. For Investors and Strategic Acquirers: Roll-up economics work for cloud-native POS specialists because mid-market F&B operators across Thailand and Vietnam are abandoning fixed installations faster than legacy incumbents can reposition. Long-term viability favors vendors with multi-country certification coverage spanning the analysis window. Acquisition target archetype: Malaysian or Indonesian software-agnostic hardware platforms with proven DuitNow and QRIS rail integration. Watch Bank of Thailand licensing timeline acceleration as inflection indicator for vendor consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Rail Certification Investment | Bank Negara Malaysia's interoperability mandate forces firmware complexity that advantages pre-qualified vendors. |
| Cloud-Native Platform Migration | Thai and Vietnamese restaurant chains merge dine-in and delivery channels through tablet-based architectures. |
| Backward Integration into Secure Elements | Taiwanese and South Korean foundry concentration creates input cost exposure for terminal manufacturers. |
| Subscription-Based Hardware Provisioning | Vietnamese and Philippine payment service providers bundle devices to eliminate upfront capital barriers. |
| Cross-Border Cybersecurity Compliance | Singapore's certification requirements position compliant vendors for premium pricing in financial hub deployments. |
Research Methodology
Multiple input streams — structured interviews with payment system executives, merchant acquiring network managers, and terminal hardware procurement leads; regulatory filings from Bank Indonesia, Bank Negara Malaysia, and Singapore's Monetary Authority; and customs data on semiconductor component trade flows — were reconciled through bottom-up and top-down triangulation. Secondary validation drew from central bank payment system reports, merchant acquiring network disclosures, and EMV certification databases. Cross-referencing primary stakeholder perspectives against documented certification timelines and hardware deployment statistics ensured statistical integrity across the analysis window.
Historical terminal deployment patterns across Jakarta, Bangkok, and Singapore were cross-referenced against panel input from payment service providers and retail chain technology officers to construct the projection framework. Segmentation dimensions modeled include hardware form factor, deployment architecture, payment authentication technology, and end-user vertical. CAGRs were derived through trend extrapolation adjusted for regulatory intervention timing and merchant tier penetration rates. Industry-specific forecast inputs incorporated QR code interoperability enforcement schedules and cloud-native migration velocity among mid-market F&B operators.
Revisions become necessary when central bank certification timelines diverge from modeled assumptions, semiconductor supply disruptions extend beyond anticipated durations, or smartphone-based soft POS substitution accelerates among micro-merchant segments. Forecasts reflect documented assumptions regarding regulatory harmonization progress and merchant acquiring network densification rates. Deviation in Bank Indonesia licensing velocity or Bank Negara Malaysia interoperability enforcement strictness would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Global Telecom Billing and Revenue Management Market
Payments
Global Virtual Cards Market
Payments
Netherlands POS Terminal Market
Payments
Canada Mobile Payments Market
Payments
MENA Digital Payments Market
Payments
Germany Payment Gateway Market
Payments
Wireless POS Terminals Market
Payments
Asia-Pacific Crypto Payment Gateway Market
Payments
Point-Of-Sale [POS] Terminal Market
Payments
Portugal Mobile Payments Market
Payments
Direct Carrier Billing Platform Market
Payments
Canada Payment Gateway Market
Payments
United States Payment Gateways Market
Payments
Remittance Market
Payments
Clearing Houses and Settlements Market
Payments
Biometric Payment Market