
 Ghana Mobile Money Market | 2026-2036
Ghana Mobile Money Market Size, Share, and Industry Trends Forecast 2026-2036
Ghana Mobile Money Market Intelligence
The capital-intensity divergence between agent-network heavyweights and API-first challengers is collapsing as cloud infrastructure costs plummet. MTN Mobile Money (MoMo) leverages its 200,000-plus agent footprint to sustain rural penetration that digital-only entrants cannot replicate. Zeepay competes through cross-border remittance corridors anchored in diaspora corridors from the United Kingdom and United States. G-Money (GCB Bank) differentiates by occupying the formal banking interface, converting unbanked users through interoperable wallet-to-account bridges.
Ghana mobile money denotes electronic value storage and transfer services accessible via basic mobile devices without requiring traditional bank accounts, typically operating over USSD sessions or lightweight applications with transaction thresholds governed by tiered know-your-customer verification. The primary commercial purpose centers on substituting cash-dominated retail commerce, agricultural commodity trading, and informal sector wage disbursements with traceable digital rails. Wallet Services dominates transaction volume by capturing peer-to-peer transfers and merchant payments that constitute daily liquidity circulation for retail customers. Payment Processing represents the fastest-expanding margin pool as small enterprises adopt QR-code acceptance for customer-facing transactions. Remittance Services carries premium pricing structures tied to foreign-exchange conversion spreads and cross-border settlement complexity.
The Bank of Ghana exercises direct oversight through its Payment Systems and Services Act, mandating capital reserves and transaction reporting that filter out undercapitalized operators. ISO 20022 messaging standards and the national interoperability switch administered by Ghana Interbank Payment and Settlement Systems compress fragmentation between competing wallet ecosystems. Stakeholders must monitor whether the central bank's e-cedi pilot program absorbs or complements private mobile money balances.
Market Dynamics
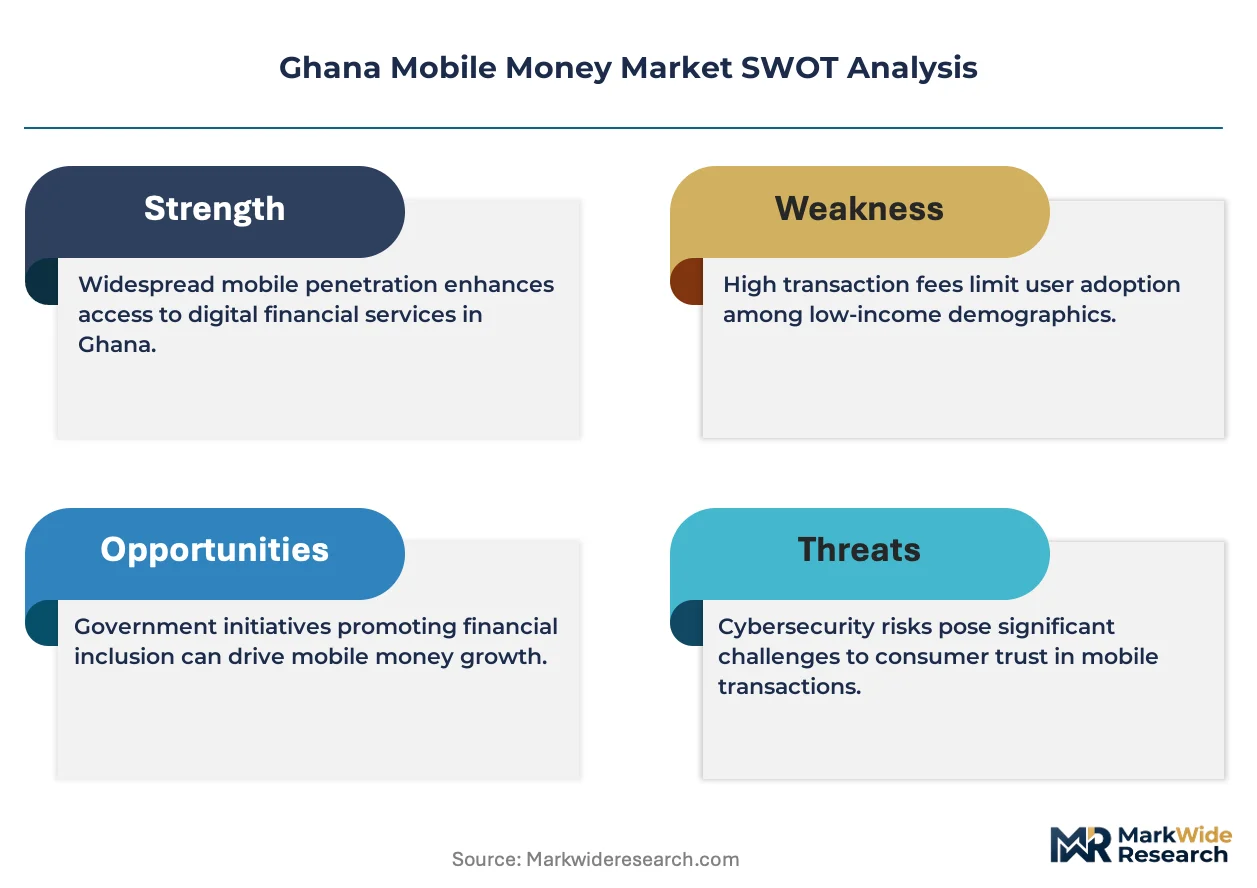
The Bank of Ghana's tiered KYC framework and interoperability mandates are compressing informal cash circulation while forcing wallet providers to rebuild infrastructure around verified identity rails rather than anonymous transaction volume.
Growth Catalysts
- Payment Systems and Services Act:Ghana's central bank mandates capital reserves and transaction reporting that professionalize operator standards and filter out undercapitalized competitors, elevating trust in formal channels.
- QR-code merchant acceptance:Small enterprises in Accra and Kumasi are adopting standardized payment codes for customer-facing transactions, converting daily retail commerce onto traceable digital rails.
- Cross-border remittance corridors:Diaspora flows from the United Kingdom and United States anchor premium-margin services, with foreign-exchange conversion spreads sustaining revenue pools unavailable in domestic peer-to-peer transfers.
Market Restraints
- Agent network concentration:Rural penetration depends on physical cash-in/cash-out points that digital-only entrants cannot replicate without massive fixed-cost deployment, locking market access behind incumbent infrastructure.
- Foreign-exchange volatility:Remittance pricing fluctuates with cedi-dollar and cedi-pound sterling movements, compressing margins unpredictably and complicating hedging for cross-border service providers.
- USSD session limitations:Basic feature-phone interfaces constrain transaction complexity and user experience, creating a technical ceiling on service sophistication for unbanked populations without smartphone access.
Strategic Opportunities
- Northern Region agricultural trading:Cocoa and shea nut value chains remain cash-dominated, presenting white-space for crop-payment digitization and warehouse-receipt financing linked to mobile wallets.
- E-cedi pilot complementarity:The central bank's wholesale CBDC experimentation may create API interfaces that private wallets can leverage for settlement finality without balance displacement.
- Interoperable wallet-to-account bridges:Formal banking interfaces that convert unbanked users through seamless fund movement between mobile money and traditional deposit accounts unlock savings-product cross-selling.
Industry Challenges
- ISO 20022 migration complexity:Message standardization across the Ghana Interbank Payment and Settlement Systems switch demands middleware rewrites that strain smaller operators' engineering capacity.
- Fraud detection talent scarcity:Machine-learning model development for real-time transaction monitoring requires data-science capabilities concentrated in Accra, creating recruitment bottlenecks for regional expansion.
- Legacy core banking integration:Rural and community banks with outdated IT infrastructure face prolonged API connection timelines, delaying interoperability benefits for their customer bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ghana Mobile Money Market |
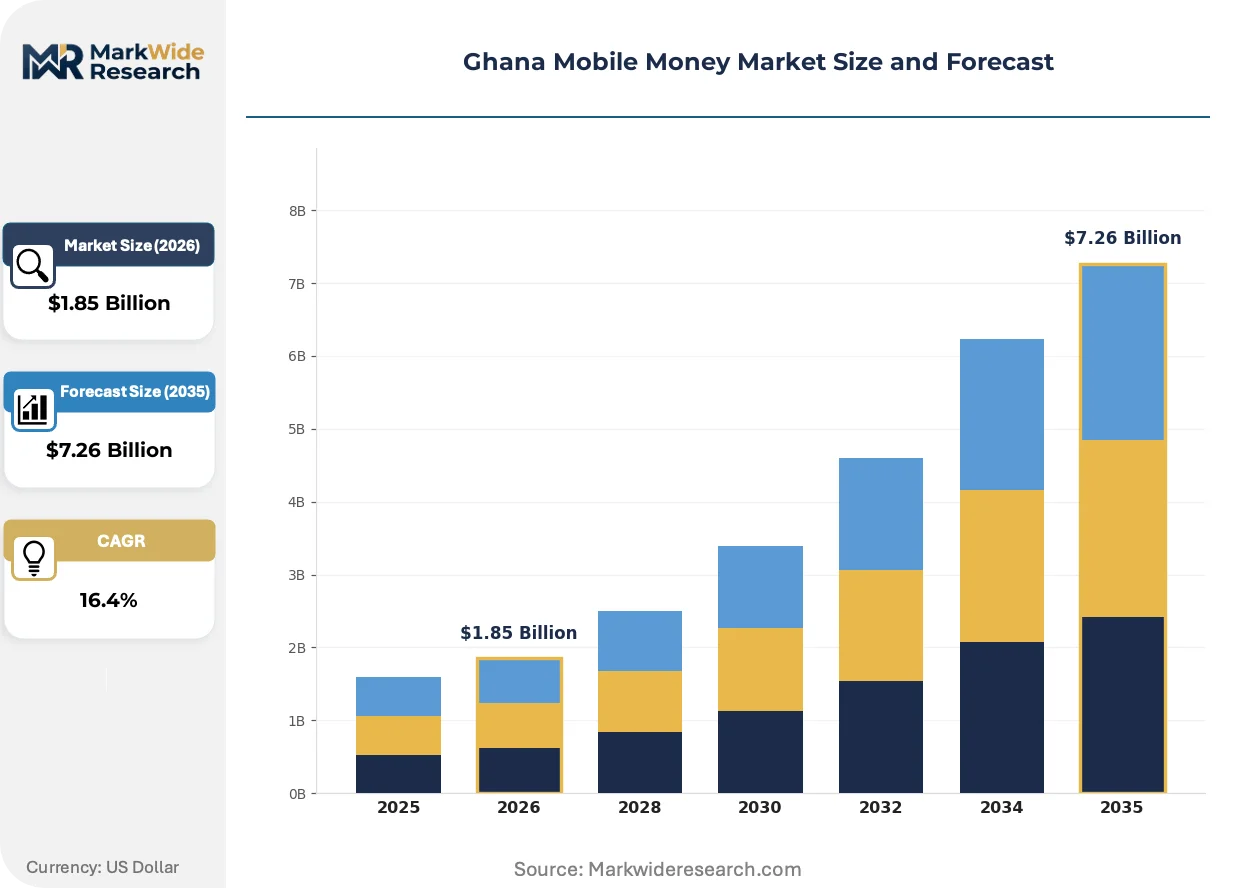
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $7.26 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Wallet Services, Payment Processing, Remittance Services, Bill Payment End User: Retail Customers, Small Enterprises, Large Enterprises, Government Agencies Technology: USSD, Mobile Apps, Web Platforms, APIs Distribution Channel: Direct Sales, Partnerships, Online Platforms, Agents |
| Companies Covered | MobileMoney Ltd., G-Money (GCB Bank), MTN Mobile Money (MoMo), Onafriq, JUMO, Vodafone Cash, Zeepay, Ghana Commercial Bank, AirtelTigo Money, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ghana Mobile Money Market Strategic Shifts & Innovations
Agent-assisted onboarding and lightweight application interfaces are reshaping how financial services reach populations outside traditional branch networks, with regulatory pressure accelerating identity-verification technology investment.
Biometric SIM registration is miniaturizing identity verification into USSD sessions and basic feature-phone interactions. Rural agricultural cooperatives in Ghana's cocoa belt are adopting fingerprint-linked wallet activation at a pace that outstrips smartphone penetration. This technology is compressing the gap between formal banking KYC standards and informal sector accessibility, enabling tiered transaction limits without branch visits.
Ghana's Payment Systems and Services Act enforcement is tightening capital reserve requirements and real-time transaction reporting obligations. The industrial consequence is a filtering effect that raises operational barriers for undercapitalized entrants while rewarding incumbents with compliance infrastructure already deployed. Tier-2 and Tier-3 wallet providers in the Greater Accra corridor are responding by consolidating or seeking strategic partnerships with bank-backed issuers.
Merchant payment behavior is fragmenting across channel preferences as small enterprises reject single-wallet exclusivity. QR-code aggregators that route transactions across multiple schemes are displacing proprietary acceptance infrastructure in Accra's digital merchant ecosystem. This channel disintermediation is most visible among fast-moving consumer goods distributors in urban centers, where checkout flexibility now outweighs loyalty program incentives in vendor selection criteria.
Ghana Mobile Money Market Segmentation
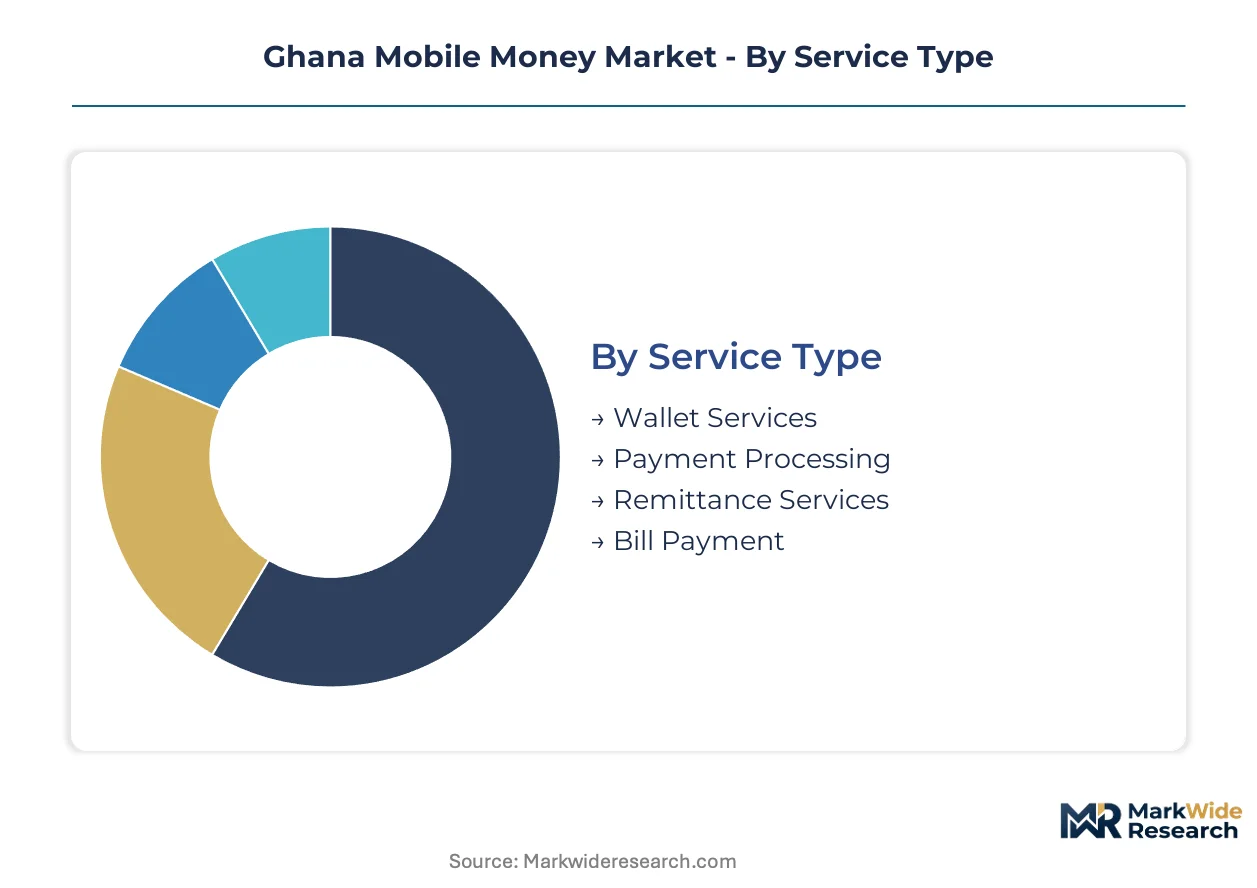
Segmentation reveals how Ghana's mobile money infrastructure fragments across service modalities and customer sophistication levels. Each dimension exposes distinct margin structures, regulatory exposure, and competitive dynamics that shape provider strategy.
Service Type:
Wallet Services faces the most intense substitute threat from emerging CBDC architectures, while Payment Processing enjoys structural protection through merchant lock-in effects.
- Wallet Services:Electronic value storage and peer-to-peer transfer functionality operating over USSD sessions or lightweight applications with tiered KYC-governed transaction thresholds. Demand concentrates within Greater Accra's informal retail sector as the Bank of Ghana's cash-lite directives compress physical currency circulation.
- Payment Processing:QR-code acceptance infrastructure and merchant-facing transaction rails that convert customer payments into digital settlements. Small enterprises in Accra and Kumasi are deepening adoption for supplier payments, displacing cash-dominant checkout behaviors.
- Remittance Services:Cross-border value transfer anchored in diaspora corridors from the United Kingdom and United States, carrying foreign-exchange conversion spreads.
- Bill Payment:Utility and service settlement functionality integrated into mobile money menus, capturing recurring payment automation demand.
Wallet Services anchors the volume base while Payment Processing gains share at the steepest rate.
End User:
Cost tier stratification separates mass-market accessibility from premium service bundles across Ghana's user base.
- Retail Customers:Individual users conducting peer-to-peer transfers, merchant payments, and informal sector wage receipts through basic feature-phone interfaces. Northern Region agricultural cooperatives are adopting biometric-linked wallet activation for crop-payment digitization.
- Small Enterprises:Informal and formal micro-businesses utilizing mobile money for supplier payments, inventory procurement, and customer checkout acceptance. Fast-moving consumer goods distributors in urban centers prioritize checkout flexibility over single-wallet loyalty programs.
- Large Enterprises:Corporate treasuries and established businesses requiring interoperable wallet-to-account bridges and formal banking interface integration.
- Government Agencies:Public sector disbursement channels for social payments, salary distribution, and tax collection digitization.
Retail Customers dominate transaction volume while Small Enterprises drive margin expansion through merchant fee structures.
Technology:
Application maturity varies sharply between legacy USSD infrastructure and smartphone-dependent platforms.
- USSD:Session-based interaction protocols enabling basic feature-phone access without internet connectivity, constrained by interface complexity limitations.
- Mobile Apps:Smartphone-deployed applications offering enhanced user experience and service sophistication for banked and digitally literate populations.
- Web Platforms:Browser-accessible interfaces serving enterprise treasury functions and higher-value transaction categories.
- APIs:Machine-readable integration endpoints enabling third-party service embedding and interoperability switch connectivity through Ghana Interbank Payment and Settlement Systems.
USSD retains the widest penetration while APIs are climbing the fastest as ISO 20022 standardization demands middleware modernization.
Distribution Channel:
Physical infrastructure concentration versus digital reach defines competitive positioning across channel strategies.
- Direct Sales:Provider-owned customer acquisition and service delivery without intermediary involvement.
- Partnerships:Strategic alliances with banks, telecommunications operators, and fintech platforms for co-branded service distribution.
- Online Platforms:Digital-native onboarding and self-service transaction capabilities.
- Agents:Physical cash-in/cash-out points sustaining rural penetration through human-assisted liquidity management.
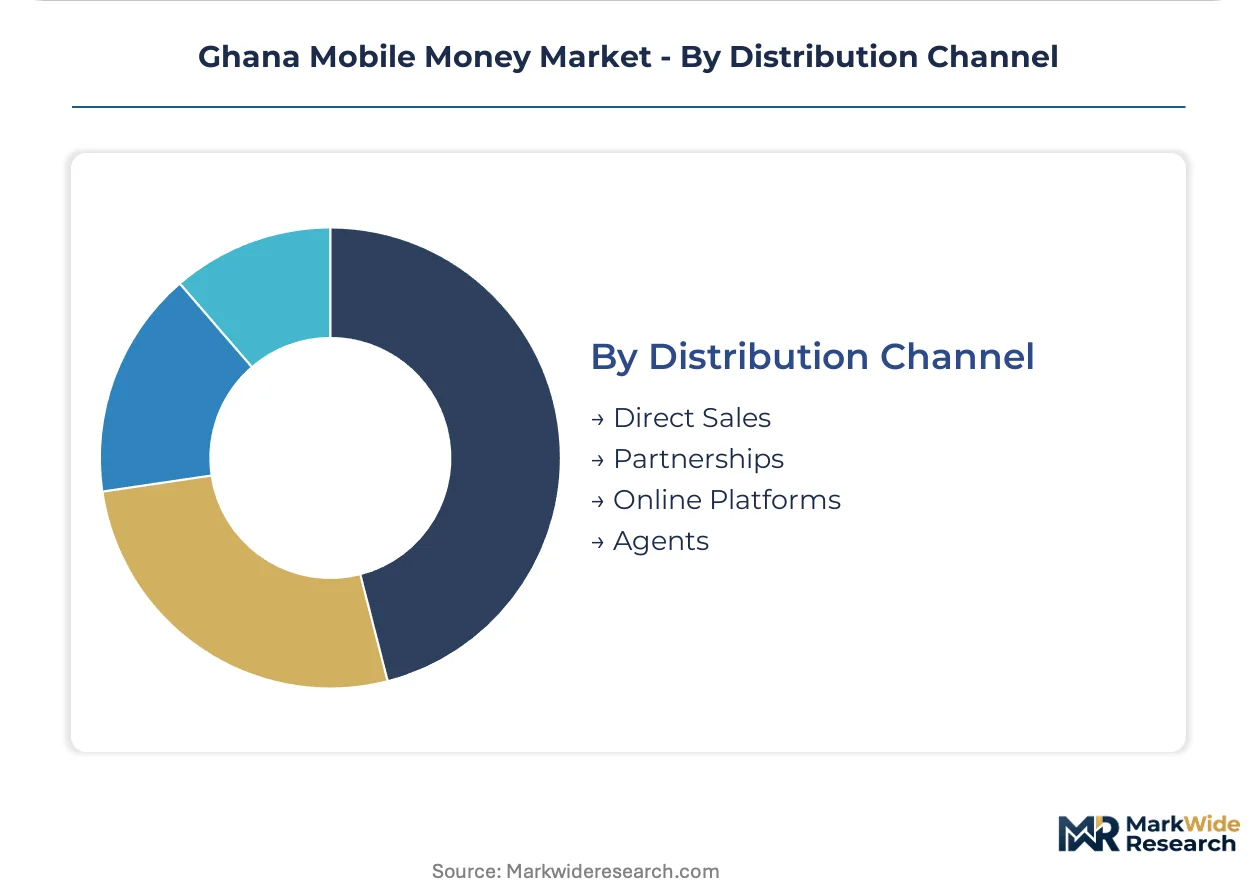
Agents anchor market access in rural corridors while Online Platforms expand most quickly among urban smartphone users.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ghana's mobile money infrastructure exhibits pronounced regional asymmetry, with trade corridors and agricultural value chains driving divergent adoption patterns across sub-national markets. The export-import balance of digital liquidity concentrates in southern commercial hubs while northern production regions lag in formal financial penetration.
Greater Accra Region
Accra's digital merchant ecosystem anchors national transaction volume through QR-code acceptance networks and interoperable wallet-to-account bridges. The Bank of Ghana's cash-lite policy directives compress informal cash handling in urban retail corridors. Tema's port logistics cluster drives corporate treasury digitization for import-export settlement workflows.
Ashanti Region
Kumasi's fast-moving consumer goods distributors prioritize checkout flexibility over single-wallet loyalty programs, accelerating merchant payment adoption. Tiered KYC regulations from the central bank professionalize operator standards across the region's informal trading networks. Suame Magazine's industrial cluster represents emerging demand for supplier payment digitization among small metalworking enterprises.
Northern Region
Cocoa and shea nut value chains remain cash-dominated, presenting white-space for crop-payment digitization linked to mobile wallets. Biometric SIM registration enables fingerprint-linked wallet activation at rural agricultural cooperatives. Tamale's emerging commercial corridor shows early merchant payment infrastructure deployment alongside traditional cash crop trading posts.
Western Region
Takoradi's oil services supply chain generates demand for interoperable wallet-to-account bridges among contract workers and logistics operators. The Bank of Ghana's Payment Systems and Services Act mandates elevate trust in formal channels for petroleum sector wage disbursements. Sekondi's port-adjacent trading communities exhibit accelerating QR-code merchant acceptance for fishing industry procurement.
Central Region
Cape Coast's tourism and education sectors drive peer-to-peer transfer volume among student populations and hospitality micro-enterprises. Agent network concentration sustains rural penetration through physical cash-in/cash-out points in cocoa belt communities. Winneba's fishing cooperative networks represent untapped demand for warehouse-receipt financing linked to mobile money balances.
Ghana Mobile Money Market Key Industry Players
Concentration sits with telecommunications-anchored incumbents possessing dense agent infrastructure that digital-native challengers cannot replicate without massive fixed-cost deployment. The market structure exhibits tiered competition between agent-network heavyweights, bank-backed issuers, and API-first fintech specialists. Three strategic archetypes dominate: infrastructure-intensive incumbents leveraging physical distribution, formal banking interfaces occupying regulated wallet-to-account bridges, and cross-border specialists capturing diaspora remittance premiums. Dominant competitive moves include strategic partnerships with agricultural cooperatives for rural penetration and interoperability investments compressing fragmentation between wallet ecosystems.
Within the telecommunications-anchored tier, MTN Mobile Money (MoMo) exemplifies infrastructure-intensive market presence through its extensive agent footprint. Zeepay occupies a position among cross-border specialists targeting diaspora corridors from the United Kingdom and United States. G-Money (GCB Bank) represents the formal banking interface archetype, converting unbanked users through interoperable wallet-to-account bridges that unlock savings-product cross-selling opportunities.
| Leading Market Players |
|---|
| MobileMoney Ltd. |
| G-Money (GCB Bank) |
| MTN Mobile Money (MoMo) |
| Onafriq |
| JUMO |
| Vodafone Cash |
| Zeepay |
| Ghana Commercial Bank |
| AirtelTigo Money |
| Others |
Cost & Logistics Intelligence
Agent network density in Ghana's Greater Accra corridor compresses per-transaction cost floors while tiered KYC compliance investments elevate minimum operational scale for viable market entry. The Bank of Ghana's Payment Systems and Services Act capital requirements force consolidation among sub-scale operators, concentrating pricing power with infrastructure-heavy incumbents that amortize fixed costs across volume bases smaller challengers cannot replicate.
Pricing Analysis
Small enterprise merchants anchor Ghana's mobile money pricing structure through QR-code acceptance networks that extract per-transaction fees from retail commerce digitization. Three-tier pricing stratifies across premium cross-border remittance corridors, standard domestic peer-to-peer transfers, and economy-tier agricultural payment rails. Pricing pressure stems from interoperability mandates compressing wallet-to-wallet friction and eroding proprietary scheme premiums. Rural agricultural cooperatives exhibit highest price sensitivity due to thin commodity trading margins, while diaspora remittance senders in the United Kingdom and United States demonstrate lowest sensitivity to foreign-exchange spread variations.
Supply Chain Analysis
Ghana and Nigeria anchor West Africa's mobile money infrastructure supply chain through dense agent network deployment and cloud-hosting capacity for platform operations. Critical inputs draw from Chinese telecommunications hardware for USSD gateway equipment, Indian software development for biometric verification modules, and South African cloud infrastructure for transaction processing resilience. Single-source vulnerability concentrates in agent liquidity management systems where cash-in/cash-out float depends on banking partner concentration. Distribution runs through telecommunications-owned agent hierarchies in urban centers and agricultural cooperative partnerships in rural corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ghana's mobile money market operates as a substitution defense against central bank digital currency displacement, with the Bank of Ghana's e-cedi pilot representing the paramount substitute threat that private wallet providers must navigate through complementarity positioning.
For Market Incumbents: Secure interoperability certification ahead of ISO 20022 migration deadlines to lock in switch connectivity advantages that undercapitalized competitors cannot fund. Deepen vertical integration into biometric verification technology to preempt regulatory KYC escalation and defend margin position against API-first challengers with leaner cost structures.
For New Entrants and Emerging Players: Agricultural payment digitization in Ghana's Northern Region cocoa and shea nut value chains offers white-space penetration where incumbent agent networks under-serve seasonal trading patterns. Target warehouse-receipt financing linkages to mobile wallets as the most penetrable application layer, deploying partnership-based go-to-market models with established agricultural cooperatives rather than proprietary infrastructure buildout.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among bank-backed wallet providers with interoperable account bridges that capture savings-product cross-selling. Long-term viability over a multi-year horizon favors acquirers targeting Tier-2 operators facing capital reserve pressure from the Payment Systems and Services Act. The signal to watch is central bank guidance on e-cedi private wallet integration APIs as inflection indicator for balance displacement risk versus complementarity opportunity.
| Strategic Initiative | Industry Significance |
|---|---|
| Agent Network Consolidation | Densifies rural penetration in cocoa belt communities beyond digital-only reach. |
| Biometric KYC Technology Deployment | Compresses identity verification costs for agricultural cooperative onboarding at scale. |
| Cross-Border Remittance Corridor Expansion | Captures premium spreads from United Kingdom and United States diaspora flows. |
| Interoperable Wallet-to-Account Bridge Development | Unlocks formal banking product cross-selling through GCB Bank infrastructure integration. |
| QR-Code Aggregator Platform Launch | Displaces proprietary merchant acceptance infrastructure in Accra's fast-moving consumer goods distribution. |
Research Approach
A standing panel of mobile money platform executives, Bank of Ghana regulatory officers, agricultural cooperative treasurers, and telecommunications infrastructure managers provided ongoing calibration across the study period. Primary interview insights combined with secondary validation from Bank of Ghana payment systems reports, Ghana Interbank Payment and Settlement Systems switch transaction disclosures, and West African telecommunications regulatory filings. Bottom-up agent network enumeration and top-down macroeconomic liquidity modeling triangulated volume and value estimates.
Consistency checks against external benchmarks validated projection outputs across service type, end user sophistication, technology deployment, and distribution channel segmentation dimensions. CAGRs derived from trend extrapolation of historical transaction growth rates, adjusted for regulatory intervention effects and interoperability penetration curves. Industry-specific forecast inputs incorporated USSD session volume trajectories and smartphone adoption elasticity in rural versus urban corridors.
Forecasts assume regulatory continuity in Bank of Ghana tiered KYC and capital reserve regimes; material policy shifts including e-cedi retail launch or agent network licensing changes would require re-modeling. Specific risk factors encompass foreign-exchange volatility in cedi-pound sterling and cedi-dollar corridors, biometric technology deployment delays in agricultural regions, and telecommunications infrastructure investment cycles. Recalibration cycles align with material shifts in central bank digital currency guidance and interoperability switch transaction reporting.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Middle East and Africa Payments Market
Payments
Global Prepaid Cards Market
Payments
Cross-Border Payment Platform Market
Payments
Europe Prepaid Card Market
Payments
Europe Accounts Payable Automation Market
Payments
UK Virtual Cards Market
Payments
Europe Gift Card and Incentive Card Market
Payments
Japan Mobile Payments Market
Payments
Global Digital Wallets Market
Payments
Nigeria Mobile Money Market
Payments
Canada Real Time Payments Market
Payments
Recurring Payments Market
Payments
Middle East and Africa Payment Gateway Market
Payments
Hungary POS Terminal Market
Payments
Europe Clearing Houses and Settlements Market
Payments
France Mobile Payment Market