
 United Kingdom Real Time Payments Market | 2026-2036
United Kingdom Real Time Payments Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Real Time Payments Market Analytics
The UK's Consumer Duty regulations from the Financial Conduct Authority is rebalancing how payment providers design real-time interfaces for transparency and fair value. Mastercard leverages its Vocalink infrastructure to sustain dominance in retail bank connectivity across the Faster Payments Service. Revolut competes through multi-currency instant transfers that anchor its position among digitally native consumers. Starling Bank differentiates via API-first banking that controls developer access to real-time settlement rails.
Real time payments are electronic fund transfers that settle funds between bank accounts within seconds, typically operating on ISO 20022 messaging standards that enable rich data attachment for reconciliation and compliance. These systems serve commercial and retail users by eliminating settlement risk and accelerating cash flow velocity for businesses dependent on immediate liquidity. Mobile payments and instant transfers lead transaction volume growth as consumers abandon card-not-present methods for biometrically authenticated smartphone-initiated settlements. API integration represents the fastest-expanding technology type, where margin pools concentrate among infrastructure providers enabling bank-fintech interoperability rather than front-end consumer applications alone.
The Financial Conduct Authority, the Competition and Markets Authority, and the Payment Systems Regulator collectively shape UK real-time payment demand through conduct standards, Open Banking mandates, and systemic competition reviews. The FCA's Consumer Duty raises product design requirements for real-time interfaces, while the PSR's access rules determine which non-bank providers can reach settlement infrastructure. Stakeholders must monitor how forthcoming central bank digital currency consultations alter the competitive boundary between private real-time rails and public settlement alternatives.
Market Dynamics
The Competition and Markets Authority's Open Banking mandate is restructuring competitive access to Faster Payments Service infrastructure, forcing incumbents to open API gateways that challenger fintechs exploit for real-time settlement products.
Growth Catalysts
- ISO 20022 migration:Rich data standards enable automated reconciliation for corporate treasuries, reducing manual processing overhead in B2B payment workflows.
- E-commerce merchant demand:Online retailers require instant settlement to eliminate chargeback risk and improve working capital velocity during peak trading periods.
- Regulatory sandbox access:The Financial Conduct Authority's controlled testing environment accelerates product validation for payment innovators seeking Faster Payments Service connectivity.
Market Restraints
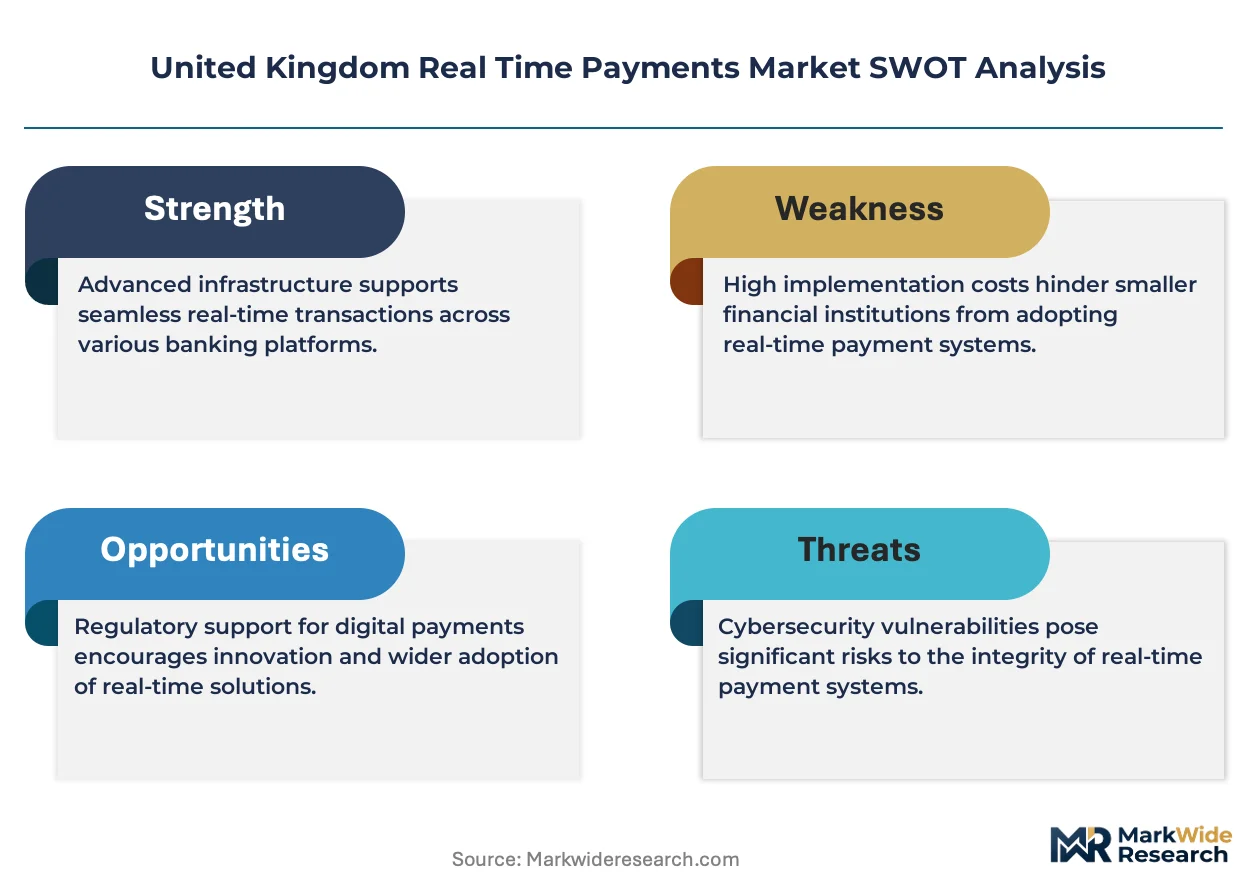
- Core banking system replacement costs:Legacy infrastructure at traditional banks requires substantial capital expenditure to achieve real-time processing capability.
- Settlement risk concentration:The Bank of England's RTGS system represents a single point of failure for wholesale real-time clearing.
- Fraud liability ambiguity:The Payment Systems Regulator's evolving reimbursement rules create uncertainty for payment service providers on liability allocation.
Strategic Opportunities
- SME treasury automation:Underpenetrated mid-market businesses in Manchester and Birmingham lack sophisticated cash management tools that real-time APIs could deliver.
- Request to Pay overlay services:The Pay.UK infrastructure upgrade enables invoice-presentment functionality that billers can deploy for B2B collections.
- Variable recurring payments:Open Banking-enabled subscription billing creates new revenue pools for utility and insurance providers seeking direct debit alternatives.
Industry Challenges
- API standardization fragmentation:Inconsistent implementation of Open Banking specifications across tier-two banks complicates fintech integration roadmaps.
- Real-time fraud detection capability gaps:Machine learning talent scarcity limits payment providers' ability to build sub-second transaction screening systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Real Time Payments Market |
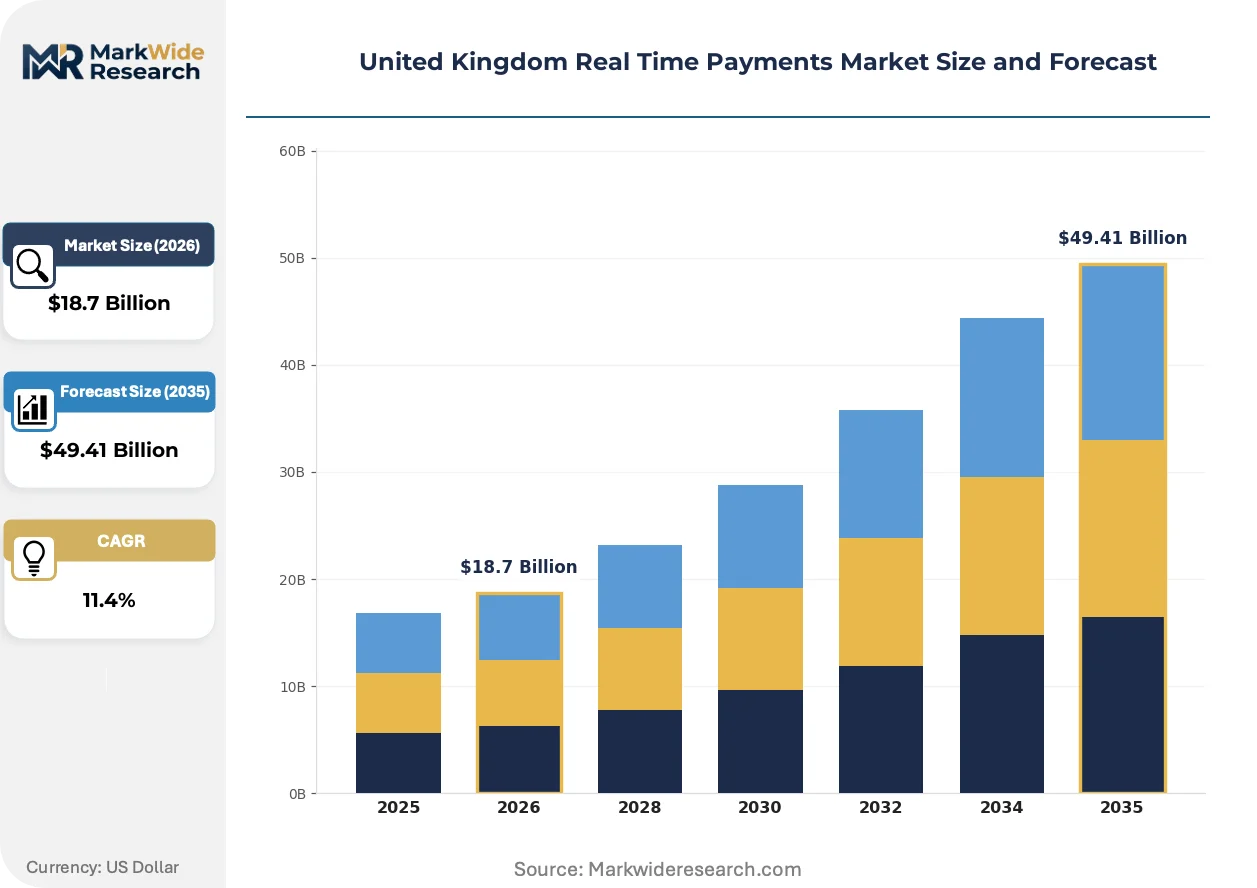
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Mobile Payments, Online Banking, Instant Transfers, QR Code Payments User Segment: Retail Consumers, Small Businesses, Corporates, Financial Institutions Technology Type: Blockchain, NFC, Open Banking, API Integration Transaction Volume: Low Value, Medium Value, High Value, Bulk Payments |
| Companies Covered | Mastercard (Vocalink), Revolut, ACI Worldwide, Starling Bank, Monzo, Fiserv, Visa, Worldpay, PayPal, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Real Time Payments Market Evolving Landscape
API-first architecture is compressing product development cycles across the UK payment stack, enabling modular services that unbundle traditional banking functionality into discrete, composable capabilities.
Cloud-native core banking platforms is electrifying infrastructure deployment for challengers, allowing new entrants to launch real-time payment products without datacenter capital. Starling Bank and Monzo have demonstrated this model at scale. The technology is electrifying margin structures by eliminating legacy maintenance burdens that weigh on incumbent cost bases.
The Financial Conduct Authority's Consumer Duty rules are tightening product design standards for real-time interfaces, requiring explicit fair value demonstration and vulnerability detection. Payment providers must document how instant transfer features serve customer interests rather than driving fee extraction. Digital banks are responding by embedding spending analytics and cooling-off periods into their real-time transfer workflows.
Merchant procurement of payment acceptance is fragmenting across specialized providers rather than consolidating with traditional acquirers. E-commerce platforms in London's retail corridor now evaluate real-time settlement capability as a primary vendor selection criterion alongside interchange pricing. This behavior is most pronounced among fashion and grocery verticals where inventory turnover demands immediate fund availability.
United Kingdom Real Time Payments Market Segmentation
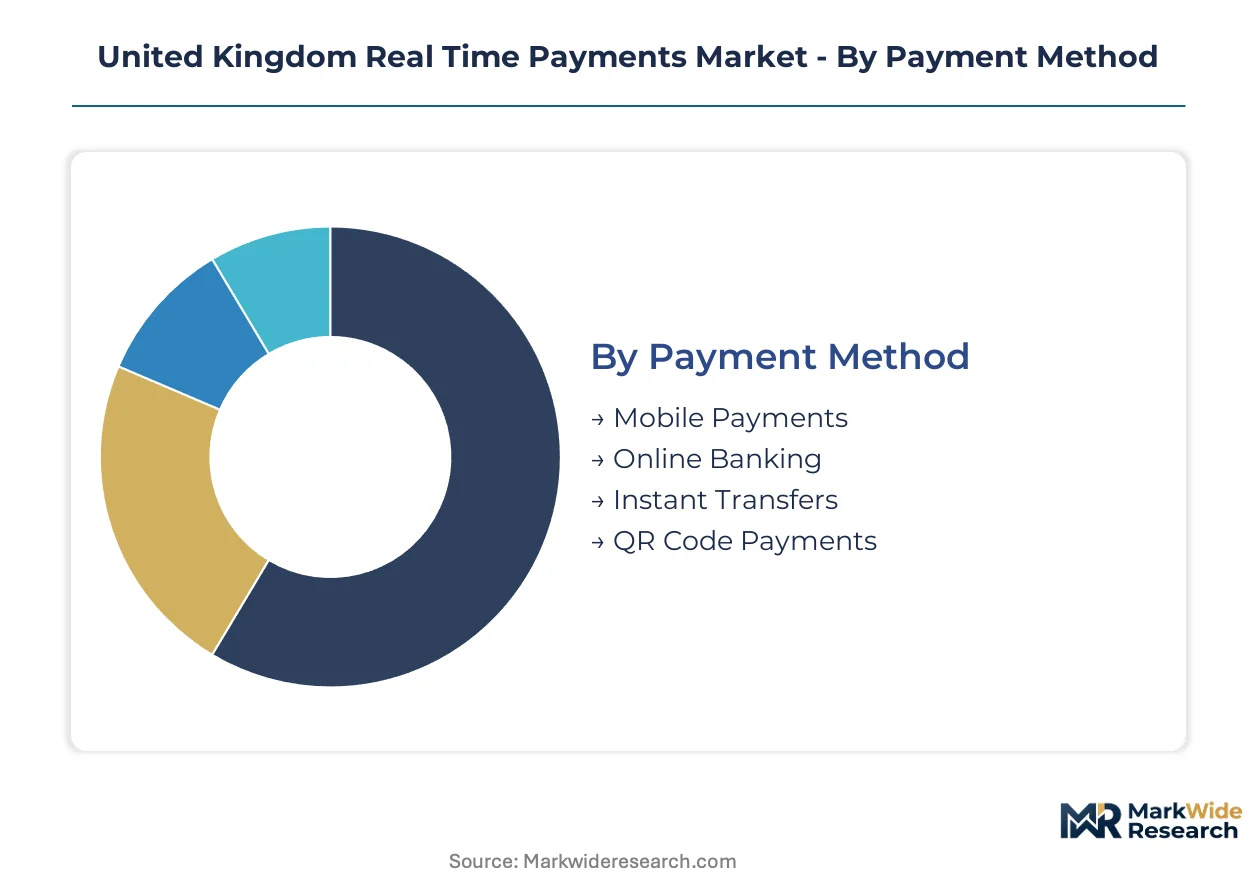
The United Kingdom Real Time Payments Market fragments across four critical dimensions that determine integration architecture and commercial viability. Payment method and technology type dictate infrastructure requirements, while user segment and transaction volume shape risk frameworks and pricing models.
Payment Method:
Integration depth varies sharply across payment methods, with some operating as standalone consumer interfaces and others embedded within broader banking workflows.
- Mobile Payments:Smartphone-initiated settlements leverage biometric authentication and tokenized credentials for in-store and remote transactions. London's retail corridor and Manchester's e-commerce clusters drive concentration as merchants prioritize instant fund availability over traditional card settlement cycles.
- Instant Transfers:Bank-account-to-bank-account rails settle via Faster Payments Service infrastructure within seconds, eliminating intermediary hold periods. Corporate treasuries in Birmingham and Edinburgh exploit these rails for supplier payments where working capital velocity outweighs cost considerations.
- Online Banking:Web-interface transfers initiated through traditional bank portals serve legacy customer segments with lower smartphone penetration. Building societies and regional banks maintain these channels for rural demographics across Wales and Northern England.
- QR Code Payments:Scannable codes bridge physical and digital commerce, requiring merchant-side display infrastructure and consumer-side banking app compatibility. Adoption concentrates among small traders in London's street markets where card terminal costs prove prohibitive.
Mobile Payments leads volumes today; QR Code Payments is gaining share fastest.
User Segment:
Cost-to-serve differentials across user segments force providers to tier their infrastructure investments and support models.
- Retail Consumers:Individual users initiating peer-to-peer transfers and personal purchases through banking apps. Challenger banks in London's fintech corridor compete aggressively for this segment through zero-fee instant transfers and spending analytics.
- Corporates:Large enterprises requiring treasury automation, batch processing, and ISO 20022 data enrichment for reconciliation. Demand clusters among FTSE-listed firms seeking to eliminate float periods in supplier payment programs.
- Small Businesses:Mid-market merchants and professional services firms needing simple instant settlement without enterprise complexity. Underpenetrated opportunities persist in Leeds and Glasgow where legacy banking relationships delay adoption.
- Financial Institutions:Banks and payment service providers accessing settlement rails for their own customer propositions. The Payment Systems Regulator's access rules determine which non-bank entities qualify for direct Faster Payments Service connectivity.
Retail Consumers dominates transaction counts; Corporates delivers the highest revenue per transaction.
Technology Type:
Margin pools concentrate unevenly across technology types, with infrastructure enablers capturing value differently than front-end application providers.
- API Integration:Programmatic interfaces connecting fintech applications to bank settlement rails, enabling modular service composition. The Competition and Markets Authority's Open Banking mandate forces tier-one banks to maintain these gateways, lowering barriers for challenger entrants.
- Open Banking:Regulatory framework and technical standards permitting third-party access to account data and payment initiation. Variable recurring payments represent the emerging use case, with utility and insurance providers piloting subscription alternatives to direct debit.
- NFC:Near-field communication enabling contactless tap-to-pay at physical terminals. Deployment requires merchant hardware upgrades, limiting penetration among sole traders compared to mobile QR alternatives.
- Blockchain:Distributed ledger infrastructure for settlement finality without central clearing, currently marginal in UK retail payments. Regulatory uncertainty from the Financial Conduct Authority constrains institutional deployment beyond pilot programs.
API Integration anchors current infrastructure spending; Open Banking is climbing the fastest as regulatory deadlines mature.
Transaction Volume:
Application context determines which volume bands attract provider investment and regulatory scrutiny.
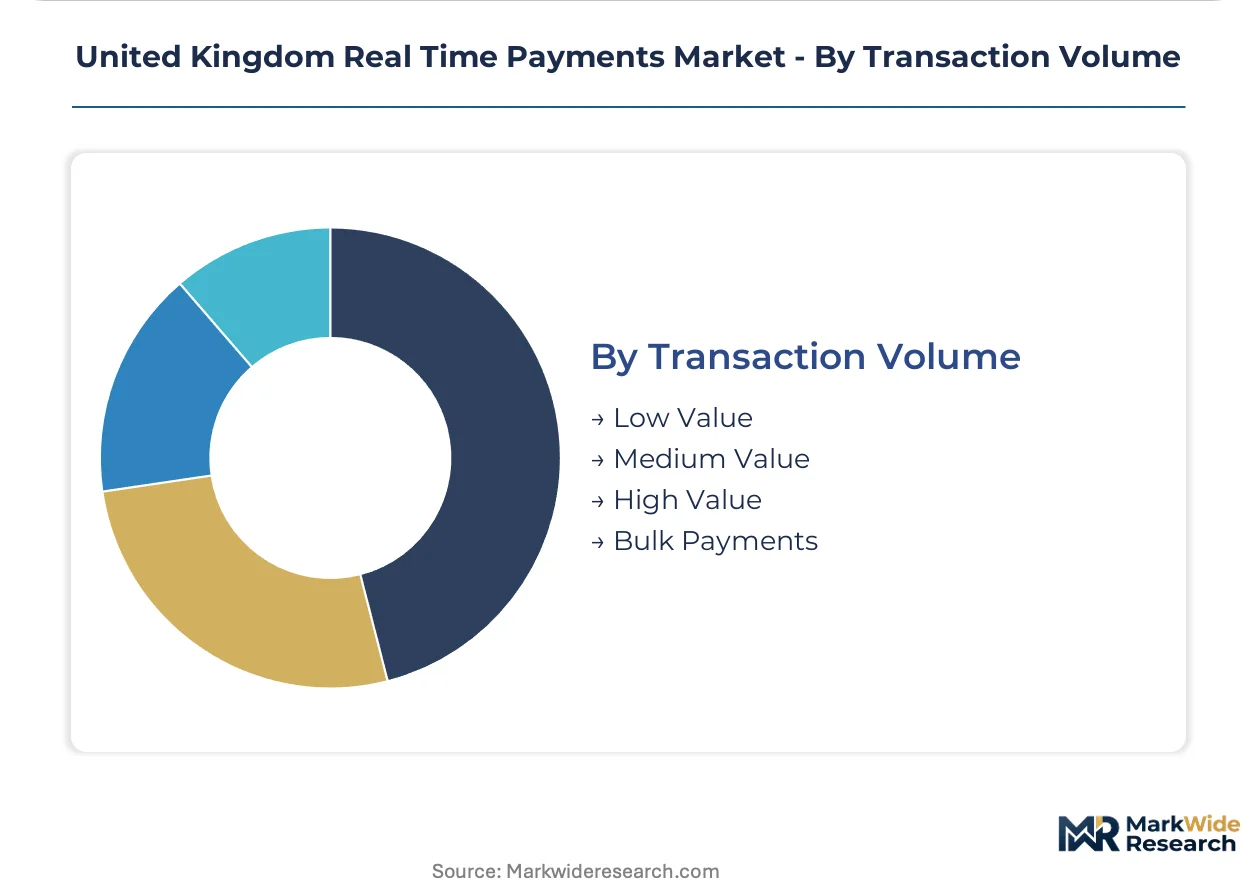
- Low Value:Transfers under £10,000 settling through standard Faster Payments Service limits with minimal screening friction. Retail peer-to-peer and small merchant payments dominate this band across all UK regions.
- High Value:Large corporate settlements requiring enhanced authentication and sanctions screening, often leveraging CHAPS for same-day high-value clearing. Financial institutions in the City of London prioritize these rails for interbank and wholesale transactions.
- Medium Value:Mid-tier B2B payments where Faster Payments Service limits suffice but fraud controls intensify. Regional corporate centers in Bristol and Edinburgh show rising adoption as real-time becomes default expectation.
- Bulk Payments:High-frequency batch files for payroll and supplier runs, requiring file-based submission rather than individual API calls. Mid-market enterprises in Birmingham and Manchester represent the conversion opportunity from BACS three-day cycles.
Low Value processes the highest transaction volumes; Bulk Payments shows the steepest expansion trajectory as BACS displacement accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United Kingdom pioneered real-time retail payments through the Faster Payments Service launch in 2008, establishing the foundational infrastructure that European and Asian markets subsequently emulated. This historical lineage positioned British regulators and private operators as architects of instant settlement standards now spreading globally.
London and the Southeast
London's financial technology corridor concentrates challenger bank headquarters and payment processor engineering centers where regulatory sandbox access accelerates product iteration. The Financial Conduct Authority's controlled testing environment enables direct Faster Payments Service connectivity for qualified fintech applicants. Canary Wharf and Shoreditch clusters host API-first banking operations that exploit Open Banking mandates for real-time settlement product development.
The Midlands
Birmingham and Manchester corporate centers drive B2B real-time adoption among mid-market enterprises seeking to displace BACS three-day payment cycles. Regional banking relationships at legacy institutions delay conversion, creating underpenetrated opportunities for treasury automation providers. The Payment Systems Regulator's access rules determine which non-bank entities qualify for direct infrastructure connectivity in these secondary commercial hubs.
Scotland
Edinburgh's fund management and insurance sectors generate institutional demand for high-value real-time clearing through CHAPS and wholesale Faster Payments Service channels. Scottish corporate treasuries prioritize settlement finality and rich ISO 20022 data for reconciliation automation. The Bank of England's RTGS system serves as the ultimate settlement anchor for these wholesale transactions.
Wales and Northern England
Building societies and regional banks maintain online banking portals for demographics with lower smartphone penetration across rural Wales and Northern England. QR code payment adoption concentrates among small traders in street markets where card terminal costs prove prohibitive. The Competition and Markets Authority's Open Banking mandate forces tier-one institutions to maintain API gateways that challenger entrants exploit.
United Kingdom Real Time Payments Market Competitive Landscape
Capital-heavy infrastructure operators compete with asset-light application developers for margin capture across the UK real-time payment stack. The market structure concentrates around three strategic archetypes: incumbent network operators controlling core settlement rails, challenger digital banks owning consumer interfaces, and technology vendors licensing connectivity software to intermediaries. Dominant competitive moves include API gateway expansion to capture fintech integration revenue and strategic partnerships between retail banks and merchant acquirers to defend transaction volume.
Within the infrastructure tier, Mastercard leverages its Vocalink acquisition to anchor retail bank connectivity across the Faster Payments Service. Revolut and Starling Bank occupy the challenger digital bank vector, with the former competing through multi-currency instant transfers and the latter differentiating via API-first developer access to settlement rails. These three entities exemplify how regulatory-mandated interoperability creates competitive entry points against legacy institutions.
| Leading Market Players |
|---|
| Mastercard (Vocalink) |
| Revolut |
| ACI Worldwide |
| Starling Bank |
| Monzo |
| Fiserv |
| Visa |
| Worldpay |
| PayPal |
| Others |
Value Network & Pricing Analysis
API-first infrastructure deployment is compressing both development costs and vendor concentration across the UK payment stack, enabling modular service unbundling that fragments margin capture away from legacy core banking providers. Cloud-native platform adoption simultaneously reduces capital barriers for challengers while concentrating compute supply among hyperscale providers, reshaping how payment processors negotiate infrastructure economics.
Pricing Analysis
Per-transaction SaaS tiering dominates UK real-time payment economics, with infrastructure providers segmenting access fees by volume scale and API call frequency. Price differentiation hinges on ISO 20022 data enrichment levels and settlement speed guarantees, with premium tiers offering sub-second confirmation. Cost compression in the mid-market tier intensifies as challenger banks absorb transaction fees to acquire retail depositors. Small businesses show highest price sensitivity, while corporate treasuries prioritize reconciliation automation over unit cost.
Supply Chain Analysis
Core banking software supply rests on US and Irish enterprise vendors, with cloud infrastructure drawing from hyperscale facilities in London, Frankfurt, and Dublin. Critical dependencies include real-time fraud detection engines, tokenization vaults, and ISO 20022 messaging libraries. Single-source vulnerability concentrates in the Bank of England's RTGS settlement anchor, where operational disruption would cascade through all private rails. Distribution runs through direct API licensing to fintech developers and indirect channel partnerships with tier-one banks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK real-time payments market functions as a regulatory compounder, where the Financial Conduct Authority's Consumer Duty mandate continuously elevates product design standards that incumbents must fund while challengers exploit. This dynamic sustains structural opportunities for well-capitalized entrants.
For Market Incumbents: Deploy API gateway monetization to capture fintech integration revenue streams before Open Banking access rules commoditize connectivity. Consolidate developer tooling investments to defend against Starling Bank's API-first developer access model, which threatens to disintermediate traditional bank-fintech relationships. The Payment Systems Regulator's evolving reimbursement rules represent the critical regulatory shift requiring proactive fraud liability reserves. For New Entrants and Emerging Players: Building society partnerships offer the most penetrable channel for reaching underbanked demographics across Wales and Northern England, where smartphone penetration lags London benchmarks. Target SME treasury automation in Birmingham and Manchester, where BACS displacement creates immediate working capital value propositions. A white-label API embedding strategy with regional accounting software vendors accelerates merchant acquisition without direct consumer marketing spend. For Investors and Strategic Acquirers: Valuations sit cheapest among infrastructure software vendors serving tier-two banks, where Open Banking compliance deadlines force accelerated procurement. Long-term viability centers on owning the connectivity layer between legacy core systems and real-time rails, a position insulated from front-end consumer application churn. The signal to watch is central bank digital currency consultation outcomes, which would recalibrate competitive boundaries between private and public settlement infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| API Gateway Expansion | Captures fintech integration revenue as Open Banking mandates proliferate connectivity demand. |
| Cloud-Native Core Migration | Eliminates datacenter capital burdens that constrain challenger bank margin structures against incumbents. |
| ISO 20022 Data Enrichment | Enables automated corporate reconciliation that justifies premium pricing for treasury automation tiers. |
| Variable Recurring Payments Pilot | Opens subscription billing revenue pools for utility providers seeking direct debit alternatives. |
| Real-Time Fraud Detection Investment | Addresses Payment Systems Regulator reimbursement rules while reducing liability exposure. |
Research Methodology
Multiple input streams — payment processor executives, regulatory affairs leads at challenger banks, Faster Payments Service infrastructure operators, and merchant acquirer product managers — were reconciled against secondary validation from Financial Conduct Authority policy filings, Payment Systems Regulator market reviews, Pay.UK infrastructure disclosures, and Bank of England RTGS consultation documents. Bottom-up transaction volume modeling and top-down market sizing triangulation anchored value estimates.
Data-stream reconciliation across payment method, user segment, technology type, and transaction volume dimensions structured the analytical framework over the projection horizon. CAGRs derived from historical adoption velocity curves adjusted for regulatory milestone impacts, with specific weighting applied to Open Banking API penetration rates and SME BACS displacement trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to central bank digital currency policy resolution and core banking system replacement cycles at traditional institutions. A small set of named triggers — Consumer Duty enforcement intensity, PSR access rule revisions, and RTGS modernization timelines — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Electronic Payment System for Transportation Market
Payments
3D Secure Payment Authentication Market
Payments
Global Bitcoin Payments Ecosystem Market
Payments
Sweden Mobile Payments Market
Payments
APAC Mobile Payments Market
Payments
Middle East & North Africa Digital Payments Market
Payments
Middle East Gift Card and Incentive Card Market
Payments
Global Accounts Payable Automation Market
Payments
US Gift Card and Incentive Card Market
Payments
B2B Payments Market
Payments
Global Telecom Billing Market
Payments
Saudi Arabia Payments Market
Payments
Europe Virtual Cards Market
Payments
Convergent Billing Market
Payments
Fuel and Convenience Store POS Market
Payments
Digital Payment in Healthcare Market