
 Mobile POS Market | 2026-2036
Mobile POS Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile POS Market Insights
Asian contract manufacturers of payment terminals is broadening output capacity for NFC-enabled devices. Square leverages its dual hardware-software ecosystem to dominate the North American small merchant segment. Toast POS anchors its position through restaurant-specific workflow integration, while SumUp competes aggressively on compact, low-cost European hardware.
Mobile POS denotes a portable electronic system combining card readers, tablets or smartphones, and cloud-connected software to process transactions outside fixed checkout locations. These systems typically integrate EMV chip compliance, end-to-end encryption, and API connectivity to inventory or accounting platforms. Cloud-based deployment captures the fastest expansion as merchants prioritize remote management and automatic security patches over on-premises server maintenance. NFC payment method volume is accelerating fastest among contactless methods, though credit card rails still occupy the largest transaction value pool across all end user categories.
FDA oversight does not extend to payment hardware, but FCC certification governs wireless communication modules in US-sold devices, while PCI DSS mandates shape encryption and tokenization requirements for all vendors processing card data. GDPR in Europe and analogous state privacy laws in California constrain how transaction data is stored and shared, forcing architecture redesigns for cross-border operators. Stakeholders must monitor evolving central bank digital currency pilots and real-time payment network integrations that could displace traditional card-acquiring economics.
Market Dynamics
Tablet-based checkout adoption by restaurants and food service operators is compressing hardware refresh cycles and forcing incumbent vendors to re-architect their software stacks for cloud-native deployment. This demand compression is reshaping how payment terminal manufacturers allocate R&D across form factors.
Growth Catalysts
- NFC Infrastructure Mandates:United States merchants upgrading contactless payment terminals to meet PCI DSS compliance deadlines are pulling forward replacement demand. Small and mid-sized operators prioritize integrated inventory management alongside payment acceptance.
- Cloud Deployment Preference:Remote management capabilities and automatic security patches are displacing on-premises server maintenance as the dominant deployment architecture. Merchants value reduced IT overhead and faster feature rollouts.
- GDPR:European transaction data storage constraints are forcing architecture redesigns that incidentally improve cross-border operational flexibility for multinational operators.
Market Restraints
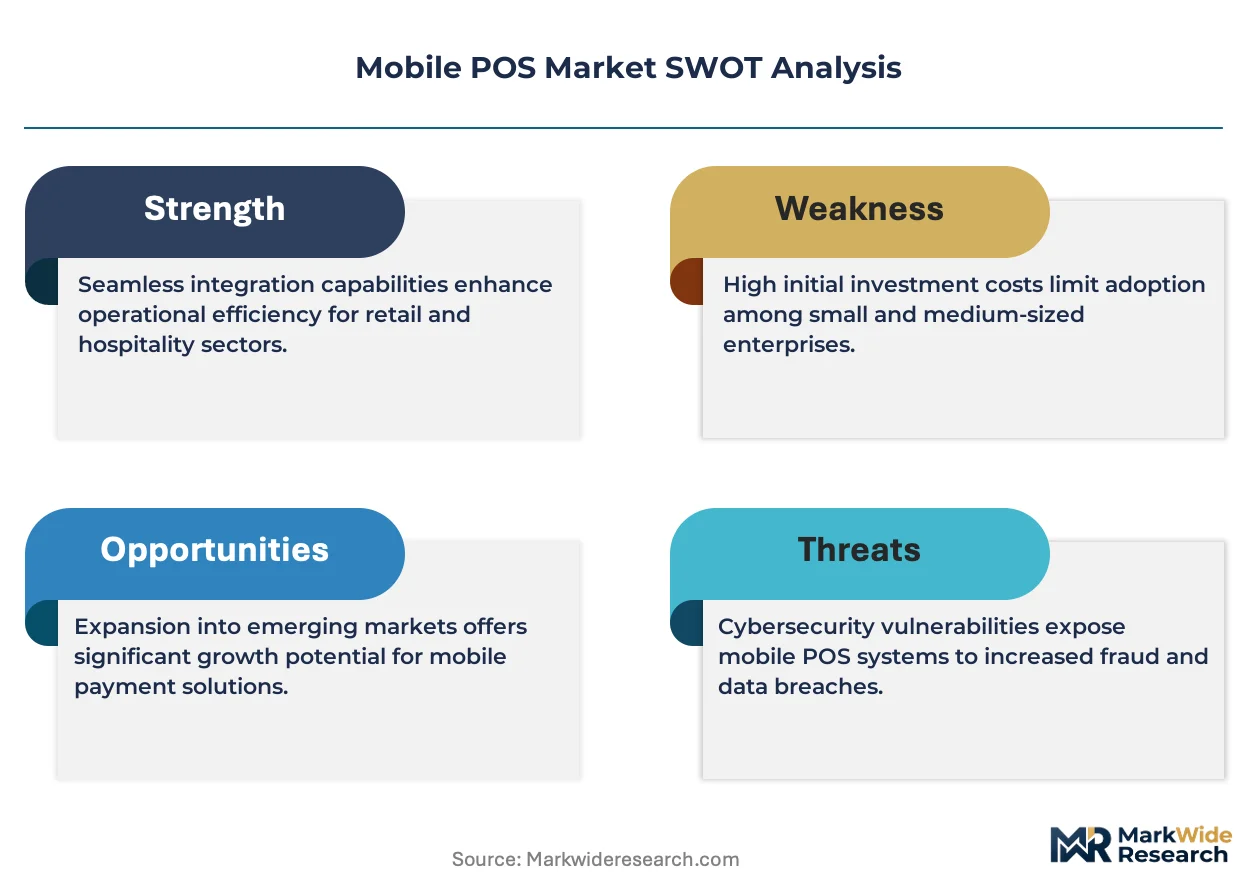
- EMV Certification Timelines:Lengthy laboratory validation periods for chip compliance create working capital strain for hardware startups. Certification bottlenecks delay product launches by quarters.
- Asian Contract Manufacturer Concentration:NFC-enabled device production clusters in Taiwan and mainland China expose vendors to geopolitical shipping disruptions and component allocation constraints.
- Central Bank Digital Currency Pilots:Experimental real-time payment networks in multiple jurisdictions threaten to displace traditional card-acquiring economics before terminal depreciation cycles complete.
Strategic Opportunities
- Underpenetrated Independent Retail:United States Main Street merchants still rely on cash or basic card readers. Integrated POS-loyalty-inventory bundles capture wallet share from fragmented software stacks.
- API-First Architecture:Convergence between payment processing and accounting platform connectivity enables subscription revenue models. Developers build vertical-specific workflows on open payment infrastructure.
- State Privacy Law Tailwinds:California Consumer Privacy Act analogues spreading across United States jurisdictions create compliance-driven upgrade cycles. Vendors with pre-built data residency architectures capture switching merchants.
Industry Challenges
- Embedded Systems Security Talent:Shortage of firmware engineers with end-to-end encryption expertise slows product development. Compensation inflation in cybersecurity functions compresses R&D budgets.
- Legacy POS Integration Complexity:Kitchen display systems and property management software at established restaurant chains resist API connectivity. Custom integration work erodes margin on enterprise deals.
- FCC Certification Friction:Wireless communication module approvals for United States market entry require specialized regulatory counsel. Smaller hardware vendors lack in-house electromagnetic compliance expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile POS Market |
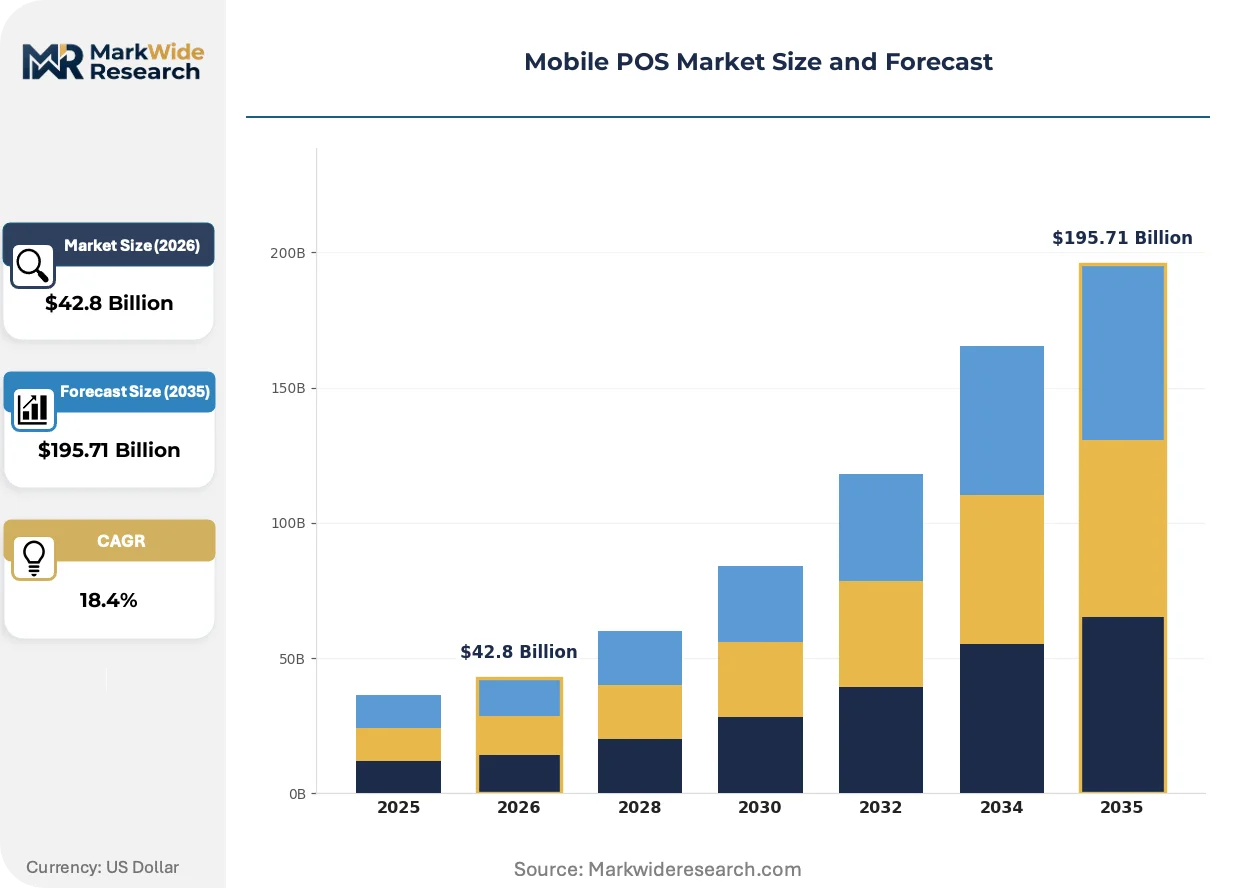
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $195.71 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Accessories, Services End User: Retailers, Restaurants, Hospitality, Events Deployment: Cloud-based, On-premises, Hybrid, Mobile Payment Method: Credit Card, Debit Card, NFC, Others |
| Companies Covered | Lightspeed Retail, Rezku, Square, SumUp, PayPal Zettle, Toast POS, Clover, Loyverse, Shopify POS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile POS Market Trends and Innovations
Software-defined payment terminals are absorbing functionality from adjacent merchant services, collapsing what were separate hardware categories into unified edge devices. This convergence is compressing vendor differentiation and elevating platform ecosystem scale as the primary competitive variable.
SoftPOS technology is absorbing smartphone and tablet processors into certified payment acceptance devices without dedicated hardware. Mid-market restaurant chains in the United States are piloting merchant-owned device deployments to reduce per-terminal lease costs. This absorption is compressing addressable market for traditional countertop terminal manufacturers and forcing them toward software subscription models.
GDPR and its United States state-level analogues are mandating data minimization and purpose limitation for transaction records. Payment processors must re-engineer data pipelines to enable merchant-specific retention policies and cross-border transfer safeguards. European operators and California-headquartered platforms face the steepest compliance architecture costs, while vendors with pre-positioned privacy-by-design systems capture competitive advantage in RFP processes.
Merchant procurement of payment infrastructure is consolidating around integrated platform decisions rather than best-of-breed hardware selection. Small United States retailers and food service operators increasingly bundle POS, payroll, and inventory through single-vendor relationships. This preference compression disadvantages standalone terminal manufacturers and rewards ecosystem players with adjacent software attach rates.
Mobile POS Market Segmentation
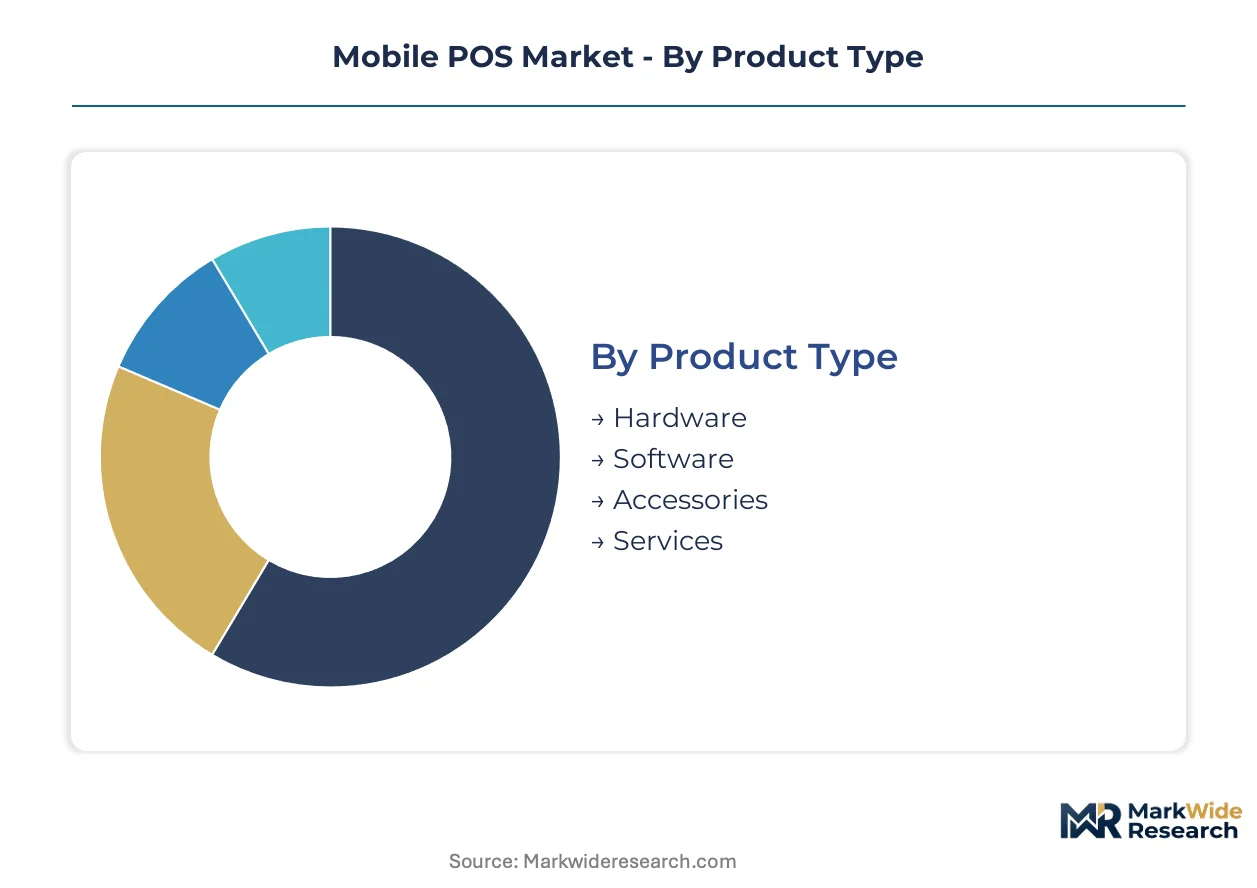
Mobile POS procurement patterns diverge sharply across merchant scale and operational complexity. Understanding how hardware preferences, deployment architectures, and payment modality demands fragment by buyer type reveals where vendor R&D investments generate the highest returns.
Product Type:
Hardware investments dominate upfront procurement decisions, while software attach rates determine lifetime customer value.
- Hardware:Card readers, tablets, and dedicated terminals with EMV chip compliance and end-to-end encryption form the foundational purchase. United States small and mid-sized merchants prioritize integrated inventory management alongside payment acceptance, compressing standalone terminal demand.
- Software:Cloud-connected platforms enable remote management, automatic security patches, and API connectivity to accounting systems. Restaurant operators in North America favor tablet-based checkout with kitchen display system integration, forcing vendors toward vertical-specific workflow modules.
- Accessories:Receipt printers, cash drawers, and barcode scanners complete physical checkout stations. Compact, low-cost European hardware configurations influence accessory bundling strategies for cost-sensitive independents.
- Services:Installation, training, and ongoing technical support reduce merchant IT overhead. PCI DSS compliance consulting and tokenization implementation attract premium pricing from security-conscious operators.
Volume sits with Hardware; growth tilts toward Software.
End User:
Operational workflow complexity separates buyers with specialized integration needs from those seeking plug-and-play simplicity.
- Retailers:Inventory synchronization demands dominate procurement criteria. United States Main Street merchants still rely on cash or basic card readers, creating wallet share capture opportunities for integrated POS-loyalty-inventory bundles.
- Restaurants:Kitchen display systems and tableside ordering workflows require purpose-built software stacks. Toast POS anchors market position through restaurant-specific integration, while tablet-based adoption compresses hardware refresh cycles industry-wide.
- Hospitality:Property management software connectivity and multi-location reporting drive enterprise decisions. Custom integration work erodes margin on deals with established chains resisting API connectivity.
- Events:Temporary deployment scenarios prioritize rapid setup and offline transaction capability. Mid-market restaurant chains pilot merchant-owned device deployments to reduce per-terminal lease costs in seasonal operations.
Restaurants command the largest transaction value pool; Events show the steepest expansion trajectory.
Deployment:
IT resource availability and security risk tolerance shape architecture selection across merchant tiers.
- Cloud-based:Remote management capabilities and automatic security patches displace on-premises maintenance. GDPR and United States state privacy law analogues mandate data minimization, forcing architecture redesigns that improve cross-border operational flexibility.
- On-premises:Legacy server maintenance persists among established operators with sunk infrastructure investments. FCC certification requirements for wireless modules create friction for smaller hardware vendors lacking in-house electromagnetic compliance expertise.
- Hybrid:Local transaction processing with cloud backup balances latency sensitivity with centralized analytics. Embedded systems security talent shortages slow product development for firmware with end-to-end encryption.
- Mobile:SoftPOS technology absorbs smartphone and tablet processors into certified payment acceptance without dedicated hardware. This absorption compresses addressable market for traditional countertop terminal manufacturers.
Cloud-based deployments anchor current volume; Mobile architectures gain share fastest.
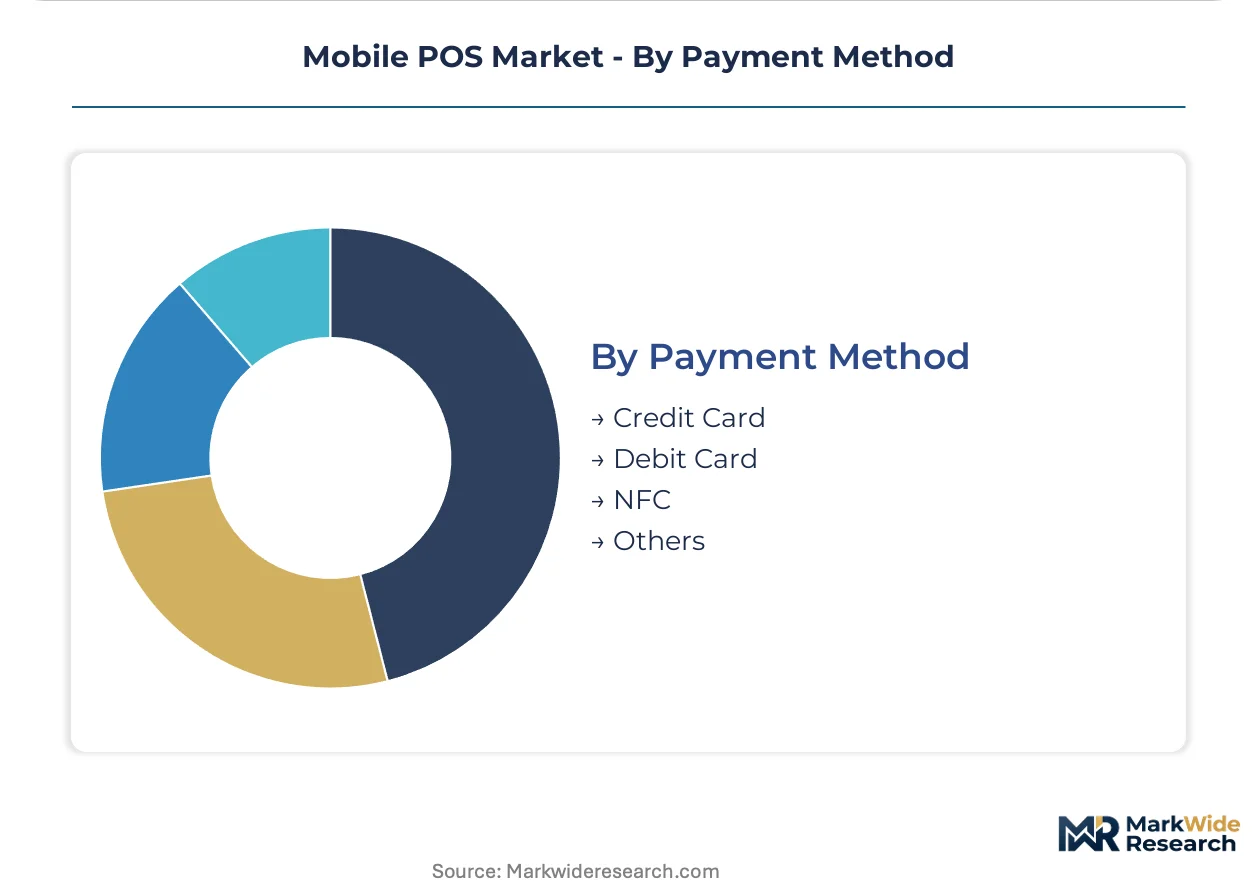
Payment Method:
Consumer preference shifts and regulatory mandates accelerate infrastructure replacement timelines.
- Credit Card:Traditional rails still occupy the largest transaction value pool across all end user categories. PCI DSS compliance deadlines pull forward replacement demand among United States merchants upgrading contactless terminals.
- Debit Card:Lower interchange rates attract cost-conscious independents with thin margins. Real-time payment network pilots threaten to displace traditional card-acquiring economics before terminal depreciation cycles complete.
- NFC:Contactless volume accelerates fastest among payment methods. Asian contract manufacturers in Taiwan and mainland China are broadening output capacity for NFC-enabled devices, exposing vendors to geopolitical shipping disruptions.
- Others:QR codes and emerging central bank digital currency experiments occupy experimental niches. California Consumer Privacy Act analogues spreading across United States jurisdictions create compliance-driven upgrade cycles for data residency architectures.
Credit Card rails dominate transaction value; NFC climbs the fastest among contactless methods.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley anchors cloud software development for tablet-based checkout systems, while Shenzhen dominates NFC-enabled terminal manufacturing. Merchant procurement patterns fragment sharply across regulatory jurisdictions and payment infrastructure maturity.
United States
Small and mid-sized merchants drive integrated payment and inventory management procurement. FCC certification governs wireless communication modules in US-sold devices, creating friction for smaller hardware vendors lacking in-house electromagnetic compliance expertise. The San Francisco Bay Area concentrates cloud-native POS platform development.
Germany
GDPR mandates reshape how transaction data is stored and shared, forcing architecture redesigns for cross-border operators. The country's federal data protection authority enforces purpose limitation requirements for payment processors. Berlin hosts multiple SoftPOS technology developers targeting merchant-owned device deployments.
China
MIIT standards govern wireless payment terminal specifications alongside GB certification requirements for electromagnetic compatibility. Shenzhen and Dongguan manufacturing clusters broaden output capacity for NFC-enabled devices, exposing vendors to component allocation constraints and shipping disruptions.
United Kingdom
Restaurant operators accelerate tablet-based checkout adoption, compressing hardware refresh cycles. The Financial Conduct Authority oversees payment services regulation while Information Commissioner's Office enforces UK GDPR analogues. London's fintech corridor anchors European headquarters for several cloud POS platforms.
India
RBI guidelines on payment aggregators and digital lending shape merchant onboarding requirements. The country's national payments corporation operates the UPI real-time payment network threatening traditional card-acquiring economics. Bengaluru concentrates API-first payment infrastructure startups targeting underpenetrated independent retail.
Mobile POS Market Competitive Landscape
Global majors compete with regional champions across cloud-native deployment architectures and vertical-specific workflow integration. The vendor base stratifies into three tiers: ecosystem players with adjacent software attach rates, hardware specialists competing on compact form factors, and API-first platforms enabling developer-built vertical workflows. Consolidation pressure intensifies as merchant procurement shifts from best-of-breed hardware selection toward integrated platform decisions. Dominant competitive moves include strategic partnerships with accounting platform providers and geographic expansion through compliance pre-positioning.
Within the ecosystem tier, Square and Toast POS exemplify divergent specialization strategies. Square leverages its dual hardware-software foundation across North American small merchants, while Toast POS anchors restaurant-specific workflow integration. SumUp occupies a position among compact hardware specialists competing aggressively on European cost structures. These three represent the archetype spectrum from horizontal platform scale to vertical depth to hardware minimalism.
| Leading Market Players |
|---|
| Lightspeed Retail |
| Rezku |
| Square |
| SumUp |
| PayPal Zettle |
| Toast POS |
| Clover |
| Loyverse |
| Shopify POS |
| Others |
Pricing and Supply Chain Analysis
Captive integration of payment hardware manufacturing by cloud software vendors anchors both supply security and pricing power in the Mobile POS Market. Square and Toast POS control their own device ecosystems, insulating margin structures from Asian contract manufacturer pricing volatility while forcing standalone terminal vendors toward software subscription models.
Pricing Analysis
Warranty and PCI DSS compliance consulting bundled into enterprise contracts separate premium-tier hardware-software packages from unbundled entry-level card readers. Three-tier pricing structure across premium, standard, and economy levels reflects EMV certification grade and kitchen display system integration depth. Cost compression in the compact hardware segment intensifies because SumUp and European competitors compete aggressively on device cost. Small United States Main Street merchants exhibit highest price sensitivity, while multi-location restaurant chains prioritize workflow integration over per-terminal cost.
Supply Chain Analysis
Ocean freight cost volatility from Taiwan and mainland China manufacturing clusters shapes working capital requirements for NFC-enabled device procurement. Taiwan Semiconductor Manufacturing Company and mainland China EMS providers feed from ARM-based processors and EMV-certified secure elements. Single-source vulnerability concentrates in Taiwan's semiconductor packaging capacity for payment terminal chipsets. Distribution runs through value-added resellers and direct-to-merchant e-commerce channels, with enterprise hospitality deals employing specialized systems integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Mobile POS Market sits in a technology-transition phase where SoftPOS absorption of smartphone processors displaces dedicated terminal demand. Cloud-native deployment architectures are replacing legacy on-premises server maintenance as the dominant merchant preference.
For Market Incumbents: Extend vertical software attach rates through payroll and inventory module integration to defend against standalone terminal commoditization. Toast POS demonstrates restaurant-specific workflow depth as a defensible moat. Capacity addition in United States cloud infrastructure regions reduces latency for tablet-based checkout systems. PCI DSS certification investment maintains enterprise deal access against emerging API-first competitors.
For New Entrants and Emerging Players: Independent retail merchants in United States secondary metros represent the most penetrable segment, with cash-dependent Main Street operators lacking integrated POS-loyalty-inventory bundles. California-headquartered platforms face steepest CCPA compliance architecture costs, creating white-space for privacy-by-design entrants. Developer channel partnerships enable rapid vertical workflow deployment without direct sales infrastructure.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by adjacent software platforms seeking payment infrastructure integration. Long-term viability favors ecosystem players with recurring SaaS revenue over hardware-dependent vendors facing terminal demand compression. Embedded systems security talent scarcity signals inflection when firmware engineering compensation inflation forces R&D budget restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Enables developer-built vertical workflows on open payment infrastructure with accounting connectivity. |
| SoftPOS Technology Deployment | Absorbs smartphone processors into certified payment acceptance without dedicated hardware investment. |
| Privacy-by-Design Architecture | Captures switching merchants as CCPA analogues spread across United States jurisdictions. |
| Restaurant-Specific Workflow Modules | Kitchen display system integration anchors competitive position against horizontal platform competitors. |
| Geographic Compliance Pre-Positioning | GDPR-aligned data residency architectures enable European expansion without architecture redesign. |
Research Methodology
Document review covered PCI DSS compliance documentation, FCC certification filings, and EMVCo specification releases, complemented by interviews with payment platform CTOs, restaurant chain IT procurement officers, and independent retail merchant owners. Secondary validation drew from SEC filings of publicly traded POS vendors, customs records for payment terminal imports, and cloud infrastructure capex disclosures. Bottom-up merchant adoption modeling and top-down payment volume aggregation provided cross-check triangulation.
Cross-referencing historical terminal deployment patterns against panel input from systems integrators shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment architecture, merchant scale tier, vertical workflow complexity, payment modality mix, and regional regulatory cluster. CAGRs derived from unit economics modeling of hardware refresh cycles and software attach rate expansion, with NFC infrastructure mandate timelines and central bank digital currency pilot progress as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including geopolitical disruption severity in Taiwan Strait shipping lanes and real-time payment network displacement of card-acquiring economics. Forecasts reflect assumptions about PCI DSS compliance deadline adherence and merchant cloud migration velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Denmark Payments Market
Payments
Smart Home Payments Market
Payments
Smart Bands Payments Market
Payments
China POS Terminals Market
Payments
United States Real Time Payments Market
Payments
Online Charging System (OCS) Market
Payments
Latin America Mobile Payment Market
Payments
India Mobile Payments Market
Payments
Global Accounts Payable (AP) Automation Software Market
Payments
North America POS Terminal Market
Payments
E-Wallet Market
Payments
Saudi Arabia Mobile Payments Market
Payments
Cryptocurrency Payment Apps Market
Payments
Digital Debit Market
Payments
Hong Kong Payments Market
Payments
Smart POS System Market