
 US Gift Card and Incentive Card Market | 2026-2036
US Gift Card and Incentive Card Market Size, Share, and Industry Trends Forecast 2026-2036
US Gift Card and Incentive Card Market Analytics
Plastic substrate is repositioning toward biodegradable and recycled-content polymers as issuers face sustainability mandates. Blackhawk Network leverages its physical retail network to sustain dominance in grocery and convenience store distribution. Amazon.com anchors online gift card velocity through platform-embedded checkout integration. Apple differentiates via Wallet-native card storage that controls the mobile redemption experience.
Gift and incentive cards function as stored-value instruments pre-loaded with fixed or variable monetary amounts, typically encoded with magnetic stripes, EMV chips, or tokenized digital credentials for redemption at designated merchants or card networks. Their primary commercial purpose centers on transferring purchasing power without requiring bank account linkage or credit underwriting. Digital cards within the Product Type dimension are capturing the fastest expansion as real-time delivery replaces physical fulfillment, while Corporate Sales channels in the Distribution Channel dimension concentrate the highest transaction values per activation. Prepaid Cards maintain the largest volume base but face margin compression from interchange fee regulations.
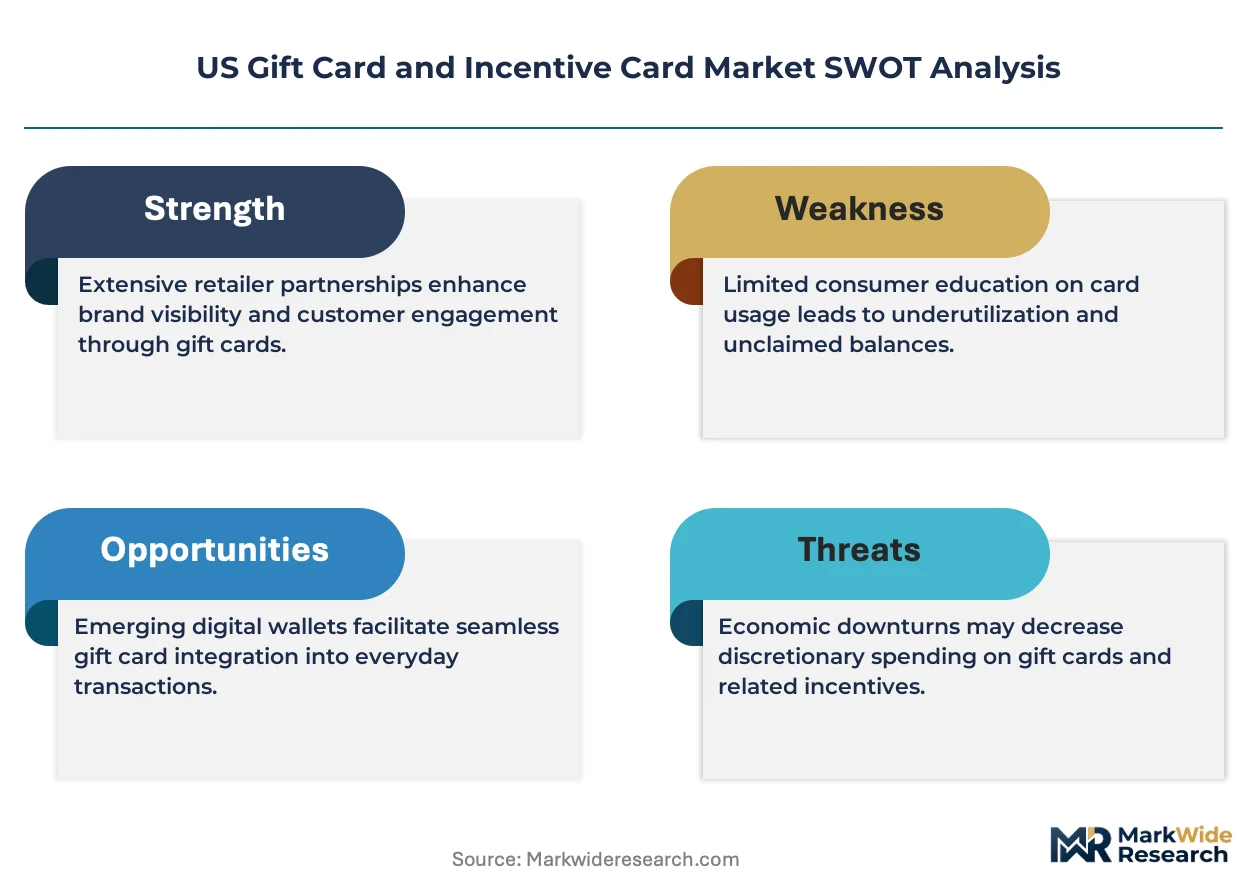
The Consumer Financial Protection Bureau enforces Regulation E protections for prepaid accounts, compelling issuers to maintain fee disclosure standards and liability frameworks. The Federal Reserve's oversight of payment system risk shapes reserve requirements for non-bank card program managers. State-level unclaimed property laws in Delaware, New York, and California create compliance fragmentation for breakage accounting. Stakeholders must monitor how open banking APIs and FedNow instant payment rails alter the competitive boundary between closed-loop merchant cards and network-branded instruments.
Market Dynamics
Digital wallet integration is compressing redemption friction to near-zero, forcing physical card issuers to reposition around tactile gifting rituals and unbanked population access.
Growth Catalysts
- Regulation E Modernization:The Consumer Financial Protection Bureau's expanded prepaid account protections build consumer trust in stored-value instruments. Fee transparency mandates reduce purchase hesitation at retail checkout.
- Corporate HR Automation:Employee recognition platforms embed incentive cards directly into performance management software. Real-time achievement-triggered issuance replaces quarterly bulk distribution.
- Biodegradable Substrate Mandates:California and New York procurement rules favor recycled-content polymers. Issuers sourcing post-consumer rPET capture sustainability-driven B2B contracts.
Market Restraints
- Interchange Fee Compression:The Federal Reserve's Durbin Amendment constraints squeeze network-branded prepaid margins. Program managers face unit economics pressure on low-denomination cards.
- Breakage Accounting Fragmentation:Delaware, New York, and California maintain divergent unclaimed property statutes. Multi-state issuers absorb compliance overhead from conflicting dormancy timelines.
- Digital Substitute Velocity:FedNow instant payment rails enable direct bank-to-bank gifting without card intermediation. Closed-loop merchant cards lose differentiation to real-time P2P transfers.
Strategic Opportunities
- Underpenetrated Rural Corridors:Mississippi and Arkansas exhibit below-average digital wallet penetration. Physical card distribution through grocery cooperatives captures cash-preferred demographics.
- API-Enabled Embedded Finance:Open banking standards allow non-financial platforms to issue branded stored value. Fitness apps and gig economy marketplaces white-label incentive infrastructure.
- State Tax Incentive Programs:Illinois and Georgia offer credits for financial inclusion technology investments. Issuers targeting unbanked populations qualify for offset against compliance costs.
Industry Challenges
- Tokenization Architecture Talent Scarcity:Secure element engineering for mobile wallet integration commands premium compensation. Regional issuers struggle to recruit against fintech compensation benchmarks.
- Legacy Core System Integration:Mainframe-based program management platforms require middleware development for real-time digital issuance. Migration timelines extend 18-24 months for mid-tier issuers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Gift Card and Incentive Card Market |
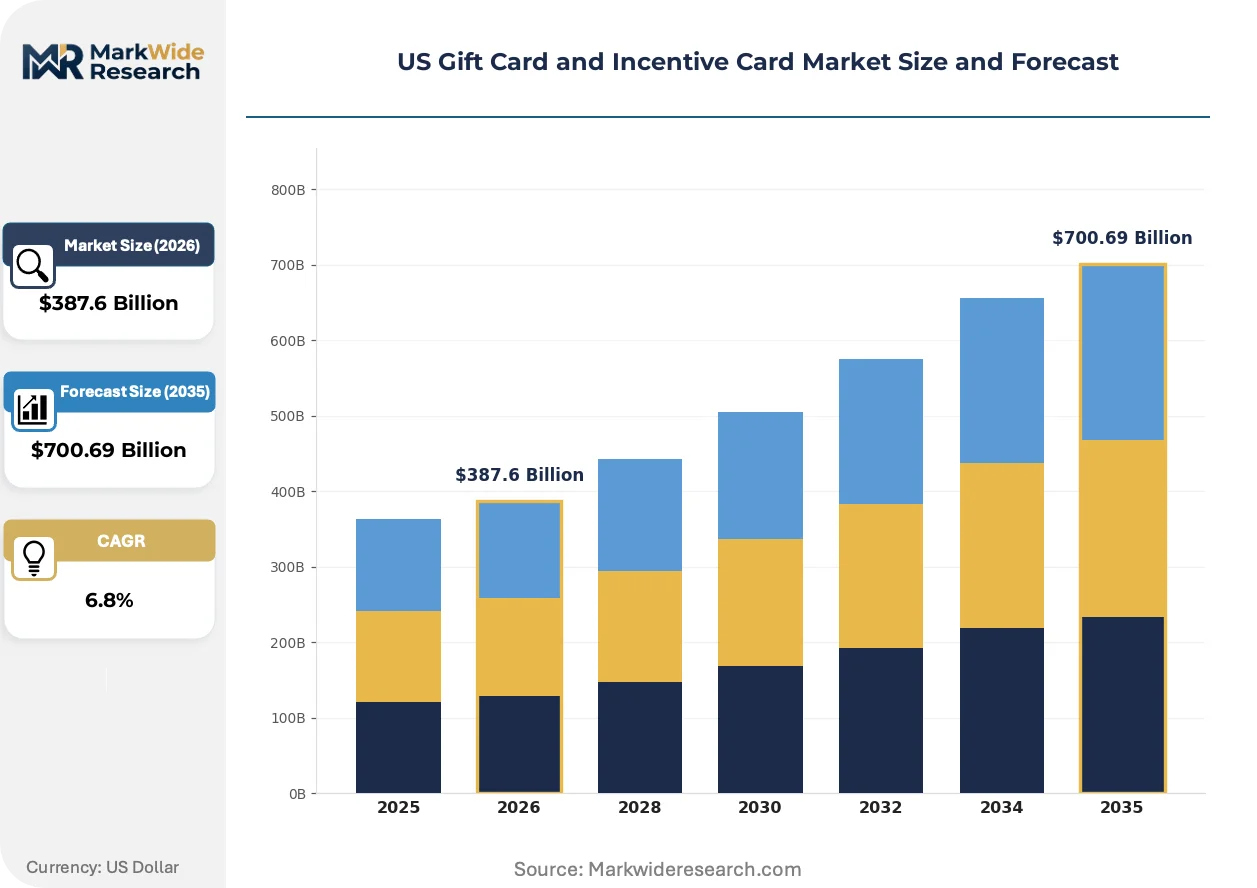
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $700.69 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Physical Cards, Digital Cards, Prepaid Cards, Incentive Cards Distribution Channel: Retail Stores, Online Platforms, Mobile Apps, Corporate Sales Customer Type: Individual Consumers, Businesses, Non-Profits, Government Agencies Usage Purpose: Gifting, Promotions, Employee Rewards, Customer Loyalty |
| Companies Covered | PayPal Holdings, American Express Company, Blackhawk Network, Apple, Amazon.com, InComm Payments, Mastercard, Target Corporation, Fiserv, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Gift Card and Incentive Card Market Evolving Landscape
Real-time delivery infrastructure is collapsing the distinction between purchase intent and redemption capability, compressing traditional fulfillment economics while expanding addressable transaction moments.
Tokenized credential vaulting is unifying gift card, loyalty point, and promotional credit balances into single mobile interfaces. Quick-service restaurant chains and ride-hailing platforms adopt this consolidation fastest, with pilot programs live in Texas and Florida. The technology is unifying previously siloed stored-value pools into fungible purchasing power, threatening standalone gift card apps with disintermediation.
The Consumer Financial Protection Bureau's 2024 prepaid account rule amendments tighten error resolution timelines and liability caps. Issuers must upgrade customer service infrastructure to meet 10-day investigation requirements. Small and mid-sized program managers in the Midwest and Southeast face disproportionate compliance cost burdens relative to transaction scale.
B2B procurement teams now mandate sustainability certifications for employee reward programs. Recycled-content card substrates and carbon-neutral digital delivery options appear in RFP scoring rubrics. This specification shift concentrates contract awards among issuers with verified supply chain documentation, visible most acutely in California corporate headquarters and New York financial services clusters.
US Gift Card and Incentive Card Market Segmentation
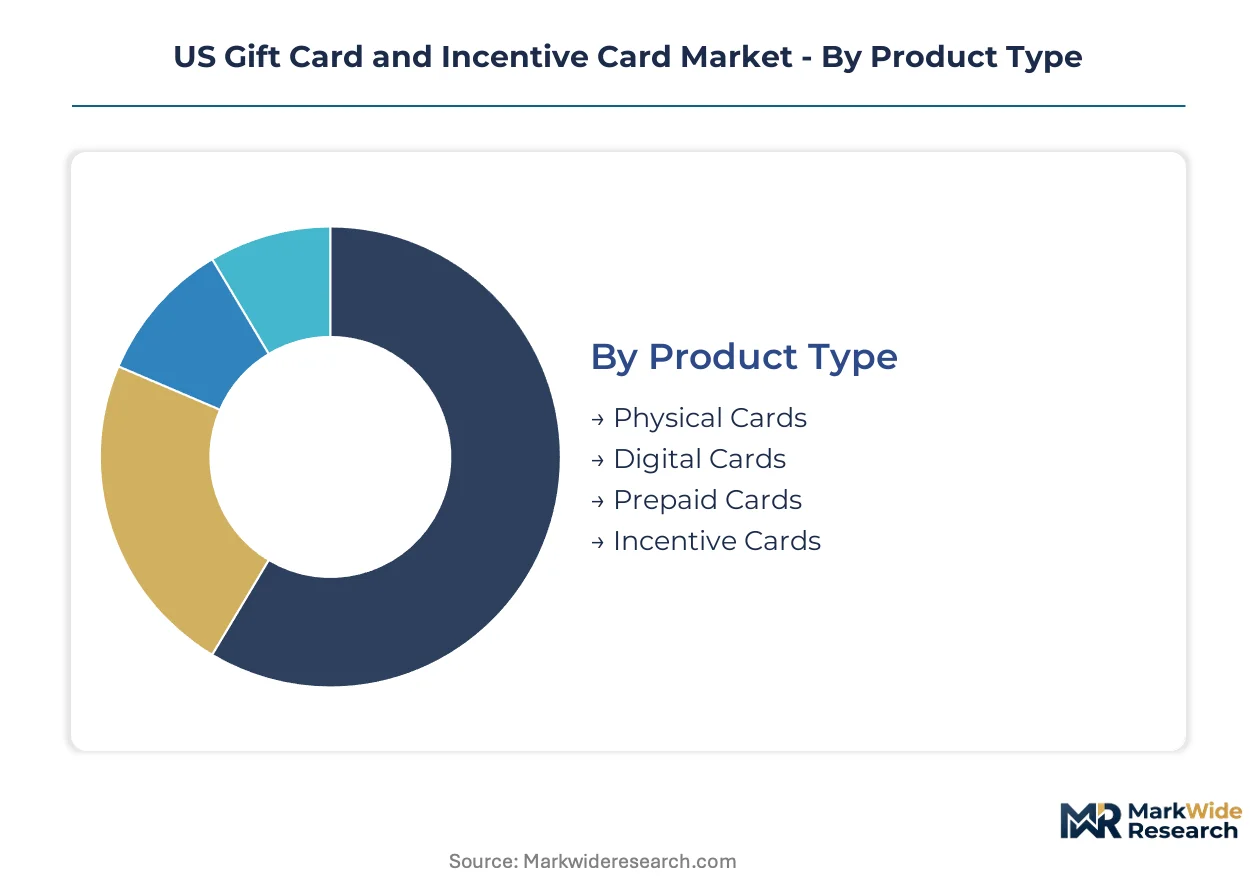
Segmentation in the US gift card and incentive card market reveals how purchasing power flows through distinct technical formats, channel infrastructures, and organizational buyer types. Each dimension carries specific regulatory exposure and margin architecture that shapes issuer strategy.
Product Type:
Buyers differentiate primarily by speed of delivery versus physical permanence, with corporate procurement teams weighing audit trails against employee experience preferences.
- Physical Cards:Magnetic stripe and EMV chip credentials embedded in plastic or biodegradable polymer substrates. Grocery cooperatives in Mississippi and Arkansas maintain strong demand for tactile distribution to cash-preferred demographics facing digital wallet underpenetration.
- Digital Cards:Tokenized credentials delivered via SMS, email, or mobile wallet APIs with real-time activation. California and New York metropolitan corridors concentrate adoption as corporate HR platforms embed instant issuance into performance management software.
- Prepaid Cards:Network-branded stored-value instruments regulated under Federal Reserve oversight with Durbin Amendment interchange constraints.
- Incentive Cards:Closed-loop or open-loop instruments designed specifically for employee recognition and channel partner motivation programs.
Physical cards lead volumes today; digital cards are gaining share fastest.
Distribution Channel:
Channel selection determines compliance burden intensity, with direct corporate contracts carrying the heaviest unclaimed property accounting obligations.
- Retail Stores:Point-of-sale activation through grocery, convenience, and pharmacy networks. Blackhawk Network leverages physical retail density to sustain dominance in card mall displays and checkout lane placement.
- Online Platforms:Direct-to-consumer purchase with email or wallet delivery. Amazon.com anchors velocity through platform-embedded checkout integration that eliminates friction between intent and fulfillment.
- Mobile Apps:Native application issuance with biometric authentication and location-aware redemption.
- Corporate Sales:Direct B2B contracting for bulk employee rewards and customer loyalty programs with custom branding and API integration.
Retail stores maintain the widest reach; corporate sales deliver the highest per-activation transaction values.
Customer Type:
Organizational scale dictates pricing architecture, with government agencies demanding the most stringent procurement documentation and audit trails.
- Individual Consumers:Single-unit purchasers seeking personal gifting or self-use stored value with minimal fee sensitivity on occasion-driven purchases.
- Businesses:Mid-market and enterprise procurement of incentive and reward instruments with volume discounts and co-branding requirements.
- Non-Profits:Donor recognition and volunteer appreciation programs with constrained budgets and mission-aligned vendor selection criteria.
- Government Agencies:Federal, state, and municipal procurement subject to competitive bidding rules and financial inclusion mandates under state tax incentive programs.
Individual consumers generate the highest transaction frequency; businesses concentrate the fastest expansion in incentive automation.
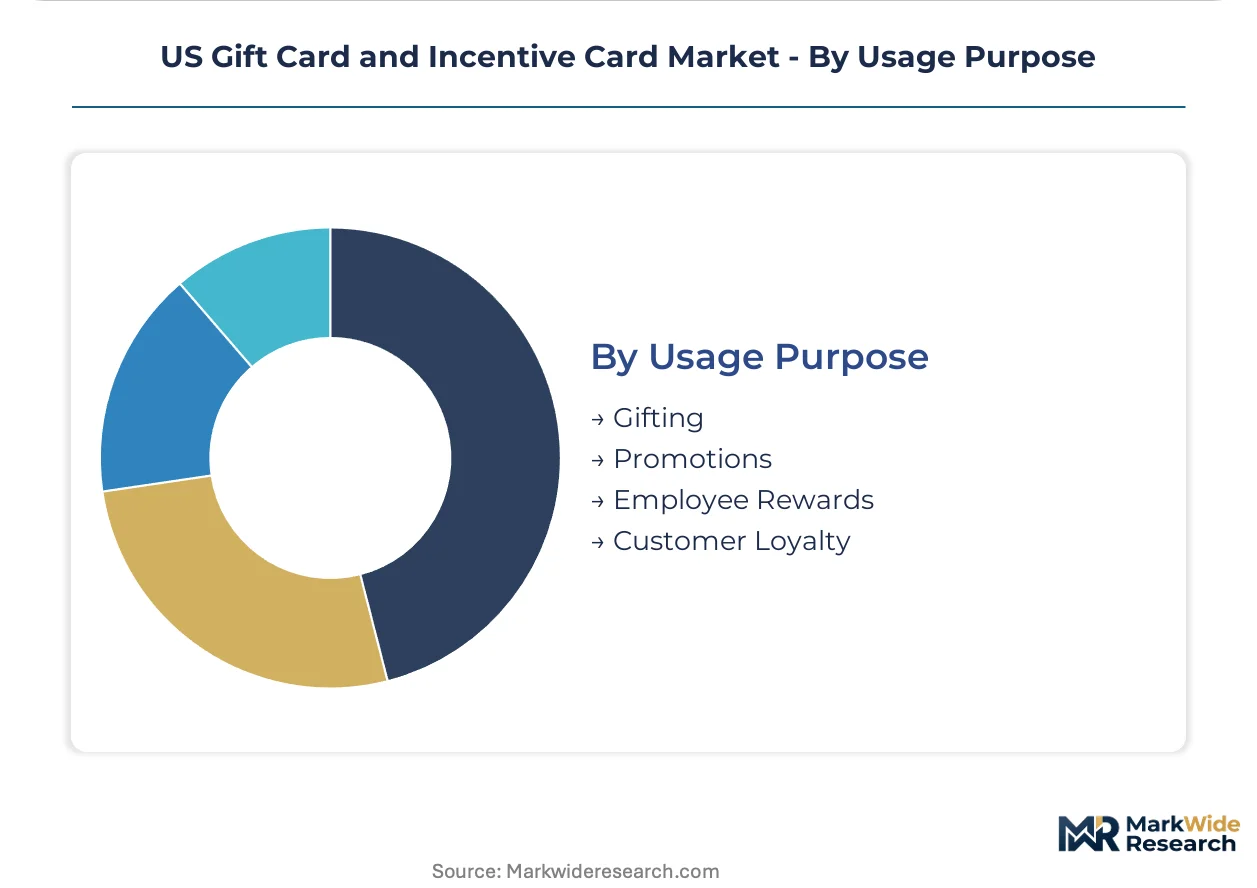
Usage Purpose:
Functional application determines card lifecycle design, with employee rewards requiring the most sophisticated real-time integration into HR systems.
- Gifting:Occasion-driven purchase for holidays, birthdays, and celebrations with emphasis on presentation and recipient choice.
- Promotions:Marketing campaign instruments with expiration dates and redemption restrictions designed to drive specific purchase behaviors.
- Employee Rewards:Performance-triggered issuance tied to achievement metrics with integration into recognition platforms and taxable benefit tracking.
- Customer Loyalty:Points redemption and retention programs with ongoing engagement mechanics and tiered benefit structures.
Gifting anchors current volume; employee rewards show the steepest expansion trajectory as HR automation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's metropolitan corridors anchor US gift card velocity through corporate headquarters density and digital wallet penetration. The state concentration reflects tech sector employment patterns and B2B procurement sophistication.
California
Corporate HR automation and sustainability procurement mandates drive demand in Los Angeles and San Francisco Bay Area corridors. State procurement rules favor recycled-content card substrates under environmental compliance frameworks. Silicon Valley tech campuses concentrate real-time digital issuance pilots for employee recognition platforms.
New York
Financial services sector employment and dense retail infrastructure sustain high transaction volumes across Manhattan and Brooklyn. State unclaimed property statutes create compliance complexity for breakage accounting timelines. The Hudson Valley corridor hosts emerging fintech infrastructure for tokenized credential vaulting.
Texas
Quick-service restaurant chains and ride-hailing platforms pilot unified stored-value consolidation in Dallas-Fort Worth and Austin metro areas. State tax incentive programs for financial inclusion technology attract issuer operations. The Energy Corridor submarket concentrates B2B incentive card distribution for oilfield services contractors.
Illinois
Corporate headquarters relocation and manufacturing sector employee recognition programs expand incentive card deployment in Chicago and Rockford. State tax credits for financial inclusion investments offset compliance infrastructure costs. The I-88 technology corridor hosts program management platforms serving Midwest enterprise accounts.
Florida
Tourism sector seasonal employment and hospitality customer loyalty programs drive promotional card issuance across Orlando and Miami-Dade counties. State procurement for government assistance programs mandates prepaid card distribution to unbanked populations. The Tampa Bay submarket concentrates retirement community gift card retail placement.
US Gift Card and Incentive Card Market Competitive Landscape
Platform-embedded checkout integration dominates the current landscape as issuers race to eliminate friction between purchase intent and redemption capability. The vendor base stratifies across network-branded payment giants, retail distribution specialists, and technology platform owners. Three archetypes define competitive positioning: payment network incumbents with regulatory scale, retail infrastructure operators with physical density, and platform-native issuers with embedded distribution. M&A activity concentrates on digital issuance capabilities while strategic partnerships lock in corporate HR platform integration.
Within the platform-native tier, Amazon.com and Apple exemplify divergent approaches to controlling the redemption experience—Amazon through marketplace-embedded checkout velocity, Apple through Wallet-native credential storage that governs mobile presentation. Blackhawk Network occupies a position representing retail infrastructure specialists, leveraging physical point-of-sale density in grocery and convenience channels to sustain distribution reach where digital wallet penetration lags.
| Leading Market Players |
|---|
| PayPal Holdings |
| American Express Company |
| Blackhawk Network |
| Apple |
| Amazon.com |
| InComm Payments |
| Mastercard |
| Target Corporation |
| Fiserv |
| Others |
Value Network & Pricing Analysis
Network-branded prepaid cards and closed-loop merchant instruments diverge sharply in margin architecture, with Durbin Amendment interchange constraints compressing unit economics on the former while digital delivery infrastructure concentrates pricing power among platform-native issuers. This bifurcation manifests in supply chain configurations: physical card programs draw from biodegradable polymer substrate suppliers facing California and New York sustainability mandates, whereas digital issuance pipelines hinge on tokenization engineering talent and mobile wallet API access.
Pricing Analysis
Input-cost pass-through from post-consumer rPET substrate sourcing and secure element chip procurement shapes issuer margin structures. Pricing stratifies across premium co-branded corporate incentive tiers, standard retail gift card placements, and economy unbanked-access programs. Cost compression in economy-tier prepaid instruments stems from Durbin Amendment interchange caps. Small and mid-sized program managers exhibit highest price sensitivity due to compliance infrastructure scale disadvantages against national issuers.
Supply Chain Analysis
Direct-to-corporate channels handle enterprise-scale incentive demand through API-embedded issuance platforms, while retail distribution runs through grocery and convenience store networks. Manufacturing concentration centers on China for EMV chip modules, Taiwan for secure element components, and domestic converters for biodegradable polymer substrates. Single-source vulnerability in tokenization architecture talent creates bottleneck risk for mobile wallet integration. Distribution downstream feeds through Blackhawk Network's physical retail density and Amazon's platform-embedded checkout velocity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where Mississippi and Arkansas cash-preferred demographics sustain physical card economics against coastal digital wallet saturation, with state tax incentive differentials between Illinois and Georgia further shaping issuer operational placement decisions.
For Market Incumbents: Extend platform-embedded checkout integration to capture HR automation-triggered issuance moments before FedNow instant payment rails disintermediate closed-loop merchant cards. Reinforce biodegradable substrate supply chain control through California-compliant rPET sourcing contracts. Vertical integration into tokenization engineering talent pools defends against fintech compensation benchmarks eroding technical capabilities. For New Entrants and Emerging Players: Enter via API-enabled embedded finance partnerships with fitness apps and gig economy marketplaces seeking white-label incentive infrastructure. Target underpenetrated rural corridors in Mississippi and Arkansas where grocery cooperative distribution maintains tactile gifting ritual relevance. Pursue state tax credit qualification in Illinois and Georgia for financial inclusion technology investments. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier issuers face disproportionate Regulation E compliance cost burdens relative to transaction scale. Long-term viability favors platform-native issuers with Wallet-native credential storage or marketplace-embedded distribution. Acquisition target archetype: regional program managers with corporate HR platform integration capabilities and verified sustainable substrate supply chains. Signal to watch: FedNow adoption velocity among unbanked population segments as closed-loop merchant card substitution indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Substrate Transition | California and New York procurement rules favor recycled-content polymers for sustainability compliance. |
| API-Enabled Embedded Finance | Open banking standards allow non-financial platforms to issue branded stored-value instruments. |
| Corporate HR Platform Integration | Real-time achievement-triggered issuance replaces quarterly bulk distribution in enterprise accounts. |
| Mobile Wallet Credential Vaulting | Apple Wallet-native storage controls mobile redemption experience against standalone gift card apps. |
| State Tax Incentive Capture | Illinois and Georgia credits for financial inclusion technology offset compliance infrastructure costs. |
Research Methodology
Multiple input streams — program manager executives, corporate HR procurement leads, retail distribution channel heads, and regulatory compliance officers — were reconciled against Consumer Financial Protection Bureau rulemaking dockets, Federal Reserve payment system risk assessments, state unclaimed property statutes, and SEC 10-K filings from listed payment network operators. Bottom-up activation volume modeling and top-down market sizing triangulation validated segment-level estimates across the analysis window.
Historical transaction velocity patterns were cross-referenced against panel input from incentive platform providers and mobile wallet operators. The analytical framework modeled product type, distribution channel, customer type, and usage purpose segmentation dimensions throughout the forecast period. CAGRs were derived from trend extrapolation adjusted for regulatory intervention timelines and technology substitution curves. Industry-specific inputs included Regulation E compliance cost trajectories and FedNow adoption penetration assumptions.
Inputs from primary stakeholder interviews and secondary regulatory databases were available through the study window; gaps in real-time digital issuance volume reporting and corporate HR platform API transaction disclosure introduce uncertainty bands around segment share estimates. Forecasts reflect documented assumptions regarding interchange fee stability and state unclaimed property harmonization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Europe Gift Card and Incentive Card Market
Payments
Southeast Asia POS Terminal Market
Payments
Spain Payment Gateway Market
Payments
Direct Carrier Billing Market
Payments
Europe Mobile Payment Market
Payments
Malta POS Terminal Market
Payments
Denmark Payments Market
Payments
Third Party Payment Market
Payments
Hong Kong Credit Cards Market
Payments
Global Gift Card Market
Payments
Retail Point of Sale (POS) Market
Payments
Mexico Digital Wallet Market
Payments
MENA Digital Payments Market
Payments
LAMEA Crypto Payment Gateway Market
Payments
Middle East Gift Card and Incentive Card Market
Payments
P2P Payment Market