
 China Prepaid Cards Market | 2026-2036
China Prepaid Cards Market Size, Share, and Industry Trends Forecast 2026-2036
China Prepaid Cards Market Intelligence
Retail store distribution networks are rewriting how prepaid cards reach consumers across China's urban centers. China UnionPay leverages its interbank clearing infrastructure to sustain dominance in open-loop card issuance. Alipay competes through embedded wallet integrations that blur boundaries between prepaid balances and digital payment accounts. WeChat Pay controls social commerce channels where gift card circulation accelerates during festival seasons.
Prepaid cards are stored-value instruments issued by financial institutions or licensed non-bank entities, encoded with magnetic stripes or chip-based EMV compliance for terminal acceptance, and designed to facilitate transactions without linked credit facilities or demand deposit accounts. Closed-loop cards dominate merchant-specific gifting and loyalty programs where issuer-retailer partnerships lock spending within branded ecosystems, while open-loop instruments carry network branding for broader acceptance and attract corporate disbursement volumes seeking standardized payroll and expense management tools. Reloadable cards are capturing professional and student segments through recurring budget allocation features, whereas non-reloadable gift variants dominate seasonal retail traffic.
SAMR licensing frameworks constrain market entry by requiring capital reserves and consumer protection mechanisms from non-bank issuers, while PBOC digital yuan pilots create parallel technical standards that prepaid card operators must accommodate. GB standards for payment security and data localization mandates shape product architecture decisions for domestic and foreign-invested issuers alike. Stakeholders must monitor how central bank digital currency interoperability requirements will redefine settlement infrastructure and issuer economics.
Market Dynamics
PBOC digital yuan pilots are forcing prepaid card operators to rebuild settlement infrastructure around central bank digital currency interoperability, compressing issuer margins while opening new disbursement channels.
Growth Catalysts
- Corporate benefit program expansion:State-owned enterprises and multinational employers in Shanghai and Beijing are standardizing prepaid cards for meal allowances and transportation subsidies, creating recurring volume commitments.
- SAMR licensing consolidation:The State Administration for Market Regulation's capital reserve requirements are filtering out undercapitalized issuers, concentrating market share among compliant operators with established interbank partnerships.
- EMV chip migration:Magnetic stripe decommissioning across China UnionPay's terminal network is accelerating hardware refresh cycles that embed contactless and QR-code capabilities.
Market Restraints
- Dual-track compliance costs:Simultaneous adherence to SAMR stored-value regulations and PBOC digital yuan technical standards demands parallel system investments that strain non-bank issuer balance sheets.
- Payment substitution pressure:Direct digital wallet transfers via Alipay and WeChat Pay are displacing prepaid card use for peer-to-peer gifting, eroding non-reloadable gift card velocity.
- Data localization mandates:GB standards for payment security require domestic server infrastructure that increases operational overhead for foreign-invested card program managers.
Strategic Opportunities
- Tier-two city penetration:Chengdu, Hangzhou, and Wuhan exhibit prepaid card underpenetration relative to their retail density, offering first-mover positioning before local competitors establish UnionPay partnerships.
- Cross-border tourism corridors:Guangdong province's integration with Hong Kong and Macau payment rails creates demand for dual-currency prepaid instruments among mainland visitors.
- Student segment reloadable products:Campus-based budget management tools linked to parental oversight features address unmet needs in higher education clusters across Jiangsu and Zhejiang provinces.
Industry Challenges
- Digital yuan integration complexity:Prepaid card core systems require API reconstruction to interface with PBOC's layered authentication protocols, stretching technical teams across 12-18 month implementation windows.
- Merchant acquisition friction:Closed-loop gift card programs face resistance from retailers prioritizing direct customer data capture over third-party issuer partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Prepaid Cards Market |
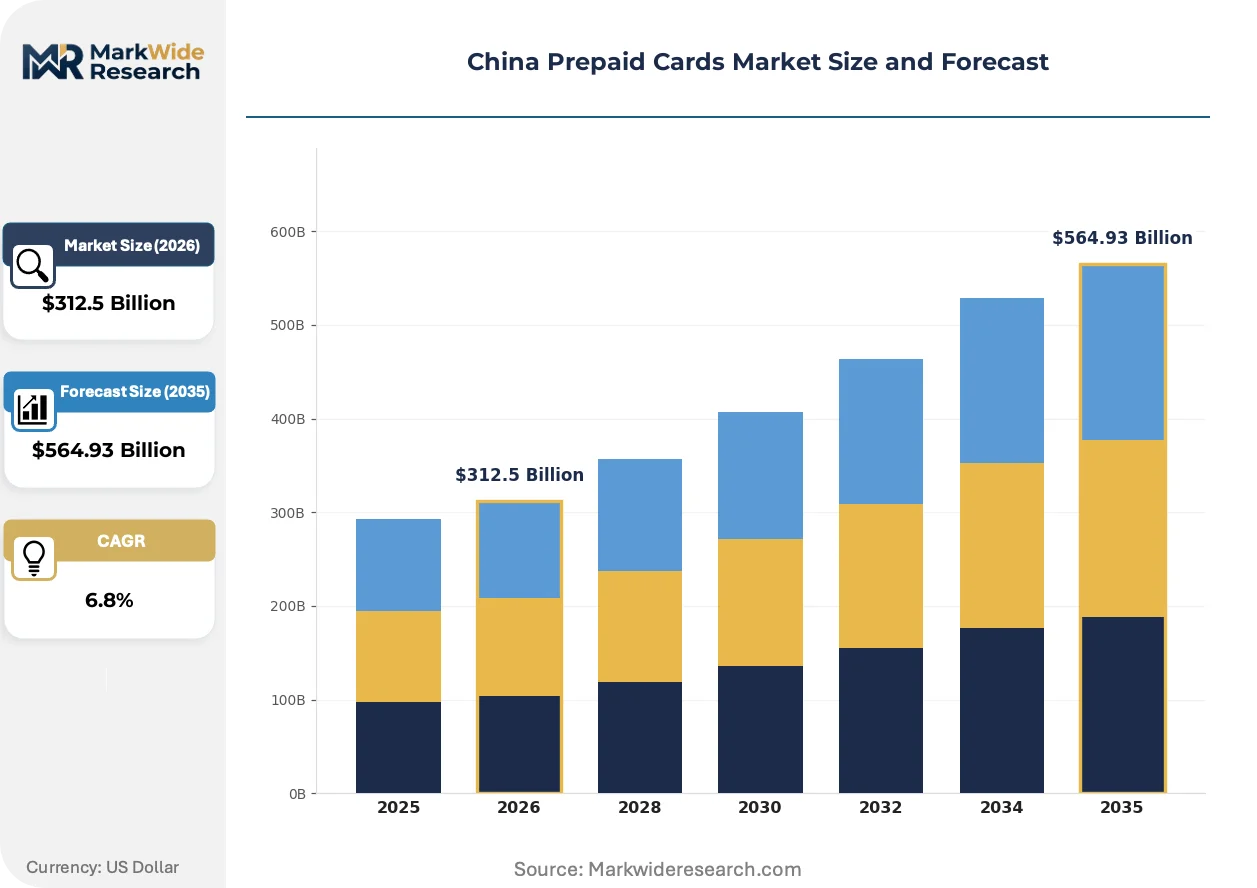
| Market Size in 2026 | $312.5 Billion |
| Market Size in 2035 | $564.93 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Card Type: Closed-loop, Open-loop, Reloadable, Non-reloadable Usage Scenario: Online Shopping, Travel Expenses, Gift Giving, Budgeting Target Customer: Students, Professionals, Tourists, Retail Shoppers Distribution Channel: Retail Stores, E-commerce Platforms, Banks, ATMs |
| Companies Covered | China UnionPay, Alipay, WeChat Pay, Industrial and Commercial Bank of China, China Construction Bank, Agricultural Bank of China, Bank of China, China Merchants Bank, Bank of Communications, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Prepaid Cards Market Strategic Shifts & Innovations
Payment infrastructure convergence is blurring distinctions between prepaid stored value and digital wallet balances, forcing issuers to differentiate through embedded loyalty and budget-management features rather than access alone.
Biometric authentication is hybridizing prepaid card security architectures. Fingerprint and facial recognition modules are replacing PIN entry at China UnionPay terminals. Corporate disbursement programs in Beijing are piloting voice-print verification for high-value reloads. This technology is hybridizing fraud prevention with user experience optimization, compressing transaction abandonment rates.
SAMR's 2024 consumer protection amendments mandate real-time balance disclosure and dispute resolution timelines for stored-value instruments. Non-bank issuers must deploy customer service infrastructure meeting 48-hour complaint resolution standards. Prepaid card program managers are responding by integrating AI-powered chatbots with human escalation protocols.
Young professionals are consolidating discretionary spending onto single reloadable instruments with automated budget categorization. University students in Shanghai and Shenzhen prefer prepaid cards with parental oversight dashboards over traditional debit products. This behavioral pivot is most visible in tier-one cities where fintech literacy and privacy concerns about full banking data sharing intersect.
China Prepaid Cards Market Segmentation
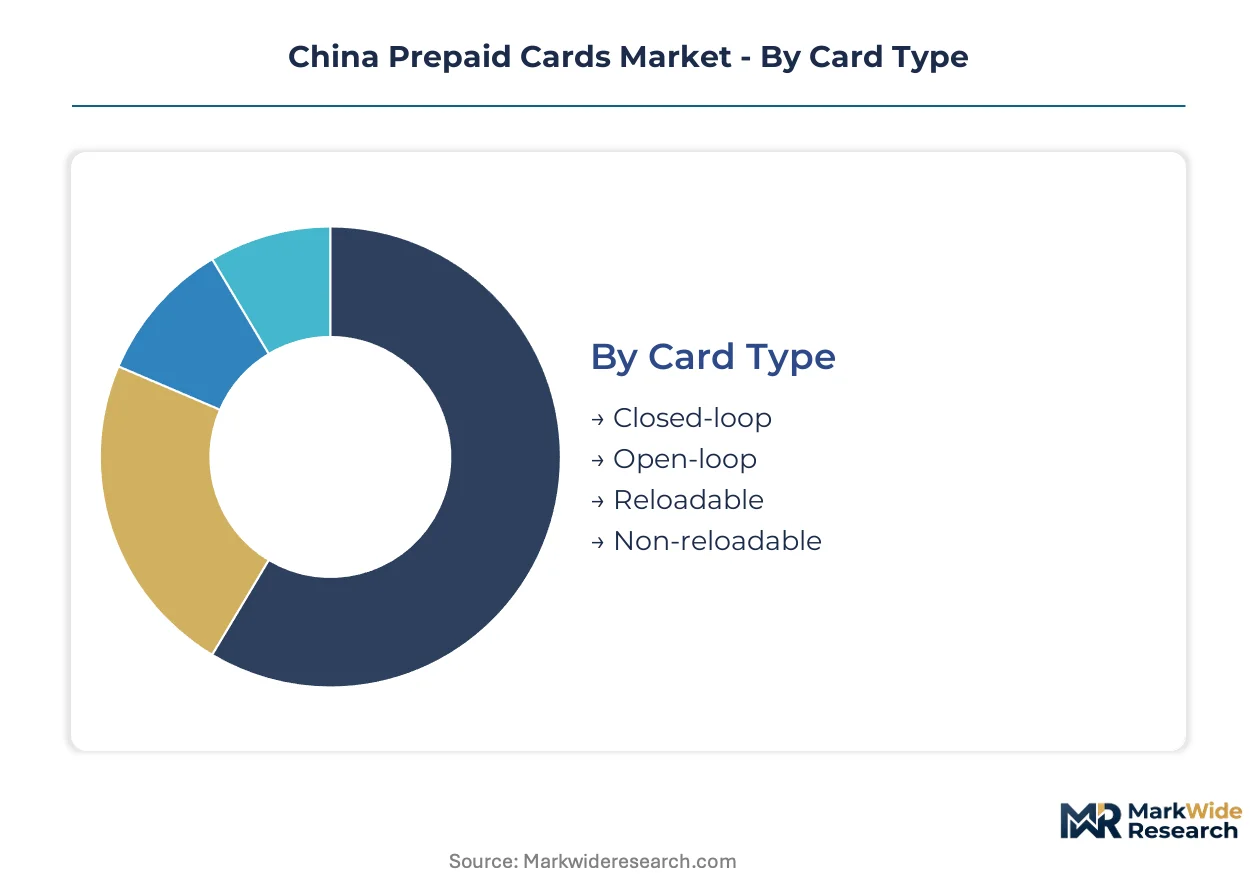
Prepaid card segmentation in China reveals how issuer business models align with distinct customer journeys and regulatory requirements. Each dimension carries implications for compliance costs, merchant partnership structures, and digital yuan integration timelines.
Card Type:
After-sales service intensity varies sharply across card types, with reloadable products demanding ongoing balance management infrastructure and dispute resolution capabilities that non-reloadable gift cards avoid entirely.
- Closed-loop:Merchant-specific instruments lock value within branded retail ecosystems through proprietary terminal networks. Shanghai-based luxury retailers deploy these for VIP loyalty programs where spending data remains captive to the issuer-retailer partnership.
- Open-loop:Network-branded cards carry China UnionPay acceptance marks enabling cross-merchant transactions. Corporate disbursement programs in Beijing standardize these for meal and transportation allowances, requiring SAMR licensing compliance and interbank settlement relationships.
- Reloadable:Recurring funding capabilities serve budget-conscious segments with parental oversight features.
- Non-reloadable:Single-load gift variants dominate seasonal retail traffic with minimal post-purchase service obligations.
Closed-loop holds the largest share; momentum sits with reloadable products as young professionals consolidate discretionary spending onto single instruments with automated budget categorization.
Usage Scenario:
Application-driven segmentation maps directly to issuer technology investments, with online shopping scenarios demanding API-first architectures while travel expense use cases require cross-border currency handling capabilities.
- Online Shopping:E-commerce integrations embed prepaid balances within checkout flows, blurring distinctions with digital wallet accounts. Alibaba and JD.com partnerships dominate this channel, requiring real-time balance verification and split-payment handling.
- Travel Expenses:Dual-currency capabilities address Guangdong province's integration with Hong Kong and Macau payment rails. PBOC digital yuan pilots are forcing reconstruction of settlement infrastructure for cross-border corridors.
- Gift Giving:Festival-season velocity concentrates in WeChat Pay's social commerce channels.
- Budgeting:Automated categorization tools attract university students in Jiangsu and Zhejiang provinces seeking parental oversight dashboards.
Gift giving captures seasonal volume peaks; budgeting applications are climbing the fastest as fintech literacy spreads through tier-one city demographics.
Target Customer:
Customer-type segmentation determines pricing architecture and distribution channel selection, with student segments accepting parental oversight features that professional segments would reject as intrusive.
- Students:Campus-based reloadable products with spending limit controls address higher education clusters across Jiangsu and Zhejiang. Shanghai and Shenzhen universities show strongest uptake where privacy concerns about full banking data sharing intersect with fintech literacy.
- Professionals:Corporate benefit program standardization drives recurring volume through state-owned enterprise and multinational employer channels in Beijing and Shanghai.
- Tourists:Dual-currency instruments serve mainland visitors to Hong Kong and Macau through Guangdong distribution networks.
- Retail Shoppers:Seasonal gift card velocity concentrates in tier-one city retail density corridors.
Professionals generate the steadiest recurring volume; students represent the steepest expansion trajectory as campus-based fintech adoption accelerates.
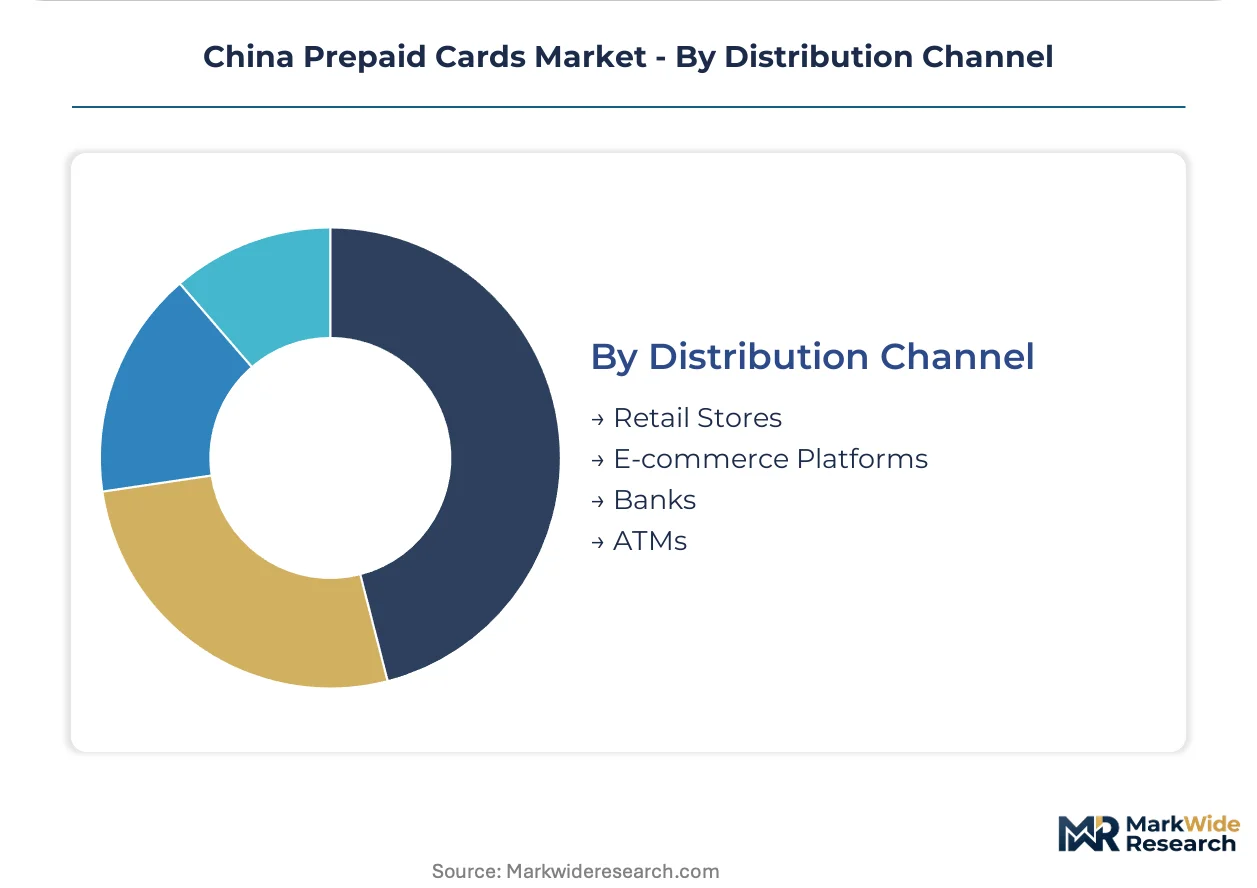
Distribution Channel:
Channel economics shape issuer margin structures, with bank partnerships carrying compliance overhead advantages that retail store networks lack despite superior customer acquisition reach.
- Retail Stores:Physical distribution networks in Shanghai, Beijing, and Guangdong province provide impulse purchase visibility for gift card variants. SAMR licensing requirements filter out undercapitalized issuers from establishing these partnerships.
- E-commerce Platforms:Digital issuance compresses distribution costs while enabling instant delivery. Tmall and JD.com integrations require API reconstruction to accommodate PBOC digital yuan interoperability standards.
- Banks:Licensed financial institutions leverage existing compliance infrastructure for corporate disbursement programs.
- ATMs:China UnionPay terminal networks enable cash-loading capabilities for reloadable products.
Retail stores maintain broadest consumer reach; e-commerce platforms are gaining share fastest as digital-native demographics bypass physical purchase occasions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR licensing requirements and PBOC digital currency pilots concentrate prepaid card infrastructure development in China's eastern corridor. Regional variation reflects retail density gradients and corporate benefit program standardization.
Yangtze River Delta
Shanghai anchors corporate disbursement volumes for state-owned enterprises and multinational employers. SAMR capital reserve requirements filter undercapitalized issuers from establishing retail partnerships. Campus-based reloadable products with parental oversight features show strongest uptake at universities in Shanghai and surrounding Jiangsu province.
Pearl River Delta
Guangdong province drives dual-currency instrument demand through Hong Kong and Macau tourism corridors. PBOC digital yuan pilots force settlement infrastructure reconstruction for cross-border payment rails. Shenzhen fintech clusters accelerate biometric authentication integration for contactless terminal networks.
Beijing-Tianjin-Hebei
Beijing concentrates voice-print verification pilots for high-value corporate reloads among state-owned enterprise benefit programs. GB standards for payment security mandate domestic server infrastructure that increases operational overhead. State Administration for Market Regulation compliance concentrates market share among established interbank partnerships.
Sichuan-Chongqing
Chengdu exhibits prepaid card underpenetration relative to retail density, offering first-mover positioning before local competitors establish UnionPay partnerships. Chongqing's expanding digital payment infrastructure attracts reloadable product launches targeting young professionals. EMV chip migration accelerates hardware refresh cycles embedding QR-code capabilities across western China terminal networks.
Shandong Peninsula
Jinan and Qingdao retail density supports seasonal gift card velocity through physical distribution networks. SAMR licensing frameworks constrain market entry by requiring consumer protection mechanisms from non-bank issuers. Local commercial banks leverage existing compliance infrastructure for corporate meal allowance standardization.
China Prepaid Cards Market Key Industry Players
State-owned banking conglomerates and fintech platform operators split the market along compliance infrastructure versus digital distribution capabilities. The vendor base concentrates among licensed financial institutions with established SAMR relationships and technology platforms with embedded wallet scale. Two strategic archetypes dominate: interbank clearing infrastructure operators and social commerce channel controllers. Competitive moves center on EMV chip migration partnerships and API reconstruction for PBOC digital yuan interoperability.
Within the state-owned banking tier, Industrial and Commercial Bank of China and China Construction Bank represent archetypal compliance-heavy issuers leveraging existing SAMR licensing for corporate disbursement programs. China UnionPay anchors the interbank clearing infrastructure segment with terminal network dominance. Alipay and WeChat Pay occupy positions as fintech platform operators controlling digital distribution channels and social commerce gift card velocity.
| Leading Market Players |
|---|
| China UnionPay |
| Alipay |
| WeChat Pay |
| Industrial and Commercial Bank of China |
| China Construction Bank |
| Agricultural Bank of China |
| Bank of China |
| China Merchants Bank |
| Bank of Communications |
| Others |
Cost & Logistics Intelligence
Regulatory chokepoint exposure through SAMR licensing and PBOC digital yuan interoperability mandates determines both pricing tier spreads and supply chain shape, as compliance infrastructure investments compress margins for non-bank issuers while concentrating procurement power among state-licensed operators with established interbank partnerships.
Pricing Analysis
The customization-premium spread separates configured corporate disbursement programs from standard retail gift card offerings, with three-tier pricing structure across premium, standard, and economy levels reflecting EMV chip compliance tiers and biometric authentication bundling. Price differentiation centers on SAMR licensing status and UnionPay network access fees, with state-owned banks commanding premium spreads due to compliance infrastructure advantages. Pricing pressure stems from digital wallet substitution eroding non-reloadable gift card velocity. Corporate benefit managers show lowest price sensitivity due to standardized procurement frameworks, while student segments prioritize parental oversight features over cost minimization.
Supply Chain Analysis
Contract-manufacturing concentration for EMV chip modules and POS terminal hardware rests on Taiwan Semiconductor Manufacturing Company capacity for secure element production, with downstream assembly anchored in China and South Korea. Raw material dependencies include semiconductor-grade silicon, EMV-compliant plastic substrates, and magnetic stripe components facing obsolescence. Supply chain risk centers on single-source vulnerability for advanced biometric sensor modules integrated into contactless terminals. Distribution runs through UnionPay's interbank clearing infrastructure for open-loop instruments, while closed-loop programs leverage direct retailer partnerships bypassing network fees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where PBOC digital yuan interoperability is fragmenting issuer economics around central bank settlement rails, rewarding operators with pre-built API architectures and SAMR licensing moats.
For Market Incumbents: Build compliance infrastructure moats through accelerated EMV chip migration partnerships and captive biometric authentication module sourcing. Vertical integration into terminal hardware refresh cycles locks in merchant acquisition channels against fintech platform encroachment. Priority lever: deepen UnionPay interbank relationships before digital yuan settlement standards crystallize. For New Entrants and Emerging Players: Pursue tier-two city white-space in Chengdu, Hangzhou, and Wuhan where retail density outpaces prepaid card penetration and local UnionPay partnerships remain unclaimed. Campus-based reloadable products with parental oversight dashboards offer the most penetrable segment, with go-to-market execution through university procurement channels bypassing incumbent retail distribution dominance. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors SAMR-licensed non-bank issuers with technical teams capable of 12-18 month digital yuan API reconstruction windows. Long-term viability hinges on interoperability architecture ownership rather than transaction volume alone. Signal to watch: PBOC pilot expansion announcements indicating which settlement standards achieve regulatory preference.| Strategic Initiative | Industry Significance |
|---|---|
| EMV Chip Migration Partnership | Terminal hardware refresh cycles embed contactless capabilities ahead of magnetic stripe decommissioning deadlines. |
| PBOC Digital Yuan API Reconstruction | Core system interoperability with layered authentication protocols secures issuer positioning in central bank settlement infrastructure. |
| Biometric Authentication Integration | Fingerprint and facial recognition modules at UnionPay terminals compress transaction abandonment rates for corporate reload programs. |
| Tier-Two City UnionPay Partnership | First-mover positioning in Chengdu and Wuhan captures retail density before local competitors establish interbank relationships. |
| Campus-Based Reloadable Product Launch | Parental oversight dashboards address unmet budgeting needs in Jiangsu and Zhejiang higher education clusters. |
Research Approach
The analysis maps closed-loop merchant-specific instruments, open-loop network-branded cards, reloadable budget management products, and non-reloadable gift variants, each validated through prepaid card program managers, SAMR licensing officers, UnionPay network operations leads, and corporate benefit procurement directors. Primary interviews combined with secondary validation from PBOC digital yuan pilot disclosures, SAMR regulatory filings, China UnionPay terminal deployment statistics, and GB standards documentation. Bottom-up segment sizing triangulated against top-down macroeconomic consumption indicators across the analysis window.
Assumptions held fixed include SAMR capital reserve requirements and PBOC interoperability technical standards, while variables tested included digital yuan adoption velocity and corporate benefit program standardization rates. Segmentation dimensions modeled encompass card type, usage scenario, target customer archetype, and distribution channel structure, with CAGRs derived from regression analysis against retail payment infrastructure investment flows and fintech platform penetration curves. Forecast inputs included EMV terminal refresh cycle timelines and biometric authentication module cost curves.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending patterns or central bank digital currency rollout sequencing would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory compliance timelines and technology migration schedules. Quarterly review of PBOC pilot expansion indicators and SAMR enforcement action patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Germany Mobile Payments Market
Payments
Payment Security Software Market
Payments
Estonia POS Terminal Market
Payments
Australia Buy Now Pay Later Services Market
Payments
In-Vehicle Payment Services Market
Payments
Electronic Payment Processing Software Market
Payments
China Virtual Cards Market
Payments
Digital Payment in Healthcare Market
Payments
Egypt Mobile Payments Market
Payments
Mexico Digital Wallet Market
Payments
UAE Card Payments Market
Payments
United Kingdom Real Time Payments Market
Payments
China Payment Gateway Market
Payments
Face-Swiping Payment Market
Payments
Global Digital Wallets Market
Payments
Online Payment Gateway Market