
 France BNPL Market | 2026-2036
France BNPL Market Size, Share, and Industry Trends Forecast 2026-2036
France BNPL Market Insights
Revenue-based financing and asset-light balance sheet structures is fragmenting competitive dynamics among France BNPL providers. Klarna leverages its proprietary risk engine and pan-European data infrastructure to sustain underwriting scale across multiple merchant categories. Alma competes through deep integration with French e-commerce platforms and localized checkout experiences. Oney anchors its position via longstanding retail partnerships with major French department stores and supermarket chains.
Buy now, pay later denotes a short-term consumer credit mechanism enabling purchasers to defer or split payments across installments, typically without interest when repaid on schedule, with algorithms assessing default probability through real-time transaction data and behavioral signals. Its primary commercial purpose is reducing cart abandonment and lifting average order values for merchants while expanding purchasing power for consumers. Pay in Installments dominates transaction volumes as the most recognized and merchant-adopted service type across French retail. Small Ticket and Medium Ticket transactions represent the fastest-growing transaction size pools, driven by grocery, apparel, and beauty purchases where BNPL displaces traditional card usage.
ANSM, the French financial markets regulator, alongside BCE and ECB oversight of credit institutions, shapes market access through licensing requirements and consumer protection mandates that elevate compliance costs for new entrants. The EU Consumer Credit Directive and GDPR impose strict transparency obligations and data handling protocols that influence product design and marketing practices. Stakeholders must monitor how forthcoming EU-wide BNPL-specific legislation alters capital requirements and merchant fee structures.
Market Dynamics
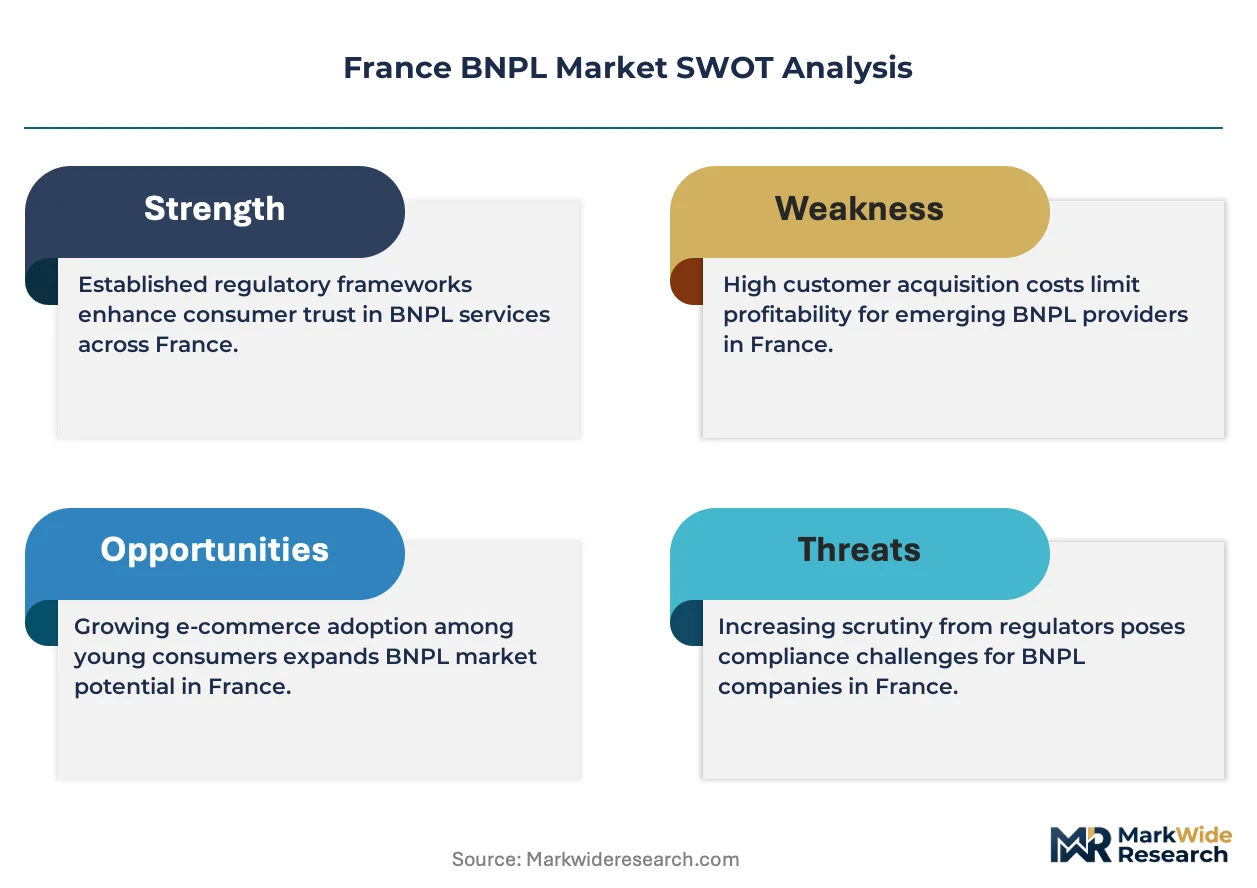
The EU Consumer Credit Directive's tightening of disclosure standards is compressing margins for French BNPL providers while elevating compliance thresholds that favor established operators with dedicated legal infrastructure.
Growth Catalysts
- Embedded checkout integration:Deep API connections with French e-commerce platforms reduce friction at point-of-sale. Alma's native plugin architecture for WooCommerce and PrestaShop accelerates merchant onboarding velocity.
- GDPR-compliant data infrastructure:Real-time behavioral scoring engines leverage transaction histories without violating data portability rules. Klarna's pan-European data reservoirs enable cross-border risk calibration.
- Paris-Île-de-France retail density:Premium department store concentration in the capital corridor sustains high-ticket BNPL adoption. Galeries Lafayette and Printemps anchor merchant volume for installment products.
Market Restraints
- ANSM licensing capital requirements:New entrants must maintain minimum regulatory capital buffers that strain early-stage balance sheets. The French financial markets regulator mandates solvency ratios above traditional consumer credit thresholds.
- Interest rate cap compression:French usury limits constrain late-fee revenue models. The Banque de France's quarterly rate revisions restrict pricing flexibility on delinquent accounts.
- Bank-issued card substitution:Traditional revolving credit products from BNP Paribas and Crédit Agricole compete for the same installment-seeking consumers. Deferred debit cards with built-in budgeting tools capture overlapping demand.
Strategic Opportunities
- Supermarket grocery vertical expansion:Small-ticket BNPL at Carrefour and Intermarché checkout lanes displaces cash for routine purchases. Weekly shopping baskets under €150 represent underpenetrated frequency.
- Healthcare and dental service financing:Elective medical procedures lack standardized installment options. Optical chains and private dental clinics present white-space merchant categories.
- CNIL-certified biometric authentication:Facial recognition at pickup points streamlines identity verification for click-and-collect orders. The French data protection authority's approval framework enables fraud reduction without friction.
Industry Challenges
- Legacy core banking system integration:French retail banks operate on decades-old COBOL architectures that resist real-time API connectivity. BNPL providers face six-to-nine-month technical onboarding timelines for merchant settlement rails.
- Credit bureau data fragmentation:The Banque de France's FICP registry captures only negative credit events, leaving positive payment histories opaque. Underwriting algorithms compensate with proprietary behavioral proxies that require continuous recalibration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France BNPL Market |
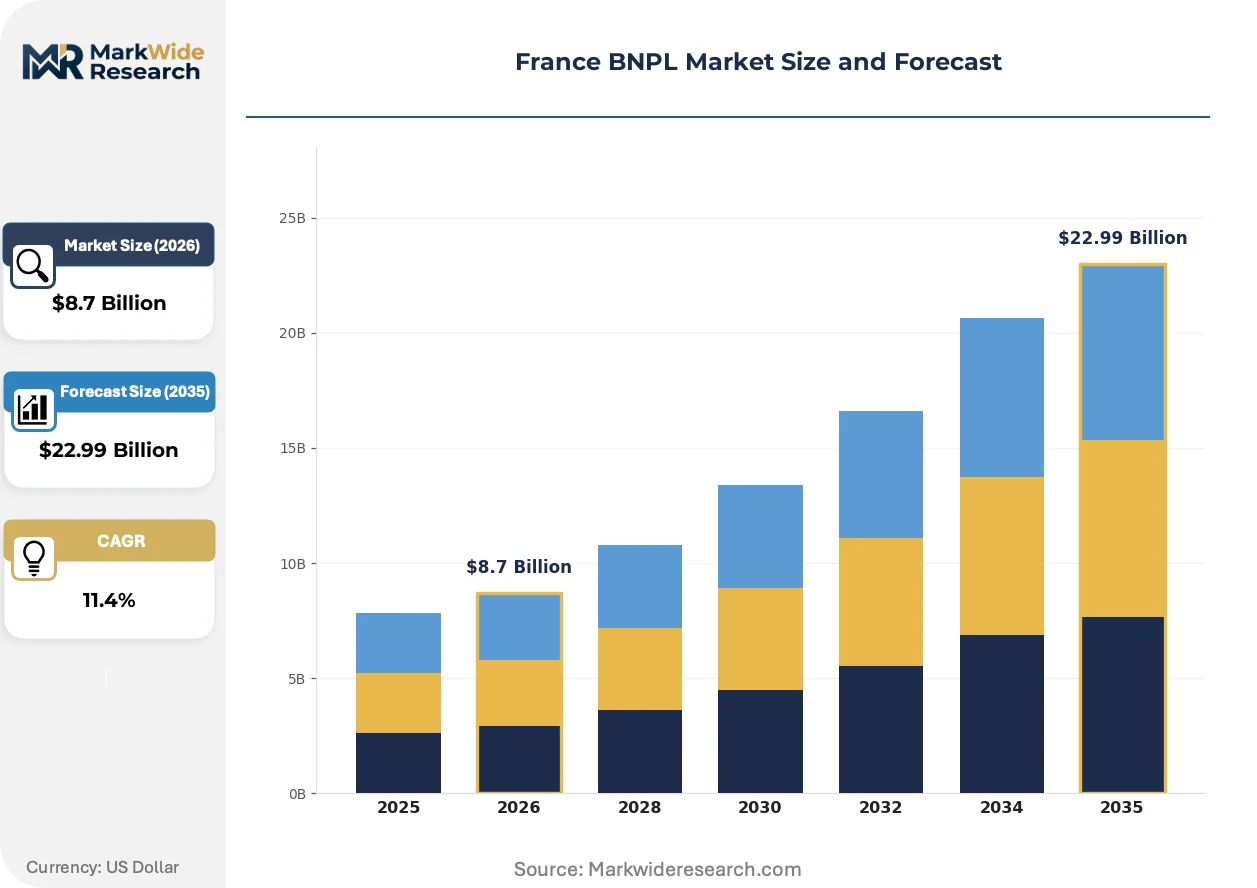
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Pay Later, Pay in Installments, Interest-Free Credit, Deferred Payment End User: Consumers, Retailers, E-commerce Platforms, Service Providers Payment Method: Credit Card, Debit Card, Digital Wallet, Bank Transfer Transaction Size: Small Ticket, Medium Ticket, High Ticket, Large Ticket |
| Companies Covered | Alma, Klarna, Oney, Floa Bank, PayPal, Scalapay, Cofidis, Younited Credit, Clearpay, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France BNPL Market Trends and Innovations
Algorithmic underwriting is virtualizing risk assessment infrastructure across French retail finance, compressing the traditional bank branch approval model into millisecond-scale checkout decisions.
Machine learning models trained on merchant-specific transaction patterns now evaluate default probability without hard credit pulls. Fashion and electronics retailers in Lyon and Marseille deploy these tools for instant approval at self-service kiosks. This capability is virtualizing the role of human credit officers in mid-market merchant relationships.
The EU Consumer Credit Directive's forthcoming BNPL-specific amendments will mandate standardized APR disclosures and cooling-off periods. French providers are pre-emptively redesigning checkout interfaces to display total cost of credit before final authorization. Small-ticket grocery and beauty segments face the steepest compliance redesign costs given high transaction volumes and thin margins.
Younger French consumers are abandoning revolving credit cards in favor of fixed-installment commitments with transparent repayment schedules. Digital-native shoppers in Bordeaux and Nantes reject compound interest products entirely. This behavioral pivot is compressing demand for traditional bank-issued deferred payment instruments in the 25-35 age cohort.
France BNPL Market Segmentation
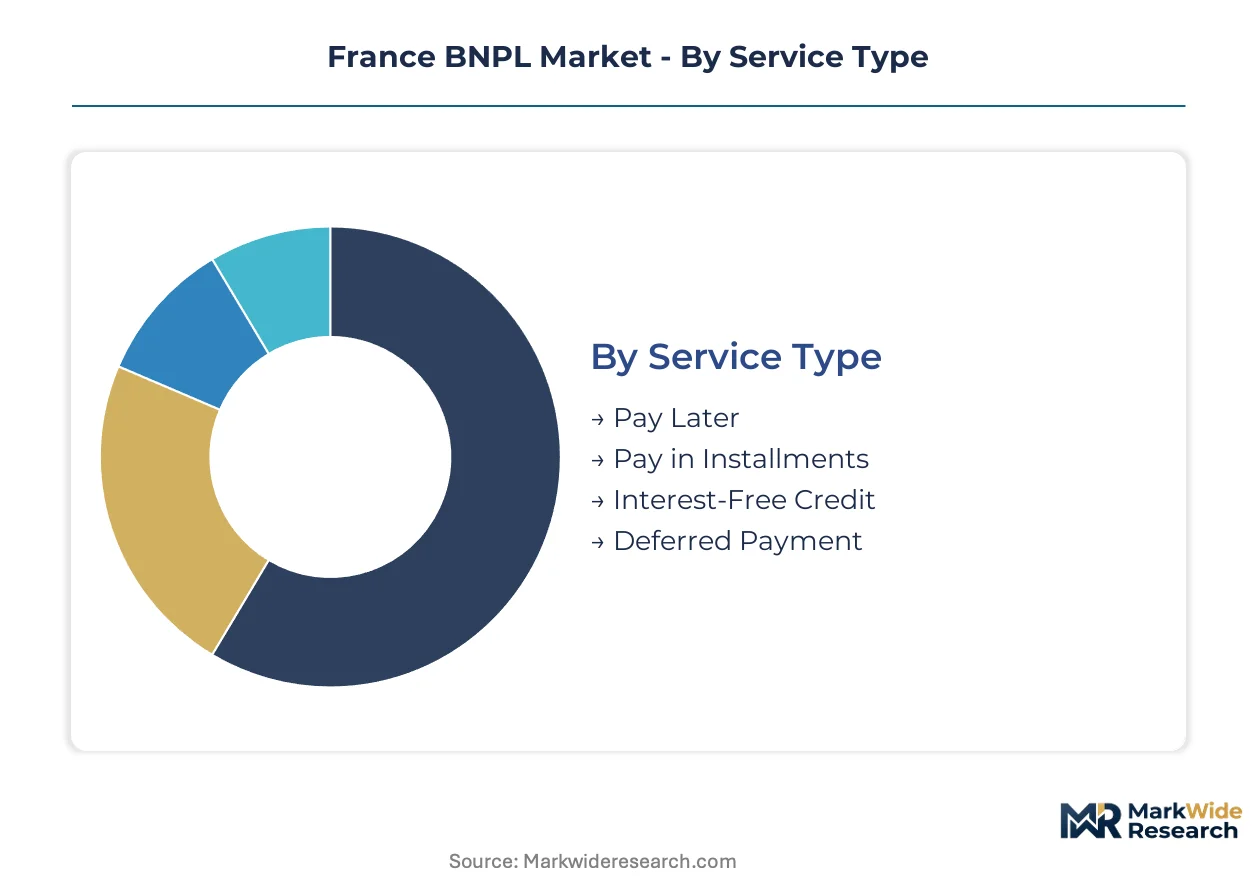
Segmentation reveals how French BNPL providers allocate capital and engineering resources across distinct risk-return profiles. Each dimension—service design, user type, payment rail, and ticket size—carries unique regulatory exposure and margin structure.
Service Type:
Mature installment products dominate merchant adoption while deferred payment models remain emergent in grocery and healthcare verticals.
- Pay Later:Single-invoice deferral typically spans 14-30 days with no interest if settled on schedule. Paris-based fashion retailers deploy this for cart abandonment recovery during seasonal sales windows.
- Pay in Installments:Fixed-schedule repayment across 3-4 monthly tranches represents the most merchant-adopted format. Electronics and appliance merchants in Lyon and Marseille anchor volume through embedded checkout APIs.
- Interest-Free Credit:Extended repayment windows up to 12 months for high-ticket purchases. Furniture and home improvement chains leverage this for average order value expansion.
- Deferred Payment:Post-delivery settlement options gaining traction in click-and-collect grocery. Carrefour and Intermarché pilot programs target weekly basket frequency under €150.
Pay in Installments handles the majority of throughput; Deferred Payment is expanding most quickly on share.
End User:
Customer-type segmentation tracks who bears the financing cost and regulatory compliance burden in each transaction chain.
- Consumers:Individual borrowers assessed via real-time behavioral algorithms. Younger demographics in Bordeaux and Nantes reject revolving credit in favor of fixed-commitment products.
- Retailers:Brick-and-mortar merchants absorbing merchant discount rates for conversion lift. Department stores in the Île-de-France corridor sustain the highest adoption density.
- E-commerce Platforms:Marketplace operators integrating BNPL as native checkout infrastructure. WooCommerce and PrestaShop plugin architectures accelerate technical deployment.
- Service Providers:B2B verticals including dental clinics and optical chains seeking patient financing solutions. Elective medical procedures represent underpenetrated white space.
Consumers generate the largest transaction flow; Service Providers are climbing the fastest as merchant categories diversify beyond retail.
Payment Method:
Rail selection determines settlement velocity, fraud exposure, and ANSM capital treatment for French providers.
- Credit Card:Visa and Mastercard network routing enables instant authorization with interchange fee pass-through. Premium department stores prefer this rail for high-ticket authorization limits.
- Debit Card:Direct bank account debiting reduces chargeback risk but requires stronger authentication protocols. SEPA-compliant flows dominate recurring installment collections.
- Digital Wallet:Apple Pay and Google Pay integration streamlines mobile-first checkout. Younger demographics in urban clusters show highest wallet-native adoption rates.
- Bank Transfer:Account-to-account settlement via SEPA Instant for cost-sensitive merchants. Supermarket chains favor this rail for thin-margin grocery baskets.
Credit Card rails carry the dominant share; Bank Transfer is gaining share fastest as merchants pressure fee compression.
Transaction Size:
Ticket stratification aligns underwriting infrastructure with purchase frequency and default probability curves.
- Small Ticket:Transactions under €50 displacing cash in convenience retail and quick-service food. Weekly grocery baskets drive frequency but compress per-unit margins.
- Medium Ticket:€50-€500 range capturing apparel, beauty, and consumer electronics. This band balances merchant fee yield with manageable default exposure.
- High Ticket:€500-€2,000 purchases concentrated in furniture and premium electronics. Longer installment terms require enhanced identity verification per CNIL guidelines.
- Large Ticket:Exceeding €2,000 for luxury goods and elective medical procedures. Stricter ANSM capital buffers apply given extended repayment horizons.
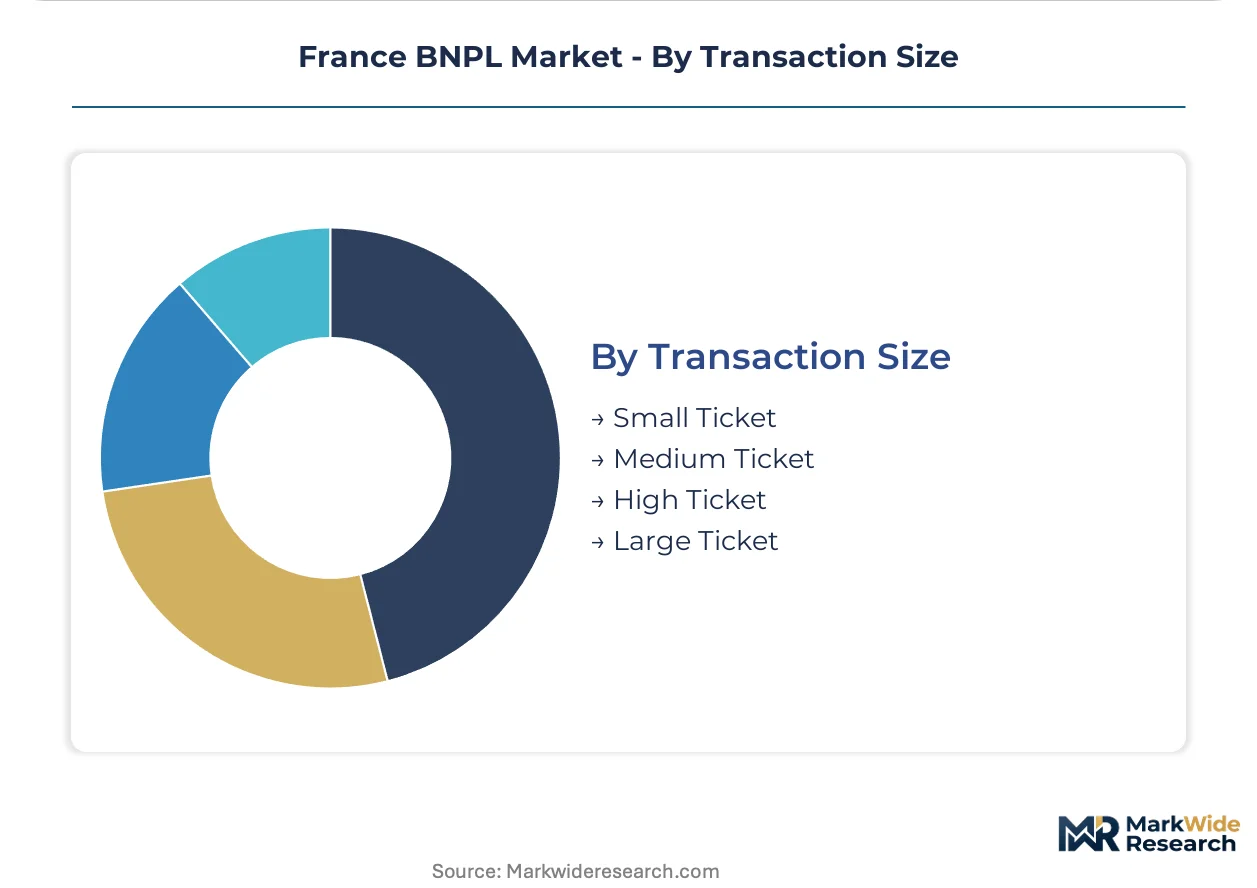
Medium Ticket transactions anchor volume concentration; Small Ticket is expanding most steeply as grocery verticals activate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Consumer Credit Directive's harmonized disclosure standards are reshaping competitive access across French sub-regions, elevating compliance costs that favor established operators with dedicated legal infrastructure in high-density retail corridors.
Île-de-France
Paris and its surrounding departments concentrate the highest BNPL transaction density through premium department store networks and fintech headquarters clustering. ANSM licensing requirements apply stringent capital buffers to operators serving the capital's 12 million residents. Galeries Lafayette and Printemps anchor installment volume in the 8th and 9th arrondissements, where embedded checkout APIs reduce cart abandonment during seasonal sales windows.
Auvergne-Rhône-Alpes
Lyon's electronics retail ecosystem drives medium-ticket BNPL adoption through self-service kiosk deployments at consumer appliance chains. The Banque de France's FICP registry integration challenges underwriters seeking positive payment history visibility. Part-Dieu and Confluence shopping districts host the densest merchant concentration for algorithmic instant-approval tools.
Provence-Alpes-Côte d'Azur
Marseille's port-adjacent retail corridors and Nice's tourism-dependent luxury boutiques sustain high-ticket financing demand for visitor purchases. GDPR-compliant data infrastructure requirements shape provider selection among merchants serving transient international customers. Aix-en-Provence's university precinct generates small-ticket frequency from student apparel and electronics purchases.
Hauts-de-France
Lille's cross-border commerce with Belgium creates unique regulatory complexity for BNPL providers operating under dual jurisdiction exposure. The EU Consumer Credit Directive's cooling-off period mandates affect merchant integration timelines for click-and-collect grocery pilots. Roubaix's textile heritage district hosts emerging fashion marketplace platforms seeking native installment checkout.
Nouvelle-Aquitaine
Bordeaux's wine tourism economy and Nantes' digital-native demographic reject revolving credit products in favor of fixed-commitment installment structures. CNIL-certified biometric authentication frameworks enable fraud reduction at pickup points without friction. Biarritz's seasonal luxury retail concentration demands flexible high-ticket financing for international visitors.
France BNPL Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic archetypes: pan-European technology platforms with proprietary risk engines, domestically integrated checkout specialists with deep e-commerce platform relationships, and legacy retail finance arms anchored through longstanding department store partnerships. Competitive dynamics center on merchant onboarding velocity and regulatory capital efficiency rather than price-based rivalry. Market participants pursue capacity expansion through API-first infrastructure deployment and strategic partnerships with supermarket chains seeking small-ticket grocery vertical penetration.
Within the domestic specialist tier, Alma exemplifies deep platform integration strategies through native plugin architectures for French e-commerce ecosystems. Klarna occupies a position representing pan-European scale advantages derived from cross-border data reservoirs and behavioral scoring infrastructure. Oney anchors the legacy retail finance archetype through embedded relationships with major French department store and supermarket networks. These three patterns illustrate how regulatory compliance burden and technical integration timelines are concentrating competitive advantage among operators with pre-existing capital buffers and merchant settlement rail access.
| Leading Market Players |
|---|
| Alma |
| Klarna |
| Oney |
| Floa Bank |
| PayPal |
| Scalapay |
| Cofidis |
| Younited Credit |
| Clearpay |
| Others |
Pricing and Supply Chain Analysis
Pan-European data infrastructure concentration in Stockholm and Berlin anchors underwriting cost structures for French BNPL providers, with proprietary risk engine licensing fees capturing margin pools that merchant discount rates cannot fully offset. This upstream technology dependency forces domestic specialists to absorb fixed cost burdens while competing on checkout integration velocity.
Pricing Analysis
Merchant fee tiering by transaction size creates the primary spread across French BNPL economics, with small-ticket grocery baskets commanding compressed rates below medium-ticket electronics and high-ticket furniture verticals. ANSM capital requirements elevate compliance costs that concentrate in large-ticket luxury segments where extended repayment horizons trigger stricter solvency buffers. Pricing pressure stems from SEPA Instant bank transfer rails gaining merchant preference for cost-sensitive supermarket volumes. E-commerce platform operators show highest price sensitivity, while premium department stores absorb fees for conversion lift during seasonal windows.
Supply Chain Analysis
Single-source vulnerability in core banking system integration dominates supply chain risk for French BNPL providers, with merchant settlement rails tethered to legacy COBOL architectures at BNP Paribas and Crédit Agricole that resist real-time API connectivity. Underwriting data feeds draw from fragmented Banque de France FICP registries and Klarna's cross-border behavioral reservoirs, creating dependency on proprietary scoring proxies. GDPR-compliant cloud infrastructure concentrates with Irish and Dutch hyperscaler regions. Distribution runs through embedded checkout APIs at WooCommerce and PrestaShop merchant networks, with direct retail partnerships anchoring volume at Galeries Lafayette and Carrefour.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Consumer Credit Directive's forthcoming BNPL-specific amendments represent a regulatory inflection that will mandate standardized APR disclosures and cooling-off periods, compressing margins for unprepared operators while rewarding those with pre-built compliance infrastructure.
For Market Incumbents: Pre-empt margin compression by consolidating merchant settlement rail access through exclusive partnerships with supermarket chains seeking small-ticket grocery penetration. Invest in CNIL-certified biometric authentication frameworks before competitors lock up fraud-reduction positioning at click-and-collect pickup points. Defensive moves must address Floa Bank's expansion into healthcare verticals.
For New Entrants and Emerging Players: Build out white-space presence in dental clinic and optical chain patient financing, where elective medical procedures lack standardized installment options. Target Bordeaux and Nantes digital-native demographics with fixed-commitment products that reject revolving credit structures entirely. Go-to-market execution should leverage CNIL approval frameworks as differentiation against established compliance burdens.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed checkout specialists possessing deep WooCommerce and PrestaShop plugin architectures but limited pan-European scale. Long-term viability hinges on regulatory capital efficiency rather than merchant fee expansion. Watch for EU-wide BNPL legislation implementation as the inflection signal separating compliant operators from forced exits.
| Strategic Initiative | Industry Significance |
|---|---|
| Supermarket Grocery Vertical Expansion | Small-ticket frequency at Carrefour and Intermarché displaces cash for weekly baskets under €150. |
| Healthcare Service Financing Integration | Elective medical procedures at optical chains and dental clinics present underpenetrated merchant categories. |
| CNIL Biometric Authentication Deployment | Facial recognition at pickup points streamlines identity verification without checkout friction. |
| Legacy Core Banking API Modernization | Real-time settlement rails reduce six-to-nine-month technical onboarding timelines for merchant partners. |
| GDPR-Compliant Cross-Border Data Reservoirs | Pan-European behavioral scoring enables risk calibration across multiple merchant categories. |
Research Methodology
A standing panel of risk underwriting officers, e-commerce platform integration specialists, merchant acquisition directors, and ANSM compliance officers provided ongoing calibration throughout the study period. Primary interview data combined with secondary validation from Banque de France regulatory filings, EU Consumer Credit Directive amendment drafts, CNIL certification registries, and SEPA Instant transaction flow disclosures. Bottom-up merchant volume estimates triangulated against top-down consumer credit market sizing across the analysis window.
Scenario-bracketing around regulatory implementation timelines and interest rate cap revisions shaped the analytical framework. Segmentation dimensions modeled include service type, transaction size tier, payment rail, and end-user category throughout the projection horizon. CAGRs derived from merchant onboarding velocity curves and consumer adoption pattern shifts, with algorithmic underwriting deployment rates and grocery vertical penetration serving as key forecast inputs.
Stress conditions across ANSM capital requirement revisions, GDPR enforcement intensity, and bank-issued card substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory harmonization and merchant fee compression trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Financial Fraud Detection Software Market
FinTech
Asia-Pacific Fintech Cloud Market
FinTech
Multichannel Digital Banking Integration Software Market
FinTech
Financial App Market
FinTech
Europe Fintech Cloud Market
FinTech
China AI in Fintech Market
FinTech
Micro-Investing Platform Market
FinTech
AI-Powered Wealth Management Solution Market
FinTech
Japan AI in Fintech Market
FinTech
Digital Banking Platform Market
FinTech
Australia Fintech Market
FinTech
Middle East AI in Fintech Market
FinTech
Financial Management Software Market
FinTech
Asia-Pacific Neo Banking Market
FinTech
Smart Finance Technologies Market
FinTech
Europe Embedded Finance Market