
 North America Payment Analytics Software Market | 2026-2036
North America Payment Analytics Software Market Size, Share, and Industry Trends Forecast 2026-2036
North America Payment Analytics Software Market Analytics
The North America payment analytics software market is decoupling into two distinct tiers: premium platforms offering real-time AI-driven transaction intelligence versus commodity dashboard tools with limited predictive capability. BlueSnap leverages its integrated payment gateway architecture to embed analytics directly at the transaction origin. ACI Payment Systems sustains technology leadership through specialized risk-scoring engines for high-velocity payment networks.
Payment analytics software encompasses platforms that ingest, process, and visualize transaction data streams to detect anomalies, optimize revenue flows, and ensure regulatory compliance, typically operating with sub-second latency requirements for real-time decisioning. The software serves commercial purposes spanning fraud prevention, interchange cost reduction, and customer payment behavior prediction. Cloud-based deployment leads segment momentum as financial institutions migrate core transaction infrastructure off-premises, while fraud detection commands premium pricing due to escalating real-time payment velocity. Revenue optimization tools for e-commerce merchants represent the fastest-expanding application area within product-type segmentation.
The Federal Reserve shapes demand through FedNow instant payment rules requiring continuous transaction monitoring, while the Consumer Financial Protection Bureau enforces data privacy standards affecting analytics data retention policies. FinCEN's anti-money-laundering guidelines mandate suspicious-activity detection capabilities that directly determine product feature requirements for market access. Stakeholders must monitor how open-banking data-sharing frameworks evolve across US and Canadian jurisdictions to anticipate platform interoperability investments.
Market Dynamics
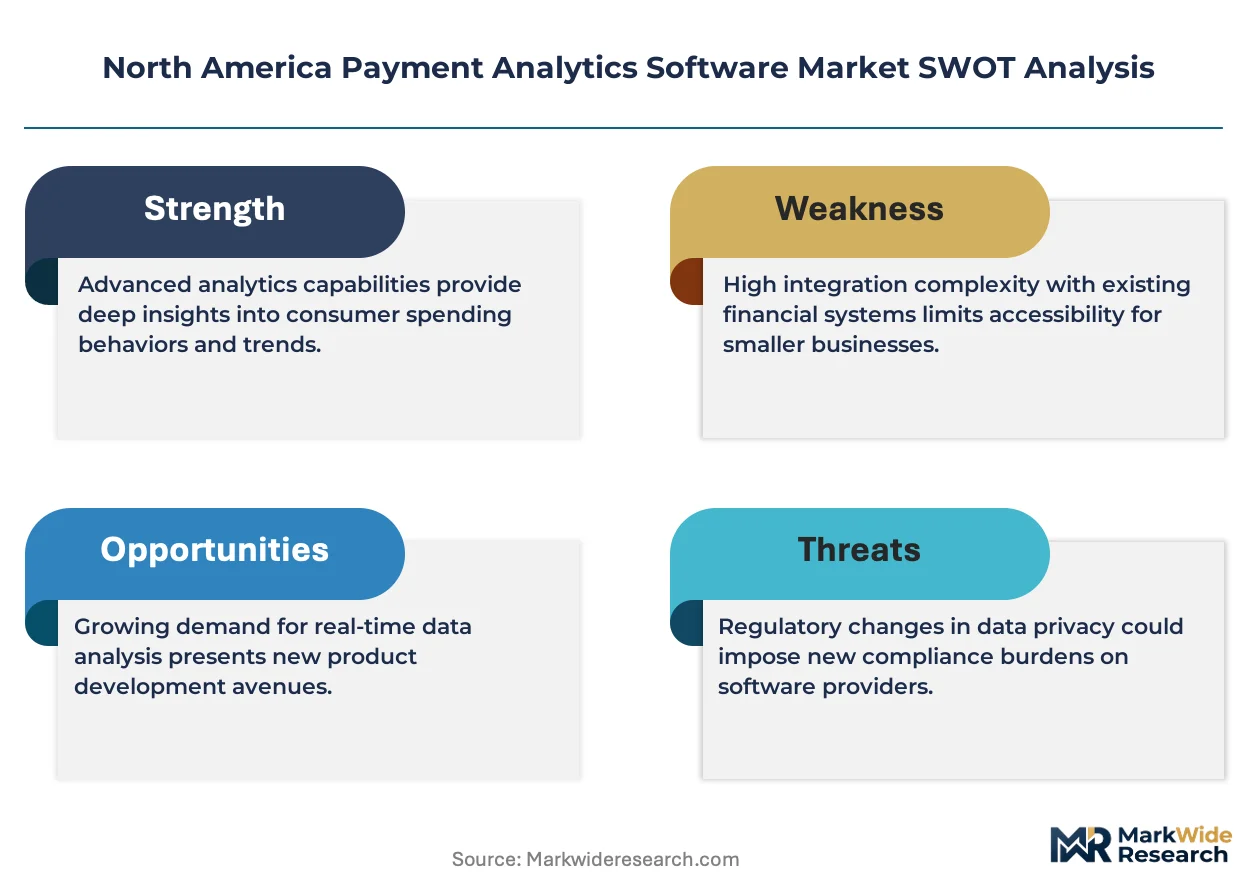
FedNow instant payment infrastructure is compressing latency requirements for transaction intelligence platforms, forcing vendors to rebuild data pipelines for sub-second decisioning or cede ground to integrated gateway providers.
Growth Catalysts
- Real-time payment mandates:The Federal Reserve's FedNow rules require continuous transaction monitoring, compelling financial institutions to upgrade legacy batch-processing systems.
- Cloud migration momentum:Mid-market banks and credit unions are accelerating off-premises core infrastructure shifts, creating demand for cloud-native analytics architectures.
- Fraud velocity escalation:Instant payment networks expose institutions to faster settlement fraud cycles, driving investment in AI-powered anomaly detection engines.
Market Restraints
- Data residency compliance costs:The Consumer Financial Protection Bureau's privacy standards impose multi-jurisdictional data localization requirements that fragment platform architectures.
- Talent scarcity in machine learning operations:Shortages of engineers capable of deploying production-grade fraud models at millisecond latency constrain vendor scaling capacity.
- Legacy core dependency:Mainframe-based transaction processing at regional banks creates integration friction that slows real-time analytics deployment.
Strategic Opportunities
- Open banking data convergence:US and Canadian frameworks enabling consumer-permissioned financial data sharing are creating interoperability requirements for unified analytics platforms.
- Revenue optimization white space:E-commerce merchants lack sophisticated interchange cost analysis tools, representing an underserved segment between enterprise banks and basic dashboard providers.
- Cross-border payment intelligence:Canadian-US corridor transaction growth is generating demand for analytics that normalize regulatory reporting across FinCEN and FINTRAC requirements.
Industry Challenges
- Model explainability demands:Regulators and risk officers require interpretable AI outputs for fraud decisions, complicating black-box neural network deployments.
- Sub-second pipeline engineering:Building data infrastructure that ingests, scores, and routes transactions within FedNow's settlement windows demands specialized distributed systems expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Payment Analytics Software Market |
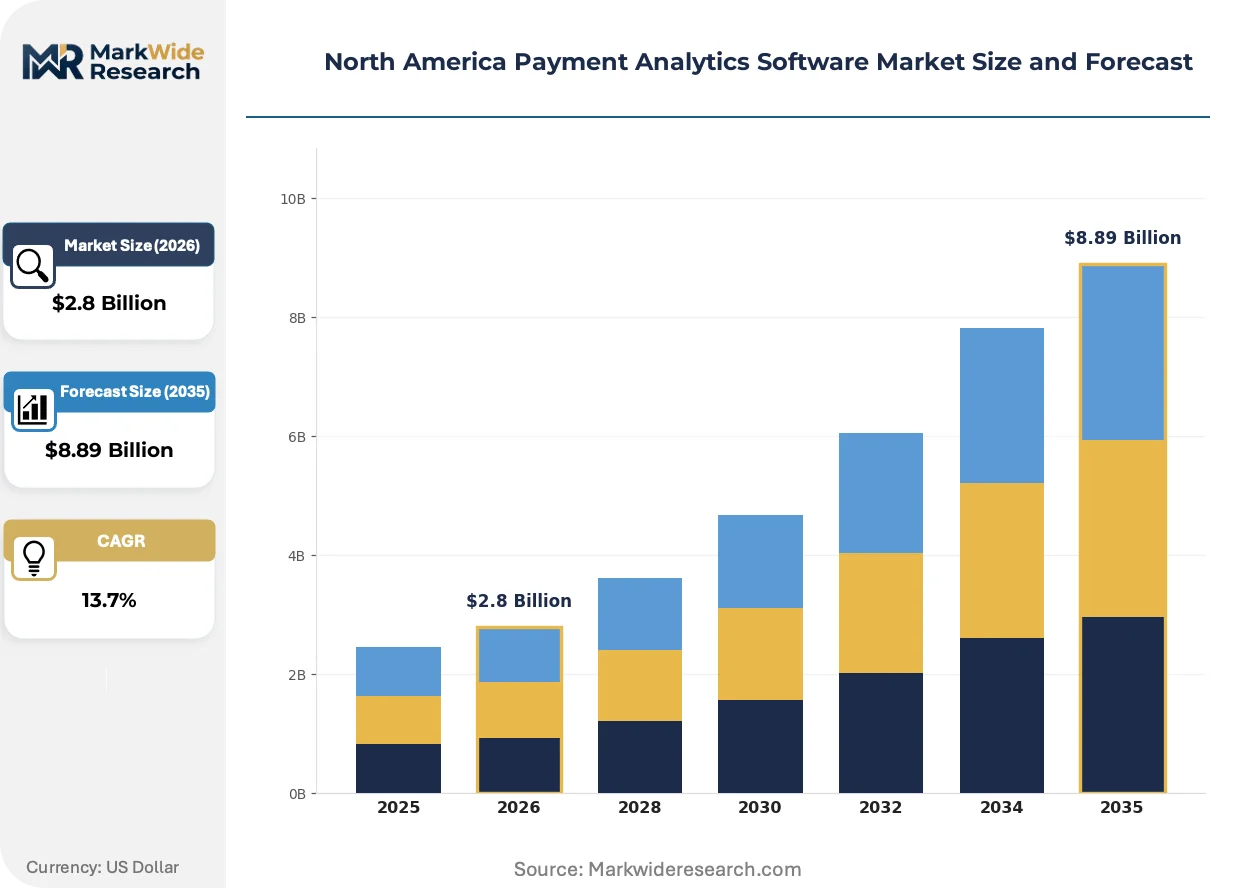
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $8.89 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transaction Monitoring, Risk Management, Revenue Optimization, Fraud Detection Deployment: On-Premises, Cloud-Based, Hybrid, SaaS End User: Retailers, Financial Institutions, E-Commerce, Payment Processors Service Type: Consulting, Implementation, Support, Maintenance |
| Companies Covered | BlueSnap, ProfitWell, Databox, ACI Payment Systems, BNY Mellon NEXEN, CashNotify, HiPay Intelligence, Payfirma, Yapstone, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Payment Analytics Software Market Evolving Landscape
Payment analytics platforms are converging transaction processing with intelligence layers, collapsing the traditional separation between payment rails and decision engines into unified real-time architectures.
Embedded analytics engines are unifying transaction origination with risk scoring and revenue optimization. Mid-market retailers and payment facilitators are adopting these integrated stacks to eliminate data latency between gateway and intelligence layers. This convergence is compressing vendor margins for standalone analytics providers while rewarding gateway-integrated platforms with stickier customer relationships.
The Consumer Financial Protection Bureau's data privacy enforcement actions are reshaping platform data retention architectures. Vendors must now engineer granular consent management and automated purge workflows into core product designs. Canadian institutions face parallel pressures from Office of the Privacy Commissioner guidelines, creating North America-wide product standardization around privacy-by-design principles.
Merchant procurement of payment intelligence is consolidating toward outcome-based pricing models that tie vendor fees to measurable fraud reduction or interchange savings. Large e-commerce platforms are displacing seat-based SaaS contracts with performance-linked agreements that shift vendor risk. This shift is most advanced in the US Northeast corridor, where Boston and New York financial technology clusters pilot these structures before broader rollout.
North America Payment Analytics Software Market Segmentation
Payment analytics software segments diverge sharply by integration depth. Standalone platforms serve legacy institutions with batch-processed intelligence, while embedded engines fuse directly into transaction origination points for sub-second decisioning.
Product Type:
Integration depth varies dramatically across product categories, with some functioning as bolt-on intelligence layers and others operating as native transaction infrastructure components.
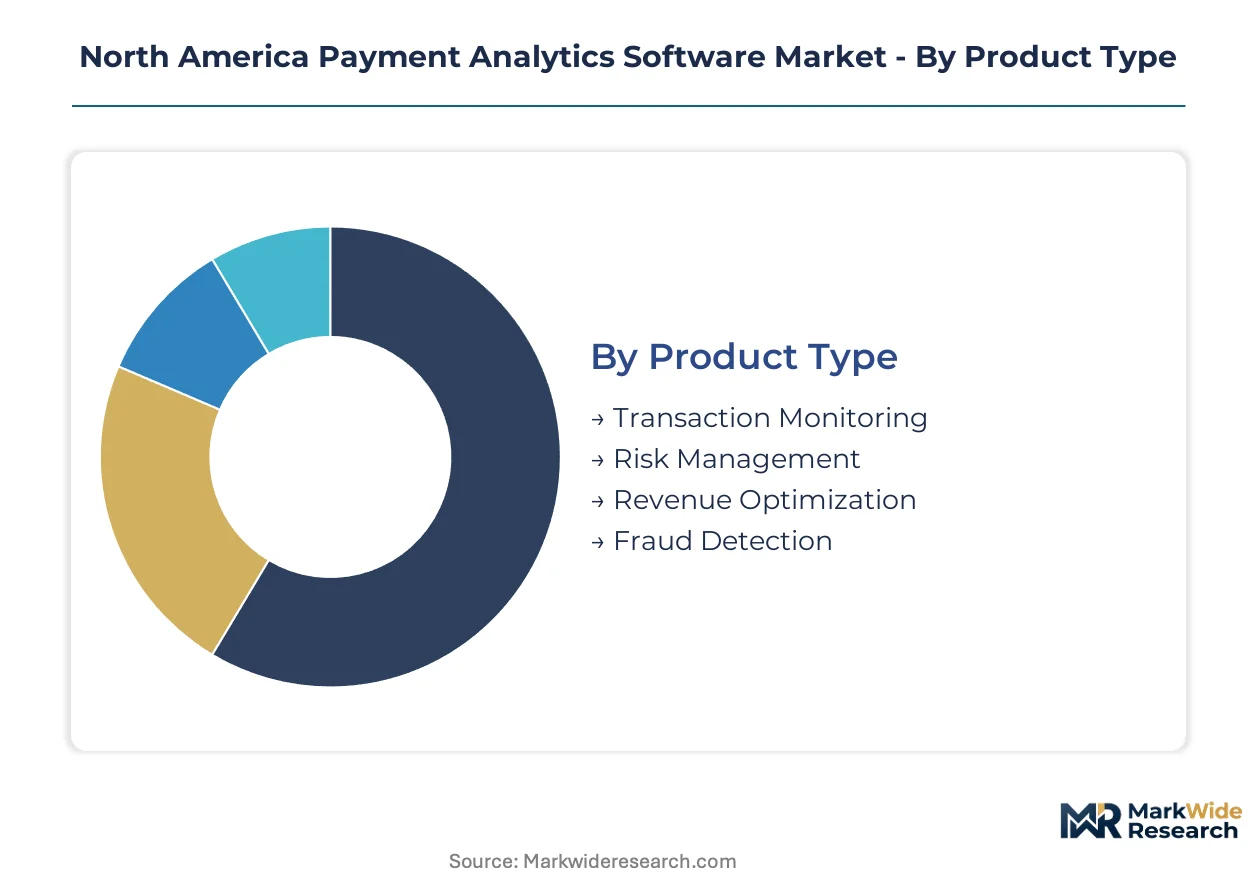
- Transaction Monitoring:Continuous surveillance platforms ingest payment streams to flag anomalies against behavioral baselines. US Northeast corridor banks deploy these for FedNow compliance, compressing detection latency from minutes to milliseconds.
- Fraud Detection:AI-powered scoring engines evaluate transaction authenticity in real time using device fingerprinting and behavioral biometrics. Payment processors in the Boston-New York corridor command premium pricing here due to instant settlement exposure.
- Risk Management:Portfolio-level exposure assessment tools aggregate counterparty and liquidity risks across payment networks.
- Revenue Optimization:Interchange cost analysis and routing intelligence for merchant fee reduction.
Transaction Monitoring leads volumes today; Fraud Detection is gaining share fastest.
Deployment:
Cost tier stratification separates enterprise-grade infrastructure investments from mid-market accessibility plays.
- Cloud-Based:Fully managed architectures eliminate capital expenditure for regional banks and credit unions. Mid-market institutions across the US Northeast corridor favor this model for FedNow readiness without data center expansion.
- SaaS:Subscription-delivered analytics with standardized dashboards and API access. E-commerce merchants in New York and Boston clusters adopt these for rapid deployment without engineering overhead.
- Hybrid:Sensitive transaction data remains on-premises while compute-intensive modeling shifts to cloud.
- On-Premises:Self-hosted installations serving institutions with stringent data residency requirements.
Cloud-Based deployments dominate new procurement; SaaS is climbing the fastest.
End User:
Application intensity differs by sector maturity, with some verticals treating analytics as compliance infrastructure and others as revenue-generating assets.
- Financial Institutions:Banks and credit unions deploy comprehensive stacks spanning monitoring, risk, and regulatory reporting. The US Federal Reserve's FedNow mandates drive replacement of legacy batch systems across this segment.
- E-Commerce:Digital merchants prioritize revenue optimization and fraud prevention with lightweight integration. This segment shows steepest expansion trajectory as interchange cost awareness spreads beyond enterprise retailers.
- Payment Processors:Gateway providers embedding native intelligence to differentiate transaction services.
- Retailers:Brick-and-mortar and omnichannel merchants with mixed payment acceptance environments.
Financial Institutions anchor current demand; E-Commerce is expanding most quickly.
Service Type:
Customer type segmentation reveals how procurement sophistication shapes vendor engagement models across the implementation lifecycle.
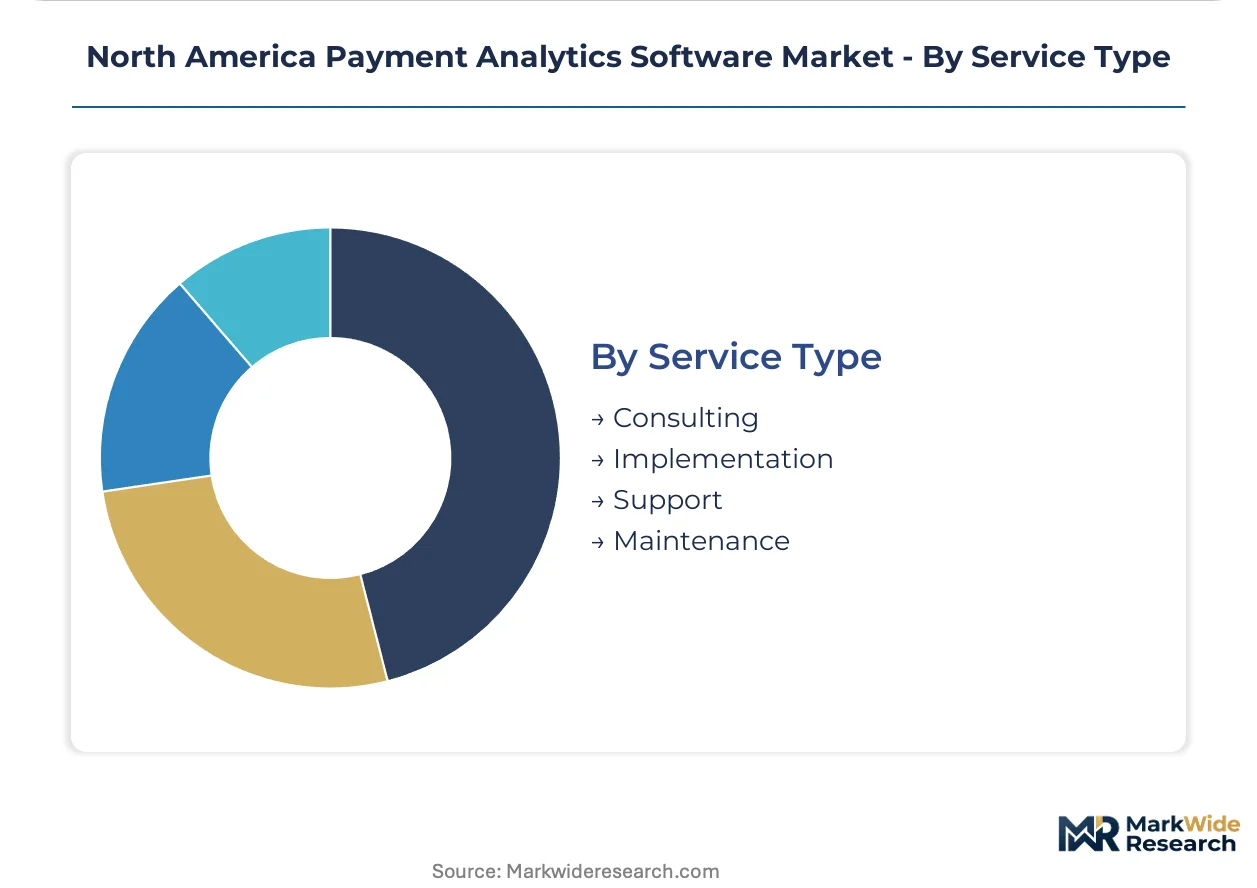
- Implementation:System integration and data pipeline construction for real-time analytics deployment. Regional banks with mainframe dependencies require extensive customization in the US Northeast corridor.
- Consulting:Strategic advisory on analytics architecture and regulatory compliance alignment. Financial institutions leverage this for FedNow readiness assessments and model governance frameworks.
- Support:Ongoing technical assistance and troubleshooting for production environments.
- Maintenance:Updates, patches, and performance optimization for deployed platforms.
Implementation services command the largest project values; Consulting is accelerating fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands substantially larger procurement volumes than Canada, though both markets face parallel FedNow compliance deadlines reshaping vendor requirements across the continent.
United States
Financial institutions in the US Northeast corridor from Boston to New York are replacing legacy batch systems with real-time pipelines. The Federal Reserve's FedNow rules mandate continuous transaction monitoring, compressing detection latency from minutes to milliseconds. Dallas and Chicago payment processing clusters are expanding engineering capacity to serve mid-market banks migrating core infrastructure off-premises.
Canada
Toronto's financial technology district is driving demand for cross-border payment intelligence normalizing FinCEN and FINTRAC reporting requirements. The Office of the Privacy Commissioner enforces data retention standards that fragment platform architectures across the 49th parallel. Montreal payment facilitators are piloting outcome-based pricing models before broader North American rollout.
Mexico
Mexico City payment processors are adopting cloud-native analytics architectures as SPEI instant payment infrastructure matures. The central bank's fintech licensing framework is accelerating foreign vendor market entry. Guadalajara software development clusters are building specialized engineering talent for sub-second pipeline deployment serving US-bound nearshore contracts.
North America Payment Analytics Software Market Competitive Landscape
Top-tier vendors anchor integrated gateway-analytics platforms, while standalone dashboard providers occupy commoditized lower tiers. The vendor base stratifies sharply by latency capability, with sub-second decisioning engines commanding premium positioning against batch-processed alternatives. Two strategic archetypes dominate: payment gateway incumbents embedding native intelligence layers, and specialized risk-scoring engine developers. Competitive moves concentrate on strategic partnerships with core banking providers and technology licensing arrangements for real-time data pipeline components.
Within the integrated platform tier, BlueSnap and ACI Payment Systems exemplify contrasting architectural approaches to transaction-origin intelligence. BlueSnap leverages its gateway foundation to collapse data latency between processing and analytics layers. ACI Payment Systems occupies a specialized position in high-velocity network risk scoring. BNY Mellon NEXEN represents the incumbent banking technology vector, anchoring enterprise-scale deployment capacity for institutions with mainframe dependencies.
| Leading Market Players |
|---|
| BlueSnap |
| ProfitWell |
| Databox |
| ACI Payment Systems |
| BNY Mellon NEXEN |
| CashNotify |
| HiPay Intelligence |
| Payfirma |
| Yapstone |
| Others |
Value Network & Pricing Analysis
Cloud infrastructure cost indices cascading through vendor pricing tiers are compressing margins for standalone analytics providers while amplifying pricing power for integrated gateway platforms. The shift toward outcome-based contracting in the US Northeast corridor accelerates this bifurcation.
Pricing Analysis
Capacity additions in Dallas and Chicago cloud regions are reshaping price floors for SaaS-delivered analytics, pressuring legacy on-premises vendors. Three-tier pricing structure across premium real-time engines, standard batch platforms, and economy dashboard tools dominates procurement. Price differentiation rests on latency capability and FedNow compliance certification. E-commerce merchants in the Boston-New York corridor exhibit highest price sensitivity, while tier-one payment processors absorb premium pricing for sub-second decisioning.
Supply Chain Analysis
Freight costs for specialized hardware accelerators deployed in hybrid cloud configurations are elevating total cost of ownership for latency-sensitive deployments. Engineering talent concentrates in the United States, Canada, and Mexico's Guadalajara corridor. Raw material dependencies span GPU compute clusters, high-throughput networking silicon, and low-latency storage arrays. Single-source vulnerability in AI training chip supply creates procurement risk. Distribution runs through direct enterprise sales teams and hyperscaler marketplace channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in real-time analytics tiers where FedNow compliance premiums offset cloud infrastructure costs. Vendors capturing gateway-embedded positions capture superior pricing power.
For Market Incumbents: Lock in FedNow-certified platform positions before regulatory deadlines harden procurement specifications. Acquire specialized ML engineering teams in Guadalajara and Toronto to defuse talent scarcity. Deepen backward integration into cloud infrastructure to control latency-critical compute costs. For New Entrants and Emerging Players: Payment facilitators serving mid-market e-commerce merchants represent the most penetrable channel partner type for embedded analytics distribution. Target interchange cost optimization white space between enterprise banks and basic dashboard providers. Lead with outcome-based pricing pilots in Montreal before broader North American rollout. For Investors and Strategic Acquirers: Asymmetric upside sits with gateway-integrated platforms possessing native real-time scoring engines. Five-to-ten-year viability favors vendors collapsing transaction processing and intelligence layers. Monitor FedNow adoption velocity across US regional banks as inflection indicator for platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding analytics at transaction origin eliminates data latency for FedNow compliance. |
| Strategic Partnership | Core banking provider alliances accelerate real-time pipeline deployment at regional institutions. |
| Acquisition of Specialist Firm | ML engineering boutiques in Guadalajara address sub-second pipeline talent scarcity. |
| Product Launch | Outcome-based pricing models displace seat-based SaaS contracts in US Northeast corridor. |
| Geographic Expansion | Toronto hub development captures cross-border payment intelligence normalization demand. |
Research Methodology
Multiple input streams — executive interviews with payment platform CTOs, procurement officers at regional banks, and FedNow implementation specialists — were reconciled against secondary validation. Primary fieldwork encompassed discussions with fraud risk officers, cloud infrastructure architects, and regulatory compliance leads across Boston, New York, Toronto, and Dallas clusters. Secondary sources included SEC filings from publicly traded payment processors, Federal Reserve technical specifications, and Office of the Privacy Commissioner enforcement records. Bottom-up deployment estimates and top-down market sizing were cross-triangulated.
Historical adoption curves were cross-referenced against panel input from vendor sales leadership and enterprise buyer committees. Segmentation modeling spanned deployment model, integration depth, end-user vertical, and regional regulatory framework across the projection horizon. CAGRs were derived from weighted scenario analysis incorporating FedNow penetration assumptions and cloud migration velocity. Industry-specific inputs encompassed real-time payment transaction growth rates and interchange cost optimization tool adoption patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FedNow regulatory evolution, open-banking framework harmonization, and AI chip supply constraints. Forecasts reflect documented assumptions about payment velocity growth and compliance timeline adherence. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Saudi Arabia Mobile Payments Market
Payments
QR Codes Payment Market
Payments
Japan Mobile Payments Market
Payments
Russia Payments Market
Payments
Denmark Mobile Payments Market
Payments
Payment Card Market
Payments
Mexico POS Terminals Market
Payments
Global Utility Billing Software Market
Payments
Global Payment Processor Market
Payments
EMV Card Market
Payments
Kenya Mobile Money Market
Payments
MENA Digital Payments Market
Payments
Portugal Mobile Payments Market
Payments
United States Real Time Payments Market
Payments
Europe Virtual Cards Market
Payments
Buy Now Pay Later Market